
 Global Industrial Design Market | 2026-2036
Global Industrial Design Market Size, Share, and Industry Trends Forecast 2026-2036
Global Industrial Design Market Outlook
Subscription-based design software licensing is hardening into the dominant commercial model for industrial design studios. IDEO leverages its Palo Alto roots to anchor premium consulting engagements for Fortune 500 product launches. Frog competes through deep specialization in connected device ecosystems, while Pininfarina sustains its reputation by extending automotive styling expertise into yacht and architecture commissions.
Industrial design encompasses the systematic creation and optimization of product form, function, and user interaction through iterative prototyping, materials science, and anthropometric analysis. Practitioners employ 3D printing for rapid physical validation and CAD software for parametric surface modeling to resolve manufacturing constraints before tooling investment. Consumer Electronics commands the largest application share due to compressed product lifecycles and interface complexity, while Medical Devices offers the strongest margin pool given regulatory documentation burdens and specialized human-factors expertise. Augmented Reality is displacing traditional clay modeling in Automotive design reviews, accelerating iteration cycles for OEM styling teams.
FDA human-factors guidance and EU MDR usability engineering requirements are elevating documentation standards for hardware interfaces across regulated sectors. ISO 9241-210 ergonomics frameworks and REACH substance restrictions are shaping material palettes and surface finish specifications in European consumer goods production. Stakeholders must monitor how generative AI tools reshape staffing ratios between senior designers and technical specialists.
Market Dynamics
Generative AI tools are compressing iteration cycles for concept visualization while tightening documentation requirements from FDA and EU MDR reshape staffing priorities across medical device design studios.
Growth Catalysts
- EU MDR Usability Mandates:Hardware interface documentation requirements for medical devices are expanding design service contracts across European notified bodies.
- Automotive AR Adoption:OEM styling teams in Germany are replacing physical clay modeling with augmented reality reviews, accelerating program timelines.
- Patient-Centric Interfaces:Medical device manufacturers are expanding human-factors budgets to address aging demographics and chronic disease management devices.
Market Restraints
- Specialized Talent Scarcity:Industrial designers with combined expertise in parametric CAD and regulatory documentation command premium compensation.
- REACH Compliance Costs:European substance restrictions limit material palettes and surface finish specifications for consumer goods producers.
- Concentrated Software Licensing:Subscription-based CAD and rendering platforms create recurring cost pressure on smaller design studios.
Strategic Opportunities
- India Manufacturing Uplift:PLI scheme incentives for electronics and medical device production are creating design localization demand in Bengaluru and Pune clusters.
- Connected Device Convergence:Integration of industrial design with IoT ecosystem architecture opens service expansion for hardware-software interface specialists.
- China Dual Carbon Goals:NMPA and MIIT sustainability mandates are elevating circular design and material traceability requirements for export-oriented manufacturers.
Industry Challenges
- Human-Factors Expertise Gap:Studios struggle to recruit specialists qualified for FDA 510(k) and EU MDR usability engineering file preparation.
- Physical-Digital Integration:Bridging generative AI concept tools with parametric CAD and 3D printing validation workflows demands capital investment and workflow redesign.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Industrial Design Market |
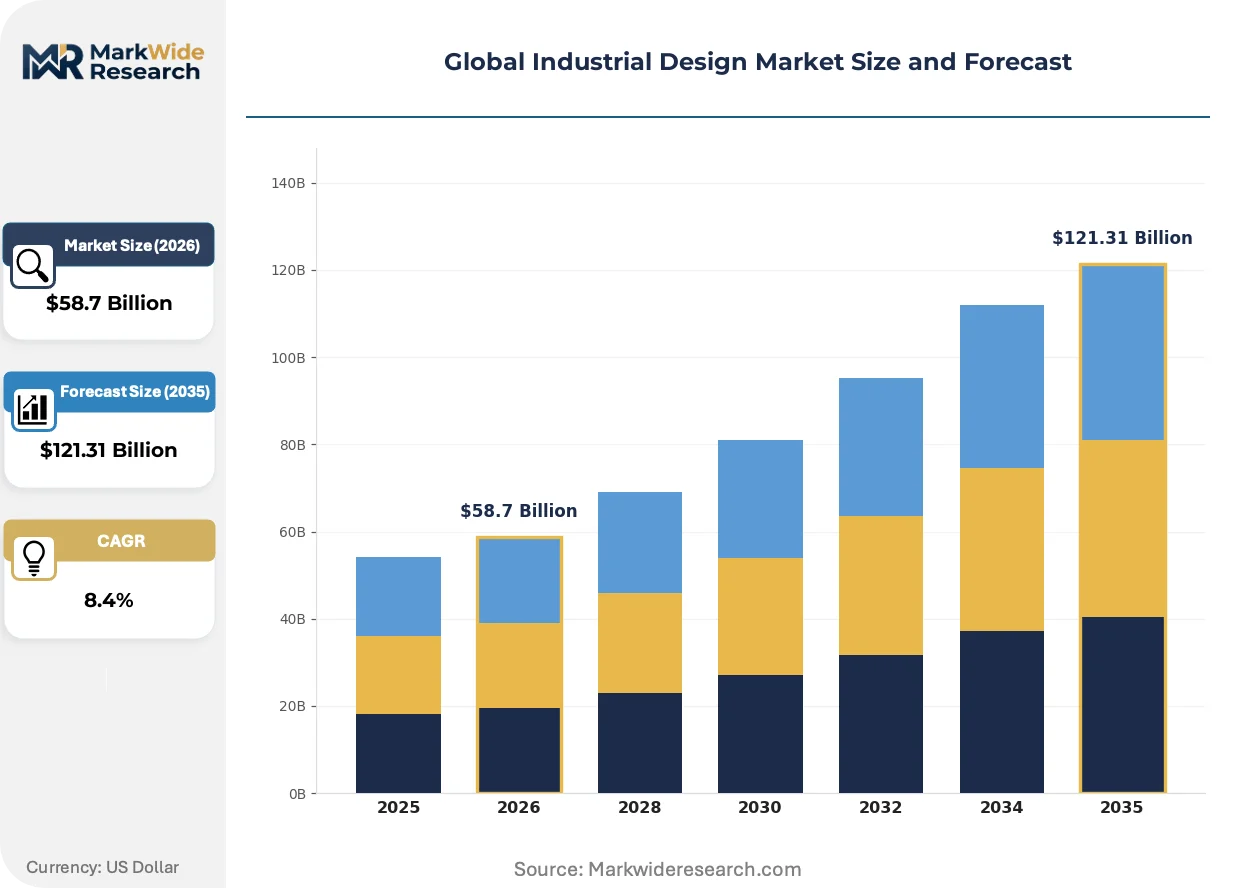
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $121.31 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Consumer Electronics, Furniture, Appliances, Medical Devices Technology: 3D Printing, CAD Software, Augmented Reality, Virtual Reality End User: Manufacturers, Retailers, Designers, Startups Application: Automotive, Aerospace, Consumer Goods, Electronics |
| Companies Covered | Whipsaw, NewDealDesign, IDEO, Pininfarina, Designworks, Frog, Speck Design, Delve, StudioRed, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Industrial Design Market Strategic Shifts
Computational design methods are redistributing workflow ownership between senior designers and technical specialists while regulatory documentation automation and sustainable material innovation reshape capability requirements.
Generative surface modeling is consolidating control over early-stage form exploration previously requiring extensive manual iteration. Automotive and consumer electronics OEMs are embedding these tools into pre-tooling validation workflows. This compression of concept-to-surface timeline is consolidating competitive advantage around studios with integrated AI-CAD pipelines.
EU MDR technical documentation requirements are elevating human-factors engineering file standards across Class IIa and above medical devices. Design consultancies must now embed usability validation protocols earlier in development cycles. German and Irish medical device clusters are responding by building captive regulatory affairs capabilities or partnering with specialized documentation firms.
Subscription-based software access is altering studio capital structures and client engagement models. Smaller practices are trading perpetual license ownership for operational flexibility while enterprise clients demand outcome-linked pricing tied to regulatory clearance milestones. This shift is most pronounced in US and UK markets where design services procurement increasingly mirrors SaaS purchasing patterns.
Global Industrial Design Market Segmentation
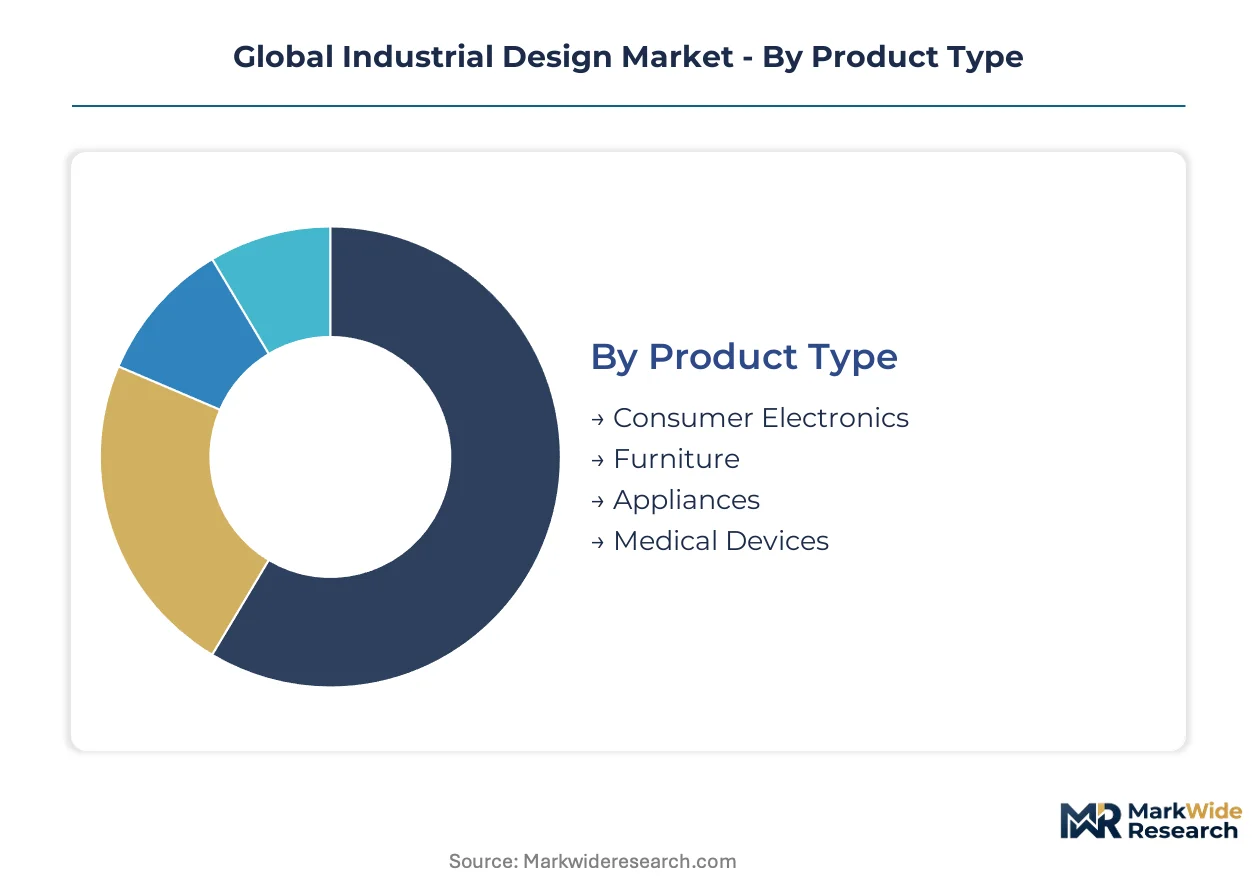
Industrial design segmentation reveals how technology adoption and regulatory requirements reshape service procurement across distinct product categories. Each dimension exposes divergent margin structures, capability requirements, and geographic concentration patterns that determine competitive positioning.
Product Type:
Technical sophistication and documentation burden separate high-margin segments from commoditized design services.
- Consumer Electronics:Parametric surface modeling and rapid prototyping cycles dominate this segment. German automotive design clusters in Munich and Stuttgart absorb significant talent flow from consumer electronics studios seeking interface complexity expertise.
- Medical Devices:FDA 510(k) and EU MDR usability engineering requirements elevate documentation standards. Human-factors specialists command premium compensation as manufacturers expand budgets for patient-centric hardware interfaces.
- Furniture:REACH substance restrictions constrain material palettes and surface finish specifications across European production.
- Appliances:Circular design mandates from China's NMPA and MIIT reshape material traceability requirements for export-oriented manufacturers.
Consumer Electronics leads on scale; Medical Devices leads on momentum.
Technology:
Capital intensity and workflow integration depth determine adoption trajectories across design tool categories.
- CAD Software:Subscription licensing has displaced perpetual ownership, altering studio capital structures. Enterprise clients now demand outcome-linked pricing tied to regulatory clearance milestones.
- 3D Printing:Rapid physical validation compresses iteration cycles before tooling investment. India's PLI scheme incentives for electronics and medical device production are accelerating design localization demand in Bengaluru and Pune clusters.
- Augmented Reality:OEM styling teams in Germany are replacing physical clay modeling with AR reviews, accelerating program timelines.
- Virtual Reality:Immersive design reviews reduce travel costs for distributed engineering teams.
CAD Software leads on scale; Augmented Reality leads on momentum.
End User:
Procurement sophistication and internal capability depth shape service engagement models.
- Manufacturers:Captive design studios and outsourced consulting relationships coexist. Medical device manufacturers are expanding human-factors budgets to address aging demographics and chronic disease management devices.
- Designers:Independent practitioners trade perpetual license ownership for subscription-based operational flexibility. Smaller practices face recurring cost pressure from concentrated software licensing.
- Retailers:Private label development drives demand for rapid concept-to-shelf pipelines.
- Startups:Generative AI tools compress early-stage form exploration previously requiring extensive manual iteration.
Manufacturers lead on scale; Startups lead on momentum.
Application:
Regulatory density and product lifecycle velocity create divergent capability requirements.
- Automotive:Augmented Reality is displacing traditional clay modeling in design reviews. German OEM styling teams are embedding computational design methods into pre-tooling validation workflows.
- Consumer Goods:REACH compliance costs limit material palettes and surface finish specifications for European producers. ISO 9241-210 ergonomics frameworks shape production standards.
- Electronics:Compressed product lifecycles and interface complexity sustain the largest application share. Connected device convergence opens service expansion for hardware-software interface specialists.
- Aerospace:Certification documentation requirements elevate human-factors engineering file standards.
Electronics leads on scale; Automotive leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cost-of-compliance arbitrage is redirecting medical device design contracts toward jurisdictions with streamlined regulatory pathways, while automotive styling concentration in Southern Germany sustains premium service premiums despite higher operational costs.
Germany
OEM styling teams in Munich and Stuttgart drive demand for augmented reality design review capabilities. EU MDR usability mandates expand documentation service contracts across notified bodies serving Class IIa and above medical devices. The Baden-Württemberg automotive cluster anchors computational design tool adoption for pre-tooling validation workflows.
United States
FDA 510(k) human-factors documentation requirements elevate staffing priorities for specialized regulatory affairs capabilities. Medical device manufacturers in Greater Boston and Minneapolis expand budgets for patient-centric hardware interfaces addressing aging demographics. California design studios leverage subscription-based software licensing to trade capital intensity for operational flexibility.
China
NMPA and MIIT sustainability mandates elevate circular design requirements for export-oriented electronics manufacturers. Dual carbon goals reshape material traceability specifications across Pearl River Delta production bases. Shenzhen and Shanghai clusters absorb generative AI tool adoption for compressed concept-to-surface timelines.
India
PLI scheme incentives for electronics and medical device production create design localization demand in Bengaluru and Pune. CDSCO regulatory alignment efforts attract contract research organizations seeking cost-advantaged documentation preparation. Karnataka's technology corridor concentrates 3D printing validation infrastructure for rapid physical prototyping.
United Kingdom
Post-Brexit divergence from EU MDR technical documentation standards fragments compliance pathways for medical device exporters. London design consultancies pivot toward SaaS purchasing patterns mirroring enterprise software procurement. The M4 corridor maintains connected device ecosystem specialization serving hardware-software interface convergence.
Global Industrial Design Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with consolidated premium consulting relationships in automotive and medical devices contrasting fragmented competition in consumer electronics rapid prototyping. Three archetypes dominate: integrated design-engineering studios with captive regulatory capabilities, boutique form-factor specialists leveraging geographic styling heritage, and technology-forward practices embedding generative AI into client workflows. M&A activity concentrates on acquiring human-factors documentation expertise, while strategic partnerships proliferate between industrial designers and specialized regulatory affairs firms.
Within the heritage-styling tier, Pininfarina exemplifies automotive-rooted expansion into adjacent luxury categories, while IDEO anchors premium consulting engagements through its Palo Alto origins. Frog occupies a position bridging connected device ecosystem specialization with hardware-software interface integration. These three represent distinct competitive vectors: geographic styling credibility, integrated innovation methodology, and convergent technology-platform capabilities.
| Leading Market Players |
|---|
| Whipsaw |
| NewDealDesign |
| IDEO |
| Pininfarina |
| Designworks |
| Frog |
| Speck Design |
| Delve |
| StudioRed |
| Others |
Value Chain & Pricing Dynamics
FDA 510(k) and EU MDR usability documentation mandates are forcing medical device manufacturers to absorb premium design service costs, compressing procurement flexibility and consolidating vendor relationships around studios with captive regulatory capabilities.
Pricing Analysis
Direct-to-OEM project pricing dominates medical device and automotive segments, bypassing distributor markups entirely. Three-tier pricing structure across premium, standard, and economy levels separates regulatory-grade documentation bundles from rapid prototyping and concept-only engagements. Cost compression in consumer electronics design services is intensifying because generative AI tools commoditize early-stage visualization. Startup hardware ventures exhibit highest price sensitivity, while Fortune 500 OEMs prioritize outcome-linked contracts tied to regulatory clearance milestones.
Supply Chain Analysis
Refurbishment flows for 3D printing equipment and CAD workstation leasing are extending asset lifecycles across Bengaluru, Shenzhen, and Munich design clusters. Component sourcing draws from Taiwan for precision optical sensors, Germany for CNC machining centers, and China for desktop 3D printing hardware. Single-source vulnerability concentrates in subscription-based software licensing platforms controlling parametric modeling and rendering pipelines. Distribution runs through direct enterprise sales teams for major studios and platform marketplaces for independent practitioners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Industrial Design Market compounds steadily as regulatory documentation burdens deepen client retention and expand contract values across medical device and automotive verticals.
For Market Incumbents: Lock in human-factors documentation specialists through equity participation or long-term employment guarantees before FDA and EU MDR staffing competition intensifies. Backward integration into 3D printing validation infrastructure in Germany and India secures pre-tooling workflow control against emerging AI-native competitors. For New Entrants and Emerging Players: Capture connected device ecosystem integration demand in the United Kingdom's M4 corridor, where hardware-software interface specialization remains underpenetrated relative to Silicon Valley and Shenzhen. Position around SaaS-enabled design collaboration tools priced per-seat below incumbent subscription tiers. For Investors and Strategic Acquirers: Asymmetric upside sits with boutique studios possessing EU MDR notified body relationships and Class IIa medical device filing track records. Five-to-ten year viability favors regulatory affairs capabilities over pure generative AI tooling. Monitor CDSCO alignment progress in India for inflection signals on design localization contract migration.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Affairs Capability Acquisition | EU MDR and FDA documentation expertise commands premium multiples in medical device vertical consolidation. |
| Generative AI Workflow Integration | Parametric CAD pipeline embedding compresses concept-to-surface timelines for automotive OEM styling teams. |
| India Design Localization Buildout | PLI scheme incentives in Bengaluru and Pune attract electronics and medical device manufacturing design contracts. |
| Connected Device Ecosystem Partnership | Hardware-software interface convergence opens service expansion for IoT architecture specialists in UK and US markets. |
| Sustainable Material Innovation Program | REACH compliance and China dual carbon goals reshape material palettes for European consumer goods producers. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with industrial design studio principals, medical device regulatory affairs leads, automotive OEM styling directors, and 3D printing service bureau operators with secondary validation against FDA 510(k) filing databases, EU MDR notified body registers, and PLI scheme disbursement records. Bottom-up service contract value aggregation and top-down market sizing triangulated segment estimates.
Historical reference periods anchored the projection horizon to observed regulatory implementation timelines and technology adoption curves across the analysis window. Segmentation dimensions modeled include product type, technology stack, end-user procurement sophistication, and application regulatory density. CAGRs derived from regression analysis of documented contract values and disclosed design service budgets, incorporating generative AI adoption rates and human-factors specialist compensation inflation as industry-specific inputs.
Regulatory pathway delays, generative AI capability disruption, and PLI scheme incentive modifications are the dominant revision risks to modeled forecasts. Forecasts reflect documented assumptions on regulatory staffing ratios and software licensing concentration. Practitioners should monitor CDSCO alignment milestones and EU MDR transition deadline extensions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Multichannel Order Management Market
Digital Solutions
Global Advanced Distribution Management System (ADMS) Market
Digital Solutions
US Digital Twin Market
Digital Solutions
Europe Digital Marketing Software Market
Digital Solutions
Cloud Based Drug Discovery Platform Market
Digital Solutions
Load Balancer Market
Digital Solutions
Online on-Demand Home Services Market
Digital Solutions
Middle East and Africa Digital Signage Market
Digital Solutions
Returnless Refund Fraud Detection Market
Digital Solutions
Laser Page-Turning Pen Market
Digital Solutions
Context Rich Systems Market
Digital Solutions
Data Monetization Platform Market
Digital Solutions
Managed File Transfer (MFT) Market
Digital Solutions
Germany Smart Office Market
Digital Solutions
Cheque Scanner Market
Digital Solutions
IT Operations and Service Management (ITOSM) Market