
 UK Route Optimization Software Market | 2026-2036
UK Route Optimization Software Market Size, Share, and Industry Trends Forecast 2026-2036
UK Route Optimization Software Market Insights
Platform licensing revenue is rewriting profit distribution across the UK route optimization landscape. Microlise leverages its telematics heritage to anchor fleet management contracts with major British hauliers. Descartes Systems Group sustains cross-border customs integration alongside its routing modules, competing for Brexit-complex supply chains. Verizon Connect dominates the small-to-mid fleet segment through aggressive channel partnerships with UK vehicle leasing networks.
Route optimization software employs combinatorial algorithms and real-time traffic APIs to calculate minimal-time or minimal-distance paths for vehicle fleets, typically processing road-network graphs with constraints on vehicle capacity, driver hours, and delivery windows. The primary commercial purpose is reducing fuel expenditure and asset idle time while meeting customer-specific arrival commitments. Cloud-based deployment leads adoption among British SMEs lacking dedicated IT infrastructure, while artificial intelligence functionality represents the fastest-expanding segment as carriers invest in predictive delay modelling. Real-time tracking remains the most mature capability, with margin pools shifting toward integrated traffic management modules that combine congestion pricing data with dynamic rerouting.
The UK Information Commissioner's Office enforces GDPR-compliant location data handling, shaping how vendors architect geofencing and driver-privacy features within their platforms. The Department for Transport's Future of Freight strategy and local authority Clean Air Zone schemes directly mandate emission-minimizing route selection, creating regulatory pull for optimization tools. Fleet operators and software vendors must monitor evolving Low Emission Zone boundaries and carbon reporting obligations as these frameworks tighten operational constraints across British urban logistics corridors.
Market Dynamics
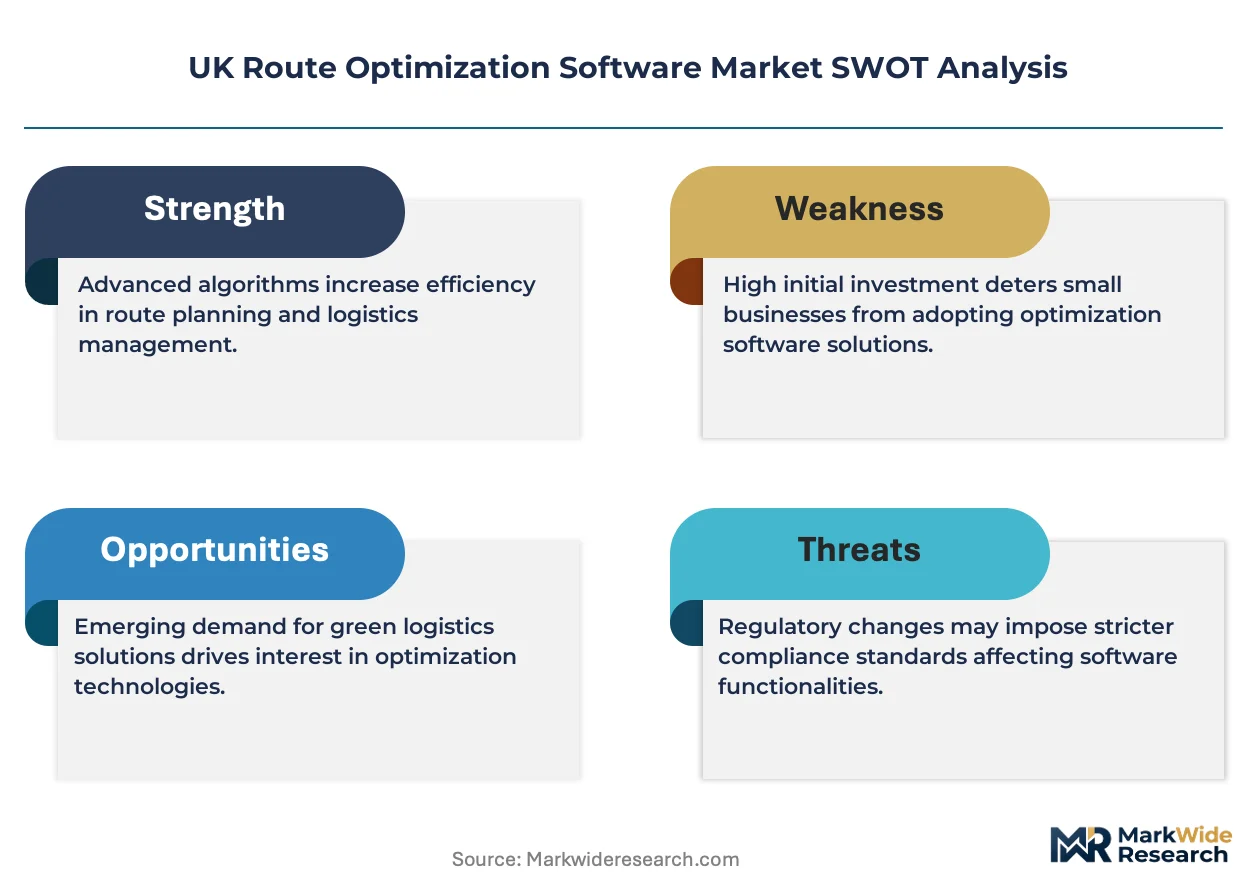
Algorithmic route planning is hybridizing with emission-minimizing constraints as Clean Air Zone enforcement tightens across British urban logistics corridors. Fleet operators now face binding operational trade-offs between delivery velocity and regulatory compliance.
Growth Catalysts
- Clean Air Zone mandates:Birmingham, London, and Bristol authorities enforce emission-minimizing route selection, compelling logistics providers to adopt dynamic routing tools or face daily charges.
- E-commerce fulfilment expansion:British distribution hubs serving grocery and fast-moving consumer goods sectors require real-time capacity balancing across unpredictable demand spikes.
- Telematics convergence:Vehicle tracking data streams now feed directly into optimization engines, enabling predictive delay modelling that reduces idle time at depots.
Market Restraints
- GDPR compliance architecture:The UK Information Commissioner's Office mandates strict location data handling, forcing vendors to redesign geofencing and driver-privacy features at substantial engineering cost.
- Cloud dependency risks:British SMEs lacking dedicated IT infrastructure remain exposed to connectivity outages that disable real-time rerouting capabilities.
- Traffic API cost concentration:Fleet operators rely on a narrow set of commercial congestion data providers, creating input cost volatility when usage scales.
Strategic Opportunities
- Midlands logistics corridor penetration:Third-party logistics providers in England's central belt show underpenetrated demand for integrated traffic management modules combining congestion pricing with dynamic rerouting.
- AI-driven predictive modelling:Machine learning convergence with historical traffic pattern analysis enables carriers to pre-position assets before demand materializes.
- Carbon reporting automation:The Department for Transport's Future of Freight strategy tightens emission disclosure obligations, creating pull for optimization tools that generate audit-ready mileage documentation.
Industry Challenges
- Legacy system integration friction:Established British hauliers operate decades-old transport management systems that resist API connectivity with modern cloud-native routing platforms.
- Algorithmic transparency requirements:Driver unions and fleet managers demand explainable routing decisions, complicating deployment of black-box optimization engines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Route Optimization Software Market |
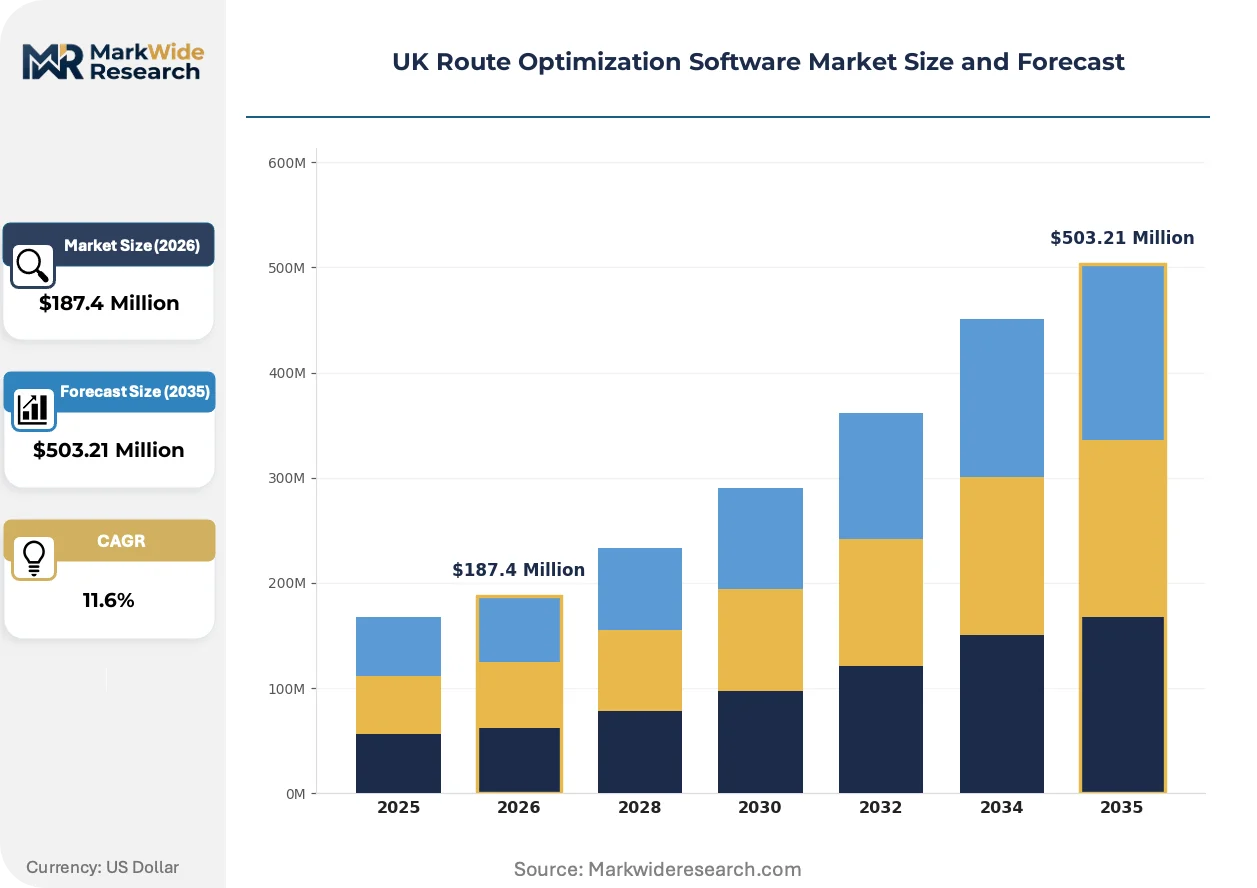
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Web-Based End User: Logistics, E-Commerce, Transportation, Retail Functionality: Real-Time Tracking, Route Planning, Traffic Management, Fleet Management Technology: Artificial Intelligence, Machine Learning, GPS, Analytics |
| Companies Covered | Microlise, Maxoptra, Paragon Software, Truckstops, Descartes Systems Group, Verizon Connect, Trimble, ORTEC, PTV Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Route Optimization Software Market Trends and Innovations
Combinatorial algorithms are absorbing real-time constraints at unprecedented speed. British fleet operators now expect routing engines to process driver hours, vehicle capacity, and delivery windows within single optimization cycles.
Machine learning is hybridizing with traditional operations research methods in British route optimization deployments. Predictive delay models now ingest weather patterns, sporting event schedules, and roadwork permits to forecast congestion before it materializes. Major grocery distributors are adopting these hybrid engines fastest, compressing planning cycles from hours to minutes.
The UK Information Commissioner's Office enforces GDPR-compliant location data handling with increasing stringency. Vendors must architect geofencing capabilities that anonymize driver identities while maintaining route accountability. Fleet operators serving London's Ultra Low Emission Zone are responding fastest, embedding privacy-by-design into procurement specifications.
Subscription-based platform access is displacing perpetual license purchases among British SMEs. Vehicle leasing networks now bundle routing software with monthly fleet contracts, unbundling what carriers previously bought as enterprise installations. This channel shift concentrates most visibly in England's South East corridor where mid-size hauliers dominate.
UK Route Optimization Software Market Segmentation
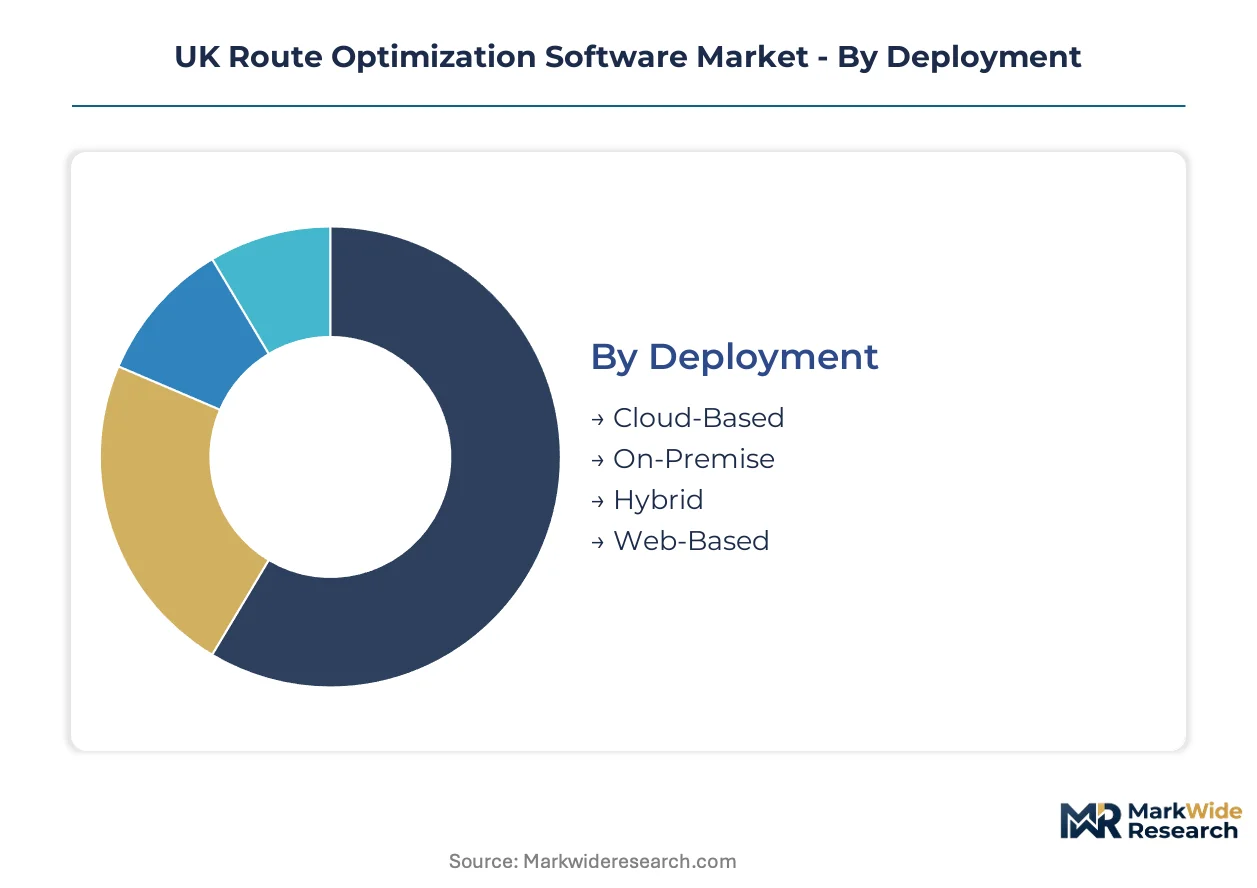
Route optimization software vendors in the United Kingdom engineer distinct deployment architectures and functionality modules to match the operational maturity of British fleet operators. Segmentation reveals how cloud-native platforms capture SME adoption while on-premise installations persist among legacy hauliers with complex integration requirements.
Deployment:
After-sales-service intensity varies sharply across deployment modes, with cloud-based installations demanding continuous vendor support for API maintenance and traffic data feeds while on-premise deployments require periodic engineering visits for algorithm updates.
- Cloud-Based:Multi-tenant SaaS architectures deliver automatic algorithm updates and elastic compute scaling for demand spikes. British grocery distributors in England's Midlands corridor favor this model for rapid deployment across seasonal capacity fluctuations without capital expenditure.
- On-Premise:Licensed software running on carrier-owned infrastructure satisfies data sovereignty requirements and enables deep customization of constraint-handling rules. Major British hauliers with decades-old transport management systems maintain this deployment to preserve legacy workflow integrations.
- Hybrid:Split architectures process sensitive driver data locally while offloading route computation to cloud engines. Fleet operators navigating GDPR compliance across London's Ultra Low Emission Zone increasingly specify this architecture.
- Web-Based:Browser-accessible platforms with minimal local installation target micro-fleets and owner-operators. Vehicle leasing networks in England's South East corridor bundle these solutions with monthly contract terms.
By volume, cloud-based deployments lead. By growth pace, hybrid architectures are expanding most quickly as compliance complexity deepens.
End User:
Application intensity shapes vendor product roadmaps, with logistics providers demanding multi-constraint optimization while retail chains prioritize customer-facing arrival predictions.
- Logistics:Third-party logistics providers serving fast-moving consumer goods sectors require dynamic rerouting across unpredictable demand spikes. These operators concentrate procurement investment in integrated traffic management modules.
- E-Commerce:Fulfilment networks demand real-time capacity balancing across British distribution hubs. Same-day delivery promises in urban corridors drive adoption of predictive delay modelling.
- Transportation:Passenger and freight carriers optimize driver hours against regulatory limits. The Department for Transport's Future of Freight strategy tightens emission disclosure obligations for this segment.
- Retail:Grocery chains and high-street brands prioritize customer arrival windows over pure mileage minimization. Store delivery scheduling in Birmingham, London, and Bristol Clean Air Zones forces emission-constrained route selection.
Logistics commands the largest installed base. E-commerce is gaining share fastest as fulfilment networks expand.
Functionality:
Margin pools concentrate differentially across capability modules, with real-time tracking commoditizing while traffic management commands premium pricing.
- Real-Time Tracking:GPS-based vehicle location monitoring represents the most mature capability with compressed margins. British SMEs lacking dedicated IT infrastructure treat this as table stakes in vendor selection.
- Route Planning:Combinatorial algorithms processing vehicle capacity, driver hours, and delivery windows form the core optimization engine. Major British hauliers anchor procurement decisions on constraint-handling sophistication.
- Traffic Management:Congestion pricing integration with dynamic rerouting captures expanding margin pools. Fleet operators serving England's Midlands corridor show underpenetrated demand for these integrated modules.
- Fleet Management:Unified platforms combining optimization with maintenance scheduling and fuel monitoring. Telematics convergence enables predictive delay modelling that reduces idle time at depots.
Route planning leads by revenue contribution. Traffic management shows the steepest expansion trajectory as Clean Air Zone enforcement tightens.
Technology:
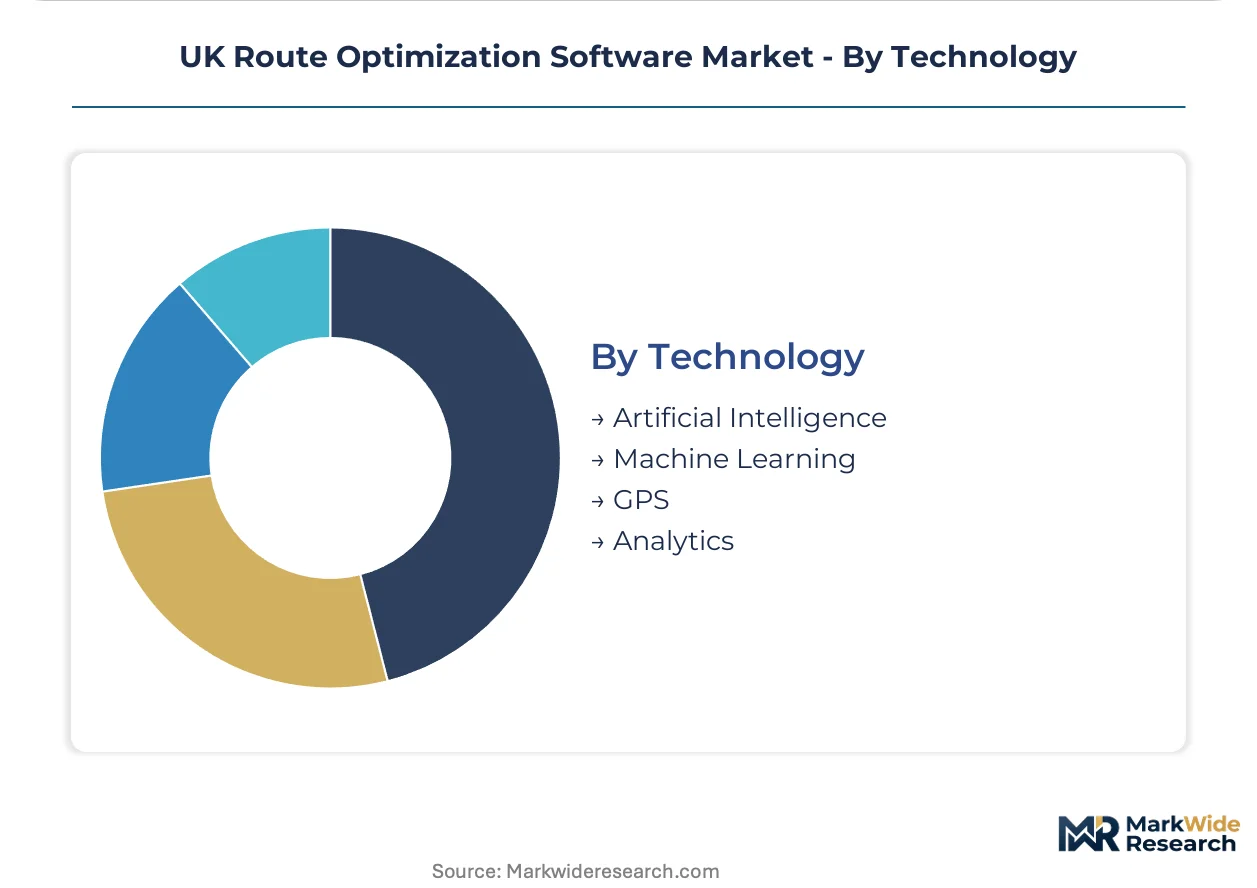
Technology selection determines architectural flexibility, with artificial intelligence representing the fastest-expanding segment as carriers invest in predictive capabilities.
- Artificial Intelligence:Neural networks and reinforcement learning enable predictive delay modelling before demand materializes. Grocery distributors compress planning cycles from hours to minutes using these engines.
- Machine Learning:Statistical models trained on historical traffic patterns forecast congestion from weather, sporting events, and roadwork permits. British fleet operators hybridize these with traditional operations research methods.
- GPS:Satellite positioning underpins real-time tracking and geofencing capabilities. The UK Information Commissioner's Office mandates GDPR-compliant location data handling that shapes how vendors architect these features.
- Analytics:Descriptive and diagnostic dashboards translate optimization outputs into operational KPIs. Carbon reporting automation for Department for Transport emission disclosure obligations depends on these capabilities.
GPS anchors the largest technology investment base. Artificial intelligence is climbing the fastest as predictive modelling becomes competitive necessity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
English logistics corridors deploy route optimization software with heavier emission-constraint weighting than Scottish or Welsh counterparts, reflecting denser Clean Air Zone enforcement and grocery fulfilment network concentration.
London and South East
The Ultra Low Emission Zone and expanding suburban fulfilment hubs drive demand for dynamic rerouting that minimizes daily charges. Transport for London's congestion pricing data feeds directly into carrier optimization engines. Dartford and Slough distribution centres anchor the densest deployment of predictive delay modelling for same-day grocery delivery.
Midlands
Birmingham's Clean Air Zone compels fleet operators to algorithmic route planning or face per-vehicle daily penalties. The Department for Transport's Future of Freight strategy tightens emission disclosure obligations for hauliers based in Coventry and Leicester. Third-party logistics providers in the M1/M6 corridor show underpenetrated demand for integrated traffic management modules.
North England
Manchester and Leeds logistics clusters prioritize cost minimization over emission constraints compared to southern counterparts. Local authority low-emission schemes remain less stringent than London or Birmingham equivalents. Liverpool port-connected hauliers adopt hybrid cloud architectures to balance GDPR-compliant driver data handling with route computation offload.
Scotland
Edinburgh and Glasgow low-emission zones follow English regulatory templates with lighter enforcement timelines. Scottish grocery distributors compress planning cycles using machine learning engines trained on narrower road-network datasets. Aberdeen's energy-sector logistics maintain distinct optimization priorities around remote site access rather than urban congestion.
Wales
Cardiff and Newport logistics operators face emerging clean air requirements that lag English implementation by 18-24 months. The Welsh Government's transport decarbonisation targets create regulatory pull for mileage-minimizing tools. Cross-border hauliers serving Bristol and Birmingham distribution hubs adopt English-standard optimization configurations.
UK Route Optimization Software Market Competitive Landscape
Capability concentration sits with telematics-heritage vendors; scale advantage sits with cross-border platform providers. The UK market structures around three tiers: legacy British routing specialists, North American fleet-technology conglomerates, and European optimization-engine vendors. Dominant competitive moves include channel partnerships with vehicle leasing networks and API integration with customs platforms for Brexit-complex supply chains.
Within the British heritage tier, Microlise and Paragon Software exemplify telematics-rooted positioning, while Maxoptra represents the cloud-native mid-market specialist. These anchors occupy positions between North American scale players and European algorithm developers, reflecting the market's structural segmentation around deployment architecture preferences and integration depth requirements.
| Leading Market Players |
|---|
| Microlise |
| Maxoptra |
| Paragon Software |
| Truckstops |
| Descartes Systems Group |
| Verizon Connect |
| Trimble |
| ORTEC |
| PTV Group |
| Others |
Pricing and Supply Chain Analysis
Traffic API providers in the United States and United Kingdom concentrate upstream data sourcing, anchoring margin pools in integrated congestion pricing modules rather than commoditized real-time tracking. British fleet operators face asymmetric pricing power as these narrow commercial feeds scale with usage.
Pricing Analysis
Subscription-based SaaS tiers dominate contract structures across British SMEs, while major hauliers negotiate multi-year enterprise licenses with embedded professional services. Price differentiation hinges on integration depth with legacy transport management systems and GDPR-compliant geofencing sophistication. Cost compression in the mid-market segment is intensifying because vehicle leasing networks bundle routing software with monthly fleet contracts. Micro-fleets and owner-operators exhibit highest price sensitivity, whereas grocery distributors prioritize constraint-handling sophistication over license cost.
Supply Chain Analysis
Cloud infrastructure providers in Ireland, Germany, and the United States hold contract-manufacturing capacity for British route optimization platforms. Algorithm development draws from open-source operations research libraries, proprietary traffic pattern datasets, and driver-hours regulatory databases. Single-source vulnerability concentrates in commercial congestion data APIs, where operator reliance on two dominant providers creates input cost volatility. Distribution runs through direct vendor sales teams for enterprise accounts and vehicle leasing network partnerships for SME penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Algorithmic talent capable of hybridizing machine learning with emission-constrained optimization remains scarce across British logistics technology, compressing competitive timelines for capability acquisition.
For Market Incumbents: Pre-empt cloud-native challengers by deepening API connectivity with decades-old transport management systems at major British hauliers. Invest in explainable routing engines to neutralize driver union resistance against black-box optimization. Channel control through exclusive vehicle leasing partnerships represents the priority defensive lever. For New Entrants and Emerging Players: Midlands third-party logistics providers serving the M1/M6 corridor represent the most penetrable entry point, showing underpenetrated demand for integrated traffic management modules. Hybrid deployment architectures addressing GDPR compliance across London's Ultra Low Emission Zone offer differentiated positioning. Go-to-market execution through direct engagement with fleet sustainability officers rather than IT procurement accelerates initial traction. For Investors and Strategic Acquirers: Secondary-cycle assets sit with telematics-heritage vendors seeking algorithmic capability bolt-ons to defend against AI-native challengers. Long-term viability across the projection horizon depends on predictive delay modelling sophistication and Clean Air Zone regulatory alignment. Monitor Birmingham and Bristol enforcement timeline acceleration as inflection indicator for demand compression or expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration with Legacy TMS | API connectivity with Paragon and Truckstops systems unlocks enterprise haulier accounts resistant to cloud migration. |
| Acquisition of Traffic Data Specialist | Vertical control over congestion pricing feeds neutralizes input cost volatility from commercial API providers. |
| Strategic Partnership with Vehicle Leasing Networks | Verizon Connect's channel dominance demonstrates bundling routes to SME market penetration at reduced CAC. |
| Geographic Expansion into Midlands Corridor | Coventry and Leicester distribution hubs face tightening Department for Transport emission disclosure obligations. |
| Product Launch: Explainable AI Routing Engine | Driver union transparency demands at British hauliers create procurement specification advantage over black-box competitors. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of Department for Transport policy documents, Transport for London congestion pricing disclosures, and UK Information Commissioner's Office GDPR enforcement records. Interviews with fleet operations directors, transport management system integrators, vehicle leasing network procurement leads, and Clean Air Zone compliance officers informed demand-side validation. Vendor-side perspectives came from product managers at telematics-heritage and cloud-native routing specialists. Secondary sources included Companies House filings, British Chambers of Commerce logistics surveys, and hyperscaler cloud infrastructure capex disclosures. Bottom-up sizing of installed fleet counts and top-down triangulation against software licensing revenue estimates anchored market value calculations.
Forecast inputs span deployment model adoption curves, Clean Air Zone expansion timelines, e-commerce fulfilment network capital expenditure patterns, and telematics convergence rates across British fleet operators. Segmentation modeling incorporates deployment architecture, end-user industry vertical, functionality module penetration, and underlying technology adoption. CAGRs derive from logistic curve fitting against historical adoption patterns and regulatory mandate enforcement schedules. Machine learning investment intensity and predictive delay modelling deployment velocity represent industry-specific demand drivers.
Stress conditions across API cost inflation, GDPR enforcement stringency escalation, and legacy system integration friction were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding Clean Air Zone geographic expansion and grocery distributor technology refresh cycles. Cross-checking against British Retail Consortium logistics cost benchmarks and Road Haulage Association fleet composition surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
AI Powered Home Solution Market
Digital Solutions
Revenue Management Solutions Market
Digital Solutions
Part-Time Job Platform Market
Digital Solutions
Container Orchestration Market
Digital Solutions
Business As a Service Market
Digital Solutions
Poland ICT Market
Digital Solutions
Price Optimization and Management Software Market
Digital Solutions
Landing Page Builders Market
Digital Solutions
Key Management As a Service (Kmaas) Market
Digital Solutions
Digital Certificates Market
Digital Solutions
Global Smart Workplace Market
Digital Solutions
Middle East and Africa Cloud Integration Market
Digital Solutions
Game Engines Market
Digital Solutions
Brazil Digital Twin Market
Digital Solutions
Global Data Collection and Labeling Market
Digital Solutions
Foot Traffic and Customer Location Intelligence Solution Market