
 Distribution Feeder Automation Market | 2026-2036
Distribution Feeder Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Distribution Feeder Automation Market Outlook
Silicon carbide is decoupling legacy copper-based switchgear economics in medium-voltage feeder applications. Eaton Corporation leverages vertical integration across power-distribution hardware to sustain cost advantages in North American utility deployments. ABB Ltd. anchors European market presence through IEC 61850-compliant intelligent electronic devices. Schneider Electric differentiates via end-to-end software platforms spanning SCADA to edge analytics for grid operators.
Distribution feeder automation encompasses intelligent switching, sensing, and control systems deployed on medium-voltage distribution networks to enable remote operation, fault isolation, and service restoration without manual intervention. These systems integrate recloser controllers, voltage sensors, and communication modules operating at 4–38 kV to reduce outage duration and optimize power flow. Hardware solutions for remote control and fault detection currently lead solution offerings, while software and integration services capture expanding margin pools as utilities pursue grid modernization. Self-healing automation types represent the fastest-growing segment as storm-hardening mandates intensify across coastal and tornado-prone service territories.
FERC Order 2222 and IEEE 1547 standards shape competitive requirements for distributed energy resource interoperability in US markets, while the EU Green Deal and F-Gas Regulation drive SF6-free switchgear transitions across European utilities. India's CEA grid codes and China's GB standards for smart distribution equipment tighten product certification thresholds for market access. Stakeholders must monitor evolving interoperability standards and carbon-accounting rules that will determine supplier qualification criteria in upcoming utility procurement cycles.
Market Dynamics
Silicon carbide power electronics is compressing switchgear cost curves while India's CEA mandates and China's dual carbon goals force utilities toward self-healing architectures. This technology-regulatory squeeze is restructuring supplier qualification criteria and procurement priorities across medium-voltage distribution networks.
Growth Catalysts
- CEA Grid Code Mandates:India's Central Electricity Authority mandates for fault isolation and restoration timelines are forcing state distribution companies toward automated recloser deployments in Maharashtra and Gujarat.
- Dual Carbon Goals:China's provincial carbon intensity targets are accelerating SF6-free switchgear transitions in coastal utilities across Jiangsu and Zhejiang provinces.
- Storm-Hardening Directives:US state-level resilience mandates in Florida and Texas are prioritizing self-healing automation for hurricane and tornado-prone feeder circuits.
Market Restraints
- Copper Price Volatility:Legacy copper-dependent switchgear architectures face margin compression when London Metal Exchange copper prices spike, disadvantaging cost-sensitive municipal utilities.
- Semiconductor Supply Concentration:Silicon carbide substrate production concentrates in specific Asian manufacturing clusters, creating single-source vulnerability for power module suppliers.
- IEC 61850 Interoperability Gaps:Incomplete implementation of manufacturing message specification profiles creates integration friction between multi-vendor intelligent electronic devices.
Strategic Opportunities
- Rural Electrification Gaps:India's western states of Rajasthan and Madhya Pradesh present underpenetrated terrain for remote-controlled sectionalizer deployments where manual switching still dominates.
- Distributed Energy Convergence:IEEE 1547-2018 compliance requirements for inverter-based resources are creating bundled automation-software procurement opportunities at the distribution edge.
- EU Green Deal Tailwind:The F-Gas Regulation's phase-down schedule is accelerating SF6-free vacuum interrupter adoption across German and French distribution network operators.
Industry Challenges
- Cybersecurity Certification Timelines:NERC CIP compliance validation for communication-enabled feeder devices extends product launch cycles by 12-18 months for North American suppliers.
- Legacy SCADA Integration:Proprietary protocols in installed DMS platforms force expensive middleware development for brownfield automation deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Distribution Feeder Automation Market |
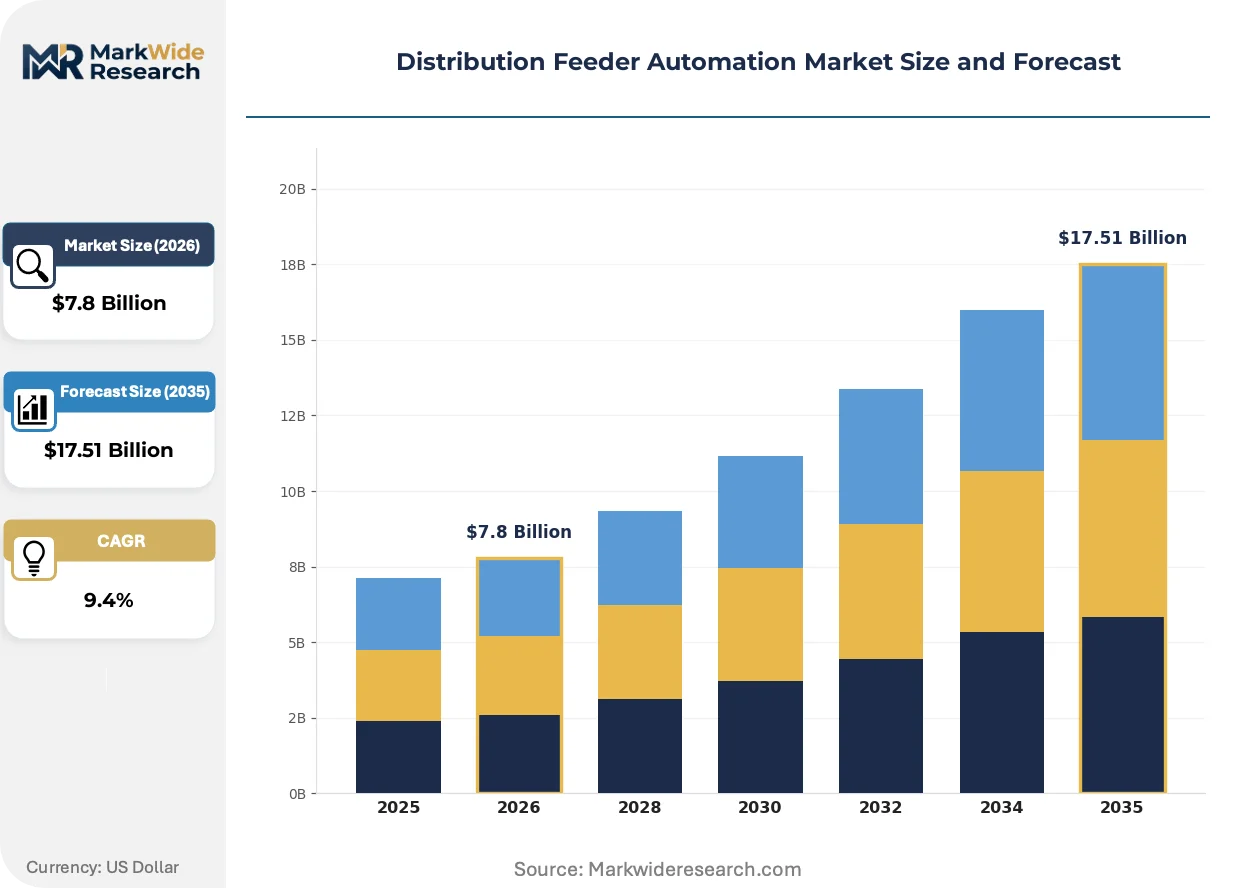
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $17.51 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Automation Type: Remote Control, Fault Detection, Load Management, Voltage Regulation, Self-Healing, Demand Response Solution Offering: Hardware, Software, Communication, Services, Integration, Consulting Application: Electric Utilities, Smart Grids, Renewable Integration, Microgrids, Energy Storage, Grid Modernization End User: Power Distributors, Municipal Corporations, Transmission Providers, Grid Operators, Energy Service Companies, Independent Power Producers |
| Companies Covered | Eaton Corporation, Hitachi Energy, ABB Ltd., GE Vernova Inc., G&W Electric Co., Schneider Electric, General Electric Company, Schweitzer Engineering Laboratories Inc., Siemens AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Distribution Feeder Automation Market Strategic Shifts
Digital twin architectures are migrating from transmission to distribution planning workflows, while edge computing hardware shrinks latency budgets for fault location algorithms. These shifts are compressing the traditional separation between planning software and real-time control systems.
Silicon carbide MOSFETs are expanding into medium-voltage recloser controllers by enabling higher switching frequencies at reduced thermal losses. European utilities in Germany and the Netherlands are piloting these devices for 24 kV applications. This expansion is compressing the total cost of ownership gap against traditional silicon IGBTs in 4-15 kV feeder segments.
The EU F-Gas Regulation's mandatory SF6 phase-down is forcing vacuum interrupter and dry air insulation development across European switchgear manufacturers. This policy is accelerating product redesign cycles and disqualifying legacy gas-insulated designs from public utility tenders. German distribution network operators are responding with accelerated procurement of alternative insulation technologies ahead of 2030 deadlines.
Utility procurement teams are unbundling hardware and software contracts that were historically packaged as turnkey automation projects. This fragmentation is elevating specialized analytics vendors and compressing margins for integrated equipment suppliers. The shift is most visible in US investor-owned utilities where capital allocation scrutiny from state public utility commissions favors modular, milestone-based contracting.
Distribution Feeder Automation Market Segmentation
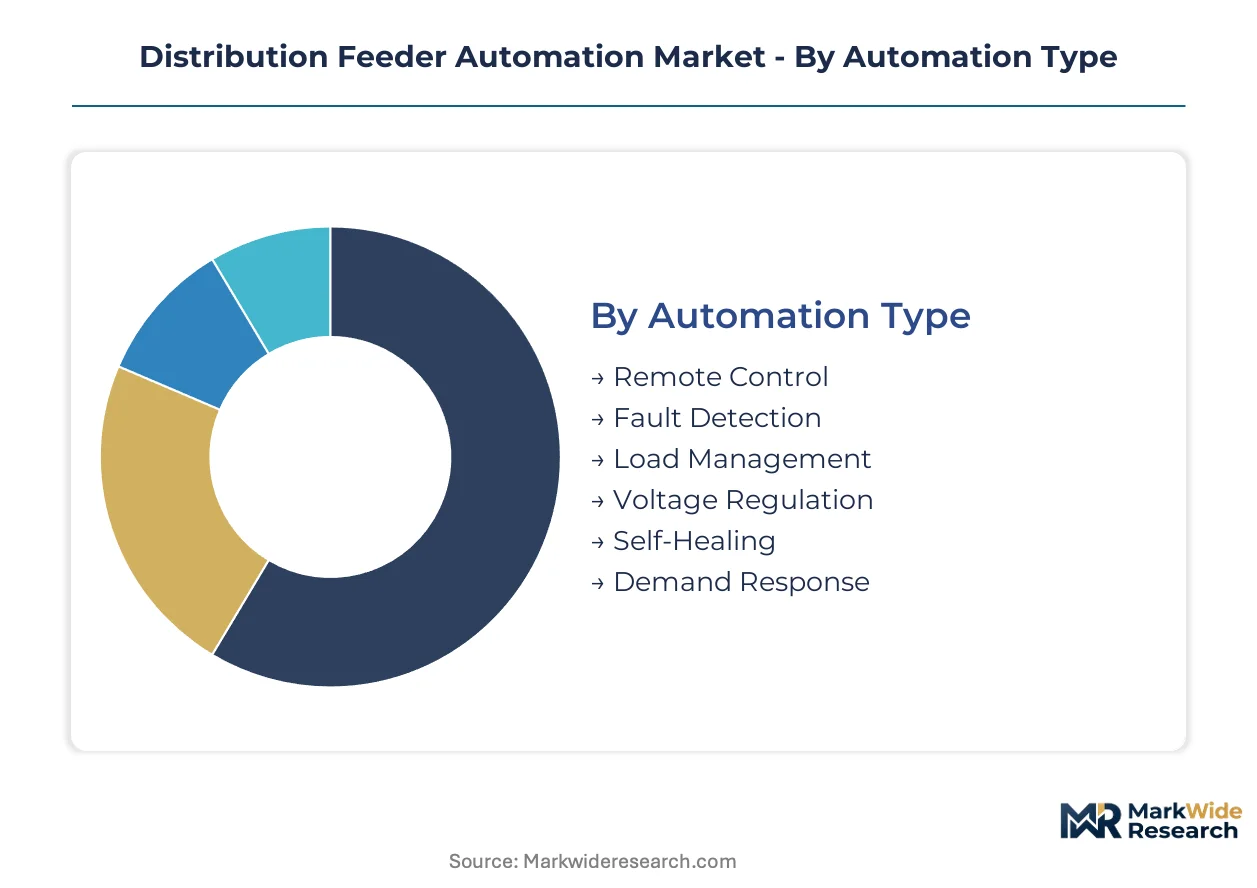
Segmentation in distribution feeder automation reveals how technology deployment varies by integration depth, from standalone recloser controllers to fully orchestrated self-healing architectures. Understanding these layers helps suppliers align R&D investments with procurement patterns across hardware-centric utilities and software-forward grid operators.
Automation Type:
Remote control and fault detection functions operate as standalone modules in legacy deployments, while self-healing and demand response capabilities require deeper SCADA integration and real-time communication infrastructure.
- Remote Control:Recloser controllers and sectionalizer switches enable manual or scheduled switching operations from distribution control centers. Demand concentrates in India's Maharashtra and Gujarat states where CEA mandates are accelerating state distribution company procurement of remote-operable devices.
- Fault Detection:Voltage sensors and fault current indicators locate line disturbances without full automation integration. China's Jiangsu province utilities are prioritizing these systems as transitional investments toward complete feeder automation architectures under provincial carbon intensity targets.
- Load Management:Peak shaving through automated load transfer schemes.
- Voltage Regulation:Capacitor bank switching and tap changer control for power quality.
- Self-Healing:Autonomous fault isolation and service restoration algorithms.
- Demand Response:Load curtailment coordination with distributed energy resources.
Remote control leads volumes today; self-healing is gaining share fastest as storm-hardening mandates intensify across hurricane-prone service territories.
Solution Offering:
Cost tier separation distinguishes capital-intensive hardware procurement from recurring software subscriptions, with integration services capturing premium margins in brownfield deployments requiring legacy SCADA bridging.
- Hardware:Physical switchgear, sensors, and controllers deployed at 4–38 kV. Municipal corporations in cost-sensitive markets favor hardware-only procurement to minimize ongoing operational expenditures.
- Software:SCADA platforms, DMS modules, and edge analytics for real-time feeder monitoring. Grid operators in Germany and the Netherlands are piloting silicon carbide-enabled control algorithms for 24 kV applications.
- Communication:Fiber, cellular, and radio modules for field device connectivity.
- Services:Maintenance contracts and technical support agreements.
- Integration:Middleware development for multi-vendor system interoperability.
- Consulting:Grid modernization planning and automation roadmapping.
Hardware dominates procurement value today; software subscriptions are expanding most quickly as utilities unbundle historically turnkey automation contracts.
Application:
Application scope ranges from conventional electric utility feeder circuits to emerging microgrid and energy storage configurations requiring bidirectional power flow management.
- Electric Utilities:Traditional distribution network automation for outage reduction. Investor-owned utilities in Florida and Texas are prioritizing hurricane resilience through automated feeder sectionalization.
- Smart Grids:Integrated sensing, communication, and control for real-time network optimization. China's coastal provinces are deploying these systems to meet dual carbon goals through loss reduction.
- Renewable Integration:Interconnection management for solar and wind distributed generation.
- Microgrids:Islanding detection and resynchronization for localized power systems.
- Energy Storage:Battery dispatch coordination with feeder load profiles.
- Grid Modernization:Comprehensive infrastructure upgrades replacing electromechanical protection.
Electric utilities anchor deployment volumes today; renewable integration is climbing the fastest as IEEE 1547-2018 compliance requirements expand.
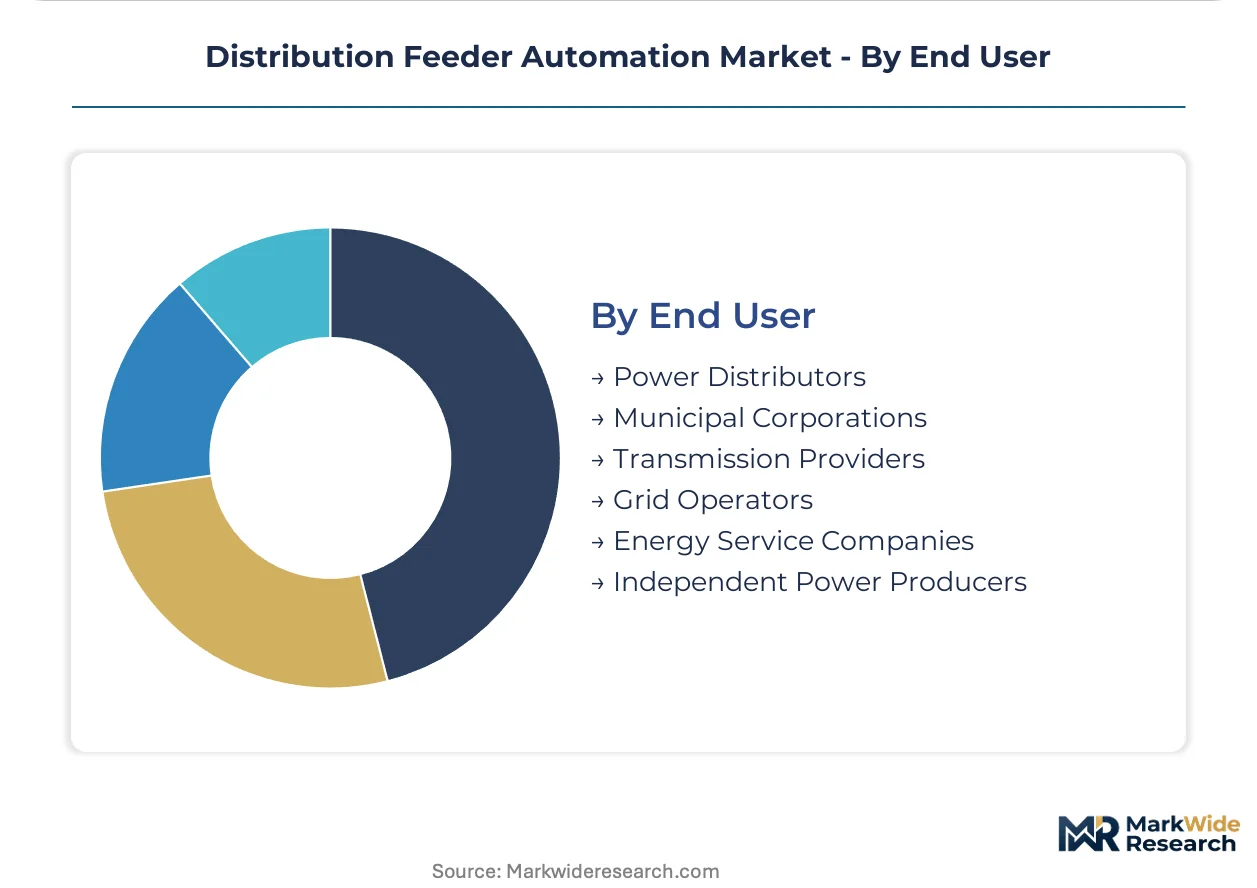
End User:
Customer type segmentation reflects divergent procurement authority, from centralized transmission providers to fragmented municipal corporations with varying technical capabilities.
- Power Distributors:Investor-owned and publicly owned utilities with distribution network responsibility. State distribution companies in India's western states are the primary demand source for remote-controlled sectionalizers.
- Municipal Corporations:City-owned utilities with limited automation expertise and constrained capital budgets. These entities favor modular, milestone-based contracting over turnkey system procurement.
- Transmission Providers:Grid-scale operators with limited distribution automation scope.
- Grid Operators:Independent system operators and regional transmission organizations.
- Energy Service Companies:Third-party contractors delivering efficiency and reliability services.
- Independent Power Producers:Non-utility generators requiring interconnection automation.
Power distributors command the largest procurement volumes today; energy service companies are expanding most quickly as performance-based contracting models proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jiangsu province's coastal utilities anchor demand concentration for self-healing grid architectures. India's western states and Germany's distribution network operators follow as secondary demand poles shaped by tightening reliability mandates and carbon transition deadlines.
United States
Florida and Texas utilities prioritize hurricane resilience through automated feeder sectionalization. FERC Order 2222 and IEEE 1547 standards mandate distributed energy resource interoperability. Storm-hardening directives from state regulators accelerate procurement in Gulf Coast and tornado-prone service territories.
China
Jiangsu and Zhejiang provincial utilities deploy SF6-free switchgear under dual carbon intensity targets. GB standards for smart distribution equipment tighten product certification thresholds. Yangtze River Delta utilities pilot silicon carbide-enabled recloser controllers for 24 kV applications.
India
Maharashtra and Gujarat state distribution companies accelerate remote-controlled recloser deployments. Central Electricity Authority grid codes mandate fault isolation and restoration timelines. Rajasthan and Madhya Pradesh present underpenetrated terrain where manual switching still dominates rural feeder circuits.
Germany
Distribution network operators accelerate vacuum interrupter procurement ahead of EU F-Gas Regulation deadlines. The Green Deal's carbon-accounting rules disqualify legacy gas-insulated switchgear from public tenders. Baden-Württemberg and Bavarian utilities lead pilot programs for dry air insulation technologies.
Distribution Feeder Automation Market Competitive Environment
Global majors compete with regional champions across hardware standardization and software integration capabilities. The supplier base organizes into three tiers: integrated electrical equipment conglomerates with captive silicon carbide supply, specialized protection and control device manufacturers, and software-native analytics vendors capturing unbundled procurement contracts. Consolidation pressure intensifies as utilities fragment historically turnkey automation projects into modular, milestone-based contracting. Dominant competitive moves include backward integration into power semiconductor supply chains and strategic partnerships for IEC 61850 interoperability middleware.
Within the integrated equipment tier, Eaton Corporation and ABB Ltd. exemplify divergent geographic anchoring strategies. Eaton's North American utility relationships position it for FERC-driven distributed energy convergence opportunities. ABB's European market presence leverages IEC 61850-compliant intelligent electronic devices for Green Deal-aligned SF6-free transitions. Schneider Electric occupies a software-forward position spanning SCADA to edge analytics as procurement patterns shift toward unbundled contracts.
| Leading Market Players |
|---|
| Eaton Corporation |
| Hitachi Energy |
| ABB Ltd. |
| GE Vernova Inc. |
| G&W Electric Co. |
| Schneider Electric |
| General Electric Company |
| Schweitzer Engineering Laboratories Inc. |
| Siemens AG |
| Others |
Value Chain & Pricing Dynamics
India's CEA-mandated fault isolation timelines and China's dual carbon intensity targets are compressing procurement cycles for SF6-free switchgear and silicon carbide-enabled controllers, forcing suppliers to absorb certification costs while competing on total cost of ownership metrics that favor modular hardware-software bundles over legacy copper architectures.
Pricing Analysis
Input-cost pass-through from silicon carbide substrate and copper conductor volatility is reshaping procurement economics across medium-voltage feeder segments. Three-tier pricing structure across premium IEC 61850-certified, standard utility-grade, and economy municipal-tier equipment dominates, with certification level and after-sales service bundling as primary differentiation drivers. Cost compression in economy-tier hardware is intensifying because state distribution companies in India prioritize capital expenditure minimization over lifecycle optimization. Municipal corporations exhibit highest price sensitivity; investor-owned utilities in storm-prone US territories demonstrate lowest sensitivity due to resilience-mandated procurement timelines.
Supply Chain Analysis
Certification gating through IEC 61850 compliance and F-Gas Regulation alignment restricts supplier qualification to a narrow tier of vertically integrated electrical equipment conglomerates. Manufacturing concentrates in China, Germany, and the United States, with silicon carbide wafer fabrication drawing from specialized Asian substrate foundries and copper winding assemblies resting on London Metal Exchange price exposure. Single-source vulnerability in silicon carbide power module supply creates structural risk for recloser controller production. Distribution runs through direct utility procurement channels and specialized electrical distributor networks serving municipal and cooperative utilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in distribution feeder automation hinges on silicon carbide cost-down curves displacing legacy silicon IGBTs, while premium-tier shifts toward software-subscription revenue streams capture recurring value from unbundled procurement patterns.
For Market Incumbents: Lock in silicon carbide supply agreements with substrate manufacturers to secure cost advantages as power module competition intensifies. Defend position by accelerating IEC 61850 middleware development to capture integration services revenue from brownfield SCADA deployments threatened by proprietary protocol fragmentation. Prioritize certification investment for F-Gas Regulation compliance ahead of 2030 deadlines to disqualify non-compliant rivals from European utility tenders. For New Entrants and Emerging Players: The premium-economy price-point gap in India's western states creates white-space opportunity for remote-controlled sectionalizers targeting Rajasthan and Madhya Pradesh rural electrification gaps. Target software-analytics modules for unbundled procurement contracts at US investor-owned utilities where capital allocation scrutiny favors milestone-based contracting. Deploy partnership-based go-to-market models with established channel partners to bypass direct utility qualification timelines. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized protection and control device manufacturers possessing captive silicon carbide module design capabilities and established IEC 61850 interoperability credentials. Long-term viability over the next decade favors suppliers with backward integration into power semiconductor supply chains and software-forward platform architectures. Watch for inflection where EU F-Gas Regulation enforcement accelerates vacuum interrupter procurement velocity as signal of structural supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Supply Agreement | Secures substrate access for 24 kV recloser controller cost advantages against silicon IGBT incumbents. |
| IEC 61850 Middleware Development | Captures integration services margin from brownfield SCADA deployments with proprietary protocol legacy. |
| SF6-Free Vacuum Interrupter Certification | Qualifies for EU Green Deal-aligned tenders ahead of F-Gas Regulation phase-down deadlines. |
| Software-Subscription Platform Launch | Addresses unbundled procurement preferences at US investor-owned utilities under PUC capital scrutiny. |
| Rural Electrification Channel Partnership | Accelerates market penetration in India's underpenetrated western states through local distributor networks. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with utility planning officers, distribution automation procurement leads, SCADA integration specialists, and silicon carbide power module engineers with secondary validation against FERC filings, CEA grid code notifications, EU F-Gas Regulation implementation guidance, and IEC standard committee documentation. Bottom-up equipment shipment tracking and top-down utility capital expenditure analysis provided triangulation across market sizing estimates.
Segment-weighting across automation type, solution offering, application scope, and end-user procurement authority anchored the analytical framework throughout the projection horizon. CAGRs were derived from modeled adoption curves for self-healing architectures against storm-hardening mandate timelines and carbon-transition deadlines. Forecast inputs incorporated silicon carbide cost-down assumptions and IEEE 1547-2018 compliance-driven distributed energy resource interoperability demand.
Caveats apply where semiconductor supply concentration, copper price volatility, or cybersecurity certification timeline extensions could materially shift the outlook. Forecasts reflect documented assumptions regarding regulatory enforcement velocity and technology substitution rates. A model refresh is warranted upon material change in EU F-Gas Regulation phase-down schedules or India's CEA mandate implementation pace.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Europe Process Automation Market
Industrial Automation
Global Industrial Wireless Automation Market
Industrial Automation
Global Operational Technology Market
Industrial Automation
Warehouse Automation Equipment Market
Industrial Automation
Sortation Systems Market
Industrial Automation
Mini-Load Systems Market
Industrial Automation
Human Machine Interface (HMI) Market
Industrial Automation
Rotary Vector (RV) Reducer Market
Industrial Automation
Programmable Logic Controller [PLC] Market
Industrial Automation
Asia-Pacific Automation Components Market
Industrial Automation
Predictive Maintenance Market
Industrial Automation
Europe Sortation Systems Market
Industrial Automation
Asia Pacific Sortation Systems Market
Industrial Automation
Global Industrial Control and Factory Automation Market
Industrial Automation
Liquid Handling Technology Market
Industrial Automation
North America Industrial Automation Market