
 India Warehouse Automation Market | 2026-2036
India Warehouse Automation Market Size, Share, and Industry Trends Forecast 2026-2036
India Warehouse Automation Market Outlook
Autonomous mobile robotics is fragmenting traditional fixed-conveyor warehouse layouts across Indian distribution networks. Addverb Technologies sustains technology leadership through in-house production of AMR fleets and AI-driven orchestration software. GreyOrange dominates sortation robotics for large-format e-commerce hubs, while Falcon Autotech navigates mid-market penetration with modular conveyor-to-robot retrofit kits.
Warehouse automation encompasses the integration of mechanized handling equipment, sensor networks, and control software to execute storage, retrieval, sorting, and dispatch operations with minimal human intervention; systems typically achieve throughput rates of 1,500–4,000 picks per hour depending on SKU profile and robot configuration. The primary commercial purpose centers on compressing order cycle times while reducing labor dependency in high-velocity fulfillment environments. Robotics and Automated Guided Vehicles command the deepest investment pools as 3PL operators replace legacy pallet jacks with vision-guided systems. Software Solutions is expanding fastest as warehouse management platforms shift toward cloud-native, API-first architectures that integrate with ONDC and Flipkart marketplace stacks. Integrated Systems retains the densest margin concentration due to the engineering intensity of combining hardware fleets with customer-specific WMS layers.
BIS safety certification requirements and the CEA electrical standards framework shape equipment procurement decisions, compelling vendors to redesign power systems and emergency-stop architectures for Indian voltage conditions and ambient temperature ranges. The PLI scheme for specialty steel and electronics manufacturing indirectly subsidizes domestic robot frame production, altering total cost of ownership calculations for buyers. Stakeholders must monitor how ONDC's open-network fulfillment protocols reshape warehouse location strategy and automation density requirements across tier-2 and tier-3 cities.
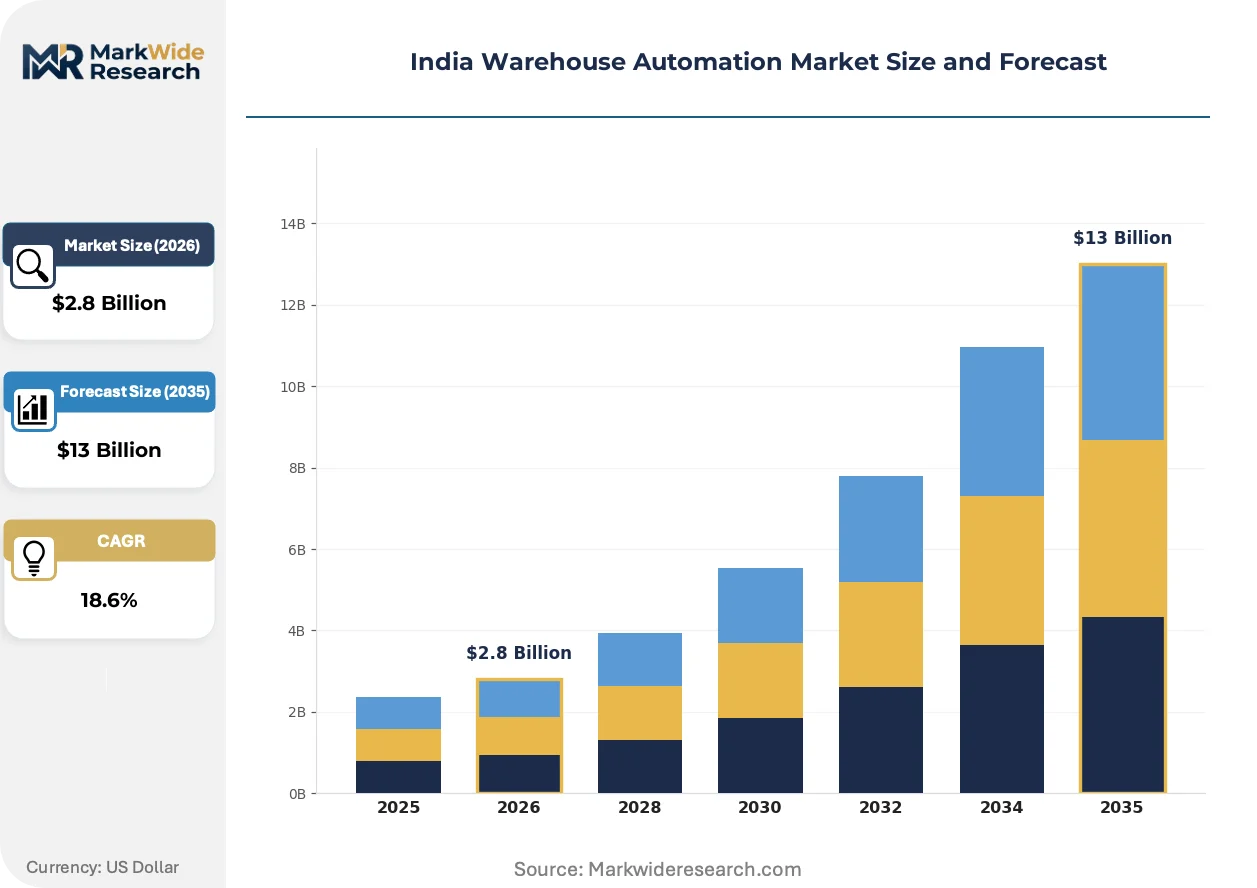
Market Dynamics
Autonomous mobile robotics is virtualizing fixed-conveyor warehouse layouts across Indian distribution networks, while BIS certification mandates and the PLI scheme for specialty steel reshape equipment procurement economics and domestic manufacturing incentives.
Growth Catalysts
- E-commerce Fulfillment Velocity:Same-day delivery promises from Flipkart and Amazon India are compressing order cycle times and forcing 3PL operators to deploy robotic picking systems in Maharashtra's Mumbai-Pune corridor.
- BIS Safety Mandates:The Bureau of Indian Standards certification requirement for industrial safety equipment is accelerating replacement of legacy material handling systems with compliant automation architectures.
- PLI Subsidy Leverage:The Production Linked Incentive scheme for electronics manufacturing is reducing total cost of ownership for domestically produced robot frames and control systems.
Market Restraints
- Capital Intensity Barrier:Integrated warehouse automation systems require upfront investment exceeding INR 50 crore for large-format fulfillment centers, constraining mid-market 3PL adoption.
- Power Infrastructure Variance:Voltage fluctuation tolerance gaps between European-designed equipment and Indian grid conditions force costly electrical redesigns for imported robotics.
- Specialized Talent Scarcity:Shortage of WMS-robotics integration engineers limits deployment velocity for multi-vendor automation stacks.
Strategic Opportunities
- Tier-2 City Penetration:ONDC's open-network fulfillment protocols are decentralizing warehouse location strategy toward Lucknow, Indore, and Coimbatore, creating demand for modular automation retrofit kits.
- Cloud-Native WMS Convergence:API-first warehouse management platforms integrating with Flipkart marketplace stacks represent the fastest-expanding software segment.
- Retrofit-First Positioning:Mid-market penetration through conveyor-to-robot modular kits addresses brownfield facilities unwilling to greenfield automate.
Industry Challenges
- Multi-Vendor Integration Complexity:Orchestrating AMR fleets from different suppliers with customer-specific WMS layers creates engineering bottlenecks and commissioning delays.
- Ambient Temperature Hardening:CEA electrical standards and Indian ambient temperature ranges exceed design specifications of temperate-climate robotics, requiring thermal management retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Warehouse Automation Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Automated Guided Vehicles, Robotics, Conveyor Systems, Sortation Systems Application: Order Fulfillment, Inventory Management, Packaging, Shipping End User: E-Commerce, Retail, Manufacturing, Pharmaceuticals Product Type: Software Solutions, Hardware Solutions, Integrated Systems, Consulting Services |
| Companies Covered | Alligator Automations, Armstrong Machine Builders Pvt. Ltd, Addverb Technologies Pvt. Ltd, Unbox Robotics, Clearpack India Pvt. Ltd, GreyOrange, Alstrut India Private Limited, Warehouse Now, Falcon Autotech Pvt. Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Warehouse Automation Market Strategic Shifts
Software-defined orchestration is displacing hardware-centric warehouse control, while regulatory pressure on safety certification and open-network commerce protocols reshape competitive positioning.
Digital twin platforms are virtualizing warehouse layout optimization and throughput simulation before physical deployment. Large-format e-commerce hubs in the Mumbai-Pune corridor are adopting these tools to de-risk capital commitments. The technology is virtualizing traditional design-build-operate sequences into iterative software-first workflows.
The BIS certification mandate for industrial safety equipment is compelling vendors to redesign emergency-stop architectures and power systems for Indian voltage conditions. Domestic manufacturers are accelerating compliant product development to capture procurement preference from safety-conscious buyers. Maharashtra-based fulfillment centers are prioritizing BIS-certified architectures to preempt regulatory enforcement.
Buyer procurement patterns are fragmenting from single-vendor turnkey contracts toward best-of-breed component sourcing. 3PL operators are unbundling AMR hardware, WMS software, and integration services across specialized suppliers. This shift is most visible among mid-market logistics providers in Gujarat and Karnataka seeking vendor flexibility over bundled solutions.
India Warehouse Automation Market Segmentation
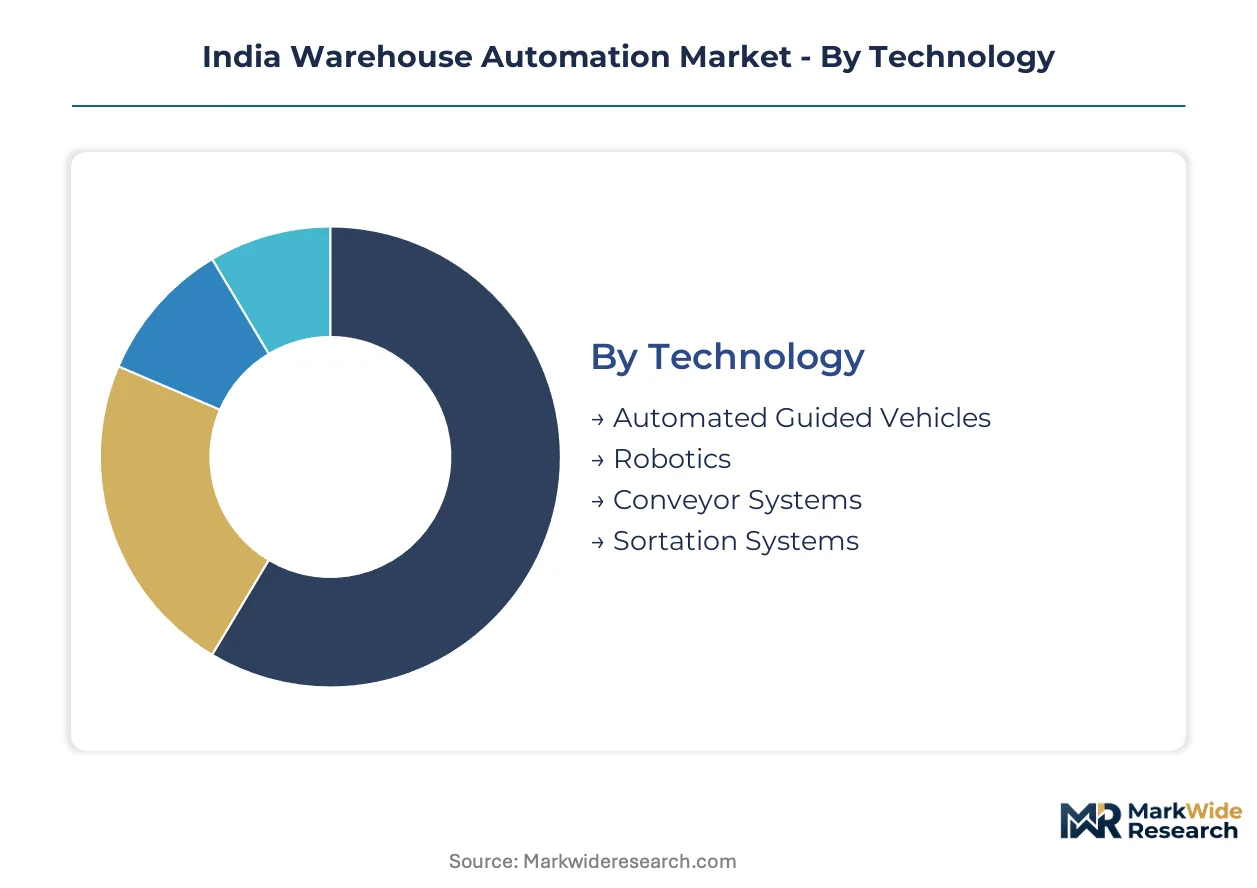
Segmentation reveals how capital deployment, regulatory compliance, and fulfillment velocity create distinct technology adoption patterns across Indian warehouse operations. Understanding these divides exposes where margin concentrates and where growth accelerates.
Technology:
After-sales service intensity varies sharply across technology categories, with mobile robotics demanding continuous fleet management while fixed infrastructure requires periodic overhaul cycles.
- Robotics:Articulated arms and collaborative picking robots execute high-SKU-density retrieval with vision-guided precision. Maharashtra's Mumbai-Pune corridor concentrates deployment as Flipkart and Amazon India compress same-day delivery windows.
- Automated Guided Vehicles:Vision-guided mobile platforms replace legacy pallet jacks in 3PL networks, requiring intensive fleet orchestration software support. BIS certification mandates for safety systems are accelerating replacement of imported temperate-climate designs with Indian-hardened architectures.
- Conveyor Systems:Belt and roller configurations handle bulk flow between zones.
- Sortation Systems:Cross-belt and tilt-tray technologies direct parcels to shipping lanes.
By volume, Conveyor Systems leads. By growth pace, Robotics is ahead.
Application:
Cost tier stratification separates premium orchestration software from commodity hardware, with integration complexity scaling non-linearly across application types.
- Order Fulfillment:Multi-SKU picking, packing, and dispatch orchestration demands real-time WMS-robotics integration. E-commerce hubs in Gujarat and Karnataka are unbundling AMR hardware from software to preserve vendor flexibility.
- Inventory Management:Cycle counting, put-away optimization, and slotting algorithms compress carrying costs. 3PL operators in tier-2 cities deploy modular retrofit kits rather than greenfield automation.
- Packaging:Automated dimensioning, void-fill, and label application stations.
- Shipping:Manifest generation, carrier sortation, and dock door assignment systems.
Order Fulfillment commands the densest software margins. Inventory Management is climbing the fastest as ONDC decentralizes warehouse location strategy.
End User:
Customer type determines procurement authority structure, with centralized corporate engineering teams driving integrated system decisions versus distributed operations managers selecting point solutions.
- E-Commerce:High-velocity fulfillment centers with same-day delivery mandates drive robotic picking density. The PLI scheme for electronics manufacturing reduces total cost of ownership for domestically produced robot frames.
- Retail:Omnichannel distribution networks balancing store replenishment with direct-to-consumer shipment.
- Manufacturing:Inbound material sequencing and finished goods staging for just-in-time production lines.
- Pharmaceuticals:Temperature-controlled storage with batch traceability and serialization compliance under CDSCO regulations.
E-Commerce anchors capital deployment. Pharmaceuticals shows the steepest expansion trajectory as cold-chain automation hardens against ambient temperature extremes.
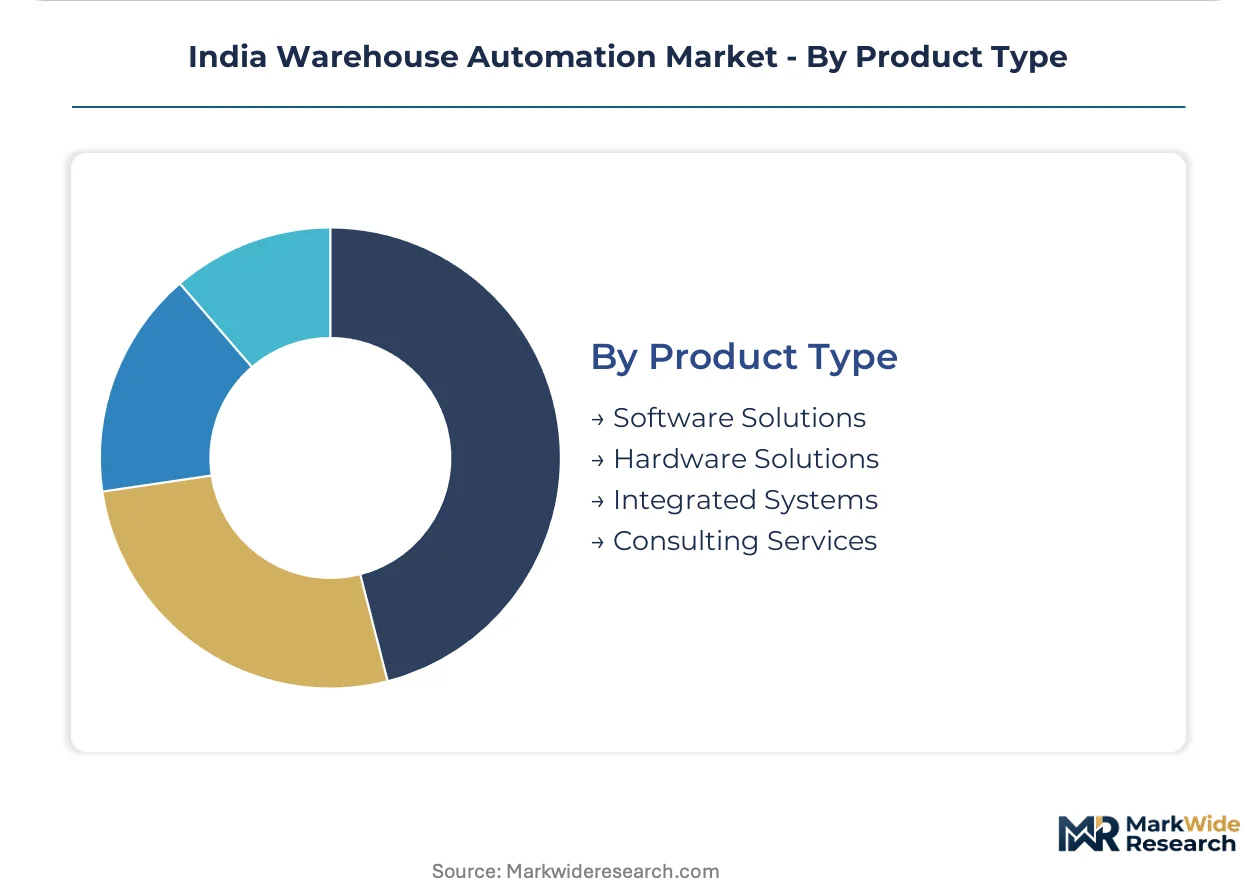
Product Type:
Supply concentration shapes competitive dynamics, with domestic control system vendors capturing share from European imports as BIS and CEA standards tighten procurement specifications.
- Integrated Systems:Combined hardware fleets with customer-specific WMS layers and commissioning services. Engineering intensity sustains margin concentration despite long sales cycles.
- Software Solutions:Cloud-native, API-first warehouse management platforms integrating with Flipkart marketplace stacks and ONDC protocols. Subscription revenue models are displacing perpetual licenses.
- Hardware Solutions:Standalone conveyors, shuttles, and robotic cells without orchestration software.
- Consulting Services:Layout optimization, digital twin simulation, and change management for brownfield retrofits.
Integrated Systems leads by revenue per deployment. Software Solutions is gaining share fastest as buyers unbundle procurement across specialized vendors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's warehouse automation sector traces its supply corridors through the Mumbai-JNPT maritime gateway, where imported robotic components from Germany and South Korea feed into Maharashtra's fulfillment hub network before redistributing to tier-2 consumption centers.
Maharashtra
Flipkart and Amazon India compress same-day delivery windows across the Mumbai-Pune logistics corridor. BIS certification mandates for industrial safety equipment accelerate replacement of legacy material handling systems with compliant automation architectures. Pune's Chakan industrial belt hosts the densest concentration of robotic picking deployments for e-commerce fulfillment centers.
Gujarat
Mid-market 3PL operators seek vendor flexibility through unbundled AMR hardware and software procurement. The state's electronics manufacturing zones leverage PLI scheme subsidies to reduce total cost of ownership for domestically produced robot frames. Ahmedabad and Surat emerge as testing grounds for modular conveyor-to-robot retrofit kits in brownfield warehouses.
Karnataka
Bengaluru's technology services ecosystem feeds cloud-native WMS platform development with API-first architectures integrating Flipkart marketplace stacks. CDSCO pharmaceutical regulations drive cold-chain automation hardening against ambient temperature extremes. The city's Whitefield logistics cluster attracts software-defined orchestration vendors targeting omnichannel retail networks.
Tamil Nadu
Coimbatore's precision engineering base supplies robot frame components to domestic automation integrators. CEA electrical standards compel power system redesigns for European-designed equipment facing Indian grid voltage fluctuations. Sriperumbudur's automotive supplier parks deploy inbound material sequencing automation for just-in-time production lines.
Telangana
Hyderabad's pharmaceutical and biotechnology corridors demand batch traceability and serialization compliance under CDSCO cold-chain regulations. ONDC open-network fulfillment protocols decentralize warehouse location strategy toward tier-2 cities. The city's Genome Valley life sciences cluster anchors temperature-controlled storage automation with serialization tracking systems.
India Warehouse Automation Market Competitive Environment
On the supply side, the industry is consolidating around three strategic tiers: integrated system providers commanding premium engineering margins, modular retrofit specialists capturing mid-market brownfield conversions, and pure-play software vendors extracting recurring revenue from cloud-native orchestration platforms. Competitive dynamics center on vertical integration into in-house AMR production versus best-of-breed component sourcing, alongside geographic expansion into tier-2 fulfillment corridors.
Within the integrated system tier, Addverb Technologies and GreyOrange exemplify contrasting scale strategies. Addverb Technologies anchors the domestic in-house production archetype through captive AMR fleet manufacturing and proprietary AI-driven orchestration software. GreyOrange occupies the large-format hub specialist position with sortation robotics deployments concentrated in Maharashtra's e-commerce corridor. Falcon Autotech represents the modular retrofit vector, targeting mid-market penetration with conveyor-to-robot kits that minimize capital displacement in existing facilities.
| Leading Market Players |
|---|
| Alligator Automations |
| Armstrong Machine Builders Pvt. Ltd |
| Addverb Technologies Pvt. Ltd |
| Unbox Robotics |
| Clearpack India Pvt. Ltd |
| GreyOrange |
| Alstrut India Private Limited |
| Warehouse Now |
| Falcon Autotech Pvt. Ltd |
| Others |
Value Chain & Pricing Dynamics
Pune's Chakan industrial belt anchors domestic AMR production capacity, and its scale dynamics translate directly into pricing leverage for integrated system vendors serving Maharashtra's e-commerce corridor. Buyers in Gujarat and Karnataka face cost premiums as supply concentrates in western India, forcing tier-2 operators toward modular retrofit alternatives.
Pricing Analysis
Current-generation AI-driven orchestration platforms command subscription premiums against prior-generation perpetual-license WMS and next-generation autonomous swarm architectures still in pilot. Three-tier pricing structure across premium, standard, and economy levels segments by integration complexity and after-sales service bundling. Price differentiation hinges on BIS certification status and fleet management software sophistication. Pricing pressure stems from PLI-subsidized domestic frame production eroding import cost structures. Mid-market 3PL operators exhibit highest price sensitivity, while large-format e-commerce hubs prioritize throughput over unit economics.
Supply Chain Analysis
Tariff exposure between Germany and India dominates component sourcing decisions for European-designed robotics facing CEA electrical compliance redesigns. Supply concentrates in Germany, South Korea, and domestic Maharashtra facilities for servo motors, LiDAR sensors, and steel frames. Raw material dependencies center on specialty steel grades, rare-earth magnets, and industrial-grade semiconductors. Single-source vulnerability runs through German motion control suppliers unprepared for Indian voltage fluctuation tolerances. Distribution runs through Mumbai-JNPT maritime gateways into Chakan and Sriperumbudur assembly clusters before regional redistribution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
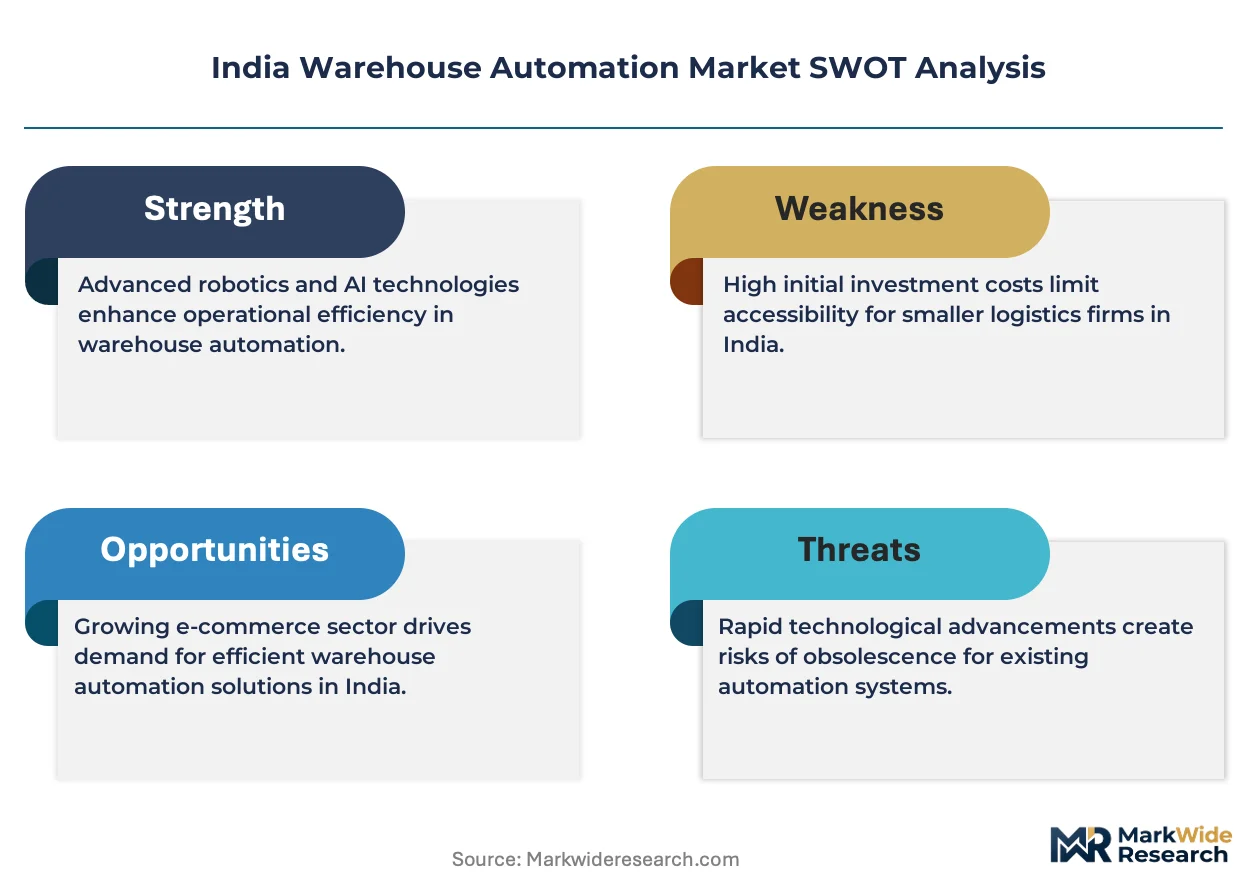
ONDC's open-network fulfillment protocols represent a platform-economics inflection, decentralizing warehouse location strategy and fragmenting procurement authority toward tier-2 city operators.
For Market Incumbents: Entrench through captive AMR production in Pune and proprietary orchestration software lock-in against modular retrofit specialists. Addverb Technologies and GreyOrange must deepen BIS-certified product lines before enforcement tightens. Capacity addition in Gujarat electronics manufacturing zones captures PLI subsidy leverage and defends margin position against mid-market entrants. For New Entrants and Emerging Players: Tier-2 city brownfield warehouses in Lucknow, Indore, and Coimbatore represent the most penetrable entry point as ONDC decentralizes fulfillment networks. Modular conveyor-to-robot retrofit kits address capital-constrained 3PL operators unwilling to greenfield automate. API-first WMS partnerships with Flipkart marketplace integrators provide the fastest go-to-market velocity. For Investors and Strategic Acquirers: Long-term, this sits as a software-defined orchestration play because recurring SaaS revenue from fleet management platforms outperforms hardware depreciation cycles. Acquisition targets should cluster around cloud-native WMS vendors with ONDC protocol integration and digital twin simulation capabilities. The signal to watch is BIS certification deadline acceleration forcing replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| In-House AMR Production | Captive manufacturing in Pune reduces import dependency and captures PLI scheme subsidies. |
| Cloud-Native WMS Development | API-first architectures integrating Flipkart and ONDC stacks command recurring revenue premiums. |
| BIS Certification Investment | Compliant emergency-stop and power system redesigns preempt regulatory enforcement and procurement preference. |
| Tier-2 Geographic Expansion | Lucknow and Indore warehouses address ONDC-decentralized fulfillment demand with modular retrofit kits. |
| Digital Twin Platform Launch | Virtual layout optimization de-risks capital commitments for large-format e-commerce hub deployments. |
Study Parameters
Cross-validation between primary stakeholder interviews and secondary regulatory filings anchors the qualitative findings. Conversations with warehouse operations directors, 3PL procurement leads, AMR fleet managers, WMS integration engineers, and BIS certification officers inform deployment velocity and procurement pattern assessments. Secondary sources include BIS certification registries, CEA electrical standards documentation, PLI scheme disbursement records, ONDC protocol specifications, and Flipkart marketplace integration disclosures. Bottom-up installation tracking and top-down addressable market sizing triangulate volume estimates.
Calibration against historical deployment cycles and announced capacity expansions refines trajectory assumptions across the analysis window. Segmentation dimensions span technology category, application type, end-user vertical, product architecture, and state-level adoption intensity. CAGRs derive from fitted growth curves adjusted for PLI subsidy phase-outs and BIS enforcement timelines. Forecast inputs incorporate ONDC network expansion schedules and e-commerce same-day delivery promise density.
Macroeconomic conditions sit as an overlay; deviation in interest rate cycles, rupee volatility, or specialty steel import tariffs would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement timing and subsidy continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Supervisory Control and Data Acquisition (SCADA) Market
Industrial Automation
Motion Control Drive Market
Industrial Automation
United States SCADA Market
Industrial Automation
North America Human Machine Interface Market
Industrial Automation
Smart Manufacturing Devices Market
Industrial Automation
Industrial Automation Services Market
Industrial Automation
North America Smart Manufacturing Market
Industrial Automation
Motion Positioning Stages Market
Industrial Automation
Global Robotic Laser Cutting Machine Market
Industrial Automation
Switzerland Industrial Automation Market
Industrial Automation
Industry 4.0 Market
Industrial Automation
Europe SCADA Market
Industrial Automation
Robotic Paint Booth Market
Industrial Automation
Global Assembly Line Solutions Market
Industrial Automation
Smart Industries Market
Industrial Automation
Global Industrial Wireless Automation Market