
 GMC Based Motion Controller Market | 2026-2036
GMC Based Motion Controller Market Size, Share, and Industry Trends Forecast 2026-2036
GMC Based Motion Controller Market Intelligence
German industrial automation suppliers is expanding output of GMC based motion controllers to serve precision manufacturing demand across Europe. Siemens leverages integrated drive platforms spanning hardware and software layers. ABB sustains technology leadership through torque control architectures. Rockwell Automation anchors North American distribution through specialized channel partnerships with machine builders.
A GMC based motion controller governs motor operation through velocity, torque, or position feedback loops with microsecond-level cycle times, typically interfacing via EtherCAT or PROFINET fieldbus protocols for synchronized multi-axis coordination. Multi axis configurations capture the largest revenue share due to robotic cell complexity, while sensorless technology represents the fastest-expanding segment by eliminating encoder hardware from cost-sensitive packaging lines. Programmable variants concentrate margin pools in semiconductor equipment where nanometer-scale positioning justifies premium controller specifications.
IEC 61800-5-1 and GB/T 12668 shape electromagnetic compatibility and safety requirements, forcing controller redesigns for export markets. CE marking under the EU Machinery Directive governs market access for European OEM sales. FDA 21 CFR Part 11 compliance pressures semiconductor equipment suppliers serving pharmaceutical cleanroom applications. Stakeholders must monitor evolving functional safety standards as deterministic Ethernet protocols displace legacy fieldbus architectures.
Market Dynamics
Deterministic Ethernet protocols are compressing legacy fieldbus architectures across industrial automation, forcing controller vendors to redesign hardware and software stacks for sub-millisecond synchronization requirements.
Growth Catalysts
- Semiconductor equipment demand:East Asian fabs are accelerating procurement of multi-axis controllers for nanometer-scale lithography and wafer handling systems, tightening specifications for positioning accuracy.
- GB/T 12668 electromagnetic compatibility mandates:China's frequency converter regulations are compelling foreign suppliers to redesign controller architectures for export compliance, expanding certified product availability.
- Sensorless vector control:Elimination of encoder hardware from cost-sensitive packaging lines is reducing bill-of-materials costs while maintaining motion precision.
Market Restraints
- Silicon supply concentration:Discrete semiconductor sourcing from concentrated East Asian foundries creates input volatility for controller ASIC production.
- IEC 61800-5-1 safety certification timelines:Functional safety documentation requirements extend product validation cycles by 8-14 months for European market entry.
- Integrated drive platform substitution:Vendors bundling motion control into servo amplifiers are compressing standalone controller addressable market.
Strategic Opportunities
- Pharmaceutical cleanroom automation:FDA 21 CFR Part 11 compliance requirements in US pharmaceutical manufacturing are creating premium controller demand for validated batch control systems.
- CE marking under EU Machinery Directive:Updated conformity assessment procedures are advantaging pre-certified suppliers against uncertified competitors in European OEM channels.
- Time-Sensitive Networking convergence:IEEE 802.1 TSN standards merging with OPC UA is enabling controller-to-cloud architectures for predictive maintenance services.
Industry Challenges
- Embedded safety firmware expertise:Shortage of engineers proficient in IEC 61508 SIL development is constraining vendor R&D throughput.
- Legacy fieldbus integration complexity:Retrofitting PROFIBUS-DP and DeviceNet infrastructures with EtherCAT masters requires custom gateway engineering for brownfield installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GMC Based Motion Controller Market |
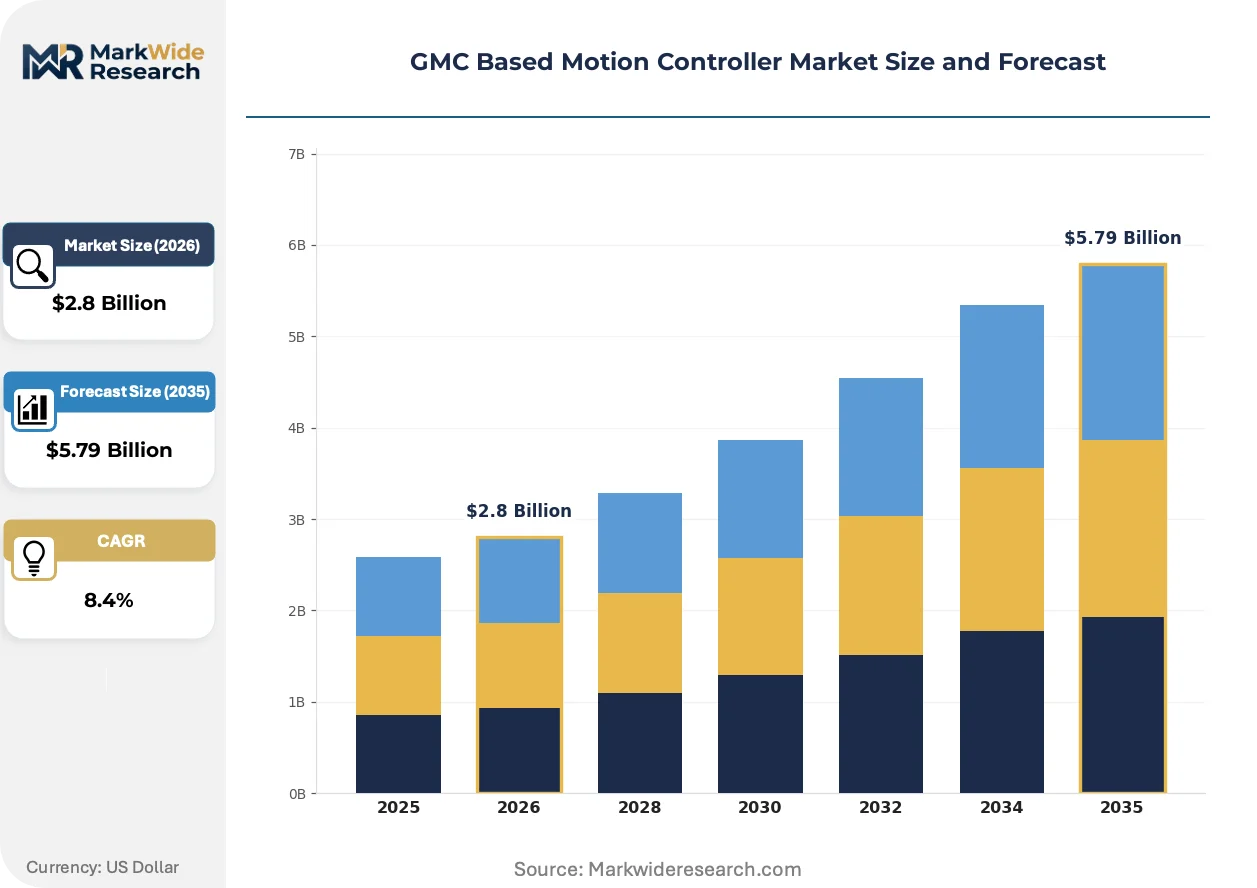
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Single Axis, Multi Axis, Programmable, Compact Technology: Velocity Control, Torque Control, Position Control, Sensorless Application: Robotics, Semiconductor Equipment, Packaging Systems, Printing Machines End User: OEMs, System Integrators, Contract Manufacturers, Machine Builders |
| Companies Covered | Siemens, ABB, Rockwell Automation, Mitsubishi Electric, Schneider Electric, Omron Corporation, Delta Electronics, Yaskawa Electric Corporation, Beckhoff Automation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GMC Based Motion Controller Market Strategic Shifts & Innovations
Motion control architectures are converging toward software-defined platforms where hardware abstraction layers enable firmware updates to modify control algorithms without hardware replacement.
Soft motion controllers running on industrial PCs are unifying PLC, motion, and safety logic onto single compute platforms. Semiconductor equipment manufacturers in Taiwan and South Korea are piloting these configurations for 300mm wafer transport systems. This unification is compressing the traditional separation between machine control tiers, forcing dedicated motion hardware vendors to differentiate through deterministic performance guarantees.
REACH substance restrictions on lead and cadmium in electronics are compelling controller manufacturers to redesign PCB assemblies and connector systems. The industrial consequence extends beyond component substitution to supply chain requalification for solder alloys and plating chemistries. German automation suppliers serving European OEMs are absorbing the highest compliance costs, passing through 12-18% material cost increases.
Machine builders are consolidating vendor relationships from point-solution purchasing to platform contracting, bundling motion controllers with servo drives and HMIs under multi-year supply agreements. System integrators in the Nuremberg industrial cluster are displacing traditional distributor channels for mid-volume OEM accounts. This concentration is most visible in automotive powertrain assembly, where Tier 1 suppliers are reducing qualified controller vendors from six to two per platform.
GMC Based Motion Controller Market Segmentation
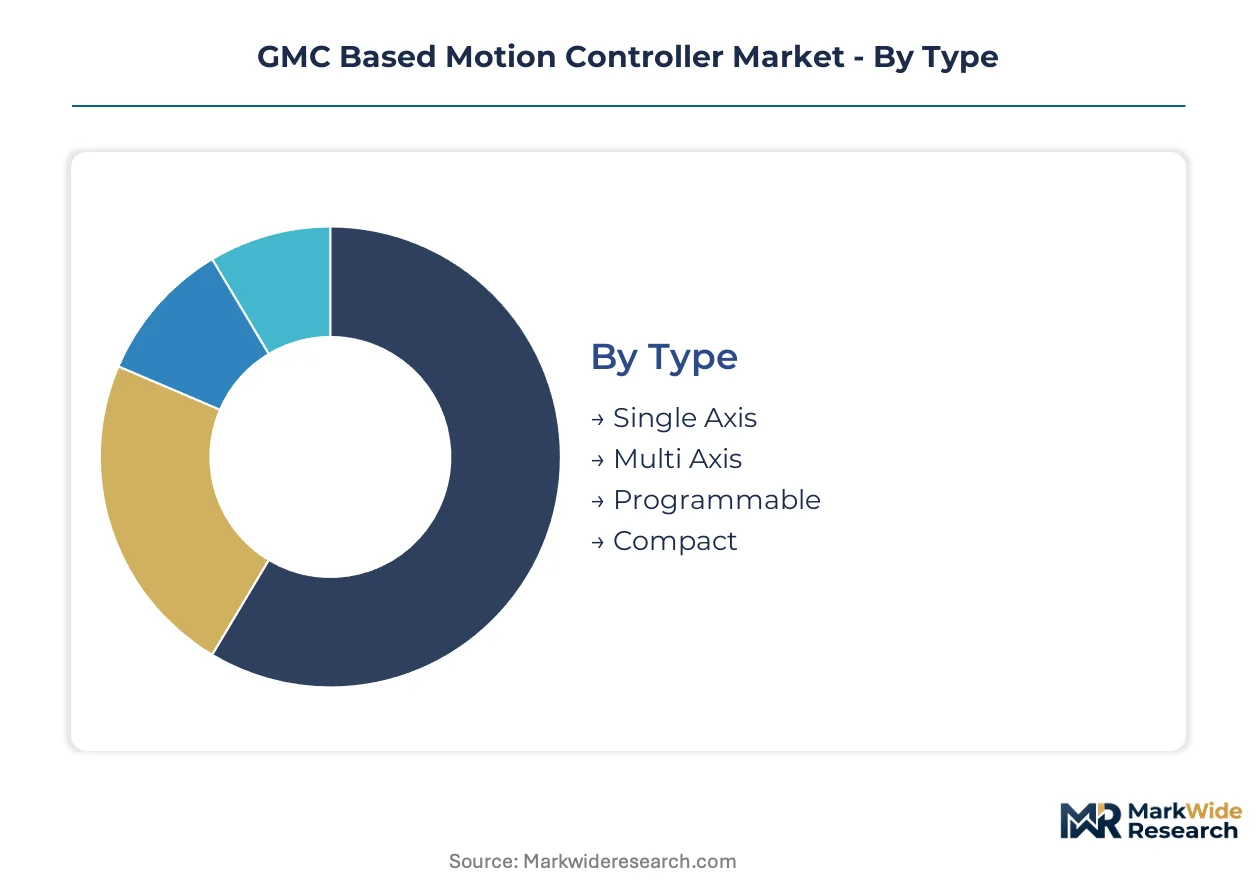
Controller architecture diversity reflects divergent supply chain configurations across precision manufacturing tiers. Semiconductor fabs demand nanometer-grade positioning systems while packaging lines prioritize cost-optimized sensorless alternatives, fragmenting vendor specialization and procurement patterns.
Type:
Supply concentration in East Asian foundry equipment is compressing controller form factor requirements toward space-optimized designs with embedded safety logic.
- Multi Axis:Synchronized coordination of six or more axes via EtherCAT masters enables robotic cell complexity in automotive powertrain assembly. Demand concentrates in Germany's Nuremberg-Stuttgart industrial corridor where Tier 1 suppliers are consolidating qualified vendors from six to two per platform.
- Sensorless:Vector control algorithms eliminate encoder hardware through motor model-based estimation, reducing bill-of-materials costs. Taiwanese and South Korean semiconductor equipment manufacturers are piloting these configurations for 300mm wafer transport systems in cleanroom environments.
- Single Axis:Standalone controllers for simple positioning tasks in conveyor systems and material handling equipment.
- Programmable:Firmware-configurable architectures supporting IEC 61131-3 languages for custom motion profiles in specialized machinery.
- Compact:DIN-rail mounted units with integrated I/O for space-constrained packaging machinery and small robotic cells.
Multi Axis absorbs the bulk of installed capacity; Sensorless is expanding most quickly.
Technology:
Cost tier differentiation separates premium closed-loop architectures from emerging algorithmic alternatives that displace hardware.
- Position Control:Closed-loop feedback with resolver or optical encoders achieves sub-micron accuracy for lithography stages and wafer alignment systems. Demand concentrates in East Asian fabs where GB/T 12668 electromagnetic compatibility mandates are forcing controller redesigns for export compliance.
- Sensorless:Model reference adaptive control eliminates position sensors through current and voltage waveform analysis, cutting encoder costs by 30-40%. Cost-sensitive packaging lines in China's Pearl River Delta are adopting these systems for rotary indexing tables and flying shear applications.
- Velocity Control:Analog or digital speed regulation for pumps, fans, and conveyor drives requiring moderate dynamic response.
- Torque Control:Direct torque or field-oriented control for winding, tensioning, and press applications requiring force limiting.
Position Control captures the dominant revenue pool; Sensorless gains share fastest in cost-driven segments.
Application:
Volume concentration in automotive and electronics manufacturing is standardizing controller specifications across equipment categories.
- Semiconductor Equipment:Nanometer-scale lithography and wafer handling systems require deterministic cycle times below 100 microseconds with SIL 3 safety integrity. East Asian fabs are accelerating procurement as process nodes shrink, tightening positioning accuracy specifications.
- Robotics:Six-axis articulated arms and SCARA systems demand synchronized multi-axis coordination with collision detection. German automotive OEMs are specifying controllers with integrated safety firmware for human-robot collaborative cells.
- Packaging Systems:High-speed cartoning, labeling, and palletizing equipment requiring cam profiles and electronic gearing.
- Printing Machines:Register control and tension management for web-fed offset and digital printing presses.
Semiconductor Equipment commands premium pricing; Robotics delivers the steepest volume expansion trajectory.
End User:
Customer type determines procurement channel structure, with platform contracting displacing point-solution purchasing across mid-volume accounts.
- Machine Builders:Original equipment manufacturers designing custom machinery for specific production processes are consolidating vendor relationships into multi-year supply agreements bundling controllers, servo drives, and HMIs. System integrators in Germany's Nuremberg cluster are displacing traditional distributors for these accounts.
- System Integrators:Engineering firms assembling turnkey automation solutions for end-user factories are specifying controllers with pre-certified safety stacks to compress commissioning timelines. FDA 21 CFR Part 11 compliance requirements in US pharmaceutical manufacturing are creating premium demand for validated batch control systems.
- OEMs:Large equipment manufacturers with captive engineering resources and established supplier qualification programs.
- Contract Manufacturers:Electronics manufacturing services providers integrating motion control into outsourced production equipment.
Machine Builders anchor procurement volume; System Integrators are climbing the fastest as outsourcing expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision engineering clusters and East Asian semiconductor fabrication anchor the geographic distribution of GMC based motion controller demand, with regulatory divergence across IEC, GB/T, and FDA frameworks fragmenting certification requirements.
United States
Pharmaceutical manufacturing automation and aerospace tooling drive multi-axis controller procurement. FDA 21 CFR Part 11 compliance mandates shape cleanroom equipment specifications. Boston-Worcester corridor system integrators are consolidating vendor relationships for validated batch control systems.
Germany
Automotive powertrain assembly and industrial machinery exports sustain premium controller demand. CE marking under the EU Machinery Directive governs OEM market access. The Nuremberg-Stuttgart industrial cluster is compressing qualified controller vendors from six to two per Tier 1 platform.
China
Packaging machinery and electronics manufacturing equipment absorb cost-optimized sensorless controllers. GB/T 12668 electromagnetic compatibility regulations are forcing foreign supplier redesigns for export compliance. Pearl River Delta rotary indexing table manufacturers are adopting encoder-free vector control systems.
Japan
Robotics manufacturing and semiconductor equipment exports drive deterministic cycle-time requirements. METI industrial automation standards influence regional procurement specifications. Nagoya-Tokyo corridor machine builders are specifying integrated safety firmware for collaborative robot cells.
South Korea
300mm wafer transport systems and display panel manufacturing tighten positioning accuracy specifications. MFDS pharmaceutical equipment regulations create secondary demand for validated motion systems. Suwon-Pyeongtaek semiconductor equipment manufacturers are piloting soft motion controllers on industrial PC platforms.
GMC Based Motion Controller Market Key Industry Players
Global majors compete with regional champions across integrated drive platforms and specialized motion hardware, producing a tiered structure where bundled servo-amplifier solutions compress standalone controller margins. Siemens, ABB, and Rockwell Automation anchor the premium tier through deterministic performance guarantees. Mid-scale specialists occupy niches in cost-sensitive packaging machinery. Strategic moves concentrate on safety firmware certification acceleration and deterministic Ethernet protocol migration.
Among German-based automation suppliers, Siemens and Beckhoff Automation exemplify the integrated platform archetype spanning hardware abstraction layers. Japanese specialists including Mitsubishi Electric and Yaskawa Electric Corporation occupy positions emphasizing torque control architectures and multi-axis synchronization. These groupings represent divergent responses to software-defined motion convergence.
| Leading Market Players |
|---|
| Siemens |
| ABB |
| Rockwell Automation |
| Mitsubishi Electric |
| Schneider Electric |
| Omron Corporation |
| Delta Electronics |
| Yaskawa Electric Corporation |
| Beckhoff Automation |
| Others |
Cost & Logistics Intelligence
Silicon wafer costs cascade through controller ASIC fabrication into tiered hardware pricing, with East Asian foundry concentration amplifying margin pressure for European vendors redesigning around IEC 61800-5-1 certification requirements.
Pricing Analysis
Warranty and field service bundling separates premium motion controller tiers, with Siemens and ABB embedding multi-year maintenance contracts while mid-scale competitors strip after-sales coverage to hit price points. Certification grade—specifically SIL 3 safety integrity and CE marking under the EU Machinery Directive—drives price differentiation alongside deterministic Ethernet protocol support. Cost compression in sensorless controller tiers is intensifying because Taiwanese packaging OEMs are standardizing encoder-free architectures. Machine builders in Germany's Nuremberg-Stuttgart corridor show lowest price sensitivity due to platform consolidation, while Pearl River Delta equipment manufacturers prioritize bill-of-materials reduction.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for discrete semiconductor foundry capacity feeding controller ASIC production. Raw material dependencies span silicon wafers, rare earth magnets for servo motors, and specialized solder alloys compliant with REACH substance restrictions. Tariff exposure on Chinese-manufactured PCB assemblies is forcing German automation suppliers to requalify Eastern European contract manufacturers. Distribution runs through system integrators displacing traditional distributors for mid-volume OEM accounts in automotive powertrain assembly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Functional safety firmware engineering scarcity props pricing for certified controllers, with IEC 61508 SIL development expertise constraining vendor R&D throughput across the analysis window.
For Market Incumbents: Extend deterministic Ethernet protocol roadmaps to compress legacy fieldbus migration timelines, countering soft motion controller substitution running on industrial PC platforms. Accelerate embedded safety firmware certification through captive IEC 61508 SIL engineering teams, defending margin pools in semiconductor equipment against integrated drive platform bundling from servo amplifier vendors.
For New Entrants and Emerging Players: Enter via pharmaceutical cleanroom automation in the Boston-Worcester corridor, where FDA 21 CFR Part 11 compliance requirements create premium controller demand with lower incumbent saturation. Target validated batch control systems through pre-certified safety stack partnerships with established system integrators, bypassing direct OEM qualification barriers.
For Investors and Strategic Acquirers: Soft motion controller pilot deployments at Suwon-Pyeongtaek semiconductor equipment manufacturers are the leading indicator that software-defined platforms will compress dedicated hardware margins within the projection horizon. Acquire mid-scale specialists with deterministic performance guarantees and existing EtherCAT master certifications, watching Time-Sensitive Networking convergence with OPC UA as the inflection signal for controller-to-cloud architecture viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Safety Firmware Certification Acceleration | IEC 61508 SIL 3 compliance compresses European market entry timelines against uncertified competitors. |
| Deterministic Ethernet Protocol Migration | EtherCAT and PROFINET integration displaces legacy PROFIBUS-DP infrastructure in brownfield installations. |
| Sensorless Vector Control Expansion | Elimination of encoder hardware reduces bill-of-materials costs for Pearl River Delta packaging lines. |
| Integrated Drive Platform Development | Bundling motion control with servo amplifiers compresses standalone controller addressable market share. |
| Pharmaceutical Cleanroom Specialization | FDA 21 CFR Part 11 validated systems capture premium pricing in US pharmaceutical manufacturing automation. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across controller hardware engineering directors, semiconductor equipment procurement managers, system integrators in Germany's Nuremberg cluster, and automotive Tier 1 supplier automation leads. SEC 10-K disclosures, IEC standard documentation, FDA 510(k) filings, and GB/T regulatory texts provided validation. Bottom-up unit shipment estimates triangulated against top-down value projections.
Reconciliation of production volume data from East Asian foundry equipment manufacturers with controller procurement patterns across Germany, China, and the United States anchored the analytical framework. Segmentation dimensions spanned axis configuration, control technology, application vertical, and end-user procurement channel. CAGRs derived from curve-fitting historical shipment trajectories against semiconductor capital expenditure cycles and automotive powertrain assembly automation intensity metrics.
Forecast precision tightens around the base case; tail outcomes carry wider variance under prolonged silicon supply disruption or accelerated Time-Sensitive Networking standard adoption. Forecasts reflect assumptions regarding regulatory stability for IEC 61800-5-1 and GB/T 12668 compliance timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
SCADA Alarm Management Market
Industrial Automation
Asia Pacific Manufacturing Execution Systems (MES) Market
Industrial Automation
Japan Factory Automation and Industrial Controls Market
Industrial Automation
Middle East and Africa Machine Control System Market
Industrial Automation
Global Intelligent Process Automation Market
Industrial Automation
Geosteering Technology Market
Industrial Automation
Warehouse Automation Solutions Market
Industrial Automation
Global Discrete Automation Market
Industrial Automation
Global Intelligent Completion Market
Industrial Automation
North America Human Machine Interface Market
Industrial Automation
Global Mining Automation Consumption Market
Industrial Automation
Tilt Tray Sorter Market
Industrial Automation
Operational Predictive Maintenance Market
Industrial Automation
Latin America HMI Market
Industrial Automation
Electric Linear Actuator Market
Industrial Automation
Smart Sorting Line Market