
 Japan Factory Automation and Industrial Controls Market | 2026-2036
Japan Factory Automation and Industrial Controls Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Factory Automation and Industrial Controls Market Foresight
The capability gap between integrated platform vendors and component specialists is collapsing as software-defined automation erodes hardware moats. Mitsubishi Electric leverages its iQ-R series PLC ecosystem to anchor large-scale manufacturing deployments across domestic automotive plants. Fanuc Corporation sustains dominance in CNC and robotic controllers through captive servo motor production and relentless R&D intensity in motion control algorithms. Keyence Corporation differentiates via direct salesforce density and rapid visual inspection system iterations that bypass traditional distributor channels.
Factory automation and industrial controls encompass electromechanical systems, software platforms, and communication protocols that govern manufacturing processes with precision measured in microseconds and positional accuracy below ten micrometers. These systems execute sequential logic, real-time feedback loops, and distributed process coordination to minimize downtime and defect rates in continuous and discrete production environments. PLC and SCADA deployments command the largest installed base among control technologies, though robotics solutions capture disproportionate margin pools as semiconductor and electric vehicle battery plants scale capacity. Sensors and drives represent the most fragmented product layer, while control software and networking solutions attract fastest-growing demand as edge computing architectures displace centralized DCS hierarchies.
METI's Industrial Cybersecurity Framework and JIS B 8433 collaborative robot safety standards shape product certification requirements and procurement specifications for domestic manufacturers. PMDA and Japan's national standards body enforce electromagnetic compatibility and functional safety protocols that filter non-compliant foreign suppliers from precision-critical segments. Stakeholders must monitor how METI's next-generation AI integration guidelines reshape interoperability mandates between legacy brownfield equipment and cloud-native control platforms.
Market Dynamics
Software-defined control architectures are dissolving the traditional hardware-software boundary in Japanese manufacturing, forcing established vendors to rearchitect product portfolios around open APIs and edge-native computing stacks rather than proprietary PLC ecosystems.
Growth Catalysts
- Society 5.0 Framework:METI's policy mandate accelerates smart factory adoption by subsidizing AI-integrated production lines and digital twin deployments across domestic automotive and electronics plants.
- Electric Vehicle Battery Manufacturing:Gigafactory construction in Kyushu and Kanto corridors drives demand for precision motion control systems and collaborative robot cells with sub-micron repeatability.
- Kanto Industrial Corridor Concentration:Dense clustering of Toyota, Honda, and Nissan suppliers in Tokyo-Kanagawa-Saitama creates network effects for automation technology diffusion and localized service ecosystems.
Market Restraints
- Rare Earth Magnet Supply Concentration:Japanese servo motor and precision drive manufacturers remain dependent on processed rare earth imports, exposing cost structures to geopolitical supply disruptions.
- JIS B 8433 Certification Burden:Collaborative robot safety standards impose lengthy third-party validation timelines that delay product launches by 8-14 months versus non-certified markets.
- Labor Cost Arbitrage Limitation:Persistent yen weakness erodes the ROI calculus for automation investments compared to offshore manufacturing alternatives in Southeast Asia.
Strategic Opportunities
- Chubu Region Underpenetration:Nagoya-centered automotive supply chains lag Kanto in Industry 4.0 maturity, creating whitespace for predictive maintenance and digital twin solution providers.
- AI-Edge Convergence:Integration of machine vision with real-time PLC control enables autonomous defect correction loops that bypass traditional SCADA hierarchies in semiconductor packaging lines.
- Direct-to-Factory Distribution:Bypassing traditional machinery trading houses through manufacturer-owned digital sales platforms captures margin and accelerates specification-to-delivery cycles.
Industry Challenges
- Mechatronics Engineering Talent Scarcity:Japanese universities produce insufficient graduates combining mechanical design, embedded software, and industrial networking expertise to support brownfield modernization projects.
- Brownfield Integration Complexity:Legacy MELSEC and FANUC control architectures from the 1990s lack native OPC-UA support, requiring expensive protocol gateway layers for cloud connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Factory Automation and Industrial Controls Market |
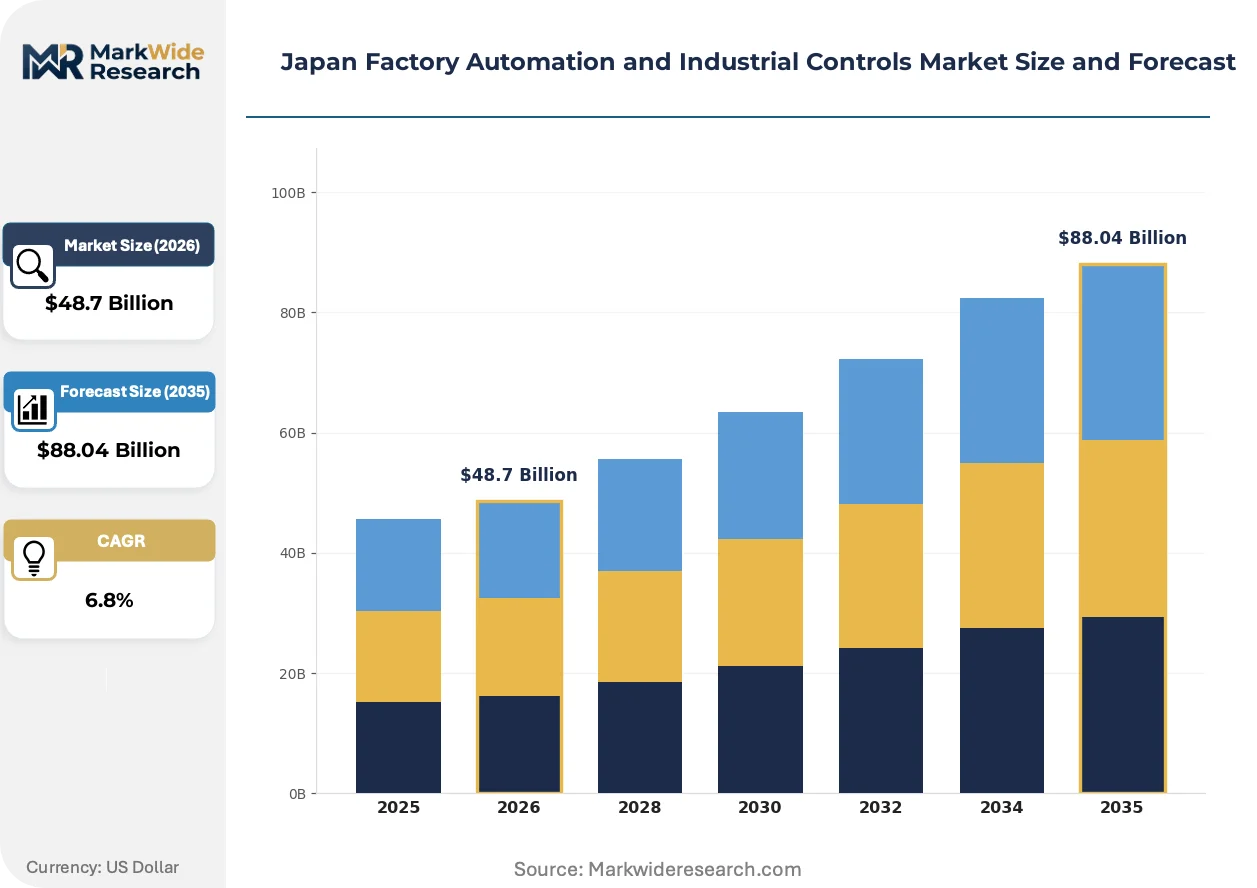
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: PLC, SCADA, DCS, HMI Product Type: Sensors, Actuators, Drives, Controllers End User: Automotive, Electronics, Food & Beverage, Pharmaceuticals Solution: Robotics, Visual Systems, Control Software, Networking Solutions |
| Companies Covered | Mitsubishi Electric Corporation, Omron Corporation, Fanuc Corporation, Yokogawa Electric Corporation, Keyence Corporation, Yaskawa Electric Corporation, SMC Corporation, Panasonic Industry Co., Ltd., Fuji Electric Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Factory Automation and Industrial Controls Market Shifts & Advancements
Time-sensitive networking standards and containerized control software are redefining how Japanese manufacturers orchestrate distributed production assets, collapsing the latency gap between field devices and enterprise systems.
Time-sensitive networking is decomposing the traditional hierarchical separation between PLCs and enterprise ERP systems. Automotive battery plants in Tochigi and Ibaraki are deploying TSN-enabled servo networks that synchronize motion control with MES-level production scheduling. This convergence is compressing system integration timelines from 18 months to under 6 months for greenfield semiconductor facilities.
METI's Industrial Cybersecurity Framework is mandating segmented network architectures and encrypted device authentication for all critical infrastructure suppliers. Domestic control system vendors must now embed hardware security modules and certificate-based device attestation into standard product lines. Food and pharmaceutical manufacturers face the steepest compliance burden, with PMDA-aligned facilities requiring full audit trails for every parameter change.
Subscription-based control software licensing is displacing perpetual hardware-software bundles in mid-sized metalworking and plastics processing plants. Machinery trading houses in Osaka and Nagoya are losing specification influence as end-users procure control runtimes directly from vendor cloud portals. This shift is most pronounced among precision component suppliers serving the medical device and aerospace tiers, where software update velocity outweighs capital depreciation preferences.
Japan Factory Automation and Industrial Controls Market Segmentation
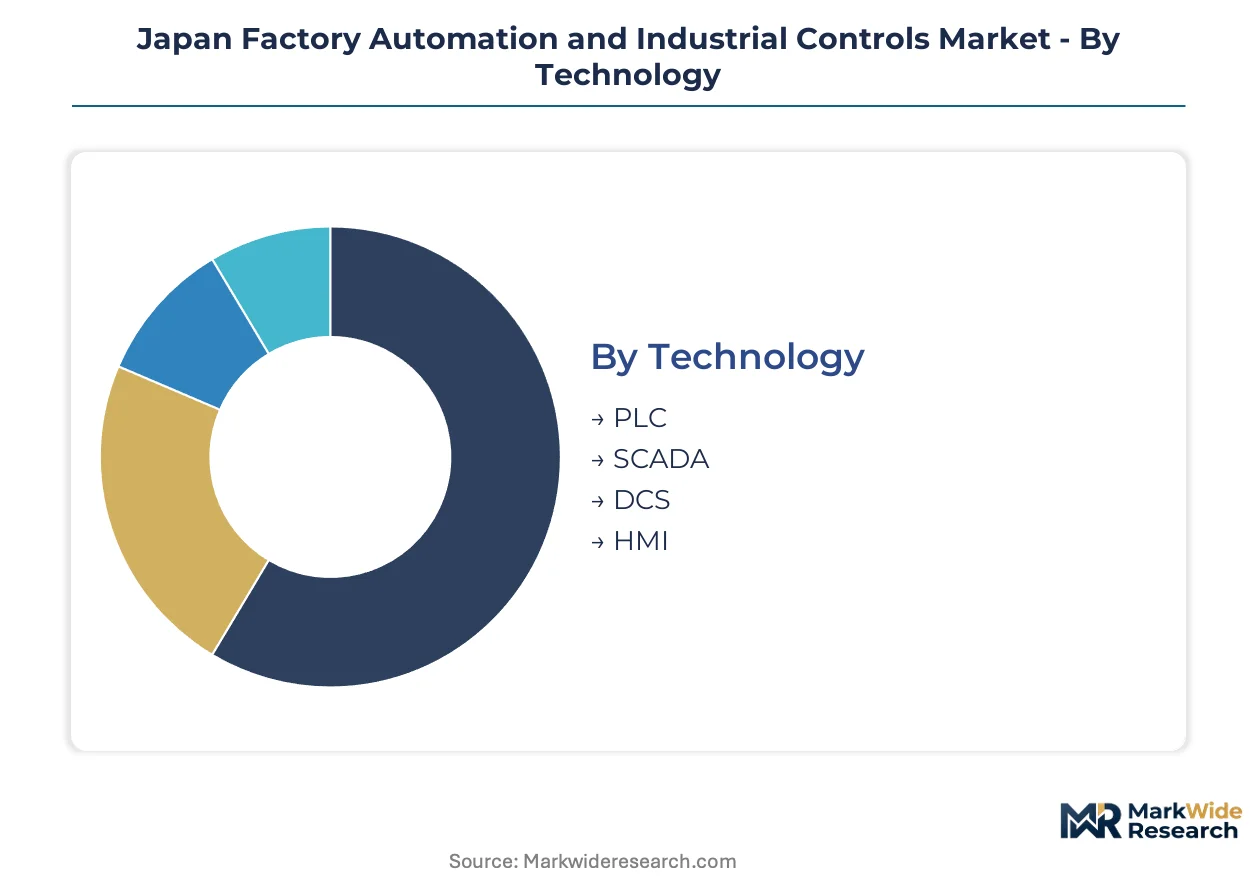
Technology-product-solution layering in Japanese factory automation reveals how margin pools migrate from hardware toward software-defined control architectures. Understanding these segment boundaries exposes where vendor consolidation pressure concentrates and where specialist differentiation remains defensible.
Technology:
Margin concentration sits with systems that bridge operational technology and enterprise IT layers, where software licensing recurring revenue displaces one-time hardware sales.
- PLC:Programmable logic controllers execute sequential machine control with deterministic cycle times measured in milliseconds. Automotive battery plants in Tochigi deploy these for coordinated motion sequences across hundreds of servo axes. METI's Society 5.0 subsidies accelerate replacement of legacy MELSEC architectures with OPC-UA native platforms.
- SCADA:Supervisory control and data acquisition systems aggregate field-level telemetry into centralized visualization dashboards. Pharmaceutical manufacturers in Osaka prefecture demand these for PMDA-mandated batch record integrity and audit trail compliance. JIS B 8433 safety standard integration adds certification complexity that filters smaller foreign vendors.
- DCS:Distributed control systems govern continuous process industries with redundant controller architectures.
- HMI:Human-machine interfaces provide operator visualization and alarm management layers.
PLC holds installed capacity. SCADA is rotating up the share rankings.
Product Type:
Volume leadership belongs to components with shortest replacement cycles and broadest cross-industry applicability, though controllers capture disproportionate value per unit.
- Sensors:Photoelectric, proximity, and vision sensors detect position, presence, and quality parameters with micron-level precision. Electronics assembly lines in Kanagawa prefecture consume these at highest density for semiconductor packaging verification. Keyence's direct salesforce bypasses traditional machinery trading houses to accelerate specification cycles.
- Controllers:Motion controllers and CNC systems coordinate multi-axis synchronization with nanometer positioning repeatability. Precision component suppliers serving medical device tiers in Saitama prioritize these for sub-micron machining operations. Fanuc's captive servo motor production creates hardware-software integration moats.
- Actuators:Pneumatic and electromechanical actuators convert control signals into physical motion.
- Drives:Variable frequency and servo drives modulate motor torque and velocity.
Controllers command premium pricing. Sensors are climbing the fastest in shipment volume.
End User:
Application intensity varies sharply by sector, with automotive and electronics driving precision requirements while food and pharmaceutical sectors shoulder steepest compliance burdens.
- Automotive:Toyota, Honda, and Nissan supplier networks in the Kanto corridor deploy collaborative robot cells and precision motion systems for electric vehicle battery module assembly. Gigafactory construction in Kyushu expands demand for sub-micron repeatability equipment. JIS B 8433 collaborative robot certification timelines delay non-domestic vendor market entry.
- Pharmaceuticals:PMDA-aligned facilities require full parameter change audit trails and electromagnetic compatibility validation that elevates procurement specifications above standard industrial grades. Osaka and Nagoya pharmaceutical clusters face the steepest METI Industrial Cybersecurity Framework compliance mandates for segmented network architectures.
- Electronics:Semiconductor packaging and flat panel display manufacturing concentrates in Kanagawa and Ibaraki prefectures.
- Food & Beverage:Hygienic design standards and washdown-rated enclosures dominate equipment selection in this sector.
Automotive anchors capital expenditure. Pharmaceuticals are expanding most quickly in control system value per production line.
Solution:
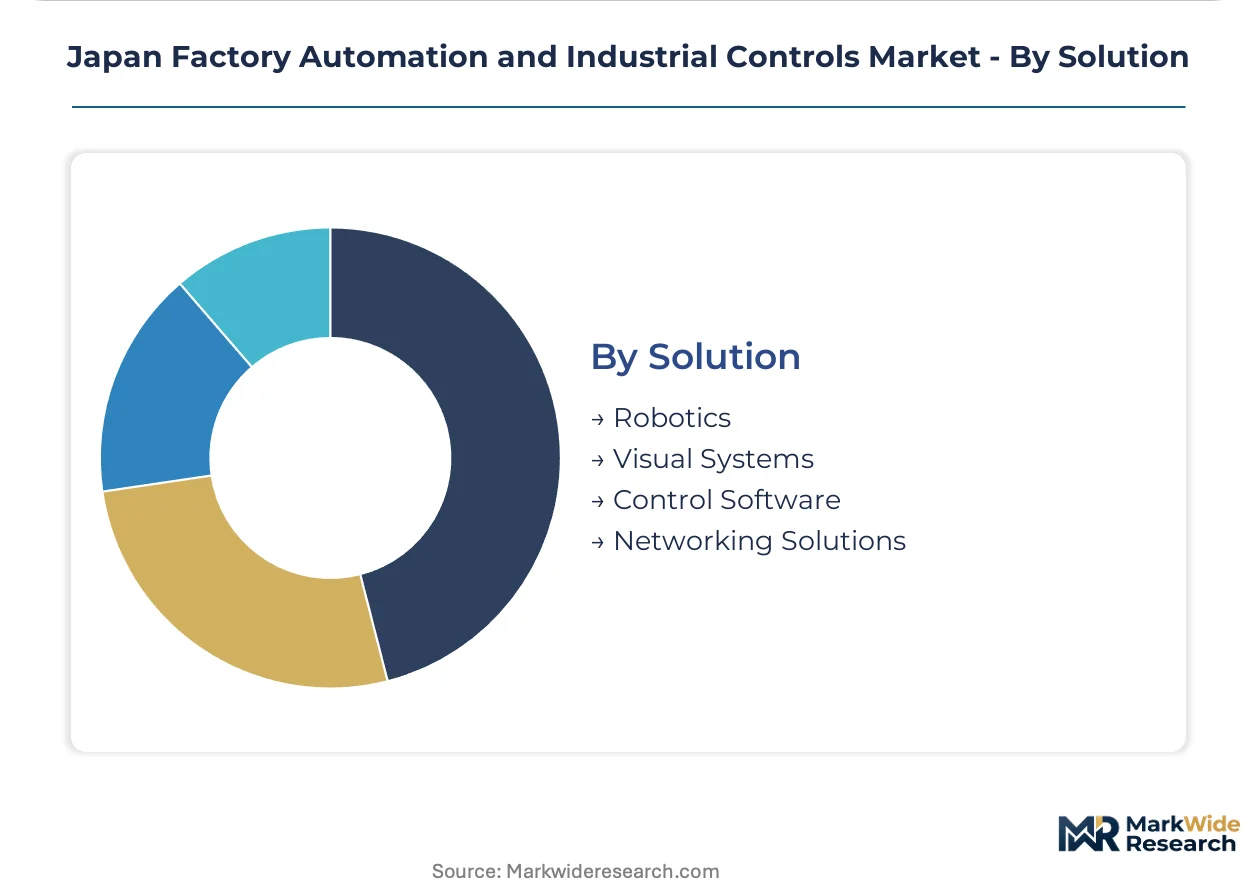
Software and service attach rates determine profitability, with robotics and visual systems commanding implementation premiums over commodity networking hardware.
- Robotics:Articulated and SCARA robot systems integrate servo control, kinematic algorithms, and safety interlocks into unified cells. Automotive plants in Aichi prefecture deploy these for battery pack assembly where collaborative operation with human workers requires force-limiting and speed monitoring compliance. METI subsidies under Society 5.0 reduce payback periods for mid-sized metalworking shops.
- Visual Systems:Machine vision platforms combine high-speed cameras, lighting, and edge-native processing for defect detection and guidance. Electronics manufacturers prioritize these for autonomous quality correction loops that bypass traditional SCADA hierarchies. Keyence's rapid iteration cycles compress specification-to-deployment timelines versus traditional distributor channels.
- Control Software:Subscription-based runtime licensing and digital twin platforms are displacing perpetual hardware-software bundles.
- Networking Solutions:Time-sensitive networking switches and industrial Ethernet infrastructure enable deterministic data flows.
Robotics holds the largest project value. Visual systems are gaining share fastest as edge-AI integration matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across Japanese manufacturing geography. Tokyo-Kanagawa buyers prioritize precision and integration over unit cost, while Kyushu gigafactory projects exhibit acute price sensitivity on standardized motion systems.
Kanto/Tokyo
Automotive battery plants and semiconductor packaging facilities drive premium automation procurement. METI's Society 5.0 subsidies accelerate AI-integrated production line deployments. Dense supplier networks in Tokyo, Kanagawa, and Saitama prefectures create localized service ecosystems that compress maintenance response times.
Kansai/Osaka
Pharmaceutical manufacturers anchor demand for PMDA-compliant control systems with full audit trail capabilities. JIS B 8433 collaborative robot certification requirements filter non-domestic vendors from precision-critical segments. Osaka prefecture's medical device supply chains prioritize electromagnetic compatibility validation above standard industrial grades.
Chubu/Nagoya
Toyota-centric automotive supply chains lag Kanto in Industry 4.0 maturity, creating whitespace for predictive maintenance providers. METI's Industrial Cybersecurity Framework mandates segmented network architectures for critical infrastructure suppliers. Aichi prefecture battery pack assembly plants deploy collaborative robot cells requiring force-limiting compliance.
Kyushu
Gigafactory construction drives volume demand for sub-micron repeatability motion control systems. Yen weakness erodes ROI calculus for automation investments versus Southeast Asian alternatives. Fukuoka and Kumamoto prefectures concentrate electric vehicle battery module assembly capacity.
Tohoku
Legacy automotive component suppliers face brownfield integration complexity with 1990s-era control architectures. PMDA-aligned food and pharmaceutical facilities in Miyagi prefecture require full parameter change audit trails. Sendai-centered electronics manufacturers prioritize machine vision for autonomous defect correction loops.
Japan Factory Automation and Industrial Controls Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in Japanese factory automation. The upper tier commands premium positioning through captive component production and direct distribution density. Specialist vendors compete on rapid iteration cycles in visual inspection and sensing applications. Dominant competitive moves include backward integration into servo motor manufacturing and geographic expansion through manufacturer-owned digital sales platforms that bypass traditional machinery trading houses.
Among Japan-based integrated conglomerates, Mitsubishi Electric Corporation and Fanuc Corporation exemplify the full-stack archetype through in-house production of PLCs, servo systems, and motion control algorithms. Keyence Corporation occupies a distinct position within the specialist tier, leveraging direct salesforce density to compress specification-to-deployment timelines. These three anchors illustrate how hardware-software integration moats and distribution model innovation separate premium positioning from commodity competition.
| Leading Market Players |
|---|
| Mitsubishi Electric Corporation |
| Omron Corporation |
| Fanuc Corporation |
| Yokogawa Electric Corporation |
| Keyence Corporation |
| Yaskawa Electric Corporation |
| SMC Corporation |
| Panasonic Industry Co., Ltd. |
| Fuji Electric Co., Ltd. |
| Others |
Supply & Pricing Matrix
Eighteen-month PLC lead times for OPC-UA native platforms concentrate pricing power with integrated Japanese vendors who control captive servo production, while subscription software licensing compresses hardware margins across machinery trading houses. Inventory buffers for rare earth-processed magnets remain thin, amplifying cost volatility for precision drive manufacturers serving automotive battery plants.
Pricing Analysis
After-sales service contracts and spare parts revenue anchor lifetime value for established automation vendors, with software subscription tiers displacing perpetual licensing in mid-sized metalworking shops. Three-tier pricing structure across premium, standard, and economy levels separates JIS B 8433-certified collaborative robot systems from uncertified imports. Pricing pressure stems from yen weakness eroding automation ROI against Southeast Asian manufacturing alternatives. Tier 1 automotive suppliers in Kanto exhibit lowest price sensitivity, prioritizing sub-micron repeatability and localized service response.
Supply Chain Analysis
China and Vietnam dominate rare earth oxide processing and precision machining subcontracting for Japanese servo motor manufacturers. Japanese automation vendors draw from Taiwanese semiconductor foundries for motion control ASICs and German specialty steel producers for precision ball screws. Single-source vulnerability concentrates in processed rare earth magnet supply, exposing cost structures to export restriction risk. Distribution runs through manufacturer-owned digital platforms that bypass Osaka and Nagoya machinery trading houses, compressing specification-to-delivery cycles for visual inspection systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against software-defined control architectures that dissolve traditional hardware moats, as open APIs and edge-native computing stacks enable non-traditional entrants to bypass proprietary PLC ecosystems.
For Market Incumbents: Fortify backward integration into servo motor manufacturing to preserve hardware-software integration advantages against modular competitors. Deepen direct salesforce density in Kanto automotive corridors to maintain specification influence as machinery trading houses lose procurement control. Prioritize METI Industrial Cybersecurity Framework certification investments to filter non-compliant foreign suppliers from PMDA-aligned pharmaceutical segments.
For New Entrants and Emerging Players: Lead with AI-edge convergence solutions targeting Chubu Region predictive maintenance whitespace, where Toyota-centric supply chains lag Kanto in Industry 4.0 maturity. Deploy manufacturer-owned digital sales platforms to capture margin and accelerate specification cycles in precision component tiers serving medical device and aerospace buyers. Bypass traditional distributor channels through rapid visual system iteration cycles that match Keyence's deployment velocity.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates seeking to monetize non-core automation divisions amid portfolio restructuring pressures. Long-term viability hinges on software attach rates and recurring revenue share rather than hardware shipment volumes. Watch for METI next-generation AI integration guideline releases as inflection signals for interoperability mandate timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Servo Motor Production | Captive supply of precision drives preserves margin pools as rare earth volatility intensifies. |
| Direct-to-Factory Digital Platform Launch | Manufacturer-owned sales portals displace Nagoya and Osaka machinery trading house intermediaries. |
| JIS B 8433 Collaborative Robot Certification | Safety standard compliance filters non-domestic vendors from automotive battery assembly lines. |
| AI-Edge Control Software Development | Machine vision integration with real-time PLC bypasses traditional SCADA hierarchies in semiconductor packaging. |
| Chubu Region Service Ecosystem Expansion | Predictive maintenance deployment targets Nagoya-centered automotive supply chain underpenetration. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads at Japanese automotive and electronics manufacturers. Secondary validation drew from METI industrial policy filings, JIS standard certification databases, customs trade records for automation equipment imports, and SEC 10-K disclosures of listed Japanese industrial conglomerates. Bottom-up segment sizing triangulated against top-down macroeconomic industrial production indices.
Across the analysis window, value and volume projections were derived from modeled segmentation across technology tier, end-use industry intensity, solution bundling configuration, and regional adoption maturity. CAGRs were computed from fitted growth curves incorporating capital expenditure cycles at named automotive battery plants and semiconductor packaging facilities. Forecast inputs included Society 5.0 subsidy allocation trajectories and JIS B 8433 certification pipeline visibility.
Forecasts assume regulatory continuity in METI policy frameworks and PMDA electromagnetic compatibility protocols; material policy shifts would require re-modeling. Specific risks include rare earth supply disruption, yen volatility effects on automation ROI calculus, and brownfield integration complexity with legacy MELSEC architectures. Recalibration cycles align with material shifts in subsidy disbursement timing and collaborative robot safety standard revision schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Industrial Human-Machine Interface Market
Industrial Automation
Parcel Sortation Systems Market
Industrial Automation
North America Industrial Vending Machine Market
Industrial Automation
Smart Sorting Line Market
Industrial Automation
Industrial Networking Solutions Market
Industrial Automation
Smart Escalator Market
Industrial Automation
Factory Automation in Japan Market
Industrial Automation
Industrial Internet Connectivity Tracker Market
Industrial Automation
Europe Water Automation and Instrumentation Market
Industrial Automation
Europe Factory Automation and Industrial Controls Market
Industrial Automation
Refining Industry Automation and Software Market
Industrial Automation
France Factory Automation and Industrial Controls Market
Industrial Automation
Industry 4.0 Market
Industrial Automation
Cold Storage AGV Market
Industrial Automation
Asia Industry 4.0 Market
Industrial Automation
Global PC Based Automation Market