
 Europe ICS Market | 2026-2036
Europe ICS Market Size, Share, and Industry Trends Forecast 2026-2036
Europe ICS Market Foresight
Energy utilities and water infrastructure operators are reorganizing procurement priorities around cyber-physical resilience, displacing traditional manufacturing buyers as the fastest-growing customer archetype in the European ICS landscape. Siemens AG leverages deep vertical integration across power automation to sustain pricing power in German and Nordic utility tenders. Schneider Electric anchors its position through edge-to-cloud orchestration platforms purpose-built for distributed renewable assets. ABB competes aggressively in maritime and offshore deployment settings where salt-corrosion ratings and SIL-3 certification requirements filter out smaller rivals.
Industrial control systems encompass hardware and software architectures that monitor, regulate, and automate physical processes through real-time data acquisition, typically executing control loops within millisecond response windows to maintain operational safety and efficiency. Programmable logic controllers handle discrete manufacturing sequences with deterministic scan cycles, while distributed control systems govern continuous processes such as refining and chemical synthesis across geographically spread unit operations. Safety instrumented systems command premium engineering margins due to IEC 61511 compliance burdens and third-party certification requirements that extend sales cycles but lock in long-term service revenues. Cloud-based solutions are gaining traction among mid-sized chemical processors seeking to outsource SCADA hosting, though on-premises architectures still dominate power generation where air-gapped networks remain mandatory.
The EU Cyber Resilience Act and NIS2 Directive are forcing ICS vendors to embed security-by-design into hardware shipped across member states, with conformity assessments now extending to software update mechanisms and vulnerability disclosure timelines. ECHA's REACH restrictions on flame-retardant additives in enclosure materials are pushing manufacturers toward halogen-free thermoplastic compounds that meet UL 94 V-0 ratings without legacy substances. Germany's BSI publishes sector-specific baseline protection catalogues that federal operators must implement, creating de facto procurement standards that ripple through supply chains. Stakeholders must decide whether to absorb compliance costs through in-house certification teams or outsource to notified bodies that carry backlog risks extending market entry timelines.
Market Dynamics
The EU Cyber Resilience Act is compressing product certification timelines while forcing automation vendors to reengineer hardware architectures for embedded security, fundamentally altering how control systems reach European industrial buyers.
Growth Catalysts
- Water treatment modernization:Utilities across Germany and the Netherlands are retrofitting legacy plants with networked safety systems to meet stricter effluent standards. Connected control architectures enable real-time quality monitoring that reduces chemical overuse.
- REACH compliance innovation:ECHA restrictions on halogenated flame retardants are accelerating adoption of halogen-free thermoplastic enclosures rated UL 94 V-0. Material suppliers with certified compound portfolios are capturing specification authority from system integrators.
- Renewable asset digitization:Distributed solar and wind installations require edge-to-cloud orchestration platforms for predictive maintenance. Nordic energy cooperatives are deploying these systems faster than centralized utilities.
Market Restraints
- Semiconductor supply concentration:Industrial-grade microcontrollers and FPGA chips depend on Taiwanese and South Korean foundry capacity. Lead times for safety-critical components extend procurement cycles beyond European project deadlines.
- Certification cost escalation:IEC 61511 SIL-3 compliance requires third-party validation that adds engineering margins exceeding smaller automation vendors' annual R&D budgets.
- Legacy protocol persistence:Proprietary fieldbus standards from the 1990s remain entrenched in German chemical corridors. Migration to Ethernet-based architectures demands forklift replacements that plant managers defer.
Strategic Opportunities
- Polish industrial corridor expansion:Automotive OEMs are establishing battery cell manufacturing clusters near Wrocław and Poznań. Greenfield facilities specify native cybersecurity architectures unavailable in retrofitted German plants.
- Maritime certification premium:Offshore wind service vessels and hydrogen transport ships require salt-corrosion rated controllers with marine-grade sealing. ABB's existing offshore positioning creates specification templates competitors must match.
- NIS2 Directive service bundling:Federal operators in Germany must implement BSI baseline protection catalogues by mandated deadlines. Vendors offering compliance-as-a-service alongside hardware capture recurring revenue streams.
Industry Challenges
- Cyber-physical systems engineering scarcity:Control theory expertise must now merge with embedded security architecture skills. Universities in Stuttgart and Munich produce insufficient graduates fluent in both deterministic control loops and cryptographic key management.
- Air-gapped network integration friction:Power generation operators maintain mandatory isolated networks. Cloud-native monitoring solutions require data diode architectures that complicate vendor support models and inflate deployment costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe ICS Market |
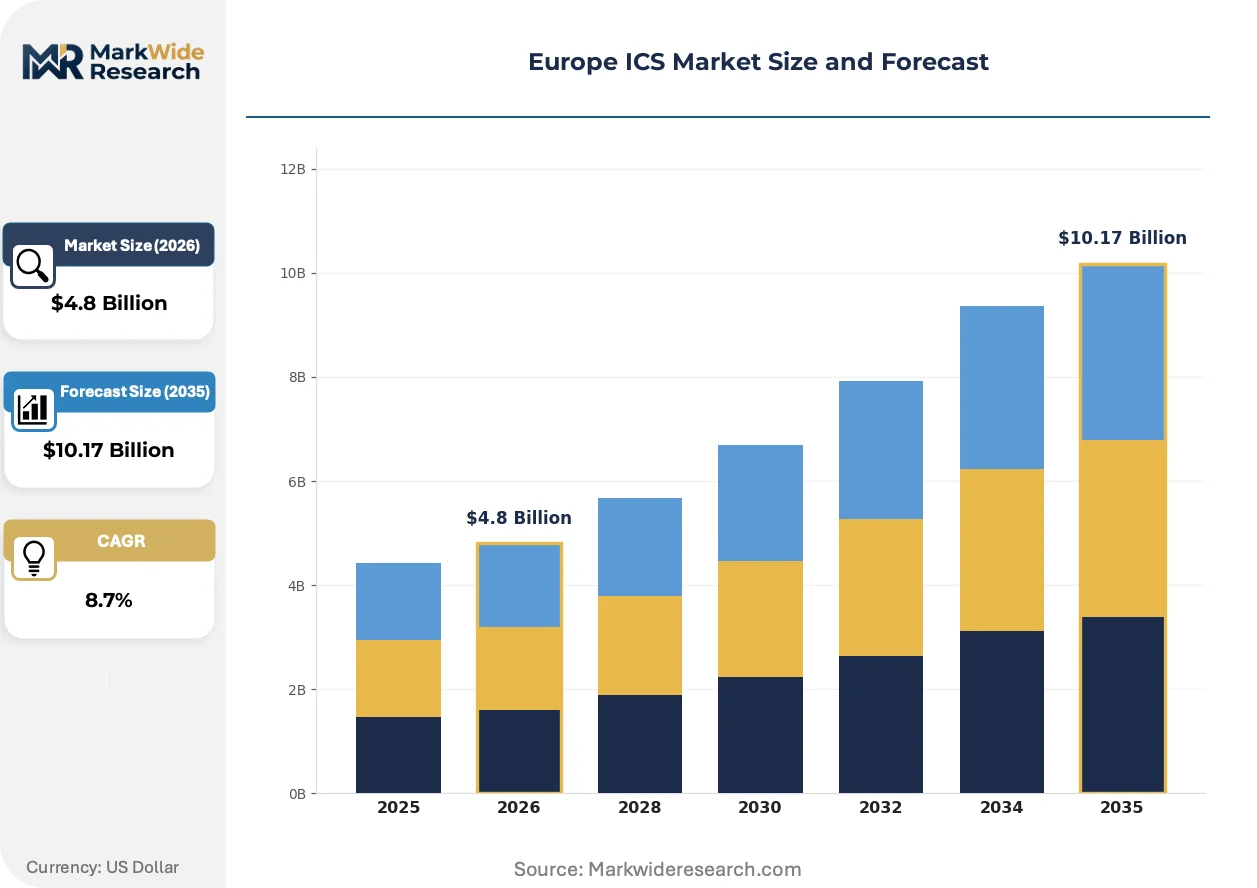
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Distributed Control Systems, Programmable Logic Controllers, Safety Instrumented Systems, Human Machine Interfaces End User: Manufacturing, Oil & Gas, Chemical, Power Generation Technology: Cloud-based Solutions, On-premises Solutions, Hybrid Systems, Edge Computing Deployment: Onshore, Offshore, Remote Sites, Industrial Locations |
| Companies Covered | Siemens AG, ABB, Schneider Electric, Honeywell International Inc., IBM, Emerson Electric Co., Mitsubishi Electric Corporation, Juniper Networks Inc., Tofino Security, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe ICS Market Shifts & Advancements
Edge-native control architectures are redefining latency requirements across process industries, while regulatory mandates accelerate security-by-design adoption and buyer procurement models pivot toward outcome-based service structures.
Time-sensitive networking over standard Ethernet is supplanting proprietary fieldbus protocols in discrete manufacturing environments. Automotive OEMs in Bavaria and Baden-Württemberg are specifying TSN-enabled controllers for new assembly lines. This convergence is compressing vendor differentiation around software stacks rather than physical layer dominance.
The EU Cyber Resilience Act mandates conformity assessments for software update mechanisms and vulnerability disclosure timelines across all hardware shipped to member states. Industrial automation vendors must now embed cryptographic identity modules and secure boot chains at the silicon level. German power utilities are prioritizing suppliers with pre-certified update infrastructures, filtering out smaller competitors without dedicated compliance teams.
Utility procurement departments are unbundling hardware acquisition from long-term service contracts, reversing decades of bundled pricing. Mid-sized chemical processors in Belgium and the Netherlands now solicit separate bids for SCADA hosting, field maintenance, and cybersecurity monitoring. This disaggregation is most visible in water infrastructure tenders where municipal operators lack internal OT security expertise and outsource vulnerability management to specialized service providers.
Europe ICS Market Segmentation
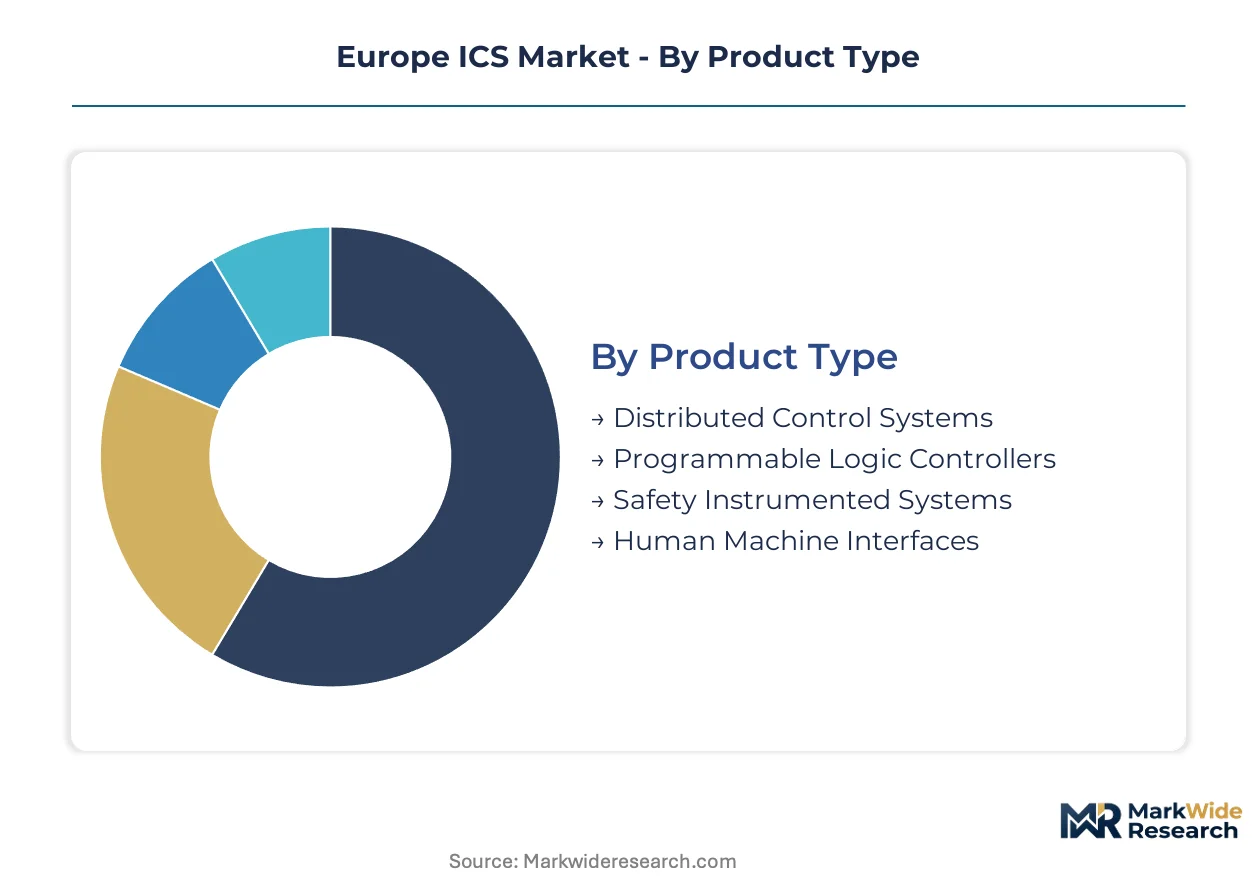
Segmentation reveals how procurement channels fragment across the European ICS landscape. System integrators and direct OEM sales compete differently depending on product complexity, end-user sophistication, and regulatory exposure.
Product Type:
Distributed Control Systems flow through engineering-procurement-construction contractors serving continuous process industries. Programmable Logic Controllers reach discrete manufacturers via distributor networks with local stocking. Safety Instrumented Systems and Human Machine Interfaces split between certified system integrators and direct vendor relationships based on SIL certification requirements.
- Distributed Control Systems:Architectures govern continuous processes such as refining and chemical synthesis across geographically distributed unit operations. German chemical corridors along the Rhine and Ruhr concentrate retrofit demand as legacy DCS platforms age beyond vendor support lifecycles. REACH compliance burdens and IEC 61511 validation requirements extend sales cycles but lock in decade-long service contracts.
- Programmable Logic Controllers:Deterministic scan-cycle controllers execute discrete manufacturing sequences with millisecond response windows. Bavarian and Baden-Württemberg automotive OEMs specify TSN-enabled controllers for new assembly lines, displacing proprietary fieldbus architectures. Time-sensitive networking convergence compresses vendor differentiation toward software stack capabilities rather than physical layer dominance.
- Safety Instrumented Systems:IEC 61511 SIL-3 certified architectures command premium engineering margins through mandatory third-party validation.
- Human Machine Interfaces:Operator visualization platforms integrate alarm management and batch reporting for process oversight.
By volume, Programmable Logic Controllers lead. By growth pace, Safety Instrumented Systems is ahead.
End User:
Cost tier differentiation separates premium-certified deployments from standard automation in this category. Oil & Gas and Chemical sectors absorb compliance burdens that Manufacturing and Power Generation avoid through air-gapped architectures.
- Manufacturing:Discrete production lines in automotive and machinery sectors prioritize TSN-enabled Ethernet architectures over legacy fieldbus. Polish battery cell manufacturing clusters near Wrocław and Poznań specify native cybersecurity architectures unavailable in retrofitted German plants. Greenfield facilities bypass proprietary protocol lock-in that constrains legacy corridor modernization.
- Oil & Gas:Continuous process hazards demand SIL-certified safety instrumented systems with third-party validation. North Sea offshore platforms and Norwegian continental shelf developments require salt-corrosion rated controllers with marine-grade sealing specifications. ABB's existing offshore positioning creates procurement templates competitors must match to qualify.
- Chemical:REACH restrictions on halogenated flame retardants accelerate halogen-free thermoplastic enclosure specifications rated UL 94 V-0.
- Power Generation:Mandatory air-gapped networks isolate generation assets from cloud-native monitoring solutions.
Manufacturing captures the largest installed base. Oil & Gas delivers the steepest expansion trajectory.
Technology:
Application context determines architecture selection. Continuous processes favor on-premises reliability. Distributed renewables drive edge and cloud adoption.
- Cloud-based Solutions:SCADA hosting and predictive analytics platforms serve mid-sized chemical processors in Belgium and the Netherlands seeking outsourced operational technology management. Municipal water infrastructure operators lacking internal cybersecurity expertise contract vulnerability management to specialized service providers. EU Cyber Resilience Act conformity assessments filter vendors without dedicated compliance teams.
- On-premises Solutions:Air-gapped architectures remain mandatory in German power generation where BSI baseline protection catalogues mandate network isolation. Data diode architectures complicate vendor support models and inflate deployment costs for cloud-native monitoring integration. Federal operators prioritize suppliers with pre-certified update infrastructures.
- Hybrid Systems:Edge-to-cloud orchestration bridges operational reliability with centralized analytics.
- Edge Computing:Latency-critical control loops execute at source for renewable asset digitization.
On-premises Solutions retains dominant share. Edge Computing is gaining share fastest.
Deployment:
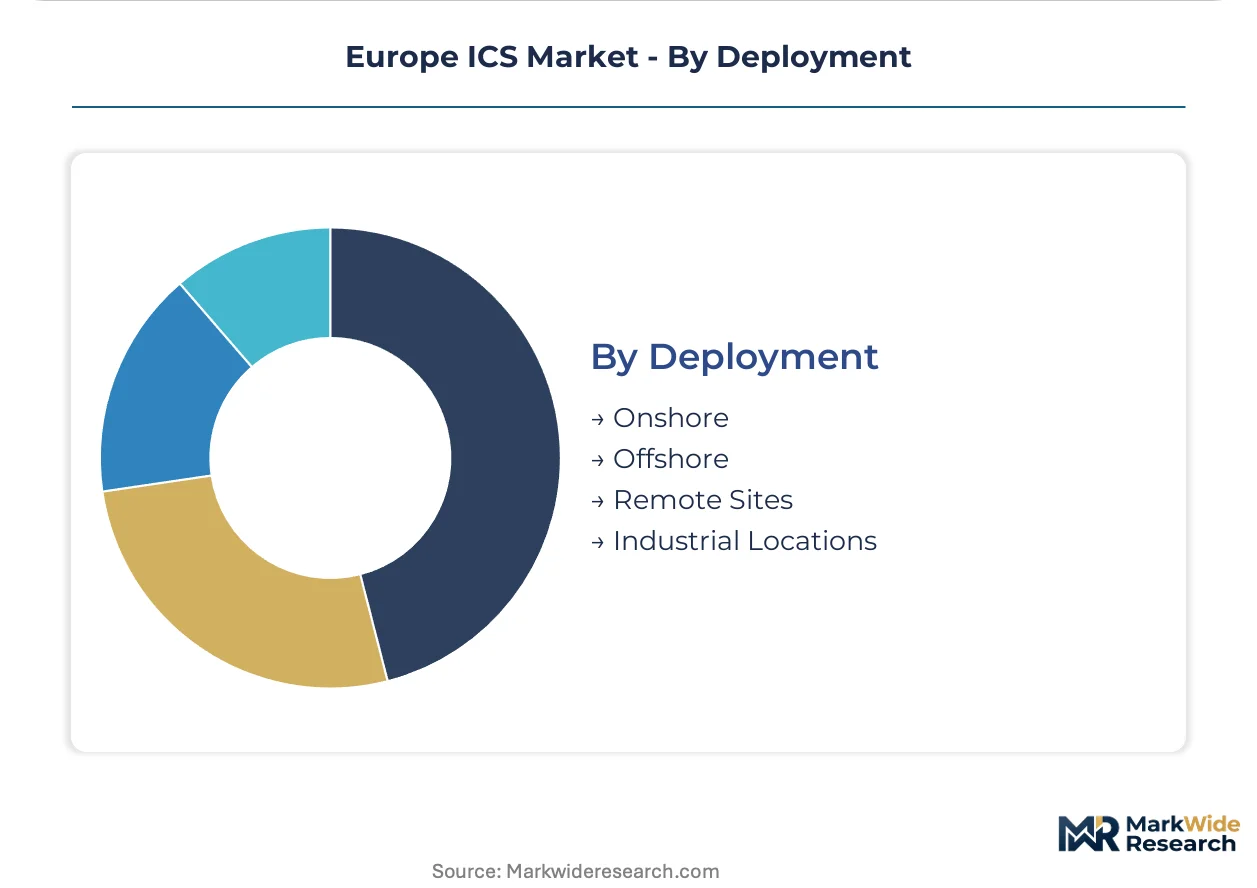
Geography and accessibility shape channel economics. Remote and offshore deployments concentrate premium service margins with vertically integrated vendors.
- Onshore:Industrial corridors in Germany's Rhine-Ruhr and Netherlands Rotterdam-Antwerp axis concentrate retrofit demand for legacy DCS modernization. Proprietary fieldbus standards from the 1990s persist in German chemical plants. Migration to Ethernet-based architectures demands forklift replacements that plant managers defer amid semiconductor supply constraints.
- Offshore:North Sea wind service vessels and hydrogen transport ships require salt-corrosion rated controllers with marine-grade sealing and SIL-3 certification. ABB competes aggressively in maritime settings where environmental ratings filter smaller rivals lacking offshore engineering heritage.
- Remote Sites:Distributed solar and wind installations require edge-native architectures for predictive maintenance.
- Industrial Locations:Greenfield battery manufacturing clusters specify native cybersecurity unavailable in retrofitted plants.
Onshore deployments dominate current revenue. Offshore is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial automation supply chains concentrate in German engineering clusters, with vendor engineering centers and certification laboratories anchoring procurement timelines for utilities across the continent.
Germany
Rhine-Ruhr chemical corridors and Bavarian automotive assembly lines drive retrofit demand for networked safety systems. BSI baseline protection catalogues mandate air-gapped network architectures for federal power operators. Stuttgart and Munich engineering universities struggle to produce graduates fluent in both control theory and embedded security architecture.
Netherlands
Rotterdam-Antwerp port logistics and water treatment infrastructure accelerate connected control adoption for effluent monitoring. REACH compliance deadlines force rapid substitution of halogenated flame retardants in enclosure materials. Municipal operators around Amsterdam outsource SCADA cybersecurity to specialized service providers lacking internal OT expertise.
Poland
Battery cell manufacturing clusters near Wrocław and Poznań specify native cybersecurity architectures unavailable in retrofitted German plants. EU Cyber Resilience Act conformity assessments filter smaller automation vendors without dedicated certification teams. Greenfield automotive facilities bypass proprietary fieldbus lock-in that constrains legacy corridor modernization.
France
Nuclear power generation assets maintain mandatory isolated networks that complicate cloud-native monitoring integration. ECHA restrictions on legacy flame-retardant additives push enclosure manufacturers toward halogen-free thermoplastic compounds. Île-de-France engineering consultancies specialize in SIL-3 validation for offshore wind developments.
Norway
North Sea offshore platforms and continental shelf developments require salt-corrosion rated controllers with marine-grade sealing specifications. Distributed renewable cooperatives deploy edge-to-cloud orchestration faster than centralized utilities. Bergen and Stavanger engineering offices concentrate subsea automation expertise for hydrogen transport vessel certification.
Europe ICS Market Competitive Landscape
Concentration sits with diversified industrial conglomerates possessing captive certification infrastructure and multi-decade utility relationships. Three to four European-headquartered engineering groups control premium-tier tenders through bundled hardware-service offerings. Mid-sized specialists compete on maritime and offshore verticals where environmental ratings filter generalist competitors. Dominant competitive moves include M&A to acquire cybersecurity software capabilities and strategic partnerships with semiconductor suppliers to secure safety-critical component allocation.
Within the diversified engineering tier, Siemens AG, ABB, and Schneider Electric exemplify archetypes of vertical integration across power automation, offshore positioning, and edge-to-cloud orchestration respectively. Siemens occupies a position defined by deep utility relationships in German and Nordic markets. ABB anchors maritime and offshore deployment settings where salt-corrosion specifications create procurement barriers. Schneider Electric represents the renewable asset digitization vector through distributed energy management platforms.
| Leading Market Players |
|---|
| Siemens AG |
| ABB |
| Schneider Electric |
| Honeywell International Inc. |
| IBM |
| Emerson Electric Co. |
| Mitsubishi Electric Corporation |
| Juniper Networks Inc. |
| Tofino Security |
| Others |
Supply & Pricing Matrix
Foundry-scale economies in Taiwanese and South Korean semiconductor manufacturing anchor cost structures across safety-critical controller tiers, compressing margins for European system integrators while elevating procurement leverage for volume buyers in German utility corridors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates SIL-3 certified safety systems from general-purpose PLCs and entry-level HMI panels. Price differentiation hinges on IEC 61511 validation burden and embedded security module integration mandated by EU Cyber Resilience Act conformity assessments. Cost compression in mid-tier DCS retrofits is intensifying because REACH-compliant halogen-free enclosure materials carry 15-20% raw material premiums. Municipal water operators in the Netherlands exhibit highest price sensitivity due to constrained public procurement budgets, while North Sea offshore developers absorb premium pricing for marine-grade sealing specifications.
Supply Chain Analysis
Strategic stockpiling of industrial-grade microcontrollers and FPGA chips has displaced just-in-time preferences among German automation vendors confronting Taiwanese foundry allocation constraints. Component sourcing draws from Taiwan, South Korea, and Japan for safety-critical silicon, with halogen-free thermoplastic compounds increasingly supplied from domestic European compounders to satisfy ECHA REACH deadlines. Single-source vulnerability concentrates in 28nm automotive-grade microcontroller supply. Distribution runs through engineering-procurement-construction contractors for DCS deployments and authorized distributor networks for PLC volume sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Cyber Resilience Act imposes embedded security mandates that favor vendors with pre-certified hardware architectures, creating a regulatory inflection that accelerates consolidation among compliance-capable suppliers.
For Market Incumbents: Secure captive allocation agreements with Taiwanese foundries for safety-critical microcontroller supply before project backlog extends beyond BSI-mandated implementation deadlines. Invest in in-house certification teams to bypass notified body queue risks that delay market entry for competitors. Defensive consolidation around cybersecurity software capabilities through targeted capability acquisition addresses the threat of cloud-native monitoring entrants.
For New Entrants and Emerging Players: Compliance-as-a-service bundling for NIS2 Directive implementation represents the most penetrable white-space target, as federal operators in Germany lack internal OT security expertise and outsource vulnerability management. Polish battery manufacturing clusters near Wrocław and Poznań offer greenfield specification authority unavailable in retrofitted German chemical corridors. A channel partnership strategy with municipal water infrastructure operators bypasses direct competition with entrenched EPC contractor relationships.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vendors offering long-term service contracts alongside SIL-certified hardware, locking in decade-long maintenance streams that outperform transactional equipment sales. The five-to-ten year viability window favors targets with demonstrated offshore engineering heritage in maritime and subsea automation. Watch for BSI baseline protection catalogue deadline acceleration as the signal indicating procurement urgency inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Cybersecurity Certification Investment | EU Cyber Resilience Act conformity assessments filter vendors without embedded security architecture capabilities. |
| Foundry Partnership Agreement | Taiwanese semiconductor allocation security determines project delivery reliability for German utility tenders. |
| Halogen-Free Material Transition | ECHA REACH restrictions on legacy flame retardants force rapid compound supplier qualification. |
| Compliance-as-a-Service Launch | NIS2 Directive implementation deadlines create recurring revenue streams from federal operator outsourcing. |
| Offshore Engineering Capability Buildout | North Sea wind and hydrogen transport specifications demand salt-corrosion rated controller expertise. |
Research Methodology
Initial hypotheses were tested against primary input from plant engineering directors, utility procurement officers, system integration specialists, and regulatory compliance leads and refined through secondary validation against ECHA substance restriction databases, BSI protection catalogues, IEC standard documentation, and customs trade flow records. Bottom-up segment sizing across product type, end user, technology, and deployment dimensions was triangulated against top-down market envelope estimates derived from vendor revenue disclosures and EPC contractor project pipelines.
Variance decomposition across the projection horizon isolates volume drivers from price-mix effects, with segmentation modeling spanning distributed control systems, programmable logic controllers, safety instrumented systems, and human machine interfaces by manufacturing, oil and gas, chemical, and power generation end uses. CAGRs were derived from fitted growth curves incorporating EU regulatory implementation timelines, semiconductor supply recovery assumptions, and greenfield capital expenditure patterns in Polish industrial corridors.
Material uncertainties — foundry capacity reallocation, REACH substance restriction expansion, and NIS2 enforcement intensity escalation — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding certification timeline standardization and BSI catalogue adoption velocity. Revision becomes warranted when Taiwanese semiconductor allocation priority shifts cross thresholds that disrupt European project delivery schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
UK Industrial Automation System Integrator Market
Industrial Automation
Smart Elevator Market
Industrial Automation
Global Electric Gripper Market
Industrial Automation
Asia Industry 4.0 Market
Industrial Automation
Asia-Pacific Automation Components Market
Industrial Automation
Geosteering Technology Market
Industrial Automation
SCADA Alarm Management Market
Industrial Automation
Latin America Factory Automation and Industrial Controls Market
Industrial Automation
Industrial Networking Solutions Market
Industrial Automation
Safety Programmable Controller Market
Industrial Automation
Smart and Connected Elevators and Elevators Control Systems Market
Industrial Automation
Programmable Logic Controller Market
Industrial Automation
Port Equipment Automation Market
Industrial Automation
Cold Storage AGV Market
Industrial Automation
Digital Rotator Market
Industrial Automation
Asia Pacific Manufacturing Execution Systems (MES) Market