
 Palletizing Systems Market | 2026-2036
Palletizing Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Palletizing Systems Market Analysis
Aftermarket service revenue is fragmenting across hardware-software bundles as OEMs defend recurring income streams. ABB Ltd. leverages its RobotStudio simulation platform to lock in long-term service contracts with beverage bottlers. KUKA Aktiengesellschaft anchors German automotive palletizing through deep integration with Mercedes-Benz and BMW assembly lines. FANUC Corporation dominates high-speed robotic cells in Japanese electronics fulfillment with predictive maintenance offerings that reduce unplanned downtime.
Palletizing systems mechanically arrange cases, bags, or containers into unit loads on pallets using layer-forming, pick-and-place, or articulated-arm methods, typically operating at throughputs from 10 to 200 cycles per minute depending on payload and gripper technology. Their primary purpose is to protect product integrity during transport while maximizing cubic efficiency in trailer and container loading. Robotic system types capture the fastest expansion as collaborative arms with vision guidance penetrate mid-volume food processing lines where changeover flexibility outweighs pure speed. Conventional high-speed layer palletizers sustain margin pools in cement and chemical bulk operations where throughput per hour remains the decisive specification. Load capacity segmentation shows high-capacity units concentrating in automotive and building materials, while custom capacity configurations grow in pharmaceutical serialization lines that handle irregular vial and blister pack geometries.
OSHA machine guarding standards in the United States mandate light curtain and area scanner integration on new robotic installations, directly inflating system cost and engineering complexity. The EU Machinery Directive and CE marking requirements enforce functional safety ratings that favor established European OEMs with certified control architectures. Stakeholders must monitor how ISO 10218 robot safety updates and evolving FDA sanitary equipment design guidelines reshape hardware specifications and aftermarket upgrade cycles.
Market Dynamics
Robotic palletizing architectures are hybridizing with vision-guided collaborative arms, compressing the traditional speed-versus-flexibility trade-off that has long segmented the market between high-speed layer machines and articulated-arm systems.
Growth Catalysts
- FDA Sanitary Design Mandates:Food and beverage processors face intensifying compliance deadlines for washdown-capable equipment, accelerating replacement cycles in dairy and ready-meal facilities.
- EU Green Deal Energy Standards:Distribution centers across Germany, France, and Italy must retrofit legacy pneumatic systems with servo-electric drives to meet mandated efficiency thresholds.
- Automotive OEM Automation Clusters:German manufacturers anchor dense supplier ecosystems around Stuttgart and Munich, creating localized demand spikes for high-capacity palletizing cells.
Market Restraints
- Stainless Steel Input Volatility:Sanitary-grade 304 and 316 stainless steel price swings compress margins on FDA-compliant equipment, particularly affecting mid-tier system builders.
- Servo Drive Supply Concentration:Japanese and German motion control suppliers dominate high-precision servo markets, exposing OEMs to single-source risks during capacity constraints.
- ISO 10218 Safety Certification Delays:Functional safety validation for collaborative robot installations extends project timelines by four to eight months in European markets.
Strategic Opportunities
- Indian Pharmaceutical Serialization:Track-and-trace mandates from CDSCO drive demand for custom-capacity palletizers handling irregular vial geometries in Mumbai and Hyderabad production hubs.
- 5G-Enabled Predictive Maintenance:Convergence of industrial IoT sensors with low-latency cellular networks allows OEMs to unbundle hardware-software service contracts for recurring revenue.
- US IRA Clean Manufacturing Credits:Domestic content incentives for greenfield food processing facilities accelerate capital deployment in automated end-of-line systems.
Industry Challenges
- Mechatronics Skill Scarcity:Integration of PLCs, servo systems, and vision hardware demands technicians with cross-domain expertise that vocational pipelines struggle to produce.
- Legacy Pneumatic Infrastructure:Brownfield sites in mature manufacturing regions face complex retrofit engineering to accommodate electric drive architectures without full line shutdowns.
- CE Marking Documentation Burden:Technical file compilation for EU Machinery Directive compliance consumes engineering resources disproportionately at smaller system integrators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Palletizing Systems Market |
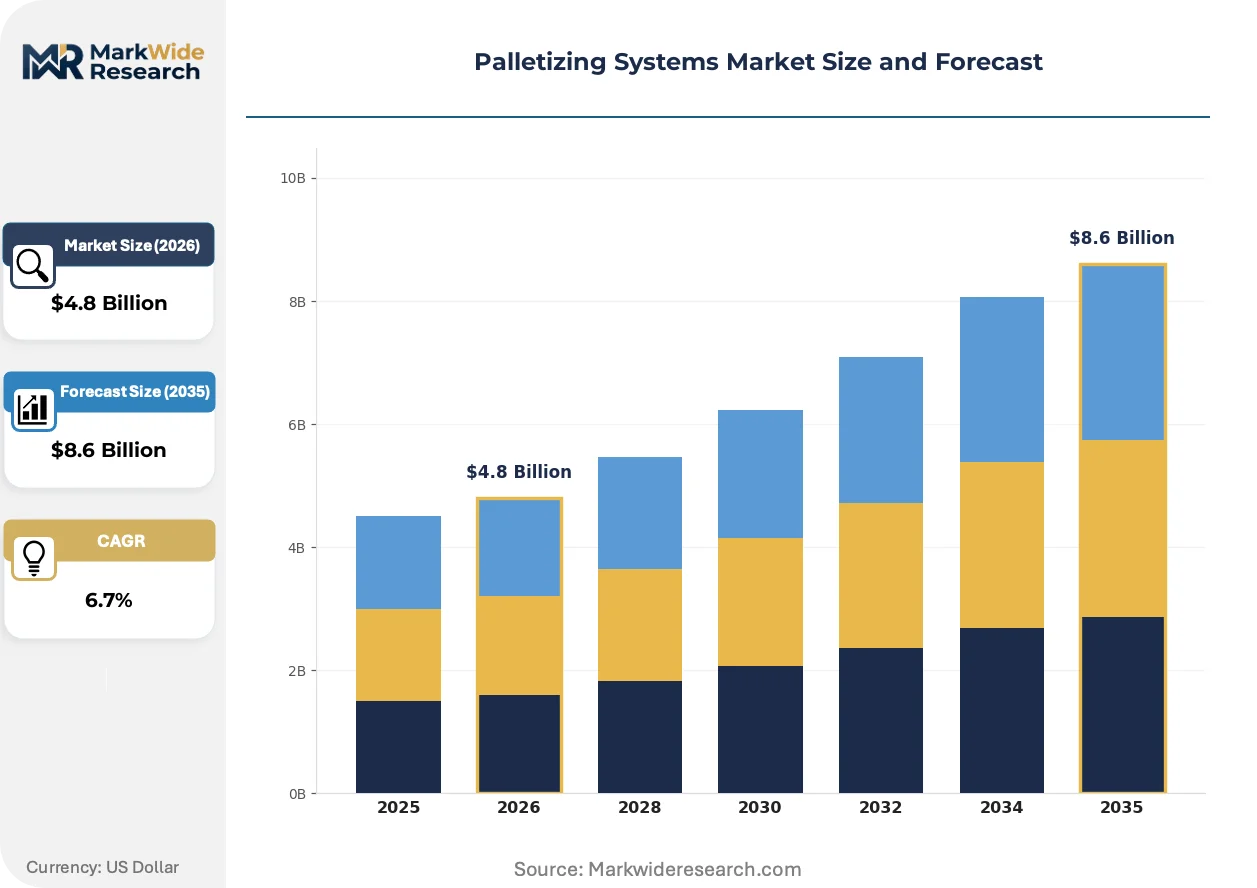
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Conventional, Robotic, Automated, Semi-Automated Load Capacity: Low Capacity, Medium Capacity, High Capacity, Custom Capacity Industry Application: Food & Beverage, Pharmaceutical, Consumer Goods, Automotive End User: Manufacturers, Distributors, Warehouses, Retailers |
| Companies Covered | ABB Ltd., KUKA Aktiengesellschaft, Daifuku Co., Ltd., Comau SpA, Yaskawa Electric Corporation, SSI Schaefer Holding GmbH, FANUC Corporation, Fives Group S.A., Beumer Group GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Palletizing Systems Market Emerging Trajectories
End-of-line automation is fragmenting into modular, software-defined architectures that decouple mechanical hardware from control intelligence, enabling rapid reconfiguration without mechanical changeover.
Collaborative robot palletizing is hybridizing layer-forming and pick-and-place methods into unified cells that adjust grip patterns and stacking algorithms in real time. Mid-volume food processors in the Netherlands and Belgium adopt these systems to manage SKU proliferation without dedicated lines. The technology is hybridizing what were historically separate equipment categories, eroding the market boundary between robotic and conventional palletizer suppliers.
OSHA machine guarding standards now mandate light curtain and area scanner integration on all new robotic installations in the United States. This regulatory pressure inflates system cost and engineering complexity, particularly for retrofit projects. Beverage bottlers in California and Texas respond by bundling safety upgrades with full line modernization rather than incremental improvements.
Aftermarket service contracts are unbundling from hardware sales as buyers demand outcome-based uptime guarantees. German automotive OEMs now specify availability metrics rather than spare parts inventories in procurement tenders. This shift concentrates service revenue with OEMs possessing remote diagnostics infrastructure, visible most acutely in Mercedes-Benz and BMW supplier networks.
Palletizing Systems Market Segmentation
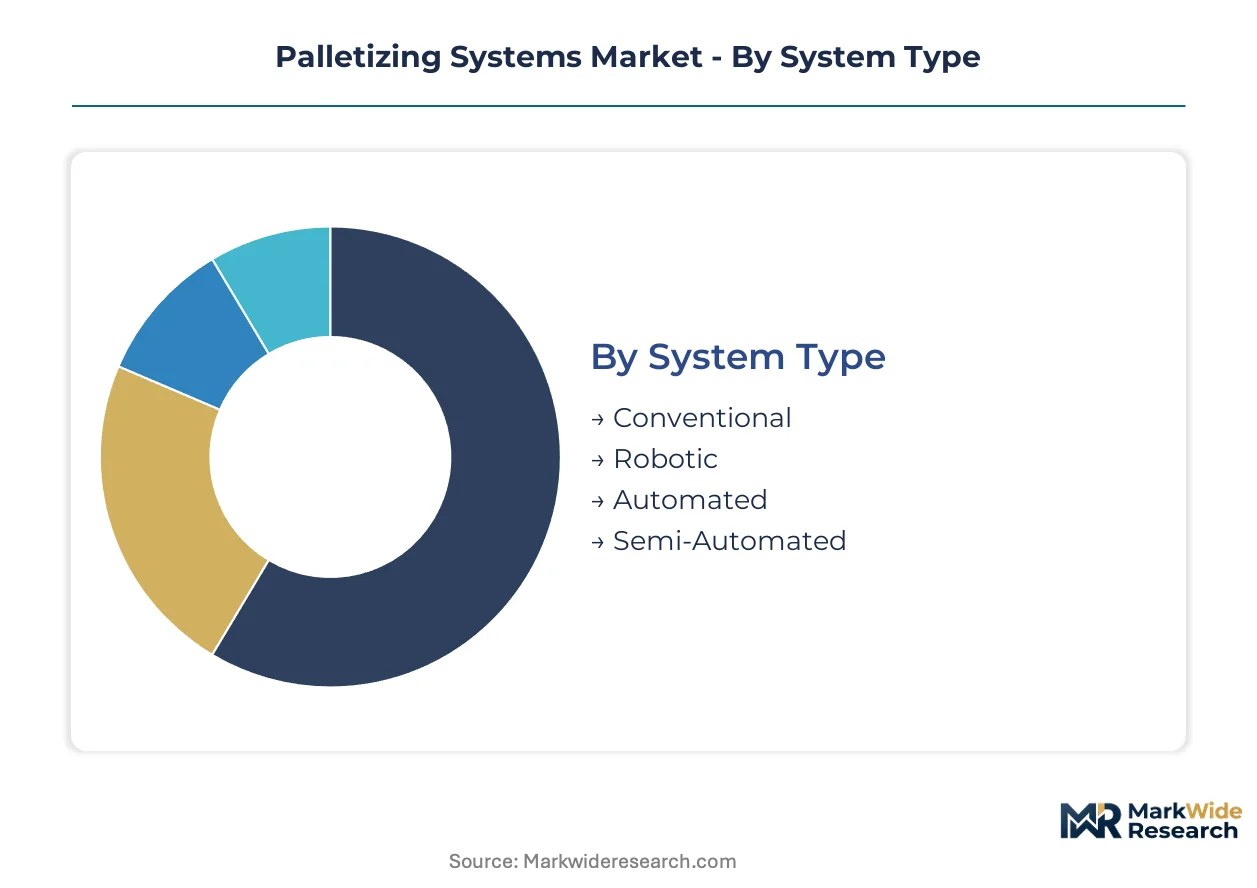
Palletizing system configurations vary sharply in service attachment rates and lifecycle revenue profiles. Aftermarket intensity differs by system complexity, load capacity, and end-user operational criticality.
System Type:
After-sales service intensity escalates with control system sophistication and software dependency.
- Robotic:Articulated-arm systems integrate servo drives, vision hardware, and path-planning software that demand continuous calibration and predictive maintenance contracts. German automotive OEMs and Japanese electronics fulfillment centers anchor replacement parts and remote diagnostics revenue.
- Conventional:Layer-forming machines with mechanical indexing and pneumatic actuation require periodic component replacement but minimal software support. Cement and chemical bulk operators in the United States and India sustain steady demand for wear parts and pneumatic valve rebuilds.
- Automated:Integrated cells combining multiple material handling functions generate bundled service contracts spanning controls, conveyors, and pallet dispensers.
- Semi-Automated:Operator-assisted systems with manual case presentation carry lower service attachment due to reduced control complexity and higher in-house maintenance capability.
Conventional systems hold the largest share; momentum sits with robotic architectures.
Load Capacity:
Capital deployment and margin profiles stratify by tonnage rating and application engineering requirements.
- High Capacity:Units rated above 50 kg per cycle employ reinforced gantries and heavy-duty servo systems for automotive powertrain components and building materials. German manufacturers around Stuttgart specify these for engine block and battery pack handling.
- Custom Capacity:Configurations for irregular geometries—pharmaceutical vials, blister packs, flexible pouches—require application-specific end-effectors and stacking algorithms. Indian pharmaceutical serialization mandates from CDSCO drive specification in Mumbai and Hyderabad production hubs.
- Medium Capacity:Standard 20-50 kg ratings serve beverage cases and consumer goods cartons with balanced throughput and flexibility.
- Low Capacity:Sub-20 kg systems target lightweight consumer electronics and specialty food items with compact footprints and lower energy consumption.
High capacity dominates revenue concentration; custom capacity configurations are climbing the fastest.
Industry Application:
Regulatory compliance intensity and sanitation requirements reshape specification patterns across verticals.
- Food & Beverage:FDA sanitary design mandates for washdown-capable equipment accelerate replacement cycles in dairy and ready-meal facilities. Stainless steel construction and sealed electronics inflate initial cost but reduce contamination risk.
- Automotive:OEM automation clusters in Germany and the United States demand high-capacity cells with traceability integration for just-in-sequence delivery.
- Pharmaceutical:Serialization and aggregation requirements impose validation documentation burdens that favor established suppliers with certified quality systems.
- Consumer Goods:SKU proliferation drives demand for rapid changeover flexibility in European distribution centers facing EU Green Deal retrofit deadlines.
Food & Beverage commands the greatest installed base; pharmaceutical applications show the steepest expansion trajectory.
End User:
Procurement authority and total cost of ownership calculations diverge by position in the supply chain.
- Manufacturers:Production-integrated palletizing demands uptime guarantees and line synchronization capabilities. Beverage bottlers in California and Texas bundle safety upgrades with full line modernization.
- Distributors:Mixed-SKU operations prioritize throughput flexibility over dedicated line speed, favoring robotic cells with vision-guided changeover.
- Warehouses:Third-party logistics operators emphasize capital efficiency and modular scalability across multi-tenant facilities.
- Retailers:Direct-to-store fulfillment networks specify compact footprints and low energy consumption for last-mile distribution centers.
Manufacturers represent the dominant procurement segment; distributors are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Japan exhibit low price elasticity as automation clusters prioritize uptime guarantees over capital savings, while distributors in India and Brazil remain highly sensitive to initial equipment costs despite rising throughput requirements.
United States
Beverage bottlers in California and Texas drive layer-palletizer replacements as they bundle OSHA-mandated safety upgrades with full line modernization. The Inflation Reduction Act's clean manufacturing credits accelerate capital deployment in greenfield food processing facilities. Midwest automotive suppliers around Detroit specify high-capacity cells for powertrain component handling.
Germany
Mercedes-Benz and BMW assembly lines anchor dense supplier ecosystems around Stuttgart and Munich, creating localized demand spikes for robotic palletizing cells. EU Green Deal energy efficiency mandates push distribution centers across Bavaria and Baden-Württemberg to retrofit legacy pneumatic systems with servo-electric drives. KUKA's proximity to these OEM clusters reinforces technical collaboration on just-in-sequence delivery integration.
Japan
Electronics fulfillment centers in the Kanto region specify high-speed robotic cells with predictive maintenance offerings to minimize unplanned downtime. FANUC's dominance in servo drive technology shapes local procurement patterns for precision motion control. METI industrial automation incentives support SME adoption of collaborative arms in Osaka-Kansai consumer goods operations.
India
CDSCO track-and-trace mandates drive demand for custom-capacity palletizers handling irregular vial geometries in Mumbai and Hyderabad pharmaceutical production hubs. Brownfield cement and chemical facilities in Gujarat sustain steady demand for conventional layer-palletizer wear parts. FSSAI sanitation compliance deadlines accelerate dairy processor equipment replacement in Maharashtra.
Netherlands
Mid-volume food processors in the Randstad adopt vision-guided collaborative systems to manage SKU proliferation without dedicated lines. EU Machinery Directive CE marking requirements favor established European OEMs with certified control architectures for Rotterdam distribution center retrofits. Belgian cross-border logistics operators source modular cells for mixed-SKU operations serving the Benelux corridor.
Palletizing Systems Market Vendor Landscape
Capability concentration sits with European and Japanese specialists possessing certified safety architectures and predictive maintenance infrastructure; scale advantage sits with diversified automation conglomerates serving multiple end-use verticals. The vendor base stratifies into three tiers: integrated robotics OEMs with software-defined control platforms, regional machinery builders focused on conventional layer-forming equipment, and emerging collaborative arm specialists penetrating mid-volume food processing. Dominant competitive moves include M&A to acquire vision guidance and AI-driven path-planning capabilities, plus vertical integration into servo drive and end-effector manufacturing to reduce supply chain exposure.
Among the integrated robotics tier, ABB Ltd., KUKA Aktiengesellschaft, and FANUC Corporation exemplify contrasting geographic and technological positioning. ABB's Swiss-Swedish structure situates it within European regulatory compliance frameworks, while KUKA's German AG form anchors automotive OEM relationships in Stuttgart and Munich. FANUC Corporation represents the Japanese specialist archetype with concentration in electronics fulfillment and precision servo applications. Daifuku Co., Ltd. and Yaskawa Electric Corporation occupy positions within the material handling and motion control segments respectively, with SSI Schaefer Holding GmbH exemplifying the German GmbH structure common to warehouse automation specialists.
| Leading Market Players |
|---|
| ABB Ltd. |
| KUKA Aktiengesellschaft |
| Daifuku Co., Ltd. |
| Comau SpA |
| Yaskawa Electric Corporation |
| SSI Schaefer Holding GmbH |
| FANUC Corporation |
| Fives Group S.A. |
| Beumer Group GmbH & Co. KG |
| Others |
Supply Flow & Price Mechanics
The Rotterdam-Antwerp freight corridor transmits stainless steel cost volatility from German mills to Dutch distribution centers, concentrating pricing power among servo-drive suppliers in Stuttgart and Munich while forcing tiered equipment premiums on FDA-compliant configurations.
Pricing Analysis
Long-term offtake contracts dominate high-capacity automotive installations, while spot procurement persists for brownfield retrofit components. Three-tier pricing structure across premium, standard, and economy levels separates CE-certified European OEMs from Asian system integrators and used-equipment brokers. Cost compression in sanitary-grade stainless steel inputs is intensifying because of nickel price instability, squeezing mid-tier builders most acutely. Beverage bottlers in California exhibit lowest price sensitivity as they bundle OSHA-mandated safety upgrades with full line replacements, whereas Indian pharmaceutical SMEs remain highly cost-conscious despite CDSCO serialization deadlines.
Supply Chain Analysis
Extended payment terms from German automotive OEMs cascade through Stuttgart supplier networks, compressing working capital for servo-drive assemblers. Component manufacturing concentrates in Germany, Japan, and China, with precision motion control anchored in Osaka-Kansai and Stuttgart industrial zones. Raw material dependencies span 304/316 stainless steel from Outokumpu mills, rare-earth magnets for servo motors, and optical sensors from Japanese semiconductor fabs. Single-source vulnerability in high-precision servo controllers exposes OEMs to allocation risk during capacity constraints. Distribution runs through authorized system integrators with certified safety engineering capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Palletizing system demand fragments across SKU-proliferating food processors and serialization-driven pharmaceutical lines, creating specialized niches for vision-guided collaborative arms and custom-capacity configurations.
For Market Incumbents: Entrench predictive maintenance infrastructure to lock in German automotive service contracts as Mercedes-Benz and BMW shift toward availability-based procurement. Capture backward integration into end-effector manufacturing to reduce exposure to Japanese gripper suppliers. Defend against emerging collaborative arm specialists by certifying control architectures under updated ISO 10218 safety protocols.
For New Entrants and Emerging Players: Build out remote diagnostics platforms to unbundle hardware-software service contracts in mid-volume food processing, where Dutch and Belgian operators prioritize changeover flexibility over speed. Target Indian pharmaceutical serialization as the most penetrable vertical, leveraging CDSCO track-and-trace mandates in Mumbai and Hyderabad. Pursue channel partnerships with established European OEMs lacking local service presence.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underoptimized palletizing divisions lacking software-defined control platforms. Long-term viability centers on OEMs possessing certified safety architectures and recurring revenue infrastructure. Monitor EU Green Deal retrofit acceleration across German distribution centers as inflection indicator for servo-electric demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Servo Drive Manufacturing | In-house production of precision motion controllers reduces exposure to Japanese and German supply concentration. |
| Vision Guidance Platform Acquisition | AI-driven path-planning capabilities compress changeover times for SKU-proliferating food processors in the Netherlands. |
| Predictive Maintenance Infrastructure Deployment | Remote diagnostics platforms capture recurring revenue from German automotive OEMs specifying uptime guarantees. |
| CE Marking Certification Investment | Functional safety ratings under EU Machinery Directive lock out non-European competitors in Rotterdam distribution retrofits. |
| Pharmaceutical Serialization Partnership | CDSCO-compliant custom-capacity configurations penetrate Mumbai and Hyderabad vial handling markets. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of EU Machinery Directive technical files, FDA sanitary equipment design guidelines, and customs trade data for stainless steel and servo drive imports. Plant engineers at beverage bottlers in California and Texas, aftermarket service heads at German automotive OEMs, and procurement leads at Indian pharmaceutical manufacturers provided operational perspectives. Technical validation drew from SEC filings of listed automation conglomerates, ISO 10218 safety standard documentation, and EIA industrial electricity consumption patterns. Bottom-up equipment shipment analysis triangulates against top-down end-use industry capital expenditure tracking.
Forecast inputs span system type segmentation by control architecture sophistication, load capacity tier by application engineering intensity, and end-use vertical by regulatory compliance burden across the analysis window. Modeled dimensions include robotic versus conventional versus hybrid system configurations, high-medium-low-custom capacity ratings, and manufacturer-distributor-warehouse-retailer procurement authority. CAGRs derive from fitted growth curves adjusted for replacement cycle timing and retrofit penetration assumptions. Industry-specific inputs incorporate EU Green Deal energy efficiency mandate compliance deadlines and CDSCO pharmaceutical serialization rollout phasing.
Sensitivities concentrate around stainless steel price volatility, servo drive supply allocation disruptions, and ISO 10218 safety certification timeline extensions. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and OEM consolidation trajectories. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Port Equipment Automation Market
Industrial Automation
Europe Intralogistics Automation Market
Industrial Automation
Modular High-Bay Solutions Market
Industrial Automation
Intelligent Conveyor System Market
Industrial Automation
GMC Based Motion Controller Market
Industrial Automation
Global Smart Manufacturing Platform Market
Industrial Automation
Global PC Based Automation Market
Industrial Automation
Agricultural Automation Market
Industrial Automation
Digital Transformation in Manufacturing Market
Industrial Automation
Global Discrete Automation Market
Industrial Automation
Japan Factory Automation and Industrial Controls Market
Industrial Automation
South East Asia Warehouse Automation Market
Industrial Automation
Asia Pacific Industrial Communication Market
Industrial Automation
Cross-Belt Sorters Market
Industrial Automation
Europe ICS Market
Industrial Automation
Robot Gearboxes Market