
 Factory Automation in Japan Market | 2026-2036
Factory Automation in Japan Market Size, Share, and Industry Trends Forecast 2026-2036
Factory Automation in Japan Market Insights
The gap between precision servo systems and basic pneumatic equipment is expanding as Japanese manufacturers split procurement strategies between high-mix, low-volume customization and mass-standardized output. Fanuc Corporation dominates robot density metrics across domestic automotive plants. Keyence Corporation differentiates through its direct sales model and rapid sensor calibration protocols. Mitsubishi Electric Corporation anchors controller architecture in heavy process industries.
Factory automation encompasses electromechanical systems, control software, and sensor networks that execute manufacturing tasks with minimal human intervention, typically operating at cycle times measured in milliseconds and positioning accuracies below 0.01 millimeters. Its primary purpose is to synchronize production flow, eliminate variance, and recover yield in continuous and discrete manufacturing environments. Robots capture the largest installed base while AI-enabled quality inspection represents the fastest-expanding margin pool. System integrators command premium pricing for retrofit deployments in legacy facilities.
METI's Industrial Cybersecurity Framework and JIS B 8433 robot safety standards shape equipment certification requirements and facility upgrade timelines. PMDA oversight intersects with automation in pharmaceutical packaging lines where validation protocols demand traceable control logic. Stakeholders must weigh in-house controller development against open-architecture partnerships as software-defined automation rewrites supplier power structures.
Market Dynamics
METI's Society 5.0 policy mandate is compressing upgrade timelines across Japanese manufacturing, forcing facility-level automation investments that previously spanned decades into single-digit-year execution cycles.
Growth Catalysts
- Automotive Electrification:Battery module assembly lines in Aichi Prefecture require precision motion control systems that exceed legacy pneumatic capabilities.
- METI Industrial Cybersecurity Framework:Certification deadlines for critical infrastructure manufacturers are accelerating controller replacement schedules.
- Pharmaceutical Serialization:PMDA track-and-trace mandates for packaging lines drive vision system and data logging investments.
Market Restraints
- Rare Earth Magnet Supply Concentration:Servo motor production faces input vulnerability from concentrated upstream rare earth processing.
- JIS B 8433 Compliance Burden:Robot safety recertification creates friction for retrofit deployments in legacy facilities.
- Semiconductor Component Lead Times:Industrial controller availability remains constrained by foundry capacity allocation.
Strategic Opportunities
- Kyushu Semiconductor Cluster:New fab construction creates demand for cleanroom automation and wafer handling systems.
- AI-Enabled Predictive Maintenance:Convergence of edge computing and vibration analysis opens service revenue models.
- Carbon Neutrality Roadmap:METI energy efficiency incentives subsidize motor drive upgrades in process industries.
Industry Challenges
- Mechatronics Engineering Shortage:System integrators struggle to staff projects requiring simultaneous mechanical, electrical, and software competency.
- Legacy PLC Architecture Migration:Brownfield facilities face downtime risk when bridging proprietary controller protocols to open standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Factory Automation in Japan Market |
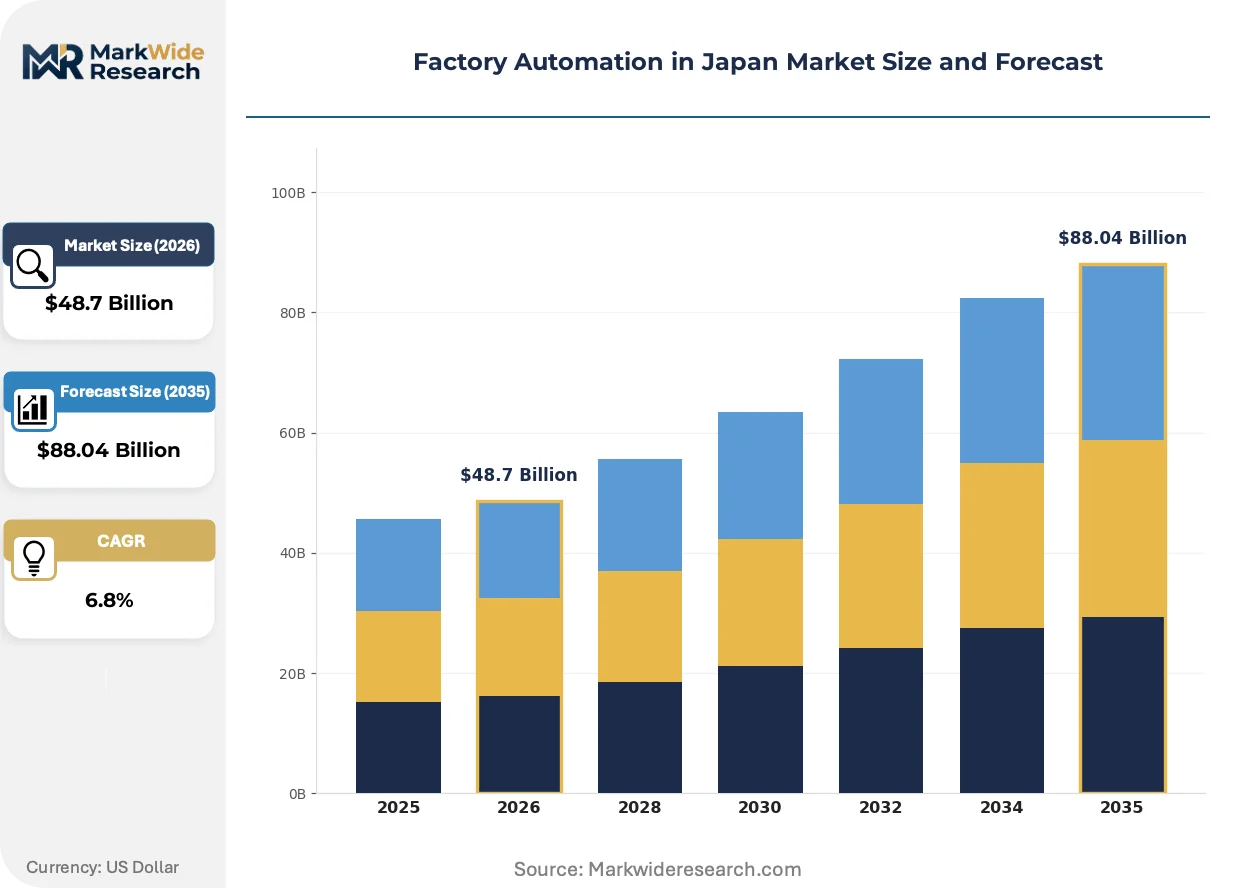
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Robots, Controllers, Sensors, Actuators End User: Manufacturers, Distributors, OEMs, System Integrators Technology: AI, Machine Learning, IoT, Automation Software Application: Assembly Line, Material Handling, Quality Control, Packaging |
| Companies Covered | Fanuc Corporation, Keyence Corporation, Omron Corporation, SMC Corporation, Mitsubishi Electric Corporation, Yaskawa Electric Corporation, Kawasaki Heavy Industries, Ltd., Panasonic Holdings Corporation, Denso Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Factory Automation in Japan Market Trends and Innovations
Software-defined automation architectures are dissolving traditional hardware-software boundaries, enabling remote parameter adjustment and predictive diagnostics that reshape supplier-customer relationships.
Edge-native control platforms are consolidating machine-level decision-making previously distributed across PLCs, HMIs, and separate safety controllers. Tier-1 automotive plants in Toyota City deploy these systems for sub-millisecond synchronization of multi-axis motion. The technology is consolidating vendor relationships by collapsing three-layer architectures into single-source platforms.
METI's Industrial Cybersecurity Framework mandates encrypted communications and access logging for designated critical infrastructure sectors. Equipment vendors must embed certificate management and anomaly detection into controller firmware. Pharmaceutical packaging lines face the steepest compliance burden due to PMDA validation requirements overlapping with cybersecurity audits.
Subscription-based automation software licensing is displacing perpetual ownership models in mid-scale discrete manufacturing. System integrators in Osaka's electronics cluster now bundle runtime licenses with commissioning services. This shift is most visible among contract manufacturers serving consumer electronics brands with volatile production schedules.
Factory Automation in Japan Market Segmentation
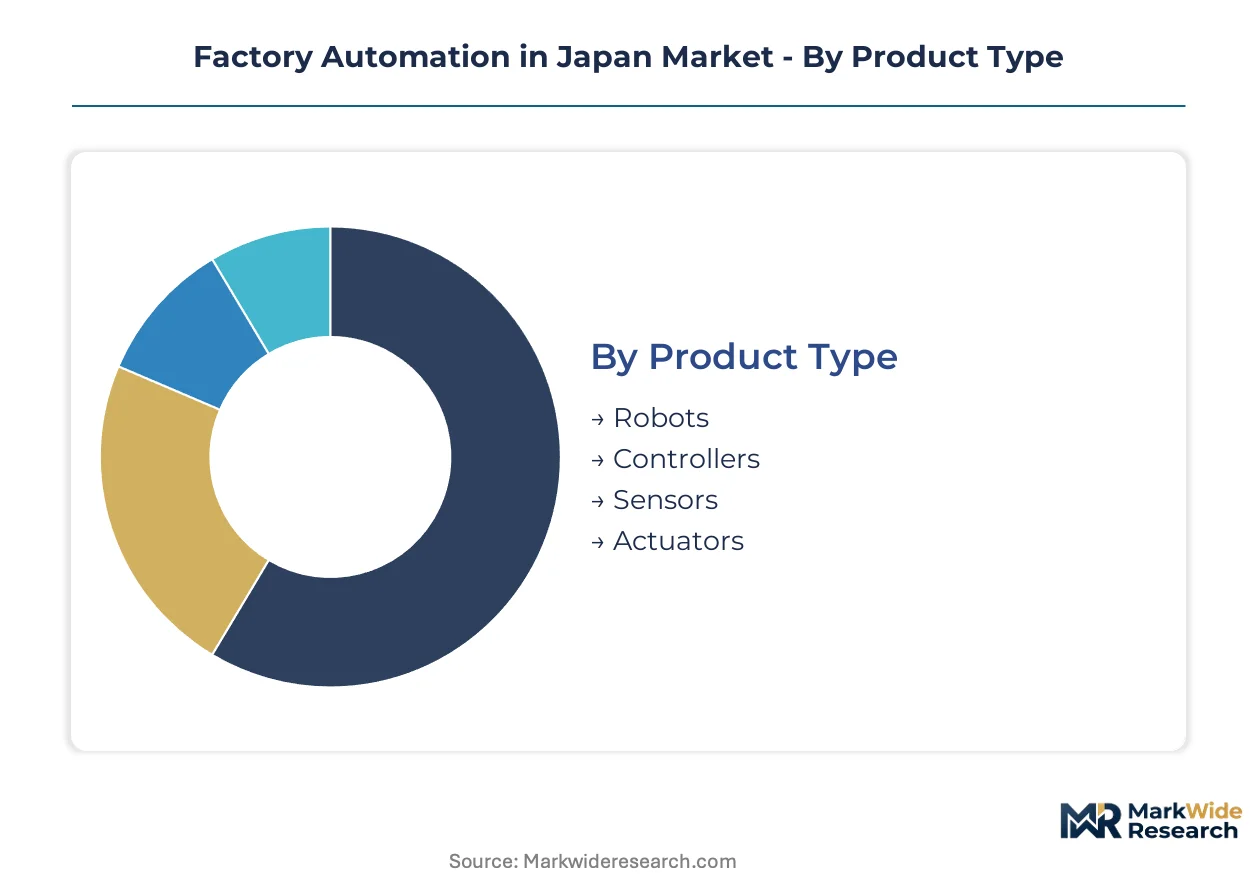
Factory automation in Japan fragments across four dimensions that determine procurement patterns and margin structures. Product type dictates capital commitment scale, while end-user category shapes service intensity and contract duration.
Product Type:
Robots demand the heaviest upfront capital outlay among all product categories, with six-axis articulated units requiring precision mechanical systems and extensive safety infrastructure.
- Robots:Six-axis articulated systems and SCARA configurations dominate automotive body shops and electronics assembly. Aichi Prefecture's Toyota City cluster drives concentrated demand for sub-millimeter repeatability in welding and coating operations.
- Controllers:Programmable logic controllers and motion control systems anchor facility-wide synchronization. Heavy process industries in Kansai's chemical corridor prioritize Mitsubishi Electric architectures for their deterministic cycle times.
- Sensors:Vision systems and proximity detectors enable closed-loop quality feedback.
- Actuators:Servo motors and linear drives convert control signals into precise mechanical motion.
Robots absorb the bulk of installed capacity; controllers are expanding most quickly as legacy PLC architectures face replacement pressure.
End User:
System integrators command the highest service premiums by bridging equipment supply with production engineering expertise.
- System Integrators:These firms design, commission, and maintain integrated automation lines across multiple manufacturing sectors. Osaka's electronics cluster depends on integrators for rapid reconfiguration of high-mix, low-volume assembly systems.
- Manufacturers:Captive automation teams at tier-1 automotive and electronics producers handle direct equipment procurement. In-house engineering capabilities allow these firms to bypass integrator margins on standard deployments.
- OEMs:Original equipment manufacturers embed automation components into their machinery offerings.
- Distributors:Channel partners stock and fulfill replacement parts for maintenance operations.
System integrators capture the highest project values; manufacturers represent the largest volume channel.
Technology:
IoT infrastructure requires sustained capital deployment across edge devices, networking hardware, and cloud connectivity layers.
- IoT:Sensor networks and connectivity platforms enable real-time production monitoring and remote diagnostics. METI's Industrial Cybersecurity Framework mandates encrypted communications for designated critical infrastructure sectors.
- AI:Machine vision and predictive algorithms optimize quality inspection and maintenance scheduling. Pharmaceutical packaging lines in Kanto deploy AI-enabled defect detection to satisfy PMDA validation protocols.
- Machine Learning:Pattern recognition systems refine process parameters through operational data accumulation.
- Automation Software:Programming environments and digital twin platforms reduce commissioning timelines.
IoT claims the largest installed base; AI shows the steepest expansion trajectory.
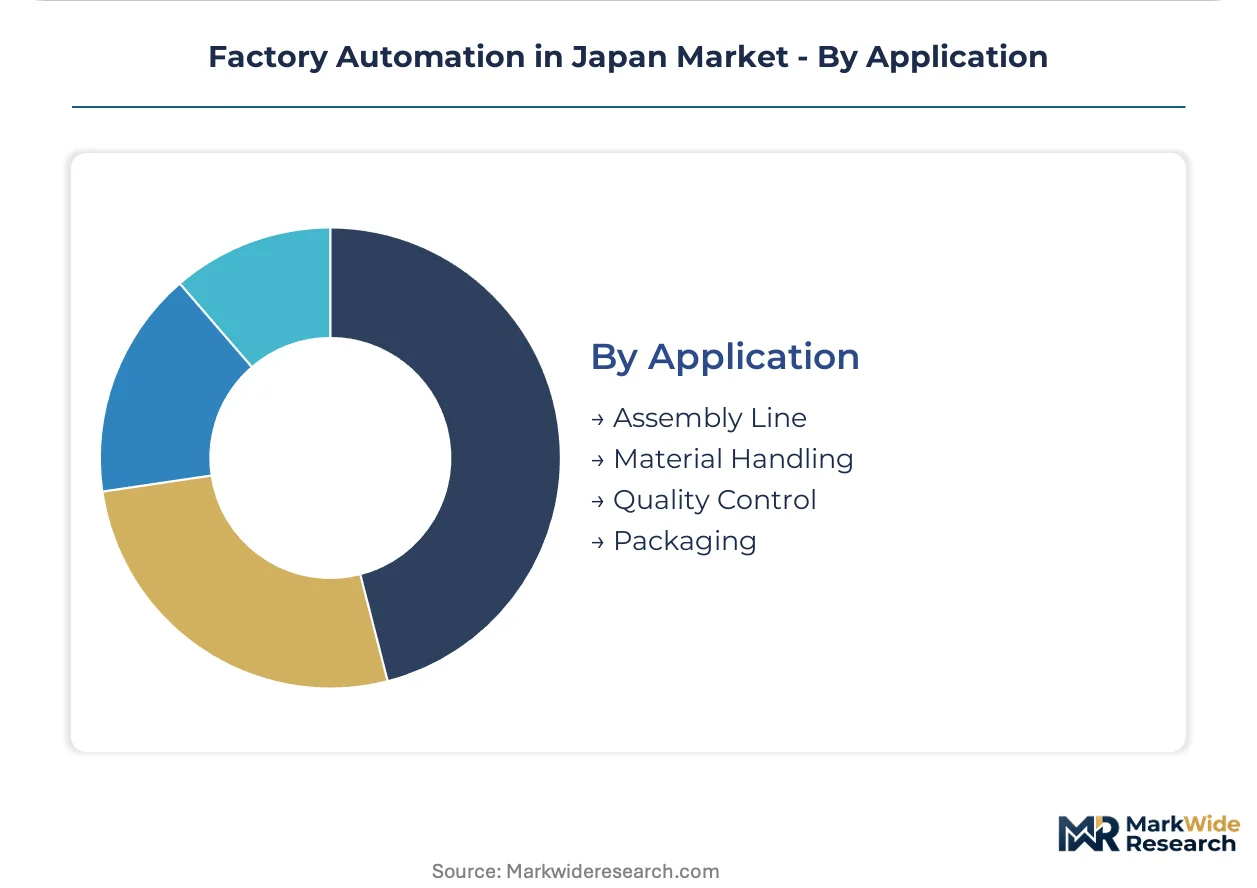
Application:
Assembly line automation demands the most comprehensive system integration across multiple equipment categories.
- Assembly Line:Multi-station synchronized operations dominate automotive and electronics manufacturing. Battery module assembly in Aichi requires precision motion control exceeding legacy pneumatic capabilities.
- Quality Control:Vision inspection and dimensional verification systems protect yield in high-value production. PMDA serialization mandates drive vision system investments in pharmaceutical packaging.
- Material Handling:Automated guided vehicles and conveyor systems manage work-in-progress flow.
- Packaging:End-of-line automation executes filling, sealing, and palletizing operations.
Assembly line applications anchor equipment demand; quality control is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Toyota City anchors Japan's factory automation demand through its dense concentration of tier-1 automotive suppliers and precision manufacturing requirements.
Kanto/Tokyo
Pharmaceutical serialization mandates and electronics contract manufacturing drive vision system deployments. METI's Industrial Cybersecurity Framework imposes encrypted communication standards on designated critical infrastructure operators. Yokohama's biotech corridor integrates track-and-trace automation for PMDA-compliant packaging lines.
Kansai/Osaka
High-mix, low-volume electronics assembly demands rapid reconfiguration capabilities from system integrators. JIS B 8433 robot safety standards govern recertification timelines for legacy facility upgrades. Osaka's electronics cluster concentrates procurement of IoT-enabled sensor networks for flexible production lines.
Chubu/Nagoya
Battery module assembly for electric vehicles requires precision motion control exceeding legacy pneumatic systems. METI's Society 5.0 policy compresses multi-decade upgrade cycles into single-digit-year execution windows. Aichi Prefecture's automotive corridor dominates six-axis articulated robot density metrics.
Kyushu
Semiconductor fab construction generates demand for cleanroom automation and wafer handling systems. The region's emerging foundry cluster attracts capital expenditure for contamination-controlled material transport. Kumamoto and Fukuoka prefectures concentrate new fab automation procurement.
Tohoku
Process industry energy efficiency retrofits align with METI carbon neutrality incentives for motor drive upgrades. Chemical and materials manufacturers modernize legacy controller architectures. Sendai's industrial corridor focuses on heavy process automation and deterministic cycle time requirements.
Factory Automation in Japan Market Competitive Landscape
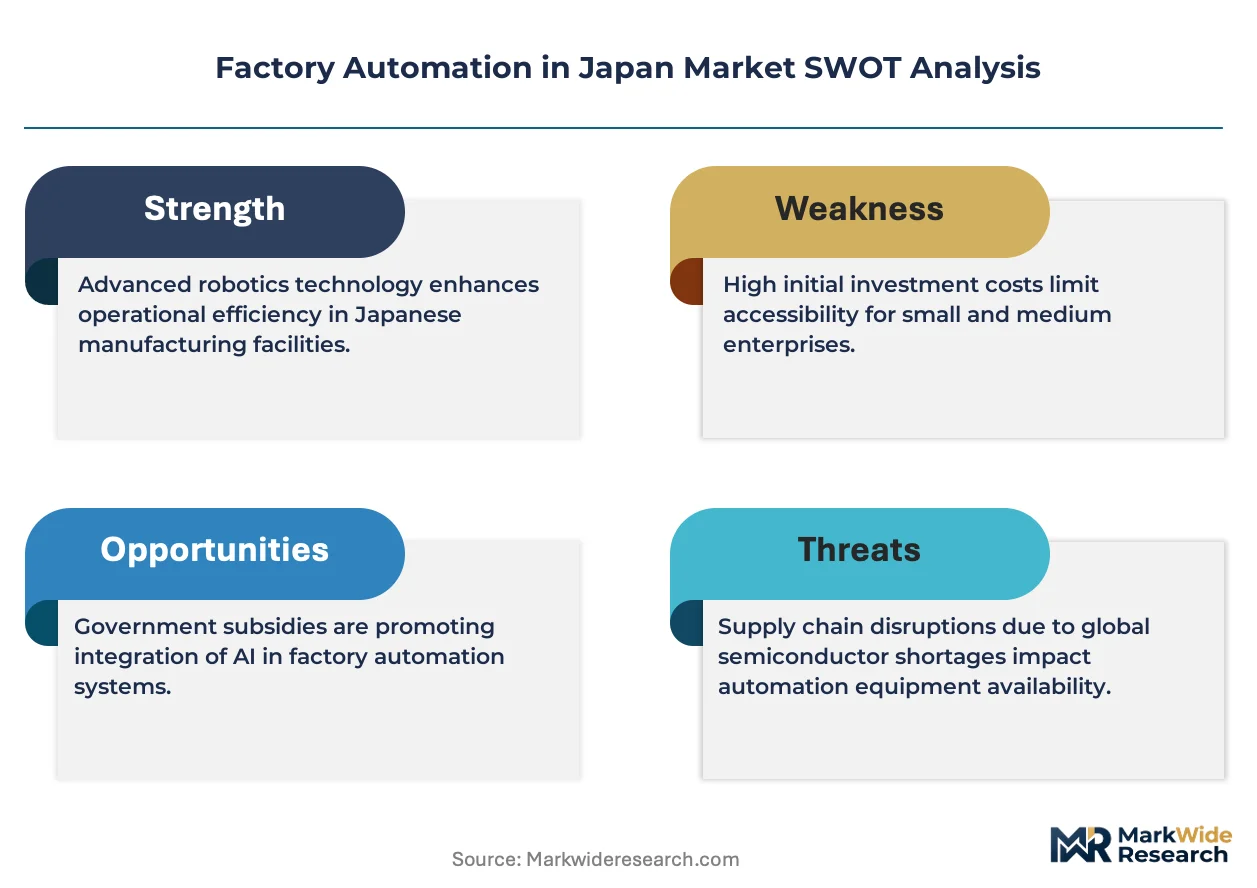
Premium-margin players sit above commodity-margin players across controller architecture and sensor calibration capabilities. The market structure consolidates around three distinct tiers: integrated electromechanical specialists, pure-play sensor and vision providers, and system integration services. Dominant competitive moves include software-defined automation partnerships and edge-native platform consolidation that collapses traditional three-layer architectures.
Within the integrated electromechanical tier, Fanuc Corporation and Mitsubishi Electric Corporation exemplify captive controller development strategies, while Keyence Corporation occupies a position emphasizing direct sales models and rapid deployment protocols. These three anchors represent divergent responses to open-architecture pressures reshaping supplier power structures.
| Leading Market Players |
|---|
| Fanuc Corporation |
| Keyence Corporation |
| Omron Corporation |
| SMC Corporation |
| Mitsubishi Electric Corporation |
| Yaskawa Electric Corporation |
| Kawasaki Heavy Industries, Ltd. |
| Panasonic Holdings Corporation |
| Denso Corporation |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap specialists anchor Japan's factory automation supply base, preserving pricing discipline through captive controller development and long-term customer relationships that resist commoditization pressure from open-architecture competitors.
Pricing Analysis
Value-based pricing anchored to throughput guarantees dominates premium controller and robot deployments, with Fanuc and Mitsubishi Electric commanding margins tied to uptime commitments rather than hardware unit costs. Three-tier pricing structure across premium, standard, and economy levels separates JIS B 8433-certified systems from uncertified imports and refurbished legacy equipment. Cost compression in standard-tier pneumatic components is intensifying because Chinese manufacturers are flooding Southeast Asian export channels. Small and mid-scale electronics contract manufacturers in Osaka exhibit the highest price sensitivity, while Aichi automotive tier-1s prioritize performance guarantees over unit economics.
Supply Chain Analysis
JIS B 8433 robot safety certification and METI Industrial Cybersecurity Framework compliance create gating barriers that filter non-qualified vendors from critical infrastructure procurement. Rare earth magnet processing concentrates in China, with secondary refining capacity in Vietnam and Australia. Industrial controller semiconductor fabrication rests on Taiwan and South Korea foundry output. Single-source vulnerability in rare earth supply chains threatens servo motor cost stability. Distribution runs through authorized system integrator networks that bundle commissioning services with equipment procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's factory automation market operates under acute supply constraint, with mechatronics engineering scarcity propping pricing power for qualified system integrators and certified equipment vendors.
For Market Incumbents: Extend software-defined automation partnerships to collapse three-layer architectures into single-source platforms before open-architecture competitors erode controller margins. Deepen backward integration into edge-native computing hardware to lock out modular challengers. Prioritize METI cybersecurity certification investments as regulatory moats against uncertified imports.
For New Entrants and Emerging Players: Begin with AI-enabled predictive maintenance service models targeting Osaka's high-mix electronics contract manufacturers, where volatile production schedules favor subscription-based automation software licensing over capital-intensive robot sales. Penetrate through rapid sensor calibration protocols that match Keyence's direct sales deployment speed.
For Investors and Strategic Acquirers: Distressed-cycle entries favor distressed system integrator assets in Kyushu's emerging semiconductor cluster, where fab construction timelines outpace qualified engineering staff availability. Long-term viability hinges on capturing cleanroom automation expertise before capacity constraints ease. Watch for inflection when METI carbon neutrality subsidies accelerate motor drive replacement cycles in Tohoku process industries.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Magnet Processing | Secures servo motor supply chains against Chinese export restrictions and price volatility. |
| Edge-Native Platform Consolidation | Collapses PLC-HMI-safety controller layers into unified architectures at Toyota City automotive plants. |
| AI-Enabled Predictive Maintenance Service Launch | Opens recurring revenue streams from Osaka electronics manufacturers with volatile schedules. |
| JIS B 8433 Certification Investment | Unlocks retrofit opportunities in legacy facilities facing safety recertification deadlines. |
| Kyushu Semiconductor Cluster Joint Venture | Captures cleanroom automation demand from Kumamoto and Fukuoka fab construction projects. |
Research Methodology
Document review covered METI policy filings, JIS standard revision records, and PMDA pharmaceutical packaging validation guidelines, complemented by interviews with plant engineers at Aichi automotive tier-1s, system integrator technical directors in Osaka, and aftermarket service heads at controller distributors. Secondary validation drew from customs trade data, industrial robot installation statistics, and SEC filings of listed automation vendors. Bottom-up equipment procurement patterns were triangulated against top-down facility investment surveys across Japan's five major industrial corridors.
Cross-referencing historical installation trajectories with expert panel input on Society 5.0 policy implementation timelines shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product type, end-user category, technology tier, and application intensity. CAGRs were derived from slope analysis of capital expenditure cycles correlated with regulatory deadline clustering. Forecast inputs incorporated rare earth supply elasticity assumptions and semiconductor foundry capacity allocation priorities.
Underlying measurement precision varies by segment; automotive electrification-driven robot demand carries tighter precision than AI software licensing projections where adoption curves remain experimental. Forecasts reflect documented assumptions on METI subsidy continuity and JIS standard enforcement intensity. A model refresh is warranted upon material change in foundry capacity allocation to industrial controller semiconductors.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Middle East and Africa Automated Storage and Retrieval System Market
Industrial Automation
Global Industrial Control and Factory Automation Market
Industrial Automation
Forklift-Mounted Computers Market
Industrial Automation
Asia-Pacific Smart Manufacturing Market
Industrial Automation
Programmable Automation Controller (PAC) Market
Industrial Automation
Asia-Pacific Programmable Logic Controller Market
Industrial Automation
Latin America Automated Storage and Retrieval System Market
Industrial Automation
UV Curing System Market
Industrial Automation
Industrial Human-Machine Interface Market
Industrial Automation
Global Smart Warehousing Market
Industrial Automation
Middle East and Africa Factory Automation and Industrial Controls Market
Industrial Automation
Electric Linear Actuator Market
Industrial Automation
Industrial Automation Device Manager Software Market
Industrial Automation
Smart Warehouse System Market
Industrial Automation
Europe Retail Automation Market
Industrial Automation
Asia-Pacific Industrial Automation Market