
 Safety Programmable Controller Market | 2026-2036
Safety Programmable Controller Market Size, Share, and Industry Trends Forecast 2026-2036
Safety Programmable Controller Market Analytics
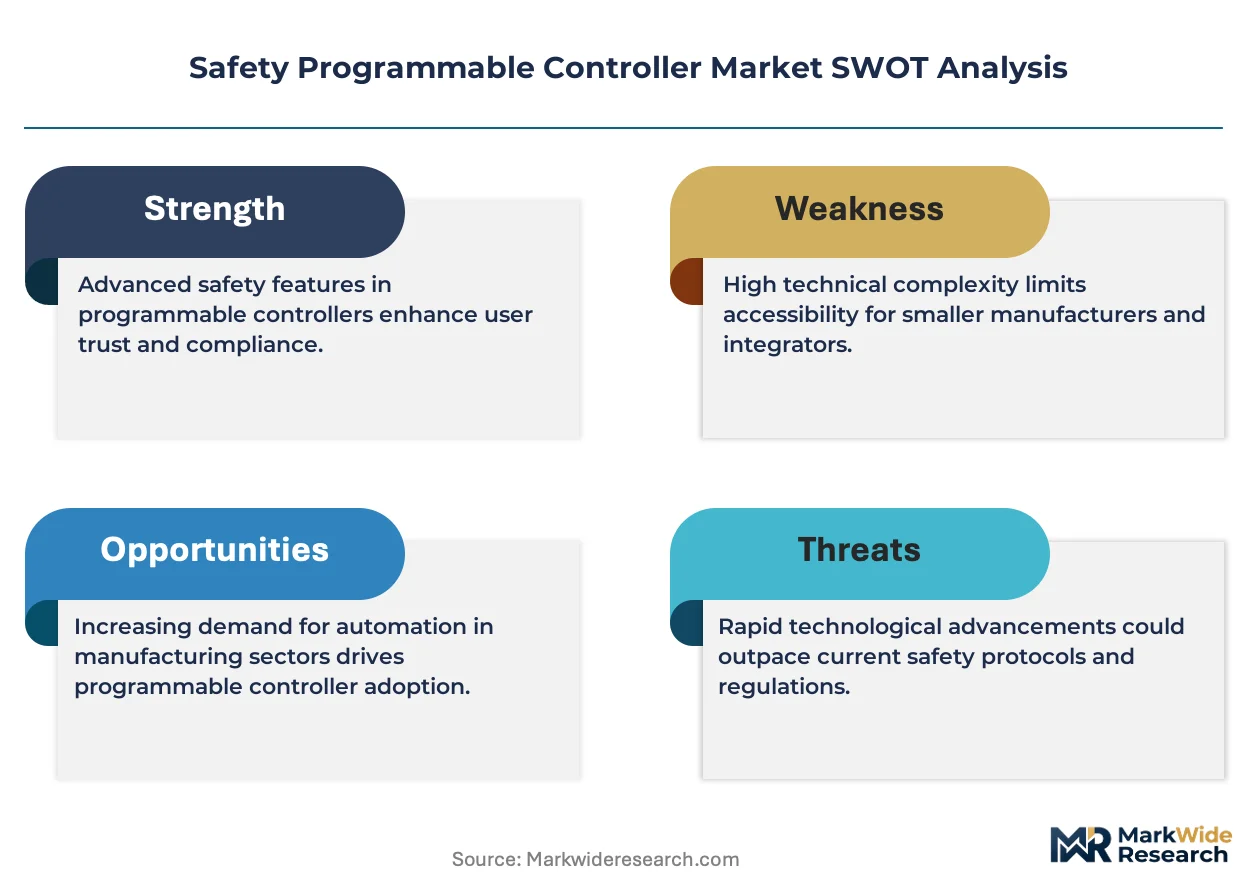
A widening capability gap between capital-heavy platform builders and lean modular specialists is unwinding competitive stability in the safety controller space. Siemens AG leverages integrated automation portfolios to anchor European process industries. Rockwell Automation sustains dominance in North American discrete manufacturing through channel depth and field service density. HIMA specializes in SIL-certified safety architectures for oil and gas applications, occupying a defensible niche against broader-platform rivals.
Safety programmable controllers are industrial computing devices engineered to execute safety-critical logic with deterministic response times, typically achieving SIL 3 or PLe certification through redundant processor architectures and diagnostic coverage exceeding 99%. These systems govern emergency stops, light curtains, and interlocked guarding on production lines where human-robot collaboration demands fail-safe operation. Modular product configurations command premium positioning as end users scale I/O counts across mixed manufacturing environments, while compact units penetrate cost-sensitive retrofit installations in pharmaceuticals. Relay-based technology retains share in legacy brownfield sites, though safety bus architectures are displacing hardwired interlocks in new automotive plant builds.
Functional safety standards IEC 61508 and IEC 62061 shape product design thresholds, compelling vendors to maintain third-party TÜV or exida certification for market access across EU industrial zones. OSHA lockout-tagout enforcement in US manufacturing facilities drives replacement cycles for non-programmable safety relays with configurable controller platforms. FDA 21 CFR Part 11 traceability requirements in pharmaceutical automation further segment vendor qualification criteria. Stakeholders must monitor evolving EU Machinery Directive amendments and emerging cybersecurity annexes to IEC 62443 as these frameworks increasingly condition purchasing specifications and service contract structures.
Market Dynamics
The collision between IEC 61508 SIL 3 certification mandates and automotive OEM demands for modular, scalable safety architectures is forcing vendors to restructure R&D roadmaps and partnership strategies around deterministic response guarantees.
Growth Catalysts
- EU Machinery Directive amendments:Tightened machinery safety requirements in German automotive clusters are compelling tier-one suppliers to replace relay-based interlocks with certified programmable controllers.
- Human-robot collaboration:Collaborative robot deployments on Japanese assembly lines require fail-safe guarding systems with diagnostic coverage exceeding 99%.
- OSHA enforcement waves:Intensified lockout-tagout inspections across US manufacturing facilities are accelerating replacement cycles for non-programmable safety relays.
Market Restraints
- Semiconductor supply concentration:Redundant processor architectures for SIL 3 certification depend on specialized industrial-grade chips sourced from a concentrated East Asian supplier base.
- TÜV certification timelines:Third-party functional safety validation for IEC 62061 compliance extends product launch windows by 12-18 months.
- Relay technology persistence:Hardwired interlock systems retain installed-base dominance in brownfield pharmaceutical facilities where validation costs deter controller migration.
Strategic Opportunities
- Pharmaceutical retrofit channel:FDA 21 CFR Part 11 traceability requirements are opening modular controller opportunities in US drug manufacturing facilities with legacy batch systems.
- Cybersecurity-integrated safety:Emerging IEC 62443 annexes for industrial cybersecurity are creating first-mover advantages for vendors bundling safety and security certification.
- India manufacturing expansion:PLI scheme incentives for automotive and electronics manufacturing are driving greenfield plant construction with native safety bus architectures.
Industry Challenges
- Functional safety engineering talent:SIL certification expertise remains concentrated among specialists in German and Swiss industrial automation clusters, constraining vendor scaling.
- Legacy system integration friction:Brownfield deployments require costly parallel validation of programmable controllers alongside existing hardwired safety circuits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Safety Programmable Controller Market |
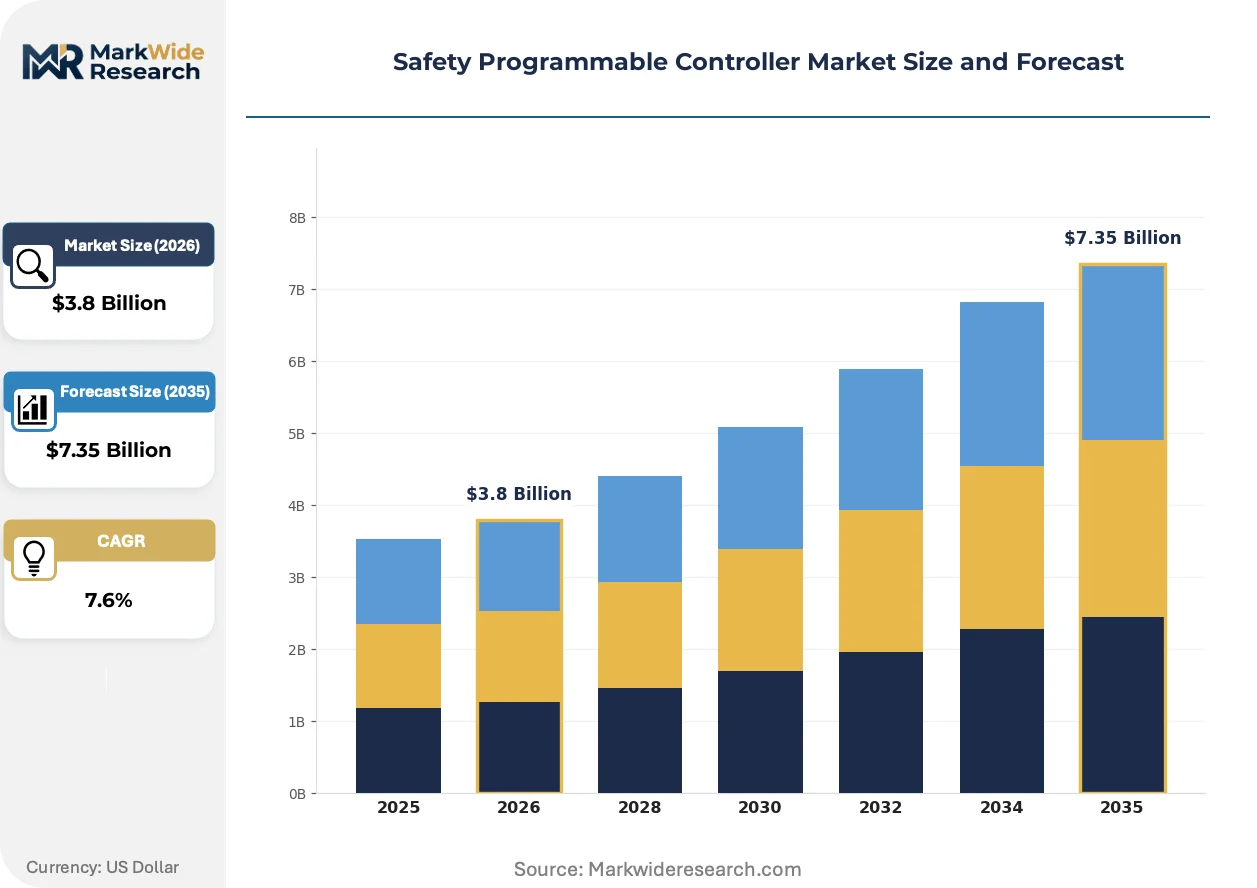
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed, Modular, Compact, Rack-mounted End User: Manufacturing, Oil & Gas, Automotive, Pharmaceuticals Technology: Relay-based, PLC, Safety Bus, Distributed Control System Installation Type: On-site, Remote, Integrated, Standalone |
| Companies Covered | Schneider Electric SE, Mitsubishi Electric Corporation, Siemens AG, IDEC Corporation, HIMA, Rockwell Automation, Omron Corporation, SICK AG, ABB Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Safety Programmable Controller Market Evolving Landscape
Safety bus architectures are actively rewriting interconnection standards across industrial automation, compressing installation complexity while elevating diagnostic granularity beyond what hardwired systems permit.
Safety-over-Ethernet protocols are supplanting dedicated safety wiring harnesses in new automotive plant builds. German OEMs are specifying these architectures for mixed-model lines where reconfiguration frequency exceeds quarterly cycles. The shift is compressing commissioning timelines and enabling centralized safety logic management across distributed I/O nodes.
EU Machinery Directive cybersecurity annexes are mandating secure-by-design validation for safety-critical programmable systems. Industrial automation vendors must now demonstrate IEC 62443-3-3 SL2 compliance alongside functional safety certification. German process industries face the steepest compliance curve, with TÜV auditors expanding assessment scopes to cover network segmentation and secure boot processes.
After-sales service unbundling is fragmenting traditional vendor-customer relationships in North American discrete manufacturing. End users are separating safety controller procurement from integration and maintenance contracts, engaging specialized system integrators for SIL validation and commissioning. This pattern is most pronounced in automotive tier-one suppliers operating across Michigan and Ohio industrial corridors.
Safety Programmable Controller Market Segmentation
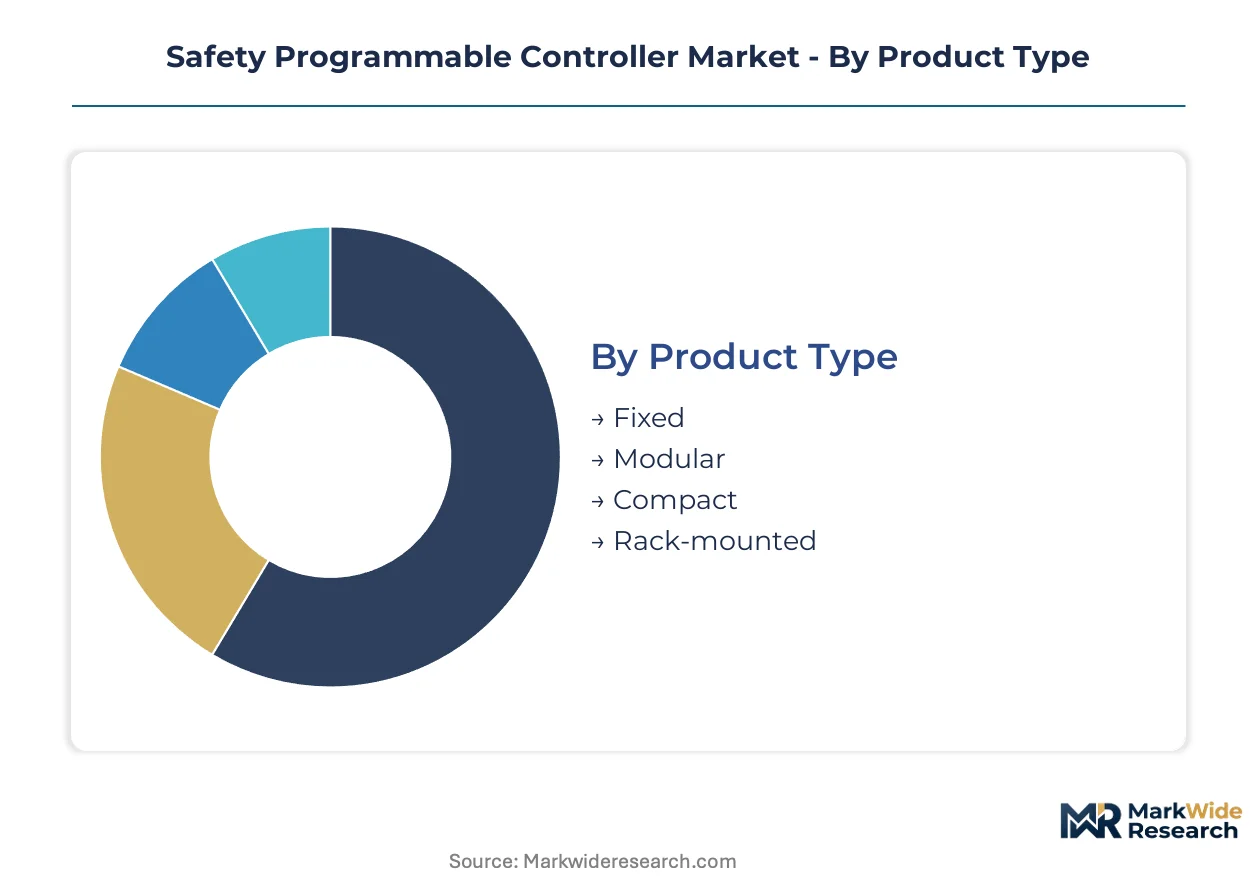
Safety programmable controller segmentation reveals distinct procurement patterns across industrial verticals. Product architecture, end-use application, and technology maturity determine channel access and margin structures for vendors competing in certified automation markets.
Product Type:
Channel mix varies sharply by form factor, with modular configurations flowing through system integrator networks while compact units penetrate direct OEM procurement channels.
- Modular:Scalable I/O architectures support mixed manufacturing environments with reconfigurable safety zones. Demand concentrates in German automotive clusters where tier-one suppliers coordinate flexible production lines around IEC 62061 compliance mandates.
- Compact:Space-constrained enclosures integrate safety logic with reduced footprint for retrofit installations. US pharmaceutical facilities with legacy batch systems drive replacement cycles under FDA 21 CFR Part 11 traceability pressure.
- Fixed:Dedicated safety controllers serve single-function guarding applications with deterministic response guarantees.
- Rack-mounted:Centralized architectures dominate process industry deployments requiring extensive I/O aggregation.
By volume, Compact leads brownfield retrofit channels. By growth pace, Modular is gaining share fastest in greenfield automotive construction.
End User:
Application context determines certification burden and service contract structure, with automotive OEMs demanding bundled validation support while oil and gas operators prioritize SIL-certified hardware sourcing.
- Automotive:Mixed-model assembly lines require fail-safe coordination of human-robot collaboration cells. Japanese OEMs specify diagnostic coverage exceeding 99% for collaborative robot guarding systems on high-frequency reconfiguration lines.
- Oil & Gas:Process safety shutdown systems demand redundant processor architectures certified to SIL 3 per IEC 61508. North Sea offshore platforms and Middle Eastern downstream facilities anchor procurement concentration for specialized safety architectures.
- Manufacturing:Discrete production environments balance cost sensitivity with lockout-tagout compliance requirements.
- Pharmaceuticals:Batch process validation and electronic record integrity requirements segment vendor qualification criteria.
By installed base, Manufacturing dominates. By expansion trajectory, Automotive is climbing the fastest on electrification-driven plant retooling.
Technology:
Technology maturity correlates with margin tier, as safety-over-Ethernet protocols command premium positioning against legacy relay infrastructure.
- Safety Bus:Networked interlock architectures compress commissioning timelines while enabling centralized diagnostics. German OEMs specify these systems for automotive plants with quarterly reconfiguration cycles, displacing hardwired harnesses in new construction.
- PLC:Programmable logic platforms integrate safety and standard control functions under unified development environments. US discrete manufacturing facilities accelerate migration from non-programmable relays under intensified OSHA enforcement.
- Relay-based:Hardwired interlock systems retain installed-base dominance where validation costs deter controller migration.
- Distributed Control System:Integrated safety-process control architectures serve large-scale continuous process operations.
By revenue concentration, PLC anchors current procurement. By technology transition velocity, Safety Bus is expanding most quickly in greenfield specifications.
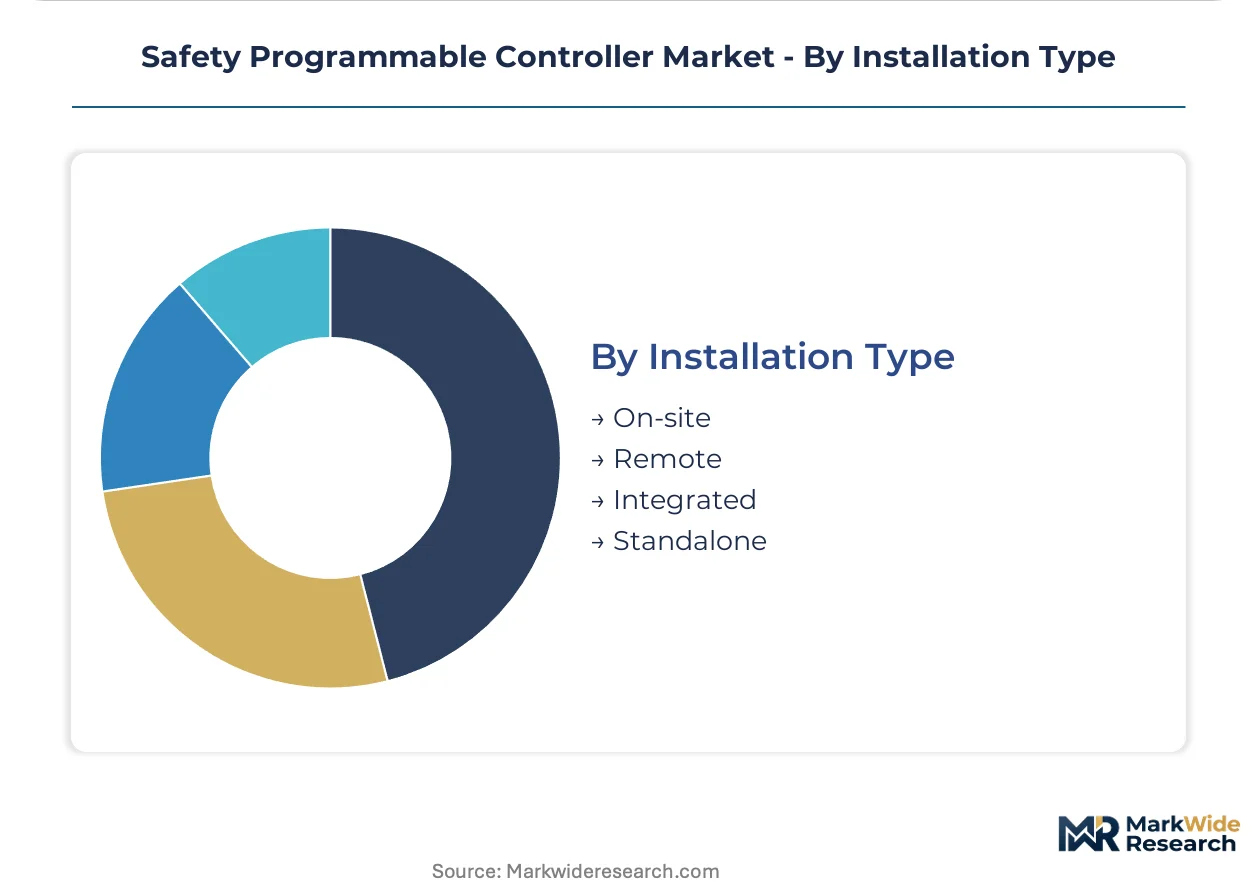
Installation Type:
Deployment architecture shapes service contract bundling, with integrated installations demanding multi-year validation support while standalone units enable unbundled procurement.
- Integrated:Embedded safety logic within larger automation platforms reduces interface complexity. German process industries favor these configurations for TÜV-audited compliance with emerging IEC 62443 cybersecurity annexes.
- Remote:Distributed I/O nodes with centralized safety logic management support geographically extended production footprints.
- On-site:Localized safety controller deployment maintains deterministic response without network dependency.
- Standalone:Dedicated safety systems enable modular procurement separated from broader automation integration contracts.
By deployment frequency, On-site dominates legacy infrastructure. By contract value expansion, Integrated is advancing the steepest on cybersecurity bundling requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial clusters command pricing premiums for SIL-certified safety architectures while US pharmaceutical retrofit channels compete on validation cost efficiency. Japanese automotive OEMs drive specification intensity for collaborative robot guarding systems. Indian greenfield construction under PLI incentives is compressing procurement timelines for modular safety bus deployments.
Germany
Automotive tier-one suppliers in Bavaria and Baden-Württemberg coordinate flexible production lines around quarterly reconfiguration cycles. EU Machinery Directive amendments enforced by KBA compel replacement of relay-based interlocks with IEC 62061-certified programmable controllers. Stuttgart industrial corridor anchors demand concentration for diagnostic coverage exceeding 99%.
United States
Pharmaceutical batch facilities in New Jersey and North Carolina accelerate controller migration under FDA 21 CFR Part 11 traceability pressure. OSHA intensifies lockout-tagout inspections across Michigan and Ohio automotive corridors. Detroit-Windsor cross-border supplier networks unbundle safety controller procurement from integration contracts.
Japan
Toyota and Honda assembly lines in Aichi Prefecture specify fail-safe guarding for human-robot collaboration cells. METI industrial safety guidelines tighten certification requirements for programmable safety systems beyond IEC 61508 baselines. Nagoya manufacturing belt concentrates specification authority for compact safety controller retrofits.
India
PLI scheme incentives for automotive and electronics manufacturing drive greenfield construction in Maharashtra and Tamil Nadu. CEA electrical safety regulations condition import approvals for industrial automation equipment. Chennai-Bengaluru industrial corridor specifies native safety bus architectures bypassing legacy relay infrastructure.
China
MIIT smart manufacturing initiatives elevate functional safety requirements for domestic robot deployments. GB standards alignment with IEC 61508 accelerates local certification capacity for SIL 3 programmable controllers. Yangtze River Delta automotive clusters integrate safety-over-Ethernet protocols in new electrification-focused plant builds.
Safety Programmable Controller Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated automation portfolios commanding premium positioning against modular specialists. The vendor base structures around three tiers: diversified industrial conglomerates with field service density, safety-focused specialists with SIL certification depth, and regional fabricators serving cost-sensitive retrofit channels. Dominant competitive moves include strategic partnerships for cybersecurity-integrated safety certification and geographic expansion into Indian PLI-driven greenfield construction.
Within the diversified industrial tier, Siemens AG and Schneider Electric SE exemplify platform breadth anchoring European process industries. Rockwell Automation occupies a position in North American discrete manufacturing characterized by channel depth and unbundled service relationships. HIMA represents the safety-specialist archetype with defensible positioning in oil and gas applications demanding redundant processor architectures.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Mitsubishi Electric Corporation |
| Siemens AG |
| IDEC Corporation |
| HIMA |
| Rockwell Automation |
| Omron Corporation |
| SICK AG |
| ABB Group |
| Others |
Value Network & Pricing Analysis
Long-term capacity reservation contracts with East Asian semiconductor foundries lock in supply access for industrial-grade safety processors while anchoring price visibility for vendors navigating SIL 3 certification timelines. German automotive OEMs and Japanese electronics manufacturers dominate offtake negotiations, compressing margin flexibility for tier-two safety controller suppliers.
Pricing Analysis
The customization-premium spread between configured-to-order modular systems and standard compact units runs through certification grade and after-sales bundling intensity. Project-based pricing dominates greenfield automotive deployments, while per-unit transactional models serve pharmaceutical retrofit channels. Price differentiation hinges on TÜV certification tier and field service density. Cost compression in compact controller tiers is intensifying because semiconductor supply concentration limits sourcing alternatives. Tier-one automotive suppliers exhibit lowest price sensitivity; brownfield pharmaceutical facilities demonstrate highest.
Supply Chain Analysis
Strategic stockpiling of industrial-grade microcontrollers and redundant processor chipsets characterizes vendor inventory strategies against just-in-time preferences among lean modular specialists. Manufacturing concentration centers on Taiwan, South Korea, and Germany for specialized safety semiconductors. Raw material dependencies include silicon wafers, automotive-grade memory modules, and precision electromechanical relays. Single-source vulnerability from East Asian foundry concentration constitutes primary supply chain risk. Distribution runs through system integrator networks for modular configurations and direct OEM procurement for compact units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Safety programmable controller incumbents face sustained substitution pressure from safety-over-Ethernet protocol stacks that collapse hardware differentiation into software-defined architectures. Defense requires structural repositioning around certification depth and cybersecurity integration.
For Market Incumbents: Consolidate SIL 3 certification expertise through captive engineering talent acquisition in German and Swiss industrial clusters. Deepen backward integration into safety semiconductor sourcing to reduce East Asian foundry dependency. Position against emerging software-defined safety entrants by bundling IEC 62443 cybersecurity certification with functional safety validation. For New Entrants and Emerging Players: Anchor in Indian PLI-driven greenfield automotive construction where native safety bus specifications bypass legacy relay infrastructure. Target US pharmaceutical retrofit channels under FDA 21 CFR Part 11 traceability pressure as the most penetrable segment. Pursue system integrator partnerships for SIL validation outsourcing rather than building captive certification capacity. For Investors and Strategic Acquirers: Capital is best deployed toward safety-specialist vendors with defensible SIL 3 positioning in oil and gas process shutdown systems. Long-term viability over the projection horizon favors acquisition targets combining functional safety depth with emerging cybersecurity certification capabilities. Monitor IEC 62443 annex adoption velocity as the critical inflection signal for valuation repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Cybersecurity Certification Bundling | IEC 62443-3-3 SL2 compliance alongside SIL 3 opens premium positioning in German process industries. |
| Backward Integration into Safety Semiconductors | In-house production of redundant processor chipsets reduces Taiwan foundry concentration exposure. |
| System Integrator Channel Partnership | Specialized SIL validation relationships penetrate unbundled procurement patterns in North American automotive. |
| Geographic Expansion into Indian Manufacturing | PLI scheme incentives for automotive greenfield construction accelerate modular safety bus adoption. |
| Pharmaceutical Retrofit Specialization | FDA 21 CFR Part 11 traceability expertise captures legacy batch system replacement cycles. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with safety system engineers, plant automation directors, OEM procurement leads, and TÜV certification auditors; and secondary validation against IEC 61508 implementation guidelines, EU Machinery Directive amendment texts, FDA 21 CFR Part 11 enforcement records, and vendor certification disclosures. Bottom-up triangulation across product-type demand curves and top-down reconciliation against regional industrial automation expenditure patterns anchored volume and value estimates.
Across the analysis window, the forecasting framework modeled demand trajectories by product architecture, end-use vertical, technology maturity tier, and installation type complexity. CAGRs were derived from segment-level growth rate reconciliation against macro industrial automation capex indicators. Key inputs included automotive electrification-driven plant retooling schedules and pharmaceutical facility validation cycle timing.
Decision-makers should treat outputs as directional under assumptions of sustained EU Machinery Directive enforcement and stable East Asian semiconductor supply access; material deviation would warrant model refresh. Revision becomes warranted when IEC 62443 cybersecurity annex adoption crosses implementation thresholds or when Indian PLI scheme incentives expire.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
North America Automated Storage and Retrieval System Market
Industrial Automation
Global Feeder Automation Market
Industrial Automation
Middle East and Africa Automated Storage and Retrieval System Market
Industrial Automation
Europe Intralogistics Automation Market
Industrial Automation
Europe Sortation Systems Market
Industrial Automation
Smart Sorting Machine Market
Industrial Automation
Global Industrial Wireless Automation Market
Industrial Automation
Europe Smart Manufacturing Market
Industrial Automation
Industry 4.0 Market
Industrial Automation
Latin America Automated Storage and Retrieval System Market
Industrial Automation
North America Industrial Automation Market
Industrial Automation
Latin America HMI Market
Industrial Automation
Mini-Load Systems Market
Industrial Automation
France Factory Automation and Industrial Controls Market
Industrial Automation
Global Motion Controller Market
Industrial Automation
Factory Automation in Japan Market