
 Industrial Gearbox Market | 2026-2036
Industrial Gearbox Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Gearbox Market Analysis
The authorized distributor channel is narrowing as SEW-EURODRIVE extends direct-to-plant service contracts with large manufacturing accounts. Siemens anchors European demand through integrated drive-train solutions that bundle motors, converters, and precision gearing. Bonfiglioli Riduttori specializes in planetary configurations for renewable energy installations, competing on torque density rather than price.
An industrial gearbox is a mechanical power transmission device comprising meshing gears within a sealed housing, typically manufactured through hobbing, shaping, or grinding processes to achieve AGMA or DIN quality class ratings, designed to modify speed, torque, and rotational direction between prime movers and driven machinery. Helical gearboxes dominate installed base volumes due to their efficiency and noise characteristics, while planetary configurations capture premium margins in robotics and wind turbine nacelles where compact torque multiplication is critical. Steel housings and alloy steel gearing sustain the bulk of heavy-duty applications, though aluminum castings gain traction in conveyor systems where weight reduction lowers energy consumption.
ISO 6336 calculation standards for gear load capacity and the EU Machinery Directive's safety requirements shape product certification costs and design validation cycles for European suppliers. China's SAMR enforces GB/T standards for mechanical transmission efficiency that filter market access for imported equipment. Stakeholders must monitor how regional efficiency mandates diverge and whether captive aftermarket service networks become the primary profit pool as hardware commoditization accelerates.
Market Dynamics
China's MIIT efficiency mandates are compressing product development cycles while wind turbine OEMs demand torque density improvements that strain conventional helical architectures. These dual pressures are forcing suppliers to redesign core gearing geometries before GB/T certification windows close.
Growth Catalysts
- Wind turbine nacelle specifications:Higher megawatt-class installations require compact planetary configurations that multiply torque in restricted envelope spaces. Gearbox suppliers capture value through integrated pitch and yaw drive systems.
- China's dual carbon goals:MIIT efficiency mandates under the 14th Five-Year Plan accelerate replacement demand in steel and cement plants. Retrofit orders for high-efficiency helical units exceed new equipment installations in heavy industry corridors.
- Automated material handling expansion:German industrial clusters drive precision gearbox demand for conveyor and AGV applications. Export-oriented machinery builders specify DIN-quality planetary units for warehouse automation systems.
Market Restraints
- Alloy steel input volatility:Nickel and molybdenum price swings compress margin predictability for forged gearing producers. Long-term supply agreements with specialty steel mills require minimum volume commitments that strain working capital.
- European certification friction:EU Machinery Directive safety validation cycles extend lead times by four to six months for non-EU suppliers. Third-party notified body capacity constraints create bottlenecks during peak quoting periods.
- Direct-drive generator substitution:Permanent magnet synchronous machines eliminate gearbox stages in low-speed wind turbine applications. OEMs above 5MW capacity increasingly specify direct-drive architectures for offshore installations.
Strategic Opportunities
- India's PLI scheme for manufacturing:Production-linked incentives for capital goods reduce effective tax burdens for gearbox assembly operations. Greenfield facilities in Gujarat and Tamil Nadu target export markets across Southeast Asia and Africa.
- Predictive maintenance convergence:Vibration sensors and edge analytics integrate with gearbox housings to enable condition-based service intervals. Industrial IoT platforms monetize uptime guarantees rather than component sales alone.
- Aluminum casting adoption:Lightweight housing materials penetrate conveyor and packaging machinery segments where energy consumption drives total cost of ownership calculations. Die-cast aluminum reduces rotating mass by thirty to forty percent versus steel equivalents.
Industry Challenges
- AGMA/DIN quality class talent scarcity:Precision grinding and honing operations require specialized machinist skills that retire faster than training programs replenish. German and Swiss technical institutes face enrollment shortfalls in gear manufacturing curricula.
- Legacy system integration complexity:New high-efficiency gearboxes must interface with decades-old prime movers and driven equipment across installed industrial bases. Custom adapter fabrication extends project timelines and erodes standardized product margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Gearbox Market |
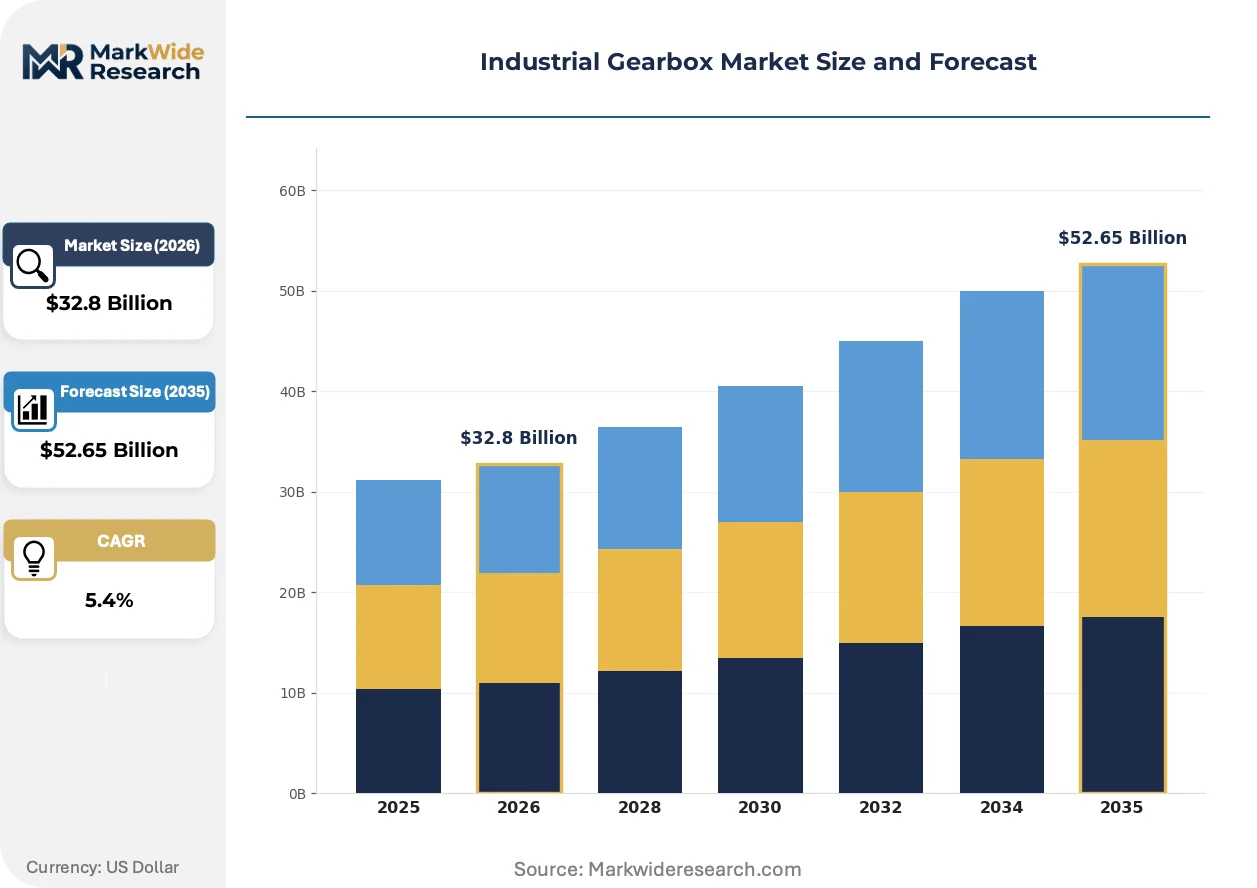
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $52.65 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Helical, Bevel, Worm, Planetary End User: Manufacturing, Construction, Automotive, Energy Material: Steel, Aluminum, Cast Iron, Composite Application: Conveyor Systems, Lifting Equipment, Pumps, Fans |
| Companies Covered | Sumitomo Heavy Industries, SEW-EURODRIVE, Bonfiglioli Riduttori, Flender, Regal Rexnord Corporation, Siemens, ZF Friedrichshafen, NORD Drivesystems, David Brown Santasalo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Gearbox Market Emerging Trajectories
Digital twin architectures and additive manufacturing are disrupting conventional gearbox development workflows. These technologies compress prototyping cycles while enabling geometries that subtractive processes cannot achieve.
Digital twin software is virtualizing gearbox performance validation before physical prototypes enter test stands. Wind turbine OEMs and robotics integrators deploy these platforms to simulate load cases across twenty-year design lives. The technology is virtualizing traditional iterative prototyping, cutting development timelines by half while exposing failure modes that physical testing misses.
China's SAMR enforcement of GB/T mechanical transmission efficiency standards is tightening market access for imported equipment. Non-compliant suppliers face customs delays and mandatory third-party retesting. European and Japanese exporters are redesigning product lines specifically for Chinese efficiency bands rather than adapting domestic specifications.
Service contract unbundling is fragmenting traditional distributor relationships. Large manufacturing accounts negotiate direct aftermarket agreements with gearbox OEMs for spare parts and refurbishment. This pattern concentrates most visibly in Germany's automotive supplier parks, where plant-level procurement teams bypass authorized distributors for critical line-item gearboxes.
Industrial Gearbox Market Segmentation
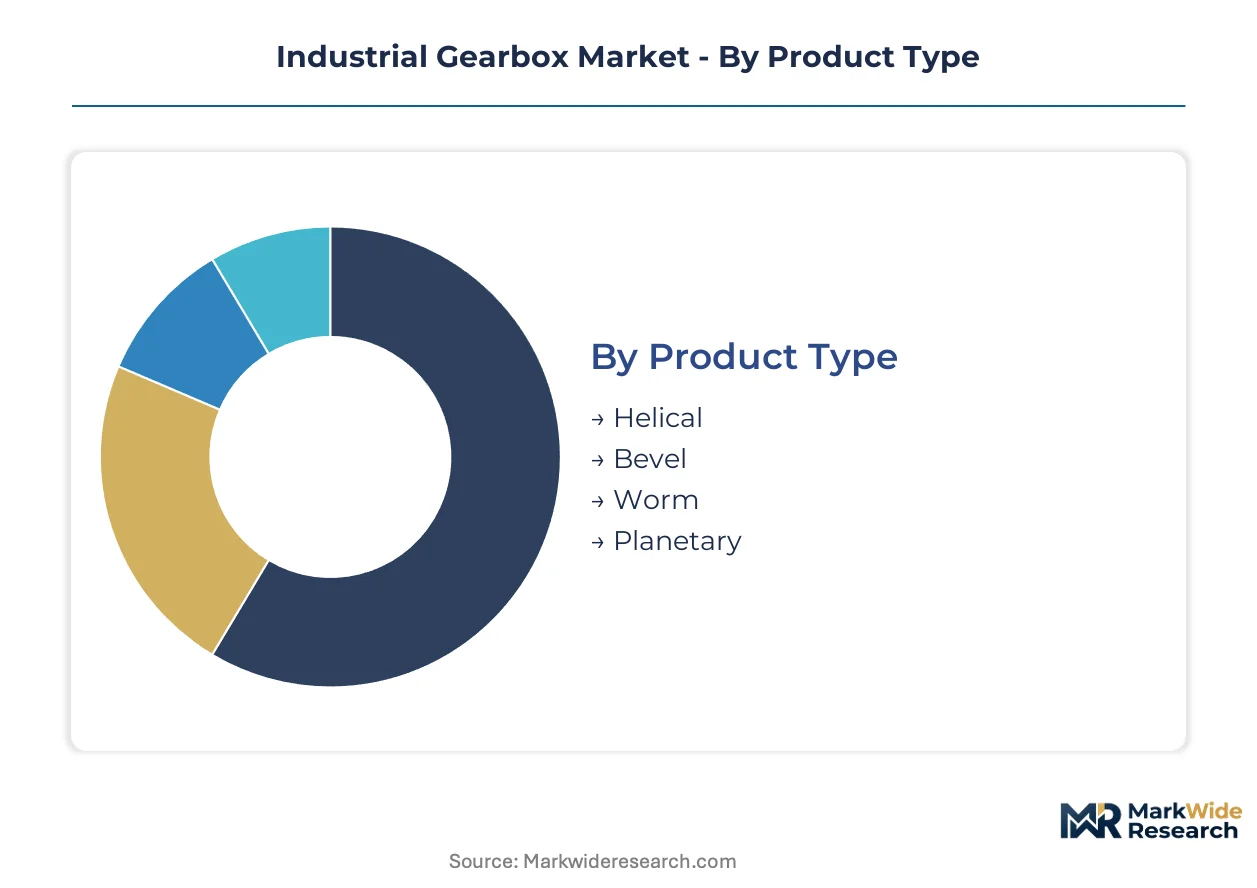
Gearbox segmentation reveals divergent margin structures across mechanical architectures and material choices. Product type and end-use concentration determine where suppliers capture value versus where price competition erodes returns.
Product Type:
Mature helical designs dominate installed volumes while emerging planetary configurations command premium positioning in torque-dense applications.
- Helical:Parallel-axis gearing with angled tooth engagement delivers smooth power transmission and reduced acoustic signature. Cement plants and steel mills across China's industrial corridors specify these units for continuous-duty material processing under MIIT efficiency mandates. Alloy steel tooth grinding achieves DIN 6 quality for heavy-load endurance.
- Planetary:Epicyclic gear trains multiply torque within compact radial envelopes through multiple planet gears orbiting a central sun gear. Wind turbine nacelles above 3MW capacity require these configurations where space constraints prevent helical alternatives. German and Danish OEMs specify integrated pitch-yaw drive systems.
- Bevel:Right-angle power transmission for intersecting shaft applications in material handling equipment.
- Worm:High reduction ratios in self-locking configurations for lifting and hoisting machinery safety requirements.
Helical configurations handle the majority of throughput; Planetary is the fastest mover on share.
End User:
Cost tier differentiation separates capital-intensive process industries from price-sensitive assembly operations.
- Energy:Wind turbine OEMs and solar tracking system builders specify AGMA 12+ precision grades with twenty-year design life validation. Offshore installations above 5MW drive demand for integrated condition monitoring and predictive maintenance interfaces. Gearbox suppliers bundle service contracts with hardware to capture lifetime value.
- Manufacturing:Automated production lines and robotic cells require compact servo-rated planetary units with backlash below three arc-minutes. German automotive supplier parks specify DIN-quality gearing for conveyor and AGV integration. Retrofit cycles accelerate under energy efficiency audits.
- Construction:Mobile crane and excavator applications demand ruggedized housings with IP65 sealing for contaminated environments.
- Automotive:Powertrain testing rigs and assembly line conveyors utilize standardized helical units with rapid spare parts availability.
Manufacturing absorbs the greatest unit volume; Energy is expanding most quickly on share.
Material:
Volume concentration favors traditional ferrous alloys while margin expansion shifts toward lightweight alternatives.
- Steel:Forged alloy housings and carburized gearing sustain extreme shock loads in mining and metal processing. Nickel-molybdenum grade selection balances fatigue resistance against input cost volatility. Heat treatment to 58-62 HRC surface hardness extends service intervals in continuous-duty applications.
- Aluminum:Die-cast housing construction reduces rotating mass by thirty-five percent versus steel equivalents. Conveyor system OEMs in packaging and logistics segments specify these units where energy consumption drives total cost of ownership calculations. Surface hardening of steel inserts maintains tooth durability.
- Cast Iron:Cost-effective vibration damping for general-purpose industrial drives in pump and fan applications.
- Composite:Emerging polymer-matrix housings for corrosive chemical processing environments and food-grade washdown requirements.
Steel retains dominant throughput position; Aluminum is climbing the fastest on share.
Application:
Customer type segmentation separates project-engineered systems from catalog-standard replacements.
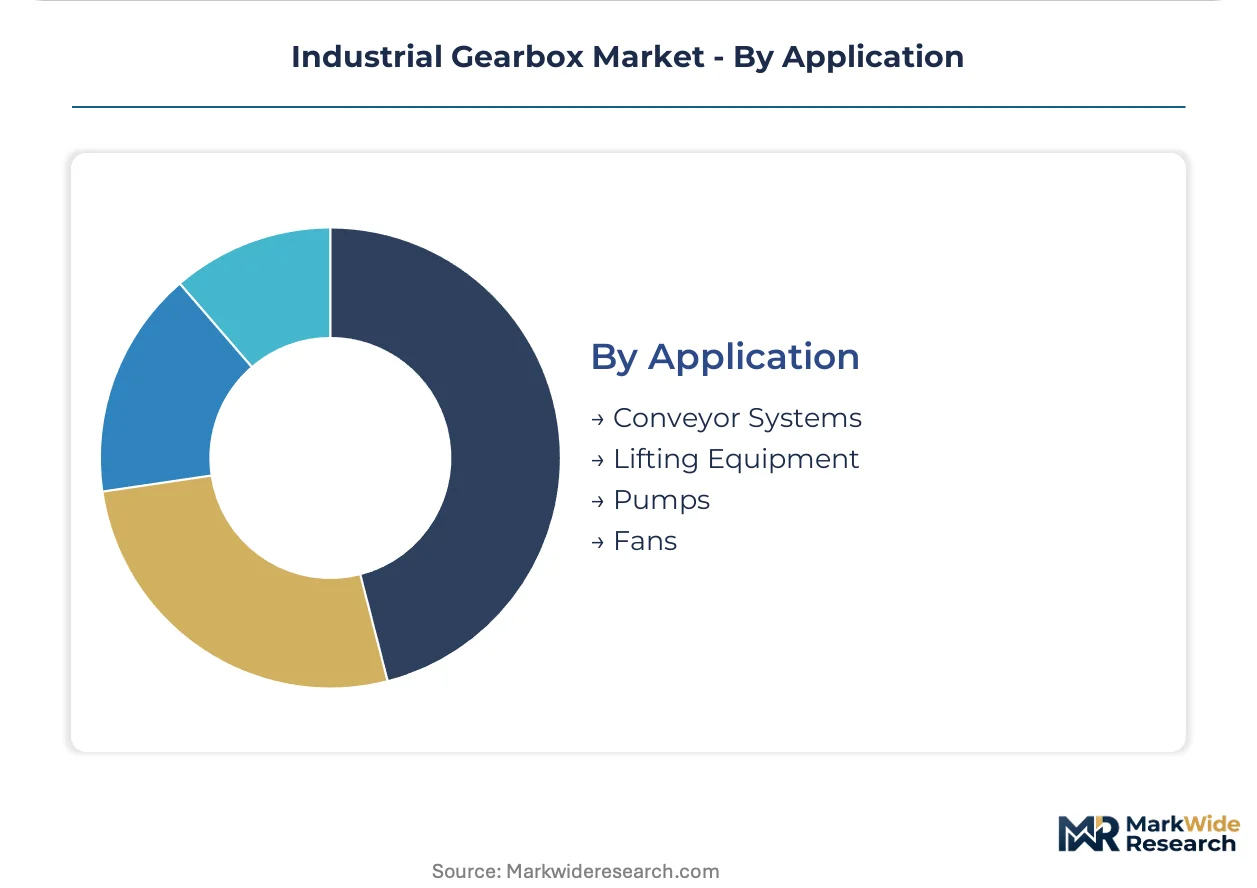
- Conveyor Systems:Bulk material handling and parcel distribution networks require modular gearbox mounting with hollow shaft or solid shaft options. Warehouse automation builders specify aluminum-housed units with integrated motor adapters. German intralogistics clusters drive precision-grade demand for high-speed sorting applications.
- Lifting Equipment:Overhead cranes and hoist mechanisms mandate redundant braking and safety-certified configurations per EU Machinery Directive. Wind turbine tower elevators and maintenance platforms require compact planetary drives with emergency manual override. Third-party notified body validation extends lead times for non-EU suppliers.
- Pumps:Centrifugal and positive displacement pump drives favor helical configurations with flexible coupling compatibility.
- Fans:HVAC and industrial ventilation applications prioritize noise attenuation through helical gearing with precision-ground tooth profiles.
Conveyor Systems move the greatest installed base; Lifting Equipment shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's automated container handling systems drive precision gearbox demand across European intralogistics networks. China's Belt and Road rail corridors accelerate high-torque transmission deployment in Central Asian freight terminals. Germany's Rhine-Alpine freight corridor anchors continental manufacturing supply chains for automated material handling equipment.
China
Wind turbine nacelle assembly lines in Jiangsu province require compact planetary configurations for pitch-yaw drive systems. MIIT efficiency mandates under the 14th Five-Year Plan compress product certification windows for imported helical units. Shanghai's Yangshan deep-water port automation projects specify aluminum-housed gearboxes for energy-efficient crane operations.
Germany
Automotive supplier parks in Stuttgart and Wolfsburg specify DIN-quality planetary units for AGV conveyor integration. The EU Machinery Directive's safety validation cycles extend lead times for non-EU gearbox exporters. Bavaria's industrial corridor concentrates precision grinding capacity for AGMA 12+ precision gearing serving export machinery builders.
United States
Shale basin pumpjack retrofits drive helical gearbox replacement cycles in Texas and North Dakota oilfields. EPA emissions regulations indirectly tighten efficiency specifications for associated gas compression equipment. Houston's energy equipment manufacturing cluster hosts service contract negotiations for direct-to-plant aftermarket agreements.
India
Cement plant expansion in Gujarat and Rajasthan accelerates high-efficiency helical unit procurement under energy audit mandates. The PLI scheme for capital goods reduces effective tax burdens for gearbox assembly operations in Tamil Nadu. Chennai's automotive component belt drives servo-rated planetary demand for robotic welding cell integration.
Japan
Robotics integrators in Nagoya specify backlash-below-three-arc-minute planetary units for precision assembly cells. METI energy efficiency standards filter market access for non-compliant imported mechanical power transmission equipment. Osaka's machine tool builders export DIN-quality gearing systems to Southeast Asian manufacturing corridors.
Industrial Gearbox Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in the value chain. The vendor base concentrates around German and Japanese precision manufacturers with captive heat-treatment capabilities. Three archetypes dominate: integrated drive-train bundlers, planetary configuration specialists, and catalog-standard helical producers. Capacity expansion and predictive maintenance service unbundling represent the dominant competitive vectors reshaping distributor relationships.
Within the integrated platform tier, SEW-EURODRIVE and Siemens exemplify system-level bundling strategies that combine motors, converters, and precision gearing into single-source contracts. Bonfiglioli Riduttori occupies a specialist position in planetary configurations for torque-dense renewable energy applications. These three anchors illustrate how geographic origin—German, German, and Italian respectively—correlates with distinct competitive positioning across the efficiency-certification spectrum.
| Leading Market Players |
|---|
| Sumitomo Heavy Industries |
| SEW-EURODRIVE |
| Bonfiglioli Riduttori |
| Flender |
| Regal Rexnord Corporation |
| Siemens |
| ZF Friedrichshafen |
| NORD Drivesystems |
| David Brown Santasalo |
| Others |
Supply Flow & Price Mechanics
Alloy steel input volatility between European specialty mills and Asian forging houses determines both the spread between DIN-certified premium tiers and catalog-standard economy units and the geographic shape of component sourcing networks. Buyers face widening price differentials as nickel-molybdenum grade selection becomes the primary lever for fatigue resistance versus cost containment.
Pricing Analysis
Volume-discount tiering structures stratify across AGMA 12+ precision planetary configurations, DIN 6-8 quality helical units, and unground commercial-grade catalog replacements. Price differentiation hinges on certification grade attainment and captive heat-treatment capabilities. Cost compression in mid-tier helical segments intensifies as Chinese MIIT efficiency mandates force redesign cycles before GB/T windows close. Cement plant procurement teams in heavy industry corridors exhibit highest price sensitivity, while wind turbine OEMs prioritize torque density over unit economics.
Supply Chain Analysis
Tariff exposure between German precision grinding clusters and Chinese forging operations dominates supply chain risk calculations for European gearbox assemblers. Component sourcing draws from German carburizing specialists, Japanese CNC hobbing equipment, and Indian casting foundries. Nickel and molybdenum price volatility strains working capital through minimum volume commitments with specialty steel mills. Distribution runs through authorized distributor networks that fragment as SEW-EURODRIVE and Siemens extend direct-to-plant service contracts with large manufacturing accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial gearbox markets approach a platform-economics inflection where integrated drive-train bundling displaces component-only procurement. Interoperability between predictive maintenance sensors and edge analytics platforms is reshaping how suppliers capture lifetime value beyond hardware margins.
For Market Incumbents: Harden aftermarket service network control by acquiring independent refurbishment specialists in Germany's automotive supplier parks. Deepen upstream control over specialty alloy forging capacity through long-term offtake agreements with ThyssenKrupp and Saarstahl to offset nickel-molybdenum volatility. SEW-EURODRIVE's direct-to-plant contract expansion demonstrates how channel disintermediation defends margin position against catalog-standard competitors. For New Entrants and Emerging Players: India's PLI scheme for capital goods in Gujarat and Tamil Nadu represents the most penetrable entry point for greenfield assembly operations targeting Southeast Asian export markets. Aluminum-housed conveyor gearboxes for warehouse automation builders offer lower certification friction than precision planetary units for wind turbine nacelles. A go-to-market angle anchored to energy-efficiency retrofit audits under China's MIIT mandates accelerates initial reference customer acquisition. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors predictive maintenance platform specialists with captive gearbox hardware relationships. Long-term viability over a five-to-ten-year window hinges on service contract unbundling that monetizes uptime guarantees rather than component sales alone. The signal to watch is direct-drive generator substitution rates above 5MW wind turbine installations, which would compress planetary gearbox addressable markets faster than efficiency-driven retrofit demand expands.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Steel Forging | Captive supply of nickel-molybdenum alloys insulates margin from commodity volatility in heavy-duty gearing. |
| Predictive Maintenance Platform Integration | Vibration sensor bundling with gearbox housings enables condition-based service intervals under EU Machinery Directive safety frameworks. |
| GB/T Certification Pre-Approval Investment | Early compliance with China's SAMR efficiency mandates accelerates customs clearance for imported helical units. |
| Aluminum Casting Capacity Expansion | Die-cast housing construction addresses conveyor system demand where energy consumption drives total cost of ownership calculations. |
| Direct-to-Plant Service Contract Negotiation | Bypassing authorized distributors captures aftermarket profit pools in Germany's automotive supplier parks. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads across steel, cement, and wind turbine manufacturing; and secondary validation through customs trade data, AGMA technical publications, MIIT regulatory filings, and SEC 10-K disclosures from listed industrial equipment suppliers. Bottom-up unit economics triangulated against top-down sectoral demand models to anchor volume projections.
Forecast inputs considered helical versus planetary product type splits, energy versus manufacturing end-use concentration, and steel versus aluminum material adoption across the projection horizon. Segmentation dimensions modeled include gear configuration architecture, precision quality grade tier, end-use industry vertical, and regional regulatory cluster. CAGRs derived from installed base replacement cycles, greenfield capacity additions, and efficiency-driven retrofit penetration curves.
Practitioners should monitor alloy steel price volatility, GB/T certification window closures, and direct-drive generator substitution rates above 5MW capacity for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Mining Vehicle AC Kits Market
Vehicle Components
Piston Market
Vehicle Components
Global Fuel Tank and Delivery System Market
Vehicle Components
Electric Wheelchair Market
Vehicle Components
Latin America Automotive Connectors Market
Vehicle Components
EV Connectors Market
Vehicle Components
Motorcycle Connectors Market
Vehicle Components
India Automotive Steering System Market
Vehicle Components
Japan Automotive Pneumatic Actuators Market
Vehicle Components
China Forklift Battery Market
Vehicle Components
Anchorage Connector Market
Vehicle Components
Global Automotive Carbon Monocoque Chassis Market
Vehicle Components
Hydrostatic Transmission Market
Vehicle Components
Passenger Air Brake Market
Vehicle Components
Electric Brake Actuator Systems for Passenger Vehicles Market
Vehicle Components
Global Car Accessories Market