
 EV Connectors Market | 2026-2036
EV Connectors Market Size, Share, and Industry Trends Forecast 2026-2036
EV Connectors Market Intelligence
The convergence toward high-power, universal charging standards like the Combined Charging System (CCS) is narrowing the technology gap between competing connector designs. TE Connectivity leverages its extensive R&D in high-voltage components to develop next-generation solutions for ultra-fast charging. Yazaki Corporation sustains a dominant position in the Asian automotive supply chain, providing integrated wiring harnesses and connectors. Amphenol Corporation competes on manufacturing scale and a diversified portfolio serving both vehicle manufacturers and charging infrastructure providers.
EV connectors are electromechanical interfaces that facilitate the transfer of electrical energy to an electric vehicle's battery. These components are engineered to handle specific power levels, from Level 2 AC charging up to ultra-fast DC charging exceeding 350 kW, and integrate communication protocols for safe and efficient charging sessions. The Combined Charging System (CCS) is becoming the de-facto standard in North America and Europe, displacing CHAdeMO in new installations. Demand for DC Fast Charging and Ultra-Fast Charging connectors is accelerating, driven by the build-out of public charging stations and the needs of commercial fleet operators.
Regulatory mandates are a primary force shaping connector design and market access. The EU's Alternative Fuels Infrastructure Regulation (AFIR) and China's GB/T standards enforce specific connector types, while in the United States, the adoption of SAE J3400 (NACS) is reshaping the competitive positioning of legacy standards. Stakeholders must now decide whether to focus on regional standard compliance or invest in developing versatile, multi-standard charging solutions to address a fragmenting hardware landscape.
Market Dynamics
The EV connector market is defined by the structural tension between global standardization efforts and regional regulatory fragmentation. While technologies like the Combined Charging System (CCS) aim for interoperability, national mandates such as China's GB/T and the US adoption of SAE J3400 create distinct, hardware-specific ecosystems.
Growth Catalysts
- Public Infrastructure Mandates:Regulations like the European Union's AFIR compel member states to expand public charging networks at specified intervals, directly stimulating demand for standardized AC and DC fast charging connectors.
- Commercial Fleet Electrification:The transition of logistics and public transport fleets to electric power creates sustained demand for high-durability, high-power connectors capable of rapid, repetitive charging cycles required for commercial operations.
- Government Incentives in Asia:China's policies promoting EV adoption, including substantial subsidies and a state-led build-out of charging infrastructure, establish it as the dominant volume market for all connector types.
Market Restraints
- Input Material Cost Volatility:The price of high-purity copper and specialized engineering polymers, essential for high-power connectors to manage heat and electrical loads, introduces significant cost uncertainty for manufacturers.
- Thermal Management Limits:For ultra-fast charging connectors operating above 350 kW, dissipating heat remains a primary technical barrier, potentially limiting charging speeds and component longevity without advanced liquid-cooling solutions.
- Standardization Fragmentation:The coexistence of CCS, CHAdeMO, GB/T, and now SAE J3400 (NACS) forces manufacturers to develop and stock multiple product lines, increasing design complexity and inventory costs.
Strategic Opportunities
- Vehicle-to-Grid (V2G) Connectors:The development of bidirectional connectors that enable V2G energy transfer opens a new market for advanced components with sophisticated communication protocols for grid stabilization services.
- Integrated Smart Connectors:Embedding PLC communication, authentication hardware, and sensor technology directly into the connector assembly provides an opportunity for differentiation and higher-margin sales to charging network operators.
- Emerging Market Infrastructure:Countries in Southeast Asia and Latin America represent nascent markets where establishing early partnerships for public and private charging infrastructure can secure long-term supply contracts.
Industry Challenges
- Complex Certification Pathways:Achieving compliance with multiple international and regional safety standards, such as those from IEC and UL, involves lengthy and expensive testing cycles that can delay product introductions.
- Supply Chain Reconfiguration:The rapid shift toward SAE J3400 in North America requires component suppliers to undertake costly retooling of manufacturing lines while managing legacy inventory for the existing CCS-based vehicle parc.
- Interoperability Failures:Ensuring seamless communication and a successful charging session between any given vehicle and charging station remains a persistent operational challenge, often stemming from firmware and protocol mismatches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EV Connectors Market |
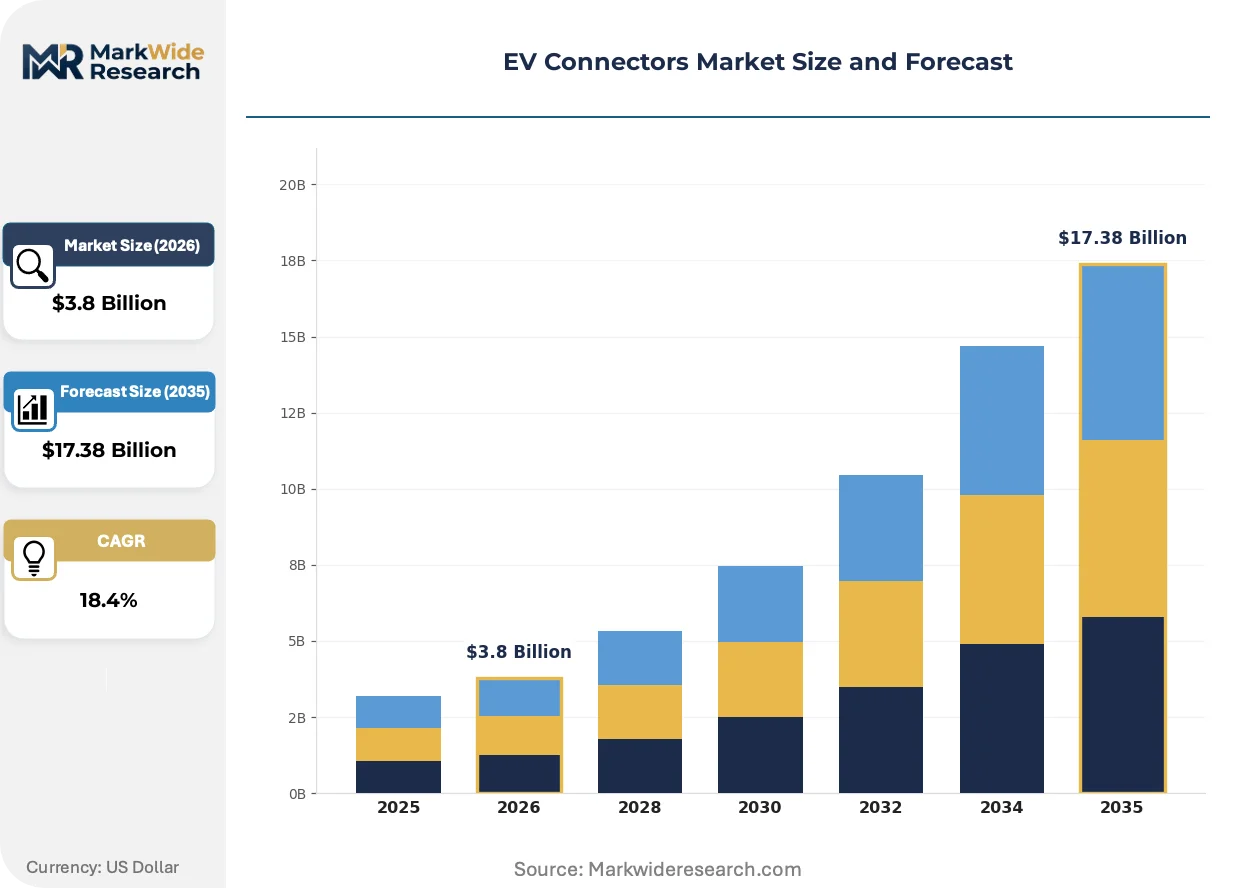
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.38 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Type 1, Type 2, Combined Charging System, CHAdeMO, Tesla Connector Charging Level: Level 1 AC, Level 2 AC, DC Fast Charging, Ultra-Fast Charging Application: Private Vehicles, Fleet Operators, Public Charging Stations, Commercial Charging Solutions, Taxi Services End User: Vehicle Manufacturers, Fleet Management Companies, Energy Utilities, Charge Point Operators |
| Companies Covered | TE Connectivity, Yazaki Corporation, Amphenol Corporation, Aptiv PLC, Sumitomo Electric, ABB Ltd., Schneider Electric, Molex, Phoenix Contact, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EV Connectors Market Strategic Shifts & Innovations
The market's evolution is centered on delivering higher power density and greater intelligence within the connector itself. This push is a direct response to consumer demand for faster charging times comparable to gasoline refueling and the operational requirements of commercial vehicle fleets needing maximum uptime.
Liquid-cooling technology integrated into charging cables and connectors is a critical innovation for enabling sustained power transfer above 350 kW. Ultra-fast charging network operators and manufacturers of heavy-duty electric trucks are the primary adopters of this technology. This advancement is rendering obsolete previous air-cooled connector designs for high-power applications, which were constrained by thermal throttling and required impractically large cable diameters.
In the United States, the formalization of SAE J3400 as the new standard based on the North American Charging Standard (NACS) marks a decisive policy shift. This regulation directs new federal funding toward infrastructure built with the more compact, high-power J3400 connector. Suppliers of legacy CHAdeMO and CCS Type 1 connectors are the most affected, facing pressure to pivot their product roadmaps to ensure continued relevance in the North American market.
A notable behavioral shift is occurring as commercial fleet operators increasingly seek turnkey charging depot solutions instead of procuring individual components. This disrupts the traditional channel of selling connectors as discrete parts, creating an advantage for suppliers who can bundle hardware with management software and installation services. This trend is most prominent in Europe and North America, where logistics and delivery companies are rapidly electrifying their vehicle fleets.
EV Connectors Market Segmentation
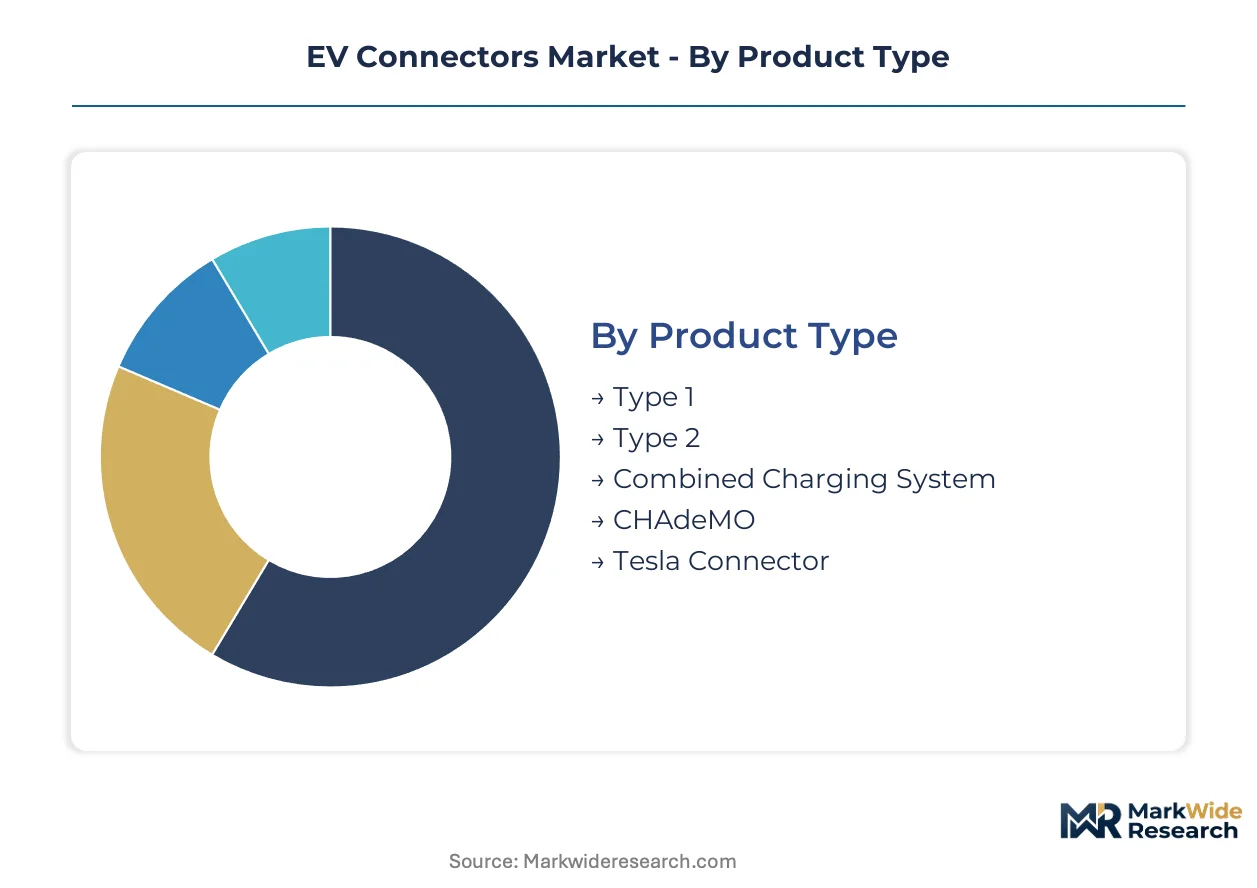
The EV connectors market segmentation clarifies how different product designs and charging requirements influence demand patterns and technological development. Understanding these distinct segments allows manufacturers to align product roadmaps with evolving infrastructure needs and regulatory shifts. This granular view highlights areas of concentrated investment and emerging opportunities for specialized connector solutions.
Product Type:
The turnover rate for connector designs varies significantly, with some legacy types undergoing rapid displacement while others maintain a stable installed base.
- Combined Charging System:This standard integrates AC and DC charging into a single port, facilitating high-power DC fast charging up to 350 kW. Demand concentrates in Europe and North America, driven by regulatory mandates like the EU's AFIR.
- Tesla Connector:Originally proprietary, this compact connector now formalized as SAE J3400, supports both AC and DC charging for Tesla vehicles. Its adoption is rapidly expanding across North America, influencing competitive positioning for charging infrastructure providers.
- Type 1:This single-phase AC connector is prevalent in North America and Japan, primarily used for Level 1 and Level 2 AC charging.
- Type 2: As the standard AC connector in Europe and many other regions, Type 2 supports single-phase and three-phase AC charging.
- CHAdeMO:This DC fast charging standard is primarily found in Japan and some older installations globally, facing displacement by CCS in new deployments.
Type 2 dominates the installed base for AC charging. Combined Charging System is where expansion concentrates for high-power DC applications.
Charging Level:
Supply concentration for different charging levels reflects the diverse needs of EV users, from overnight home charging to rapid public top-ups.
- DC Fast Charging:These connectors enable rapid charging at public stations, typically delivering 50 kW to 150 kW of power. Demand is accelerating in China and Germany, supported by government initiatives for public infrastructure.
- Ultra-Fast Charging:Designed for power levels exceeding 150 kW, often reaching 350 kW or more, these connectors require advanced thermal management. Commercial fleet operators in the United States and Norway are primary adopters.
- Level 1 AC:This basic level uses standard household outlets, providing slow overnight charging typically below 2.4 kW.
- Level 2 AC:Offering faster AC charging up to 22 kW, Level 2 connectors are common in homes, workplaces, and public charging points.
The fastest-growing trajectory for connector technology is visible in Ultra-Fast Charging. Level 2 AC maintains a significant volume of deployments due to its versatility.
Application:
The sheer volume of connectors required across different applications influences design robustness and integration capabilities.
- Public Charging Stations:These installations require highly durable connectors capable of frequent use and exposure to various environmental conditions. Demand is concentrating in the Netherlands and the United Kingdom, driven by national charging network build-outs.
- Fleet Operators:Commercial fleets demand connectors built for high-duty cycles and rapid charging to maximize vehicle uptime. Logistics companies in France and Sweden are driving significant volume.
- Private Vehicles:Connectors for individual car owners prioritize ease of use and compatibility with home charging setups.
- Commercial Charging Solutions:This segment includes charging infrastructure for businesses, workplaces, and residential complexes, requiring scalable and integrated systems.
- Taxi Services:Connectors for taxi fleets emphasize speed and reliability for high-utilization vehicles.
Customer type differentiation drives demand for Fleet Operators. Public Charging Stations show robust growth in infrastructure investment.
End User:
The maturity of end-user segments dictates their purchasing power and influence on connector specifications and standards.
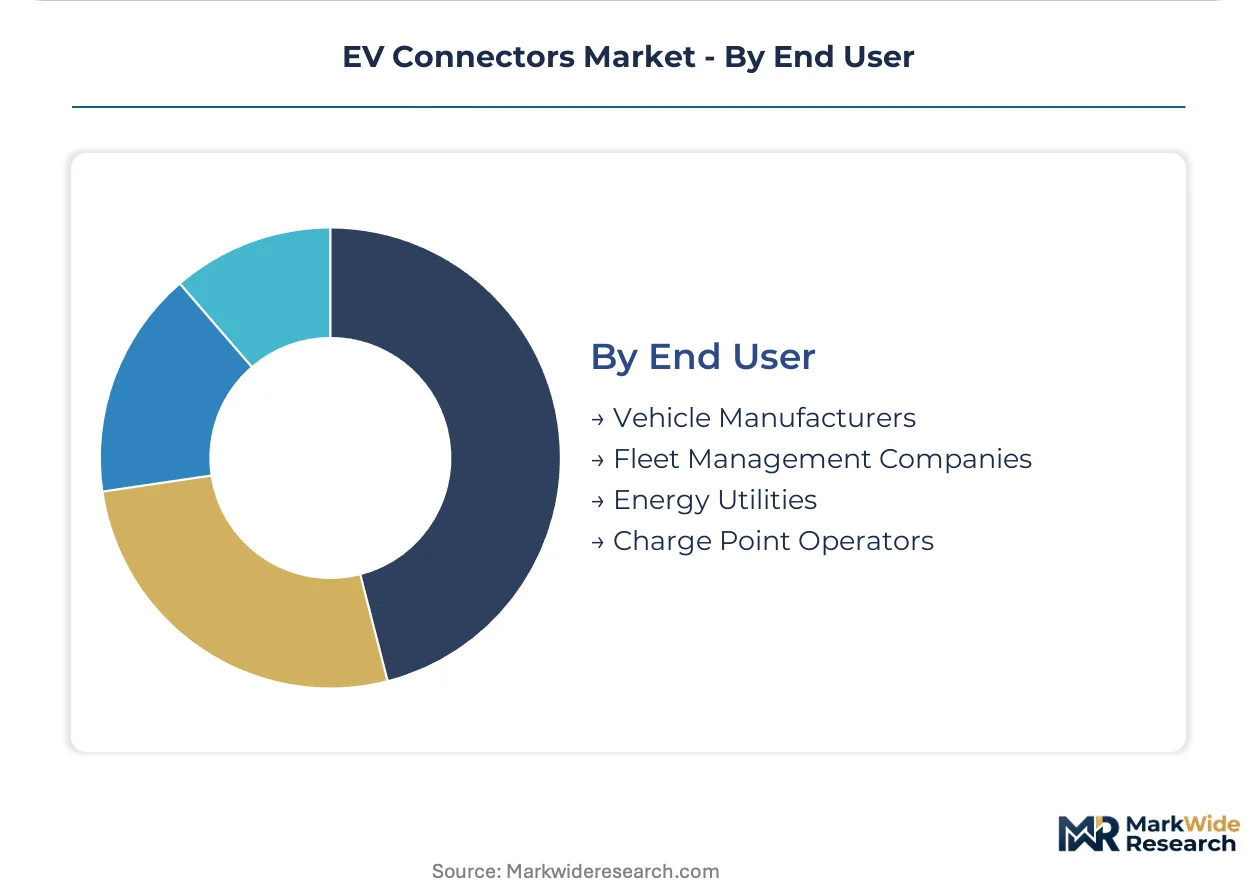
- Charge Point Operators:These companies manage and operate public and private charging networks, demanding reliable and interoperable connector solutions. Their purchasing decisions influence the adoption of new standards in Germany and the United States.
- Vehicle Manufacturers:OEMs integrate connectors into their vehicle designs, influencing the initial choice of compatible charging standards. Companies like Hyundai and Volkswagen are shaping future connector requirements.
- Fleet Management Companies:These entities procure charging solutions for commercial vehicle fleets, focusing on durability and operational efficiency.
- Energy Utilities:Utilities participate in charging infrastructure development, particularly in grid integration and smart charging solutions.
Charge Point Operators exhibit strong margin potential with their focus on network reliability. Vehicle Manufacturers drive foundational connector specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer archetypes significantly influence regional EV connector market dynamics. China's state-led initiatives drive massive volume, while commercial fleet operators and charge point operators shape demand in Western markets. This varied landscape necessitates adaptable connector solutions.
China
Government incentives for EV adoption and infrastructure build-out drive substantial demand for all connector types. The GB/T standards enforce specific connector types, creating a distinct hardware ecosystem. Beijing and Shanghai lead in public charging infrastructure deployment, supporting rapid EV penetration. Volume growth remains unparalleled across the Yangtze River Delta.
Germany
Charge Point Operators and vehicle manufacturers drive significant demand for reliable connector solutions. The EU's AFIR mandates expand public charging networks, directly stimulating demand for CCS and Type 2 connectors. Stuttgart and Munich, automotive hubs, concentrate research and development in high-power charging technologies. This focuses on interoperability and advanced thermal management.
United States
Commercial fleet operators require high-durability, high-power connectors for rapid, repetitive charging cycles. The adoption of SAE J3400 (NACS) is reshaping competitive positioning for legacy standards. California and Texas lead in infrastructure build-out, driven by state incentives and federal funding. This accelerates demand for ultra-fast charging capabilities.
Norway
Ultra-fast charging connectors see primary adoption among commercial fleet operators due to the country's advanced EV penetration. National policies strongly support electric vehicle infrastructure, including high-power charging. Oslo and Bergen are key centers for deploying advanced charging solutions, emphasizing cold-weather performance. Demand for liquid-cooled connectors is particularly high.
EV Connectors Market Key Industry Players
Channel-controlling players compete with product-specialist players across the EV connector market. The market exhibits a tiered structure, with established electronics manufacturers alongside specialized automotive suppliers. Strategic archetypes include diversified component giants leveraging extensive R&D, dedicated EV charging solution providers focused on specific power levels, and regional specialists adapting to local standards. Companies pursue portfolio diversification and strategic partnerships to address evolving standards and regional demands, often through M&A activities.
At the scale-driven end, TE Connectivity leverages its extensive R&D in high-voltage components, exemplifying a diversified component giant. Yazaki Corporation, a Japan-based entity, occupies a strong position within the Asian automotive supply chain, representing a regional specialist with integrated offerings. Amphenol Corporation, a US-based manufacturer, anchors a broad portfolio serving both vehicle manufacturers and charging infrastructure providers, demonstrating a diversified approach. These companies navigate the complex landscape of global standardization efforts and regional regulatory fragmentation.
| Leading Market Players |
|---|
| TE Connectivity |
| Yazaki Corporation |
| Amphenol Corporation |
| Aptiv PLC |
| Sumitomo Electric |
| ABB Ltd. |
| Schneider Electric |
| Molex |
| Phoenix Contact |
Cost & Logistics Intelligence
Input material cost volatility, particularly for high-purity copper and specialized engineering polymers, determines both pricing tier spreads and the structural shape of the EV connector supply chain.
Pricing Analysis
Cost-plus contract patterns with named indexation to commodity prices characterize the EV connector market. Pricing stratifies across premium, standard, and economy tiers, driven by certification levels (IEC, UL, GB/T compliance) and volume scale for large orders. Pricing softness reflects intense competition in established segments, especially for AC connectors. Commercial fleet operators and charging network developers exhibit higher price sensitivity compared to vehicle manufacturers procuring specialized, high-power components.
Supply Chain Analysis
Single-source vulnerability for specialized components, such as liquid-cooling systems, presents a significant supply chain risk. Geographic supply concentration includes China for high-volume production, Germany for advanced R&D in high-power charging, and Japan for integrated automotive harness systems. Raw material dependencies center on high-purity copper, specialized engineering polymers, and advanced cooling fluids. Distribution runs primarily through direct sales channels to vehicle manufacturers and charge point operators, with integrated solutions gaining traction for fleet customers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment, particularly through mandated charging standards, frames this market as a defensive-moat story for established players.
For Market Incumbents:
Insulate core market share by investing in versatile, multi-standard connector solutions, particularly for the North American and European markets. Deepen R&D in advanced thermal management and liquid-cooling technologies to address ultra-fast charging requirements, mitigating the threat from specialized component providers. Secure long-term supply agreements for critical raw materials like high-purity copper and specialized polymers, leveraging existing channel control with major OEMs and CPOs.
For New Entrants and Emerging Players:
Underpenetration in emerging markets across Southeast Asia and Latin America offers a strategic entry point for new players. Target the commercial charging solutions segment, focusing on integrated smart connectors with V2G capabilities. A go-to-market angle focused on establishing early partnerships with local utilities and public transport authorities for infrastructure build-out can secure long-term supply contracts. Focus on developing cost-effective, regionally compliant solutions.
For Investors and Strategic Acquirers:
SAE J3400 adoption reshapes the acquisition landscape, favoring companies with adaptable manufacturing capabilities or intellectual property in compact, high-power designs. This market offers long-term viability as an essential component of EV infrastructure. Identify acquisition targets specializing in advanced thermal management, bidirectional charging technology, or those with strong certification portfolios in multiple regions. Watch for further consolidation of regional charging standards as an inflection indicator for market harmonization.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Streamlines manufacturing processes and reduces inventory complexity for diverse connector types. |
| Charging Infrastructure Partnership | Secures long-term supply agreements and integrates solutions directly into expanding charging networks. |
| Backward Integration | Mitigates input material cost volatility and ensures a stable supply of critical components. |
| Product Launch: V2G Connectors | Opens new revenue streams by enabling bidirectional energy transfer and grid stabilization services. |
| Geographic Expansion | Captures nascent demand in emerging EV markets across Southeast Asia and Latin America. |
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Streamlines manufacturing processes and reduces inventory complexity for diverse connector types. |
| Charging Infrastructure Partnership | Secures long-term supply agreements and integrates solutions directly into expanding charging networks. |
| Backward Integration | Mitigates input material cost volatility and ensures a stable supply of critical components. |
| Product Launch: V2G Connectors | Opens new revenue streams by enabling bidirectional energy transfer and grid stabilization services. |
| Geographic Expansion | Captures nascent demand in emerging EV markets across Southeast Asia and Latin America. |
Research Approach
Operator-level perspectives from Charge Point Operators, Vehicle Manufacturers, Commercial Fleet Operators, and Component Engineers anchored the qualitative base. This primary research was triangulated with secondary validation from regulatory body publications, automotive industry association reports, and financial filings. Both bottom-up and top-down approaches ensured comprehensive data collection and cross-verification.
Scenario-bracketing framing informed the analytical framework across the modeling period. Segmentation dimensions included product type, charging level, application, end-user, and regional regulatory frameworks. Compound annual growth rates were derived from historical data extrapolation and future growth projections based on market drivers. EV sales forecasts and public charging station deployment rates served as key industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by disruptive technology developers or state-backed infrastructure players would shift outcomes. Forecasts reflect assumptions regarding technological advancements and market acceptance. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Electric Wheelbarrow Market
Vehicle Components
Forestry Trailers Market
Vehicle Components
India Automotive Steering System Market
Vehicle Components
Automotive Composite Suspension Components Market
Vehicle Components
Global Automotive EGR Valves Market
Vehicle Components
LAMEA Vehicle Exhaust Hose Market
Vehicle Components
Global Boat Trailers Market
Vehicle Components
Crank Case Ventilation Valve Market
Vehicle Components
South Africa Automotive Thermoplastic Polymer Composites Market
Vehicle Components
Driveline Systems for Electric Vehicle Market
Vehicle Components
Anchorage Connector Market
Vehicle Components
Marine Wheel Bearings Market
Vehicle Components
Rear-Wheel Steering Actuator Systems for SUVs Market
Vehicle Components
Global Automotive Rain, Light, Humidity Sensor Market
Vehicle Components
Bicycle Lights Market
Vehicle Components
Trailer Axle Market