
 Intralogistics Containers Market | 2026-2036
Intralogistics Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Intralogistics Containers Market Insights
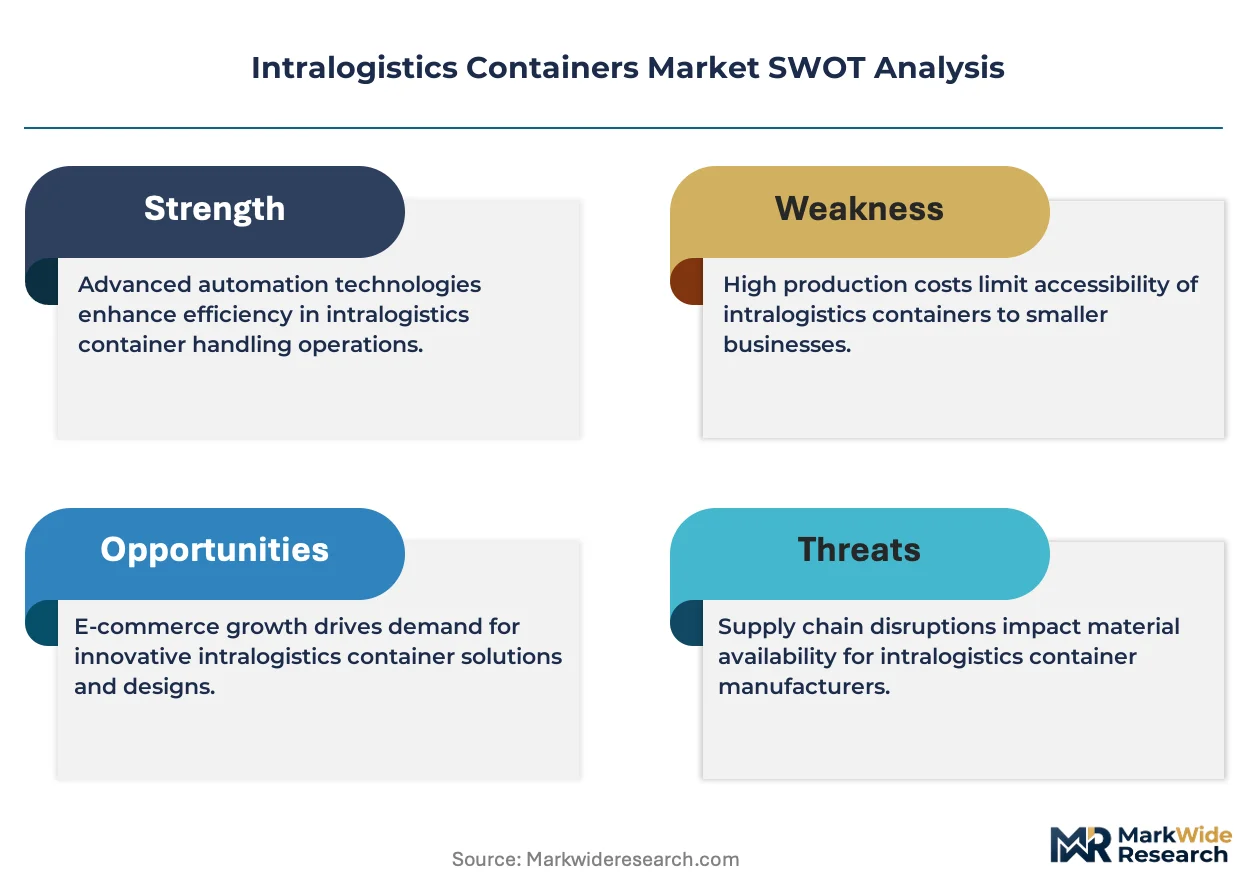
Asset-light leasing models for reusable container fleets are reshaping competitive dynamics in the Intralogistics Containers Market. Georg Utz Holding AG leverages its European manufacturing footprint to sustain long-term rental contracts with automotive suppliers. SSI Schaefer anchors its position through integrated software-hardware offerings that tie container tracking to warehouse execution systems. Bekuplast GmbH differentiates via specialized folding containers designed for pharmaceutical cold-chain compliance.
Intralogistics containers are standardized load carriers engineered from polypropylene, steel, or high-density polyethylene with defined external dimensions for automated handling equipment, designed to protect goods during internal transport, storage, and order fulfillment within distribution and production facilities. Plastic crates dominate volume shipments due to their modularity and compatibility with conveyor and robotic picking systems, while folding containers capture the fastest expansion as warehouses prioritize cube utilization in high-rent locations. Metal bins retain margin concentration in heavy-duty applications serving automotive suppliers and metalworking operations where durability thresholds exceed polymer capabilities.
The EU Packaging and Packaging Waste Regulation and REACH chemical compliance frameworks are elevating recyclability requirements and restricting certain additive formulations in polypropylene containers sold across Europe. FDA food-contact standards and OSHA material handling guidelines in the United States shape product specifications for containers deployed in food processing and manual picking environments. Stakeholders must monitor evolving extended producer responsibility schemes and automation interface standards as these will determine which container formats achieve preferred vendor status with warehouse automation integrators.
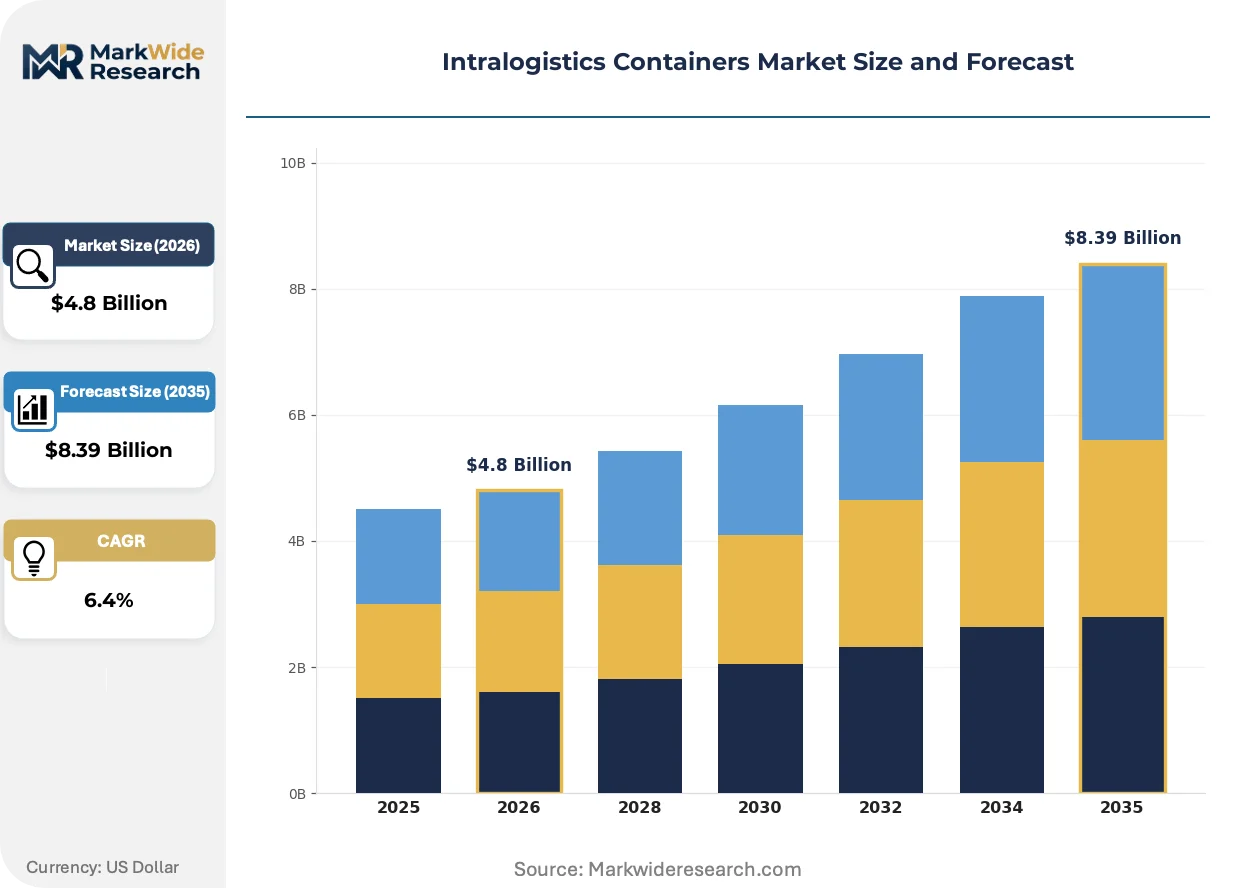
Market Dynamics
EU Packaging and Packaging Waste Regulation mandates are forcing container manufacturers to redesign polypropylene formulations for circularity while e-commerce fulfillment centers demand standardized footprints compatible with robotic handling systems.
Growth Catalysts
- EU reusability mandates:The EU Packaging and Packaging Waste Regulation tightens reusability thresholds across member states, compelling automotive suppliers to replace single-use corrugated with returnable polypropylene totes.
- Automated warehouse expansion:E-commerce fulfillment centers in Germany and the Netherlands deploy standardized foldable containers to maximize cube density in high-rent logistics corridors.
- Polypropylene modularity:Injection-molded containers with integrated RFID pockets enable seamless tracking integration with warehouse execution systems.
Market Restraints
- Feedstock volatility:Propylene monomer prices fluctuate with naphtha cracking economics, compressing margins for European container manufacturers dependent on petrochemical supply chains.
- REACH compliance costs:ECHA restrictions on certain phthalate plasticizers and flame retardants force reformulation cycles that extend product development timelines by 8-14 months.
- Steel substitution in heavy-duty:Automotive stamping operations retain metal stillages for engine block transport where polymer deflection limits exceed safety thresholds.
Strategic Opportunities
- Pharmaceutical cold-chain:Insulated folding containers with phase-change material integration address temperature excursion risks in biologics distribution.
- Asset-light leasing:Fleet rental models reduce capital barriers for mid-tier third-party logistics providers seeking standardized container pools without ownership.
- Extended producer responsibility schemes:France and Germany advance packaging deposit systems that reward manufacturers with verified recyclability pathways.
Industry Challenges
- Automation interface standardization:Divergent conveyor and robotic gripper specifications across warehouse integrators force container producers to maintain multiple dimensional variants.
- RFID integration complexity:Embedding durable transponders in polypropylene walls without signal interference requires specialized overmolding expertise that concentrates among tier-one suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intralogistics Containers Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Container Type: Plastic Crates, Metal Bins, Folding Containers, Mesh Containers, Bulk Boxes Material: Polypropylene, Steel, Aluminum, High-Density Polyethylene, Composite Materials Application: Warehouse Storage, Order Picking, Parts Handling, Distribution Centers, Assembly Lines End User Industry: E-commerce Fulfillment, Food Processing, Electronics Manufacturing, Pharmaceutical Packaging, Automotive Suppliers |
| Companies Covered | AUER Packaging, Bekuplast GmbH, Bito, Corplex, Deluxe Packaging, Flexcon, Georg Utz Holding AG, SSI Schaefer, Shanghai Join Plastic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intralogistics Containers Market Trends and Innovations
Container intelligence, material circularity, and procurement model flexibility are converging to redefine competitive advantage in intralogistics load carrier supply.
RFID-embedded smart containers are migrating from pilot deployments in pharmaceutical distribution to mainstream adoption across grocery and electronics fulfillment networks. German automotive suppliers now specify transponder-integrated totes for sequenced parts delivery to assembly lines. This migration from passive identification to real-time location tracking compresses inventory reconciliation cycles and enables dynamic route optimization within warehouse management systems.
REACH chemical compliance frameworks are elevating recyclability requirements and restricting certain additive formulations in polypropylene containers sold across Europe. Industrial consequence includes mandatory recyclate content thresholds and restricted substance lists that disqualify legacy colorants and stabilizers. Container producers serving food-contact applications face the steepest reformulation burdens as EFSA evaluates migration limits for novel polymer blends.
Third-party logistics providers are consolidating container procurement under long-term fleet leasing arrangements rather than capital purchase models. This behavioral shift concentrates buying power among specialized container-as-a-service operators and displaces spot-market transactions. The Netherlands and Belgium exhibit the fastest leasing penetration where dense logistics clustering justifies pooled container circulation networks.
Intralogistics Containers Market Segmentation
Intralogistics container procurement diverges sharply across handling environments, with automated fulfillment centers demanding precision-engineered footprints while heavy manufacturing tolerates dimensional variance for durability gains. Segmentation reveals how material selection and structural format determine compatibility with conveyor systems, robotic grippers, and inventory tracking infrastructure.
Container Type:
Mature formats dominate established verticals while emerging designs capture warehouse automation retrofits.
- Plastic Crates:Injection-molded polypropylene units with standardized base dimensions for conveyor compatibility. E-commerce fulfillment centers in Germany and the Netherlands specify these for high-velocity picking operations where RFID integration enables real-time inventory tracking.
- Folding Containers:Collapsible sidewall designs reduce return transport volume by 60-75 percent. Third-party logistics providers in Belgium prioritize these for pooled fleet models where cube utilization directly reduces freight spend on empty container repositioning.
- Metal Bins:Welded steel constructions for engine block and stamping transport in automotive supply chains.
- Mesh Containers:Wire-grid sidewalls for visual inventory verification in assembly line sequencing.
- Bulk Boxes:Large-format polymer or steel containers for raw material inbound logistics.
Plastic crates retain volume leadership; folding containers hold the steepest expansion curve.
Material:
Cost tier stratification separates commodity polymers from performance metals and engineered composites.
- Polypropylene:Thermoplastic polymer offering chemical resistance and fatigue endurance across temperature cycles. REACH compliance mandates are forcing reformulation of legacy additive packages to eliminate restricted phthalate plasticizers.
- Steel:Carbon and stainless grades for load-bearing applications exceeding polymer deflection limits. Automotive stamping operations in Germany specify steel stillages where dynamic loading thresholds surpass safety margins for plastic alternatives.
- High-Density Polyethylene:Lower-density alternative for cold-storage applications requiring impact resistance at sub-zero temperatures.
- Aluminum:Lightweight metal for aerospace component handling and weight-sensitive transport.
- Composite Materials:Fiber-reinforced polymers for specialized pharmaceutical and electronics applications.
Polypropylene commands the broadest application base; composite materials are gaining share fastest in regulated industries.
Application:
Volume concentration tracks automation penetration, with manual handling environments representing mature demand and robotic integration driving specification upgrades.
- Warehouse Storage:Static racking applications with dimensional constraints dictated by pallet and shelf standards. Food processing facilities in France deploy stackable containers with FDA-compliant contact surfaces for ingredient staging.
- Order Picking:High-velocity retrieval operations requiring ergonomic handholds and barcode visibility. Electronics fulfillment centers specify translucent polypropylene totes for visual confirmation without container opening.
- Parts Handling:Sequenced delivery to manufacturing lines with first-in-first-out orientation.
- Distribution Centers:Cross-dock and sortation infrastructure with conveyor compatibility requirements.
- Assembly Lines:Point-of-use presentation with return logistics integration.
Warehouse storage anchors procurement volumes; order picking applications are expanding most quickly with e-commerce automation.
End User Industry:
Customer type determines specification stringency, with regulated industries imposing material traceability and hygiene protocols that commodity manufacturing bypasses.
- E-commerce Fulfillment:Automated storage and retrieval systems with robotic handling compatibility. Amazon and Zalando logistics networks in Germany specify foldable containers with integrated RFID pockets for warehouse execution system integration.
- Pharmaceutical Packaging:Cold-chain and cleanroom compliance with EMA guidance on primary packaging materials. Temperature-validated containers with phase-change material integration address biologics distribution excursion risks.
- Automotive Suppliers:Sequenced parts delivery with just-in-time synchronization to assembly schedules.
- Food Processing:EU food-contact regulations and national hygiene codes for ingredient and finished goods handling.
- Electronics Manufacturing:Electrostatic discharge protection and particulate contamination control.
E-commerce fulfillment drives the largest procurement volumes; pharmaceutical packaging holds the steepest expansion trajectory as cold-chain biologics distribution accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive suppliers command premium pricing for polypropylene container systems, while Chinese manufacturers compete on volume throughput for standardized folding bins. This pricing-power asymmetry reflects divergent automation penetration and regulatory stringency across manufacturing corridors.
Germany
Automotive sequenced parts delivery and third-party logistics consolidation drive procurement volumes for returnable container fleets. The EU Packaging and Packaging Waste Regulation mandates reusability thresholds that accelerate replacement of single-use corrugated packaging. The Stuttgart industrial corridor anchors demand from Bosch and Daimler Truck suppliers deploying RFID-integrated totes for just-in-time assembly line synchronization.
United States
E-commerce fulfillment center automation and food processing cold-chain expansion sustain demand for FDA-compliant container systems. OSHA material handling guidelines shape ergonomic specifications for manual picking environments in high-velocity distribution networks. The Chicago-Milwaukee logistics corridor concentrates procurement from Amazon and Target regional fulfillment hubs requiring standardized footprints for robotic handling integration.
China
Domestic e-commerce platform logistics networks and electronics manufacturing clusters propel volume shipments of injection-molded folding containers. The country's national packaging standardization framework accelerates footprint harmonization across conveyor and automated storage systems. The Yangtze River Delta manufacturing belt around Shanghai and Suzhou hosts the densest concentration of container fabricators serving JD.com and Alibaba fulfillment infrastructure.
Netherlands
Rotterdam port-centric distribution and European cross-dock consolidation favor asset-light leasing models for pooled container circulation. The country's extended producer responsibility scheme for packaging rewards manufacturers with verified recyclability pathways and circular material flows. The Venlo logistics cluster bordering Germany anchors procurement from DHL and Kuehne+Nagel regional distribution hubs prioritizing cube utilization in high-rent corridors.
France
Pharmaceutical cold-chain distribution and food processing hygiene compliance elevate specification requirements for temperature-validated container systems. ANSM guidance on primary packaging materials for biologics distribution shapes material traceability protocols. The Lyon-Saint-Étienne pharmaceutical manufacturing corridor drives demand for insulated folding containers with phase-change material integration from Sanofi and Boehringer Ingelheim distribution operations.
Intralogistics Containers Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower scope but deeper format expertise. The market structures around three tiers: multinational material handling conglomerates with software-hardware bundles, mid-cap container fabricators with regional manufacturing footprints, and specialized leasing operators managing pooled fleet logistics. Strategic differentiation concentrates on RFID integration capabilities, circular material certifications, and long-term rental contract structures. Competitive moves center on backward integration into polymer compounding and geographic expansion through distribution partnerships with warehouse automation integrators.
Within the European manufacturing tier, Georg Utz Holding AG, Bekuplast GmbH, and SSI Schaefer occupy positions defined by automation interface depth and sector-specific compliance expertise. Georg Utz exemplifies the family-owned fabricator archetype with captive injection molding capacity and automotive supplier relationships. Bekuplast represents specialization in pharmaceutical cold-chain formats with folding structural designs. SSI Schaefer anchors the integrated platform segment where container hardware ties to warehouse execution software. These three sit within a competitive set where differentiation depends on REACH-compliant material formulations and RFID pocket standardization rather than commodity volume scale.
| Leading Market Players |
|---|
| AUER Packaging |
| Bekuplast GmbH |
| Bito |
| Corplex |
| Deluxe Packaging |
| Flexcon |
| Georg Utz Holding AG |
| SSI Schaefer |
| Shanghai Join Plastic |
| Others |
Pricing and Supply Chain Analysis
Propylene monomer volatility from naphtha cracking economics compresses margin buffers across European injection molders and forces pricing tier spreads that separate REACH-certified premium grades from commodity polypropylene alternatives. This feedstock instability simultaneously accelerates backward integration into polymer compounding among tier-one fabricators and expands supply chain redundancy requirements for automotive suppliers managing sequenced parts delivery.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with automotive sequenced parts delivery commanding the highest certification premiums due to RFID integration and EMA traceability requirements. Price differentiation hinges on REACH compliance grade and volume scale, with long-term fleet leasing contracts compressing per-unit spot pricing for third-party logistics providers. Cost compression in standard-grade polypropylene is intensifying because of Asian import competition, while pharmaceutical cold-chain buyers show the least price sensitivity due to biologics temperature excursion liability.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk calculations for injection-molded folding containers, with German automotive suppliers accelerating dual-sourcing verification to reduce dependency on Yangtze River Delta fabricators. Manufacturing concentrates in China, Germany, and the Netherlands, with raw material sourcing drawing from Saudi petrochemical complexes, Belgian polymer compounding facilities, and domestic European recyclate streams. Distribution runs through Rotterdam port-centric consolidation hubs and regional container pooling networks managed by specialized fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Container-as-a-service leasing models are expanding faster than hardware shipments, with RFID-enabled fleet management and circular material certification emerging as the primary recurring-revenue layers. This service attach opportunity restructures competitive advantage toward software-hardware integration and long-term contract retention.
For Market Incumbents: Harden automation interface depth by embedding standardized RFID pockets compatible with warehouse execution systems from SSI Schaefer and comparable integrators. Defend against Asian volume competition by securing captive polymer compounding capacity in Germany or the Netherlands to insulate margin buffers from propylene price swings. Prioritize EFSA food-contact certification investments to capture pharmaceutical and food processing procurement specifications that disqualify commodity alternatives.
For New Entrants and Emerging Players: Mid-market third-party logistics providers in Belgium and the Netherlands represent the most penetrable entry point, with asset-light leasing demand outpacing capital purchase capacity among regional distributors. Pharmaceutical cold-chain folding containers with phase-change material integration offer specification differentiation that bypasses commodity price competition. A direct go-to-market angle through warehouse automation integrators rather than end-user sales accelerates technical validation and specification inclusion.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialized container fabricators with REACH-compliant material formulations and established automotive supplier relationships. Long-term viability rests on circular economy positioning as extended producer responsibility schemes mature across France, Germany, and the Netherlands. The signal to watch is regulatory acceleration of recyclate content thresholds that would disqualify legacy additive formulations and concentrate procurement among certified suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captive propylene supply from BASF or SABIC partnerships insulates margin compression from naphtha volatility. |
| RFID Pocket Standardization | Universal transponder compatibility with Dematic and Swisslog systems accelerates warehouse automation specification. |
| Extended Producer Responsibility Compliance | Verified recyclability pathways under France's Citeo scheme unlock preferred vendor status with pooled fleet operators. |
| Pharmaceutical Cold-Chain Format Development | Phase-change material integration addresses EMA guidance on biologics distribution temperature validation. |
| Regional Manufacturing Footprint Expansion | Injection molding capacity in Venlo or Stuttgart corridors reduces lead times for German automotive sequenced delivery. |
Research Methodology
Initial hypotheses were tested against primary input from warehouse automation integrators, automotive Tier 1 procurement directors, third-party logistics fleet managers, and polymer compounding technical leads, then refined through secondary validation. Primary fieldwork combined structured interviews with secondary analysis of EU Packaging and Packaging Waste Regulation implementation timelines, ECHA restricted substance list updates, and customs data on polypropylene container trade flows. Bottom-up container shipment estimates by format and material were triangulated against top-down e-commerce fulfillment center automation capex projections.
Demand-supply balance modeling across the analysis window incorporated container type, material grade, application environment, and end-user industry segmentation dimensions. CAGRs were derived from growth rate reconciliation between historical shipment trajectories and forward-looking automation penetration assumptions. Forecast inputs included warehouse rent index movements in German logistics corridors and REACH compliance cost pass-through elasticity observed in automotive supplier procurement.
Macroeconomic conditions sit as an overlay; deviation in propylene monomer pricing, EU regulatory enforcement intensity, or e-commerce fulfillment automation deployment schedules would shift the trajectory. Forecasts reflect documented assumptions on material substitution thresholds and leasing model adoption curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
South Korea Third-Party Logistics (3PL) Market
Logistics and Shipping
Canada Cold Chain Logistics Market
Logistics and Shipping
UAE Logistics Market
Logistics and Shipping
North America Logistics Market
Logistics and Shipping
Italy Freight and Logistics Market
Logistics and Shipping
Europe Full Container Load (FCL) Market
Logistics and Shipping
Terminal Tractors Market
Logistics and Shipping
Australia 3PL Market
Logistics and Shipping
China Freight and Logistics Market
Logistics and Shipping
Kazakhstan Freight and Logistics Market
Logistics and Shipping
Peru Cold Chain Logistics Market
Logistics and Shipping
China Digital Freight Forwarding Market
Logistics and Shipping
Digital Logistics Market
Logistics and Shipping
South America Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Europe FMCG Logistics Market
Logistics and Shipping
Germany Dangerous Goods Logistics Market