
 North America Precision Gearbox Market | 2026-2036
North America Precision Gearbox Market Size, Share, and Industry Trends Forecast 2026-2036
North America Precision Gearbox Market Analysis
Equipment leasing and power-by-the-hour service contracts are reshaping capital deployment across the North America precision gearbox sector. Nabtesco Corporation leverages its strain-wave gear expertise to anchor high-repeatability robotics applications in Michigan and Ohio. Emerson Electric Co. competes through integrated motor-gearbox platforms that reduce commissioning complexity for automotive OEMs. Regal Rexnord sustains aftermarket revenue streams via extensive distributor networks covering the Mexican maquiladora belt.
A precision gearbox transmits rotational power between mechanical systems with minimal backlash, typically achieving positioning accuracy below one arc-minute through hardened alloy-steel gearing and ground tooth profiles. These units convert motor torque into controlled motion for CNC machine tools, robotic joints, and wind-turbine pitch systems. Planetary gearboxes dominate industrial automation installations where coaxial packaging and load distribution matter most. Helical gearboxes occupy material handling and conveyor applications requiring continuous-duty torque transmission with reduced noise signatures. Worm gearboxes retain share in machine-tool indexing tables where self-locking characteristics eliminate brake hardware.
NHTSA Corporate Average Fuel Economy standards compel automotive OEMs to specify lighter, more efficient gearbox architectures for electric-vehicle powertrains. EPA Clean Air Act enforcement shapes lubricant chemistry and sealing specifications for hydraulic drive systems deployed in heavy manufacturing. OSHA machine-guarding mandates influence integrated safety-rated encoder options on servo-grade units. Stakeholders must monitor how IEEE 1547 interconnection standards for grid-tied renewable assets alter gearbox duty-cycle requirements in Texas and California wind farms.
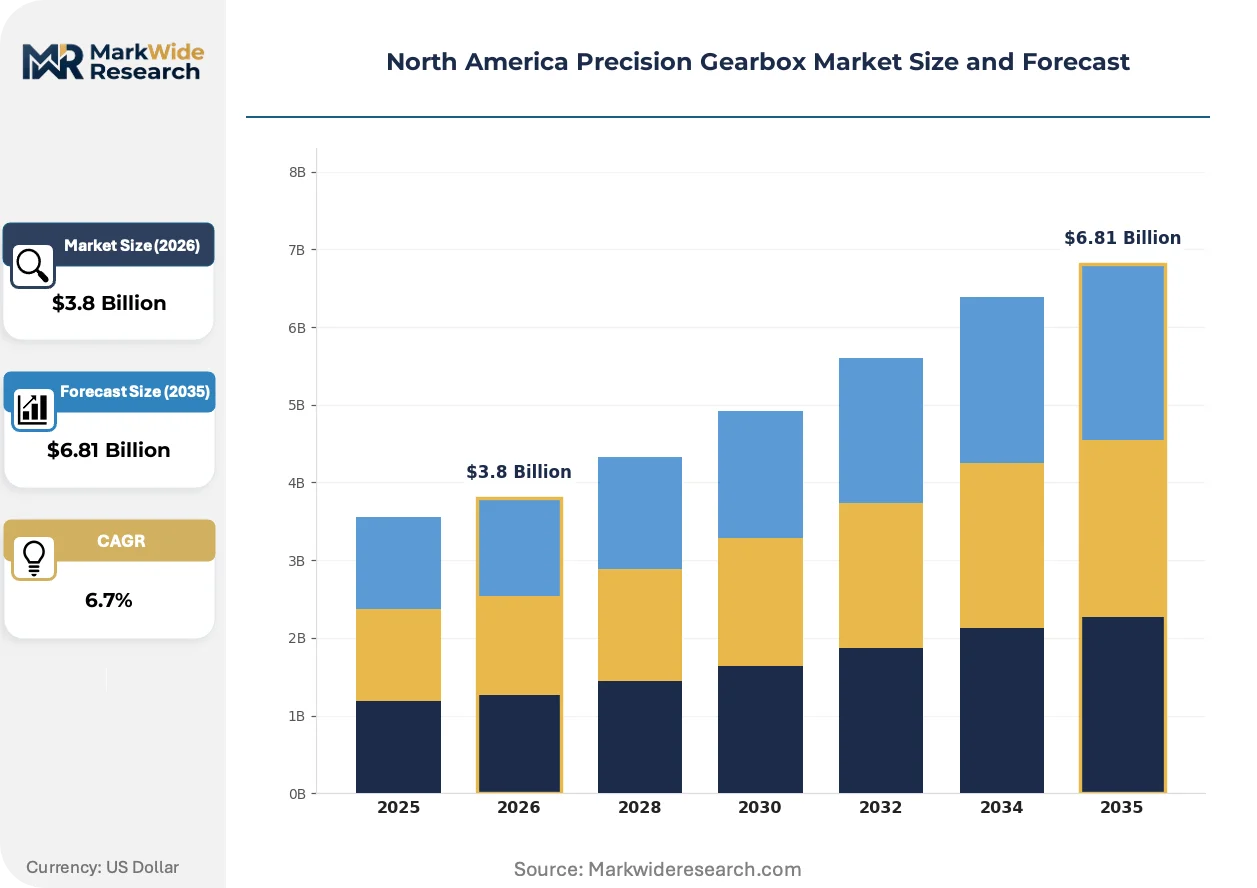
Market Dynamics
NHTSA Corporate Average Fuel Economy mandates and EPA industrial emissions enforcement are compressing gearbox tolerances and driving OEMs toward precision-matched drivetrain architectures across automotive and renewable-energy applications.
Growth Catalysts
- Automotive Electrification Mandates:NHTSA fuel-economy standards compel EV powertrain designers to specify lighter, more efficient precision gearboxes that reduce rotational losses and extend range.
- Robotics Density Expansion:Michigan and Ohio automotive plants are deploying high-torque compact strain-wave units for collaborative robot joints requiring sub-arc-minute repeatability.
- Wind Energy Infrastructure Buildout:Texas and California renewable-energy zones are installing precision pitch-control gearboxes to meet IEEE 1547 grid-interconnection standards for variable-speed turbine operation.
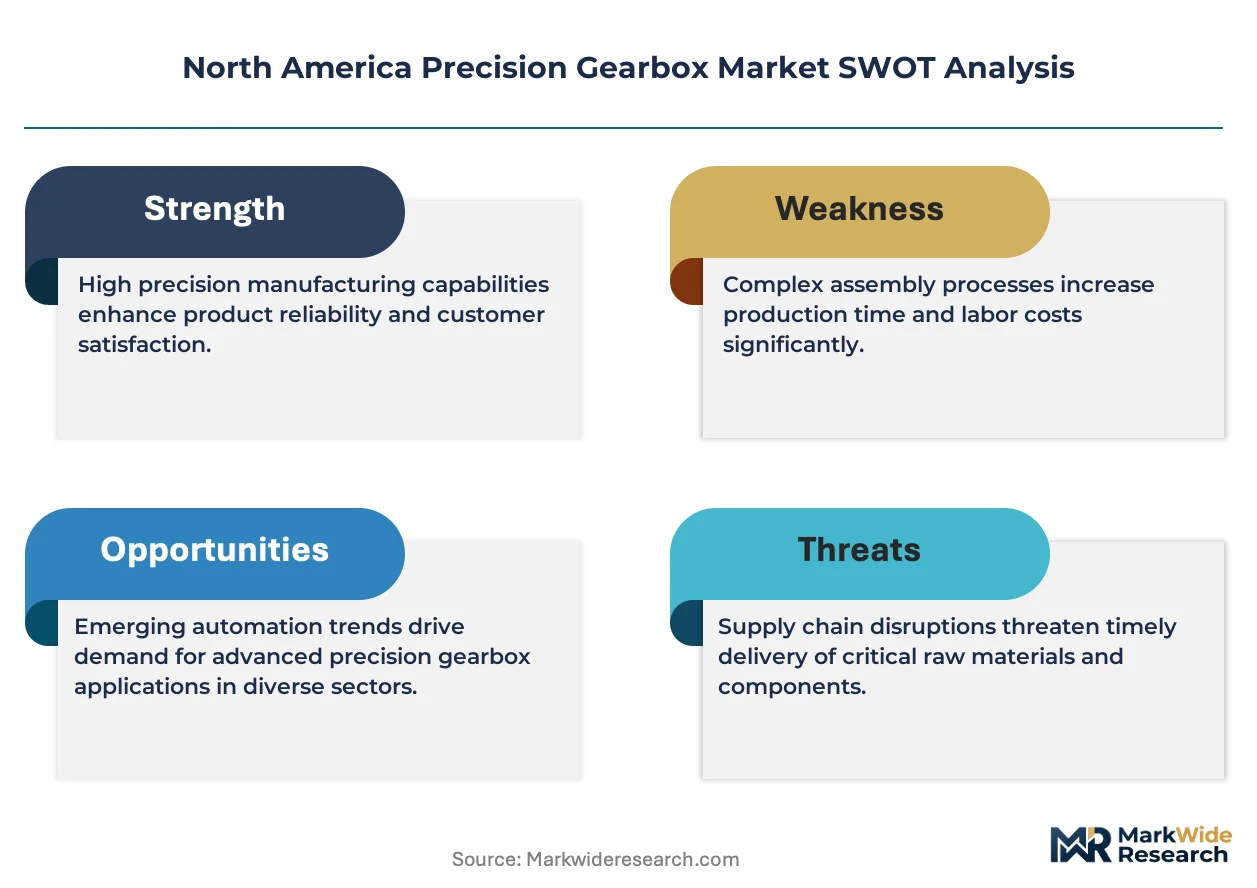
Market Restraints
- Alloy Steel Input Volatility:Hardened alloy-steel billet prices fluctuate with nickel and molybdenum commodity markets, compressing margin predictability for ground-tooth gearbox producers.
- Supply Concentration Risk:High-precision grinding spindle and CMM inspection equipment production concentrates in Germany and Japan, creating lead-time vulnerability for North American gearbox manufacturers.
- Technical Limitation:Strain-wave gearboxes face torque-density ceilings above 500 Nm that exclude them from heavy-material handling and large-scale industrial press applications.
Strategic Opportunities
- Mexican Maquiladora Expansion:Regal Rexnord distributor networks already cover the northern Mexico manufacturing belt, positioning precision gearbox vendors to capture automotive and aerospace subcontractor demand.
- Power-by-the-Hour Contracts:Equipment leasing and uptime-guarantee service models are displacing capital purchase patterns among Great Lakes automotive tier-one suppliers.
- Integrated Motor-Gearbox Convergence:Servo motor and precision gearbox combination units reduce commissioning complexity and panel space for CNC machine tool builders.
Industry Challenges
- Precision Grinding Talent Scarcity:Ground tooth profile production requires specialized machinist skills that vocational programs in the United States and Canada are not replenishing at replacement rates.
- OSHA Machine-Guarding Compliance:Integrated safety-rated encoder specification adds engineering cycle time and certification documentation burden for servo-grade gearbox launches.
- Legacy Hydraulic System Integration:Retrofitting precision electromechanical actuators into existing press and conveyor infrastructure demands custom adapter engineering and extended commissioning periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Precision Gearbox Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bevel Gearboxes, Planetary Gearboxes, Worm Gearboxes, Helical Gearboxes End User: Automotive OEMs, Aerospace Industries, Robotics Manufacturers, Renewable Energy Providers Technology: Electrical Drive Systems, Pneumatic Drive Systems, Hydraulic Drive Systems, Mechanical Drive Systems Application: Industrial Automation, Material Handling, Conveyor Systems, Machine Tools |
| Companies Covered | Emerson Electric Co., Harmonic Drive Systems Inc, Nabtesco Corporation, Nidec Corp, Sumitomo Corp, ABB Ltd, Bonfiglioli, Hiwin Technologies Corp, Regal Rexnord, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Precision Gearbox Market Emerging Trajectories
Digital twin technology and additive manufacturing are compressing prototype-to-production cycles while regulatory pressure on lubricant chemistry is forcing material science adaptation across precision gearbox architectures.
Digital twin software is virtualizing gearbox performance simulation before physical prototyping. Automotive OEMs in Michigan and Ohio are adopting these platforms to validate thermal and fatigue behavior under NHTSA drive-cycle loads. This capability is virtualizing traditional build-and-test development sequences that previously consumed twelve to eighteen months.
EPA Clean Air Act enforcement is restricting traditional petroleum-based lubricant formulations for hydraulic drive systems. Gearbox manufacturers are qualifying synthetic ester and polyalkylene glycol chemistries that maintain viscosity stability across wider temperature ranges. Heavy manufacturing deployments in Texas and the Great Lakes corridor are most affected, with OEMs now specifying biodegradable seal materials to preempt compliance exposure.
Power-by-the-hour service contracts are displacing outright equipment ownership among automotive tier-one suppliers. Leasing providers assume maintenance liability and uptime risk, unbundling aftermarket service from original equipment margins. This model concentrates most visibly in the Great Lakes automotive corridor where capital deployment flexibility outweighs balance-sheet asset preference.
North America Precision Gearbox Market Segmentation
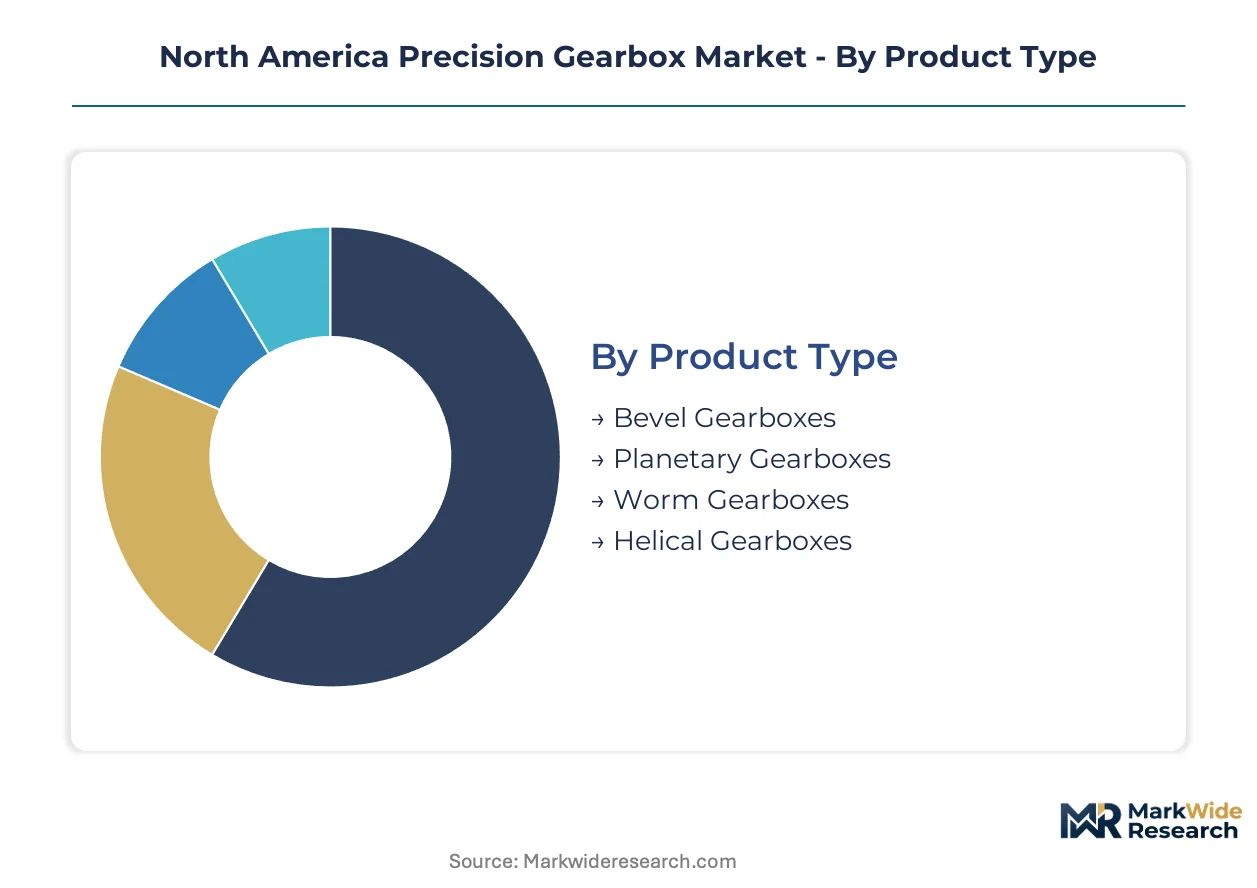
Precision gearbox architectures vary dramatically across torque requirements, motion profiles, and environmental constraints. Each segmentation dimension reveals distinct procurement patterns and technical specifications that shape vendor positioning across Michigan automotive plants, Texas wind farms, and Ohio robotics facilities.
Product Type:
Planetary configurations dominate where coaxial packaging and load distribution intersect with space constraints.
- Planetary Gearboxes:Multiple planet gears distribute torque across a sun gear and ring gear assembly, achieving torque densities exceeding 300 Nm per kilogram. Michigan and Ohio automotive OEMs specify these for robotic joint actuation where NHTSA lightweighting mandates intersect with precision positioning requirements.
- Helical Gearboxes:Angled tooth engagement produces axial thrust alongside torque transmission, yielding noise signatures 8-12 dB lower than spur equivalents. Great Lakes material handling corridors deploy these for continuous-duty conveyor applications where OSHA noise exposure limits govern equipment selection.
- Worm Gearboxes:Screw-wheel meshing creates irreversible motion transfer eliminating external brake hardware.
- Bevel Gearboxes:Orthogonal shaft arrangements redirect power through intersecting axes for compact right-angle installations.
Established volume favors Planetary; emerging adoption favors Helical.
End User:
Procurement sophistication varies sharply across capital intensity and certification requirements.
- Automotive OEMs:EV powertrain integration demands gearboxes achieving rotational efficiencies above 96% to preserve range under NHTSA Corporate Average Fuel Economy testing protocols. Tier-one suppliers in Michigan and Ohio now specify integrated motor-gearbox platforms that compress commissioning cycles.
- Robotics Manufacturers:Strain-wave and planetary architectures serve collaborative robot joints requiring sub-arc-minute repeatability. Texas and California automation clusters source high-torque compact units for six-axis articulated arms deployed in automotive subassembly.
- Aerospace Industries:AS9100 certification and traceability requirements govern every machining operation.
- Renewable Energy Providers:Texas and California wind farms specify pitch-control gearboxes meeting IEEE 1547 grid-interconnection standards for variable-speed turbine operation.
Capital deployment scale concentrates with Automotive OEMs; technical specification intensity peaks with Aerospace Industries.
Technology:
Drive system selection traces back to power density needs and infrastructure availability.
- Electrical Drive Systems:Servo motor and precision gearbox integration enables closed-loop positioning with encoder feedback resolutions below 0.1 arc-seconds. EPA industrial emissions enforcement is accelerating displacement of hydraulic alternatives in Great Lakes manufacturing zones.
- Hydraulic Drive Systems:Fluid power transmission delivers stall-proof torque multiplication for heavy pressing and forming operations. EPA Clean Air Act restrictions on petroleum-based lubricants are forcing synthetic ester qualification across Texas heavy manufacturing deployments.
- Pneumatic Drive Systems:Compressed air power suits explosive atmosphere applications where electrical ignition risks are prohibitive.
- Mechanical Drive Systems:Direct mechanical linkages persist in legacy machine-tool installations.
Electrical Drive Systems are gaining share fastest; Hydraulic Drive Systems face regulatory headwinds.
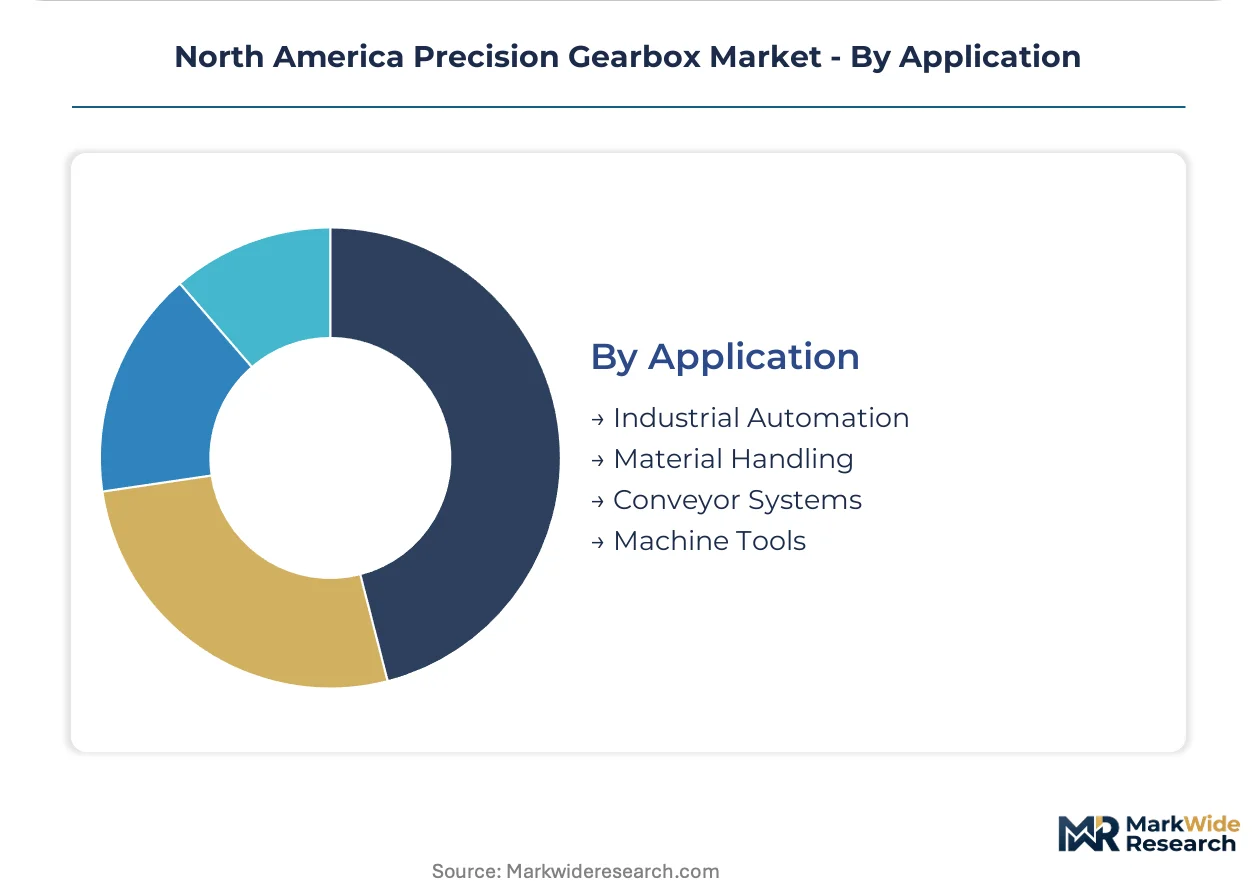
Application:
Motion profile requirements dictate gearbox architecture selection across factory floors.
- Industrial Automation:CNC machine tools and robotic workcells demand positioning accuracy below one arc-minute with repeatability across millions of cycles. Michigan and Ohio metalworking clusters specify ground-tooth planetary units with integrated safety-rated encoders complying with OSHA machine-guarding mandates.
- Machine Tools:Indexing tables and spindle drives require self-locking characteristics or ultra-low backlash depending on cutting force vectors. Worm and helical configurations split this territory based on speed-torque tradeoffs.
- Material Handling:Continuous-duty torque transmission with minimal maintenance intervals governs conveyor and hoist specifications.
- Conveyor Systems:Distributed drive architectures favor modular gearbox-motor combinations.
Technical complexity concentrates in Industrial Automation; unit volume concentrates in Material Handling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEMs and robotics integrators concentrate procurement authority across three distinct national manufacturing corridors. NHTSA fuel-economy mandates and EPA industrial emissions rules shape specification requirements from Detroit to Monterrey.
United States
Michigan and Ohio automotive clusters drive demand for high-torque compact strain-wave units in collaborative robot joints. NHTSA Corporate Average Fuel Economy standards compel EV powertrain designers to specify precision-matched drivetrains achieving rotational efficiencies above 96%. Texas wind farms install IEEE 1547-compliant pitch-control gearboxes for variable-speed turbine operation.
Canada
Ontario's automotive supplier base sources integrated motor-gearbox platforms to compress commissioning cycles for EV component manufacturing. Environment and Climate Change Canada enforces industrial emissions thresholds that accelerate displacement of hydraulic alternatives in Great Lakes manufacturing zones. Quebec's aerospace subcontractors specify AS9100-certified units with full machining traceability.
Mexico
Nuevo León and the Bajío Region automotive maquiladoras expand precision gearbox procurement for export-oriented assembly operations. PROFEPA environmental enforcement restricts petroleum-based lubricant formulations in heavy manufacturing deployments. Northern Mexico distributor networks capture tier-one supplier demand across the Monterrey-Saltillo industrial corridor.
North America Precision Gearbox Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base clusters around three strategic archetypes: integrated electromechanical platform providers, strain-wave gear specialists, and aftermarket service network operators. Dominant competitive moves include geographic expansion into Mexican manufacturing zones and portfolio diversification toward power-by-the-hour service contracts.
Among Japan-based precision gear specialists, Nabtesco Corporation and Harmonic Drive Systems Inc. occupy positions within the high-repeatability robotics tier. Emerson Electric Co. sits within the integrated motor-gearbox platform archetype alongside ABB Ltd. Regal Rexnord exemplifies the aftermarket network model with coverage extending across the Mexican maquiladora belt.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Harmonic Drive Systems Inc |
| Nabtesco Corporation |
| Nidec Corp |
| Sumitomo Corp |
| ABB Ltd |
| Bonfiglioli |
| Hiwin Technologies Corp |
| Regal Rexnord |
| Others |
Supply Flow & Price Mechanics
Overcapacity in German precision-grinding spindle manufacturing is compressing lead-time premiums and forcing North American gearbox assemblers to renegotiate annual contracts. This utilization slack simultaneously erodes supplier pricing power while enabling OEMs to consolidate vendor panels across the Great Lakes automotive corridor.
Pricing Analysis
Certification level (ISO/AS9100/CE-grade) creates the primary spread between premium servo-grade units and standard industrial configurations. Three-tier pricing structure across premium, standard, and economy levels reflects traceability documentation depth and ground-tooth precision grades. Price erosion runs through the standard tier as Chinese planetary gearbox imports penetrate material handling applications. Tier-one automotive suppliers in Michigan exhibit lowest price sensitivity due to NHTSA compliance liability, while Mexican maquiladora subcontractors face acute cost compression.
Supply Chain Analysis
Contract manufacturing concentration sits with specialized gear-grinding houses in Germany, Japan, and Taiwan holding high-precision CMM inspection capacity. Hardened alloy-steel billets draw from mills in the United States, Sweden, and Japan, while ground tooth profiles hinge on imported grinding spindle technology. Single-source vulnerability concentrates in Japanese strain-wave gear component supply. Distribution runs through authorized distributor networks covering the Monterrey-Saltillo industrial corridor and Great Lakes manufacturing zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Direct-drive torque motor substitution threatens precision gearbox incumbents in high-repeatability robotics joints, compelling defensive repositioning across the value chain.
For Market Incumbents: Harden aftermarket service revenue through power-by-the-hour contract penetration among Great Lakes automotive tier-one suppliers. Deepen backward integration into alloy-steel billet sourcing to offset nickel and molybdenum commodity volatility. Prioritize AS9100 certification investment to capture Quebec aerospace subcontractor demand with full machining traceability requirements. For New Entrants and Emerging Players: Establish a beachhead in Mexican maquiladora precision gearbox refurbishment services, where PROFEPA environmental enforcement is accelerating hydraulic system replacement cycles. Target the Nuevo León automotive corridor with rapid-turnaround ground-tooth reconditioning capabilities. Pursue go-to-market partnerships with Regal Rexnord distributor networks already embedded across the northern Mexico manufacturing belt. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated motor-gearbox platform providers serving NHTSA-compliant EV powertrain applications. Long-term viability favors vendors with captive strain-wave gear intellectual property and established IEEE 1547 wind-farm qualification. Monitor Texas renewable-energy interconnection queue depth as an inflection indicator for pitch-control gearbox demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy-Steel Sourcing | Captive billet supply insulates margin from nickel and molybdenum commodity swings. |
| Power-by-the-Hour Service Contract Expansion | Uptime-guarantee models displace capital purchase patterns among Michigan automotive suppliers. |
| AS9100 Certification Investment | Full machining traceability unlocks Quebec aerospace subcontractor procurement channels. |
| Integrated Motor-Gearbox Platform Development | Closed-loop servo integration reduces commissioning complexity for Ohio CNC builders. |
| Mexican Maquiladora Distribution Network Extension | Monterrey-Saltillo corridor coverage captures automotive and aerospace export demand. |
Methodological Framework
Cross-validation between OEM procurement director interviews and SEC 10-K supply chain disclosures anchors the qualitative findings. Primary fieldwork engaged plant engineers at Michigan and Ohio automotive facilities, aftermarket service heads at Great Lakes distributor networks, and platform engineers at Texas wind-farm developers. Secondary sources incorporated NHTSA fuel-economy compliance filings, EPA Clean Air Act enforcement records, and IEEE 1547 interconnection standards documentation. Bottom-up unit demand modeling triangulated against top-down industrial automation capex forecasts.
Calibration against historical CAGRs in adjacent motion-control sectors refined the projection framework across the analysis window. Segmentation dimensions modeled include gearbox architecture, end-user industry, drive system technology, and application environment. Automotive electrification mandates and robotics density expansion served as primary demand-side inputs, while alloy-steel commodity indices and grinding equipment lead times informed supply-side constraints.
Macroeconomic conditions sit as an overlay; deviation in industrial production indices and renewable-energy tax credit stability would shift the trajectory. Forecasts reflect documented assumptions regarding NHTSA rulemaking continuity and EPA enforcement intensity. Quarterly review of German grinding spindle order backlogs and Texas wind-farm interconnection approvals is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Automotive Transmission Fluid Market
Powertrain
EV Powertrain-in-the-Loop (P-HIL) Test Benches Market
Powertrain
United Kingdom Automotive Engine Oils Market
Powertrain
Global Automotive Torque Converter Market
Powertrain
Diesel Engine Market
Powertrain
Transmission Mounting Brackets Market
Powertrain
Transmission Oil Filters Market
Powertrain
Global Automotive Clutch Market
Powertrain
EGR and Emissions Control Actuator Systems Market
Powertrain
Automotive Crankshaft Market
Powertrain
Global Industrial Turbocharger Market
Powertrain
Automotive Performance Tuning Market
Powertrain
Gear Oil Market
Powertrain
Automotive Turbo-Compounding System Market
Powertrain
Russia Electro Hydraulic Power Steering Market
Powertrain
EV Drivetrain Systems Market