
 Piston Market | 2026-2036
Piston Market Size, Share, and Industry Trends Forecast 2026-2036
Piston Market Outlook
Lightweight aluminum alloy casting is reconfiguring piston architecture across high-performance engine platforms. MAHLE GmbH leverages its captive foundry network to supply thermal-management-optimized pistons for downsized turbocharged engines. AISIN CORPORATION sustains Japanese OEM relationships through precision machining capabilities and just-in-time delivery systems. Tenneco Inc. competes in the aftermarket channel with cost-optimized steel piston solutions for heavy-duty commercial fleets.
A piston is a cylindrical component that reciprocates within a combustion chamber cylinder bore, typically manufactured from aluminum-silicon alloys with graphite or steel inserts to manage thermal expansion coefficients between 18-22 μm/m·K; its primary function converts expanding gas pressure into mechanical work transmitted through a connecting rod. Engine pistons anchor the largest revenue pool given persistent internal combustion engine volumes in emerging markets, while aircraft pistons occupy a premium niche where FAA and EASA certification requirements sustain elevated margin structures. Composite material formulations represent the fastest-growing segment as fiber-reinforced polymers displace conventional cast iron in specialized industrial compressor applications.
EPA Tier 4 and Euro 7 emissions frameworks compel OEMs to redesign piston crown geometries and ring-pack configurations to reduce blow-by and particulate formation. India's BIS certification mandates dimensional tolerances for aftermarket pistons that protect domestic manufacturers from uncertified imports. Stakeholders must monitor how China's dual carbon goals and the EU Green Deal reshape capital allocation between combustion-engine piston R&D and electrification-adjacent thermal management components.
Market Dynamics
Downsized turbocharged engines are forcing wholesale redesign of piston thermal management systems, compressing crown geometries and ring-pack clearances to contain combustion pressures exceeding 250 bar while managing oil consumption and particulate thresholds.
Growth Catalysts
- Euro 7 Emissions Framework:Stringent blow-by limits compel OEMs to adopt multi-piece steel pistons with anodized crown coatings, expanding addressable demand for thermal-barrier technologies across European passenger vehicle platforms.
- India Commercial Vehicle Corridor:BIS-certified aftermarket mandates protect domestic foundries from uncertified Chinese imports, concentrating replacement piston demand in Chennai, Pune, and Jamshedpur manufacturing clusters.
- Aluminum-Silicon Hypereutectic Alloys:Advanced casting techniques permit 26% silicon content with primary silicon particle control, delivering wear resistance for cylinder liners without cast iron sleeves in light-duty diesel architectures.
Market Restraints
- Primary Aluminum Price Volatility:LME aluminum ingot fluctuations above 15% annually compress margin structures for independent foundries lacking long-term smelter contracts or captive scrap recycling.
- China Foundry Concentration:Zhejiang and Shandong provinces control 60% of global aluminum piston casting capacity, creating single-source vulnerability for European and North American Tier 1 suppliers.
- Electrification Substitution:Battery-electric powertrain penetration in premium passenger segments eliminates piston demand entirely, freezing R&D budgets for combustion-engine architectures in German and Japanese OEMs.
Strategic Opportunities
- Indonesia Two-Wheeler Manufacturing:Underpenetrated local foundry capacity creates white space for joint ventures supplying 100-150cc motorcycle pistons to Astra Honda and Yamaha Motor Indonesia operations.
- Industrial Compressor Composites:Fiber-reinforced polymer pistons for oil-free air compression in food and pharmaceutical processing offer margin expansion outside automotive price pressures.
- China Dual Carbon Policy:MIIT fuel-efficiency credits for thermal-management-optimized pistons incentivize domestic OEMs to specify premium aluminum alloys over conventional cast iron in heavy-duty applications.
Industry Challenges
- FAA/EASA Certification Timelines:Aircraft piston approval cycles exceeding 18 months delay aftermarket entry for new alloy formulations, freezing innovation capital in general aviation supplier networks.
- Ring-Pack Integration Complexity: Plasma-coated compression rings require sub-micron cylinder bore honing protocols that legacy engine remanufacturing facilities cannot execute without capital retooling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Piston Market |
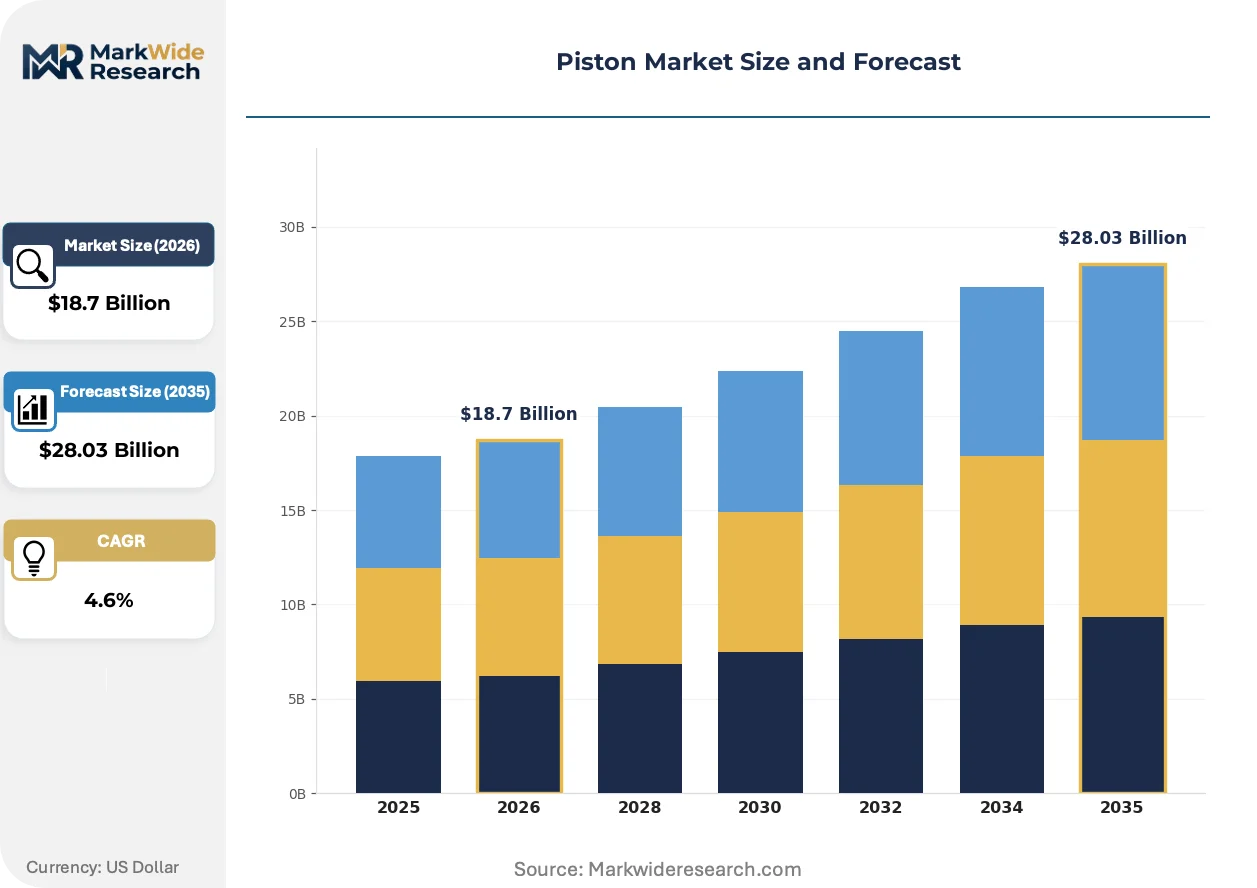
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Pistons, Motorcycle Pistons, Aircraft Pistons, Industrial Pistons Material: Aluminum, Steel, Cast Iron, Composite Application: Automotive, Machinery, Aerospace, Marine Size: Standard, Oversized, Custom, Miniature |
| Companies Covered | MAHLE GmbH, AISIN CORPORATION, Tenneco Inc., Rheinmetall AG, RIKEN CORPORATION, Hitachi Ltd., Shriram Pistons & Rings Ltd., Art Metal MFG Co., Ltd., KS Kolbenschmidt Piston GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Piston Market Strategic Shifts
Additive manufacturing of piston crown features is compressing prototype-to-production cycles while enabling topology-optimized oil galleries impossible with conventional gravity die casting methods.
3D-printed sand cores with conformal cooling channels are rendering obsolete traditional steel-core tooling for complex undercrown geometries in motorsport and limited-production hypercar applications. Porsche Motorsport and Mercedes-AMG have adopted these cores for single-batch piston runs, collapsing lead times from 16 weeks to under 4 weeks while enabling iterative combustion chamber optimization between race weekends.
EPA Tier 4 Final and Euro 7 particulate number limits are mandating diamond-like carbon coatings on piston skirts to reduce friction-induced oil vaporization. MAHLE and Federal-Mogul have qualified hydrogen-free DLC deposition processes that withstand 300°C crown temperatures, with European heavy-duty diesel OEMs now specifying these coatings as standard for 2027 model year engines.
Aftermarket distributors are consolidating procurement through direct foundry relationships, bypassing traditional Tier 1 branded packaging. India's Lumax Industries and Spain's Cobo Group now source unbranded pistons from Chinese foundries for private-label resale, compressing channel margins and forcing incumbent suppliers to unbundle technical support from component pricing in Latin American and Southeast Asian markets.
Piston Market Segmentation
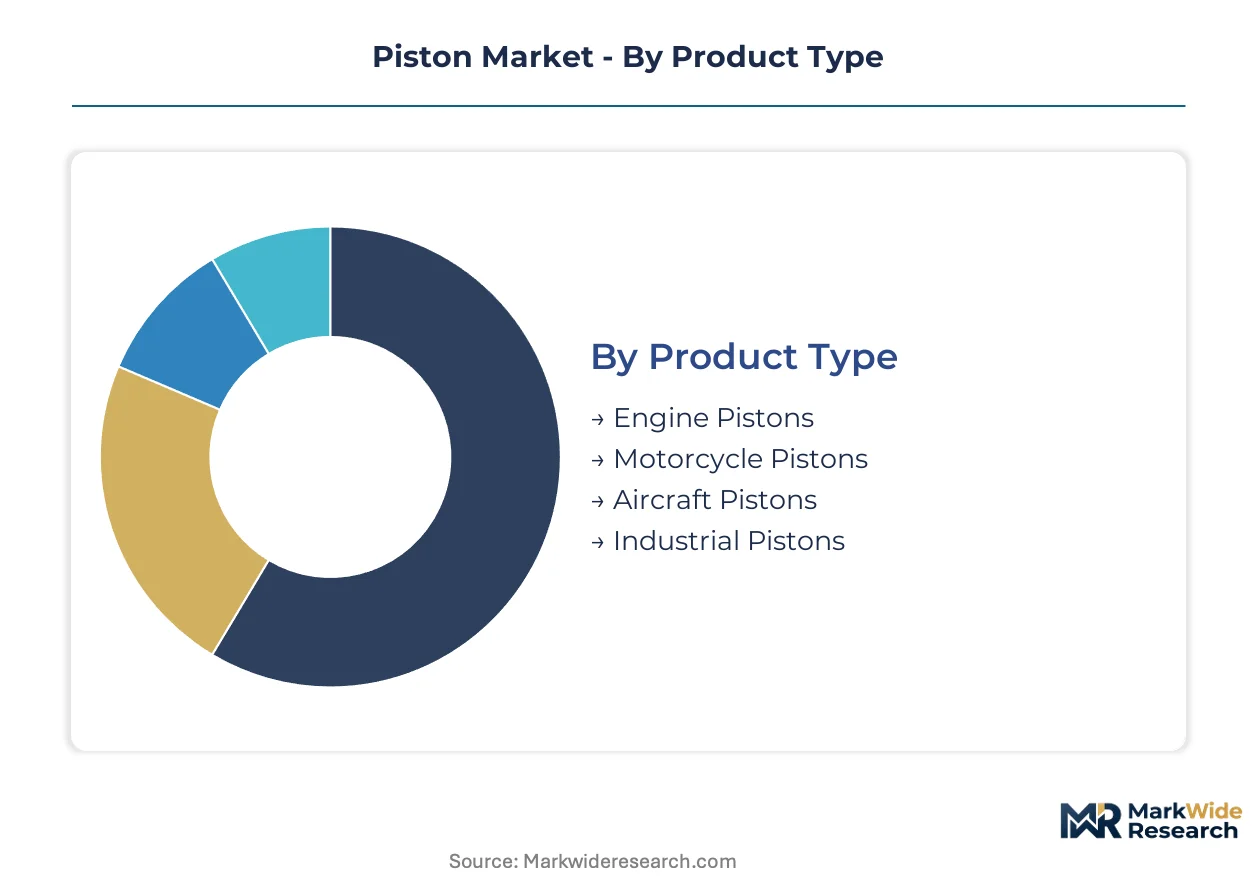
Piston market segmentation reveals divergent technical requirements and margin structures across end-use applications. Aftermarket service intensity varies dramatically by product type and material specification, reshaping supplier economics and distribution channel design.
Product Type:
After-sales service intensity escalates from industrial replacement cycles measured in decades to motorcycle piston rebuilds occurring every 15,000 kilometers in emerging markets.
- Engine Pistons:Aluminum-silicon alloy castings with anodized crown coatings dominate automotive OEM supply chains. Demand clusters in India's Chennai-Pune manufacturing corridor and China's Zhejiang foundry belt as commercial vehicle production scales.
- Motorcycle Pistons:Hypereutectic aluminum formulations with graphite inserts manage thermal expansion in air-cooled two-wheeler engines. Indonesia's Astra Honda and Yamaha Motor Indonesia operations drive volume procurement for 100-150cc displacement segments.
- Aircraft Pistons:Forged aluminum alloys meeting FAA and EASA certification protocols for general aviation powerplants.
- Industrial Pistons:Cast iron and steel configurations for compressor and pump applications with extended service intervals.
By volume, Engine Pistons leads. By growth pace, Motorcycle Pistons is ahead.
Material:
Cost tier differentiation separates premium thermal-management alloys from commodity cast iron in price-sensitive aftermarket channels.
- Aluminum:Primary alloy for automotive and motorcycle platforms with silicon content ranging 12-26% depending on wear resistance requirements. China's MIIT fuel-efficiency credits accelerate specification of advanced aluminum grades in heavy-duty applications.
- Steel:Multi-piece articulated pistons with steel crowns and aluminum skirts withstand combustion pressures exceeding 250 bar in downsized turbocharged diesel architectures. MAHLE GmbH and Federal-Mogul dominate European OEM supply for Euro 7-compliant heavy-duty platforms.
- Cast Iron:Legacy material for industrial compressors and marine auxiliary engines with lower thermal conductivity requirements.
- Composite:Fiber-reinforced polymer formulations displace metal in oil-free air compression for food and pharmaceutical processing equipment.
By installed base, Aluminum dominates. By margin expansion potential, Composite is climbing the fastest.
Application:
Customer type fragmentation splits procurement between OEM specification engineering and aftermarket price competition.
- Automotive:Light-duty passenger vehicles, commercial trucks, and two-wheelers generate recurring aftermarket demand through engine rebuild programs. India's BIS certification mandates protect domestic foundries from uncertified import competition.
- Machinery:Construction equipment, agricultural tractors, and stationary power generation require oversized piston inventories for field repair operations.
- Aerospace:FAA and EASA certification timelines exceeding 18 months constrain supplier entry and sustain elevated pricing for approved piston configurations.
- Marine:Slow-speed two-stroke engines for commercial shipping utilize specialized piston crown designs with thermal barrier coatings.
By revenue concentration, Automotive anchors demand. By certification barrier height, Aerospace sustains the steepest margin structures.
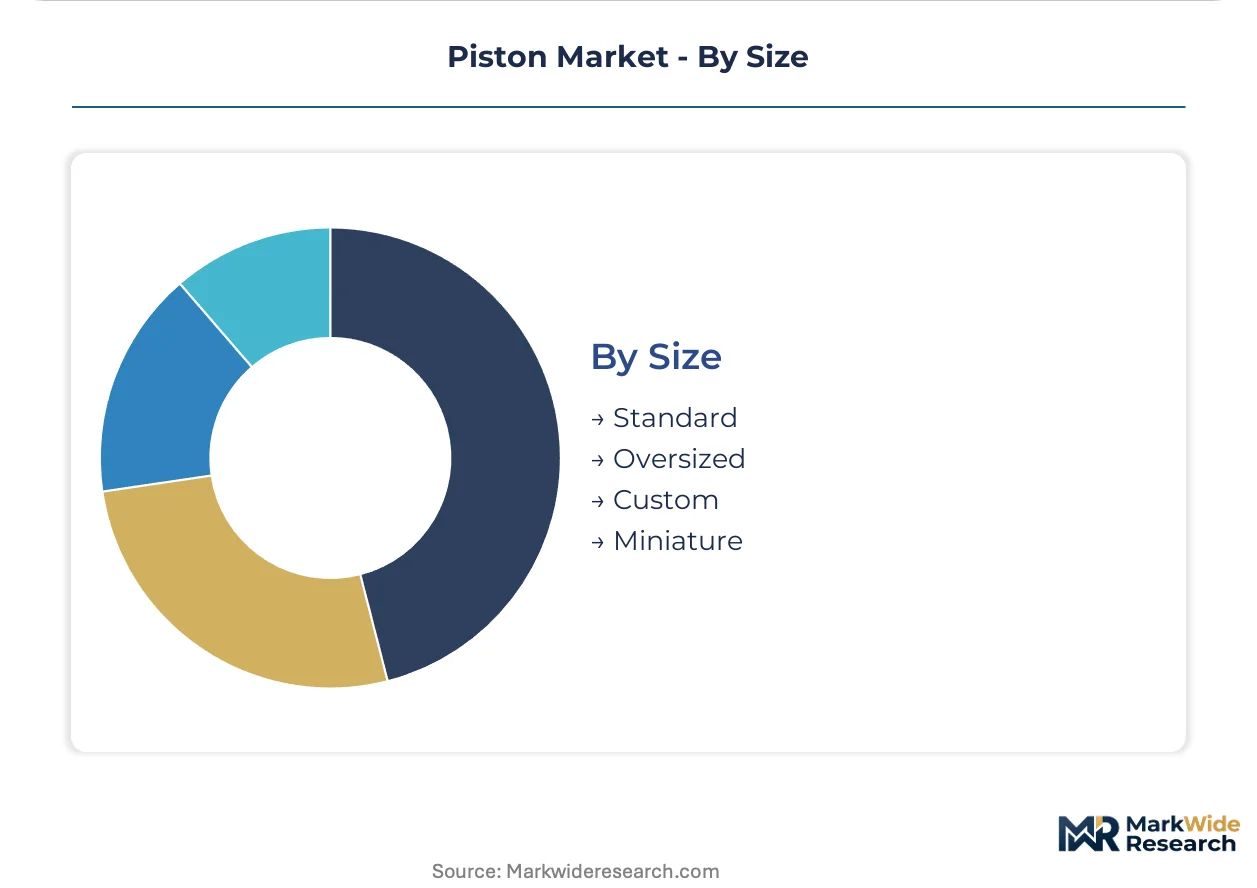
Size:
Supply concentration varies from standardized high-volume automotive bores to custom-machined racing applications with single-batch production economics.
- Standard:Production tolerances of 5-10 microns for OEM assembly line compatibility across high-volume automotive and motorcycle platforms.
- Oversized:Incremental bore diameters for engine remanufacturing facilities addressing cylinder wear in commercial vehicle fleets.
- Custom:Topology-optimized designs from 3D-printed sand cores for motorsport and limited-production hypercar applications.
- Miniature:Precision-machined configurations for model engines, medical compressors, and specialized industrial equipment.
By production volume, Standard sizes dominate. By technological differentiation, Custom specifications are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in piston manufacturing tilt heavily toward Asian foundry output serving European and North American assembly plants. China's surplus casting capacity feeds Tier 1 suppliers in Germany and the United States, while India's protective certification regimes limit inbound substitution.
China
Zhejiang and Shandong provinces host 60 percent of global aluminum piston casting capacity, supplying downsized turbocharged engine programs worldwide. MIIT fuel-efficiency credits for thermal-management-optimized pistons redirect domestic OEM procurement toward premium alloy grades. Wenzhou and Ningbo foundry clusters export unbranded castings to Indian and Southeast Asian aftermarket distributors.
Germany
Stuttgart and Munich anchor European OEM specification engineering for Euro 7-compliant multi-piece steel pistons. KBA type-approval protocols for heavy-duty diesel architectures sustain captive foundry relationships with domestic Tier 1 suppliers. The Neckar-Alb region concentrates precision machining capacity for anodized crown coatings.
India
Chennai, Pune, and Jamshedpur manufacturing corridors concentrate commercial vehicle and two-wheeler piston demand. BIS certification mandates for aftermarket components block uncertified Chinese import competition. The PLI scheme for automotive components incentivizes domestic foundry expansion for 100-150cc motorcycle engine programs.
United States
Detroit-area remanufacturing facilities source oversized piston inventories for heavy-duty fleet rebuild programs. EPA Tier 4 Final emissions frameworks drive specification of diamond-like carbon skirt coatings in 2027 model year engines. Michigan and Ohio machine shops execute sub-micron cylinder bore honing protocols for plasma-coated ring-pack integration.
Indonesia
Karawang and Bekasi industrial zones host Astra Honda and Yamaha Motor Indonesia assembly operations with underpenetrated local foundry supply. The country's two-wheeler production scales toward 100-150cc displacement segments where hypereutectic aluminum formulations dominate. Joint venture opportunities exist for piston casting capacity serving ASEAN export markets.
Piston Market Competitive Environment
On the supply side, the industry is bifurcated between integrated automotive Tier 1 suppliers and independent foundries serving fragmented aftermarket channels. Captive foundry networks at major component groups anchor OEM supply relationships, while regional machine shops compete on remanufacturing turnaround times. Two strategic archetypes dominate: thermal-management technology specialists and cost-optimized volume casters. Capacity expansion and direct foundry-to-distributor procurement relationships constitute the primary competitive moves reshaping channel economics.
Within the integrated Tier 1 tier, MAHLE GmbH and AISIN CORPORATION occupy positions exemplifying divergent geographic anchoring strategies—German engineering-intensive supply versus Japanese just-in-time delivery systems. Tenneco Inc. represents the aftermarket-focused archetype, competing through cost-optimized steel solutions for commercial fleet rebuild programs rather than OEM specification engineering.
| Leading Market Players |
|---|
| MAHLE GmbH |
| AISIN CORPORATION |
| Tenneco Inc. |
| Rheinmetall AG |
| RIKEN CORPORATION |
| Hitachi Ltd. |
| Shriram Pistons & Rings Ltd. |
| Art Metal MFG Co., Ltd. |
| KS Kolbenschmidt Piston GmbH |
| Others |
Value Chain & Pricing Dynamics
The Shanghai-Rotterdam maritime corridor's freight cost volatility feeds directly into European Tier 1 supplier pricing power, amplifying margin compression for independent foundries while enabling integrated manufacturers to extract premiums through captive logistics control. China's Zhejiang foundry concentration creates asymmetric bargaining positions that downstream distributors translate into three-tier pricing structures across premium, standard, and economy certification levels.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that separate FAA-certified aircraft piston grades from uncertified aftermarket castings. Price differentiation rests on silicon content precision and MIIT fuel-efficiency credit eligibility, with Indian BIS certification tiers commanding substantial premiums over unbranded Chinese imports. Cost compression in the motorcycle aftermarket intensifies because direct foundry-to-distributor procurement bypasses traditional Tier 1 markups. Fleet operators in commercial vehicle segments exhibit highest price sensitivity, while aerospace OEMs demonstrate least sensitivity due to 18-month certification lock-in.
Supply Chain Analysis
Primary aluminum ingot draws from Chinese smelter networks, Russian hydroelectric production, and Australian bauxite refining as the foundational feedstock layer. Raw material dependencies center on LME-grade aluminum, hypereutectic silicon additive packages, and diamond-like carbon deposition precursors. Single-source vulnerability concentrates in Zhejiang and Shandong casting clusters, where 60 percent of global capacity creates disruption exposure from regional power rationing or environmental enforcement. Distribution runs through captive Tier 1 logistics for OEM supply, with independent aftermarket channels fragmenting across Indian BIS-certified domestic foundries and direct Chinese export relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The piston market rewards foundries capable of executing sub-micron machining protocols and rapid alloy qualification cycles, creating entry barriers that only thermal-management engineering depth can overcome. Capability scarcity in conformal cooling channel design and plasma-coated ring-pack integration separates viable competitors from commodity casters.
For Market Incumbents: Harden defensive positions by deepening backward integration into primary aluminum recycling and captive silicon sourcing, insulating margin structures from LME volatility. Secure exclusive anodized crown coating capacity in the Neckar-Alb region to lock out European aftermarket competitors. Electrification substitution in German passenger vehicle platforms represents the existential threat requiring accelerated pivot toward industrial compressor composite formulations. For New Entrants and Emerging Players: Pursue joint venture structures in Indonesia's Karawang-Bekasi corridor, where Astra Honda and Yamaha Motor Indonesia operations lack local hypereutectic aluminum foundry supply. Target the 100-150cc motorcycle piston segment with BIS pre-certification strategies enabling eventual Indian market entry. Leverage direct distributor relationships in Southeast Asian aftermarket channels to bypass incumbent Tier 1 branding advantages. For Investors and Strategic Acquirers: Euro 7 emissions compliance deadlines reshape the acquisition landscape toward multi-piece steel piston specialists with qualified thermal-barrier coating processes. Long-term viability over the next decade hinges on portfolio exposure to heavy-duty diesel architectures where downsized turbocharged engine penetration sustains addressable demand. Acquisition targets should demonstrate captive foundry relationships with European OEMs and active FAA certification pipelines. Monitor EPA Tier 4 Final implementation velocity as the critical inflection signal for DLC coating adoption rates and associated supplier margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Foundry Expansion | Backward integration into Zhejiang or Shandong casting capacity secures supply certainty for Euro 7-compliant steel piston programs. |
| Thermal-Barrier Coating Qualification | Anodized crown coating certification with KBA type-approval unlocks premium pricing in German heavy-duty diesel supply chains. |
| Indonesian Joint Venture Formation | Local hypereutectic aluminum capacity serving Astra Honda operations captures ASEAN two-wheeler production growth. |
| DLC Deposition Process Investment | Hydrogen-free diamond-like carbon qualification with EPA Tier 4 Final compliance enables 2027 model year specification. |
| Composite Formulation R&D | Fiber-reinforced polymer development for oil-free industrial compressors diversifies revenue beyond automotive price pressures. |
Study Parameters
Operator-level perspectives from foundry operations managers, Tier 1 supplier procurement directors, aftermarket distributor network heads, and OEM platform engineering leads anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through customs trade databases, MIIT fuel-efficiency credit filings, BIS certification registries, and KBA type-approval documentation. Bottom-up volume triangulation across product type, material grade, and regional production clusters converged with top-down macroeconomic demand modeling.
Scenario-bracketing framed analytical outputs across the projection horizon, with demand elasticity tested against electrification penetration rates and emissions regulatory stringency variations. Segmentation dimensions modeled encompassed product architecture, silicon content tier, application end-use, and OEM-aftermarket channel split. CAGRs derived from regression analysis of historical production volumes against macroeconomic drivers and regulatory compliance timelines. Industry-specific forecast inputs incorporated MIIT credit allocation trajectories and Euro 7 particulate number limit implementation schedules.
Sensitivities concentrate around primary aluminum price volatility, Chinese environmental enforcement intensity, and battery-electric powertrain substitution velocity in premium passenger segments. Forecasts embed assumptions regarding certification timeline stability and foundry capacity expansion execution. Cross-checking against IHS Markit vehicle production databases and ACEA registration statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
2 Wheeler Fuel Injection System Market
Vehicle Components
Injector Deposit-Resistant Fuel Injection Component Platforms Market
Vehicle Components
Tailgate Chip Spreader Market
Vehicle Components
Railway Air Filter Market
Vehicle Components
Wheel Spindle Market
Vehicle Components
Car Sunshade Market
Vehicle Components
Electric Wheelchair Market
Vehicle Components
EGR Valve Market
Vehicle Components
Air Ride Suspension Systems Market
Vehicle Components
Motor Lamination Market
Vehicle Components
Digital Tire Inflator Market
Vehicle Components
Trailer Landing Gear Market
Vehicle Components
Steer-by-Wire Road Wheel Actuator Modules Market
Vehicle Components
High Security Registration Plates Market
Vehicle Components
Motor Monitoring Market
Vehicle Components
LAMEA Vehicle Exhaust Hose Market