
 Electric Wheelchair Market | 2026-2036
Electric Wheelchair Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Wheelchair Market Intelligence
The integration of joystick control systems with advanced sensor fusion and AI-powered obstacle avoidance is reshaping product design and user safety. Permobil AB leverages its expertise in complex rehabilitation technology to serve users with specialized needs. Invacare Corporation competes through its extensive global distribution network and broad product portfolio. Ottobock SE & Co. KGaA differentiates with a focus on high-performance, sports, and pediatric models.
An electric wheelchair is a self-propelled mobility device powered by batteries and an electric motor, typically featuring a power base with drive wheels and a customizable seating system. Its primary purpose is to provide independent mobility for individuals unable to use manual wheelchairs due to physical limitations or health conditions. Heavy-duty and reclining product types cater to users with higher support needs in long-term care facilities and for chronic disease management. Joystick control remains the dominant technology, while voice activation represents a growing segment for users with severe neuromuscular disorders.
Product safety and market access are governed by regulations such as the FDA's medical device classifications in the United States and CE marking requirements under the MDR in Europe. Additionally, ISO 7176 standards provide a global benchmark for wheelchair testing and performance specifications. Manufacturers must navigate complex reimbursement policies and evolving accessibility standards across different healthcare systems to secure market share.
Market Dynamics
The market's central dynamic is the convergence of rising geriatric populations and integrated AI systems. This transforms wheelchairs from mobility aids into connected health devices, driving demand for sophisticated functionality.
Growth Catalysts
- Supportive Reimbursement Policies:Favorable reimbursement codes in healthcare systems like Japan's and Germany's reduce user costs, stimulating demand from long-term care facilities.
- Demographic Aging:The expanding geriatric population in developed nations directly increases the addressable market for powered mobility assistance due to age-related chronic conditions.
- Advanced Sensor Technology:AI-powered obstacle avoidance enhances user safety and independence, broadening appeal to individuals with severe physical or cognitive impairments.
Market Restraints
- High Product Cost:The price of advanced models is a primary barrier in markets with limited insurance coverage, restricting access for many individuals.
- Complex Regulatory Pathways:Navigating disparate regulations like FDA classifications and Europe's MDR creates lengthy and costly approval cycles, delaying market entry.
- Battery Technology Limitations:Constraints on battery life and charging time limit operational range, restraining user convenience and all-day mobility without careful planning.
Strategic Opportunities
- Telehealth Integration:Connecting wheelchairs to telehealth platforms via IoT enables remote diagnostics and maintenance, creating new service-based revenue.
- Emerging Market Penetration:Expanding into Latin America and Southeast Asia offers growth for standard models as their populations age and incomes rise.
- Specialized Pediatric Models:Developing customizable wheelchairs for children is an underserved niche, allowing for product differentiation and focused market entry.
Industry Challenges
- Supply Chain Vulnerability:Reliance on a concentrated supply of electronic components like microcontrollers exposes manufacturers to price volatility and shortages.
- Customization at Scale:Balancing individual user needs with efficient, scalable manufacturing is a primary operational challenge for producers.
- Navigating Global Standards:Compliance with ISO 7176 and country-specific rules requires significant investment in testing and certification infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Wheelchair Market |
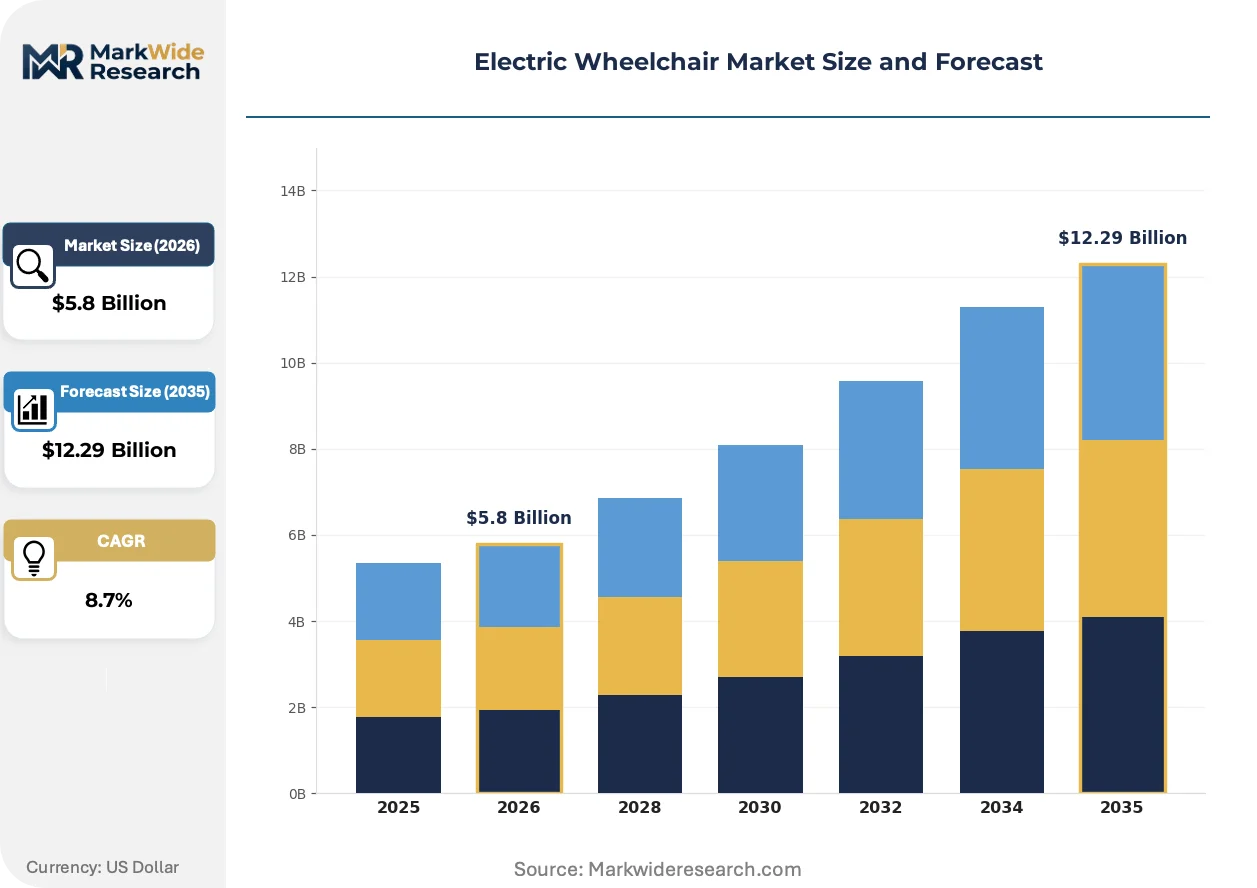
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $12.29 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heavy Duty, Lightweight, Portable, Sports, Pediatric, Reclining Technology: Joystick Control, Sip-and-Puff, Head Control, Touchscreen Interface, Voice Activation, Switch Control End User: Hospices, Rehabilitation Centers, Long-Term Care Facilities, Assisted Living Communities, Veterans Facilities, Home Care Application: Mobility Assistance, Post-Surgical Recovery, Chronic Disease Management, Neuromuscular Disorders, Spinal Cord Injuries, Geriatric Support |
| Companies Covered | Ottobock SE & Co. KGaA, Karman Healthcare, Permobil AB, Hoveround Corporation, Golden Technologies, Sunrise Medical, Invacare Corporation, Iyasocare, Pride Mobility Products Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Wheelchair Market Strategic Shifts & Innovations
Product development is shifting from a focus on mobility alone toward integrated personal health and navigation platforms. This evolution reflects a deeper integration of software, connectivity, and user-centric design, fundamentally changing the device's role in a patient's life.
Sensor fusion technology combines input from cameras, ultrasonic sensors, and gyroscopes for real-time environmental awareness. Adoption is accelerating within the complex rehabilitation segment for users with significant cognitive challenges. This advancement is collapsing the boundary between a user-controlled mobility aid and a semi-autonomous vehicle, enhancing safety and independent navigation in complex environments.
The European Union's Medical Device Regulation (MDR) mandates more stringent clinical evidence and post-market surveillance for medical devices. This directive increases the time and cost of achieving CE marking, a prerequisite for market access. Manufacturers of specialized models face the greatest pressure to generate robust data proving safety and performance to comply with the MDR.
A behavioral shift is underway in institutional procurement, moving from capital purchases to operational models like leasing or subscriptions. This change affects durable medical equipment distributors, who must bundle maintenance services to compete. The trend is most prominent in healthcare systems in the UK and Scandinavia, where facilities prioritize predictable costs and device uptime.
Electric Wheelchair Market Segmentation
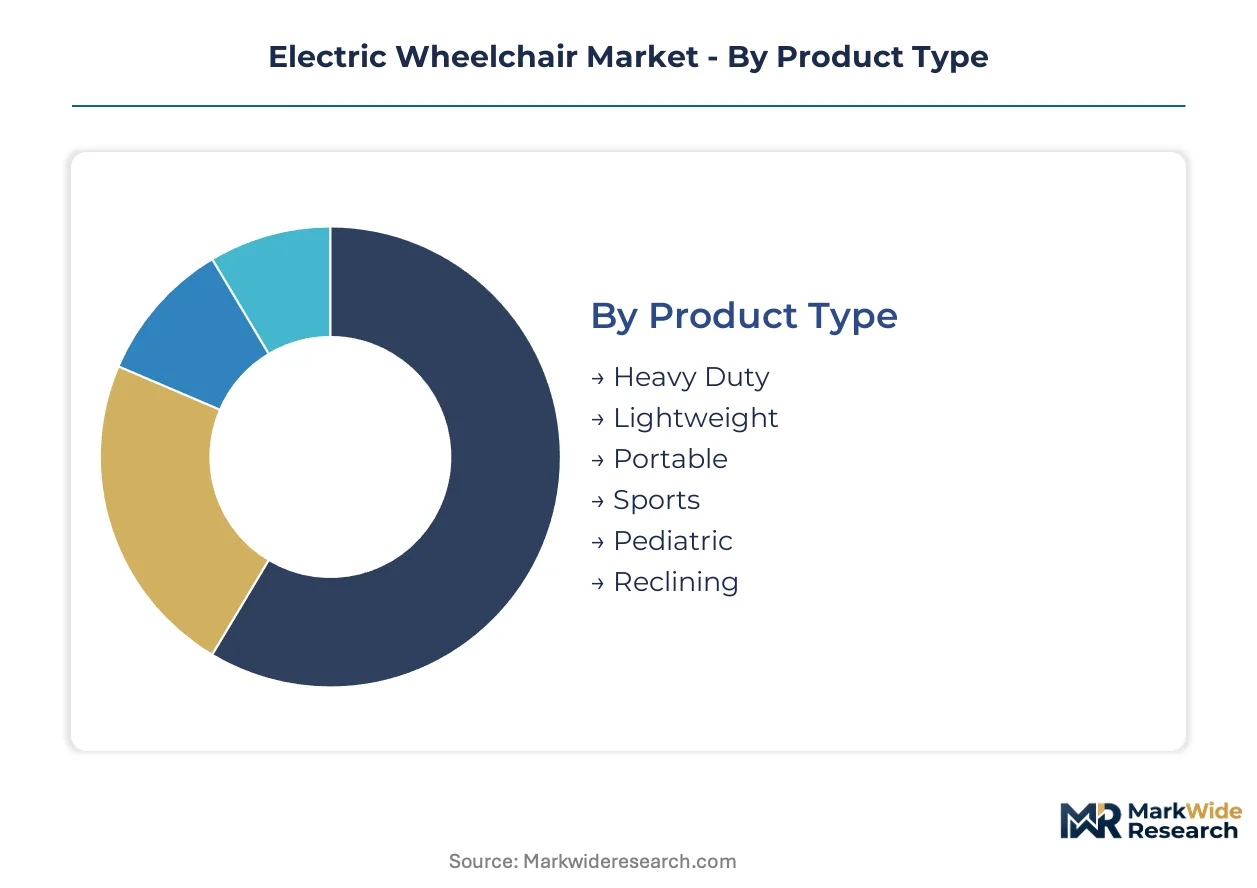
The electric wheelchair market is segmented to reflect the diverse needs of its user base, ranging from specific medical conditions to various environments of use. Understanding these distinct segments allows manufacturers to tailor product development and market strategies effectively.
Product Type:
Product design differentiates electric wheelchairs based on user requirements and mobility needs.
- Heavy Duty:These models feature reinforced frames, higher weight capacities, and robust motors for bariatric users or those requiring extensive support. Demand concentrates in long-term care facilities due to the specific needs of geriatric populations and chronic disease management.
- Reclining:Reclining electric wheelchairs offer adjustable backrests and leg rests, enabling pressure relief and repositioning for users spending extended periods in the device. These are particularly sought after in long-term care settings for users with higher support needs and complex medical conditions.
- Lightweight:These models prioritize ease of transport and maneuverability for active users.
- Portable:Designed for convenient disassembly and transport, portable units serve users requiring mobility solutions during travel.
- Sports:Specialized sports models offer enhanced durability and agility for recreational activities.
- Pediatric:Custom-designed pediatric wheelchairs accommodate the unique growth and postural support requirements of children.
Heavy Duty models hold significant installed capacity. Pediatric models are rotating up the share rankings.
Technology:
Control interfaces define the interaction methods users employ with their electric wheelchairs.
- Joystick Control:This dominant technology utilizes a simple lever for directional and speed adjustments, offering intuitive operation for a broad spectrum of users. Demand for joystick control systems remains high across all end-user segments due to their reliability and widespread familiarity.
- Voice Activation:Voice-activated systems allow users to command their wheelchair through spoken instructions, providing independent mobility for individuals with severe limb impairment or limited manual dexterity. This technology represents a growing segment for users with severe neuromuscular disorders.
- Sip-and-Puff:These systems translate breath patterns into directional commands, serving users with minimal head or limb movement.
- Head Control:Head control interfaces enable navigation through subtle head movements, offering an alternative for users with limited upper body function.
- Touchscreen Interface:Touchscreen interfaces provide a visual and tactile method for controlling wheelchair functions and accessing integrated features.
- Switch Control:Switch control systems use single or multiple switches to operate the wheelchair for users with specific physical limitations.
Joystick Control technology maintains a significant market presence. Voice Activation is gaining share fastest among advanced interfaces.
End User:
The diverse settings where electric wheelchairs are utilized shape product requirements and service models.
- Long-Term Care Facilities:These institutions require durable, often heavy-duty and reclining models, for residents with chronic conditions and geriatric support needs. Strong demand from long-term care facilities is a primary contributor to market expansion, particularly in regions with aging demographics.
- Home Care:Users in home care settings prioritize maneuverability, portability, and ease of use for navigating personal residences and community environments. This segment drives demand for compact and adaptable models that facilitate independent living within private homes.
- Hospices:Hospices utilize electric wheelchairs to enhance comfort and mobility for individuals receiving end-of-life care.
- Rehabilitation Centers:Rehabilitation centers employ these devices for therapy and to facilitate patient recovery and skill development.
- Assisted Living Communities:Assisted living communities provide electric wheelchairs to support residents' independence in daily activities.
- Veterans Facilities:Veterans facilities procure specialized models to meet the unique mobility needs of service members and veterans.
Long-Term Care Facilities represent a foundational demand base. Home Care applications are seeing substantial expansion.
Application:
Specific medical and functional needs dictate the primary applications for electric wheelchair deployment.
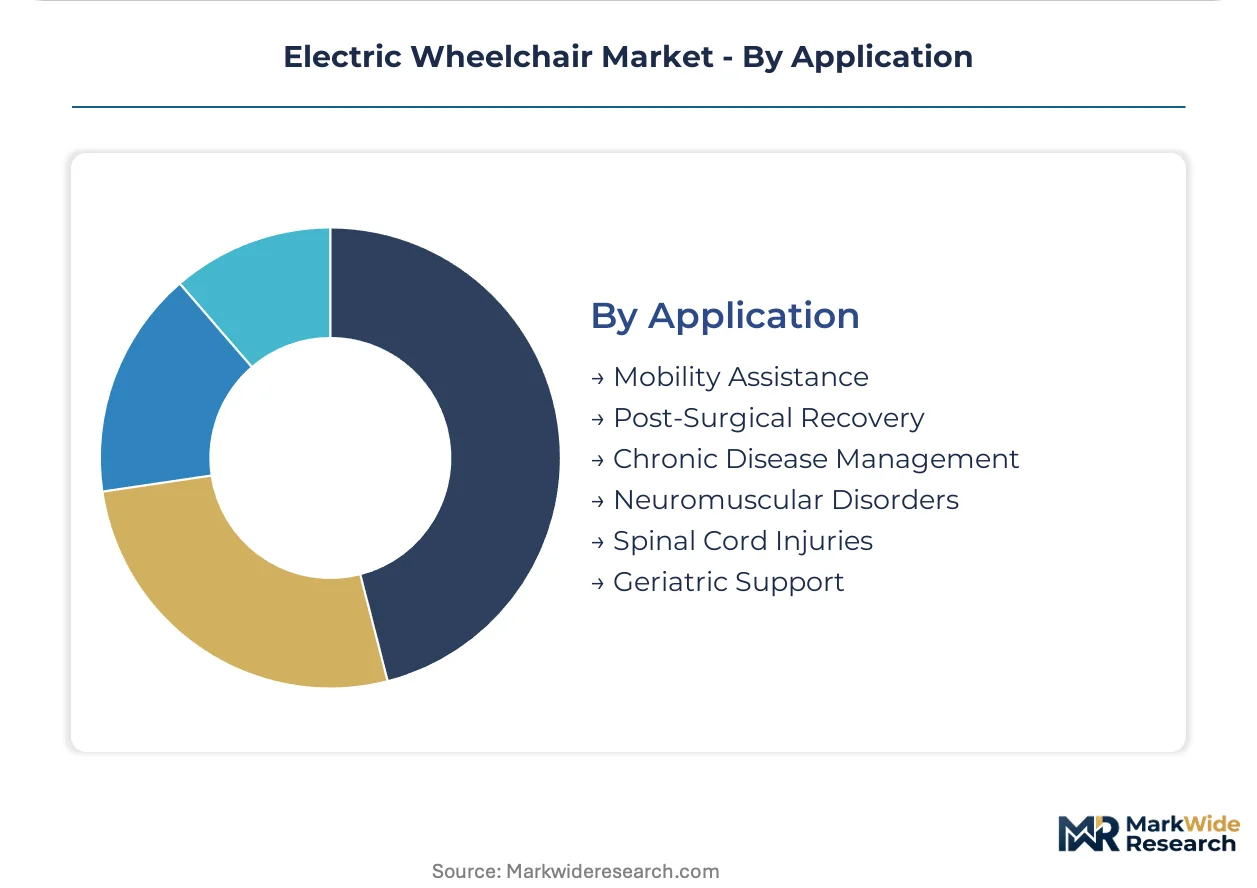
- Geriatric Support:This application addresses mobility challenges faced by the elderly due to age-related conditions, emphasizing ease of use, comfort, and safety features. The expanding geriatric population in developed nations directly increases the addressable market for powered mobility assistance.
- Chronic Disease Management:Electric wheelchairs assist individuals managing long-term health conditions such as multiple sclerosis or cerebral palsy, requiring consistent mobility and postural support. Heavy-duty and reclining product types cater significantly to users within this application due to their higher support needs.
- Mobility Assistance:This broad application covers general independent movement for individuals unable to use manual wheelchairs.
- Post-Surgical Recovery:Electric wheelchairs aid in temporary mobility during recuperation from surgical procedures, facilitating patient comfort.
- Neuromuscular Disorders:This application supports individuals with conditions like muscular dystrophy, often requiring advanced control interfaces.
- Spinal Cord Injuries:Electric wheelchairs provide essential mobility and independence for individuals with varying degrees of spinal cord damage.
Geriatric Support applications form a significant volume segment. Neuromuscular Disorders solutions are experiencing accelerated product innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Long-term care facilities represent a concentrated buyer archetype, driving demand for electric wheelchairs in regions with significant aging populations. These institutions prioritize durable models and specialized features for geriatric support, influencing product development and market penetration strategies across diverse geographies.
Japan
Japan's advanced national healthcare infrastructure and rapidly expanding geriatric population fuel strong demand for electric wheelchairs. The Ministry of Health, Labour and Welfare (MHLW) provides supportive reimbursement policies, reducing out-of-pocket costs for users. Major medical device clusters in Tokyo and Osaka focus on integrating AI-driven navigation systems into mobility solutions.
United States
Geriatric support applications and chronic disease management drive demand for electric wheelchairs in the United States. The Food and Drug Administration (FDA) regulates medical device classifications, ensuring product safety and market access. Medical technology hubs in states like Massachusetts and Minnesota are centers for innovation in advanced sensor fusion and control systems.
Germany
Favorable reimbursement codes and a substantial aging demographic stimulate the market for electric wheelchairs across Germany. CE marking requirements under the Medical Device Regulation (MDR) ensure stringent safety and performance standards for devices sold in the European Union. Southern German regions, including Baden-Württemberg, host specialized manufacturers developing high-performance and pediatric models.
United Kingdom
Institutional procurement in the United Kingdom is shifting towards operational models like leasing, influencing demand from long-term care facilities. Compliance with CE marking requirements is essential for market entry, ensuring devices meet European safety directives. Healthcare innovation centers in London and Cambridge explore telehealth integration for remote diagnostics and maintenance services.
China
China's expanding geriatric population and rising disposable incomes contribute to a growing market for standard and advanced electric wheelchair models. The National Medical Products Administration (NMPA) oversees product approvals and regulatory compliance for medical devices. Manufacturing hubs in the Yangtze River Delta region are increasing production capacity to meet domestic and regional needs.
Electric Wheelchair Market Key Industry Players
Channel-controlling players compete with product-specialist players, creating a tiered market structure. Large, diversified healthcare equipment providers offer broad portfolios, while niche innovators focus on specific user needs or advanced technologies. Competitive moves include geographic expansion into emerging markets and strategic investments in AI-powered navigation systems.
Global manufacturers like Invacare Corporation occupy a position focused on extensive distribution networks and a wide array of products. Permobil AB, a Swedish company, represents specialization in complex rehabilitation technology, catering to users with highly individualized requirements. Germany-based Ottobock SE & Co. KGaA exemplifies differentiation through its emphasis on high-performance, sports, and pediatric electric wheelchair models.
| Leading Market Players |
|---|
| Ottobock SE & Co. KGaA |
| Karman Healthcare |
| Permobil AB |
| Hoveround Corporation |
| Golden Technologies |
| Sunrise Medical |
| Invacare Corporation |
| Iyasocare |
| Pride Mobility Products Corporation |
| Others |
Cost & Logistics Intelligence
Concentration in electronic component manufacturing, particularly microcontrollers, dictates where significant margin pools accumulate within the advanced electric wheelchair segment. This upstream dependency influences pricing power for manufacturers integrating sophisticated AI-driven navigation systems and sensor fusion technologies.
Pricing Analysis
Cost-plus contract patterns, often indexed to material and component costs, frequently govern institutional procurement for electric wheelchairs. Pricing stratifies across premium, standard, and economy tiers, driven by customization levels, specialized features like AI integration, and certification under FDA or CE marking requirements. Pricing pressure stems from high product costs in markets with limited insurance coverage, affecting individual users. Long-term care facilities, prioritizing predictable operational costs, show less price sensitivity for models bundled with maintenance services.
Supply Chain Analysis
Export control regimes targeting advanced electronic components could limit the flow of microcontrollers and specialized sensors essential for high-tech electric wheelchairs. Geographic supply concentrates in China for general manufacturing, with specialized components sourcing from East Asia and Europe. Raw material dependencies include lithium for batteries, rare earth elements for motors, and various plastics for frames. Regulatory restrictions, such as CE marking requirements under the MDR, represent a structural risk, creating costly approval cycles. Distribution runs through extensive global networks for broad portfolios and direct sales channels for complex rehabilitation solutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electric wheelchair market is experiencing a buyer-power shift, evidenced by the move towards operational models like leasing and subscriptions among large institutional purchasers such as long-term care facilities.
For Market Incumbents: Harden core product offerings by integrating advanced AI-driven navigation and sensor fusion technologies, countering the threat of specialized tech entrants. Secure long-term supply agreements for critical electronic components like microcontrollers to mitigate supply chain vulnerabilities. Invest in certification processes for evolving regulatory frameworks, such as Europe's MDR, ensuring broad market access. Expand telehealth integration capabilities to offer remote diagnostics and maintenance, enhancing after-sales service value.
For New Entrants and Emerging Players: Establish a beachhead in underserved niches like specialized pediatric models or high-performance sports wheelchairs, leveraging product differentiation. Target emerging markets in Latin America and Southeast Asia with cost-effective, standard models as populations age and incomes rise. Focus go-to-market strategies on advanced control interfaces such as voice activation, catering to users with severe neuromuscular disorders. Partner with regional distributors who can bundle maintenance services for institutional buyers.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with established manufacturers with strong distribution networks or niche innovators possessing proprietary AI/sensor technology. The long-term viability of this market is anchored by persistent global demographic aging and the ongoing integration of medical devices into connected health ecosystems. Watch for increased reimbursement coverage for advanced features, signaling an inflection point for broader market adoption and profitability in high-tech segments.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Driven Navigation System Development | Enhances user safety and independence, expanding market appeal for advanced models. |
| Telehealth Platform Integration | Creates new service-based revenue and remote diagnostics capabilities for manufacturers. |
| CE Marking Pathway Investment | Ensures market access and compliance with stringent European medical device regulations. |
| Emerging Market Distribution Expansion | Captures growth from aging populations and rising incomes in new geographic regions. |
| Specialized Pediatric Model Launch | Addresses an underserved niche with unique growth and postural support requirements. |
Research Approach
Desk research of regulatory documents, scientific publications, and national health ministry reports preceded structured interviews with clinicians, long-term care facility administrators, medical device engineers, and regulatory affairs specialists. This approach combined primary insights with secondary validation, ensuring a comprehensive understanding of market dynamics. Bottom-up and top-down triangulation methods were applied to reconcile data from diverse sources.
The analytical framework modeled various conditions, holding macroeconomic factors fixed while varying technological adoption and demographic shifts across the analysis window. Segmentation dimensions included product type, technology, end-user, application, and regional healthcare infrastructure. Compound annual growth rates were derived from historical trends, projected demographic changes, and anticipated technological advancements, with geriatric population growth rates and healthcare expenditure trends serving as key forecast inputs.
Stress conditions across regulatory changes, battery technology advancements, and supply chain disruptions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect a specific set of assumptions regarding market evolution and policy stability. Cross-checking against external medical device market benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Automotive Battery Terminals Market
Vehicle Components
Marine Wheel Bearings Market
Vehicle Components
Precision Bearing Market
Vehicle Components
Automotive Wheel Hub Bearing Aftermarket Market
Vehicle Components
Tow Tractor Market
Vehicle Components
4x4 Vehicle Parts and Accessories Market
Vehicle Components
Railway Vehicle Coupler Market
Vehicle Components
Vehicle Cargo Box Market
Vehicle Components
Automotive Composite Suspension Components Market
Vehicle Components
Trailer Surge Brake Market
Vehicle Components
Bicycle Front Hub Market
Vehicle Components
Composite Bearings Market
Vehicle Components
Global Automotive Composite Liftgate Market
Vehicle Components
Engine Mounting Brackets Market
Vehicle Components
Global Car Accessories Market
Vehicle Components
Two Wheeler Footrest Market