
 Passenger Air Brake Market | 2026-2036
Passenger Air Brake Market Size, Share, and Industry Trends Forecast 2026-2036
Passenger Air Brake Market Insights
Aftermarket providers is collapsing as a buyer archetype as rail operators and OEMs consolidate procurement under long-term service agreements. Knorr-Bremse leverages its vertical integration across compressor units and electronic control modules to anchor European high-speed contracts. Wabtec Corporation sustains manufacturing scale across North American passenger corridors. Nabtesco Automotive Corporation dominates pneumatic system supply for Japanese Shinkansen operators.
Passenger air brakes are pneumatic or electropneumatic braking systems that use compressed air to transmit force through brake shoes, valves, and control units, typically operating at pressures between 8 and 10 bar to achieve controlled deceleration of rail vehicles. These systems serve the critical function of ensuring safe, reliable stopping performance across varying load conditions and speeds in passenger transport. Brake valves and electronic control units represent the fastest-expanding product segments as operators replace mechanical relay systems with computer-controlled brake management. Pneumatic systems remain the volume backbone but hybrid solutions combining pneumatic actuation with electronic monitoring are capturing margin pools in premium fleet segments.
FDA and FRA safety mandates in the United States enforce rigorous testing protocols for brake system failure modes, while REACH and the EU F-Gas Regulation restrict fluorinated compounds in air dryer desiccants and compressor lubricants. India's CEA and BIS standards for rolling stock equipment are raising certification barriers for imported brake assemblies. Stakeholders must weigh backward integration into electronic control manufacturing against partnering with established semiconductor suppliers as software-defined braking architectures advance.
Market Dynamics
Rail operators are consolidating brake system procurement under long-term service agreements, collapsing the aftermarket buyer archetype and forcing component suppliers to reposition as integrated service partners rather than discrete hardware vendors.
Growth Catalysts
- High-speed fleet modernization:European and Asian rail operators are replacing mechanical relay brake systems with computer-controlled architectures across expanding intercity corridors.
- REACH and F-Gas Regulation:European chemical restrictions on fluorinated compounds in air dryer desiccants are accelerating material substitution programs and qualifying new supplier ecosystems.
- Metro buildouts:India's urban rail expansion under CEA and BIS certification frameworks is generating concentrated demand for pneumatic and electropneumatic brake assemblies.
Market Restraints
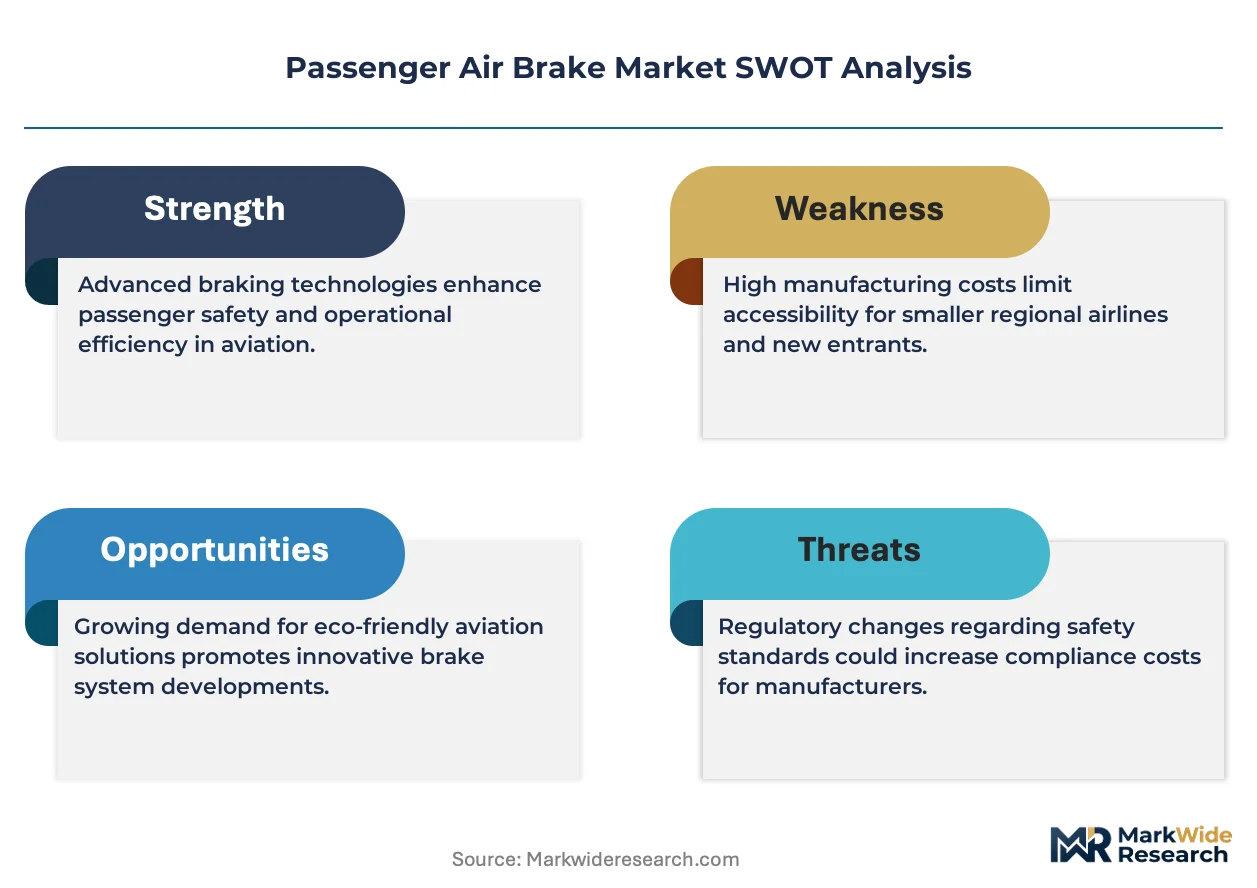
- Semiconductor supply concentration:Electronic control unit production depends on captive chip supply from a narrow base of foundry operators, exposing brake system OEMs to allocation volatility.
- Specialized alloy input costs:High-performance brake shoe formulations require nickel and rare earth elements subject to export restriction regimes in supplier countries.
- Legacy system interoperability:Mechanical-pneumatic brake architectures in existing rolling stock resist seamless integration with digital control overlays, fragmenting upgrade paths.
Strategic Opportunities
- Software-defined braking architectures:Convergence of electropneumatic actuation with edge computing and sensor fusion creates margin pools in premium fleet segments.
- Hybrid system penetration:China's intercity network expansion offers white space for brake solutions combining pneumatic reliability with electronic monitoring.
- Service contract bundling:Long-term availability agreements covering compressors, valves, and control modules displace spot procurement in operator maintenance programs.
Industry Challenges
- Embedded systems engineering talent:Brake control firmware development requires scarce expertise in safety-critical real-time operating systems and SIL certification protocols.
- Multi-jurisdiction homologation:Simultaneous compliance with FRA failure-mode testing, REACH material restrictions, and BIS rolling stock standards extends product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Passenger Air Brake Market |
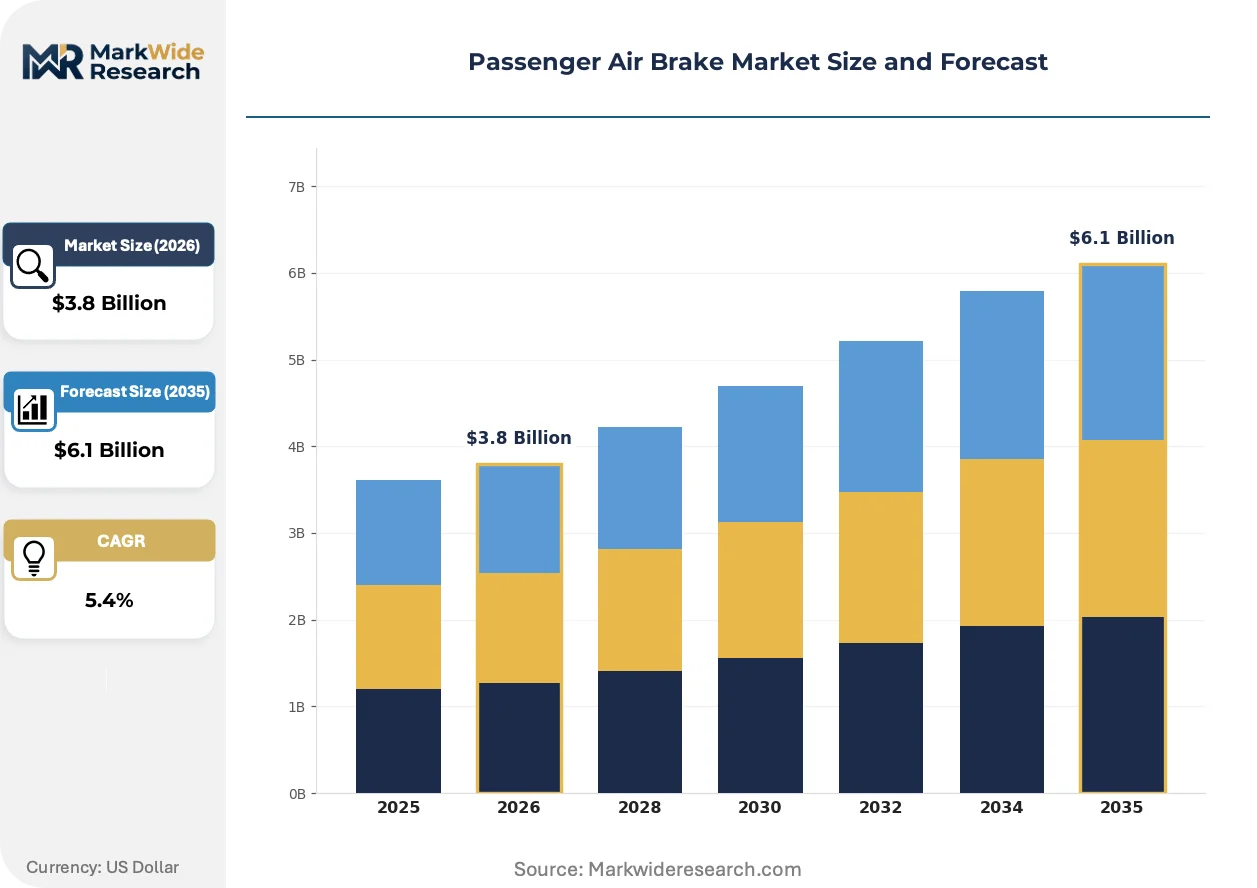
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.1 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Brake Shoes, Brake Valves, Compressor Units, Air Dryers End User: Rail Operators, OEMs, Aftermarket Providers, Maintenance Facilities Installation Type: Retrofitting, New Installations, Upgrades, Modular Systems Technology: Pneumatic Systems, Electronic Control Units, Hybrid Solutions, Mechanical Systems |
| Companies Covered | Knorr-Bremse, ZF Friedrichshafen, Wabtec Corporation, Meritor, Haldex, Nabtesco Automotive Corporation, TSE Brakes, Sorl Auto Parts, UNO Minda, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Passenger Air Brake Market Trends and Innovations
Brake system architecture is migrating from pneumatic-mechanical to electropneumatic-digital, compressing supplier margins on commodity valves while expanding value capture for control electronics and predictive maintenance software.
Electropneumatic brake control is displacing conventional pneumatic relay systems in high-speed passenger fleets. Japanese Shinkansen operators and European intercity rail providers are retrofitting computer-controlled brake management units to achieve precise deceleration curves. This shift is displacing mechanical valve manufacturers from specification-setting roles and transferring system integration authority to semiconductor-enabled control specialists.
F-Gas Regulation in Europe restricts hydrofluorocarbon compounds in air dryer desiccants and compressor lubricants, forcing reformulation of sealing materials and filtration media. Brake system suppliers are qualifying alternative chemistries to maintain CE marking eligibility. Compressor unit manufacturers face the steepest compliance burden, as lubricant compatibility testing extends development cycles by 12-18 months.
Service unbundling is compressing the traditional aftermarket channel for brake components. Rail operators in North America and Western Europe are negotiating direct long-term agreements with valve and control module producers, bypassing distributor intermediaries. This pattern is most visible in commuter rail segments where maintenance outsourcing concentrates buying power with fleet management contractors.
Passenger Air Brake Market Segmentation
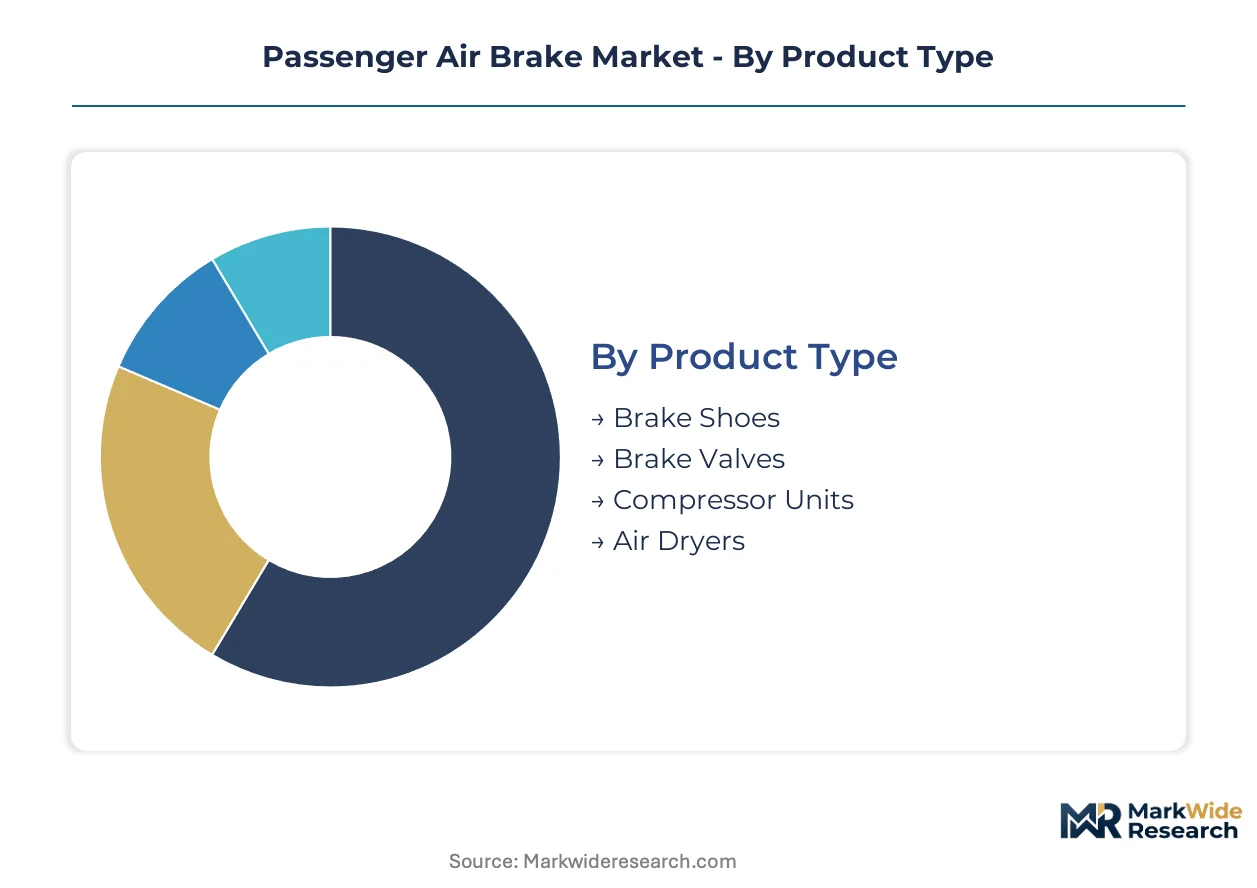
Segmentation in passenger air brake systems reveals how technology transitions and procurement consolidation reshape competitive boundaries across hardware categories and customer channels. Understanding these divides exposes where supplier margins concentrate and where substitution threats from electronic architectures erode traditional pneumatic revenue pools.
Product Type:
Brake valves and electronic control units face the most acute substitution pressure as mechanical relay systems lose specification authority to computer-controlled architectures across high-speed corridors.
- Brake Valves:Electropneumatic valve assemblies modulate air pressure distribution across brake cylinders with millisecond response times. Demand concentrates in European intercity fleet retrofits where operators replace pneumatic relay systems to achieve precise deceleration curves under ECHA REACH material compliance.
- Compressor Units:Air generation systems operating at 8-10 bar supply the pneumatic backbone for braking force transmission. Procurement clusters in China's expanding intercity network where fleet scale rewards suppliers qualifying alternative lubricant formulations under tightening fluorinated compound restrictions.
- Brake Shoes:Friction material formulations containing nickel and rare earth elements provide wear-resistant braking surfaces.
- Air Dryers:Desiccant-based moisture removal systems protect downstream pneumatic components from corrosion.
Brake valves anchor the volume base while electronic control units gain share at the steepest rate.
End User:
Cost tier stratification separates integrated service partners from discrete hardware vendors as procurement authority migrates toward long-term availability agreements.
- Rail Operators:Fleet owners in India and China negotiate direct compressor and valve supply contracts bypassing distributor intermediaries. CEA and BIS certification requirements for rolling stock equipment raise barriers for imported brake assemblies, favoring domestic-qualified suppliers.
- OEMs:Rolling stock manufacturers bundle brake systems into original equipment specifications for new high-speed train deliveries. Japanese Shinkansen builders specify pneumatic-electronic hybrid architectures from vertically integrated subsystem specialists.
- Aftermarket Providers:Independent distributors face collapsing specification authority as maintenance outsourcing concentrates buying power.
- Maintenance Facilities:Third-party repair shops perform component replacement under operator-directed service contracts.
Rail operators command the largest procurement volume while OEMs capture the most favorable margin terms through specification control.
Installation Type:
Application timing determines technology adoption constraints—retrofit programs grapple with legacy interoperability while new installations embed software-defined architectures from inception.
- New Installations:Greenfield rolling stock deployments incorporate electropneumatic control as baseline specification. China's intercity expansion offers white space for hybrid solutions combining pneumatic reliability with electronic monitoring.
- Upgrades:Mid-life fleet modernization replaces mechanical brake management with computer-controlled units. European operators pursue these conversions to satisfy F-Gas Regulation compliance timelines for air dryer desiccants.
- Retrofitting:Legacy mechanical-pneumatic architectures resist seamless integration with digital overlays, fragmenting upgrade paths.
- Modular Systems:Standardized brake subassemblies enable rapid field replacement and reduce maintenance downtime.
New installations dominate absolute volume while upgrades expand most quickly as regulatory deadlines accelerate fleet refresh cycles.
Technology:
Supply concentration in semiconductor foundries exposes electronic control production to allocation volatility, constraining how fast electropneumatic systems can displace pneumatic volume.
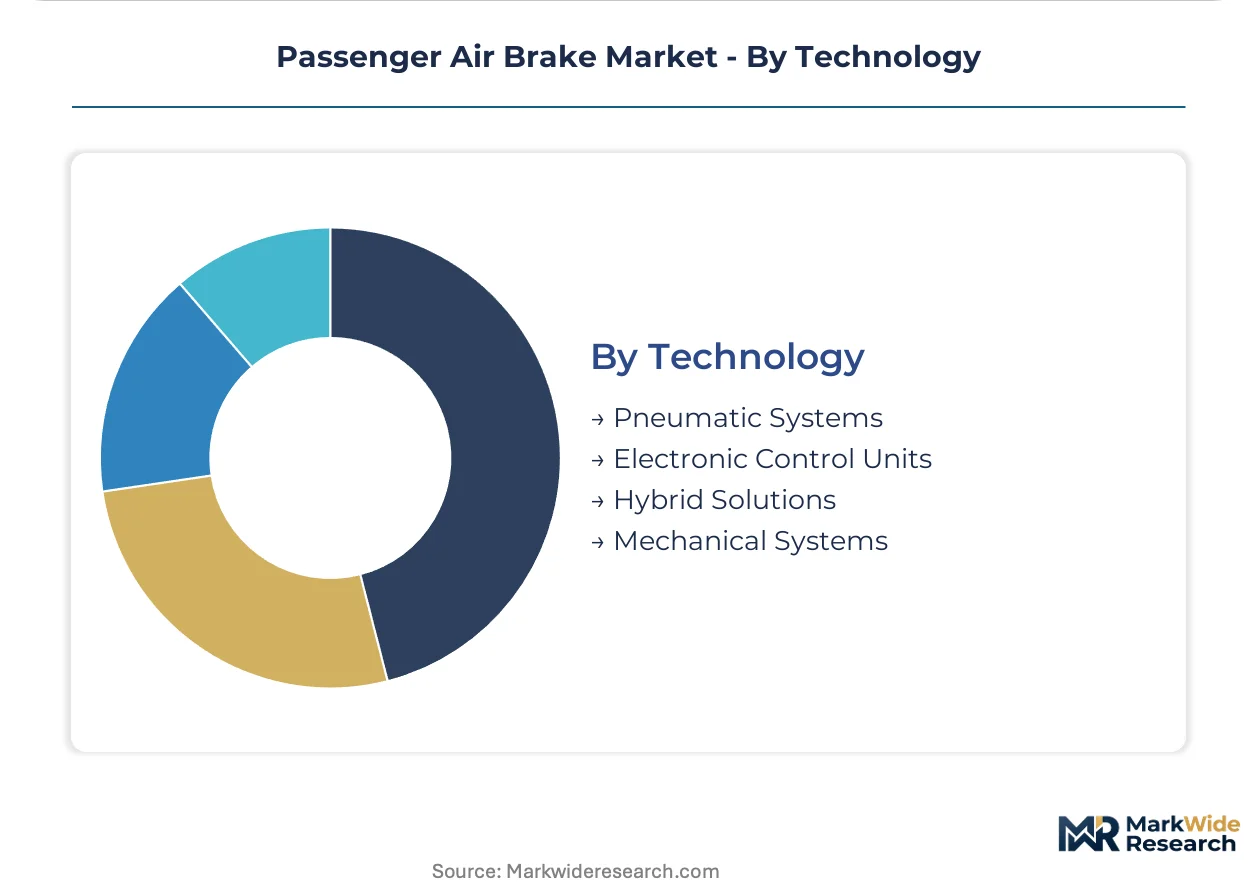
- Electronic Control Units:Computer-based brake management systems process sensor inputs to modulate deceleration curves with precision unavailable to mechanical architectures. Development requires scarce firmware engineering talent in safety-critical real-time operating systems and SIL certification protocols.
- Hybrid Solutions:Architectures combining pneumatic actuation with electronic monitoring capture margin pools in premium fleet segments. These configurations satisfy operators demanding reliability redundancy alongside predictive maintenance capability.
- Pneumatic Systems:Conventional compressed-air braking remains the volume backbone across established rail corridors.
- Mechanical Systems:Relay-based architectures persist in older rolling stock with limited upgrade economics.
Pneumatic systems retain the installed base while hybrid solutions climb the fastest as operators balance reliability requirements with digital service demands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Beijing-Shanghai high-speed rail corridor anchors China's intercity passenger network expansion. India's Dedicated Freight Corridors and metro buildouts in Mumbai, Delhi, and Bangalore concentrate brake system procurement. Germany's Stuttgart-Mannheim corridor and France's LGV Sud-Est exemplify European fleet modernization intensity.
China
China's intercity rail expansion under the 14th Five-Year Plan drives compressor and valve demand across 40,000 kilometers of operational track. The Ministry of Transport enforces GB standards for rolling stock brake performance that exceed legacy pneumatic specifications. Manufacturing clusters in Changchun and Qingdao host joint ventures qualifying alternative lubricant formulations under tightening fluorinated compound restrictions.
India
Metro construction in Delhi-NCR, Mumbai, Bangalore, and Hyderabad generates concentrated demand for electropneumatic brake assemblies. CEA and BIS certification requirements for rolling stock equipment raise barriers for imported brake systems, favoring domestic-qualified suppliers. Industrial corridors in Gujarat and Tamil Nadu host fabrication facilities serving state rail procurement tenders.
Germany
The Stuttgart-Mannheim high-speed corridor retrofit program replaces mechanical relay systems with computer-controlled brake management. ECHA REACH compliance and the EU F-Gas Regulation restrict hydrofluorocarbon compounds in air dryer desiccants, forcing material substitution programs. Manufacturing concentration in Bavaria and Baden-Württemberg supplies brake valves for Deutsche Bahn's ICE fleet modernization.
United States
Northeast Corridor Amtrak operations and California high-speed rail planning sustain demand for electronic control units. FRA safety mandates enforce rigorous failure-mode testing protocols that extend product qualification timelines. Manufacturing activity in Pennsylvania and Illinois serves commuter rail operators consolidating procurement under long-term service agreements.
Japan
Shinkansen network expansion on the Hokkaido and Kyushu lines drives specification of hybrid pneumatic-electronic architectures. METI industrial standards govern brake system interoperability across JR East, JR Central, and JR West procurement. Manufacturing concentration in Aichi Prefecture and the Kansai region supplies precision valve assemblies for 320 km/h operations.
Passenger Air Brake Market Competitive Landscape
Concentration sits with vertically integrated subsystem specialists and diversified automotive-originated industrial conglomerates. Three archetypes define competitive positioning: European brake system pure-plays with captive compressor and control module production, North American rail-industrial conglomerates with manufacturing scale across passenger corridors, and Japanese precision component specialists serving Shinkansen operators. Dominant competitive moves include backward integration into electronic control manufacturing and geographic expansion through qualification under multi-jurisdiction homologation frameworks.
Within the European pure-play tier, Knorr-Bremse GmbH exemplifies vertical integration across pneumatic and electronic brake architectures. Wabtec Corporation anchors North American manufacturing scale for commuter and intercity rail corridors. Nabtesco Automotive Corporation occupies a specialist position serving Japanese high-speed operators with precision pneumatic system supply. These three companies represent distinct geographic anchoring strategies rather than overlapping competitive terrain.
| Leading Market Players |
|---|
| Knorr-Bremse |
| ZF Friedrichshafen |
| Wabtec Corporation |
| Meritor |
| Haldex |
| Nabtesco Automotive Corporation |
| TSE Brakes |
| Sorl Auto Parts |
| UNO Minda |
| Others |
Pricing and Supply Chain Analysis
REACH and the EU F-Gas Regulation gate both supplier qualification and price differentiation simultaneously, forcing brake system OEMs to absorb 12-18 month lubricant reformulation cycles while tiering offerings around CE marking tiers and service bundling depth. This regulatory architecture compresses margins on commodity pneumatic components while expanding premium capture for electronically controlled architectures that embed compliance costs into specification authority.
Pricing Analysis
Volume-discount tiering structures separate rail operator direct procurement from distributor-mediated spot purchases, with three-tier pricing stratification across premium electropneumatic systems, standard pneumatic assemblies, and economy mechanical replacements. Price differentiation rests on SIL certification grade and long-term availability contract duration, with pressure intensifying as Chinese and Indian domestic suppliers qualify under local BIS and GB standards. Tier 1 rail operators in Europe and Japan exhibit lowest price sensitivity due to total-cost-of-ownership procurement models, while maintenance contractors in emerging corridors drive aggressive negotiation on standardized valve replacements.
Supply Chain Analysis
Strategic stockpiling of nickel and rare earth elements for brake shoe formulations supersedes just-in-time preferences given export restriction exposure from supplier countries, while semiconductor inventory for electronic control units runs on allocation-dependent 26-40 week lead times. Manufacturing concentrates in Germany, China, and Japan for precision valve machining and compressor assembly, with raw material dependencies spanning Chilean copper, Australian nickel, and Chinese rare earth processing. Single-source vulnerability in automotive-grade chip foundries poses the dominant structural risk, as distribution runs through OEM-integrated subsystem suppliers rather than independent aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The passenger air brake market enters a cyclical recovery phase as high-speed fleet modernization programs accelerate replacement demand following pandemic-deferred capital expenditure. Rail operator procurement consolidation under long-term service agreements compresses traditional aftermarket margins while rewarding integrated subsystem specialists.
For Market Incumbents: Fortify specification-setting authority by backward integration into safety-critical firmware development and captive semiconductor sourcing partnerships. Defend against emerging Chinese domestic suppliers qualifying under GB standards by anchoring European contracts through REACH-compliant material substitution programs and compressor unit refurbishment service bundling.
For New Entrants and Emerging Players: BIS certification fast-track for India's metro buildouts offers the most penetrable entry corridor, with CEA rolling stock standards creating qualification barriers that favor early-mover investment in Tamil Nadu and Gujarat fabrication partnerships. Target white space in hybrid pneumatic-electronic architectures for China's intercity expansion, leveraging joint venture structures with state-owned rolling stock manufacturers to bypass import substitution policies.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underperforming rail brake divisions lacking electronic control capabilities. Long-term viability favors suppliers with software-defined braking architectures and predictive maintenance platforms over pure-play pneumatic component manufacturers. Watch semiconductor allocation normalization as the inflection signal for electropneumatic system margin expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Electronic Control Manufacturing | Captures margin pools migrating from pneumatic valves to semiconductor-enabled brake management systems. |
| REACH-Compliant Material Substitution Program | Secures CE marking eligibility for compressor lubricants and air dryer desiccants under F-Gas Regulation timelines. |
| Long-Term Service Agreement with Rail Operators | Displaces spot procurement and locks in recurring revenue across valve, compressor, and control module replacement cycles. |
| Joint Venture with Chinese Rolling Stock Manufacturers | Qualifies alternative lubricant formulations under GB standards while accessing 40,000 kilometer intercity network expansion. |
| Safety-Critical Firmware Development Investment | Addresses scarce SIL certification expertise while transferring system integration authority from mechanical to electronic architectures. |
Research Methodology
Desk research of customs trade databases, rolling stock procurement tender records, and regulator filing repositories preceded structured interviews with brake system procurement directors at European and Asian rail operators, compressor unit plant managers in Germany and China, and electronic control firmware engineering leads. Primary fieldwork with maintenance facility contractors and OEM specification engineers validated secondary findings on technology transition timelines and certification barrier heights. Bottom-up unit demand modeling triangulated against top-down market value estimates from disclosed contract values and subsystem pricing benchmarks.
Variance decomposition across product type, technology architecture, installation timing, and end-user procurement channel anchored the analytical framework throughout the projection horizon. CAGRs derived from segment-level growth rate reconciliation against macro rail infrastructure investment forecasts and fleet replacement cycle analysis. Industry-specific inputs incorporated F-Gas Regulation compliance deadline phasing, BIS certification queue lengths, and semiconductor foundry allocation visibility for electronic control unit production scaling.
Decision-makers should treat outputs as directional under assumptions of sustained rail infrastructure investment, stable rare earth element supply flows, and gradual semiconductor capacity normalization; material deviation would warrant model refresh. Revision becomes warranted when semiconductor allocation constraints for automotive-grade chips cross thresholds that stall electropneumatic system deployment timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Cylindrical Roller Bearings Market
Vehicle Components
Intake-Air Temperature Sensor Market
Vehicle Components
Rail Components Market
Vehicle Components
Rail Wheel Market
Vehicle Components
Automotive Aftermarket Shock Absorbers Market
Vehicle Components
Bicycle Lights Market
Vehicle Components
Air Suspension Market
Vehicle Components
Refrigerated Trailer Door Lock Market
Vehicle Components
Car Diffuser Market
Vehicle Components
Crash Lock Box Market
Vehicle Components
Airport Ground Support Vehicle Market
Vehicle Components
EV Connectors Market
Vehicle Components
Electric Wheelchair Market
Vehicle Components
Exhaust Manifolds and Downpipes Market
Vehicle Components
Car Sunshade Market
Vehicle Components
Off-Highway Diesel Engine Market