
 Japan Automotive Pneumatic Actuators Market | 2026-2036
Japan Automotive Pneumatic Actuators Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Automotive Pneumatic Actuators Market Foresight
Aftermarket service revenue is fragmenting across Japan's automotive pneumatic actuator value chain as original equipment margins compress. SMC Corporation leverages its domestic manufacturing footprint to sustain replacement part availability nationwide. CKD Corporation anchors its position through specialized valve-integrated actuator designs for compact vehicle platforms. Nabtesco Corporation differentiates via precision rotary mechanisms serving robotics-adjacent automotive applications.
Japan automotive pneumatic actuators are electromechanical devices converting compressed air into linear or rotational mechanical motion, typically operating at pressures between 0.1 and 1.0 MPa to control engine intake, exhaust, braking, and transmission systems in vehicle assemblies. Linear actuators dominate OEM procurement for throttle and valve control functions, while gripper actuator demand accelerates from automated assembly line retrofits in Toyota City and Yokohama manufacturing clusters. Rotary actuator configurations retain mature, stable volumes across legacy powertrain architectures where electric conversion remains cost-prohibitive for Tier-1 suppliers.
METI enforces JIS B 8377 pneumatic equipment standards that mandate fatigue testing and leak-rate thresholds, directly shaping product certification requirements for domestic suppliers. Japan's Ministry of Land, Infrastructure, Transport and Tourism (MLIT) imposes vehicle type approval protocols that incorporate actuator reliability into whole-system safety assessments. PMDA-aligned material traceability expectations for imported sealing compounds further complicate supply qualification timelines. Stakeholders must weigh domestic content thresholds against offshore component sourcing as carbon accounting rules harden across keiretsu supply networks.
Market Dynamics
METI's tightening energy efficiency mandates are forcing Tier-1 suppliers to redesign pneumatic actuator architectures across Aichi Prefecture's manufacturing corridor, compressing product lifecycles and fragmenting aftermarket service revenue streams.
Growth Catalysts
- JIS B 8377 fatigue testing mandates:Certification requirements for leak-rate thresholds are accelerating replacement schedules among commercial vehicle fleet operators seeking compliance certainty.
- Automated assembly line retrofits:Gripper actuator demand from Toyota City and Yokohama manufacturing clusters is expanding as robotics integration penetrates legacy powertrain facilities.
- Carbon accounting rules:Keiretsu supply networks are hardening domestic content thresholds, redirecting procurement toward localized pneumatic component sourcing.
Market Restraints
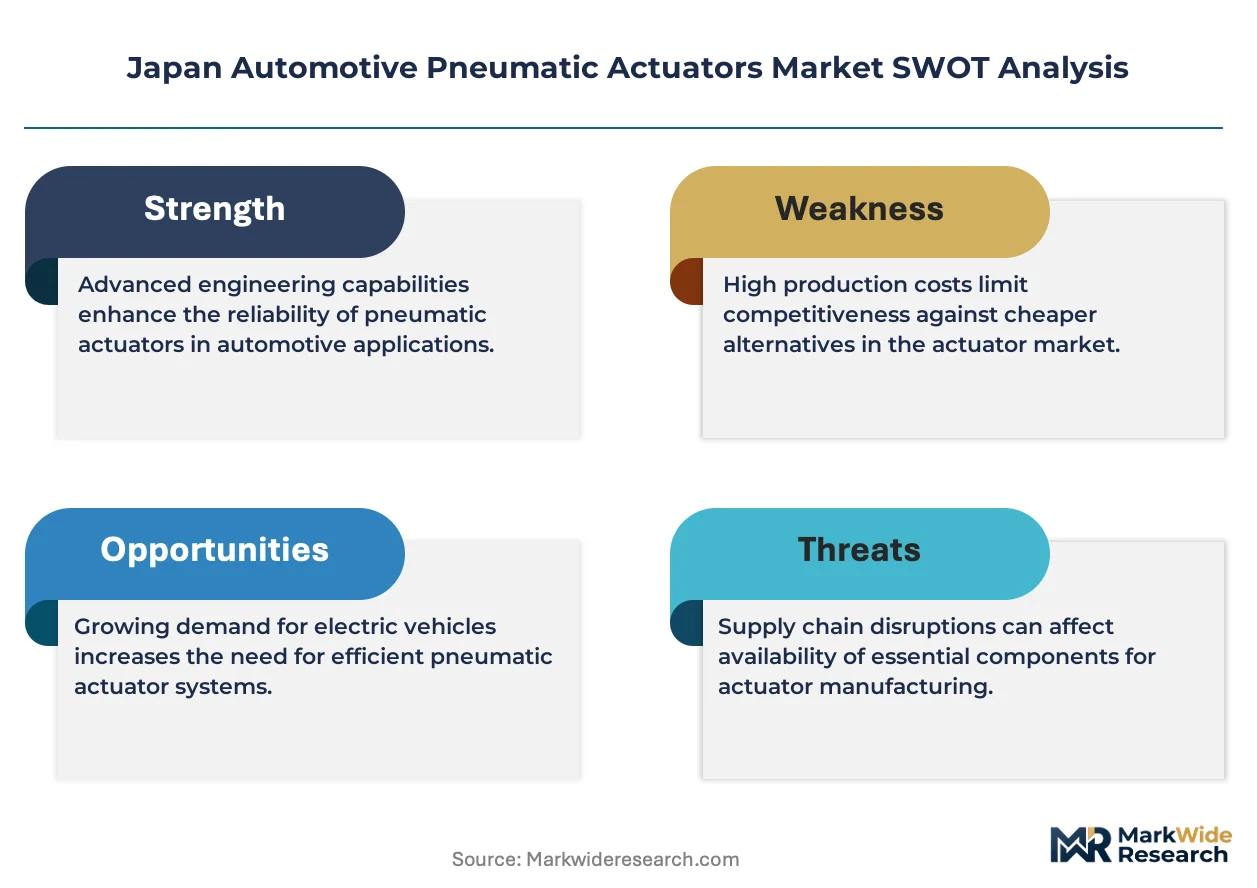
- Sealing compound import delays:PMDA-aligned material traceability expectations extend supply qualification timelines for fluoropolymer seal suppliers by 4-6 months.
- Electric actuator substitution:Battery-electric vehicle powertrains are eliminating pneumatic throttle control functions in new platform designs.
- Specialized valve-integrated designs:CKD Corporation's compact vehicle patents create licensing friction for standardized actuator architectures.
Strategic Opportunities
- Rotary mechanism precision gaps:Robotics-adjacent automotive applications in Nagoya industrial zones remain underserved by legacy linear actuator suppliers.
- Replacement part availability networks:SMC Corporation's domestic manufacturing footprint enables same-day fulfillment models that offshore competitors cannot replicate.
- MLIT vehicle type approval protocols:Whole-system safety assessments create certification barriers that favor established Japanese suppliers with testing infrastructure.
Industry Challenges
- Pneumatic-electronic control integration:Hybrid actuator systems require mechatronics expertise scarce among traditional compressed-air engineering teams.
- Legacy powertrain service continuity:Maintenance of 0.1-1.0 MPa operating pressure specifications across multi-decade vehicle fleets strains technical documentation systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Automotive Pneumatic Actuators Market |
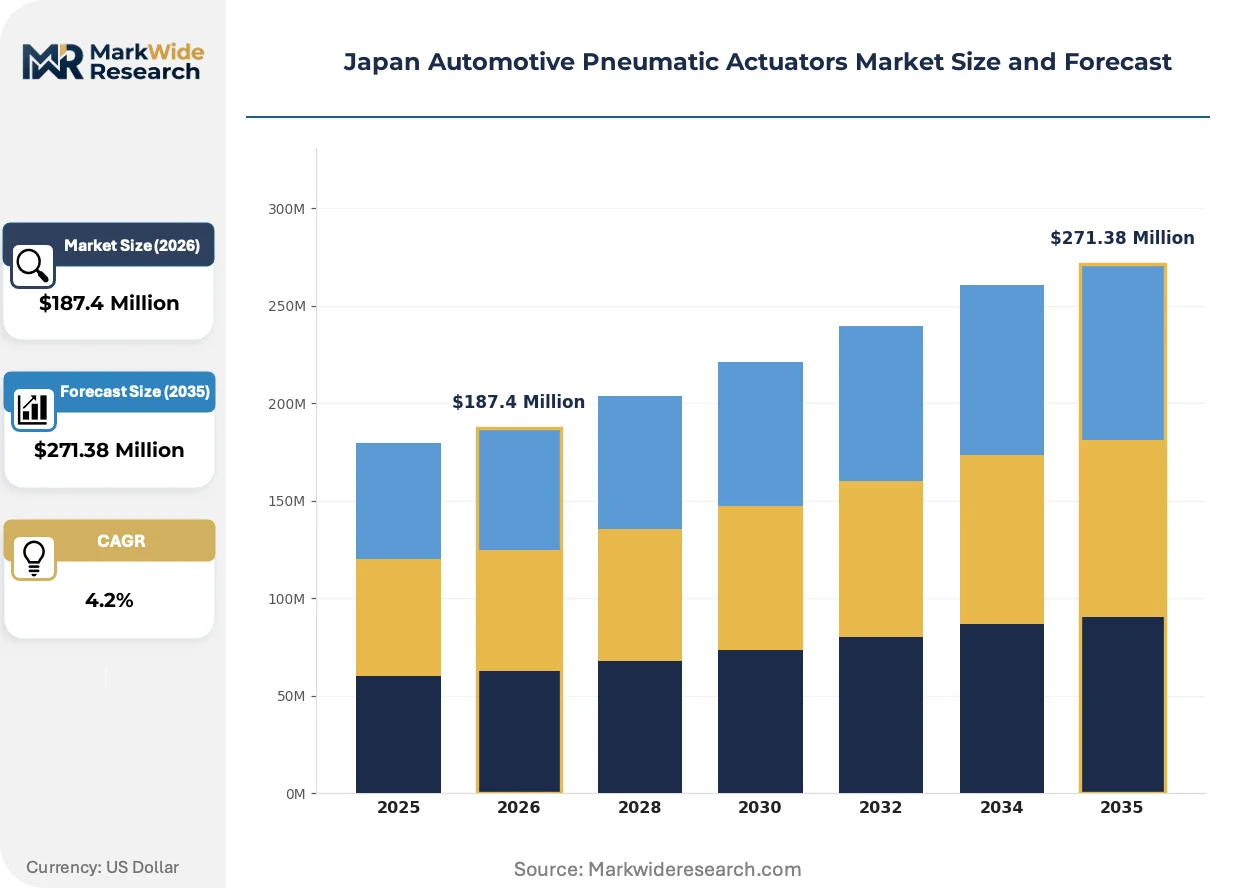
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $271.38 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Linear Actuators, Rotary Actuators, Gripper Actuators, Miniature Actuators Installation Type: Inline Installation, Direct Mount, Remote Mount, Modular Installation End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Control Technology: Pneumatic Control, Electric Control, Hydraulic Control, Manual Control |
| Companies Covered | SMC Corporation, CKD Corporation, NOK Corporation, Nabtesco Corporation, Toyota Industries Corporation, Denso Corporation, Nidec Corporation, Festo Corporation, Yokohama Rubber Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Automotive Pneumatic Actuators Market Shifts & Advancements
Digital twin technology is virtualizing actuator performance validation, compressing prototype-to-production cycles while METI carbon accounting rules restructure supplier qualification protocols across domestic manufacturing networks.
Sensor-integrated pneumatic actuators are virtualizing real-time pressure monitoring and predictive maintenance functions. Tier-1 suppliers in Aichi Prefecture are adopting these architectures for engine intake and exhaust control systems. This convergence is virtualizing traditional scheduled replacement models into condition-based service contracts.
METI's 2024 energy efficiency enforcement protocols mandate documented fatigue testing for all pneumatic equipment deployed in commercial vehicle applications. The regulation is forcing redesign of legacy rotary actuator configurations that cannot meet revised leak-rate thresholds. Domestic suppliers are responding by consolidating certification testing within captive Aichi Prefecture laboratories.
Fleet operators are unbundling actuator replacement from bundled maintenance agreements, creating direct procurement relationships with component manufacturers. This disintermediation is fragmenting traditional keiretsu supply hierarchies in the commercial vehicle segment. The shift is most visible among Tokyo-based logistics operators managing multi-brand vehicle portfolios.
Japan Automotive Pneumatic Actuators Market Segmentation
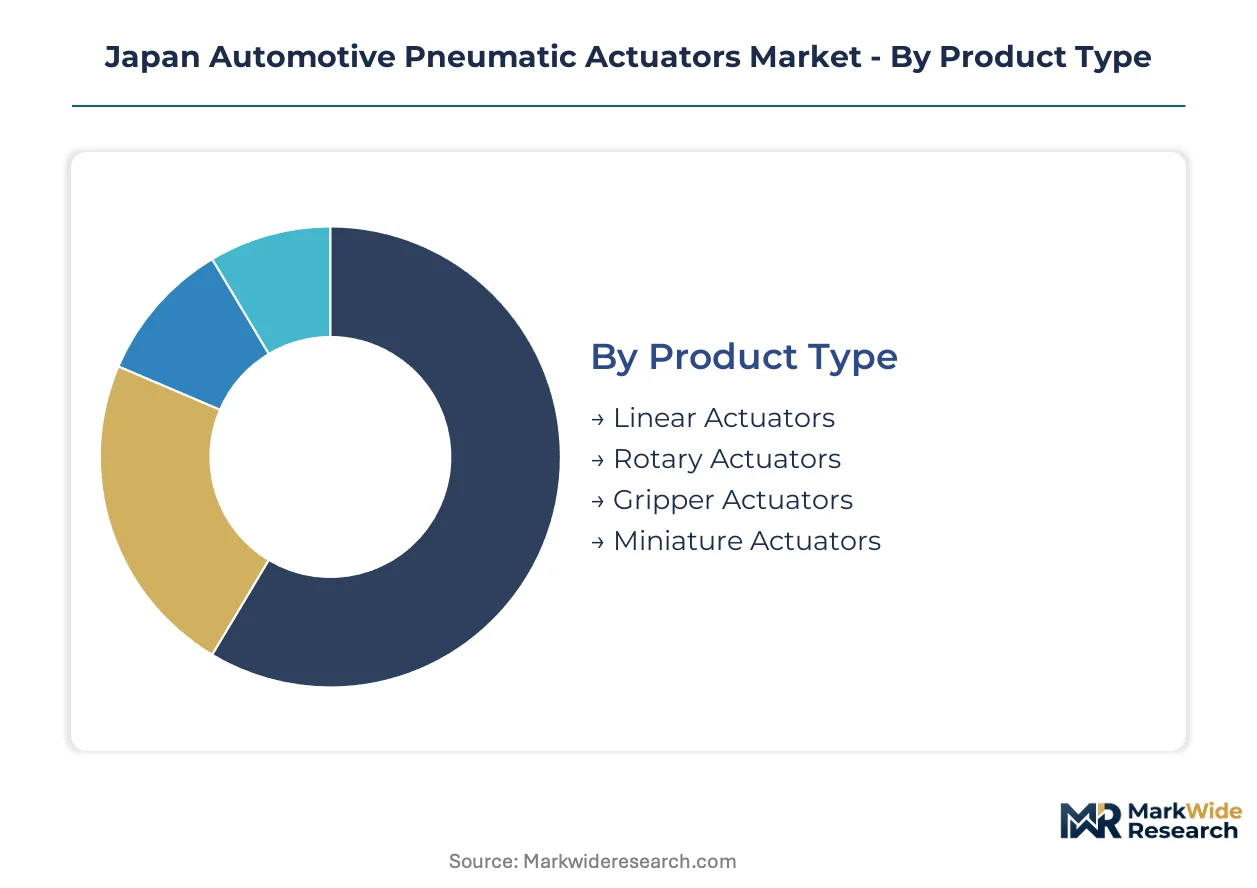
Segmentation reveals how METI certification requirements and keiretsu procurement patterns reshape demand across actuator configurations. Each dimension exposes distinct pressure points where JIS B 8377 compliance costs concentrate.
Product Type:
Use-case spectrum spans legacy powertrain maintenance through robotics-integrated assembly automation, with each configuration carrying distinct certification burdens.
- Linear Actuators:Cylindrical or rod-style mechanisms converting compressed air into straight-line motion, typically deployed for throttle and valve control. OEM procurement in Aichi Prefecture dominates volume as Tier-1 suppliers redesign architectures to meet tightened leak-rate thresholds. METI fatigue testing mandates compress product lifecycles and accelerate replacement schedules among commercial vehicle fleets.
- Rotary Actuators:Vane or rack-and-pinion designs generating angular displacement for transmission and exhaust flap applications. Legacy powertrain architectures in Nagoya industrial zones sustain mature volumes where electric conversion remains cost-prohibitive for established suppliers. Precision mechanism demand from robotics-adjacent automotive applications is expanding fastest.
- Gripper Actuators:Clamping mechanisms for automated material handling in assembly environments.
- Miniature Actuators:Sub-50mm bore devices for compact vehicle platforms and space-constrained engine bays.
The dominant share belongs to Linear Actuators, while Rotary Actuators are closing the gap fastest through precision mechanism specialization.
Installation Type:
Cost tier differentiation separates field-serviceable configurations from integrated factory installations requiring specialized tooling.
- Inline Installation:Series-connected actuators within pneumatic circuits, common in braking and transmission control systems. Toyota City manufacturing clusters favor these for standardized maintenance protocols across multi-model assembly lines. Replacement part availability networks prioritize inline configurations for same-day fulfillment.
- Direct Mount:Actuator-body integration with valve or throttle hardware, eliminating tubing runs. Compact vehicle platforms in Yokohama facilities specify direct mount to reduce leak points and satisfy JIS B 8377 certification. Design patents from established suppliers create licensing friction for standardized architectures.
- Remote Mount:Actuator placement distant from control points via extended pneumatic lines.
- Modular Installation:Interchangeable sub-assemblies enabling field reconfiguration.
Direct Mount captures the premium tier on integration complexity, yet Inline Installation expands most quickly through aftermarket service fragmentation.
End User:
Customer type determines procurement authority and certification documentation requirements.
- OEMs:Original equipment manufacturers specifying actuators for new vehicle platforms. Aichi Prefecture's supplier corridor concentrates design authority as METI energy efficiency mandates force architectural redesigns. Carbon accounting rules harden domestic content thresholds and redirect procurement toward localized sourcing.
- Aftermarket Providers:Independent distributors and service networks managing replacement cycles. Fleet operators unbundle actuator procurement from bundled maintenance agreements, fragmenting traditional keiretsu hierarchies. Direct manufacturer relationships are emerging among Tokyo-based logistics operators.
- Tier-1 Suppliers:Component integrators serving multiple OEM accounts.
- Vehicle Assemblers:Final assembly facilities managing line-fit pneumatic systems.
OEMs retain specification control, though Aftermarket Providers are gaining procurement autonomy fastest through fleet operator disintermediation.
Control Technology:
Technology maturity curves separate electromechanical convergence from legacy pneumatic dominance.
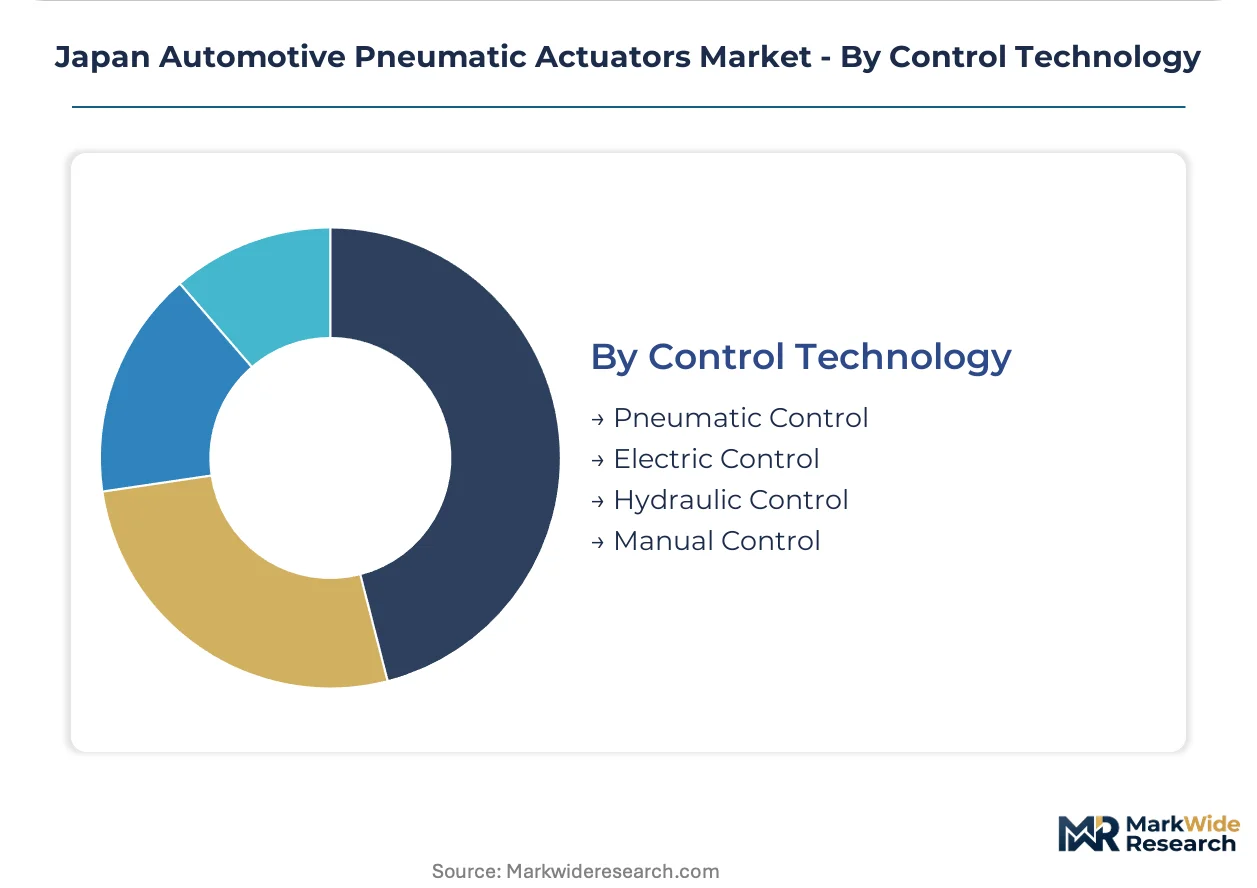
- Pneumatic Control:Pure compressed-air actuation without electronic feedback, dominant in legacy braking and transmission systems. MLIT vehicle type approval protocols incorporate actuator reliability into whole-system safety assessments, favoring established Japanese suppliers with captive testing infrastructure. Maintenance of 0.1-1.0 MPa operating specifications strains technical documentation across multi-decade vehicle fleets.
- Electric Control:Servo-motor or solenoid-driven alternatives eliminating compressed air. Battery-electric vehicle powertrains are eliminating pneumatic throttle functions in new platform designs, displacing volumes in next-generation architectures. Hybrid actuator systems require mechatronics expertise scarce among traditional compressed-air engineering teams.
- Hydraulic Control:Fluid-power alternatives for high-force applications.
- Manual Control:Direct mechanical linkage for emergency override functions.
Pneumatic Control maintains installed-base dominance, while Electric Control climbs fastest on powertrain electrification mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's automotive pneumatic actuator supply base clusters heavily within Aichi Prefecture's industrial corridor, where Tier-1 suppliers maintain captive testing laboratories and just-in-time fulfillment networks. METI's JIS B 8377 certification requirements and carbon accounting protocols are hardening domestic content thresholds across keiretsu supply networks. Regional demand patterns diverge sharply between legacy powertrain maintenance in Nagoya industrial zones and robotics-integrated assembly automation in Yokohama manufacturing clusters.
Kanto/Tokyo
Tokyo-based logistics operators managing multi-brand commercial vehicle fleets are unbundling actuator procurement from bundled maintenance agreements. MLIT vehicle type approval protocols incorporate actuator reliability into whole-system safety assessments, favoring established suppliers with captive testing infrastructure. Fleet operators in the capital region are creating direct manufacturer relationships that fragment traditional keiretsu hierarchies.
Chubu/Nagoya
Aichi Prefecture's supplier corridor concentrates design authority as METI energy efficiency mandates force architectural redesigns of pneumatic actuator systems. JIS B 8377 fatigue testing mandates accelerate replacement schedules among commercial vehicle fleet operators seeking compliance certainty. Toyota City manufacturing clusters favor inline installation configurations for standardized maintenance protocols across multi-model assembly lines.
Kansai/Osaka
Osaka industrial zones sustain mature demand for legacy rotary actuator configurations where electric conversion remains cost-prohibitive for established suppliers. PMDA-aligned material traceability expectations extend supply qualification timelines for fluoropolymer seal suppliers by 4-6 months. Precision mechanism demand from robotics-adjacent automotive applications is expanding fastest in this region.
Kyushu
Fukuoka-based automotive assemblers specify direct mount actuator-body integration to reduce leak points and satisfy JIS B 8377 certification requirements. Design patents from established suppliers create licensing friction for standardized architectures in compact vehicle platforms. Regional procurement is redirecting toward localized pneumatic component sourcing as carbon accounting rules harden.
Japan Automotive Pneumatic Actuators Market Competitive Landscape
Domestic manufacturing specialists and diversified industrial conglomerates split the market between captive keiretsu supply relationships and independent aftermarket service networks. The vendor base concentrates around three strategic archetypes: integrated pneumatic component manufacturers with nationwide fulfillment capabilities, precision mechanism specialists serving robotics-adjacent applications, and diversified automotive suppliers leveraging powertrain integration expertise. Competitive positioning hinges on backward integration into seal manufacturing and upstream control over fatigue testing infrastructure.
Within the integrated component tier, SMC Corporation and CKD Corporation exemplify contrasting strategic positions. SMC Corporation anchors the domestic manufacturing footprint archetype through same-day fulfillment models that offshore competitors cannot replicate. CKD Corporation occupies the specialized design position, with patent-protected valve-integrated configurations creating licensing friction for standardized architectures. Nabtesco Corporation represents the precision mechanism specialist archetype, differentiating via rotary actuator expertise serving robotics-adjacent automotive applications in Nagoya industrial zones.
| Leading Market Players |
|---|
| SMC Corporation |
| CKD Corporation |
| NOK Corporation |
| Nabtesco Corporation |
| Toyota Industries Corporation |
| Denso Corporation |
| Nidec Corporation |
| Festo Corporation |
| Yokohama Rubber Co., Ltd. |
| Others |
Supply & Pricing Matrix
Undercapacity in Aichi Prefecture's captive testing laboratories is driving supplier prioritization toward certified fleet operators while compressing margins for non-compliant architectures. METI's JIS B 8377 enforcement is redrawing procurement hierarchies as carbon accounting rules harden domestic content thresholds across keiretsu networks.
Pricing Analysis
METI's JIS B 8377 certification mandates dictate the pricing tier structure across Japan's automotive pneumatic actuator market. Three-tier pricing stratifies across premium certified, standard compliant, and economy non-certified levels based on fatigue testing documentation and leak-rate performance. Cost compression in the economy tier is intensifying as electric actuator substitution eliminates pneumatic functions from new battery-electric platforms. Aftermarket fleet operators exhibit highest price sensitivity due to unbundled procurement relationships, while OEMs absorb premium tier costs to secure MLIT type approval certainty.
Supply Chain Analysis
Extended payment terms from Tier-1 suppliers to fluoropolymer seal vendors are straining working capital across Aichi Prefecture's manufacturing corridor. Domestic production draws from Japanese steel forging, Chinese rare-earth magnet feedstock, and German precision bearing imports. Single-source vulnerability concentrates around PMDA-aligned sealing compound qualification timelines that extend supplier onboarding by multiple months. Distribution runs through captive keiretsu fulfillment networks with same-day replacement part availability concentrated in Toyota City and Yokohama clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's automotive pneumatic actuator market is approaching a platform-economics inflection as sensor-integrated architectures virtualize traditional scheduled maintenance into condition-based service contracts. Interoperability between pneumatic and electronic control systems is fragmenting legacy supplier hierarchies.
For Market Incumbents: Entrench certification testing infrastructure within Aichi Prefecture laboratories to defend against emerging precision mechanism specialists. SMC Corporation's same-day fulfillment model demonstrates how backward integration into seal manufacturing creates switching costs for fleet operators. Prioritize sensor-integrated actuator R&D to capture condition-based service contract revenue before electric substitution accelerates. For New Entrants and Emerging Players: Pursue robotics-adjacent rotary actuator applications in Nagoya industrial zones where legacy linear suppliers lack precision mechanism expertise. White-space concentrates in compact vehicle direct-mount configurations where CKD Corporation's patent portfolio creates licensing friction for established architectures. Target aftermarket procurement autonomy among Tokyo-based logistics operators through unbundled direct relationships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among sensor-integrated actuator suppliers with condition-based service contract penetration. Long-term viability hinges on backward integration into fatigue testing infrastructure and seal manufacturing capability. Watch for inflection signals in electric actuator substitution rates across next-generation OEM platform designs.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Integrated Actuator Development | Virtualizes scheduled maintenance into condition-based contracts for Aichi Prefecture fleet operators. |
| Captive Certification Laboratory Investment | Compresses JIS B 8377 compliance timelines against PMDA-aligned import qualification delays. |
| Fluoropolymer Seal Backward Integration | Eliminates supply chain vulnerability from extended PMDA material traceability protocols. |
| Rotary Mechanism Precision Specialization | Captures robotics-adjacent demand in Nagoya zones underserved by linear actuator suppliers. |
| Direct Mount Patent Portfolio Expansion | Creates licensing friction for standardized architectures in Yokohama compact vehicle platforms. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of METI regulatory filings, JIS standard documentation, and keiretsu supply network disclosures. Primary interviews engaged Tier-1 supplier procurement leads, OEM platform engineers, aftermarket service directors, and commercial fleet maintenance managers across Aichi, Kanto, and Kansai regions. Secondary validation drew from MLIT vehicle type approval records, PMDA material qualification databases, and customs trade flow analysis. Bottom-up actuator shipment data triangulated against top-down automotive production forecasts.
Forecast inputs span product type segmentation by linear, rotary, and gripper configurations; installation architecture across inline, direct, and modular approaches; end-user procurement authority between OEM specification and aftermarket autonomy; and control technology migration from pneumatic to electric-hybrid systems. CAGRs derived from regression analysis against vehicle production volumes, METI energy efficiency enforcement trajectories, and electric powertrain substitution elasticities across the projection horizon. Carbon accounting rule stringency and fleet operator compliance cost sensitivity anchored scenario weightings.
Sensitivities concentrate around electric actuator substitution velocity, PMDA seal qualification timeline extensions, and keiretsu procurement hierarchy fragmentation. Forecasts embed assumptions regarding METI enforcement continuity and MLIT type approval protocol stability. Macroeconomic contraction, regulatory enforcement relaxation, or breakthrough electric actuator cost parity would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
5th Wheel Hitches Market
Vehicle Components
Oil Filter Elements Market
Vehicle Components
Automotive Steering Shaft Market
Vehicle Components
Global Motorcycle Chain Sprocket Market
Vehicle Components
Airport Ground Support Vehicle Market
Vehicle Components
Intelligent Rubber Tracks Market
Vehicle Components
Hydraulic Actuators Market
Vehicle Components
Argentina Automotive Carbon Fiber Composites Market
Vehicle Components
Vehicle-To-X Products Market
Vehicle Components
Traffic Control Device Tape Market
Vehicle Components
Bicycle Frames Market
Vehicle Components
Motorcycle Connectors Market
Vehicle Components
Vehicle Cargo Box Market
Vehicle Components
Bicycle Chain Market
Vehicle Components
Bicycle Front Hub Market
Vehicle Components
Automotive Sensors Market