
 Transmission Shift Actuator Market | 2026-2036
Transmission Shift Actuator Market Size, Share, and Industry Trends Forecast 2026-2036
Transmission Shift Actuator Market Insights
ISO 26262 functional safety certification is unwinding competitive access for suppliers lacking ASIL-rated design capabilities. Robert Bosch GmbH leverages captive semiconductor fabrication to secure actuator controller supply. ZF Friedrichshafen AG anchors European OEM programs through integrated mechatronic modules. Continental AG competes on software-defined calibration that reduces shift latency in dual-clutch architectures.
A transmission shift actuator is an electromechanical or electro-hydraulic device that translates electronic control signals into precise mechanical movement of gearbox selector forks, typically operating at voltages between 12V and 48V with response times under 100 milliseconds to enable automated manual, dual-clutch, and electric vehicle transmission architectures. Electromechanical stepper motor actuators lead unit volume in passenger vehicle applications where packaging density and energy efficiency outweigh cost sensitivity, while electro-hydraulic variants retain margin concentration in commercial vehicles and construction equipment where torque capacity and thermal durability command premium pricing. The OEM end-user channel dominates value capture due to multi-year platform contracts and co-development obligations, though aftermarket providers are expanding in regions with aging automatic transmission fleets.
NHTSA crashworthiness standards, EPA greenhouse gas regulations, and ISO 26262 safety integrity levels collectively mandate redundant position sensing and fault-tolerant actuator designs that add bill-of-materials complexity. The European Union's F-Gas Regulation and REACH chemical restrictions further constrain hydraulic fluid formulations and sealing materials used in electro-hydraulic units. Stakeholders must monitor how 48V mild-hybrid architectures and dedicated electric vehicle platforms alter actuator duty cycles, force profiles, and thermal management requirements as powertrain electrification progresses.
Market Dynamics
Powertrain electrification is fragmenting actuator architectures as 48V mild-hybrid and battery-electric platforms impose divergent force profiles, thermal envelopes, and duty cycles on transmission hardware suppliers.
Growth Catalysts
- EPA greenhouse gas benchmarks:Tightening fleet emissions standards in the United States are compelling OEMs to deploy automated manual transmissions with precision shift actuators to optimize fuel efficiency across light-duty vehicle lineups.
- Electromechanical stepper motor adoption:Passenger vehicle manufacturers are substituting electro-hydraulic units with compact electromechanical designs that reduce parasitic losses and improve packaging density in front-wheel-drive architectures.
- China manufacturing concentration:Domestic OEM expansion and joint-venture localization programs are generating concentrated demand for shift actuators in the world's largest automotive production base.
Market Restraints
- Rare earth magnet cost volatility:Neodymium and dysprosium price swings embedded in high-torque stepper motor rotors compress margin stability for electromechanical actuator producers.
- ISO 26262 certification barriers:ASIL-D functional safety requirements for transmission control systems impose multi-year validation timelines and specialized engineering talent scarcity that exclude mid-tier suppliers from OEM qualification programs.
- Hydraulic fluid substitution pressure:Electro-hydraulic actuator demand faces erosion from dry-clutch electromechanical alternatives as the European Union's F-Gas Regulation restricts conventional hydraulic formulations.
Strategic Opportunities
- Commercial vehicle electrification:Heavy-duty truck and bus electrification programs in Germany are creating demand for high-torque shift actuators capable of managing multi-speed e-axle transmissions under severe duty cycles.
- Software-defined calibration services:Tier-1 suppliers can capture recurring revenue by offering shift-pattern optimization as an over-the-air subscription service tied to dual-clutch transmission platforms.
- Aftermarket channel expansion:Aging automatic transmission fleets in Japan are generating replacement actuator demand through independent service networks and remanufacturing specialists.
Industry Challenges
- ASIL-rated firmware engineering scarcity:Functional safety software development for actuator controllers requires specialized expertise in embedded systems and fault-tolerant architectures that outpaces current workforce supply.
- Legacy transmission integration complexity:Electrified powertrain programs must maintain backward compatibility with existing manufacturing tooling and supplier qualification systems, extending development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transmission Shift Actuator Market |
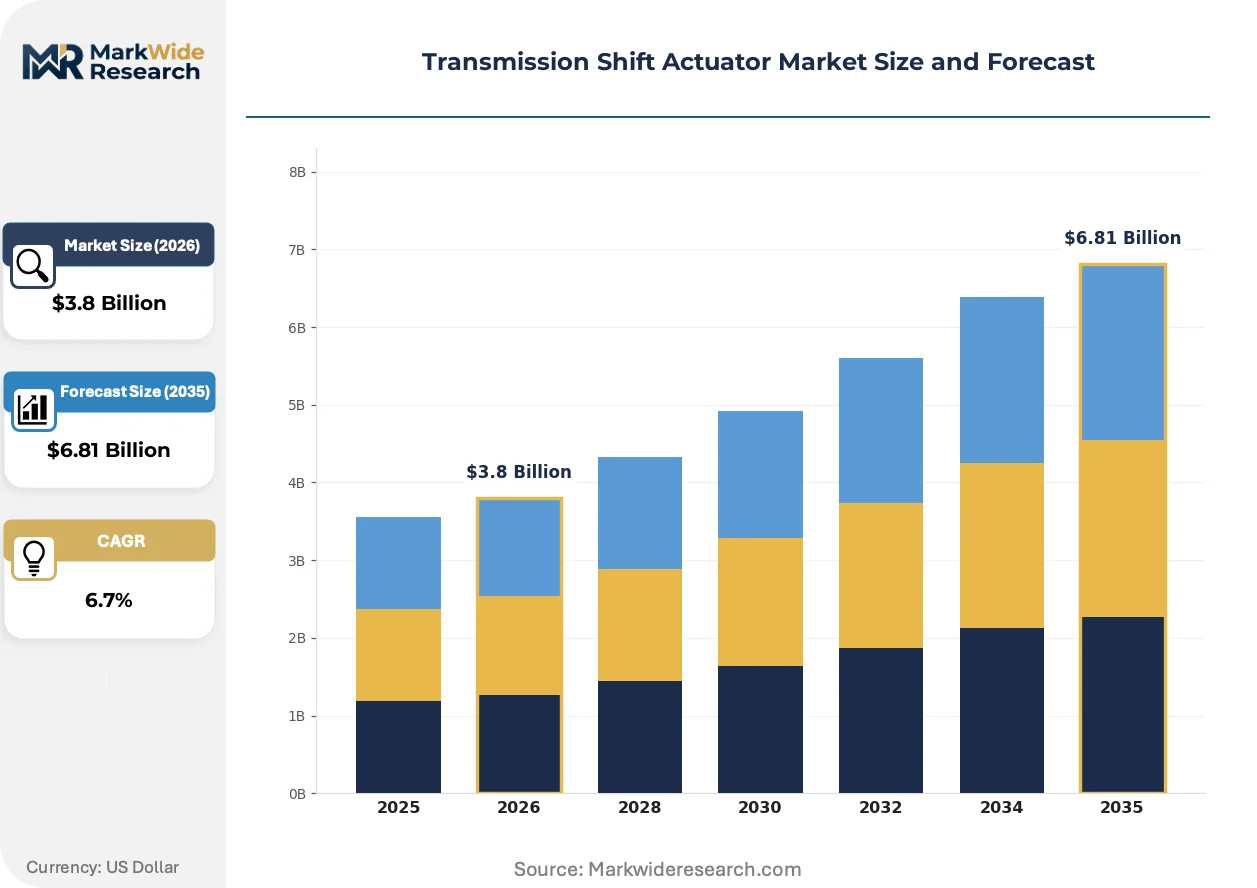
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Electric, Hydraulic, Pneumatic, Electro-Hydraulic Technology: Electromechanical, Solenoid, Stepper Motor, Piezoelectric Application: Commercial Vehicles, Passenger Vehicles, Construction Equipment, Agricultural Machinery End User: OEMs, Tier-1 Suppliers, Vehicle Assemblers, Aftermarket Providers |
| Companies Covered | Robert Bosch GmbH, ZF Friedrichshafen AG, Continental AG, Denso Corporation, BorgWarner Inc., Schaeffler AG, Magna International, Hitachi Astemo, Ltd., Aisin Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transmission Shift Actuator Market Trends and Innovations
Actuator control intelligence is migrating from centralized transmission control units toward edge computing architectures embedded within mechatronic modules, compressing response latency and enabling real-time adaptive shift strategies.
Integrated motor-inverter-actuator modules are decomposing the traditional three-tier supplier structure where discrete motor, controller, and hydraulic valve vendors operated independently. Tier-1 powertrain integrators in Germany and Japan are consolidating these functions into sealed mechatronic units that reduce assembly complexity and wiring harness mass. This consolidation is compressing the addressable market for standalone component suppliers while expanding contract values for system-level providers capable of delivering calibrated, vehicle-ready subassemblies.
REACH chemical restrictions and the EU F-Gas Regulation are compelling electro-hydraulic actuator manufacturers to reformulate sealing elastomers and hydraulic fluids around bio-based and low-global-warming-potential alternatives. Compound suppliers in the European Union are accelerating qualification programs for hydrogenated nitrile butadiene rubber and polyether ether ketone sealing solutions that maintain chemical compatibility under elevated thermal stress. Commercial vehicle applications with extended service intervals face the steepest reformulation costs and validation burdens.
Platform-level procurement consolidation among OEMs is concentrating annual actuator volume commitments into multi-year, sole-source agreements that displace spot purchasing and competitive second-sourcing arrangements. Volkswagen Group and Stellantis have shifted transmission component sourcing toward integrated mechatronic module contracts that bundle actuators, sensors, and controllers under single-supplier responsibility. Tier-2 actuator specialists in China and South Korea are responding by deepening subsystem integration capabilities or accepting margin compression to retain volume access.
Transmission Shift Actuator Market Segmentation
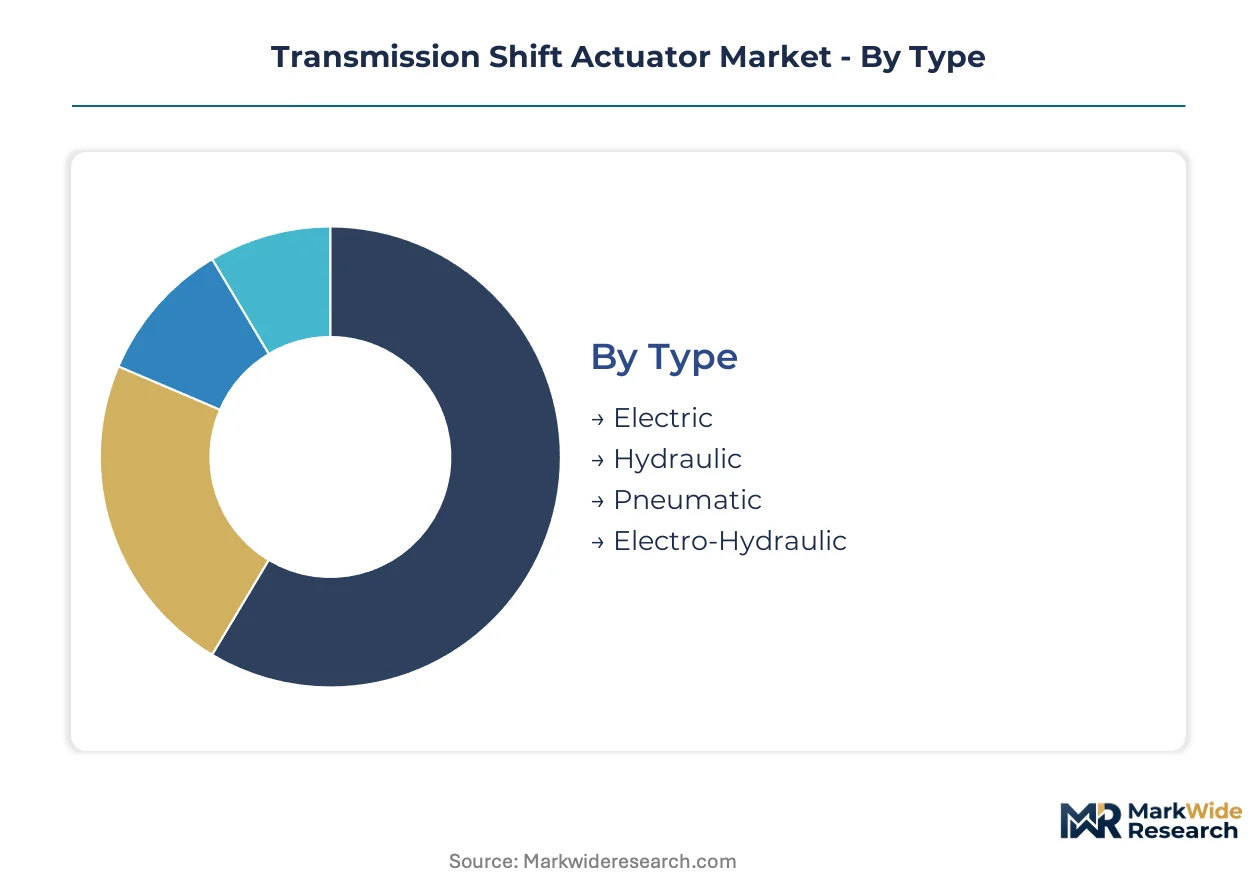
Actuator segmentation reveals divergent margin architectures across powertrain electrification trajectories. Suppliers must align capability investments with where OEM procurement is consolidating.
Type:
Margin pools concentrate in electromechanical variants where precision manufacturing and embedded software create defendable positions.
- Electric:Direct-drive motor architectures eliminate hydraulic infrastructure and enable 48V mild-hybrid integration. Passenger vehicle OEMs in Germany and Japan are standardizing electric actuators for dual-clutch platforms to meet NHTSA fuel economy benchmarks.
- Hydraulic:High-pressure fluid systems deliver torque multiplication for commercial vehicle transmissions. Demand clusters in construction equipment where thermal durability requirements exceed electromechanical duty ratings.
- Pneumatic:Compressed-air systems serve niche applications in heavy-duty mining trucks where explosive atmosphere certifications prohibit electrical components.
- Electro-Hydraulic:Hybrid architectures combine electronic control with hydraulic force multiplication. REACH chemical restrictions and EU F-Gas Regulation are forcing reformulation of hydraulic fluids and sealing elastomers.
Electric holds installed capacity. Electro-Hydraulic is rotating up the share rankings in commercial vehicle electrification programs.
Technology:
Technology selection determines which suppliers capture platform-level contracts versus component spot sales.
- Electromechanical:Integrated motor-gearbox assemblies with position feedback sensors enable sub-100 millisecond shift response. OEMs in China are localizing electromechanical production for domestic automatic transmission expansion.
- Solenoid:Electromagnetic plungers provide cost-optimized shifting for entry-level automated manual transmissions. Volume concentrates in India and Brazil where cost sensitivity dominates procurement criteria.
- Stepper Motor:Discrete angular positioning enables precise selector fork control without feedback sensors. Rare earth magnet cost volatility compresses margin stability for rotor manufacturers.
- Piezoelectric:Ceramic crystal expansion delivers nanometer-scale positioning accuracy for racing transmission applications. Ultra-low volume limits addressable market to motorsport and hypercar segments.
Stepper Motor dominates unit economics. Piezoelectric is climbing the fastest as electrification demands precision positioning.
Application:
Application mix shapes force profile requirements and thermal envelope specifications.
- Commercial Vehicles:Heavy-duty trucks and buses require actuators rated for continuous operation under severe duty cycles. German OEM electrification programs are driving multi-speed e-axle actuator demand.
- Passenger Vehicles:Front-wheel-drive architectures prioritize packaging density and parasitic loss reduction. Electromechanical designs are displacing hydraulic alternatives across compact and mid-size platforms.
- Construction Equipment:Excavators and wheel loaders demand sealed actuators resistant to contamination and shock loading. Extended service intervals command premium pricing for hydraulic variants.
- Agricultural Machinery:Tractor transmissions operate in high-vibration environments with intermittent duty cycles. Aftermarket replacement demand concentrates in North American and European farming regions.
Passenger Vehicles anchor volume scale. Commercial Vehicles is gaining share fastest through electrification mandates.
End User:
End-user channel determines contract structure and value capture mechanism.
- OEMs:Vehicle manufacturers procure actuators through multi-year platform contracts with co-development obligations. Volkswagen Group and Stellantis have shifted toward integrated mechatronic module sourcing.
- Tier-1 Suppliers:Powertrain integrators bundle actuators with transmission control units and calibration services. These suppliers capture recurring revenue through software-defined shift optimization subscriptions.
- Vehicle Assemblers:Contract manufacturers and regional assembly operations purchase validated actuator subassemblies. Procurement concentrates in China and Mexico where localization requirements apply.
- Aftermarket Providers:Independent service networks and remanufacturing specialists serve aging automatic transmission fleets. Japan's aging vehicle parc generates concentrated replacement actuator demand.
OEMs control platform access. Aftermarket Providers is expanding fastest as fleet age extends replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEM procurement concentrates in manufacturing hubs where electrification mandates and transmission platform localization intersect. Tier-1 suppliers align actuator production with these buyer clusters to minimize logistics costs and satisfy domestic content requirements.
United States
NHTSA fuel economy standards and EPA greenhouse gas benchmarks compel Detroit automakers to deploy precision shift actuators in automated manual transmissions. The Inflation Reduction Act's domestic manufacturing incentives accelerate local actuator controller production. Michigan and Ohio host concentrated transmission engineering centers where suppliers co-develop mechatronic modules with OEM powertrain divisions.
Germany
Commercial vehicle electrification programs drive demand for high-torque actuators in multi-speed e-axle transmissions for heavy-duty trucks. KBA type-approval requirements and EU F-Gas Regulation constrain hydraulic fluid formulations used in electro-hydraulic variants. Baden-Württemberg and Bavaria anchor supplier engineering headquarters where integrated motor-inverter-actuator modules undergo vehicle-level calibration.
China
Domestic OEM expansion and joint-venture localization generate concentrated actuator demand across automatic transmission capacity buildouts. MIIT new energy vehicle mandates and dual carbon goals accelerate electromechanical actuator adoption in 48V mild-hybrid platforms. Shanghai and Guangzhou manufacturing corridors host transmission assembly plants where local suppliers qualify for platform contracts.
Japan
Aging automatic transmission fleets create aftermarket replacement actuator demand through independent service networks. METI automotive industry policies support shift actuator remanufacturing capabilities for circular economy compliance. Aichi Prefecture transmission clusters concentrate precision component suppliers serving both OEM and aftermarket channels.
South Korea
Domestic automaker dual-clutch transmission programs source electromechanical actuators from localized Tier-1 production. MFDS industrial standards and KATRI certification requirements govern functional safety validation for transmission control systems. Gyeonggi-do supplier parks house actuator motor and controller manufacturing aligned with Hyundai-Kia platform cycles.
Transmission Shift Actuator Market Competitive Landscape
Player mix skews toward diversified automotive Tier-1 suppliers with captive powertrain divisions. Market structure concentrates around integrated mechatronic module providers capable of delivering calibrated subassemblies under multi-year platform contracts. Strategic archetypes include semiconductor-fabricating conglomerates, transmission-specialized engineering groups, and software-defined calibration houses. Dominant competitive moves encompass backward integration into motor and controller production, plus geographic co-location with OEM assembly plants.
Among German engineering conglomerates, Robert Bosch GmbH and ZF Friedrichshafen AG exemplify the integrated systems archetype through their positions in mechatronic module development. Continental AG represents the software-calibration specialist tier with capabilities in shift-pattern optimization. Japanese keiretsu-affiliated suppliers including Denso Corporation and Aisin Corporation occupy positions in precision electromechanical component supply. These named entities anchor competitive intensity around functional safety certification, captive semiconductor access, and OEM platform co-development obligations.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| ZF Friedrichshafen AG |
| Continental AG |
| Denso Corporation |
| BorgWarner Inc. |
| Schaeffler AG |
| Magna International |
| Hitachi Astemo, Ltd. |
| Aisin Corporation |
| Others |
Pricing and Supply Chain Analysis
ISO 26262 ASIL-D certification gates both supplier qualification and price differentiation simultaneously, creating a bifurcated market where certified incumbents command platform-level premiums while uncertified competitors face spot-market margin compression. Electromechanical actuator pricing stratifies across premium, standard, and economy tiers based on functional safety rating, with OEMs paying substantial uplifts for redundant position sensing and fault-tolerant controller architectures that satisfy NHTSA crashworthiness mandates.
Pricing Analysis
Cost-plus contracts with rare earth magnet indexation dominate electromechanical actuator procurement, protecting suppliers from neodymium and dysprosium price volatility while exposing margins to permanent magnet cost swings. Price differentiation centers on ASIL certification tier and software-defined calibration capability, with Tier-1 integrators capturing recurring revenue through over-the-air shift optimization subscriptions. Cost compression in hydraulic variants is intensifying because REACH chemical restrictions force bio-based fluid reformulation, squeezing margin stability for electro-hydraulic specialists. Commercial vehicle OEMs exhibit highest price sensitivity due to fleet procurement scale, while premium passenger vehicle manufacturers prioritize shift latency performance over unit economics.
Supply Chain Analysis
China, Germany, and Japan anchor transmission shift actuator manufacturing, with Shanghai and Guangzhou corridors hosting electromechanical motor production while Baden-Württemberg concentrates mechatronic module integration and Aichi Prefecture supplies precision gear components. The supply chain draws from rare earth magnet processors in Inner Mongolia, semiconductor foundries in Taiwan, and sealing elastomer compounders in the European Union. Single-source vulnerability concentrates in high-torque stepper motor rotor supply, where limited qualified magnet sintering capacity creates bottleneck exposure. Distribution runs through Tier-1 powertrain integrators that consolidate actuators, controllers, and calibration services into vehicle-ready subassemblies for OEM platform contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Powertrain electrification fragments actuator architectures into divergent 48V mild-hybrid and battery-electric specifications, creating specialization niches for suppliers that align capability investments with specific OEM electrification trajectories rather than pursuing horizontal coverage.
For Market Incumbents: Secure captive semiconductor fabrication or long-term controller supply agreements to defend against Bosch-style vertical integration that locks competitors out of platform contracts. Deepen software-defined calibration capabilities to capture recurring revenue streams that offset hardware margin compression from rare earth cost volatility. Prioritize ASIL-D firmware engineering recruitment to maintain OEM qualification access as ISO 26262 validation timelines extend. For New Entrants and Emerging Players: ASIL-B certification fast-tracks entry into aftermarket replacement channels where aging automatic transmission fleets in Japan generate demand independent of multi-year OEM platform lock-in. Target commercial vehicle electrification programs in Germany, where multi-speed e-axle actuator specifications remain fluid and incumbent positions are less entrenched than passenger vehicle dual-clutch platforms. Pursue remanufacturing partnerships with independent service networks to bypass capital-intensive clean-sheet actuator development. For Investors and Strategic Acquirers: EPA greenhouse gas benchmark tightening reshapes the acquisition landscape by accelerating automated manual transmission deployment and expanding the addressable market for precision shift actuator suppliers. Long-term viability centers on electromechanical specialists with demonstrated 48V integration capability and software-defined calibration infrastructure rather than hydraulic legacy exposure. Watch for MIIT new energy vehicle mandate acceleration in China as the signal indicating when localized supplier consolidation premiums will compress.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Semiconductor Controllers | Captive controller supply secures actuator platform access against Bosch and ZF supply dominance. |
| Software-Defined Calibration Subscription Launch | Recurring revenue from shift-pattern optimization reduces hardware margin dependency for Tier-1 integrators. |
| ASIL-D Certification Investment Program | Functional safety rating unlocks OEM platform co-development contracts excluded from mid-tier competition. |
| Geographic Manufacturing Footprint Expansion | Localized production in Shanghai and Guangzhou corridors satisfies MIIT domestic content requirements. |
| Remanufacturing Capability Buildout | Circular economy compliance with METI policies captures Japan aftermarket replacement actuator demand. |
Research Methodology
The analysis maps electromechanical, electro-hydraulic, and pneumatic actuator sub-sectors, each validated through transmission platform engineers, Tier-1 supplier procurement leads, aftermarket distributor operations, and powertrain calibration specialists. Primary fieldwork combined structured interviews with OEM powertrain divisions and secondary validation against IHS Markit vehicle production databases, EPA regulatory filings, and MIIT new energy vehicle mandate documentation. Bottom-up segmentation modeling triangulated against top-down powertrain electrification scenario analysis.
Consistency checks validated volume and value outputs against external benchmarks including transmission platform build schedules and rare earth magnet demand forecasts. The analytical framework modeled propulsion architecture, vehicle class, duty cycle severity, and regional regulatory cluster across the projection horizon. CAGRs derived from segment-level unit economics and content-per-vehicle trajectories, with specific inputs including 48V mild-hybrid adoption curves and commercial vehicle electrification program timelines.
Decision-makers should treat outputs as directional under base assumptions of sustained EPA and NHTSA regulatory tightening and stable rare earth supply chain configuration; material deviation in electrification subsidy levels or magnet export restrictions would warrant model refresh. Recalibration cycles align with material shifts in OEM platform sourcing consolidation and functional safety certification requirement evolution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Automotive Transmission Fluid Market
Powertrain
Tuning Box Market
Powertrain
Global Automotive Tappet Market
Powertrain
Diesel Engine Market
Powertrain
Global Automotive Powertrain Systems Market
Powertrain
Power Assisted Steering Market
Powertrain
Brazil Automotive Market
Powertrain
Gasoline Direct Injection (GDI) System Market
Powertrain
Global Automotive Clutch Market
Powertrain
Power Steering Filter Market
Powertrain
Automotive Power Steering Pump Market
Powertrain
Automotive Tuner Market
Powertrain
Brazil Automotive Actuators Market
Powertrain
Engine Tuner Market
Powertrain
Global Industrial Engine Market
Powertrain
Engine Cylinder Liners Market