
 Robotic Haul Trucks Market | 2026-2036
Robotic Haul Trucks Market Size, Share, and Industry Trends Forecast 2026-2036
Robotic Haul Trucks Market Insights
High-strength steel is hardening chassis designs across heavy-duty autonomous platforms, reducing unladen weight while preserving structural integrity under extreme payloads. Waymo leverages its Waymo Driver stack to anchor long-haul freight trials in the southwestern United States. Torc Robotics competes through its independent subsidiary structure under Daimler Truck, sustaining direct OEM integration without diluting engineering focus.
Robotic haul trucks are self-driving heavy vehicles engineered for material transport in controlled industrial environments, typically integrating LiDAR arrays, millimeter-wave radar, and redundant braking systems to achieve ISO 26262 functional safety ratings; their core purpose centers on eliminating human operator exposure to hazardous terrain while sustaining continuous production cycles. Fully autonomous systems dominate capital deployment in surface mining, where labor cost arbitrage and shift-pattern optimization generate the clearest return thresholds. AI-driven navigation platforms represent the fastest-expanding technology layer, as neural perception stacks displace rule-based path planning in unstructured off-road conditions.
The U.S. Department of Transportation's Federal Motor Carrier Safety Administration and the National Highway Traffic Safety Administration jointly govern autonomous truck testing protocols, while the International Organization for Standardization publishes ISO 17757 for autonomous mining vehicle safety, collectively forcing OEMs to maintain dual compliance tracks for on-road and off-road certification pathways. Stakeholders must monitor how fragmented national type-approval regimes constrain cross-border fleet standardization before committing to single-vendor platform bets.
Market Dynamics
Neural perception architectures are compressing development cycles for off-road autonomy, forcing mining operators to choose between retrofitting existing fleets versus greenfield deployments of integrated platforms.
Growth Catalysts
- Labor Arbitrage in Surface Mining:Australian iron ore operators achieve continuous haulage through 24-hour autonomous shifts, eliminating fatigue-related downtime and shift-change intervals.
- ISO 17757 Certification Pathway:The International Organization for Standardization's autonomous mining vehicle safety standard creates unified compliance benchmarks across equipment suppliers.
- LiDAR-Radar Sensor Fusion:Redundant environmental perception stacks enable operation in dust-laden, GPS-denied pit conditions where single-modality systems fail.
Market Restraints
- High-Grade Steel Input Volatility:Chassis fabrication depends on specialized high-strength alloy supply concentrated in East Asian rolling mills, exposing OEMs to tariff and logistics cost swings.
- EU Machinery Directive Friction:The European Union's unsupervised vehicle operation requirements impose multi-year type-approval timelines that delay fleet deployment.
- Remotely Operated Dozer Substitution:Semi-autonomous dozer fleets retain human-in-the-loop flexibility for irregular material handling, constraining full-autonomy penetration in smaller pits.
Strategic Opportunities
- Western Australian Expansion:The Pilbara region's established 5G private networks and maintenance infrastructure position it for next-generation fleet scaling beyond current deployment levels.
- Copper Belt Electrification Mandates:Chilean and Peruvian decarbonization policies create demand for battery-electric autonomous haulers in Andean open-pit operations.
- Digital Twin Integration:Convergence of real-time fleet telemetry with mine planning software enables predictive haul route optimization and crusher feed balancing.
Industry Challenges
- Autonomy Systems Integration Talent:Mining equipment OEMs compete with automotive and defense sectors for embedded software engineers with ISO 26262 functional safety expertise.
- Legacy Fleet Interoperability:Mixed fleets of autonomous and manned trucks require traffic management systems capable of coordinating heterogeneous vehicle protocols.
- Dual Certification Burden:Suppliers must maintain parallel compliance tracks for on-road testing protocols under NHTSA and off-road mining standards under ISO.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Robotic Haul Trucks Market |
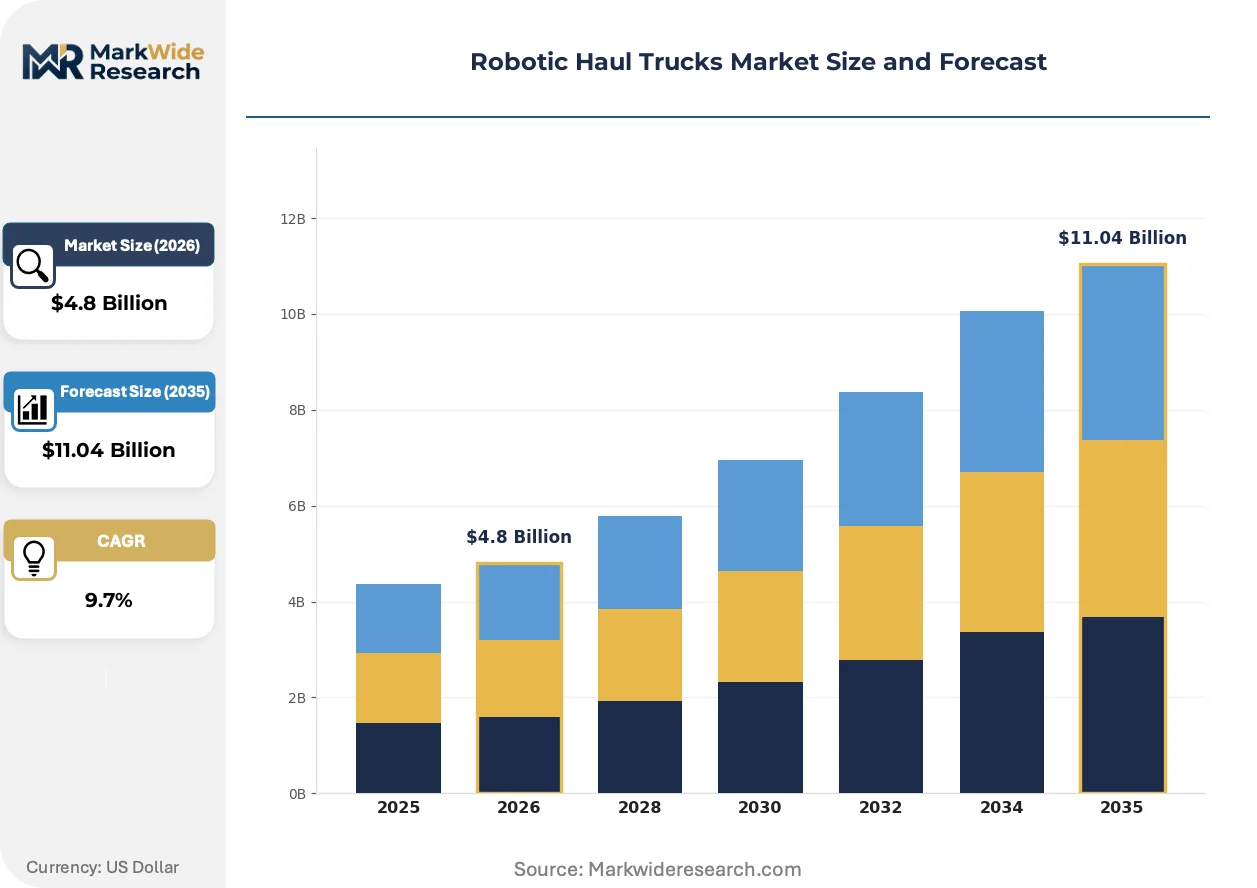
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fully Autonomous, Semi-Autonomous, Remote-Controlled, Hybrid Terrain Type: Off-Road, Mining, Construction, Quarry Payload Capacity: 10-20 Tons, 20-30 Tons, 30-40 Tons, Above 40 Tons Technology: GPS Navigation, Sensor-Based, AI-Driven, Machine Learning |
| Companies Covered | Aurora Innovation, Kodiak Robotics, Inceptio Technology, Plus.ai, Torc Robotics, TuSimple, Waymo, Einride, Gatik, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Robotic Haul Trucks Market Trends and Innovations
Artificial intelligence inference at the edge is redefining how haul trucks perceive and respond to unstructured terrain, compressing the gap between research prototypes and production-grade autonomy.
Sensor fusion architectures are consolidating around solid-state LiDAR paired with 4D imaging radar, replacing mechanically scanned units prone to vibration failure in high-shock mining environments. Australian operators in the Pilbara region are deploying these integrated perception stacks across new fleet orders. This consolidation is compressing supplier margins for single-modality sensor vendors while rewarding full-stack platform providers.
The EU AI Act's risk-based classification system now governs autonomous vehicle decision-making algorithms as high-risk AI applications, mandating conformity assessment procedures before market placement. Mining OEMs serving European projects must document training data provenance and model validation protocols. Surface extraction contractors in Scandinavia are responding by pre-qualifying suppliers with established EU notified body relationships.
Equipment procurement is fragmenting between integrated platform purchases and retrofit autonomy kits, as mid-tier mining houses seek to extend existing truck asset life. Distributor channels in North American coal and Canadian oil sands are building retrofit installation capabilities to capture this demand. Western Canadian operations show the clearest bifurcation, with large diversified miners favoring integrated platforms while junior operators pursue staged automation investments.
Robotic Haul Trucks Market Segmentation
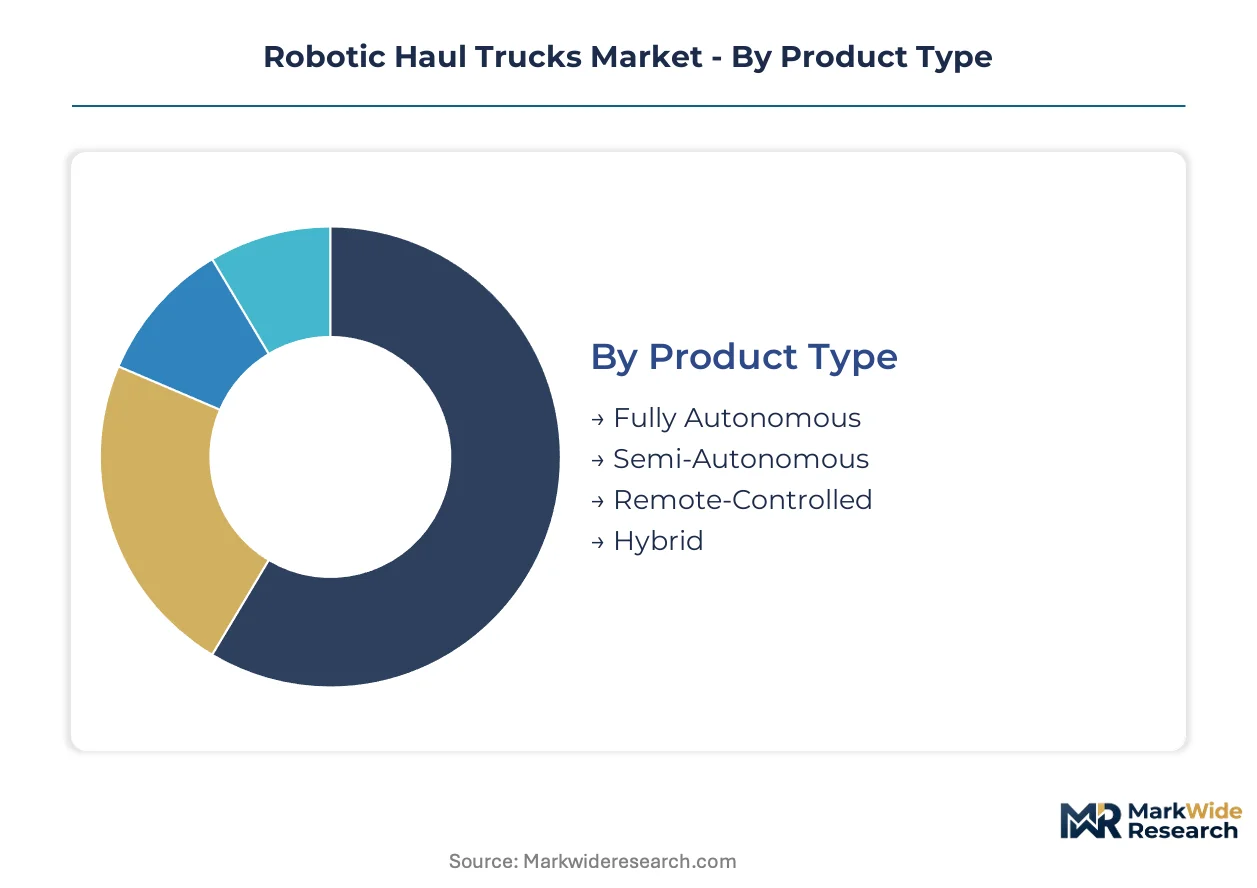
Segmentation in the robotic haul trucks market exposes where capital concentrates versus where technology is advancing. Product architecture and payload capacity drive procurement decisions, while terrain requirements and navigation systems determine supplier qualification thresholds.
Product Type:
Volume deployment clusters in systems eliminating human operators entirely, while premium pricing attaches to hybrid architectures preserving manual override capability.
- Fully Autonomous:These systems integrate redundant LiDAR-radar perception stacks with ISO 26262-certified braking architectures to enable unsupervised 24-hour operation in Western Australia's Pilbara iron ore pits. Australian operators achieve continuous haulage cycles without shift-change intervals, compressing cost per ton against conventional manned fleets.
- Semi-Autonomous:Human-in-the-loop designs retain operator stations for complex maneuvering in irregular pit geometries, attracting mid-tier mining houses in Chile's Andean copper belt seeking staged automation investments without full fleet replacement.
- Remote-Controlled:Teleoperation centers enable human oversight from surface facilities, deployed in hazardous underground conditions where full autonomy remains technically immature.
- Hybrid:Switchable autonomy modes allow manual operation during maintenance windows or emergency egress, commanding price premiums from diversified miners requiring operational flexibility.
Today's leader: Fully Autonomous. Tomorrow's challenger: Hybrid.
Terrain Type:
Application environment dictates chassis specification, suspension travel, and sensor protection ratings across procurement categories.
- Off-Road:Extended suspension articulation and sealed electronics enclosures enable operation in unimproved terrain across Canadian oil sands and Siberian alluvial deposits.
- Mining:Reinforced frame rails and dust-ingress protection dominate surface extraction deployments, representing the largest installed base concentration.
- Construction:Compact turning radii and variable ride height accommodate earthmoving contractors in urban infrastructure projects where space constraints limit vehicle dimensions.
- Quarry:Abrasion-resistant body liners and high-approach-angle geometry address limestone and granite extraction in European and North American aggregate operations.
Construction applications are gaining share fastest as infrastructure stimulus programs accelerate fleet procurement.
Payload Capacity:
Scale economics favor the heaviest configurations in established mining districts, while mid-range capacities serve contractor fleets requiring highway transportability.
- 10-20 Tons:Highway-legal dimensions enable rapid site relocation for civil construction contractors and quarry operators in Germany and France where road weight limits constrain larger units.
- 20-30 Tons:Balanced payload-to-weight ratios attract mid-tier mining contractors in Peru's copper corridor seeking diesel-electric hybrid platforms.
- 30-40 Tons:Standardized body geometries support rapid bucket matching with electric rope shovels in South African platinum and gold operations.
- Above 40 Tons:Ultra-class configurations achieve 400-ton single-pass capacities in Pilbara iron ore and Mongolian coking coal mines where shovel size dictates fleet specification.
Above 40 Tons commands current procurement volume. 20-30 Tons shows steepest expansion trajectory as electrification mandates reshape mid-scale fleet planning.
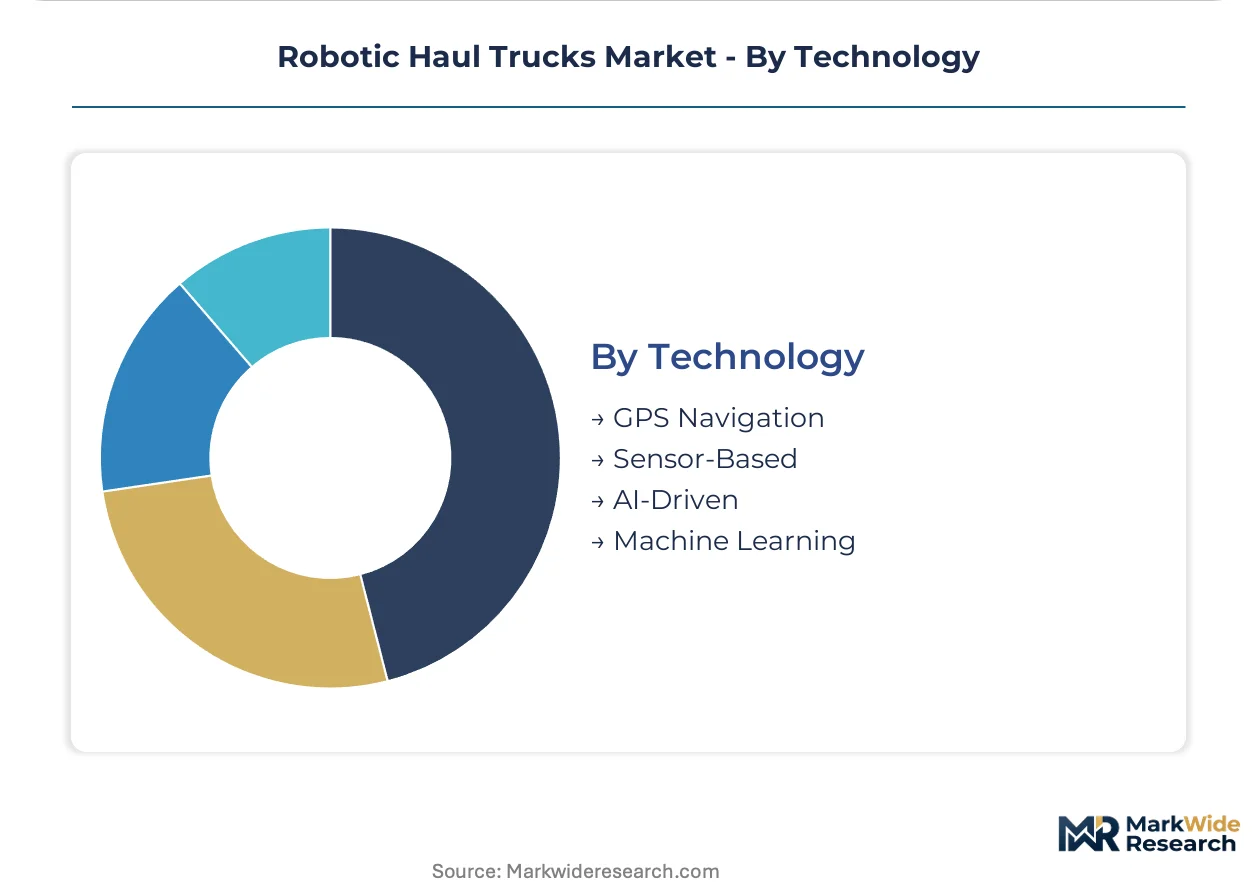
Technology:
Navigation architecture determines supplier qualification and long-term software upgrade pathways.
- GPS Navigation:Centimeter-level RTK correction enables precise haul road adherence in open-pit environments with clear sky visibility across Nevada gold operations.
- Sensor-Based:Multi-modal perception stacks operate in GPS-denied conditions including tunnels and steep-walled pits where satellite signals attenuate.
- AI-Driven:Neural perception architectures process unstructured terrain features in real-time, climbing fastest as training data accumulates from deployed fleets.
- Machine Learning:Predictive maintenance models analyze vibration and thermal telemetry to schedule component replacement before failure in Kazakh bauxite and Guinean iron ore operations.
Sensor-Based systems anchor current reliability standards. AI-Driven platforms are displacing rule-based alternatives in new fleet specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Western Australia's Pilbara iron ore district anchors procurement volume for autonomous haulage systems, with surface mining operators pursuing fleet electrification alongside full-autonomy deployment.
Australia
Private 5G networks across Pilbara mine sites enable real-time fleet coordination for autonomous ultra-class trucks operating in 24-hour continuous cycles. The country's national resources regulator enforces autonomous vehicle safety protocols under state mining legislation. Perth-based equipment distributors are expanding maintenance infrastructure to support next-generation battery-electric autonomous deployments.
Chile
Andean copper producers face decarbonization mandates driving demand for battery-electric autonomous haulers in high-altitude open-pit operations. The Ministry of Mining's National Mining Policy prioritizes automation for productivity and worker safety in remote desert conditions. Antofagasta and Calama mining clusters host concentrated pilot programs for electrified autonomous fleets.
United States
Southwestern long-haul freight trials leverage highway corridor infrastructure for autonomous truck testing between distribution hubs. The Department of Transportation's NHTSA governs on-road autonomous vehicle testing protocols under federal motor carrier regulations. Arizona's Sun Corridor and Texas freight corridors attract concentrated technology validation programs.
Canada
Oil sands operators in Alberta deploy heavy-duty autonomous platforms for bitumen extraction in extreme cold conditions. Transport Canada's Motor Vehicle Safety Directorate coordinates provincial autonomous vehicle permitting frameworks. Fort McMurray and the Athabasca region concentrate fleet deployments with established remote monitoring centers.
Sweden
Underground mining automation advances in Kiruna and Malmberget iron ore districts where full autonomy remains technically challenging. The Swedish Work Environment Authority enforces machinery safety standards aligned with EU Machinery Directive requirements. Arctic mining clusters drive specialized sensor development for GPS-denied tunnel operations.
Robotic Haul Trucks Market Competitive Landscape
Strategic partnerships dominate the current landscape as autonomy stack providers align with heavy-duty chassis manufacturers. The vendor base concentrates around three archetypes: full-stack platform developers, Tier 1 automotive suppliers with mining divisions, and pure-play autonomy software houses. Technology licensing agreements and joint venture structures represent the primary competitive moves, with geographic expansion into mining districts following established customer relationships.
Within the full-stack autonomy tier, Aurora Innovation and Waymo exemplify platform-first approaches developed through extensive on-road mileage accumulation. Torc Robotics occupies a position within the automotive supplier ecosystem through its Daimler Truck subsidiary structure. Kodiak Robotics represents the venture-backed specialist archetype focused on freight corridor deployment before mining sector extension.
| Leading Market Players |
|---|
| Aurora Innovation |
| Kodiak Robotics |
| Inceptio Technology |
| Plus.ai |
| Torc Robotics |
| TuSimple |
| Waymo |
| Einride |
| Gatik |
| Others |
Pricing and Supply Chain Analysis
High-strength alloy steel rolls through East Asian mills into chassis fabrication tiers, with specialized rolling capacity concentration granting pricing leverage to Pilbara iron ore operators placing bulk fleet orders while junior miners absorb spot-market volatility through retrofit kit procurement.
Pricing Analysis
Input-cost pass-through from high-grade steel tariffs and lithium-ion battery pack pricing shapes three-tier pricing structure across premium, standard, and economy levels. Premium tiers attach to ISO 26262-certified fully autonomous platforms with integrated perception stacks, while economy positioning targets remote-controlled retrofit kits for mid-tier contractors. Pricing pressure stems from OEM margin compression as Australian mega-miners consolidate procurement through multi-year framework agreements. Junior mining houses in Chile and Peru exhibit highest price sensitivity, prioritizing staged automation investments over integrated platform replacement.
Supply Chain Analysis
Australian local-content mandates under state mining legislation reshape sourcing toward Perth-based maintenance infrastructure and domestic assembly partnerships. Chassis fabrication draws from South Korean and Japanese high-strength steel rolling mills, while solid-state LiDAR arrays and 4D imaging radar modules source from Chinese and German sensor specialists. Single-source vulnerability concentrates in specialized alloy supply chains exposed to tariff escalation. Distribution runs through equipment distributors building retrofit installation capabilities across North American coal and Canadian oil sands regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The robotic haul trucks market compounds steadily as surface mining automation mandates eliminate human operator exposure across hazardous terrain, embedding recurring fleet replacement cycles into capital planning.
For Market Incumbents: To counter autonomy stack commoditization from automotive sector entrants, anchor defensive positioning through backward integration into solid-state LiDAR manufacturing and exclusive 5G private network partnerships across Pilbara mine sites. Deepen certification moats by accelerating EU AI Act conformity assessment documentation before competitor qualification.
For New Entrants and Emerging Players: Launch via retrofit autonomy kit distribution partnerships with established mining equipment dealers in Western Canada and Chilean copper corridors. Target the 20-30 ton payload segment where electrification mandates reshape mid-scale fleet planning with less entrenched incumbent relationships. Pursue white-space in underground remote-controlled teleoperation where full autonomy remains technically immature.
For Investors and Strategic Acquirers: Consolidation pressure builds where autonomy software houses lack OEM chassis integration partnerships and face dual certification burden costs. Frame long-term viability around platform providers with demonstrated ISO 17757 compliance pathways and accumulated fleet training data repositories. Watch the signal of Australian iron ore operators accelerating battery-electric autonomous fleet conversion as inflection indicator for electrified platform demand scaling.
| Strategic Initiative | Industry Significance |
|---|---|
| 5G Private Network Deployment | Enables real-time fleet coordination for 24-hour continuous haulage cycles across Pilbara mine sites. |
| Battery-Electric Platform Development | Addresses Chilean and Peruvian decarbonization mandates for high-altitude Andean open-pit operations. |
| Retrofit Autonomy Kit Distribution | Captures mid-tier mining house demand for staged automation without full fleet replacement commitment. |
| EU AI Act Conformity Assessment | Unlocks European project access through documented training data provenance and model validation protocols. |
| Digital Twin Integration Partnership | Converges fleet telemetry with mine planning software for predictive haul route optimization. |
Research Methodology
Coverage spans Australia, Chile, the United States, Canada, and Sweden, with primary inputs from each market through structured interviews with mine operations directors, autonomous fleet managers, equipment procurement leads, and aftermarket service heads. Secondary validation draws from ISO 17757 documentation, NHTSA autonomous vehicle testing protocols, SEC filings from listed mining equipment OEMs, and Australian state mining safety regulator publications. Bottom-up fleet deployment tallies triangulate against top-down capital expenditure projections from major mining houses.
Granularity-level modeling disaggregates volume and value across product type, terrain application, payload capacity tier, and navigation technology architecture throughout the forecast period. CAGRs derive from segmented growth trajectory analysis weighted by regional fleet replacement cycles and automation mandate implementation timelines. Industry-specific inputs include shovel-to-truck matching ratios in Pilbara iron ore operations and copper belt electrification policy compliance deadlines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU Machinery Directive enforcement or sustained high-grade steel tariff escalation. Forecasts reflect assumptions regarding 5G private network rollout pace and battery-electric platform technical maturation for high-altitude deployment. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Vehicles
Europe Light Commercial Vehicle Trailer Market
Commercial Vehicles
Van Market
Commercial Vehicles
Truck-As-A-Service Market
Commercial Vehicles
Canada Commercial Vehicles Market
Commercial Vehicles
Waste or Garbage Collection Vehicle Market
Commercial Vehicles
Electric LCV Market
Commercial Vehicles
Modular Trailer Market
Commercial Vehicles
Utility Vehicle Market
Commercial Vehicles
France Light Commercial Vehicles Market
Commercial Vehicles
Global Commercial Vehicle Remote Diagnostics Market
Commercial Vehicles
Industrial Truck Market
Commercial Vehicles
Indonesia Box Truck Market
Commercial Vehicles
Flatbed Semi-Trailer Market
Commercial Vehicles
Russia Commercial Vehicle Market
Commercial Vehicles
Global Commercial Vehicles Market
Commercial Vehicles
Cryogenic Liquid Transport Vehicle Market