
 Motorcycle Connectors Market | 2026-2036
Motorcycle Connectors Market Size, Share, and Industry Trends Forecast 2026-2036
Motorcycle Connectors Market Analysis
Market Context with Strategic Players
Southeast Asian connector capacity is fragmenting as tier-one suppliers and local specialists compete for motorcycle electrification programs. TE Connectivity leverages its automotive connector heritage to transfer high-reliability designs into two-wheeler platforms. Yazaki anchors regional supply through its Thailand-based wiring harness operations, sustaining long-term OEM relationships across Japanese and domestic motorcycle brands.
Technical Definition and Structural Segments
Motorcycle connectors are electromechanical interfaces engineered to transmit power and signals between subsystems, typically rated for 12-48V operation with IP67 or higher ingress protection against dust and water immersion. These components enable modular assembly, field serviceability, and system integration across internal combustion, hybrid, and fully electric powertrains. Waterproof connectors command premium positioning due to stringent reliability requirements in monsoon climates and off-road applications, while plug-and-play technology is gaining traction among aftermarket providers and custom builders seeking reduced installation complexity. Crimp technology still dominates OEM assembly lines where automated termination speeds and joint consistency justify capital equipment investment.
Regulatory Frame and Forward-Looking Close
China's MIIT enforces GB/T standards for electric motorcycle electrical safety, while Thailand's Industrial Standards Institute mandates TISI certification for connector assemblies used in domestic production. REACH and RoHS compliance in Europe restricts hazardous substances in connector plating and housings, reshaping material selection across export-oriented suppliers. Stakeholders must monitor how evolving electric motorcycle platform voltages redefine connector specification thresholds and qualification protocols.
Market Dynamics
High-voltage electrification of motorcycle platforms is forcing connector manufacturers to requalify component portfolios for 800V+ architectures while maintaining backward compatibility with legacy 12-48V systems. This voltage bifurcation is compressing development cycles and fragmenting procurement specifications across OEM electrification roadmaps.
Growth Catalysts
- GB/T Standard Tightening:China's MIIT mandates enhanced waterproofing and vibration resistance for electric two-wheeler electrical systems, compelling connector upgrades across domestic and export-oriented supply chains.
- Southeast Asian Manufacturing Expansion:Vietnam and Thailand production clusters are scaling motorcycle assembly capacity, concentrating connector demand in regional procurement hubs.
- Silicon Carbide Inverter Adoption:Power semiconductor transitions in electric powertrains necessitate connector redesigns for higher thermal cycling tolerance and electromagnetic compatibility.
Market Restraints
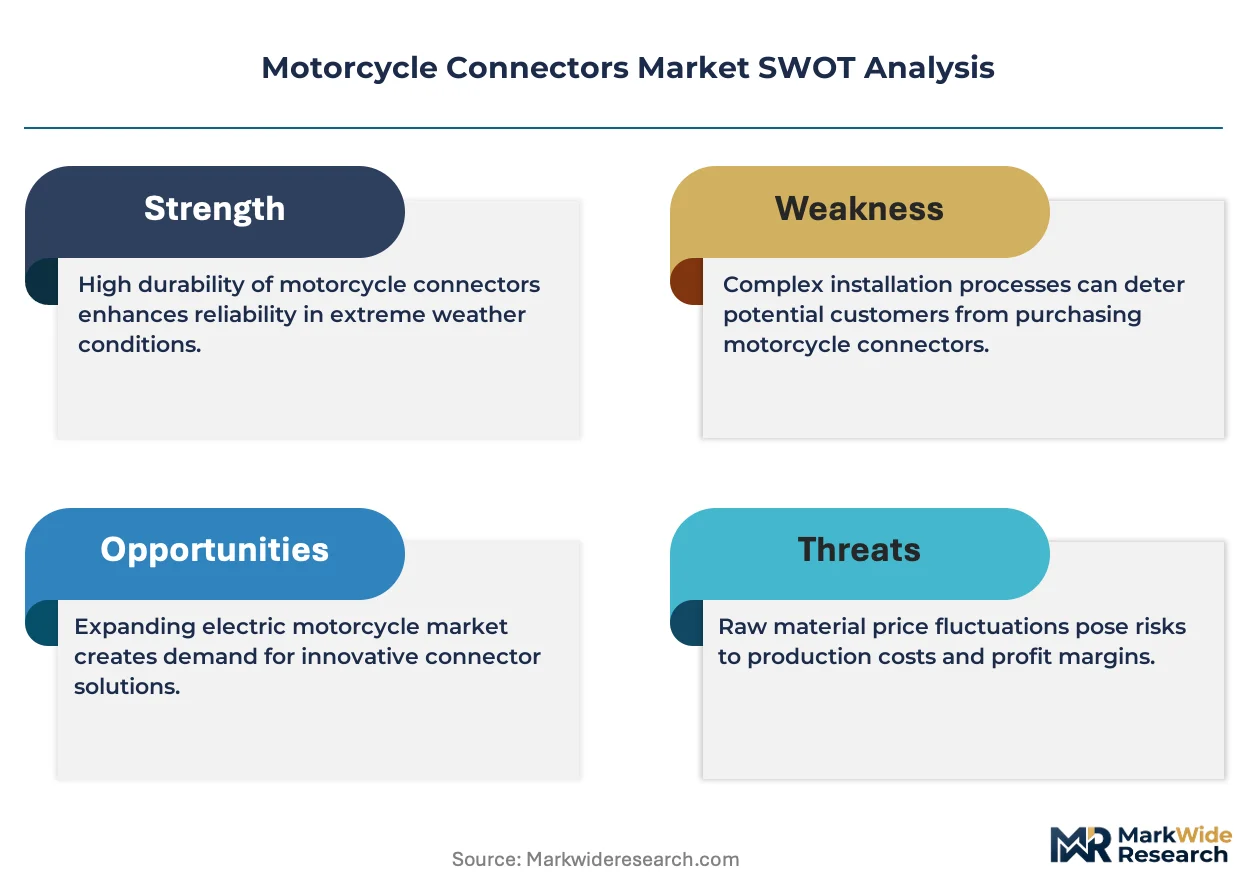
- Copper Price Volatility:Terminal and contact material costs fluctuate with commodity markets, squeezing margin structures for mid-tier connector suppliers.
- Japanese Supplier Concentration:Premium waterproof connector technology remains concentrated among established automotive-tier suppliers, limiting second-source options for cost-sensitive OEMs.
- Legacy Fleet Inertia:Internal combustion motorcycle parc longevity delays aftermarket connector refresh cycles, constraining replacement revenue streams.
Strategic Opportunities
- Indian Electric Two-Wheeler Subsidies:FAME-II incentive structures and state-level EV policies are accelerating domestic electric motorcycle production, opening connector procurement channels.
- Swappable Battery Interoperability:Gogoro and competing ecosystem standards create demand for standardized high-current connectors enabling cross-platform battery exchange networks.
- Modular Wiring Harness Platforms:Plug-and-play connector architectures reduce assembly labor and enable over-the-air configuration updates for software-defined vehicles.
Industry Challenges
- High-Voltage Safety Certification:IEC 60664 and UL 1977 qualification timelines extend 18-24 months for new connector families, delaying platform integration.
- Cross-Platform Pinout Standardization:OEM-proprietary connector configurations fragment volumes and prevent scale economies for component suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Motorcycle Connectors Market |
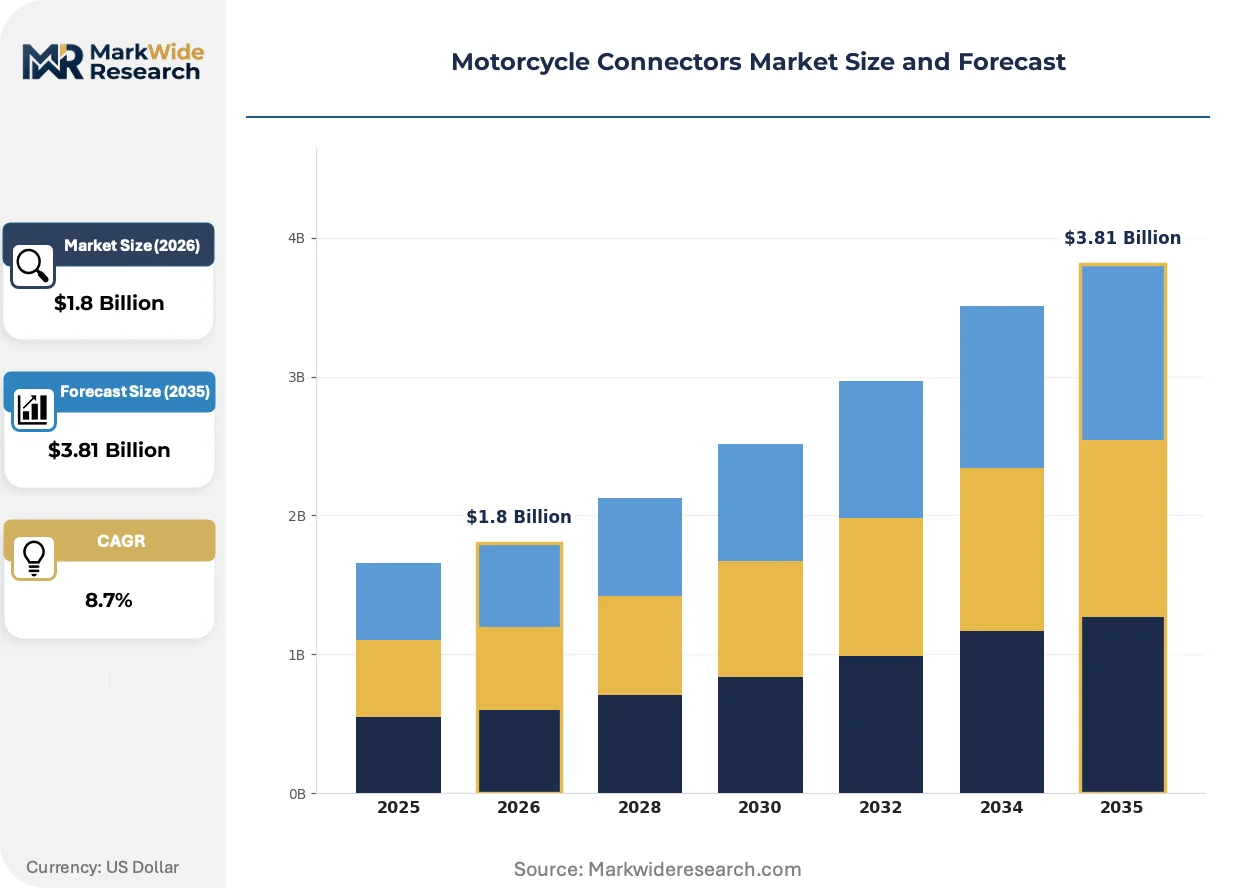
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wire Connectors, Circuit Connectors, Waterproof Connectors, Charging Connectors Technology: Crimp Technology, Solder Technology, Screw Technology, Plug-and-Play Technology End User: OEMs, Aftermarket Providers, Custom Builders, Repair Shops Feature: High Durability, Lightweight Design, Weather Resistance, Easy Installation |
| Companies Covered | TE Connectivity, Yazaki, Delphi Automotive, Sumitomo Electric Wiring Systems, Japan Aviation Electronics Industry, Hirose Electric, Hu Lane Associates, Korea Electric Terminal, Molex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Motorcycle Connectors Market Emerging Trajectories
Connector technology is bifurcating between legacy electromechanical designs and solid-state contact alternatives as electric motorcycle architectures demand higher power density. Material science advances and regulatory pressure on hazardous substances are simultaneously reshaping component specifications.
Sealed connector housings are migrating from traditional PA66 thermoplastics to bio-based polyamides and recycled-content polymers. European REACH compliance deadlines and OEM sustainability targets are accelerating this transition. Tier-one suppliers are qualifying halogen-free flame-retardant grades that maintain IP67 performance across -40°C to 150°C thermal envelopes.
China's GB/T 18487 and GB/T 20234 standards for electric motorcycle charging interfaces are mandating unified connector geometries and communication protocols. This regulatory harmonization reduces supplier qualification burden for domestic manufacturers while creating export compliance hurdles for foreign component makers. Southeast Asian assemblers importing Chinese electric platforms must adapt harness designs to these specifications.
Fleet operators and shared mobility providers are consolidating connector procurement through long-term supply agreements with technical assistance clauses. Direct OEM relationships are displacing traditional aftermarket distribution for high-volume electric motorcycle deployments. This concentration is most pronounced in Indonesian and Vietnamese ride-hailing electrification programs where total cost of ownership calculations dominate sourcing decisions.
Motorcycle Connectors Market Segmentation
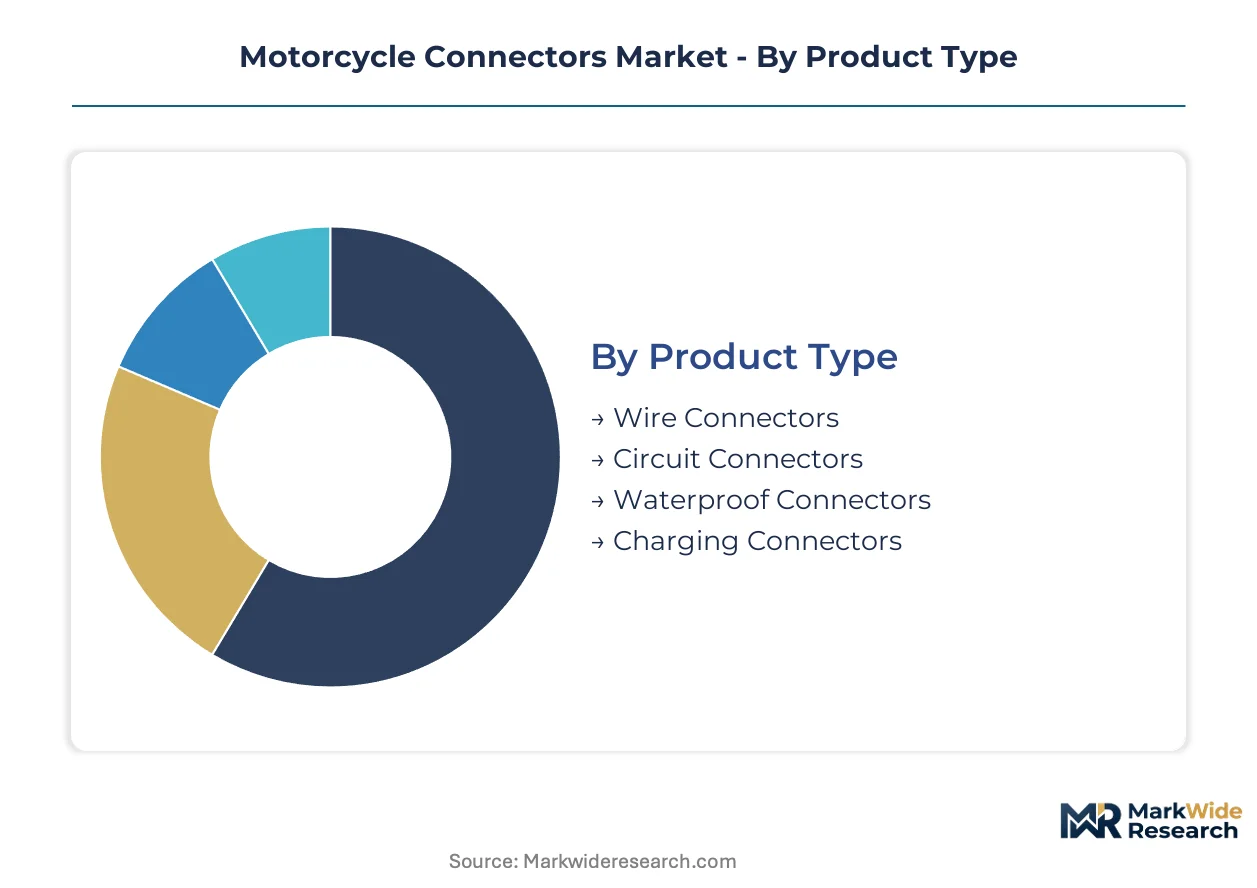
Segmentation in motorcycle connectors reveals distinct procurement rhythms across product categories. OEMs prioritize qualification-heavy waterproof designs with 24-36 month lifecycles, while aftermarket channels cycle through standard wire and circuit connectors on 6-12 month refresh schedules.
Product Type:
Replacement cycles vary dramatically by product type, with charging connectors turning over fastest as electric platform voltages evolve, while wire connector specifications remain stable across decades of internal combustion production.
- Wire Connectors:Multi-pin electromechanical interfaces terminating copper conductors with tin or gold plating, typically handling 12-48V distribution. Demand concentrates in Vietnamese and Thai wire harness assembly plants supplying Japanese motorcycle OEMs, constrained by copper price volatility and terminal crimp automation requirements.
- Waterproof Connectors:Sealed interfaces rated IP67 or higher with silicone gaskets and PA66 or bio-based polyamide housings. Expansion concentrates in Chinese electric two-wheeler programs where GB/T standards mandate enhanced ingress protection, driven by MIIT regulatory tightening and monsoon climate reliability requirements.
- Circuit Connectors:Board-level and inline connectors enabling signal transmission between control modules. Indian electric motorcycle startups under FAME-II subsidies drive procurement volume.
- Charging Connectors:High-current interfaces for battery charging infrastructure, subject to GB/T 18487 and GB/T 20234 standard harmonization. Southeast Asian assemblers importing Chinese platforms adapt harness designs to these specifications.
Wire connectors dominate installed base across internal combustion parc. Charging connectors are where expansion concentrates as electric motorcycle volumes scale.
Technology:
Cost structures separate automated OEM assembly methods from labor-intensive aftermarket and custom build techniques, with capital equipment requirements creating tiered supplier entry barriers.
- Crimp Technology:Mechanical compression termination creating gas-tight electrical joints via automated press systems. Thai and Vietnamese harness factories serving Japanese OEMs sustain demand, driven by joint consistency requirements and high-volume production economics.
- Plug-and-Play Technology:Tool-free mating interfaces with positive-locking mechanisms enabling field serviceability. Custom builders and aftermarket providers in European markets drive adoption, constrained by REACH and RoHS compliance deadlines reshaping housing material selection.
- Solder Technology:Metallurgical bonding via tin-lead or lead-free alloys, prevalent in repair shop environments and low-volume production.
- Screw Technology:Mechanical clamping termination allowing field-adjustable connections, common in custom builder applications requiring configuration flexibility.
Crimp technology commands OEM assembly line share. Plug-and-play interfaces are gaining share fastest in aftermarket and custom build channels.
End User:
Procurement concentration diverges between high-volume long-term supply agreements and fragmented spot purchasing, with fleet electrification programs consolidating formerly distributed demand.
- OEMs:Original equipment manufacturers specifying connector systems during platform development with 18-24 month qualification timelines. Chinese electric motorcycle producers under MIIT GB/T enforcement and Indian OEMs leveraging FAME-II incentives drive specification activity, constrained by IEC 60664 and UL 1977 certification delays.
- Aftermarket Providers:Distributors and retailers serving replacement and upgrade demand across legacy internal combustion parc. Indonesian and Vietnamese ride-hailing electrification programs consolidate procurement through direct supplier relationships, displacing traditional distribution.
- Custom Builders:Small-volume manufacturers and modification shops prioritizing configuration flexibility and reduced installation complexity.
- Repair Shops:Service providers replacing failed connectors in existing motorcycle fleets, constrained by legacy fleet inertia delaying refresh cycles.
OEMs dominate specification authority. Aftermarket providers are where procurement consolidation is concentrating through fleet operator direct agreements.
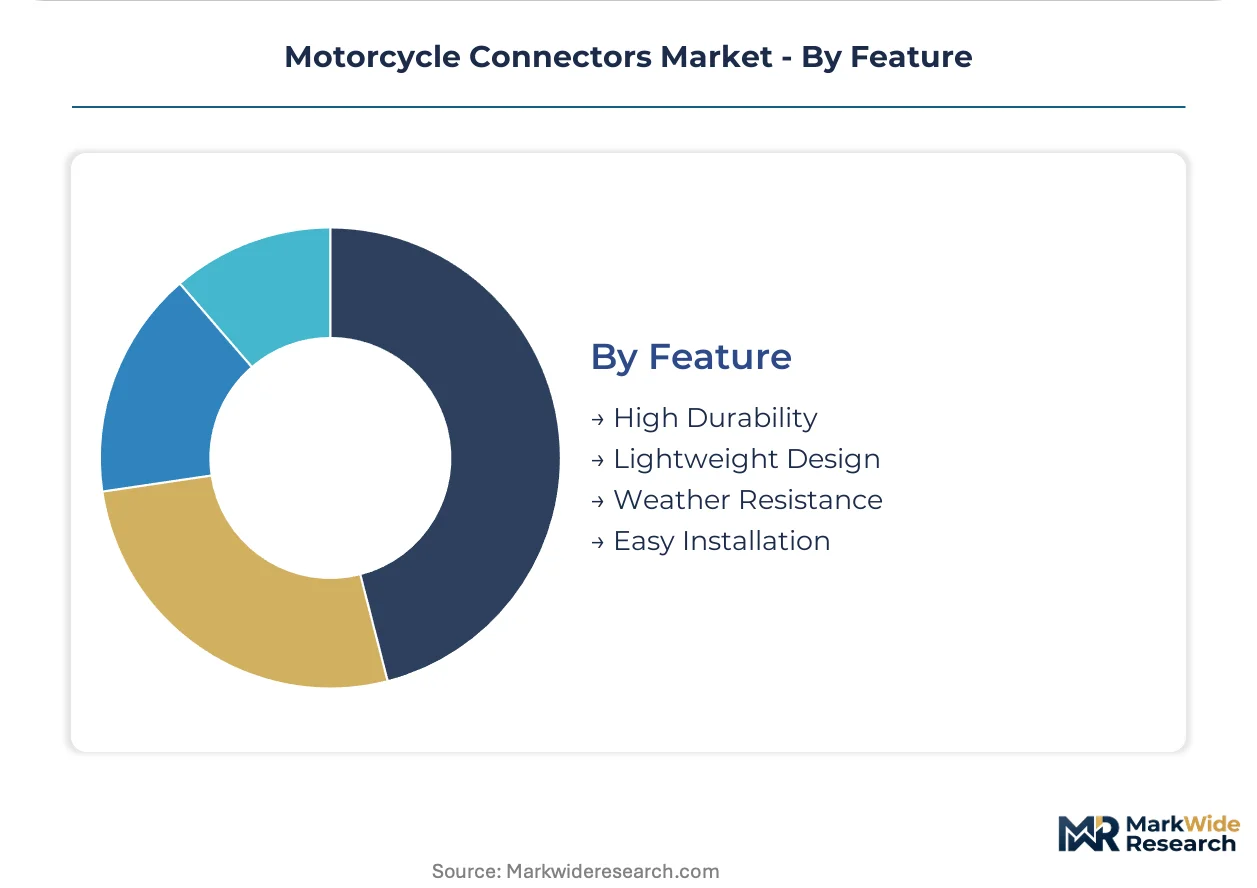
Feature:
Performance premiums align with application severity, with weather resistance and durability commanding price multiples over standard interfaces in exposed and high-vibration mounting locations.
- Weather Resistance:Sealed connector systems maintaining IP67 performance across thermal cycling from -40°C to 150°C with halogen-free flame-retardant housings. Chinese electric two-wheeler exports to Southeast Asian monsoon climates and European REACH-compliant markets drive specification, accelerated by bio-based polyamide material transitions.
- High Durability:Enhanced mechanical retention and contact normal force for high-vibration motorcycle applications. Off-road and adventure motorcycle segments in Thai and Vietnamese assembly prioritize these specifications.
- Lightweight Design:Miniaturized connectors with aluminum alloy housings or reduced-wall thermoplastics for performance motorcycle weight reduction.
- Easy Installation:Reduced-tool or tool-free mating features prioritizing service technician efficiency and field replaceability.
Weather resistance dominates premium positioning. High durability is where specification activity is climbing the fastest as electric platform voltages increase thermal and mechanical stress.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT's GB/T standards enforcement in China anchors regional demand trajectories, with connector procurement patterns radiating outward through Southeast Asian assembly networks and into export compliance frameworks.
China
Electric two-wheeler OEMs in Jiangsu and Zhejiang provinces are expanding high-voltage connector procurement for 800V architectures. MIIT mandates enhanced waterproofing under GB/T 18487 and GB/T 20234 standards, compelling component upgrades across domestic supply chains. The Yangtze River Delta manufacturing cluster concentrates connector qualification activity for export-oriented electric motorcycle platforms.
Vietnam
Japanese motorcycle OEMs operating assembly plants in Hanoi and Ho Chi Minh City sustain wire harness demand through Thai and Vietnamese wire connector procurement. The country's Ministry of Industry and Trade monitors TISI-aligned import standards for electrical components. The Northern Key Economic Region hosts expanding connector terminal crimping capacity serving regional motorcycle export programs.
Thailand
Yazaki's Thailand-based wiring harness operations anchor regional supply relationships across Japanese and domestic motorcycle brands. TISI certification requirements from the Industrial Standards Institute govern connector assemblies used in domestic production. The Eastern Economic Corridor concentrates electrification-focused connector specification activity as OEMs localize electric platform assembly.
India
FAME-II subsidy structures and state-level EV policies are accelerating domestic electric motorcycle production in Maharashtra and Tamil Nadu. BIS certification requirements shape connector material selection for export-oriented suppliers. The Chennai-Bengaluru industrial corridor hosts emerging connector procurement channels for electric two-wheeler startups.
Indonesia
Ride-hailing electrification programs in Jakarta and Surabaya are consolidating connector procurement through direct supplier relationships, displacing traditional aftermarket distribution. The national standardization agency's electrical safety frameworks influence component import specifications. The Jababeka industrial estate hosts expanding harness assembly capacity for domestic motorcycle brands transitioning to electric platforms.
Motorcycle Connectors Market Vendor Landscape
Capability concentration sits with established automotive-tier suppliers possessing high-voltage qualification expertise; scale advantage sits with regional specialists serving cost-sensitive wire harness assembly. The market structures around three tiers: premium waterproof connector specialists, mid-tier crimp technology providers, and emerging solid-state contact innovators. Dominant competitive moves include geographic expansion into Vietnamese and Thai manufacturing clusters and portfolio diversification toward 800V-compatible connector families.
Within the automotive heritage tier, TE Connectivity and Yazaki exemplify capability concentration through high-reliability design transfer into two-wheeler platforms. Among Asia-Pacific specialists, Japan Aviation Electronics Industry and Hirose Electric occupy positions in precision connector manufacturing. Sumitomo Electric Wiring Systems represents integrated harness-to-connector supply chain control. These archetypes illustrate how qualification timelines and OEM relationship depth create tiered competitive positioning.
| Leading Market Players |
|---|
| TE Connectivity |
| Yazaki |
| Delphi Automotive |
| Sumitomo Electric Wiring Systems |
| Japan Aviation Electronics Industry |
| Hirose Electric |
| Hu Lane Associates |
| Korea Electric Terminal |
| Molex |
| Others |
Supply Flow & Price Mechanics
The Yangtze River Delta freight corridor's container cost dynamics amplify supply concentration effects for motorcycle connector producers, compressing margin structures for mid-tier suppliers while enabling premium-tier manufacturers to sustain price differentiation through certification leverage and volume scale advantages.
Pricing Analysis
Chinese domestic prices for IP67-rated waterproof connectors run 15-25% below equivalent Japanese-manufactured units, a geographic spread that narrows when GB/T compliance and REACH-certified bio-based polyamide housings enter specification. Three-tier pricing structure across premium, standard, and economy levels dominates procurement, with TE Connectivity and Yazaki commanding brand premiums on 800V-qualified families while Vietnamese wire harness assemblers compete on crimp automation efficiency. Cost compression in standard wire connector tiers is intensifying because copper terminal volatility and Japanese supplier concentration limit second-source options. Fleet operators consolidating procurement through direct supply agreements exhibit lowest price sensitivity; aftermarket distributors serving legacy internal combustion parc face highest pressure.
Supply Chain Analysis
Dual-use technology export controls on precision crimping equipment and high-voltage testing apparatus constrain capacity expansion outside established manufacturing zones. Connector terminal and contact production concentrates in China, Japan, and Thailand, with PA66 and bio-based polyamide resin supply drawing from German and Chinese chemical producers. Single-source vulnerability sits with silicon carbide-compatible contact plating chemistries qualified to IEC 60664 standards. Distribution runs through Thai and Vietnamese wire harness assembly plants serving Japanese OEMs, with direct OEM relationships displacing traditional aftermarket channels for electric motorcycle programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric motorcycle platform electrification sits in early-cycle expansion, with FAME-II subsidies and GB/T regulatory tightening accelerating connector procurement velocity beyond internal combustion replacement rates.
For Market Incumbents: Insulate qualification-heavy portfolios by deepening captive supply of bio-based polyamide housings and expanding 800V test capacity in Thai manufacturing clusters. Solid-state contact alternatives from emerging semiconductor-tier suppliers threaten electromechanical incumbents; counter through accelerated IEC 60664 certification pipelines and exclusive supply agreements with Vietnamese harness assemblers. For New Entrants and Emerging Players: Indian electric two-wheeler startups under FAME-II incentive structures represent the most penetrable entry point for mid-tier waterproof connector specialists lacking legacy OEM relationships. Swappable battery interoperability standards for Gogoro-competing ecosystems create specification white-space for standardized high-current connector families. Lead with technical assistance clauses and localized BIS certification support to differentiate from established automotive-tier suppliers. For Investors and Strategic Acquirers: Regional specialists with integrated harness-to-connector capabilities and existing MIIT GB/T qualification relationships offer the strongest acquisition target archetype for exposure to Southeast Asian electric motorcycle electrification. Long-term viability hinges on 800V architecture transition timing; monitor silicon carbide inverter adoption rates in Chinese OEM roadmaps as the critical inflection signal for connector redesign demand.| Strategic Initiative | Industry Significance |
|---|---|
| 800V Architecture Qualification | IEC 60664 certification enables premium positioning in Chinese electric motorcycle OEM procurement. |
| Backward Integration into Bio-Based Polyamides | REACH compliance deadlines and OEM sustainability targets reshape material cost structures. |
| Thailand-Vietnam Manufacturing Expansion | Eastern Economic Corridor and Northern Key Economic Region concentrate harness assembly demand. |
| Swappable Battery Connector Standardization | Gogoro ecosystem interoperability creates cross-platform volume for qualified suppliers. |
| Fleet Operator Direct Supply Agreements | Indonesian and Vietnamese ride-hailing electrification consolidates formerly distributed aftermarket procurement. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of MIIT GB/T standard filings, TISI certification registries, and customs trade data for connector terminal and housing materials. Primary interviews engaged platform engineers at Chinese electric two-wheeler OEMs, procurement leads at Thai wire harness assemblers, regulatory affairs specialists tracking REACH and RoHS compliance, and fleet operations directors in Indonesian ride-hailing electrification programs. Secondary validation drew from BIS certification databases, FAME-II subsidy disbursement records, and IHS Markit motorcycle production data. Bottom-up connector demand modeling triangulated against top-down electric motorcycle volume projections across the analysis window.
Forecast inputs include electric motorcycle platform voltage evolution timelines, GB/T standard enforcement trajectories, and copper price volatility scenarios. Segmentation dimensions span product type, termination technology, end-user procurement channel, and regional regulatory cluster. CAGRs derive from installed base turnover analysis and new platform specification rates. Silicon carbide inverter adoption curves and swappable battery network deployment schedules inform electric-specific demand elasticity.
Practitioners should monitor MIIT GB/T standard revision cycles and FAME-II subsidy renewal negotiations for early signals of specification threshold shifts. Forecasts reflect assumptions regarding 800V architecture transition pacing and Southeast Asian manufacturing cluster expansion continuity. Material shifts in Chinese export control enforcement on precision connector manufacturing equipment would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
UK Automotive Carbon Fiber Composites Market
Vehicle Components
Idler Arm Market
Vehicle Components
LAMEA Vehicle Exhaust Hose Market
Vehicle Components
Wheelhouse Liner Market
Vehicle Components
Vehicle-To-X Products Market
Vehicle Components
Bicycle Chain Market
Vehicle Components
Truck Axle Market
Vehicle Components
Trailer Spindles Market
Vehicle Components
Automotive Rubber Molded Components Market
Vehicle Components
Passenger Air Brake Market
Vehicle Components
Towing Equipment Market
Vehicle Components
Global Automotive Wheel Bearings Market
Vehicle Components
Electric Forklifts Market
Vehicle Components
Car Radiator Market
Vehicle Components
Cross Roller Bearings Market
Vehicle Components
Global Boat Trailers Market