
 Mining Vehicle AC Kits Market | 2026-2036
Mining Vehicle AC Kits Market Size, Share, and Industry Trends Forecast 2026-2036
Mining Vehicle AC Kits Market Foresight
Underground mine operators are rotating toward climate-controlled cabin retrofits as open-pit fleet managers trim discretionary upgrade budgets. Robert Bosch GmbH leverages its automotive thermal heritage to compete in electrified mining vehicle architectures. DC Airco anchors Nordic underground mining demand with severe-duty refrigeration systems engineered for sub-zero ambient starts. DENSO CORPORATION extends its compressor technology leadership into hybrid-electric haul truck applications.
Mining vehicle AC kits integrate vapor-compression refrigeration circuits, hermetic scroll compressors, and corrosion-resistant condenser coils to maintain cabin temperatures between 20°C and 24°C in ambient conditions exceeding 50°C. Fixed kits dominate current installation volumes due to OEM integration mandates on new haul trucks and loaders, while hybrid kits represent the fastest-expanding category as diesel-electric powertrains proliferate. OEM sales channels capture the deepest margin pools through multi-year fleet supply agreements, though distributor sales sustain aftermarket replacement velocity for aging surface equipment fleets.
ISO 2631 whole-body vibration standards and MSHA heat stress thresholds shape product certification requirements for cabin thermal systems in North American underground operations. Australia's national mining regulator enforces mandatory cooling performance benchmarks that accelerate replacement timelines for surface haul truck fleets. Stakeholders must monitor autonomous vehicle thermal load profiles and evolving refrigerant phase-down schedules under the Kigali Amendment to anticipate specification shifts before next procurement cycles.
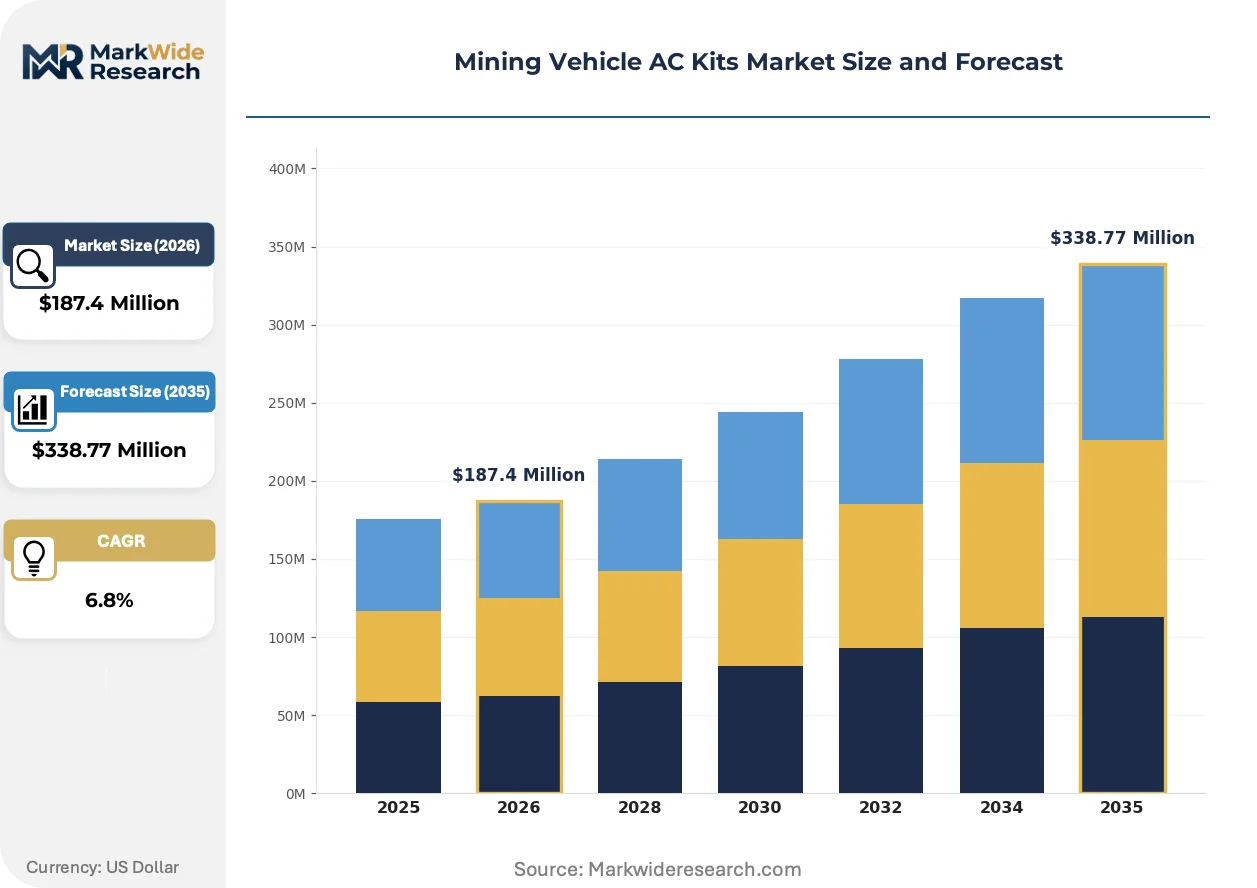
Market Dynamics
Fleet electrification and autonomous haulage deployment are compressing thermal management upgrade cycles as mining operators retrofit legacy diesel platforms while architecting new electric vehicle architectures.
Growth Catalysts
- ISO 2631 vibration compliance:Underground operators across Australia, Canada, and Chile are retrofitting climate-controlled cabins to meet whole-body vibration thresholds, accelerating replacement demand for aging surface fleet cooling systems.
- Heat stress mitigation mandates:Australia's national mining regulator enforces mandatory cooling performance benchmarks that intensify replacement timelines for Pilbara iron ore corridor haul trucks.
- Autonomous vehicle thermal loads:Sensor arrays and compute hardware on driverless haul trucks generate supplemental heat rejection requirements, expanding kit specifications beyond traditional cabin comfort parameters.
Market Restraints
- Refrigerant phase-down schedules:The Kigali Amendment's hydrofluorocarbon reduction timelines force premature obsolescence of existing compressor technologies before full depreciation cycles complete.
- Copper and aluminum price volatility:Condenser coil raw material costs swing with commodity markets, compressing margin stability for kit manufacturers locked into multi-year fleet supply agreements.
- Surface fleet budget trimming:Open-pit operators are deferring discretionary cabin upgrades amid iron ore price softness, elongating replacement cycles for non-mandated equipment categories.
Strategic Opportunities
- Western Australia's electrification corridor:The Pilbara region's simultaneous deployment of battery-electric and autonomous haul trucks creates demand for upgraded thermal management architectures with integrated battery cooling circuits.
- Aftermarket distributor channel expansion:Independent parts distributors are capturing replacement velocity for aging surface equipment fleets as OEM direct sales concentrate on new-build contracts.
- Sub-zero ambient start engineering:Nordic underground mining operations require severe-duty refrigeration systems engineered for cold climate reliability, opening specialized kit configurations beyond standard desert specifications.
Industry Challenges
- Refrigerant certification timelines:Next-generation low-global-warming-potential refrigerants require extended safety and performance validation before mine-site deployment, delaying product launches.
- Legacy fleet integration complexity:Retrofitting vapor-compression circuits onto decades-old haul truck platforms demands custom mounting fabrication and electrical system upgrades that extend installation downtime.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mining Vehicle AC Kits Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Kits, Fixed Kits, Hybrid Kits, Custom Kits End User: Mining Operators, Equipment Manufacturers, Maintenance Providers, Contractors Delivery Mode: Direct Sales, Distributor Sales, Online Sales, OEM Sales Installation Type: DIY Installation, Professional Installation, Onsite Installation, Remote Installation |
| Companies Covered | Robert Bosch GmbH, DC Airco, ZF Friedrichshafen AG, DENSO CORPORATION, Continental AG, Valeo, BorgWarner Inc, Subros Limited, Red Dot Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mining Vehicle AC Kits Market Shifts & Advancements
Thermal management architectures are bifurcating between legacy diesel retrofits and native electric vehicle designs, with refrigerant chemistry and compressor topology emerging as the primary axes of technical differentiation.
Scroll compressor technology is fragmenting across competing refrigerant chemistries as manufacturers hedge between R-454B and R-1234yf adoption timelines. Underground fleet managers in high-ambient jurisdictions are piloting dual-circuit systems that segregate cabin comfort from battery thermal regulation. This technical divergence is compressing standardization efforts and forcing kit suppliers to maintain parallel inventory pools.
The Kigali Amendment's hydrofluorocarbon phase-down mandates are accelerating refrigerant transition roadmaps across mining jurisdictions with strong environmental enforcement traditions. Equipment suppliers serving Western Australia and Chilean copper belts are pre-certifying low-global-warming-potential alternatives ahead of statutory deadlines. Compressor seal materials and lubricant compatibility are absorbing the bulk of re-engineering resources as the compliance window narrows.
Buying patterns are consolidating around multi-year fleet supply agreements that bundle AC kits with predictive maintenance telemetry. Surface mining operators in the Pilbara are unbundling after-sales service from hardware procurement, pressuring incumbent OEM channels. Independent distributors with regional parts stocking capabilities are capturing this disaggregated service demand.
Mining Vehicle AC Kits Market Segmentation
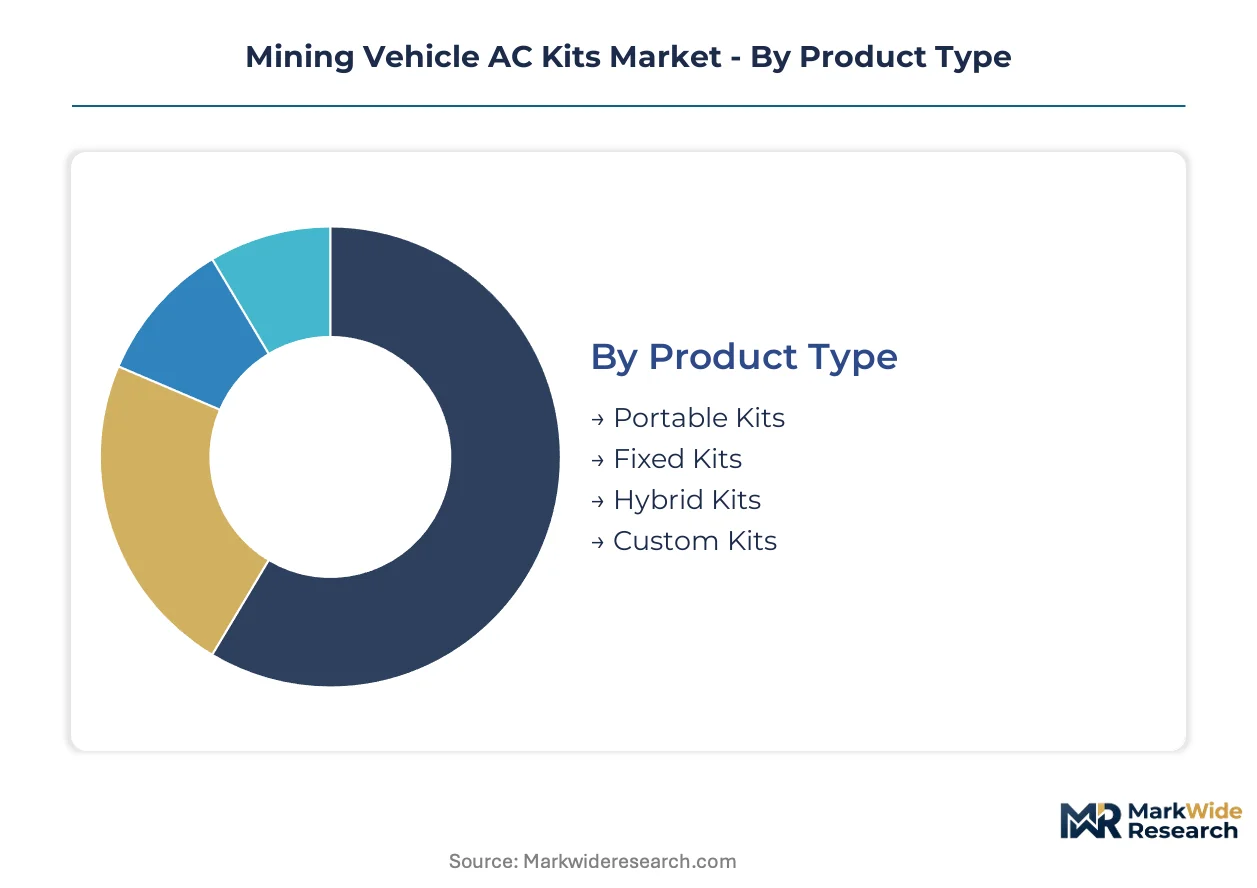
Thermal management architectures diverge sharply across mining operational models, with ISO 2631 compliance mandates and electrification timelines forcing distinct specification requirements by vehicle type and procurement channel. Segmentation clarity enables suppliers to align refrigerant transition roadmaps with customer upgrade cycles.
Product Type:
Regulatory differentiation separates portable retrofit solutions from integrated OEM systems, with refrigerant chemistry and compressor topology as the primary compliance variables.
- Fixed Kits:Factory-integrated vapor-compression circuits with hermetic scroll compressors and corrosion-resistant condenser coils dominate new-build haul truck specifications. OEM integration mandates on Australian and Chilean iron ore fleet replacements concentrate demand here, though Kigali Amendment refrigerant phase-downs force premature technology transitions before full depreciation cycles complete.
- Hybrid Kits:Dual-circuit architectures segregating cabin comfort from battery thermal regulation address autonomous vehicle sensor arrays and compute hardware heat loads. Western Australia's Pilbara electrification corridor drives fastest specification expansion as battery-electric and autonomous haul trucks deploy simultaneously.
- Portable Kits:Aftermarket retrofit solutions for aging surface equipment fleets with custom mounting fabrication requirements.
- Custom Kits:Severe-duty refrigeration systems engineered for sub-zero ambient starts in Nordic underground operations.
Fixed Kits handle the majority of throughput; Hybrid Kits are climbing the fastest on share.
End User:
Cost tier stratification separates multi-year fleet agreements from spot procurement, with compliance urgency determining budget allocation across operator categories.
- Mining Operators:Direct fleet owners in Australia's Pilbara and Chilean copper belts negotiate bundled hardware-service contracts with predictive maintenance telemetry. Australia's national mining regulator enforces mandatory cooling performance benchmarks that accelerate replacement timelines regardless of iron ore price softness.
- Equipment Manufacturers:OEMs integrating AC kits at assembly face refrigerant certification delays as next-generation low-global-warming-potential alternatives require extended safety validation before mine-site deployment.
- Maintenance Providers:Independent service contractors capturing disaggregated aftermarket demand as Pilbara operators unbundle after-sales service from hardware procurement.
- Contractors:Project-based mining services firms with discretionary upgrade budgets trimmed amid commodity price volatility.
Mining Operators command the deepest volume concentration; Maintenance Providers are gaining share fastest through distributor channel expansion.
Delivery Mode:
Margin structure varies dramatically by channel control, with captive OEM relationships yielding pricing power against fragmented distributor competition.
- OEM Sales:Multi-year fleet supply agreements with integrated manufacturers capture premium margins through specification lock-in on new-build haul trucks and loaders.
- Distributor Sales:Independent regional parts stocking sustains replacement velocity for aging surface equipment fleets as direct OEM sales concentrate on electrification contracts.
- Direct Sales:Manufacturer-to-operator relationships for large fleet retrofits with custom engineering requirements.
- Online Sales:Limited penetration for standardized components in remote procurement scenarios.
OEM Sales retain the highest margin pool; Distributor Sales are expanding most quickly in aftermarket replacement.
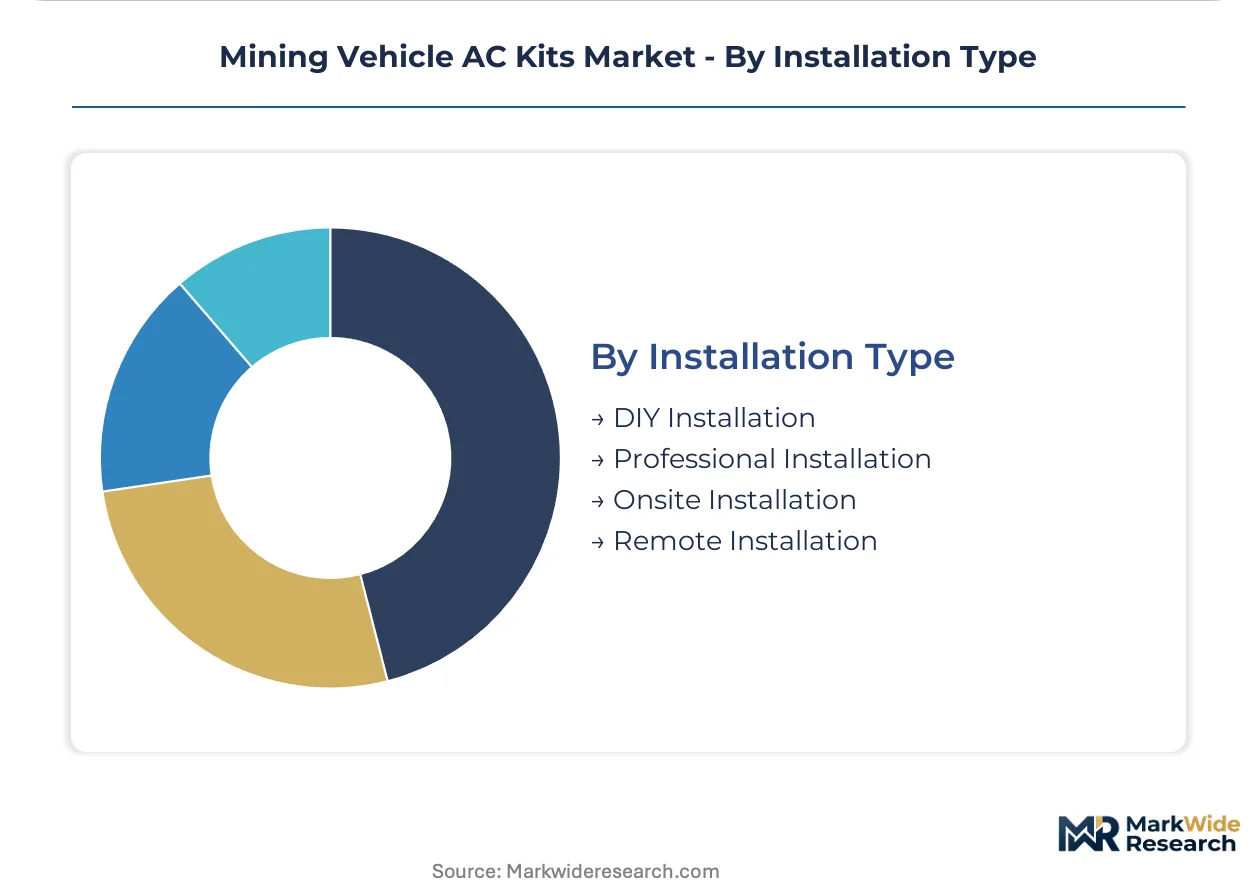
Installation Type:
Customer capability maturity determines installation economics, with downtime cost sensitivity favoring professional deployment over operator-managed retrofit.
- Professional Installation:Certified technician deployment minimizes downtime for production-critical haul truck fleets. Legacy fleet integration complexity demands custom mounting fabrication and electrical system upgrades that extend installation timelines without professional execution.
- DIY Installation:Standardized kit configurations for smaller loader and utility vehicle fleets with in-house maintenance capabilities.
- Onsite Installation:Mobile service teams deployed directly to Pilbara and Chilean mine sites for fleet-scale retrofit programs.
- Remote Installation:Telematics-guided self-install with virtual technician support for peripheral equipment categories.
Professional Installation manages the critical fleet volume; Onsite Installation is gaining traction fastest in remote mining jurisdictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australian mining vehicle AC kit exports flow primarily to Chilean copper operations and Indonesian coal fleets, establishing a transpacific trade corridor that shapes regional specification standards. This bilateral equipment movement concentrates procurement influence in Perth-based engineering offices and Santiago distributor networks.
Australia
Western Australia's Pilbara iron ore corridor drives fleet-scale electrification retrofits requiring upgraded thermal management architectures. The national mining regulator enforces mandatory cooling performance benchmarks that compress replacement timelines regardless of commodity price cycles. Perth engineering clusters coordinate multi-year supply agreements for autonomous haul truck deployments.
Chile
Atacama Desert copper operations generate sustained demand for severe-duty refrigeration systems in ambient conditions exceeding 50°C. Chile's environmental enforcement traditions align with Kigali Amendment phase-down schedules, accelerating refrigerant transition roadmaps. Antofagasta and Calama mining districts anchor distributor channel expansion for aftermarket replacement velocity.
Canada
Ontario and Quebec underground operations prioritize ISO 2631 vibration compliance through climate-controlled cabin retrofits. Provincial occupational health regulators enforce whole-body vibration thresholds that mandate thermal comfort system upgrades. Sudbury and Val-d'Or mining clusters concentrate professional installation demand for legacy fleet integration programs.
China
Inner Mongolia and Shanxi coal basins deploy domestic-manufactured AC kits for surface haul truck fleets amid electrification pilots. MIIT standards for mining equipment thermal management shape compressor specification requirements. Baotou and Taiyuan industrial zones concentrate OEM integration mandates for new-build loader production lines.
United States
Arizona and Nevada open-pit copper operations balance MSHA heat stress thresholds against discretionary upgrade budget constraints. OSHA workplace safety guidelines influence cabin comfort system procurement for underground limestone and salt operations. Phoenix distributor networks capture replacement demand for aging surface equipment fleets in the Southwest.
Mining Vehicle AC Kits Market Competitive Landscape
Player mix skews toward diversified automotive thermal specialists with mining-adjacent portfolios rather than pure-play mining equipment fabricators. Market structure concentrates around tiered supply relationships where OEM integration mandates favor multi-year fleet agreement holders. Two strategic archetypes dominate: automotive heritage players leveraging compressor technology scale, and severe-duty refrigeration specialists engineering for sub-zero ambient reliability. Competitive moves center on refrigerant certification pre-positioning ahead of Kigali deadlines and distributor channel expansion into Pilbara aftermarket replacement.
Within the automotive heritage tier, Robert Bosch GmbH and DENSO CORPORATION occupy positions exemplifying thermal management technology translation from passenger vehicle scale into electrified mining architectures. DC Airco represents the severe-duty specialization archetype, with its corporate identity signaling Nordic engineering orientation toward sub-zero climate reliability. These three company structures illustrate the bifurcation between volume-scale OEM integration and regional aftermarket service density.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| DC Airco |
| ZF Friedrichshafen AG |
| DENSO CORPORATION |
| Continental AG |
| Valeo |
| BorgWarner Inc |
| Subros Limited |
| Red Dot Corporation |
| Others |
Supply & Pricing Matrix
Kigali Amendment refrigerant phase-down schedules gate both supplier qualification and price differentiation simultaneously, compressing margins for manufacturers locked into legacy compressor technologies while rewarding early movers with low-global-warming-potential certifications. OEM integration mandates on Australian and Chilean new-build fleets concentrate pricing power with tiered kit configurations that bundle predictive maintenance telemetry.
Pricing Analysis
Current-generation R-410A systems, prior-generation R-134A retrofits, and next-generation R-454B/R-1234yf architectures command distinct price bands. Three-tier pricing structure across premium OEM-integrated, standard distributor-supplied, and economy portable retrofit levels reflects certification grade and after-sales bundling. Cost compression in the standard tier is intensifying because copper and aluminum price volatility swings condenser coil input costs. Contractors with discretionary upgrade budgets exhibit highest price sensitivity, while Pilbara mining operators under mandatory cooling benchmarks show lowest.
Supply Chain Analysis
Strategic stockpiling of hermetic scroll compressors and corrosion-resistant condenser coils dominates over just-in-time preferences given refrigerant certification delays and mine-site uptime requirements. Manufacturing concentrates in Germany, Japan, and China, with Australia and Chile serving as critical aftermarket distribution hubs. Raw material dependencies span copper and aluminum for heat exchangers, rare-earth magnets for compressor motors, and specialized lubricants for next-generation refrigerant compatibility. Single-source vulnerability around hermetic scroll compressor suppliers in Japan and Germany elevates disruption risk. Distribution runs through captive OEM channels for new-build fleets and independent regional distributors for aging surface equipment replacement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
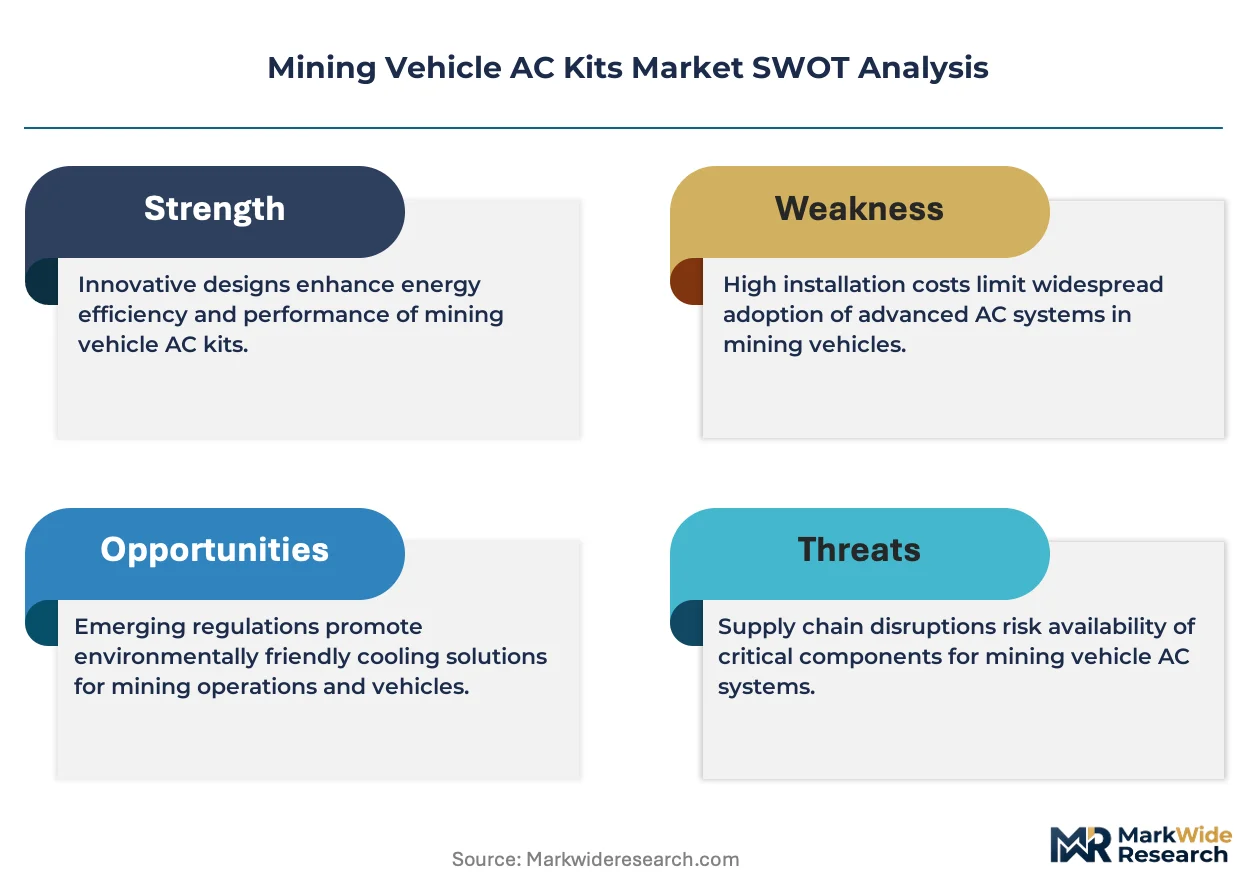
Incumbents face substitution pressure from electrified thermal management architectures that displace traditional vapor-compression circuits in battery-electric haul truck designs.
For Market Incumbents: Shield installed base revenue by accelerating low-global-warming-potential refrigerant pre-certification ahead of statutory deadlines, and deepen backward integration into condenser coil fabrication to offset copper and aluminum commodity volatility. Refrigerant transition timelines and emerging severe-duty refrigeration specialists in Nordic markets represent the dual threat vector. For New Entrants and Emerging Players: ISO 2631 vibration compliance fast-track for climate-controlled cabin retrofits in Canadian and Australian underground operations opens immediate qualification pathways. Target aftermarket distributor channel expansion in Western Australia's Pilbara corridor and Chile's Antofagasta mining district where maintenance providers capture disaggregated service demand. Lead with mobile onsite installation capabilities for fleet-scale retrofit programs. For Investors and Strategic Acquirers: Secondary-cycle assets sit with automotive heritage thermal specialists seeking mining-adjacent portfolio diversification beyond passenger vehicle scale. Five-to-ten year viability hinges on electrification architecture translation capabilities. Watch refrigerant certification completion rates as the inflection signal for next procurement cycle positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Pre-Certification Investment | Low-global-warming-potential alternatives ahead of Kigali Amendment deadlines secure OEM integration mandates in Australia and Chile. |
| Backward Integration into Coil Fabrication | In-house condenser coil production hedges copper and aluminum price volatility compressing margin stability. |
| Aftermarket Distributor Channel Expansion | Regional parts stocking capabilities capture replacement velocity as Pilbara operators unbundle service from hardware. |
| Sub-Zero Ambient Engineering Specialization | Sever-duty refrigeration systems for Nordic underground mining open premium pricing beyond standard desert specifications. |
| Predictive Maintenance Telemetry Bundling | Multi-year fleet supply agreements with sensor-based service contracts deepen customer lock-in against independent distributors. |
Research Methodology
Desk research of refrigerant phase-down regulatory filings, compressor technology patent databases, and mining fleet procurement records preceded structured interviews with thermal system engineering directors, aftermarket service managers at regional distributors, and procurement leads at Pilbara iron ore operators. Primary fieldwork with OEM integration teams and independent maintenance providers validated specification trends across the analysis window. Bottom-up kit shipment tracking and top-down mining capital expenditure analysis were triangulated for market sizing.
Variance decomposition across product type, end user category, and delivery mode dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level volume trajectories weighted by refrigerant transition timelines and electrification deployment schedules. Forecast inputs incorporated autonomous vehicle thermal load profiles and evolving ISO 2631 compliance mandates across Australian, Canadian, and Chilean jurisdictions.
Underlying assumptions cover stable copper and aluminum commodity price bands and Kigali Amendment enforcement consistency, with deviation risk concentrated in refrigerant certification delays and legacy fleet integration complexity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Europe Automotive Connectors Market
Vehicle Components
Global Wheel Tractor Scraper Market
Vehicle Components
Steering Gear Market
Vehicle Components
Aircraft and Marine Turbochargers Market
Vehicle Components
Wheelhouse Liner Market
Vehicle Components
Rail Wheel and Axle Market
Vehicle Components
Railroad Equipment Manufacturing Market
Vehicle Components
CV Brake Controls Market
Vehicle Components
Rolling Stock LED Lights Market
Vehicle Components
Trailer Terminal Tractor Market
Vehicle Components
2 Wheeler Fuel Injection System Market
Vehicle Components
Railway Brake Pads Market
Vehicle Components
Locomotive Lighting Batteries Market
Vehicle Components
Trailer Stabilizer Market
Vehicle Components
Vehicle Pillar Market
Vehicle Components
Bicycle Chain Tensioner Market