
 Latin America Automotive Connectors Market | 2026-2036
Latin America Automotive Connectors Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Automotive Connectors Market Intelligence
ISO 26262 functional safety certification is unwinding competitive access across the Latin America automotive connector supply base, forcing suppliers to demonstrate ASIL-rated design capabilities before qualifying for OEM programs. TE Connectivity leverages its captive cable assembly footprint to dominate high-voltage electric vehicle connector shipments into Mexican assembly plants. Yazaki Corporation anchors regional production through its Guadalajara manufacturing complex, sustaining just-in-time delivery contracts with Japanese transplant OEMs. Amphenol Corporation competes on sealed interconnect platforms engineered for the dust and humidity exposure common to Brazilian operating conditions.
Automotive connectors are electromechanical joining devices that establish signal and power pathways between vehicle subsystems, typically engineered to IP67 or higher ingress protection ratings and temperature thresholds exceeding 125°C to survive engine bay thermal cycling. Their primary commercial purpose is ensuring reliable electrical continuity across vibration-prone automotive environments while enabling modular assembly and service replacement. Wire-to-Board configurations command the deepest OEM integration given their role in linking sensor arrays to central control modules, while Wire-to-Wire assemblies retain aftermarket relevance where harness repair drives replacement demand. Electric Vehicles as an end-user category absorbs the most engineering-intensive connector variants due to high-amperage battery interconnect requirements and shielded data bus needs.
INMETRO, Brazil's national metrology institute, enforces compulsory certification for automotive electrical components, directly shaping product approval timelines and testing cost structures for suppliers targeting Mercosur markets. Mexico's NOM standards under the Secretariat of Economy align with USMCA technical provisions, creating dual-compliance obligations for connectors shipped to cross-border OEM supply chains. ANVISA, Brazil's health surveillance agency, intersects with automotive connector regulation where vehicle-integrated medical-grade monitoring systems require biocompatibility assessments. Stakeholders must monitor evolving alignment between Latin American electromagnetic compatibility standards and US EPA fuel-efficiency verification protocols, as emissions testing instrumentation demands increasingly sophisticated connector fidelity.
Market Dynamics
ISO 26262 functional safety certification is compressing supplier qualification timelines across Latin America, forcing connector manufacturers to demonstrate ASIL-rated design capabilities before securing OEM program approvals. This regulatory pressure is restructuring competitive access and concentrating procurement relationships around certified suppliers.
Growth Catalysts
- Electric vehicle production expansion:Battery assembly lines across Brazil and Mexico are scaling procurement of sealed high-voltage connector assemblies. OEMs are qualifying new supplier footprints to match localized EV manufacturing capacity.
- INMETRO certification mandates:Brazil's compulsory automotive electronics standards are tightening product qualification requirements and filtering out uncertified competitors from Mercosur supply chains.
- Wire-to-Board integration depth:Sensor-to-control module architectures in advanced driver-assistance systems are driving specification upgrades toward higher-pin-density configurations.
Market Restraints
- Copper and engineering resin volatility:Raw material input costs for terminal housings and conductive alloys fluctuate with commodity cycles, compressing margin stability for mid-tier suppliers.
- Supplier concentration in Guadalajara:Japanese transplant OEMs anchor procurement around captive regional production complexes, limiting market entry for independent connector manufacturers.
- IP67+ sealing cost premiums:Dust and humidity protection requirements for Brazilian operating conditions add manufacturing complexity and testing overhead versus standard industrial grades.
Strategic Opportunities
- Colombian assembly plant corridor:Underpenetrated Andean manufacturing zones present whitespace for connector suppliers as regional OEMs diversify production geography beyond the Brazil-Mexico axis.
- Shielded data bus convergence:Integration of high-speed Ethernet and power delivery into single connector housings is opening specification windows for hybrid interconnect platforms.
- USMCA alignment leverage:Mexico's NOM standards harmonization with US technical provisions creates dual-compliance product pathways for suppliers targeting cross-border OEM supply chains.
Industry Challenges
- ASIL-D functional safety engineering scarcity:Qualified hardware architects capable of fault-tolerant connector design for autonomous systems command premium compensation and extended recruitment cycles.
- INMETRO testing timeline compression:Extended certification queues at Brazilian national laboratories are delaying product launches and freezing working capital in pre-approval inventory.
- Legacy harness integration friction:New sealed interconnect platforms must maintain backward compatibility with existing vehicle electrical architectures without compromising ingress protection ratings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Automotive Connectors Market |
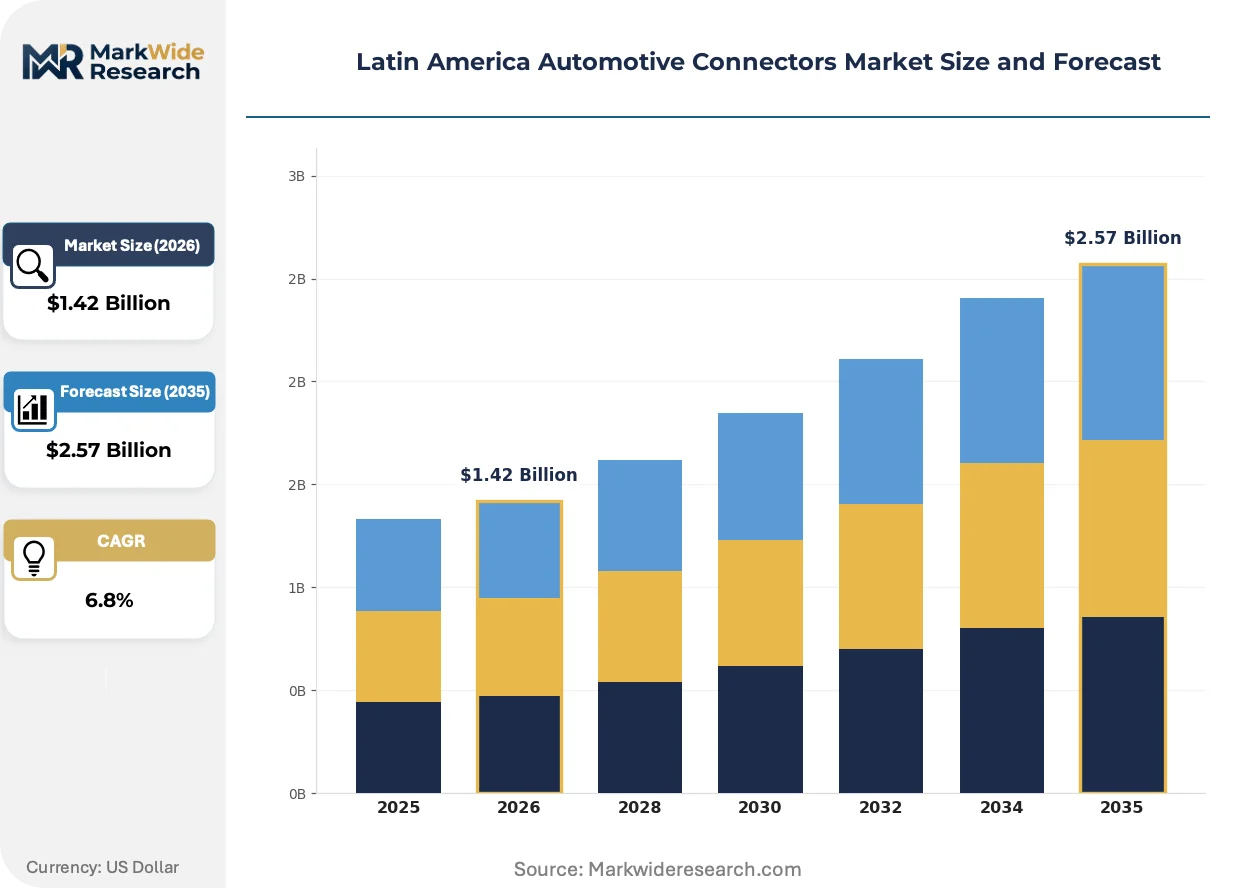
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
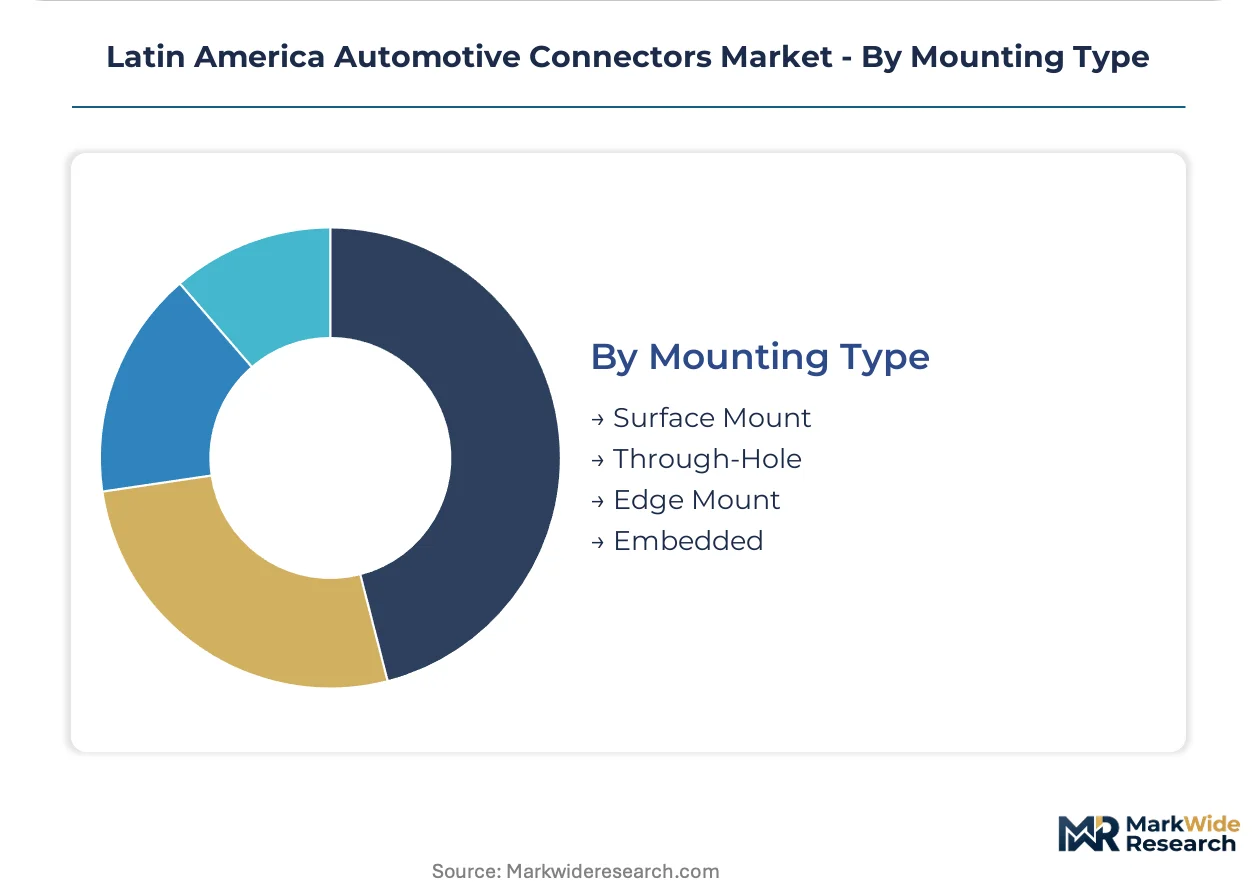
| Segmentation | Product Type: Board-to-Board, Wire-to-Board, Wire-to-Wire, Panel Mount End User: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Aftermarket Solutions Connection Technology: Crimping, Soldering, IDC, Compression Mounting Type: Surface Mount, Through-Hole, Edge Mount, Embedded |
| Companies Covered | TE Connectivity, Aptiv PLC, Amphenol Corporation, Yazaki Corporation, Molex Incorporated, Sumitomo Electric Industries, Ltd., Hirose Electric Co., Ltd., JST Manufacturing Co., Ltd., Kyocera Corporation, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Automotive Connectors Market Strategic Shifts & Innovations
High-voltage electrification architectures are decomposing traditional connector specification boundaries, forcing suppliers to merge power handling, data transmission, and thermal management into unified platform designs. Three interconnected developments are restructuring technical roadmaps and procurement criteria across Latin American OEM supply chains.
Modular high-voltage interconnect systems are decomposing discrete component sourcing strategies. These platforms consolidate battery-to-inverter, inverter-to-motor, and charging inlet functions into scalable housing families. Tier-1 harness suppliers in Mexican border states are adopting these systems to reduce SKU complexity and accelerate platform variants across multiple OEM programs. The technology is compressing supplier qualification cycles by enabling single-platform multi-vehicle certification.
INMETRO's evolving electromagnetic compatibility test protocols are extending automotive electronics approval timelines. The Brazilian regulator's alignment with US EPA emissions verification instrumentation standards is imposing stricter signal fidelity requirements on diagnostic connector interfaces. Suppliers targeting Mercosur markets are reengineering contact geometries and shielding topologies to meet tightened interference suppression thresholds.
Just-in-time delivery contracts are consolidating procurement authority at the assembly plant level. Tier-1 harness manufacturers are bypassing traditional distributor channels and contracting directly with connector producers for sequenced line-feed arrangements. This pattern is most visible in Guadalajara's Japanese transplant OEM ecosystem, where inventory ownership has shifted upstream to suppliers capable of hourly replenishment cycles.
Latin America Automotive Connectors Market Segmentation
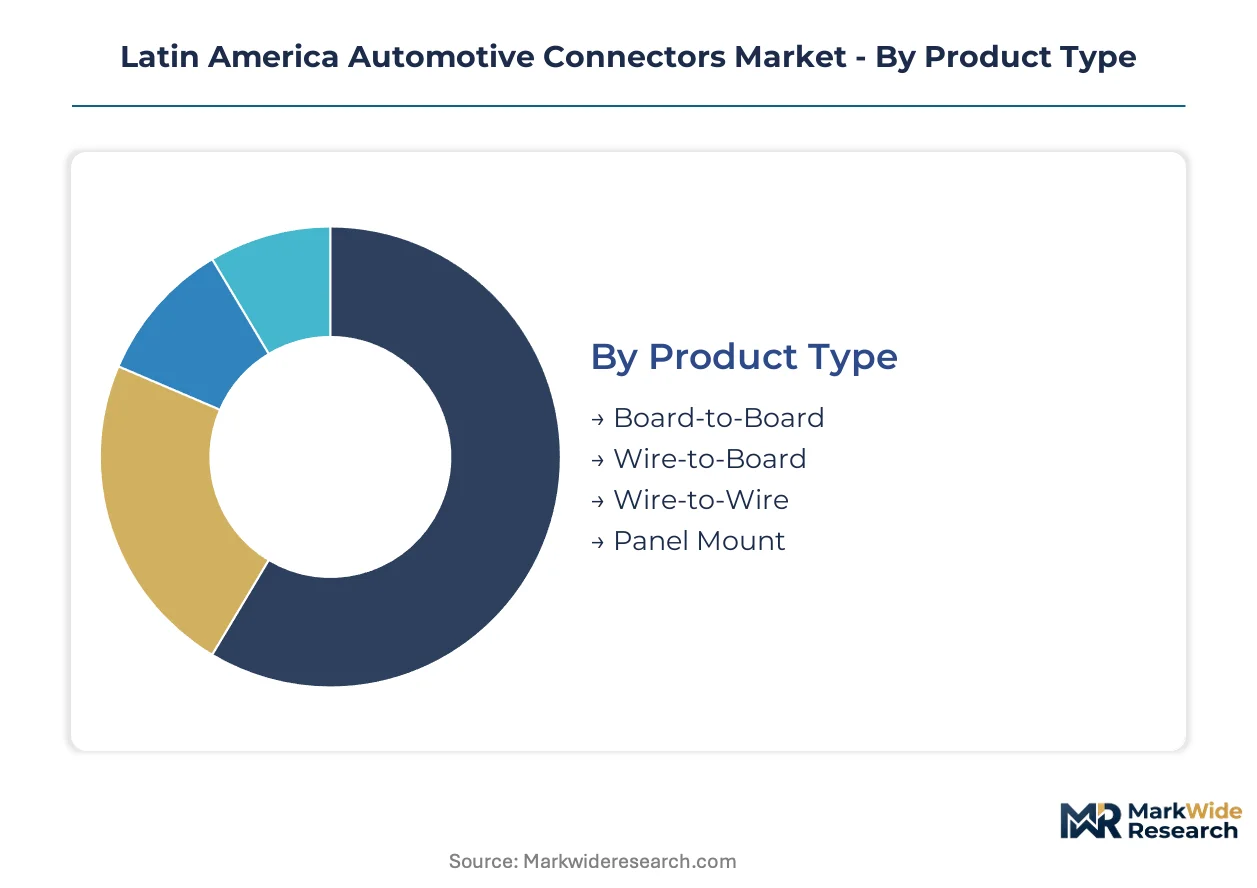
Connector specification boundaries in Latin America are dissolving as electrification architectures force cross-category engineering. Procurement teams now evaluate segments by their interoperability across high-voltage, data, and thermal functions rather than traditional mechanical classifications.
Product Type:
Wire-to-Board configurations face intensifying substitution pressure from modular high-voltage platforms that merge power and signal pathways into unified housings.
- Wire-to-Board:These assemblies link sensor arrays to central control modules through pin densities exceeding 100 positions. Mexican OEM assembly plants along the border states concentrate demand for these configurations as advanced driver-assistance systems proliferate across vehicle programs. INMETRO certification timelines for high-density variants are extending qualification cycles by forcing electromagnetic compatibility retesting.
- Wire-to-Wire:Harness repair applications dominate aftermarket demand for these field-serviceable joining devices. Brazilian independent service networks drive replacement volume given the country's extended vehicle operating lifespans and humidity-induced corrosion failures. Dust sealing specifications for these connectors must exceed IP67 ratings to survive Brazilian Cerrado and Pantanal operating conditions.
- Board-to-Board:Stacked PCB interconnects serve infotainment and telematics module integration.
- Panel Mount:Bulkhead penetration assemblies anchor charging inlet and diagnostic port functions.
Wire-to-Board anchors the volume base while Wire-to-Wire gains share at the steepest rate.
End User:
Cost tier segmentation separates engineering-intensive OEM supply from price-sensitive aftermarket procurement channels.
- Electric Vehicles:Battery interconnect demands amperage ratings exceeding 300A combined with shielded data bus integration. Brazilian and Mexican EV production lines are qualifying new supplier footprints as localized manufacturing capacity scales. High-voltage safety requirements under INMETRO mandates are filtering out legacy connector architectures from new platform approvals.
- Passenger Vehicles:Internal combustion programs still generate the deepest connector specification diversity across engine bay, cabin, and chassis zones. Guadalajara-based Japanese transplant OEMs sustain just-in-time delivery contracts that compress inventory cycles to hourly replenishment. Wire-to-Board configurations dominate sensor integration while sealed Wire-to-Wire assemblies retain chassis harness relevance.
- Commercial Vehicles:Heavy-duty cycling requirements prioritize vibration resistance and extended temperature ranges.
- Aftermarket Solutions:Repair channel demand concentrates on backward-compatible replacement interfaces.
Passenger Vehicles anchors the volume base while Electric Vehicles gains share at the steepest rate.
Connection Technology:
Application requirements dictate technology selection, with high-reliability end-uses imposing stricter process control than cost-driven segments.
- Crimping:Mechanical compression termination dominates high-volume harness manufacturing for its cycle speed and field serviceability. Mexican tier-1 suppliers have automated crimping lines to match sequenced line-feed contracts with Japanese transplant OEMs. Process validation under INMETRO standards requires destructive pull-force testing at production intervals.
- Soldering:Metallurgical bonding delivers superior electrical continuity for miniaturized electronics modules. Brazilian PCB assembly operations favor soldering for infotainment and telematics connectors where vibration exposure is minimal. Lead-free alloy transitions have complicated process windows and extended qualification timelines.
- IDC:Insulation displacement connectors serve rapid-assembly applications in lower-amperage signal pathways.
- Compression:Bolted interfaces anchor high-current battery and motor termination points.
Crimping anchors the volume base while Compression gains share at the steepest rate.
Mounting Type:
Supply concentration in Mexican electronics manufacturing clusters favors surface mount process compatibility.
- Surface Mount:Reflow-solderable terminations enable automated PCB assembly for telematics and sensor module integration. Guadalajara's electronics manufacturing services sector has concentrated surface mount capacity to serve Japanese transplant OEM supply chains. Miniaturization trends are pushing pin pitches below 0.5mm for advanced driver-assistance system controllers.
- Through-Hole:Mechanical lead retention delivers superior structural integrity for high-vibration engine bay applications. Brazilian commercial vehicle programs specify through-hole mounting for powertrain control modules exposed to extended thermal cycling. Manual assembly requirements limit cost reduction potential versus surface mount alternatives.
- Edge Mount:PCB perimeter termination serves high-density backplane and mezzanine applications.
- Embedded:Substrate-integrated connectors merge interconnect functions with structural electronics packaging.
Through-Hole anchors the volume base while Surface Mount gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
INMETRO certification mandates and USMCA technical alignment are reshaping procurement geography across Latin America. Brazilian EV incentives and Mexican border-state manufacturing expansion are redirecting connector demand toward certified supplier footprints.
Brazil
Battery assembly lines in São Paulo and Minas Gerais are scaling sealed high-voltage connector procurement. INMETRO's compulsory automotive electronics standards filter uncertified competitors from Mercosur supply chains. The ABC Paulista industrial corridor concentrates demand as OEMs localize EV platform manufacturing.
Mexico
Japanese transplant OEMs in Guadalajara sustain just-in-time delivery contracts compressing inventory cycles. NOM standards under the Secretariat of Economy align with USMCA provisions, creating dual-compliance obligations for cross-border shipments. Nuevo León's electronics manufacturing cluster anchors surface-mount connector capacity for telematics module integration.
Argentina
Automotive production stabilization in Córdoba and Buenos Aires provinces sustains wire-to-wire harness repair demand. The country's national automotive regulator maintains alignment with Mercosur technical standards. Rosario's industrial belt retains aftermarket connector consumption for extended-vehicle-lifecycle service networks.
Colombia
Andean manufacturing diversification is opening whitespace for connector suppliers beyond the Brazil-Mexico axis. The national standards body enforces electromagnetic compatibility protocols for automotive electronics imports. Bogotá's assembly plant corridor attracts tier-1 harness manufacturers seeking geographic risk distribution.
Chile
Copper mining fleet electrification is generating commercial vehicle connector demand for heavy-duty cycling applications. The national energy commission's EV adoption targets stimulate charging infrastructure component procurement. Antofagasta's mining equipment suppliers specify vibration-resistant interconnect platforms for desert operating conditions.
Latin America Automotive Connectors Market Key Industry Players
Player mix skews toward diversified electromechanical component conglomerates with captive cable assembly footprints. Market structure concentrates procurement authority around ASIL-certified suppliers capable of high-voltage platform engineering. Three archetypes dominate: integrated harness-connector producers, specialized sealed interconnect fabricators, and Japanese keiretsu-affiliated manufacturers. Competitive moves center on Guadalajara production complex expansion and INMETRO certification queue prioritization.
Among diversified electromechanical suppliers, TE Connectivity and Amphenol Corporation exemplify the integrated platform archetype, while Yazaki Corporation occupies a position within the Japanese keiretsu-affiliated tier. These three anchors represent distinct competitive vectors: TE Connectivity leverages captive cable assembly integration, Amphenol competes on sealed interconnect specialization for humidity-exposed environments, and Yazaki sustains just-in-time delivery contracts through Guadalajara-based production. Molex Incorporated and Sumitomo Electric Industries, Ltd. sit within the high-density miniaturization specialist tier, though the analysis focuses strategic commentary through the three primary anchors.
| Leading Market Players |
|---|
| TE Connectivity |
| Aptiv PLC |
| Amphenol Corporation |
| Yazaki Corporation |
| Molex Incorporated |
| Sumitomo Electric Industries, Ltd. |
| Hirose Electric Co., Ltd. |
| JST Manufacturing Co., Ltd. |
| Kyocera Corporation |
| Others |
Cost & Logistics Intelligence
Sequenced line-feed contracts with hourly replenishment cycles lock in supply access for Japanese transplant OEMs while compressing price visibility windows for connector suppliers serving Guadalajara assembly plants. These arrangements tether pricing power to inventory ownership transfer points and certification queue priority at INMETRO laboratories.
Pricing Analysis
Certification level under INMETRO and ISO 26262 ASIL ratings creates the primary spread between premium and standard connector tiers. Three-tier pricing structure across ASIL-D certified, ASIL-B compliant, and uncertified industrial grades dominates procurement negotiations. Cost compression in standard-grade wire-to-wire assemblies is intensifying because Brazilian aftermarket distributors consolidate purchasing volume. Aftermarket service networks exhibit highest price sensitivity, while OEM platform engineering teams prioritize certified supply security over unit cost.
Supply Chain Analysis
Mexico and Brazil anchor regional connector manufacturing, with Guadalajara concentrating high-volume harness assembly and São Paulo state hosting sealed interconnect fabrication for Mercosur markets. Copper alloy terminals and high-temperature engineering resins draw from global commodity markets, creating margin volatility for mid-tier suppliers. Single-source vulnerability concentrates around Japanese keiretsu-affiliated production complexes in Jalisco state. Distribution runs through Tier 1 harness manufacturers bypassing traditional distributor channels for OEM direct contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Latin America automotive connectors sit in early-cycle expansion as EV production localization across Brazil and Mexico accelerates platform qualification windows for certified suppliers.
For Market Incumbents: Shield ASIL-certified program positions by securing INMETRO queue priority and expanding captive cable assembly capacity in Nuevo León. Consolidation of sequenced line-feed contracts with Japanese transplant OEMs defends against emerging Korean connector manufacturers seeking Guadalajara footholds. Certification investment in high-voltage platform engineering represents the critical defensive lever. For New Entrants and Emerging Players: Anchor in Colombian Andean manufacturing corridors where OEM geographic diversification creates whitespace beyond Brazil-Mexico supply concentration. Underpenetrated EV charging infrastructure assembly and commercial vehicle electrification fleets in Chilean mining zones offer the most penetrable entry segments. Direct contracting with tier 2 harness assemblers bypasses keiretsu procurement lock-in. For Investors and Strategic Acquirers: Capital is best deployed toward ASIL-D capable engineering shops with INMETRO certification relationships and Mexican manufacturing presence. Long-term viability hinges on electrification content per vehicle expansion across Latin American OEM platforms. The signal to watch is INMETRO electromagnetic compatibility protocol alignment with US EPA emissions verification standards tightening signal fidelity requirements.| Strategic Initiative | Industry Significance |
|---|---|
| INMETRO Certification Queue Prioritization | Accelerates product launch timelines for Mercosur market access. |
| High-Voltage Platform Engineering Investment | Enables 300A+ battery interconnect qualification for EV programs. |
| Guadalajara Production Complex Expansion | Matches sequenced line-feed contracts with Japanese transplant OEMs. |
| Backward Integration into Cable Assembly | Captures margin from harness manufacturing consolidation trends. |
| Colombian Assembly Plant Corridor Entry | Diversifies geographic risk beyond Brazil-Mexico supply concentration. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across OEM platform engineering, Tier 1 harness procurement, aftermarket distribution, and INMETRO certification consulting roles. Primary fieldwork combined with secondary validation from vehicle production databases, customs trade records for copper alloy and resin imports, OEM supplier quality manuals, and SEC filings of listed connector manufacturers. Bottom-up segment sizing triangulated against top-down macro automotive production forecasts.
Across the analysis window, volume and value outputs reflect segmentation by product type, end-user category, connection technology, and mounting configuration, with propulsion architecture and regional production cluster as cross-cutting dimensions. CAGRs were derived from trend extrapolation of EV penetration rates and content-per-vehicle escalation for high-voltage interconnect platforms. Forecast inputs incorporated INMETRO certification timeline assumptions and USMCA technical alignment provisions.
Underlying assumptions cover EV production localization pace, copper price stability, and INMETRO laboratory capacity, with deviation risk concentrated in electromagnetic compatibility protocol evolution and Japanese OEM procurement consolidation. Recalibration cycles align with material shifts in Mercosur regulatory alignment and EV incentive program extensions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Bicycle Chain Market
Vehicle Components
Hooklift Trailer Market
Vehicle Components
China Automotive Carbon Fiber Composites Market
Vehicle Components
Passenger Air Brake Market
Vehicle Components
Off-Highway Diesel Engine Market
Vehicle Components
Charge Air Coolers Market
Vehicle Components
Trailer Terminal Tractor Market
Vehicle Components
Vehicle Exhaust Hose Market
Vehicle Components
Steering Column Cowls Market
Vehicle Components
Global Automotive Carbon Monocoque Chassis Market
Vehicle Components
Self Loading Trailer Market
Vehicle Components
Driveline Systems for Electric Vehicle Market
Vehicle Components
EGR Valve Market
Vehicle Components
Snowplows Market
Vehicle Components
Automotive Steering Shaft Market
Vehicle Components
Saudi Arabia Refrigerated Trailer Market