
 Electric Brake Actuator Systems for Passenger Vehicles Market | 2026-2036
Electric Brake Actuator Systems for Passenger Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Brake Actuator Systems for Passenger Vehicles Market Insights
A widening capital-intensity gap between integrated brake system architects and component specialists is reorganizing competitive tiers in electric brake actuator supply. Robert Bosch leverages captive semiconductor foundry partnerships to secure microcontroller supply for brake-by-wire modules. Continental sustains dual-source manufacturing footprints across Central Europe and Mexico to hedge logistics exposure. ZF Friedrichshafen anchors its position through integrated electro-hydraulic valve block production that tier-2 competitors cannot replicate.
Electric brake actuator systems for passenger vehicles are electromechanical or electro-hydraulic assemblies that translate electronic control signals into precise hydraulic pressure or mechanical clamping force at each wheel, typically operating with response latencies below 120 milliseconds to meet emergency braking protocols. These systems serve as the terminal execution layer in modern brake-by-wire architectures, replacing vacuum-assisted boosters and mechanical linkages in electrified powertrain vehicles where no engine vacuum exists. Electro-mechanical actuators now command the fastest expansion trajectory within product type categories, driven by their compatibility with regenerative braking blending algorithms. Brake-by-wire technology absorbs disproportionate engineering investment as OEMs eliminate hydraulic fluid circuits entirely, while the electric vehicle application segment concentrates margin pools due to mandatory integration with energy recovery systems and autonomous emergency braking mandates.
NHTSA Federal Motor Vehicle Safety Standard 135 governs stopping distance requirements that directly shape actuator torque specifications in the United States, while ECE R13-H under United Nations Economic Commission for Europe protocols defines electronic stability control performance thresholds that European homologation demands. China's MIIT embeds GB/T standards for electric vehicle braking energy recovery that dictate actuator duty cycles and thermal management thresholds for domestic-market certification. Stakeholders must monitor divergence between regional electromagnetic compatibility testing regimes, as divergent FCC and CE marking thresholds for brake control signal integrity threaten to fragment platform engineering costs.
Market Dynamics
Brake-by-wire platform standardization is compressing supplier tiers as OEMs consolidate actuator procurement under integrated system architects capable of delivering full electro-hydraulic modules rather than discrete components.
Growth Catalysts
- NHTSA FMVSS 135 mandates:Stopping distance requirements in the United States force actuator torque upgrades across light-duty vehicle fleets, pulling electro-hydraulic unit demand.
- Regenerative braking blending:Electrified powertrain architectures require actuators capable of seamless torque handoff between friction and energy recovery modes.
- Yangtze River Delta cluster:China's concentrated EV assembly base generates localized procurement volumes that sustain dedicated electro-hydraulic component ecosystems.
Market Restraints
- Semiconductor input volatility:Microcontroller supply constraints for brake control modules create production scheduling instability for tier-1 integrators.
- Central European supplier concentration:Valve block and electro-hydraulic component manufacturing clusters in Germany expose downstream assemblers to single-region logistics disruption.
- Mechanical fallback requirements:ECE R13-H homologation mandates redundant hydraulic circuits that brake-by-wire architectures must accommodate, adding engineering complexity.
Strategic Opportunities
- India passenger EV segment:Domestic OEM platform launches create first-mover positioning for electro-hydraulic actuator suppliers establishing local assembly footprints.
- Autonomous emergency braking mandates:European type-approval requirements for AEB systems expand addressable actuator volumes across compact and mid-size vehicle classes.
- Sensor-actuator convergence:Integration of wheel-speed sensing with clamping force generation enables module consolidation and value capture for integrated system architects.
Industry Challenges
- Embedded software certification:ISO 26262 functional safety validation for brake control algorithms extends development timelines and requires specialized automotive safety competence.
- Thermal management engineering:High-duty-cycle regenerative blending demands actuator designs capable of sustained thermal dissipation without performance degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Brake Actuator Systems for Passenger Vehicles Market |
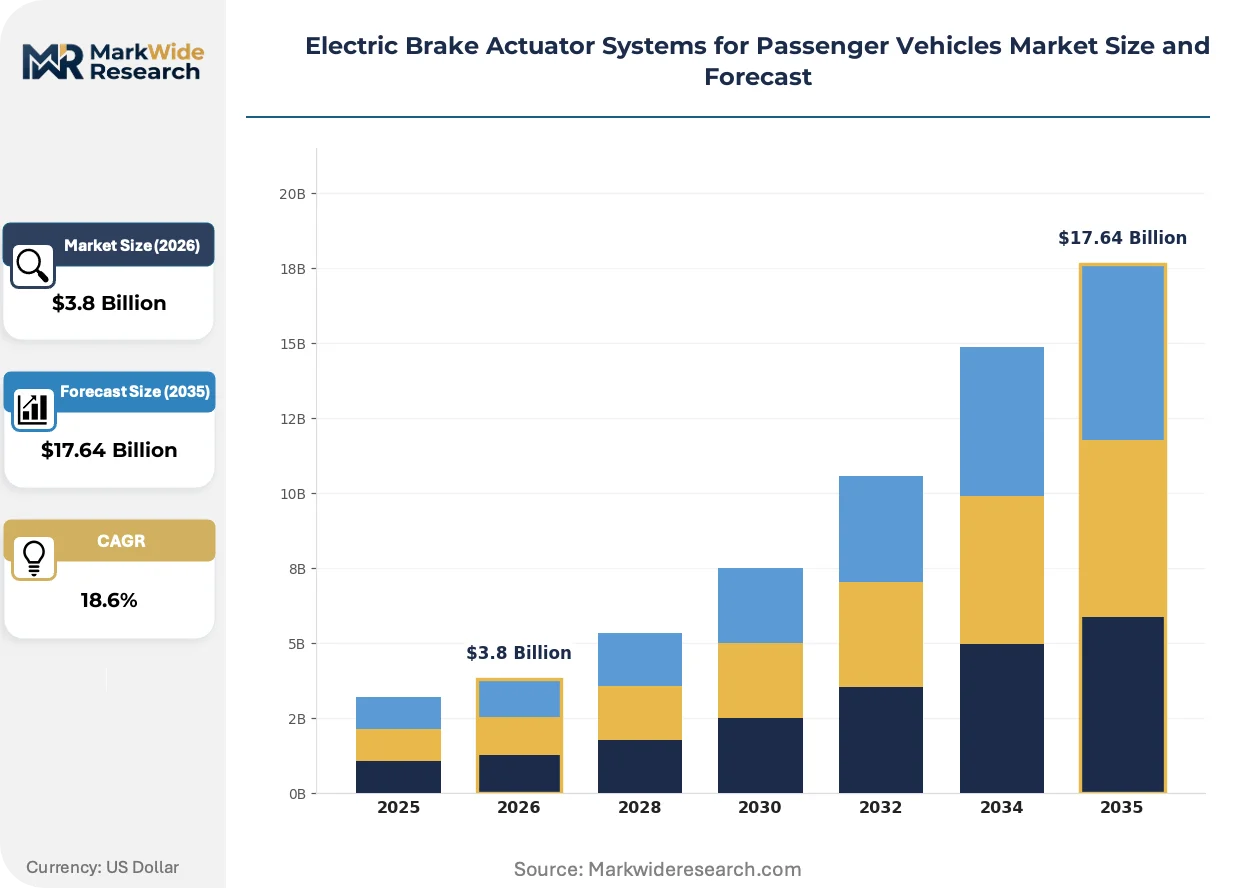
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic, Electro-Mechanical, Pneumatic, Electro-Hydraulic Technology: ABS, ESP, Brake-by-Wire, Regenerative Braking Application: Compact Cars, SUVs, Luxury Sedans, Electric Vehicles End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | Robert Bosch, Continental, Denso, Aisin, ZF Friedrichshafen, Brembo, Hitachi Astemo, Hyundai Mobis, HL Mando, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Brake Actuator Systems for Passenger Vehicles Market Trends and Innovations
Actuator architecture evolution is splitting competitive positioning between full-system integrators and component specialists, with technology choices determining margin capture potential across brake-by-wire transitions.
Electro-mechanical brake actuators is fragmenting the traditional electro-hydraulic dominant design by eliminating hydraulic fluid circuits entirely. Premium EV platforms from German and South Korean OEMs are adopting these units for weight reduction and maintenance simplification. This technology is fragmenting established supplier relationships as semiconductor-capable tier-1s capture module value previously held by hydraulic component specialists.
ECE R13-H electronic stability control thresholds are tightening actuator response latency specifications for European homologation. The regulation compresses allowable development validation cycles and forces hardware redesigns for platforms targeting EU type-approval. Brake-by-wire architectures face the steepest compliance burden as they must demonstrate fail-operational performance under single-fault conditions.
Fleet procurement of integrated brake systems is consolidating actuator sourcing under long-term platform supply agreements. Automotive OEMs are disintermediating discrete component distributors in favor of direct tier-1 relationships covering electro-hydraulic modules, software, and thermal management. This pattern concentrates most visibly in Japan, where keiretsu-affiliated assemblers prefer captive supply structures for critical safety systems.
Electric Brake Actuator Systems for Passenger Vehicles Market Segmentation
Segmentation in electric brake actuator systems reveals how procurement channels, technology roadmaps, and vehicle platform strategies intersect. Each dimension exposes different margin structures and competitive access points for suppliers.
Product Type:
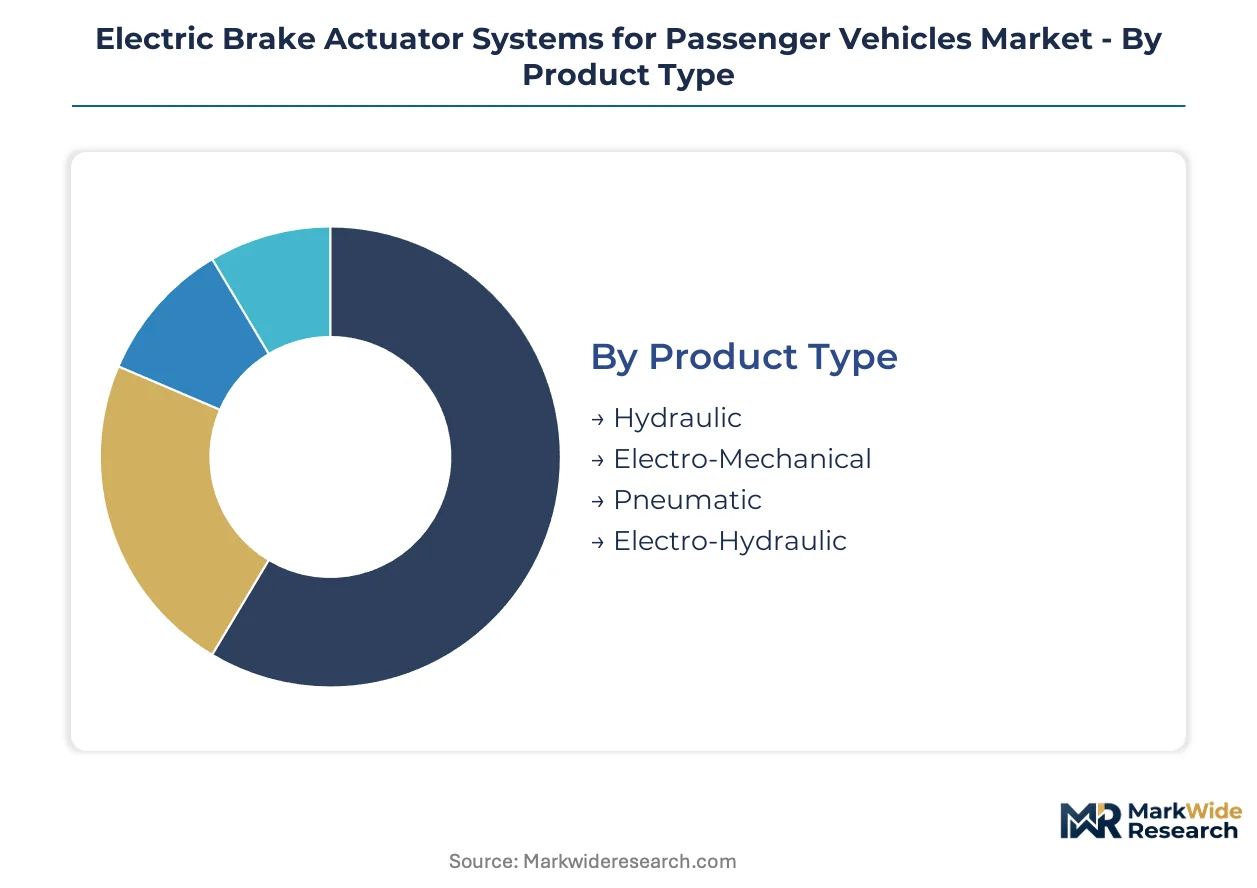
Channel flow varies sharply: electro-hydraulic units move through tier-1 system integrators to OEMs, while electro-mechanical designs increasingly ship direct to platform architects.
- Electro-Hydraulic:Combines electric motor-driven pumps with hydraulic valve blocks to modulate pressure at each wheel circuit. China's Yangtze River Delta EV assemblers source these heavily from domestic tier-1 suppliers due to GB/T energy recovery certification requirements.
- Electro-Mechanical:Eliminates hydraulic fluid entirely through motor-driven caliper clamping mechanisms. German and South Korean OEMs on premium EV platforms specify these units for weight reduction and maintenance simplification.
- Hydraulic:Traditional vacuum-boosted architectures persist in internal combustion fleet retrofits and emerging market price-sensitive segments.
- Pneumatic:Compressed-air actuation systems serve niche commercial-to-passenger vehicle conversions and specialty mobility applications.
By volume, electro-hydraulic leads. By growth pace, electro-mechanical is climbing the fastest.
Technology:
Cost tier stratification separates mature safety systems from emerging brake-by-wire investments that command engineering premiums.
- Brake-by-Wire:Fully electronic pedal-to-actuator signal transmission with no mechanical backup. NHTSA FMVSS 135 stopping distance mandates and ECE R13-H fail-operational requirements drive OEM platform commitments.
- Regenerative Braking:Integrated torque blending between friction and energy recovery modes. Mandatory on all China-market EVs under MIIT dual carbon compliance pathways.
- ABS:Anti-lock braking modules with wheel-speed modulation represent baseline homologation requirements across all passenger vehicle classes.
- ESP:Electronic stability control with yaw-rate intervention now required under EU type-approval and expanding to Indian compact vehicle mandates.
ABS dominates installed base. Brake-by-Wire shows the steepest expansion trajectory.
Application:
Volume concentration tracks electrification intensity, with platform scale determining actuator specification standardization.
- Electric Vehicles:Dedicated EV architectures require brake-by-wire or advanced electro-hydraulic units compatible with regenerative blending algorithms and autonomous emergency braking integration.
- SUVs:Higher mass and all-terrain duty cycles demand upgraded actuator torque specifications and thermal management capacity.
- Compact Cars:Cost-constrained segments prioritize ABS-ESP integration with minimal electro-hydraulic content.
- Luxury Sedans:Premium positioning enables full brake-by-wire adoption with redundant fail-operational architectures.
SUVs anchor current volume. Electric vehicles are gaining share fastest.
End User:
Supply concentration shapes procurement leverage, with tier-1 integrators capturing margin pools previously distributed across component specialists.
- OEMs:Direct platform specification authority over brake system architects, particularly in Japan's keiretsu-affiliated supply structures.
- Tier-1 Suppliers:Integrated system houses delivering electro-hydraulic modules, software, and thermal management under long-term agreements.
- Vehicle Assemblers:Contract manufacturers and emerging market joint ventures sourcing pre-validated brake system kits.
- Aftermarket Providers:Replacement actuator units for collision repair and fleet maintenance, constrained by embedded software calibration requirements.
Tier-1 suppliers lead procurement volume. OEM direct engagement is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in electric brake actuator systems tilt heavily toward surplus regions with integrated automotive semiconductor supply chains. Germany and South Korea run structural export surpluses in electro-hydraulic modules. The United States and China absorb the largest import volumes as domestic EV platform launches outpace local actuator capacity.
China
Domestic EV assemblers in the Yangtze River Delta cluster source electro-hydraulic units aggressively from local tier-1 suppliers. MIIT's GB/T standards for braking energy recovery dictate actuator duty cycles and thermal management thresholds for all China-market certification. Shanghai and Suzhou host concentrated electro-hydraulic component ecosystems serving BYD, NIO, and XPeng platform requirements.
Germany
Premium OEM brake-by-wire procurement anchors demand for fail-operational actuator architectures across Bavaria and Baden-Württemberg. KBA enforces ECE R13-H electronic stability control thresholds that compress allowable development validation cycles for EU type-approval. Stuttgart and Ingolstadt industrial corridors concentrate integrated brake system engineering competence for Mercedes-Benz, BMW, and Audi platforms.
United States
Detroit Three electrification programs pull electro-hydraulic unit imports from Central European and Mexican manufacturing footprints. NHTSA FMVSS 135 stopping distance mandates force actuator torque upgrades across light-duty vehicle fleets. Michigan and Ohio retain brake control algorithm development hubs despite module sourcing from offshore tier-1 integrators.
South Korea
Hyundai Motor Group and Kia platform standardization drives dedicated brake-by-wire supply agreements with captive tier-1 affiliates. MFDS-aligned vehicle safety frameworks incorporate UN ECE braking performance protocols for domestic and export market alignment. Gyeonggi Province and Ulsan host concentrated electro-mechanical actuator production serving Genesis and Ioniq dedicated EV architectures.
Japan
Keiretsu-affiliated assemblers prefer captive supply structures for critical safety systems, limiting foreign tier-1 penetration. METI's automotive safety technology roadmaps prioritize brake-by-wire fail-operational performance standards. Aichi Prefecture and Kanagawa maintain integrated brake system engineering clusters around Toyota, Honda, and Nissan technical centers.
Electric Brake Actuator Systems for Passenger Vehicles Market Competitive Landscape
Concentration sits with diversified automotive tier-1s capable of delivering full electro-hydraulic modules rather than discrete valve components. The supplier base organizes into three strategic tiers: integrated system architects with captive semiconductor partnerships, electro-hydraulic specialists with valve block manufacturing depth, and emerging electro-mechanical challengers exploiting brake-by-wire transitions. Competitive dynamics center on long-term platform supply agreements and backward integration into microcontroller supply chains.
Among German-based diversified suppliers, Robert Bosch, Continental, and ZF Friedrichshafen occupy positions as integrated system architects. Robert Bosch exemplifies the semiconductor-capable tier through captive foundry partnerships securing microcontroller supply. Continental represents dual-source manufacturing strategies spanning Central Europe and Mexico. ZF Friedrichshafen anchors the electro-hydraulic valve block production tier that smaller competitors struggle to replicate. Denso and Aisin from Japan sit within keiretsu-affiliated supply structures serving domestic OEM platforms with limited external procurement.
| Leading Market Players |
|---|
| Robert Bosch |
| Continental |
| Denso |
| Aisin |
| ZF Friedrichshafen |
| Brembo |
| Hitachi Astemo |
| Hyundai Mobis |
| HL Mando |
| Others |
Pricing and Supply Chain Analysis
Foundry-scale semiconductor partnerships at Robert Bosch and Continental create asymmetric cost structures that tier-2 valve block specialists cannot match, compressing price floors for electro-hydraulic modules while elevating entry barriers for brake-by-wire architectures. This scale concentration forces component-only suppliers toward niche aftermarket servicing or acquisition by integrated system architects.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across brake-by-wire platform supply agreements, with pricing stratifying across premium fail-operational architectures, standard electro-hydraulic modules, and economy-grade ABS-ESP integration tiers. Price differentiation centers on ISO 26262 functional safety certification grade and microcontroller integration depth. Cost compression in standard electro-hydraulic tiers is intensifying because Yangtze River Delta domestic suppliers are absorbing margin to secure platform share. Fleet procurement officers at volume OEMs exhibit highest price sensitivity, while premium German and South Korean platform engineers prioritize response latency performance over unit cost.
Supply Chain Analysis
Sixteen-week microcontroller lead times for brake control modules have forced tier-1 integrators into dual-source foundry arrangements and safety stock accumulation at Central European hubs. Manufacturing concentrates in Germany, China, and Mexico, with valve block machining and electro-hydraulic assembly drawing from precision casting feedstock in Bavaria and Guanajuato. Semiconductor input volatility represents the dominant structural risk, as single-source microcontroller dependencies threaten production scheduling stability. Distribution runs through captive tier-1 channels directly to OEM platform engineering teams, bypassing traditional component distributors for brake-by-wire content.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of ISO 26262-certified brake control algorithm engineers and captive semiconductor procurement relationships concentrates margin capture among integrated system architects, leaving component specialists vulnerable to platform consolidation.
For Market Incumbents: Secure microcontroller supply through foundry partnership extensions or in-house production of brake control ASICs to defend against emerging electro-mechanical challengers exploiting brake-by-wire transitions. Consolidate valve block manufacturing depth in Central Europe while adding Mexican dual-source capacity to hedge logistics exposure from single-region concentration. For New Entrants and Emerging Players: Anchor in India's passenger EV segment where domestic OEM platform launches create first-mover positioning for electro-hydraulic actuator suppliers establishing local assembly footprints. Target sensor-actuator convergence modules for compact vehicle autonomous emergency braking mandates as the most penetrable white-space, leveraging direct OEM engineering relationships rather than tier-1 distribution channels. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated brake system architects with long-term platform supply agreements spanning multiple vehicle generations. Long-term viability over the projection horizon favors semiconductor-capable tier-1s with backward integration into microcontroller supply chains. Monitor NHTSA brake performance mandate tightening as the critical inflection signal for accelerated brake-by-wire procurement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Semiconductor Supply Agreement | Captive foundry partnerships at Bosch secure microcontroller allocation ahead of tier-2 competitors facing allocation constraints. |
| Dual-Source Manufacturing Footprint | Continental's Central Europe-Mexico split hedges logistics disruption from German supplier cluster concentration. |
| Sensor-Actuator Module Integration | Wheel-speed sensing convergence with clamping force generation enables value capture previously distributed across component specialists. |
| Local Assembly Footprint Expansion | Dedicated electro-hydraulic production in India's passenger EV corridor captures platform procurement from emerging domestic OEMs. |
| ISO 26262 Certification Investment | Functional safety validation competence extends development timelines but locks out unqualified competitors from brake-by-wire sourcing. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across OEM platform engineering directors, tier-1 brake system procurement managers, semiconductor foundry account executives, and aftermarket distribution channel heads. Secondary validation drew from NHTSA FMVSS 135 regulatory filings, ECE R13-H type-approval databases, MIIT GB/T standard publications, and vehicle production registration data from IHS Markit. Bottom-up actuator unit demand estimates were triangulated against top-down OEM platform electrification spend projections.
Across the analysis window, forecasts were constructed through segment-level modeling of product type, technology architecture, vehicle application, and end-user procurement channel dimensions. CAGRs were derived from regression analysis of historical platform adoption curves applied to announced OEM brake-by-wire transition timelines. Key inputs included semiconductor supply constraint scenarios, regional homologation requirement divergence, and EV platform launch schedules by major automotive groups.
Decision-makers should treat outputs as directional under assumptions of continued NHTSA and ECE regulatory tightening and stable microcontroller supply normalization; material deviation in semiconductor allocation or mandate delay would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Digital Tire Inflator Market
Vehicle Components
Precision Bearing Market
Vehicle Components
Railway Vehicle Coupler Market
Vehicle Components
United States Automotive Connectors Market
Vehicle Components
Rail Components Market
Vehicle Components
Global Automotive Wheel Bearings Market
Vehicle Components
Global Automotive EGR Valves Market
Vehicle Components
Wheel Studs Market
Vehicle Components
Brake Hoses Market
Vehicle Components
Car Sunshade Market
Vehicle Components
Crash Lock Box Market
Vehicle Components
UK Automotive Carbon Fiber Composites Market
Vehicle Components
Autonomous Trains Components Market
Vehicle Components
HCV Suspension System Market
Vehicle Components
Ceramic Ball Bearings Market
Vehicle Components
Portable Wheel Jack Market