
 Global Automotive Carbon Monocoque Chassis Market | 2026-2036
Global Automotive Carbon Monocoque Chassis Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Carbon Monocoque Chassis Market Intelligence
Electric vehicle OEMs is rotating toward carbon monocoque architectures as range optimization becomes the dominant purchasing criterion for premium buyers. McLaren Automotive dominates track-proven composite manufacturing, leveraging decades of Formula One-derived autoclave expertise. Porsche anchors its Taycan and upcoming electric sports car lines with in-house carbon cell production at its Zuffenhausen facility. Ferrari competes through limited-series supercars where monocoque construction justifies seven-figure price positioning.
An automotive carbon monocoque chassis constitutes a single-piece structural shell fabricated from carbon fiber reinforced polymer prepreg layers, typically cured under heat and pressure exceeding 120 psi in autoclaves to achieve specific stiffness-to-weight ratios above 150 GPa per g/cm³, serving primarily to eliminate welded joints while reducing unibody mass by 30-40 percent versus aluminum-intensive architectures. Prepreg layup manufacturing technology leads current production volumes due to its established aerospace supply chain and predictable fiber orientation control, though resin transfer molding captures fastest growth as cycle times compress for electric vehicle scale. Sports cars and supercars occupy the mature margin pool where hand-layup tolerances justify premium pricing, while electric vehicles represent the structural demand shift where automated preforming must reconcile cost targets with crashworthiness validation.
The EU Green Deal's embodied carbon tracking requirements and ECHA REACH substance restrictions on epoxy resin hardeners are reshaping material qualification timelines for European suppliers, while EPA fuel economy standards and NHTSA crash safety protocols in the United States create divergent certification burdens for platform-global architectures. China's MIIT new energy vehicle technical guidelines and GB standards for passenger car structural integrity add a third regulatory vector that OEMs must navigate for market access. Stakeholders must monitor how rapidly evolving battery pack integration standards redefine load path requirements before committing to next-generation monocoque tooling investments.
Market Dynamics
Electric vehicle platform engineering is compressing monocoque development cycles as battery pack integration demands fundamentally reshape load path architecture and crashworthiness validation protocols.
Growth Catalysts
- EU Green Deal weight-reduction mandates:Embodied carbon tracking requirements and vehicle mass targets are compelling premium OEMs to specify carbon fiber structures for range optimization.
- Prepreg automation:Robotic fiber placement systems are reducing hand-layup labor content and enabling electric vehicle scale production without sacrificing fiber orientation precision.
- Stuttgart-to-Munich corridor:Germany's concentrated engineering ecosystem clusters tier-one composite suppliers adjacent to Porsche, Mercedes-Benz, and BMW development centers.
Market Restraints
- Autoclave capacity scarcity:Aerospace-grade autoclave availability constrains automotive expansion, with cure cycles exceeding six hours limiting throughput economics.
- Epoxy resin hardener restrictions:ECHA REACH substance limitations on aromatic amine curing agents are extending material qualification timelines by 18-24 months.
- Aluminum-intensive platform competition:High-pressure die-cast aluminum megacasting from Tesla and Volvo is achieving 15-20% weight savings at substantially lower capital intensity.
Strategic Opportunities
- Resin transfer molding scale-up:Out-of-autoclave processing is opening pathways to mid-volume electric vehicle architectures with sub-30-minute cycle times.
- MIIT new energy vehicle technical guidelines:China's structural integrity standards for battery electric platforms are creating certification pathways for imported composite chassis systems.
- Crash simulation convergence:Coupled finite element modeling linking composite damage mechanics with battery thermal runaway is reducing physical prototype requirements.
Industry Challenges
- Multiscale modeling talent scarcity:Composite damage prediction requires expertise spanning micromechanics, laminate theory, and vehicle-level crash simulation that outpaces university pipeline output.
- Battery integration load path redefinition:Evolving pack mounting standards and side-impact requirements force iterative monocoque redesign before tooling freeze.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Carbon Monocoque Chassis Market |
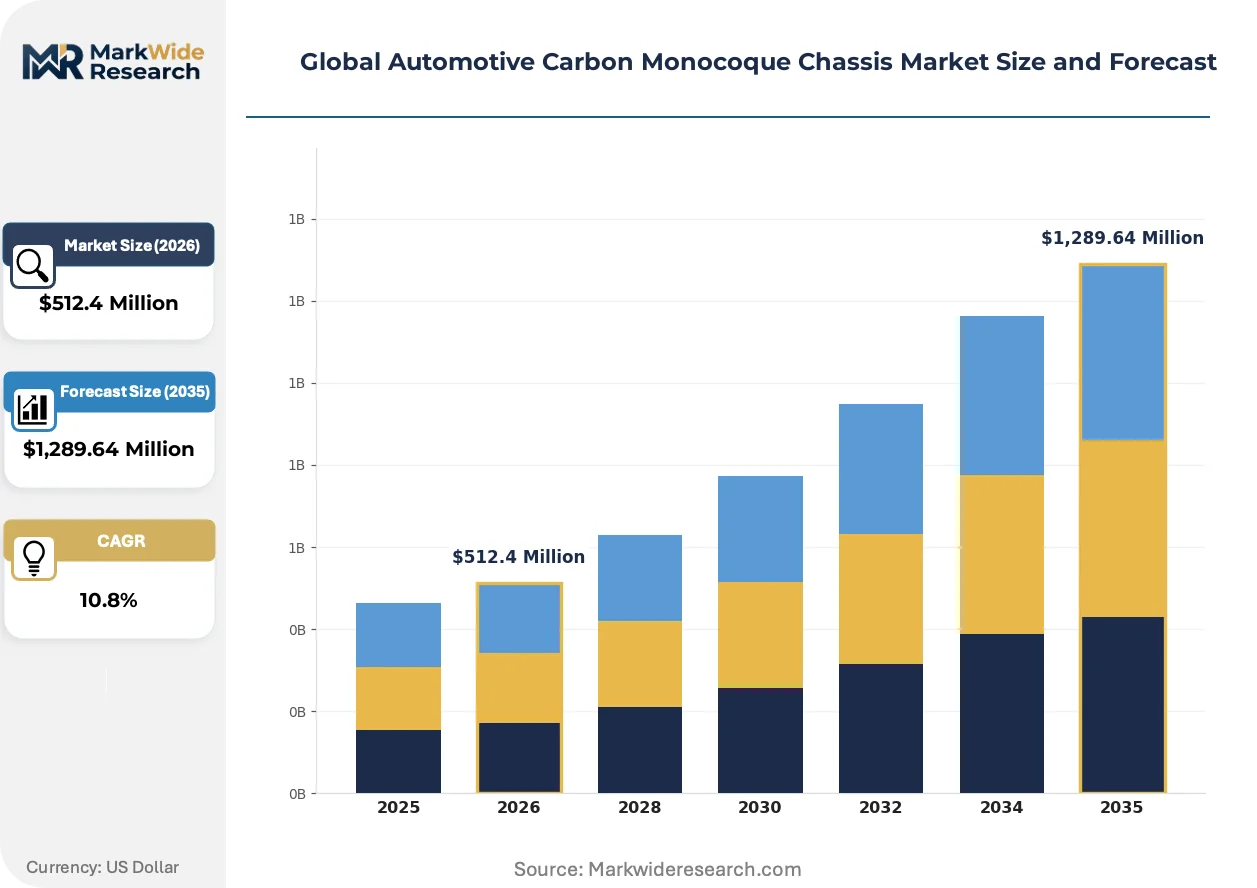
| Market Size in 2026 | $512.4 Million |
| Market Size in 2035 | $1,289.64 Million |
| CAGR (2026 – 2036) | 10.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Carbon Fiber Reinforced Polymer, Aluminum Composite, Steel Alloy, Titanium Composite, Magnesium Alloy Vehicle Category: Sports Cars, Electric Vehicles, Luxury Sedans, Supercars, Concept Cars Manufacturing Technology: Prepreg Layup, Resin Transfer Molding, Vacuum Bagging, Autoclave Curing, Filament Winding End User: OEM Manufacturers, Tier-1 Suppliers, Specialty Coaches, Vehicle Assemblers |
| Companies Covered | Porsche, Audi, McLaren Automotive, Lotus Cars, Dallara, Ferrari, Bayerische Motoren Werke AG, Koenigsegg Automotive AB, Lamborghini, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Carbon Monocoque Chassis Market Strategic Shifts & Innovations
Manufacturing technology trajectories are diverging between aerospace-heritage autoclave methods and automotive-scale out-of-autoclave processes, while regulatory tracking of embodied carbon reshapes material selection criteria.
Prepreg layup automation is bifurcating the manufacturing landscape. Established aerospace suppliers dominate hand-layup tolerance control for supercar volumes. Automated fiber placement and tape laying systems are penetrating electric vehicle programs where throughput requirements exceed 10,000 units annually. This technology division is compressing supplier margins in the mid-volume segment where neither manual nor fully automated economics achieve target costs.
ECHA REACH substance restrictions on epoxy hardener chemistries are forcing reformulation of qualified aerospace-grade resin systems. European suppliers must resubmit material safety dossiers for alternative aliphatic amine catalysts. Premium electric vehicle platforms targeting European type approval face extended validation schedules as new resin matrices undergo mechanical property characterization.
Buyer specification patterns are rotating toward embodied carbon disclosure requirements. Fleet procurement departments at German premium leasing companies now request cradle-to-gate carbon footprint documentation for chassis structures. This behavioral shift concentrates demand on suppliers with certified renewable energy manufacturing and recycled fiber feedstock integration, visible first in Stuttgart and Munich corporate fleet channels.
Global Automotive Carbon Monocoque Chassis Market Segmentation
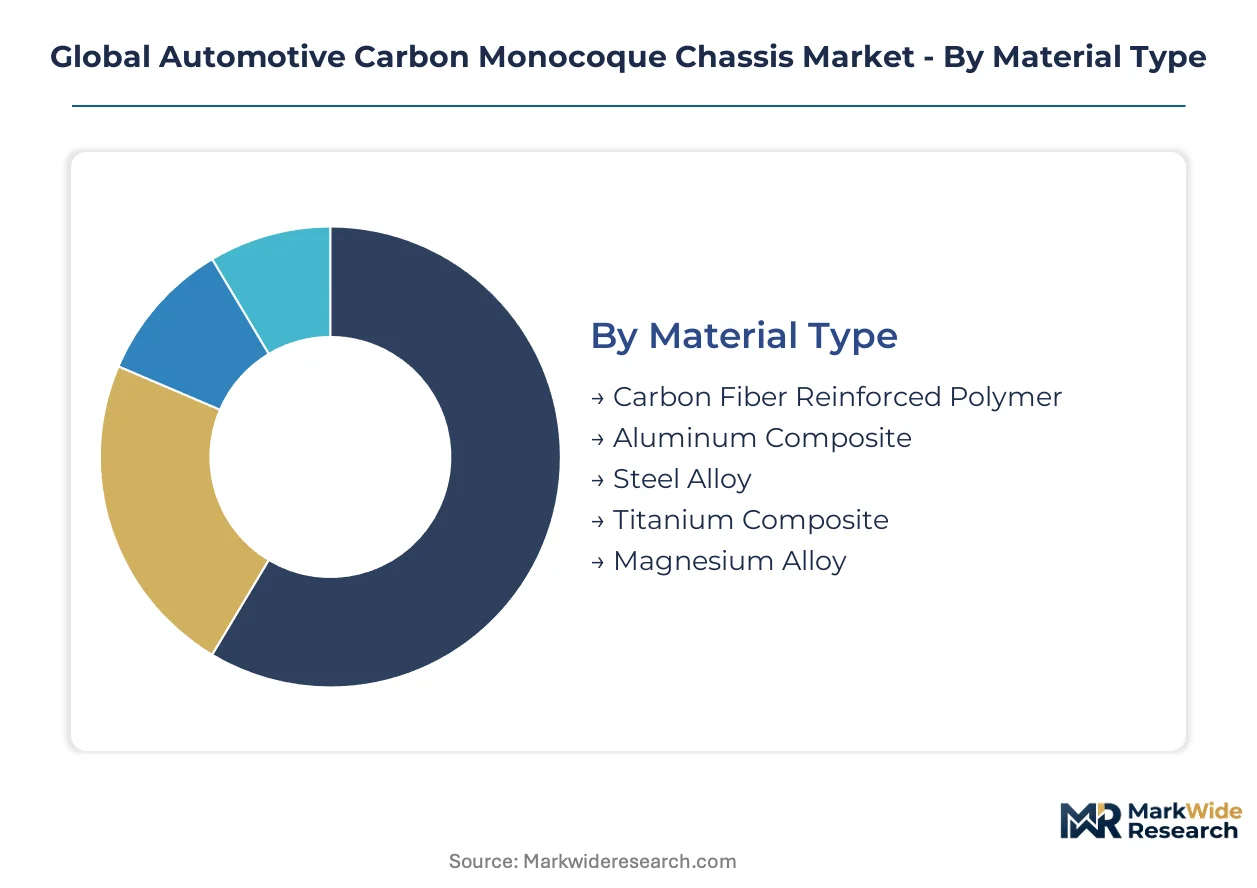
Carbon monocoque chassis procurement channels diverge sharply by segment, with aerospace-heritage suppliers dominating hand-layup supercar volumes while automotive-tier vendors capture electric vehicle scale through automated preforming. Understanding these flow patterns clarifies where margin pools concentrate and which technology transitions threaten incumbent positioning.
Material Type:
Channel economics separate aerospace-grade fiber suppliers serving autoclave programs from commodity resin compounders feeding out-of-autoclave automotive lines.
- Carbon Fiber Reinforced Polymer:Aerospace-grade T800 and T1000 fiber tows impregnated with toughened epoxy matrices deliver specific stiffness exceeding 150 GPa per g/cm³. Stuttgart and Munich OEMs specify these grades for European type approval, though ECHA REACH hardener restrictions extend qualification timelines. Demand concentrates in Germany's premium electric vehicle platforms where range optimization justifies unit costs.
- Aluminum Composite:Hybrid architectures combining carbon fiber skins with aluminum honeycomb cores reduce raw material costs while preserving torsional rigidity targets. Italian supercar assemblers in Modena favor this construction for limited-series production where crashworthiness validation budgets are constrained.
- Steel Alloy:High-strength martensitic grades with carbon fiber reinforcement patches serve cost-sensitive performance variants. Porsche deploys these selectively in non-structural tub sections at Zuffenhausen.
- Titanium Composite:Ti-6Al-4V matrix systems with silicon carbide fiber reinforcement target extreme thermal environments. McLaren Automotive evaluates these for battery pack proximity structures in track-focused derivatives.
- Magnesium Alloy:AZ91D and WE43 castings with carbon fiber overmolding address NVH-critical floor pan sections. BMW sources these from Austria's concentrated magnesium processing corridor.
By volume, carbon fiber reinforced polymer leads. By growth pace, aluminum composite is ahead.
Vehicle Category:
Application maturity separates decades-proven motorsport architectures from battery electric platforms still defining load path standards.
- Sports Cars:Mid-engine layouts from Porsche and McLaren established monocoque manufacturing tolerances now codified in ISO 12407. These programs sustain hand-layup supplier ecosystems through predictable annual volumes.
- Electric Vehicles:Skateboard platforms with integrated battery housings demand redesigned crash structures and side-impact load distribution. China's MIIT technical guidelines and GB standards create compliance pathways for imported composite systems.
- Luxury Sedans:Four-door architectures from Mercedes-Benz and BMW incorporate carbon tubs selectively in roof and floor sections rather than full monocoque construction.
- Supercars:Ferrari and Lamborghini limited-series programs justify seven-figure pricing through visible carbon fiber craftsmanship and FIA-derived safety cell engineering.
- Concept Cars:Design study vehicles from OEM advanced studios consume prototype prepregs with minimal recyclability constraints.
Sports cars anchor current revenue. Electric vehicles are climbing the fastest.
Manufacturing Technology:
Capital intensity and cycle time tradeoffs determine which processes serve which volume tiers.
- Prepreg Layup:Automated fiber placement systems deposit resin-impregnated tapes with ±3° angular precision, enabling electric vehicle scale without sacrificing laminate quality. BMW's Landshut facility operates the largest automotive AFP installation in Europe.
- Resin Transfer Molding:Closed-mold injection of thermoset resins into preformed fiber stacks achieves sub-30-minute cycle times. This process is expanding most quickly as Chinese electric vehicle OEMs seek European supplier partnerships.
- Vacuum Bagging:Atmospheric pressure consolidation of wet layups serves prototype and repair applications where autoclave access is unavailable.
- Autoclave Curing:Supercar and motorsport programs maintain six-hour cure cycles at 180°C and 120 psi to achieve aerospace-grade void content below 1%.
- Filament Winding:Continuous fiber deposition around mandrels produces drive shafts and structural columns with optimized hoop strength.
Prepreg layup commands installed capacity. Resin transfer molding shows steepest expansion trajectory.
End User:
Procurement authority concentration varies from integrated OEM engineering centers to fragmented specialty vehicle assemblers.
- OEM Manufacturers:Porsche, McLaren, and Ferrari maintain captive composite manufacturing for intellectual property protection and design iteration speed.
- Tier-1 Suppliers:Germany's SGL Carbon and Italy's Automobili Lamborghini supply composite structures to multiple OEM platforms under long-term frame contracts.
- Specialty Coaches:Small-volume manufacturers in Modena and Sant'Agata Bolognese source hand-finished tubs from local artisan suppliers.
- Vehicle Assemblers:Contract manufacturers for electric vehicle startups procure complete chassis modules from system integrators.
OEM manufacturers dominate value capture. Tier-1 suppliers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German carbon fiber prepreg suppliers export finished monocoque structures to Chinese electric vehicle OEMs seeking European type approval, establishing a transcontinental trade corridor that channels Stuttgart-to-Munich engineering expertise into Shanghai and Beijing battery platform programs.
Germany
Porsche and Mercedes-Benz specifications drive demand for T800-grade carbon fiber tubs with ECHA REACH-compliant resin matrices. Germany's KBA enforces UNECE crashworthiness protocols that de facto standardize composite validation across EU member states. The Stuttgart-to-Munich corridor concentrates SGL Carbon and in-house OEM autoclave facilities within 200 kilometers of premium brand engineering centers.
China
Domestic electric vehicle platforms from NIO and Xpeng integrate imported carbon monocoque modules for flagship performance variants. MIIT technical guidelines and GB standards for passenger car structural integrity create compliance pathways for European composite suppliers. Shanghai's Yangtze River Delta hosts battery-electric vehicle final assembly where composite chassis modules arrive via Hamburg-Rotterdam container routes.
United States
EPA fuel economy standards and NHTSA crash safety protocols impose divergent certification burdens on platform-global architectures from European-headquartered OEMs. California's Advanced Clean Cars program accelerates weight-reduction specifications for premium electric vehicle fleets. The Pacific Northwest maintains aerospace-grade autoclave capacity that automotive programs occasionally access for motorsport-derived development.
Italy
Ferrari and Lamborghini limited-series programs sustain hand-layup artisan suppliers in Modena and Sant'Agata Bolognese with seven-figure unit economics. ECHA REACH substance restrictions on aromatic amine hardeners extend material qualification timelines for Emilia-Romagna composite shops. The Modena supercar cluster preserves decades of FIA-derived safety cell engineering expertise visible in visible carbon fiber craftsmanship.
United Kingdom
McLaren Automotive's Woking facility channels Formula One-derived autoclave expertise into road car monocoque production with ISO 12407-certified tolerances. The UK's Vehicle Certification Agency administers UNECE type approval parallel to EU member state processes post-Brexit. Motorsport Valley between Oxford and Silverstone concentrates composite engineering talent pools that supply adjacent automotive programs.
Global Automotive Carbon Monocoque Chassis Market Key Industry Players
Player mix skews toward integrated OEM manufacturers with captive composite facilities rather than independent tier-one suppliers. Market structure concentrates around three to five premium automotive brands with decades of motorsport heritage and in-house autoclave infrastructure. Strategic archetypes separate Formula One-derived specialists, volume-premium electric vehicle integrators, and limited-series supercar artisans. Dominant competitive moves include backward integration into carbon fiber preform manufacturing and geographic expansion of engineering centers into China's Yangtze River Delta.
Among integrated OEM manufacturers, Porsche, McLaren Automotive, and Ferrari occupy positions exemplifying distinct competitive vectors. Porsche represents volume-capable electric vehicle integration with Zuffenhausen captive production. McLaren Automotive anchors motorsport-derived expertise translation into road-legal architectures. Ferrari exemplifies limited-series supercar positioning where monocoque construction justifies premium pricing tiers. Each maintains proprietary composite engineering rather than sourcing from tier-one suppliers.
| Leading Market Players |
|---|
| Porsche |
| Audi |
| McLaren Automotive |
| Lotus Cars |
| Dallara |
| Ferrari |
| Bayerische Motoren Werke AG |
| Koenigsegg Automotive AB |
| Lamborghini |
| Others |
Cost & Logistics Intelligence
Eighteen-month material qualification timelines for ECHA REACH-compliant epoxy hardeners compress pricing power for European suppliers while amplifying cost premiums for aerospace-grade autoclave capacity. This lead-time band concentrates procurement leverage with Stuttgart and Munich OEMs that maintain captive composite manufacturing, forcing tier-one vendors to absorb resin reformulation costs or surrender margin to secure frame contracts.
Pricing Analysis
Autoclave-cured prepreg layup commands substantial premiums over out-of-autoclave resin transfer molding, with the technology-generation pricing gap widening as electric vehicle scale demands compress cycle-time economics. Three-tier pricing structure across motorsport-proven, automotive-qualified, and prototype-grade certification levels separates Porsche and McLaren captive production from Modena artisan suppliers and Chinese electric vehicle integrators. Price differentiation hinges on fiber grade specification and UNECE type-approval status, with T800-grade aerospace fiber drawing substantial premiums over industrial-grade T300 alternatives. Cost compression in mid-volume electric vehicle segments is intensifying because resin transfer molding throughput economics undercut autoclave depreciation schedules. Fleet procurement departments at German premium leasing companies exhibit lowest price sensitivity, prioritizing embodied carbon disclosure and renewable energy manufacturing certification over unit cost.
Supply Chain Analysis
Aerospace-grade autoclave capacity scarcity in Germany's Stuttgart-to-Munich corridor and the Pacific Northwest constitutes the dominant chokepoint constraining automotive expansion. Supply concentrates in Germany, Italy, and China, with SGL Carbon and in-house OEM facilities anchoring European prepreg production while Chinese electric vehicle OEMs source imported modules via Hamburg-Rotterdam container routes. Raw material dependencies center on Toray and Hexcel carbon fiber tows, Huntsman and Hexion epoxy resin systems, and aliphatic amine hardener alternatives undergoing ECHA REACH resubmission. Single-source vulnerability pervades aerospace-grade autoclave availability, with cure cycles exceeding six hours limiting throughput economics and creating queue bottlenecks for new automotive programs. Distribution runs through tier-one system integrators delivering complete chassis modules to OEM final assembly, with limited direct procurement from raw material suppliers except for captive OEM manufacturing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric vehicle platform fragmentation creates structural white space as battery pack integration standards remain unsettled, enabling specialist composite engineers to capture niche applications before volume economics consolidate procurement around integrated OEM manufacturers.
For Market Incumbents: Consolidate autoclave capacity utilization across motorsport heritage programs and emerging electric vehicle architectures to amortize depreciation against aluminum-intensive megacasting competition from Tesla and Volvo. Secure backward integration into carbon fiber preform manufacturing to protect intellectual property around load path architecture, while accelerating ECHA REACH-compliant resin qualification to preempt European type-approval delays that threaten Zuffenhausen and Woking program schedules. For New Entrants and Emerging Players: MIIT fast-track certification for GB-standard structural integrity offers entry pathway into Chinese electric vehicle supply chains before European type-approval timelines harden incumbent positioning. Target resin transfer molding equipment supply and automated fiber placement system integration for mid-volume electric vehicle programs where neither aerospace hand-layup nor fully automated economics achieve target costs. Pursue joint development agreements with NIO and Xpeng platform engineering teams seeking European supplier partnerships for flagship performance variants. For Investors and Strategic Acquirers: Carve-out targets emerge from aerospace conglomerates divesting non-core automotive composite divisions as electric vehicle scale requirements diverge from legacy autoclave heritage. Five-to-ten year viability hinges on out-of-autoclave process technology maturation and battery pack integration standard convergence. Monitor SGL Carbon and Automobili Lamborghini supply contract renewal cycles as inflection indicators for tier-one supplier consolidation timing, alongside ECHA REACH substance restriction enforcement that extends material qualification timelines and strains smaller Emilia-Romagna composite shops.| Strategic Initiative | Industry Significance |
|---|---|
| Out-of-Autoclave Process Scale-Up | Resin transfer molding expansion unlocks mid-volume electric vehicle economics without aerospace cure-cycle constraints. |
| Automated Fiber Placement Investment | BMW's Landshut AFP installation demonstrates throughput viability for 10,000-plus annual unit programs. |
| ECHA REACH Resin Reformulation | Aliphatic amine hardener qualification preserves European type-approval access against aromatic amine restrictions. |
| Battery Pack Integration Partnership | Coupled finite element modeling with NIO and Xpeng reduces physical prototype requirements for crashworthiness validation. |
| Captive Carbon Fiber Preform Manufacturing | Porsche's Zuffenhausen in-house production protects load path intellectual property from tier-one supplier dissemination. |
Research Approach
Operator-level perspectives from OEM platform engineers, tier-one composite procurement leads, autoclave facility managers, and ECHA regulatory affairs specialists anchored the qualitative base for this analysis. Primary interview data combined with secondary validation from UNECE type-approval filings, MIIT technical guideline publications, KBA crashworthiness protocols, and vehicle production databases. Bottom-up unit economics for prepreg layup and resin transfer molding processes triangulated against top-down market size estimates from carbon fiber consumption metrics and OEM platform rollout schedules.
Sensitivity analysis across fiber grade substitution scenarios, cure-cycle time compression assumptions, and battery pack integration standard evolution framed forecast uncertainty bounds. Segmentation dimensions modeled include vehicle category, manufacturing technology, material type, and end-user procurement authority, with regional production cluster dynamics overlaying geographic demand distribution. CAGRs derived from installed capacity expansion timelines, OEM platform announcement pipelines, and regulatory weight-reduction mandate enforcement schedules. Electric vehicle skateboard architecture adoption curves and aluminum-intensive megacasting competitive response informed demand-side elasticity assumptions.
Decision-makers should treat outputs as directional under base assumptions of sustained EU Green Deal weight-reduction mandate enforcement and MIIT technical guideline stability; material deviation in ECHA REACH substance restriction scope or battery pack mounting standard finalization would warrant model refresh. Practitioners should keep alternative scenarios live as out-of-autoclave process yield rates and Chinese electric vehicle export volume trajectories evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Electric Forklifts Market
Vehicle Components
Italy Automotive Glass Fiber Composites Market
Vehicle Components
Truck Axle Market
Vehicle Components
Steering Knuckle Market
Vehicle Components
Railway Vehicle Coupler Market
Vehicle Components
Global Automotive Carbon Fiber Composites Market
Vehicle Components
Global Automotive EGR Valves Market
Vehicle Components
Two Wheeler Footrest Market
Vehicle Components
Bicycle Brake Cable Market
Vehicle Components
Railway Air Filter Market
Vehicle Components
Global Automotive Composite Liftgate Market
Vehicle Components
Refrigerated Trailer Hinges Market
Vehicle Components
Aircraft and Marine Turbochargers Market
Vehicle Components
Global Boat Trailers Market
Vehicle Components
HCV Suspension System Market
Vehicle Components
Automotive Wheel Hub Bearing Aftermarket Market