
 Anchorage Connector Market | 2026-2036
Anchorage Connector Market Size, Share, and Industry Trends Forecast 2026-2036
Anchorage Connector Market Analytics
ANSI Z359.12 Class A specification upgrades is collapsing the gap between entry-level and premium anchorage connector offerings. MSA leverages captive testing laboratories to accelerate certification throughput for new alloy formulations. Honeywell International Inc anchors its position through backward integration into forged steel component production. WernerCo competes on distributor breadth, stocking SKUs across three regional fulfillment centers.
Anchorage connectors are load-bearing devices engineered to secure personal fall arrest systems to structural substrates, typically rated for 5,000 pounds minimum tensile strength per OSHA 1926.502 and manufactured through drop forging or CNC machining of alloy steel with zinc plating or stainless steel finishes. Their primary industrial purpose is to create compliant tie-off points for workers at height on construction sites, bridges, and industrial facilities. Bridges as a product type leads volume due to continuous infrastructure rehabilitation programs across aging transportation networks. Smart Infrastructure technology represents the fastest-expanding segment as embedded load sensors and RFID tracking enable predictive maintenance scheduling for installed connectors. Municipalities as an end user constitute the most mature demand pool, bound by public procurement cycles and standardized specification sheets.
OSHA enforces minimum breaking strength and corrosion resistance thresholds that disqualify uncertified imports from federal construction projects. ANSI Z359.12 and CSA Z259.12-01 in Canada impose quarterly inspection protocols that accelerate replacement rates for connectors showing wear indicators. Stakeholders must monitor evolving alloy substitution trends as domestic mills adjust pricing for high-strength steel feedstock.
Market Dynamics
The Anchorage Connector Market is experiencing structural compression as ANSI Z359.12 Class A specification upgrades collapse the performance gap between entry-level and premium offerings, forcing manufacturers to accelerate alloy formulation testing and consolidate certification pipelines.
Growth Catalysts
- Infrastructure Rehabilitation Mandates:Bridge reconstruction programs across aging transportation networks in the United States generate continuous replacement demand for certified anchorage systems on elevated work platforms.
- OSHA 1926.502 Enforcement Intensification:Federal construction project disqualification of uncertified imports tightens compliance thresholds and redirects procurement toward domestically certified manufacturers.
- Embedded Sensor Convergence:Smart Infrastructure adoption integrating load sensors and RFID tracking enables predictive maintenance scheduling, expanding attach rates for connected anchorage connector systems.
Market Restraints
- High-Strength Steel Feedstock Volatility:Domestic mill pricing adjustments for alloy steel inputs compress margins on forged component production.
- Canadian Supply Concentration:CSA Z259.12-01 quarterly inspection protocols accelerate replacement cycles but create dependency on North American certification bodies.
- Corrosion Resistance Threshold Escalation:Stainless steel finish requirements disqualify zinc-plated alternatives from coastal and chemical facility applications.
Strategic Opportunities
- Municipal Procurement Digitization:Public procurement cycle acceleration through e-procurement platforms reduces specification sheet standardization delays for standardized anchorage connectors.
- Wind Energy Installation Expansion:Offshore and onshore turbine maintenance protocols create new elevated work platform applications requiring certified tie-off points.
- ANSI Z359.12 Backward Compatibility Waivers:Regulatory pathways for phased legacy system upgrades reduce replacement cost barriers for commercial high-rise developers.
Industry Challenges
- Certification Throughput Bottlenecks:Captive testing laboratory capacity constraints delay new alloy formulation approvals for drop-forged connector variants.
- Regional Fulfillment Network Complexity:Multi-SKU stocking requirements across distributed fulfillment centers strain inventory optimization for distributor-dependent manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anchorage Connector Market |
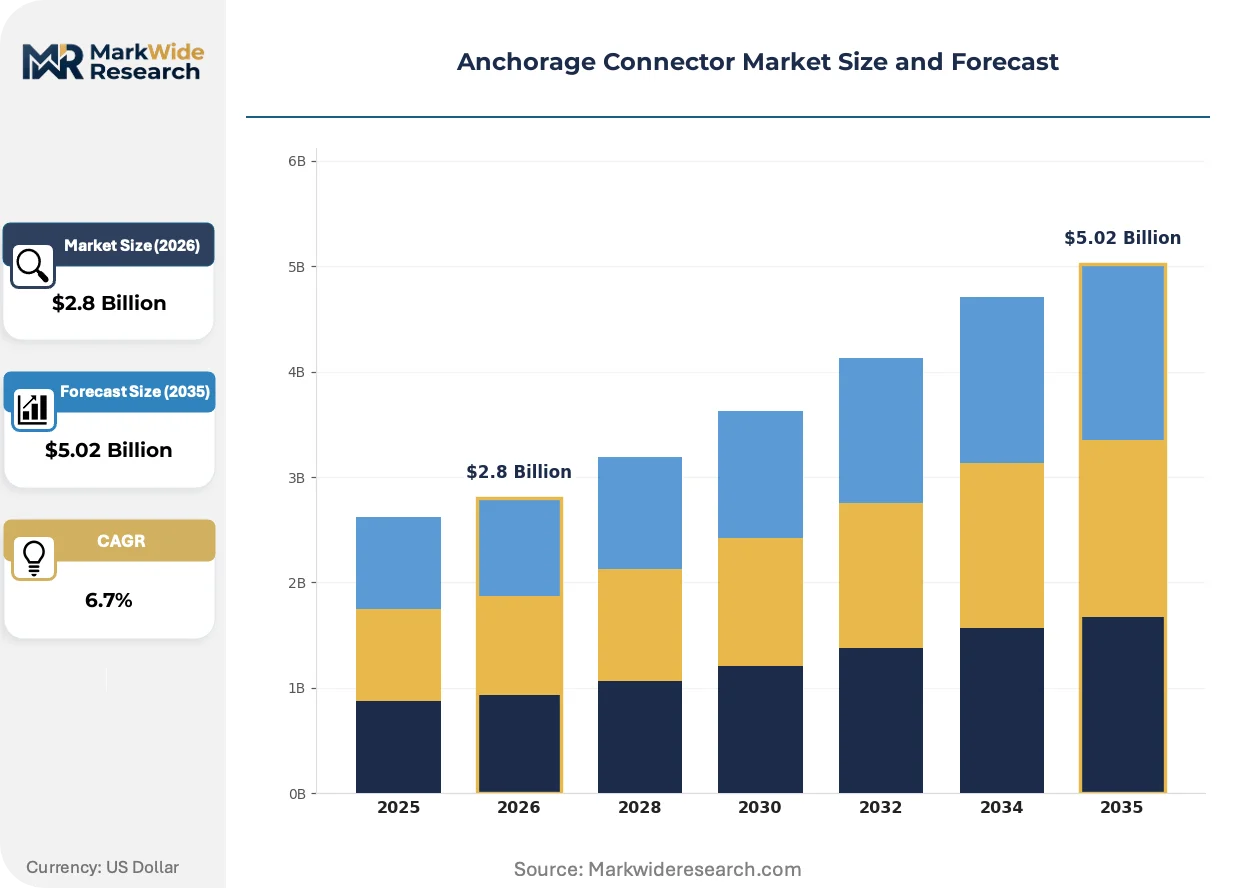
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bridges, Tunnels, Overpasses, Underpasses End User: Municipalities, Construction Companies, Transport Agencies, Private Developers Service Type: Design, Construction, Maintenance, Consultation Technology: Smart Infrastructure, Traditional Engineering, CAD Systems, Sustainable Materials |
| Companies Covered | 3M, Honeywell International Inc, MSA, Miller Fall Protection, WernerCo, Improved Construction Methods, Mazzella Companies, Seton, MTN SHOP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anchorage Connector Market Evolving Landscape
Sensor-embedded anchorage systems are compressing traditional maintenance cycles and enabling predictive asset management. Material science advances in alloy formulations are reshaping strength-to-weight ratios. Procurement digitization is accelerating specification compliance verification.
Load-sensing microelectronics integrated directly into connector bodies is miniaturizing predictive maintenance hardware. Wind energy maintenance contractors are adopting these systems fastest, replacing quarterly manual inspections with continuous structural health monitoring. This convergence is compressing service contract structures from reactive replacement toward condition-based subscription models.
OSHA is tightening fall protection audit protocols for federal construction contractors. Third-party certification pre-qualification requirements now block uncertified import participation in infrastructure stimulus-funded projects. Bridge rehabilitation specialists in the United States are responding by mandating ANSI Z359.12 Class A documentation in all bid specifications.
Specification-driven procurement is consolidating buyer decision criteria around certification grade rather than price point. Distributor networks are unbundling after-sales inspection services from product sales, replacing bundled offerings with separate compliance service contracts. Municipal procurement officers in the United States are most visibly adopting this shift, separating connector acquisition from installation verification.
Anchorage Connector Market Segmentation
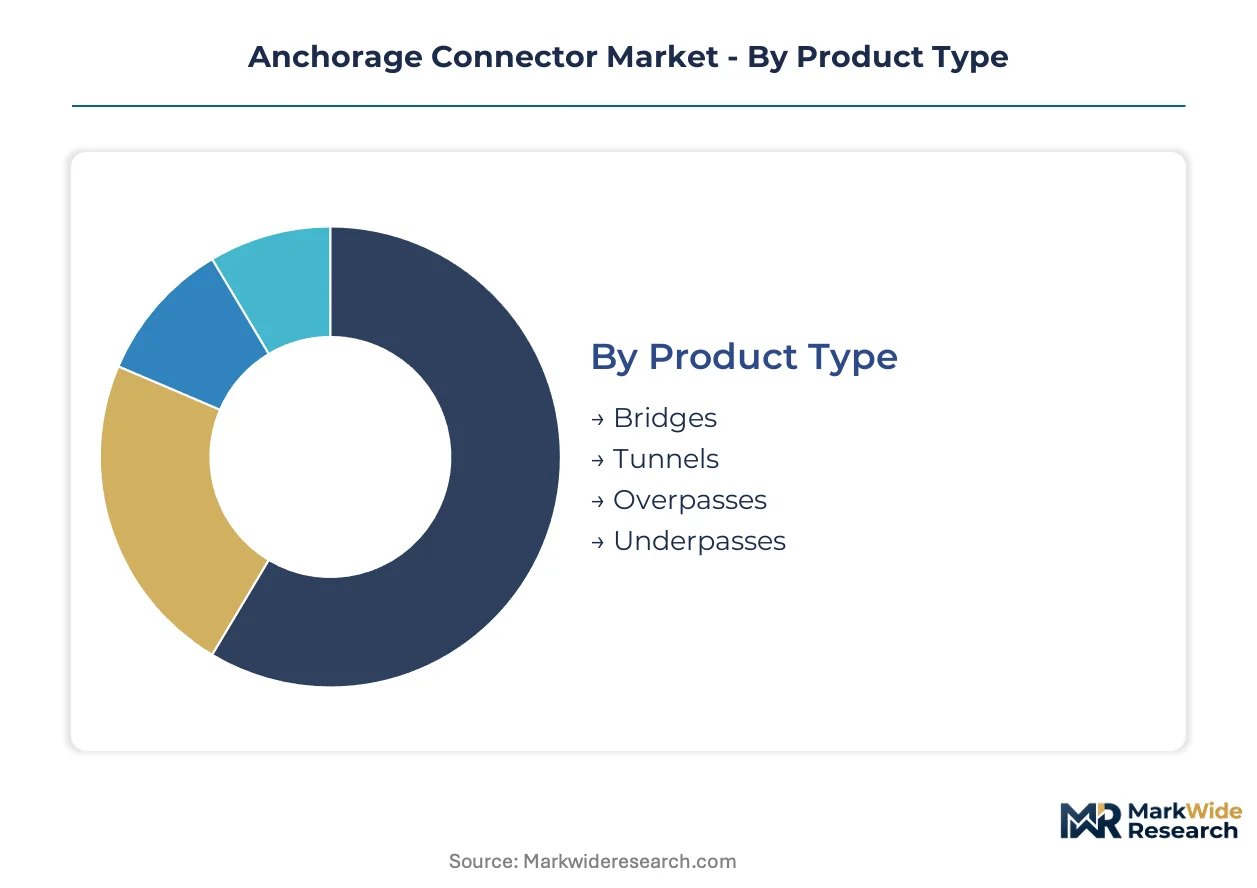
Anchorage connector procurement decisions split across structural application, contracting entity, and embedded technology. Specification compliance requirements differ materially across these dimensions, driving divergent certification and sourcing strategies.
Product Type:
OSHA 1926.502 mandates distinct load ratings and substrate attachment methods for each structural environment, forcing manufacturers to maintain discrete certification portfolios per application type.
- Bridges:Cantilevered and suspension bridge decks require corrosion-resistant stainless steel connectors rated for dynamic wind loading and thermal expansion cycles. Continuous federal and state transportation rehabilitation programs across the United States sustain replacement demand for certified systems on aging steel and concrete superstructures.
- Tunnels:Confined-space ventilation constraints and limited overhead clearance drive demand for low-profile, side-mounted anchorage configurations with integrated inspection access ports. Urban rail and highway tunnel maintenance contracts in the United States concentrate procurement through specialized infrastructure contractors.
- Overpasses:Elevated roadway structures with high traffic exposure prioritize rapid-installation clamp systems.
- Underpasses:Sub-grade moisture and freeze-thaw cycling necessitate enhanced galvanization specifications.
Bridges handles the majority of throughput; Tunnels is the fastest mover on share.
End User:
Contracting authority determines inspection frequency, documentation requirements, and acceptable certification pathways.
- Municipalities:Public procurement cycles bind purchasing to standardized specification sheets and competitive bidding protocols. City and county infrastructure departments across the United States accelerate replacement of legacy systems to meet ANSI Z359.12 Class A compliance deadlines.
- Construction Companies:General and specialty contractors prioritize SKU availability and distributor proximity over brand specification. Large commercial high-rise developers in the United States negotiate volume pricing through regional fulfillment networks.
- Transport Agencies:State DOTs and federal authorities mandate third-party testing documentation.
- Private Developers:Mixed-use and industrial facility owners balance insurance premium reductions against upfront certification costs.
Municipalities dominate absolute volume; Construction Companies are expanding most quickly.
Service Type:
Value capture shifts upstream as compliance complexity increases.
- Design:Structural engineers specify connector placement, load paths, and substrate compatibility during pre-construction phases.
- Construction:Installation contractors source certified hardware to meet project-specific fall protection plans.
- Maintenance:Quarterly inspection protocols under ANSI Z359.12 generate recurring revenue from wear-indicator assessments and replacement scheduling.
- Consultation:Third-party compliance auditors verify documentation for federal project eligibility.
Maintenance commands the highest recurring attach rates; Consultation is climbing the fastest.
Technology:
Embedded capability separates premium positioning from commodity replacement.
- Smart Infrastructure:Load sensors and RFID tracking enable predictive maintenance scheduling and real-time structural health monitoring. Wind energy maintenance contractors across the United States adopt these systems to replace manual quarterly inspections with continuous data feeds.
- Traditional Engineering:Drop-forged alloy steel connectors with zinc plating serve cost-sensitive applications where inspection intervals remain manual.
- CAD Systems:Digital twin integration allows pre-installation load simulation and placement optimization.
- Sustainable Materials:Recycled-content alloys and low-carbon forging processes address emerging procurement scoring criteria.
Traditional Engineering retains the installed base; Smart Infrastructure shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Drop-forged component production clusters in the United States, Germany, and China, with certification testing capacity concentrated near major infrastructure corridors. Demand patterns track federal stimulus allocation cycles and bridge rehabilitation program timelines.
United States
Federal transportation rehabilitation programs drive connector replacement across aging steel bridge decks. OSHA 1926.502 enforcement disqualifies uncertified imports from stimulus-funded construction contracts. Bridge maintenance specialists in the Northeast Corridor accelerate procurement of ANSI Z359.12 Class A systems for cantilevered superstructure access.
Germany
Industrial facility modernization sustains demand for corrosion-resistant stainless steel anchorage systems. REACH compliance mandates documentation of alloy composition for zinc-plated and galvanized finishes. Engineering contractors in the Ruhr industrial cluster specify embedded load sensors for predictive maintenance on chemical plant elevated platforms.
Canada
CSA Z259.12-01 quarterly inspection protocols accelerate replacement cycles for connectors showing wear indicators. Transport Canada bridge safety audits mandate third-party certification documentation for federal highway rehabilitation tenders. Infrastructure contractors in Ontario concentrate procurement through regional distributor networks serving Toronto-Ottawa corridor projects.
China
GB standards for fall protection equipment tighten quality thresholds for export-oriented manufacturers. MIIT industrial safety directives require documentation of minimum breaking strength for construction site tie-off systems. Forging operations in the Yangtze River Delta supply alloy steel components to domestic wind energy installation contractors.
Australia
Mining sector maintenance protocols drive demand for ruggedized anchorage systems on elevated processing platforms. Work Health and Safety regulations mandate engineered tie-off points for heights above two meters. Resource extraction contractors in Western Australia specify stainless steel finishes for coastal and remote site applications.
Anchorage Connector Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Integrated safety equipment conglomerates compete against specialized fall protection manufacturers and regional forging operations. Three archetypes dominate: diversified industrial safety portfolios, dedicated height safety specialists, and contract fabrication houses serving private-label distributors. Consolidation pressure favors backward integration into forged steel production and captive certification laboratory capacity.
Within the diversified safety conglomerate tier, 3M and Honeywell International Inc occupy positions defined by broad personal protective equipment portfolios and established federal contracting relationships. MSA exemplifies the dedicated fall protection specialist archetype, anchoring competitive positioning around ANSI certification throughput and alloy formulation testing capabilities. Among distributor-dependent manufacturers, WernerCo represents scale-driven fulfillment network strategies across regional stocking locations.
| Leading Market Players |
|---|
| 3M |
| Honeywell International Inc |
| MSA |
| Miller Fall Protection |
| WernerCo |
| Improved Construction Methods |
| Mazzella Companies |
| Seton |
| MTN SHOP |
| Others |
Value Network & Pricing Analysis
Project-based procurement contracts for federal bridge rehabilitation programs lock in multi-year supply commitments for ANSI Z359.12 Class A certified connectors, anchoring price visibility against alloy steel feedstock swings. Municipalities and construction contractors negotiate these agreements to secure capacity at drop-forging operations while buffering spot-market volatility in high-strength steel inputs.
Pricing Analysis
OSHA 1926.502 dictates the pricing tier structure across the Anchorage Connector Market, separating certified from uncertified offerings. Pricing stratifies across premium smart infrastructure systems with embedded load sensors, standard ANSI Class A drop-forged units, and economy zinc-plated alternatives facing corrosion-resistance disqualification. Cost compression in economy tiers is intensifying because stainless steel finish requirements now exclude zinc-plated products from coastal applications. Construction companies show highest price sensitivity, while wind energy maintenance contractors accept premium positioning for predictive maintenance capabilities.
Supply Chain Analysis
Inbound logistics costs through Port of Los Angeles and Port of Long Beach congestion patterns influence landed pricing for alloy steel feedstock shipments from East Asian mills. Drop-forged component production concentrates in the United States, Germany, and China, with the Yangtze River Delta feeding domestic wind energy contractors. Supply chains rest on high-strength steel billet, zinc plating chemicals, and microelectronic sensor modules. Single-source vulnerability clusters around captive certification laboratory capacity for ANSI Z359.12 testing. Distribution runs through regional fulfillment centers stocking multi-SKU portfolios for distributor-dependent manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as specification-driven procurement splinters demand across certification grades, creating niche positions for specialized alloy formulators and embedded sensor integrators.
For Market Incumbents: Secure captive certification throughput by expanding in-house testing laboratory capacity, eliminating third-party bottlenecks that delay new alloy approvals. Deepen backward integration into forged steel component production to buffer margin pressure from domestic mill pricing adjustments. Threat intensity concentrates in substitute smart infrastructure systems displacing traditional quarterly inspection cycles. For New Entrants and Emerging Players: Differentiate on municipal procurement digitization readiness, offering e-procurement platform integration that accelerates specification compliance verification. Target wind energy maintenance contractors as the most penetrable segment, where predictive maintenance subscription models replace transactional hardware sales. Go-to-market leverage centers on condition-based service contracts bundling sensor-embedded connectors with continuous monitoring. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among maintenance service providers with quarterly inspection protocols under ANSI Z359.12 and CSA Z259.12-01. Long-term viability over the next decade favors acquisition targets combining captive forging capacity with embedded sensor integration capabilities. Signal to monitor: Transport Canada and state DOT adoption of smart infrastructure mandates in bridge rehabilitation bid specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Forged Steel Production | Captive supply of high-strength alloy billets insulates margin pressure from domestic mill pricing volatility. |
| Certification Laboratory Capacity Expansion | In-house ANSI Z359.12 testing throughput accelerates new product approvals and blocks competitor pipeline entry. |
| Smart Infrastructure Sensor Integration | Embedded load monitoring enables predictive maintenance subscriptions that compress traditional replacement cycles. |
| Municipal E-Procurement Platform Partnerships | Direct integration with public procurement systems reduces specification sheet standardization delays. |
| Wind Energy Maintenance Service Contracting | Offshore turbine access protocols create new elevated work platform applications requiring certified tie-off systems. |
Research Methodology
Desk research of customs trade databases, OSHA enforcement records, and ANSI certification registries preceded structured interviews with plant engineers at drop-forging operations, procurement leads at infrastructure contractors, distributor inventory managers, and fall protection compliance officers. Primary fieldwork with municipal procurement departments and wind energy maintenance supervisors validated secondary findings on specification-driven demand shifts. Bottom-up unit economics triangulated against top-down federal stimulus allocation models.
Variance decomposition across product type, end user contracting authority, and embedded technology capability shaped the analytical framework over the projection horizon. Modeled segmentation spans structural application environment, certification grade tier, and service type from design through maintenance. CAGRs derived from replacement cycle analysis of aging bridge infrastructure and inspection protocol enforcement intensity. Forecast inputs incorporated alloy substitution elasticity and embedded sensor attach rate trajectories.
The analysis sits within stated boundaries; outcomes outside sustained federal transportation rehabilitation funding and OSHA 1926.502 enforcement continuity would require recalibration. Forecasts reflect assumptions on certification body capacity expansion and high-strength steel feedstock pricing stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Snowplows Market
Vehicle Components
Tail Lifts Market
Vehicle Components
North America Forklift Rental Market
Vehicle Components
Automotive Brake Valves Market
Vehicle Components
Steering Tie Rod Market
Vehicle Components
Global Air Spring Components Market
Vehicle Components
Bicycle Chain Device Market
Vehicle Components
Trailer Surge Brake Market
Vehicle Components
Car Radiator Market
Vehicle Components
Automotive Composite Suspension Components Market
Vehicle Components
Tricycle Vending Cart Market
Vehicle Components
GCC Automotive Connectors Market
Vehicle Components
Trailer Brake Controllers Market
Vehicle Components
Automotive Wheel Hub Bearing Aftermarket Market
Vehicle Components
Railway Air Filter Market
Vehicle Components
Global Automotive Carbon Monocoque Chassis Market