
 Positive Crankcase Ventilation Valve Market | 2026-2036
Positive Crankcase Ventilation Valve Market Size, Share, and Industry Trends Forecast 2026-2036
Positive Crankcase Ventilation Valve Market Analytics
Asset-light contract manufacturing and third-party leasing arrangements for injection-molding capacity is reshaping how tier-two suppliers enter the PCV valve segment. Continental AG leverages captive polymer compounding operations to sustain margin control across thermal cycling specifications. MANN+HUMMEL anchors European OEM supply through integrated filter-ventilation modules. Cummins Inc. specializes in heavy-duty calibrated orifice designs for diesel blow-by management.
A positive crankcase ventilation valve regulates pressure and routes hydrocarbon-rich blow-by gases from the engine crankcase back into the intake manifold for combustion, typically incorporating a spring-loaded pintle, elastomer seal, and calibrated flow orifice rated for temperatures exceeding 120°C. Mechanical PCV valves still dominate installed base volumes due to cost parity and diagnostic simplicity, though electronic PCV valves with pulse-width modulation are capturing margin pools in hybrid powertrains where precise crankcase pressure mapping prevents seal degradation. Aftermarket Suppliers represent a structurally fragmented channel with shorter design cycles and lower certification barriers than OEM direct supply.
EPA enforces evaporative emission and onboard diagnostic thresholds that mandate functional PCV systems across the US light-duty fleet, while EMA coordinates European type-approval testing under Euro 7 provisions that expand crankcase monitoring to cold-start and extended-idle conditions. China's MEE implements dual carbon goals through GB standards that tighten blow-by hydrocarbon limits for domestic and imported engines alike. Stakeholders must monitor how software-defined engine calibration redefines hardware durability requirements for PCV components.
Market Dynamics
Electronic pulse-width modulation architectures are displacing mechanical pintle designs across hybrid powertrain platforms, forcing suppliers to recalibrate thermal cycling specifications and pressure-mapping algorithms for crankcase ventilation hardware.
Growth Catalysts
- Euro 7 Cold-Start Mandates:EMA type-approval testing now extends crankcase monitoring to extended-idle conditions, requiring upgraded PCV valve durability across European OEM platforms.
- Hybrid Powertrain Proliferation:Precise crankcase pressure control prevents seal degradation in stop-start architectures, elevating demand for electronically actuated ventilation modules.
- China GB Standard Tightening:MEE enforcement of dual carbon goals through domestic blow-by hydrocarbon limits accelerates replacement cycles for mechanical valve inventories.
Market Restraints
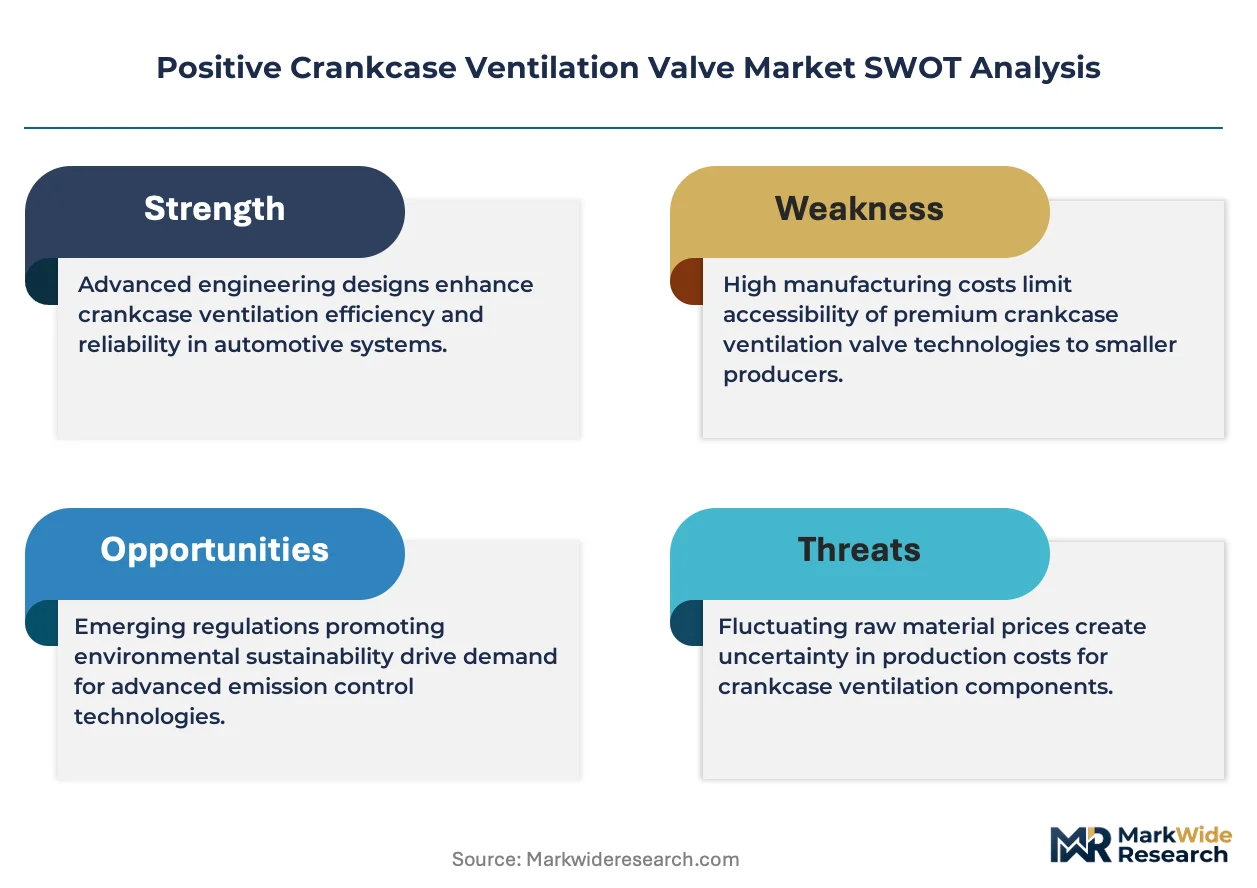
- Fluoroelastomer Feedstock Volatility:Specialized FKM seal compounds face price instability from concentrated fluoropolymer resin supply, compressing margin pools for calibrated orifice manufacturers.
- Injection-Molding Capacity Concentration:Asset-light contract manufacturers in East Asia dominate high-temperature polymer component fabrication, creating single-source exposure for tier-two valve assemblers.
- Mechanical Valve Obsolescence Risk:Diagnostic simplicity of spring-loaded designs cannot satisfy EPA onboard diagnostic thresholds for real-time pressure fault detection.
Strategic Opportunities
- India Two-Wheeler Electrification:BIS emission protocols for small-displacement engines create first-mover positioning for compact PCV modules in motorcycle crankcase ventilation.
- Filter-Ventilation Module Integration:Converging oil separation and pressure regulation into single housing architectures reduces assembly steps for OEM powertrain integration teams.
- Aftermarket Diagnostic Tool Pairing:Bluetooth-enabled electronic valves enable independent service channels to read crankcase pressure data, opening margin capture beyond dealer networks.
Industry Challenges
- Embedded Software Talent Scarcity:Pulse-width modulation firmware development for automotive-grade pressure sensors outpaces available controls engineering capacity at tier-two suppliers.
- Multi-Regulatory Certification Overlap:Simultaneous EPA Tier 3, Euro 7, and China GB homologation timelines compress product validation windows for platform-shared engine architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Positive Crankcase Ventilation Valve Market |
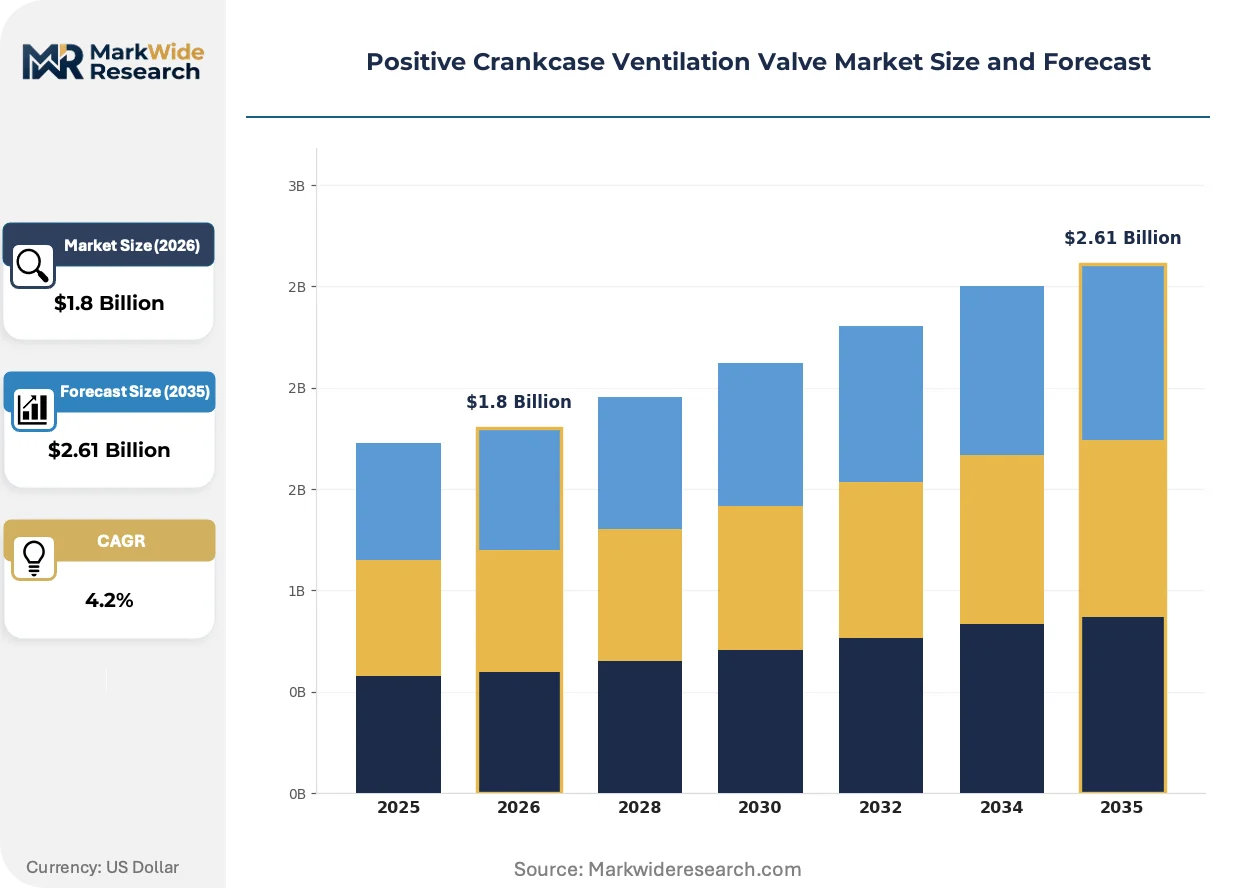
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.61 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronic PCV Valve, Mechanical PCV Valve, Vacuum PCV Valve, Oil Control Valve End User: Automakers, Aftermarket Suppliers, OEMs, Repair Shops Material: Plastic, Aluminum, Steel, Rubber Installation Type: In-line, Integrated, Standalone, Retrofit |
| Companies Covered | Parker Hannifin Corp., Sogefi Spa, MANN+HUMMEL, SMP Deutschland GmbH, Alfdex AB, Cummins Inc., Tenneco Inc., Continental AG, Aisan Industry Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Positive Crankcase Ventilation Valve Market Evolving Landscape
Sensor fusion architectures and predictive pressure algorithms are redefining how crankcase ventilation hardware interfaces with engine management systems, shifting competitive advantage toward electromechanical integration capabilities.
Electronic PCV valves with integrated manifold absolute pressure sensing are digitizing crankcase pressure feedback loops for real-time calibration adjustments. Hybrid OEMs in Germany and Japan are adopting these modules at accelerated placement rates. This digitization is compressing the diagnostic latency window from fault detection to corrective action from seconds to milliseconds.
EPA Tier 3 evaporative emission thresholds now mandate functional PCV system verification across the full US light-duty fleet operating envelope. The regulation forces hardware suppliers to validate thermal cycling performance beyond 150°C for turbocharged direct-injection architectures. Heavy-duty diesel platforms face the steepest compliance cost escalation as blow-by volume scales with displacement.
Fleet operators are unbundling after-sales ventilation service from comprehensive powertrain maintenance contracts, creating direct procurement relationships with valve manufacturers. Independent service channels in the United States and Germany are capturing this disintermediation opportunity through specialized crankcase pressure diagnostic equipment. This purchasing pattern shift is most visible in commercial vehicle segments where uptime guarantees override brand loyalty in supplier selection.
Positive Crankcase Ventilation Valve Market Segmentation
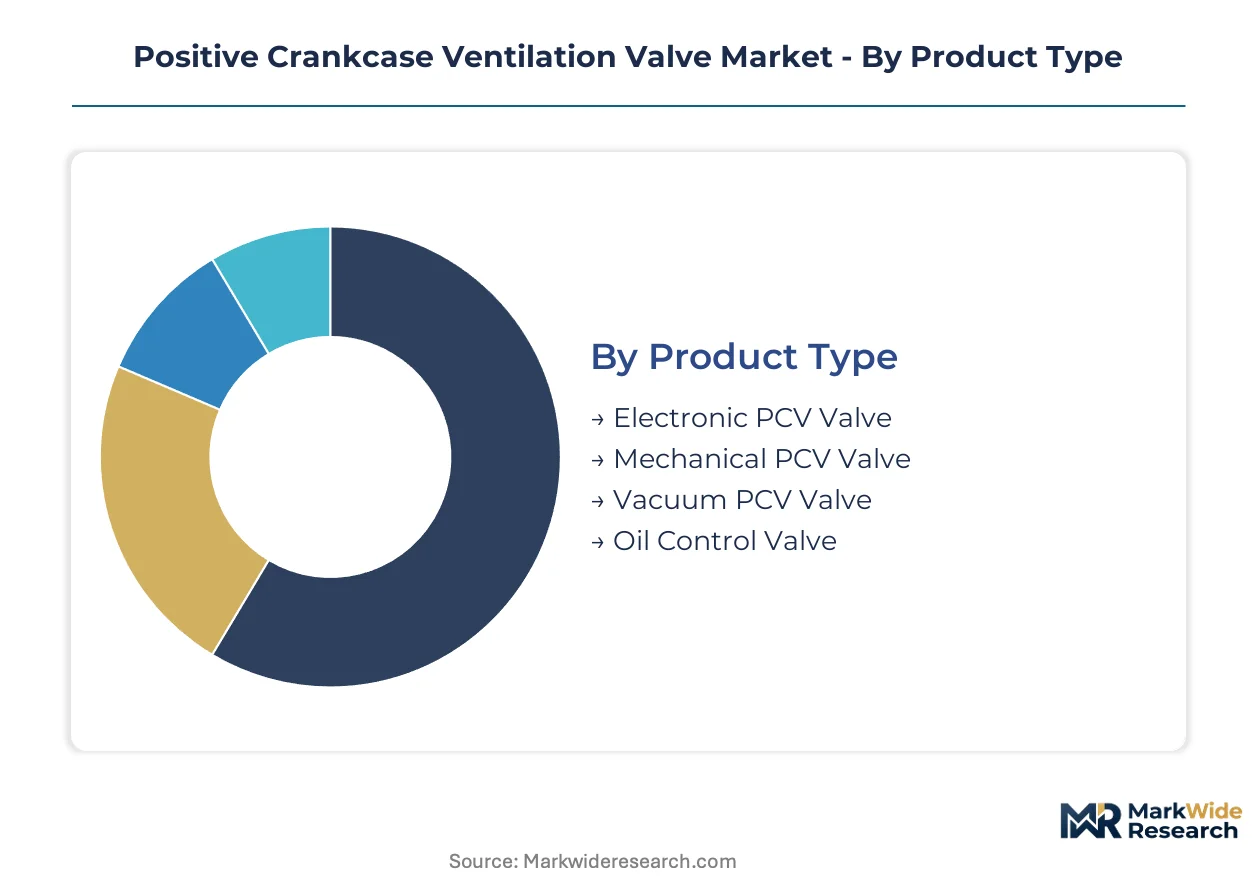
PCV valve segmentation reveals how material selection, actuation technology, and channel economics create divergent margin structures across automotive supply chains. Understanding these splits helps suppliers prioritize R&D investment and manufacturing footprint decisions.
Product Type:
Actuation mechanisms span precision electronic control to legacy mechanical simplicity, with each architecture serving distinct powertrain thermal and diagnostic requirements.
- Electronic PCV Valve:Pulse-width modulation enables millisecond-response pressure mapping for hybrid stop-start systems. German and Japanese OEMs specify these modules for turbocharged gasoline direct-injection platforms where seal protection demands real-time calibration.
- Mechanical PCV Valve:Spring-loaded pintle designs with fluoroelastomer seals dominate installed base volumes due to diagnostic simplicity and cost parity. China's domestic engine manufacturers continue specifying these for conventional powertrains despite tightening GB emission thresholds.
- Vacuum PCV Valve:Manifold vacuum-actuated designs serve naturally aspirated engine architectures with stable crankcase pressure profiles.
- Oil Control Valve:Integrated pressure regulation and flow control functions for variable valve timing systems in compact engine bays.
The dominant share belongs to Mechanical PCV Valve, while Electronic PCV Valve is closing the gap fastest.
End User:
Channel economics split between long-cycle OEM integration and fragmented aftermarket replacement demand with divergent certification barriers.
- Automakers:Light-duty passenger vehicle production lines in China, Germany, and the United States specify PCV modules during powertrain assembly. EPA Tier 3 and Euro 7 mandates force these buyers to validate thermal cycling beyond 150°C for turbocharged architectures.
- Aftermarket Suppliers:Independent distributors and service chains procure replacement valves with shorter design cycles and lower homologation requirements than OEM direct supply.
- OEMs:Captive powertrain divisions of integrated automotive groups source PCV hardware through long-term supply agreements with tier-one ventilation system specialists.
- Repair Shops:Fleet operators and independent service channels in the United States and Germany now procure directly from valve manufacturers as maintenance contracts unbundle.
Automakers command the largest procurement volumes, though Aftermarket Suppliers are expanding most quickly as vehicle age profiles lengthen.
Material:
Polymer and metal selection trades off thermal resilience, weight reduction, and injection-molding cycle economics across manufacturing footprints.
- Plastic:High-temperature polymer compounds with glass fiber reinforcement dominate electronic valve housings. Continental AG leverages captive polymer compounding to control margin across thermal cycling specifications exceeding 120°C.
- Aluminum:Die-cast housings serve heavy-duty diesel applications where thermal mass stabilizes pressure regulation across extended-idle conditions.
- Steel:Stamped and machined components persist in cost-sensitive mechanical valve designs for high-volume small-displacement engines.
- Rubber:FKM and HNBR seal formulations face feedstock volatility from concentrated fluoropolymer resin supply.
Plastic holds the dominant position, while Aluminum is gaining share fastest in commercial vehicle specifications.
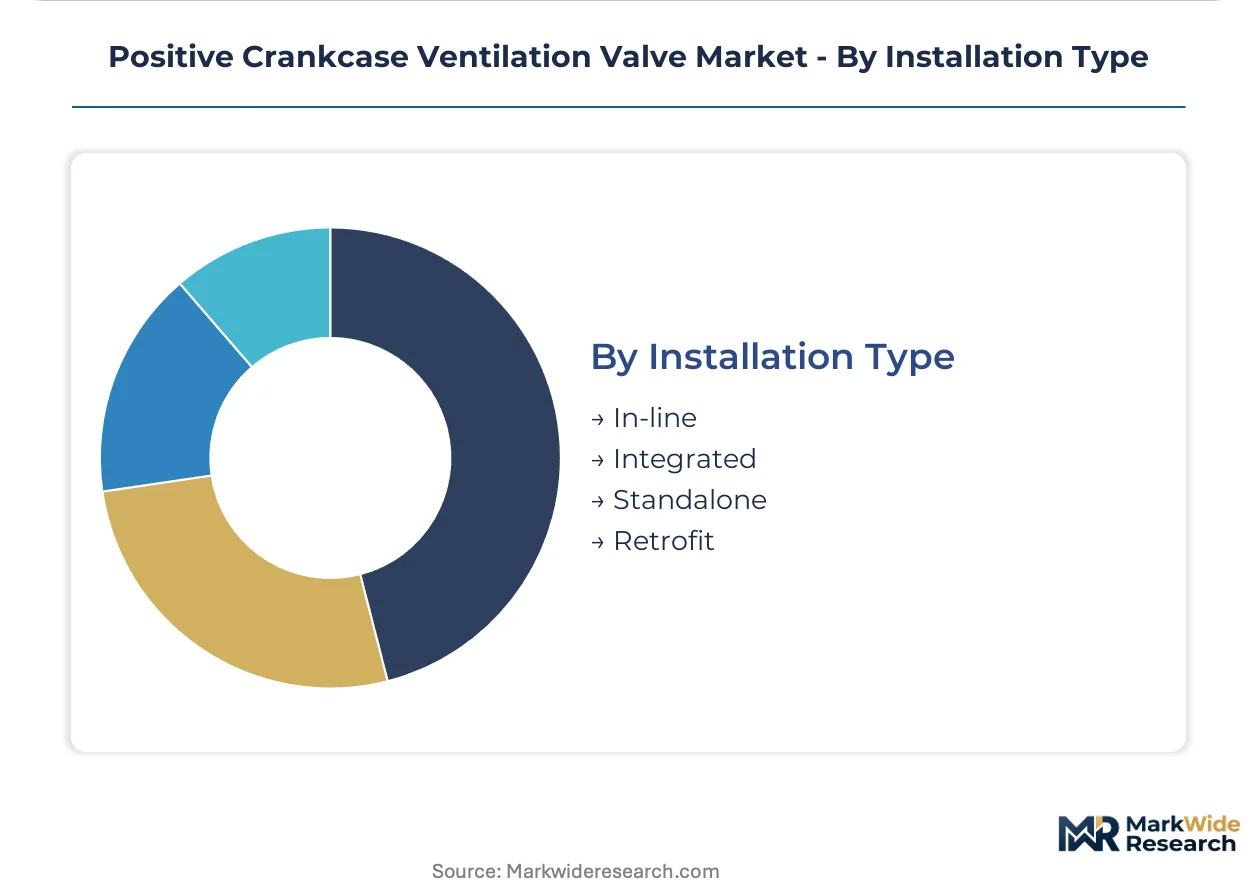
Installation Type:
Packaging architecture determines assembly labor content and diagnostic accessibility for powertrain integration teams.
- In-line:Modular valves insert into rubber hose assemblies between crankcase and intake manifold for service-friendly replacement. Aftermarket channels in the United States favor this architecture for diagnostic simplicity.
- Integrated:Filter-ventilation modules combine oil separation and pressure regulation in single housings. MANN+HUMMEL anchors European OEM supply through these converged designs that reduce assembly steps.
- Standalone:Discrete valve units mount directly to valve cover castings with threaded or clip-fit retention.
- Retrofit:Upgrade kits enable older engine platforms to meet tightened emission standards without full powertrain redesign.
Integrated captures the largest share, while In-line maintains steepest expansion trajectory in independent service channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA Tier 3 mandates and Euro 7 cold-start provisions are reconfiguring PCV valve procurement across major automotive manufacturing clusters. China's GB standard tightening and India's BIS emission protocols are accelerating hardware replacement cycles in Asia-Pacific engine production corridors.
United States
Turbocharged direct-injection gasoline platforms from Detroit Three automakers drive thermal cycling requirements beyond 150°C. EPA Tier 3 evaporative emission thresholds mandate functional PCV system verification across the full light-duty fleet operating envelope. Michigan and Ohio powertrain corridors concentrate validation testing for heavy-duty diesel blow-by management specifications.
Germany
Hybrid stop-start architectures from premium OEMs elevate demand for electronically actuated ventilation modules with millisecond-response pressure mapping. EMA type-approval testing under Euro 7 provisions extends crankcase monitoring to extended-idle conditions. Stuttgart and Munich engineering centers anchor European supply chain integration for filter-ventilation module architectures.
China
Domestic engine manufacturers specify mechanical PCV valves for conventional powertrains despite tightening GB emission thresholds. MEE enforcement of dual carbon goals accelerates replacement cycles for mechanical valve inventories. Yangtze River Delta manufacturing clusters concentrate injection-molding capacity for high-temperature polymer valve housings.
Japan
Hybrid powertrain proliferation from Toyota and Honda platforms demands precise crankcase pressure control to prevent seal degradation. METI coordinates automotive component standardization with JIS specifications for crankcase ventilation hardware. Nagoya and Tokyo metropolitan areas concentrate electromechanical integration capabilities for pulse-width modulation valve production.
India
Small-displacement motorcycle and scooter engines create first-mover positioning for compact PCV modules under tightening BIS emission protocols. Two-wheeler electrification trends are reshaping crankcase ventilation requirements for residual internal combustion platforms. Tamil Nadu and Maharashtra automotive corridors concentrate tier-two supplier assembly operations for cost-sensitive mechanical valve specifications.
Positive Crankcase Ventilation Valve Market Competitive Landscape
On the supply side, the industry is consolidating around tier-one system integrators with captive polymer compounding and filter-ventilation module capabilities. The vendor base spans German automotive conglomerates, Japanese precision component specialists, and North American heavy-duty diesel equipment manufacturers. Three strategic archetypes dominate: integrated filtration-ventilation module suppliers, heavy-duty calibrated orifice specialists, and asset-light contract manufacturers leveraging third-party injection-molding capacity. Dominant competitive moves include backward integration into polymer compounding operations and strategic partnerships for pulse-width modulation firmware development.
Among German-based automotive suppliers, Continental AG and MANN+HUMMEL exemplify the integrated module archetype, anchoring European OEM supply through converged oil separation and pressure regulation architectures. Cummins Inc. occupies a distinct position among North American heavy-duty equipment manufacturers, representing the calibrated orifice specialization for diesel blow-by management. These three companies illustrate how geographic clustering and technical focus areas segment competitive positioning across thermal cycling specifications and powertrain platform requirements.
| Leading Market Players |
|---|
| Parker Hannifin Corp. |
| Sogefi Spa |
| MANN+HUMMEL |
| SMP Deutschland GmbH |
| Alfdex AB |
| Cummins Inc. |
| Tenneco Inc. |
| Continental AG |
| Aisan Industry Co. Ltd. |
| Others |
Value Network & Pricing Analysis
Yangtze River Delta injection-molding clusters concentrate high-temperature polymer capacity for PCV valve housings, translating into asymmetric pricing power for tier-one suppliers with captive compounding operations versus asset-light contract manufacturers.
Pricing Analysis
Certification level (EPA Tier 3, Euro 7, China GB) creates the primary spread between premium electronic modules and economy mechanical valves. Three-tier pricing structure across OEM-direct, tier-one supply, and aftermarket channels reflects divergent homologation burdens and thermal cycling specifications. Cost compression in fluoroelastomer seal compounds intensifies as FKM resin supply concentrates among Asian chemical producers. Aftermarket distributors exhibit highest price sensitivity due to shorter inventory cycles and diagnostic simplicity requirements.
Supply Chain Analysis
Extended payment terms from German and Japanese OEMs strain tier-two valve assemblers without supply-chain finance facilities, compressing working capital buffers. Manufacturing draws from China, Germany, and Mexico for polymer compounding, precision machining, and final assembly respectively. Fluoropolymer resin and glass-fiber reinforced nylon constitute critical input dependencies. Single-source exposure in East Asian injection-molding capacity creates vulnerability to logistics chokepoints. Distribution runs through tier-one system integrators to OEM powertrain divisions, with aftermarket channels fragmenting toward independent service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electronic PCV valve proliferation in hybrid powertrains threatens mechanical valve incumbents with obsolescence, forcing substitution defense through firmware-capable product architectures.
For Market Incumbents: Build captive polymer compounding moats to control margin across thermal cycling specifications exceeding 150°C. Secure long-term FKM seal compound supply agreements to hedge feedstock volatility from concentrated Asian resin producers. Invest in pulse-width modulation firmware development partnerships to counter electronic valve displacement of mechanical designs. For New Entrants and Emerging Players: Pursue compact PCV module opportunities in India's two-wheeler electrification corridor under tightening BIS emission protocols. Target aftermarket diagnostic tool pairing as a service-margin capture mechanism beyond dealer networks. Enter through Bluetooth-enabled electronic valve specifications that enable independent crankcase pressure data access. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors tier-one system integrators with filter-ventilation module capabilities over standalone valve manufacturers. Long-term viability hinges on electromechanical integration depth across hybrid powertrain platforms. Acquisition targets should demonstrate embedded software competency and OEM validation relationships. Monitor EPA onboard diagnostic threshold enforcement as the signal indicating electronic valve displacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Continental AG's captive operations sustain margin control across turbocharged direct-injection thermal specifications. |
| Pulse-Width Modulation Firmware Development | German and Japanese OEM specifications demand millisecond-response pressure mapping for hybrid stop-start architectures. |
| Filter-Ventilation Module Convergence | MANN+HUMMEL's integrated designs reduce assembly steps for European powertrain integration teams. |
| Aftermarket Diagnostic Tool Partnership | Independent service channels in the United States capture disintermediation through specialized crankcase pressure equipment. |
| China GB Standard Compliance Investment | MEE dual carbon goals accelerate replacement cycles for mechanical valve inventories in domestic engine production. |
Research Methodology
Cross-validation between OEM platform engineering disclosures and tier-one supplier procurement patterns anchors the qualitative findings. Primary interviews with powertrain integration directors, thermal management specialists, aftermarket distribution managers, and polymer compounding engineers informed structural assessments. Secondary sources include EPA Tier 3 enforcement documentation, EMA Euro 7 type-approval protocols, China GB standard filings, and vehicle production databases. Bottom-up segmentation triangulation against top-down regulatory impact modeling ensures consistency across volume and value estimates.
Calibration against historical replacement cycle data and powertrain electrification roadmaps shapes the projection framework across the analysis window. Segmentation dimensions encompass actuation technology, material selection, installation architecture, and regional regulatory cluster. CAGRs derive from regression analysis of content-per-vehicle trends and emission standard phase-in schedules. Hybrid powertrain penetration rates and thermal cycling specification escalation constitute primary forecast inputs.
Sensitivities concentrate around Euro 7 cold-start mandate enforcement timing and fluoroelastomer feedstock price volatility. Forecasts reflect assumptions regarding OEM platform sharing and tier-two supplier consolidation trajectories. Macroeconomic contraction affecting light-duty vehicle production, regulatory delay in China GB implementation, or breakthroughs in solid-state crankcase pressure sensing would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Automotive Balance Shaft Market
Powertrain
Natural Gas Engines Market
Powertrain
Automotive Tuner Market
Powertrain
Drive Mode-Linked Powertrain Actuator Systems Market
Powertrain
Engines Market
Powertrain
Europe Electrically Powered Hydraulic Steering Market
Powertrain
Automotive Turbocharger Hose Market
Powertrain
Asia-Pacific Automotive Engine Oils Market
Powertrain
Automotive Fuel Feed Pumps Market
Powertrain
Engine Tuner Market
Powertrain
Mechanical Reciprocating Engine Market
Powertrain
Global Automotive Engine Belt and Hose Market
Powertrain
Advanced Gear Shifter System Market
Powertrain
Tachometer Market
Powertrain
Asia Pacific Electrically Powered Hydraulic Steering Market
Powertrain
Automotive Intermediate Shaft Market