
 Hydrostatic Transmission Market | 2026-2036
Hydrostatic Transmission Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrostatic Transmission Market Analysis
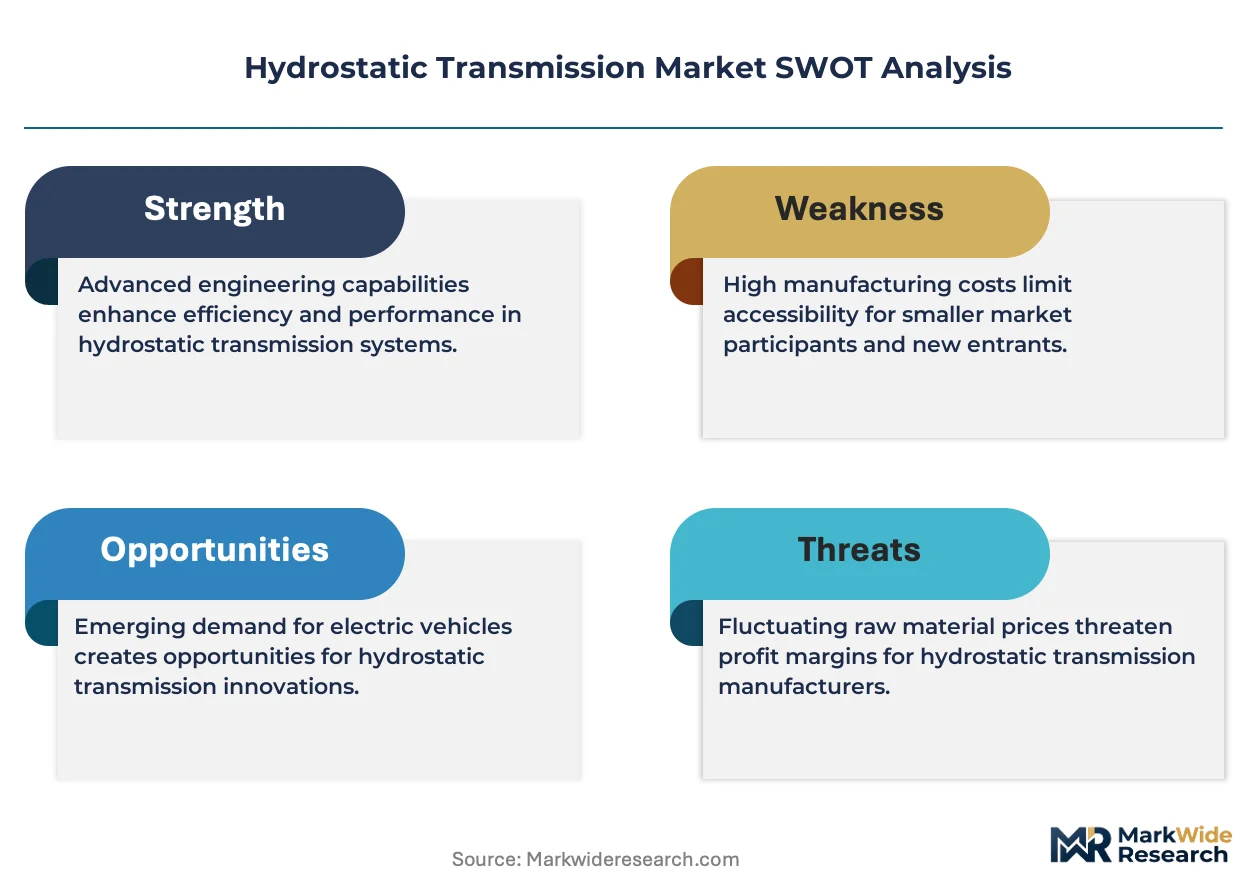
Aluminum housings is restructuring cost structures across hydrostatic transmission architectures by displacing traditional cast-iron enclosures without sacrificing pressure ratings. Dana Incorporated leverages in-house casting capabilities to anchor North American supply for off-highway OEMs. Bosch Rexroth AG dominates closed-loop system engineering through its deep R&D footprint in Germany. Danfoss Power Solutions extends its position in electronic control modules that integrate with variable-displacement pump platforms.
Hydrostatic transmission refers to a fluid power system that transmits rotational mechanical energy through pressurized hydraulic oil circulating between a variable-displacement pump and a hydraulic motor, typically operating at continuous pressures of 350–450 bar. Its primary purpose is to provide stepless speed variation and high torque at low speeds for heavy mobile equipment. Piston pumps command the dominant margin pool due to precision machining requirements and replacement-part premiums. Agricultural machinery applications are expanding fastest in regions where tractor horsepower ratings climb toward 300 hp and above. Closed-loop technology leads in construction and mining segments where regenerative braking and energy recovery justify higher system complexity.
EPA Tier 4 Final and EU Stage V emissions frameworks compel engine downsizing, which in turn elevates hydrostatic systems as the torque multiplication layer that preserves machine performance. ISO 4406 cleanliness standards and IEC functional-safety ratings determine component qualification for OEM supply contracts. OEM procurement teams must weigh captive electronic control development against sourcing from established hydraulic-electronic integrators as machine electrification advances.
Market Dynamics
Engine downsizing mandates across major economies are forcing OEMs to treat hydrostatic transmissions as torque multiplication layers rather than simple driveline components, fundamentally repositioning these systems within machine architecture.
Growth Catalysts
- EPA Tier 4 Final:US emissions rules compel diesel engine downsizing for off-highway equipment, elevating hydrostatic systems as the compensatory torque source.
- Precision agriculture expansion:German farmers are upgrading tractor fleets toward 300+ horsepower ratings, driving closed-loop transmission demand in high-tillage applications.
- Aluminum casting advances:Pressure-tight aluminum housings now withstand 450-bar continuous operation, cutting component weight by one-third versus cast iron.
Market Restraints
- Steel and rare-earth input volatility:Neodymium magnet costs for high-efficiency pump motors fluctuate with Chinese export quotas, squeezing margin predictability.
- Closed-loop hydraulic oil dependency:System performance hinges on ISO 4406 cleanliness compliance, creating qualification bottlenecks for secondary suppliers.
- Electric drivetrain substitution:Battery-electric wheel loaders and excavators in urban construction zones bypass hydrostatic architectures entirely.
Strategic Opportunities
- China's mining provinces:Shanxi and Inner Mongolia coal operations are modernizing haul fleets, creating demand for regenerative braking-capable transmissions.
- Variable-displacement pump-electronics convergence:Integration of CANbus control modules with axial-piston platforms enables telematics-ready drivelines.
- EU Stage V retrofit incentives:German and French equipment renewal programs subsidize Tier 4 Final-compliant transmission upgrades in aging agricultural fleets.
Industry Challenges
- Hydraulic-fluid chemist scarcity:Formulation expertise for biodegradable, high-pressure lubricants concentrates among a handful of European additive houses.
- Functional-safety certification timelines:IEC 61508 SIL ratings for electronic pump controls require 18–24 month validation cycles, delaying OEM platform launches.
- Legacy mechanical interface integration:Retrofitting electronically controlled transmissions into existing axle and PTO architectures demands custom engineering for each chassis.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrostatic Transmission Market |
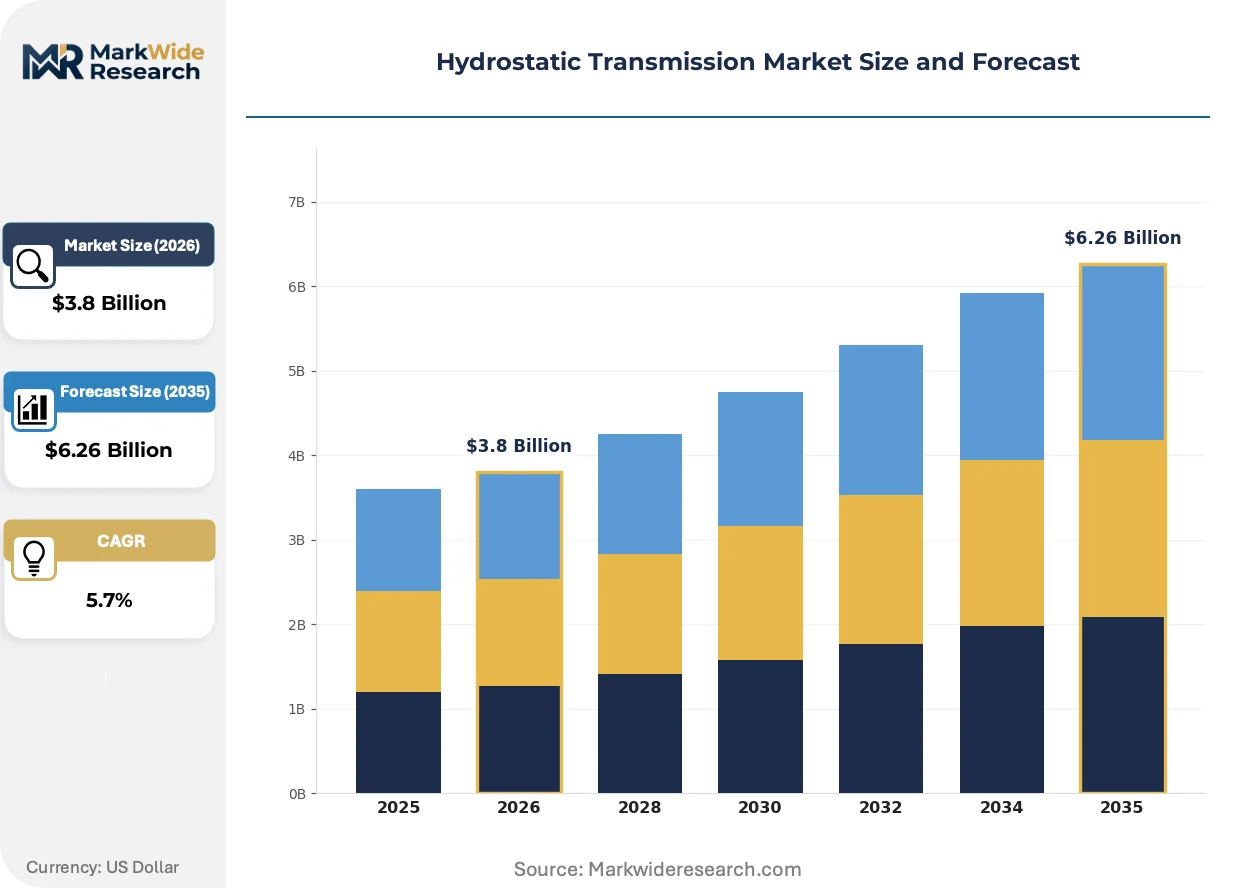
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Piston Pumps, Gear Pumps, Motors, Valves End User: Agriculture, Construction, Automotive, Mining Application: Material Handling, Agricultural Machinery, Industrial Equipment, Off-Road Vehicles Technology: Open Loop, Closed Loop, Variable Displacement, Fixed Displacement |
| Companies Covered | Dana Incorporated, Linde Hydraulics GmbH & Co. KG, Danfoss Power Solutions, Carraro SpA, Kawasaki Heavy Industries Ltd., Parker Hannifin Corporation, Bosch Rexroth AG, Tuff Torq Corporation, Eaton Corporation PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrostatic Transmission Market Emerging Trajectories
Electrification of auxiliary systems and digitalization of fluid power control are converging to redefine how hydrostatic architectures interface with machine-level energy management.
Electro-hydrostatic actuation is unifying power generation and motion control in compact loaders and telehandlers. Construction OEMs in Germany and Japan are piloting these self-contained pump-motor units to eliminate separate hydraulic circuits. This unification compresses the traditional valve-pump-motor supply chain into single-source procurement relationships.
EU Stage V emissions frameworks are tightening particulate matter limits for non-road mobile machinery. The regulation forces engine-aftertreatment packaging that crowds engine bays, pushing hydraulic component miniaturization. Agricultural tractor manufacturers in France and Italy are responding with axial-piston pumps redesigned for sub-200mm envelope dimensions.
Equipment owners are bundling transmission maintenance into total-cost-of-ownership contracts rather than transactional parts purchases. Rental fleet operators in the US and Canada now specify guaranteed fluid cleanliness and replacement-pump availability as contract terms. This shift concentrates aftermarket revenue with hydraulic-electronic integrators who can warranty system-level performance.
Hydrostatic Transmission Market Segmentation
Segmentation reveals where capital deployment concentrates and which machine architectures drive component specification. Procurement patterns diverge sharply between closed-loop mining systems and open-loop agricultural drivelines.
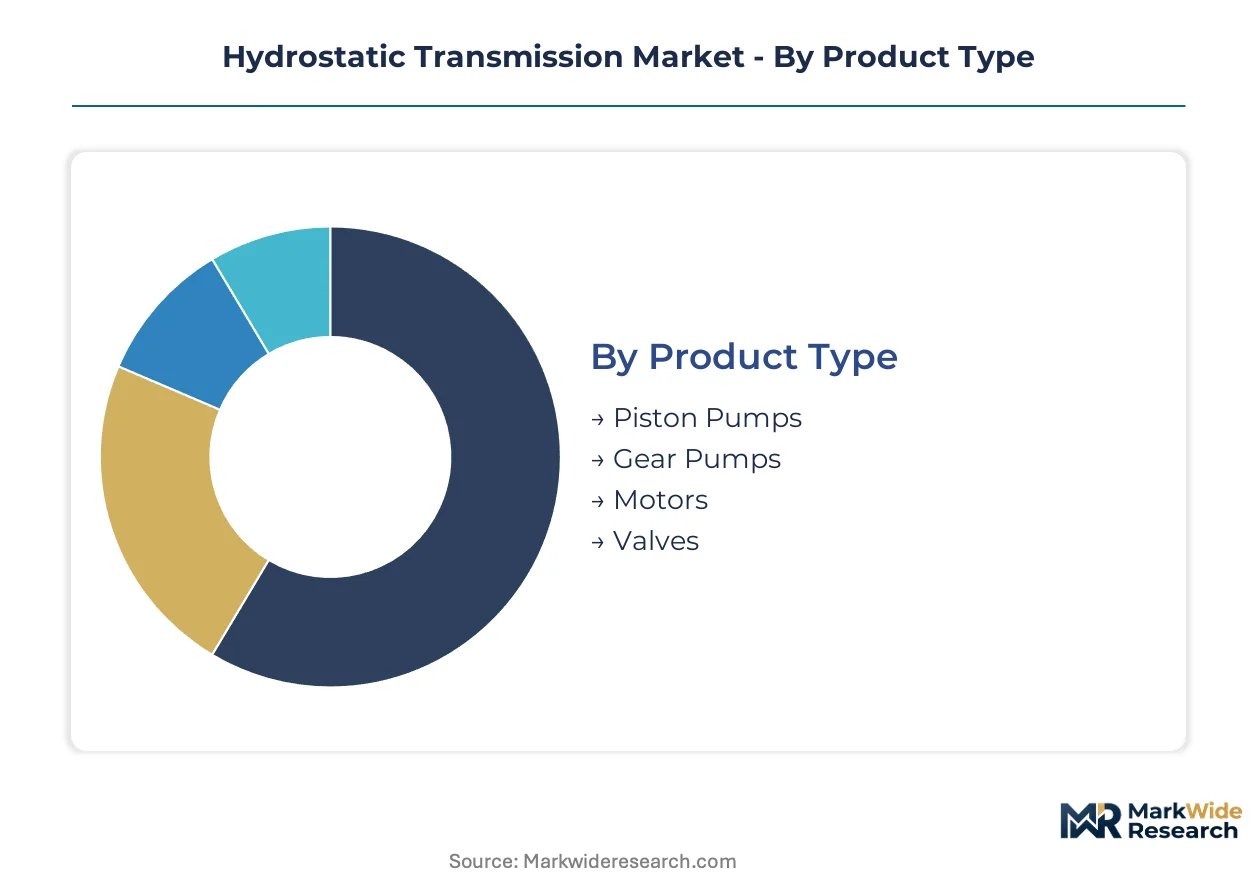
Product Type:
Precision machining requirements and replacement-part premiums create steep capital barriers across component categories.
- Piston Pumps:Axial-piston architectures deliver 350–450 bar continuous pressure ratings through hardened steel cylinder blocks and precision-ground valve plates. German agricultural OEMs specify these for 300+ horsepower tractors where tillage loads demand stepless torque multiplication. ISO 4406 cleanliness standards and lengthy validation cycles protect incumbent suppliers.
- Gear Pumps:External-gear designs circulate hydraulic oil at lower pressure thresholds with simpler casting requirements. Material handling equipment in North American distribution centers favors these for first-cost sensitivity and maintenance accessibility. Aluminum housing adoption is displacing cast-iron enclosures without sacrificing durability ratings.
- Motors:Orbital and axial-piston motor configurations convert fluid pressure into rotational mechanical energy at the wheel or implement.
- Valves:Directional and pressure-control valves regulate flow distribution between pump and motor circuits.
Piston pumps absorb the bulk of installed capacity; gear pumps are expanding most quickly in cost-sensitive applications.
End User:
Emissions compliance timelines and fleet renewal cycles determine regional demand concentration across equipment sectors.
- Agriculture:German and French precision agriculture belts are upgrading tractor fleets toward 300+ horsepower ratings. EU Stage V retrofit incentives subsidize Tier 4 Final-compliant transmission upgrades in aging equipment pools. Closed-loop systems dominate high-tillage applications where regenerative braking recovers implement energy.
- Construction:EPA Tier 4 Final rules compel diesel engine downsizing for US off-highway equipment. Hydrostatic architectures compensate as torque multiplication layers that preserve machine performance with smaller displacement powerplants. Urban construction zones in Japan and Germany are piloting electro-hydrostatic actuation to eliminate separate hydraulic circuits.
- Automotive:Specialty vehicle applications include airport ground support equipment and municipal utility trucks requiring precise speed control.
- Mining:Shanxi and Inner Mongolia coal operations in China are modernizing haul fleets with regenerative braking-capable transmissions.
Construction commands the largest equipment population; agriculture is climbing the fastest on horsepower escalation trends.
Application:
Operating duty cycles and contamination exposure differentiate specification requirements across use cases.
- Material Handling:Forklifts and telehandlers demand compact pump-motor envelopes that fit crowded engine bays crowded by aftertreatment packaging. CANbus-integrated electronic controls enable telematics-ready drivelines for rental fleet operators specifying guaranteed fluid cleanliness contracts.
- Agricultural Machinery:Tractors, combines, and self-propelled sprayers operate across seasonal intensity patterns with extended idle periods. Biodegradable hydraulic fluid formulations address spill-sensitive watersheds in France and Italy where additive house expertise concentrates.
- Industrial Equipment:Stationary applications include injection molding and metal forming where constant-pressure operation dominates.
- Off-Road Vehicles:Wheel loaders and excavators in North American construction fleets are converting to hydrostatic drivelines for fuel efficiency gains.
Material handling anchors replacement-part revenue; agricultural machinery is gaining share fastest on precision farming capital investment.
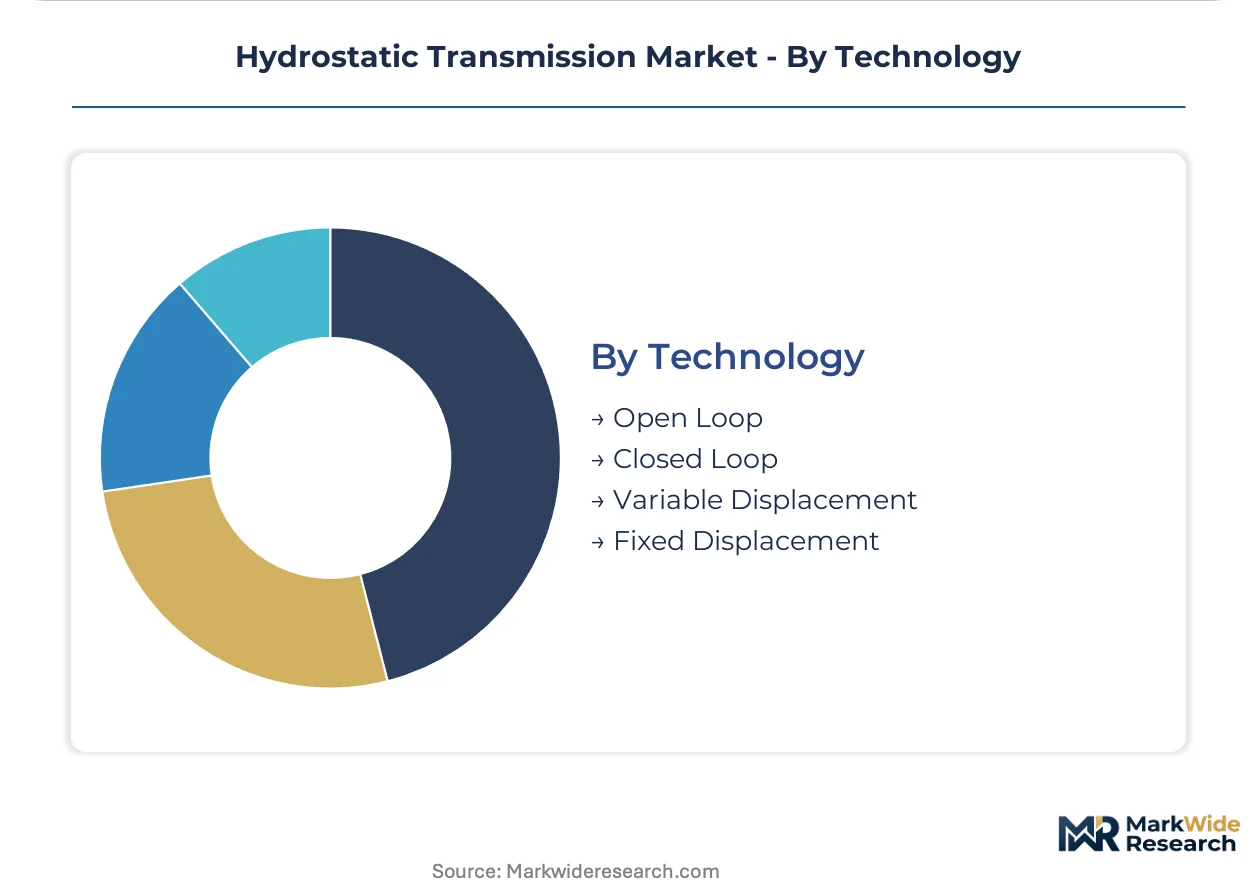
Technology:
System complexity trade-offs separate energy recovery architectures from simpler first-cost alternatives.
- Closed Loop:Circulating hydraulic oil flows directly between pump and motor without reservoir return, enabling regenerative braking and energy recovery. Mining haul trucks in China's expanding provinces specify these for downhill braking duty. IEC 61508 SIL ratings for electronic pump controls require 18–24 month validation cycles.
- Open Loop:Pump output returns to reservoir after motor passage, simplifying circuit design and maintenance access. Lower-cost agricultural and material handling equipment favors these where energy recovery does not justify complexity premiums.
- Variable Displacement:Swashplate angle adjustment matches pump output to instantaneous power demand, cutting parasitic losses.
- Fixed Displacement:Constant-volume output suits applications with steady-state load profiles and minimal speed variation requirements.
Closed-loop systems dominate premium equipment specification; variable displacement is expanding most quickly on electrification integration trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision agriculture and Chinese mining modernization anchor demand concentration, while EPA Tier 4 Final compliance drives North American fleet conversions. Regulatory emissions frameworks and horsepower escalation trends determine regional investment cycles across equipment sectors.
United States
Construction equipment fleets in the Midwest and Southeast are converting to hydrostatic drivelines for fuel efficiency gains. EPA Tier 4 Final emissions rules compel diesel engine downsizing, elevating hydrostatic systems as torque multiplication layers. Ohio and Illinois manufacturing clusters supply off-highway OEMs with aluminum-housed transmission architectures.
Germany
Farmers in Bavaria and Lower Saxony are upgrading tractor fleets toward 300+ horsepower ratings for high-tillage applications. EU Stage V retrofit incentives subsidize Tier 4 Final-compliant transmission upgrades in aging agricultural equipment pools. Stuttgart and Munich engineering centers dominate closed-loop system R&D for precision agriculture.
China
Coal operations in Shanxi and Inner Mongolia are modernizing haul fleets with regenerative braking-capable transmissions. The country's national emissions regulator enforces non-road mobile machinery standards that accelerate equipment replacement cycles. Heavy machinery manufacturing concentrates in Changzhou and Jinan industrial zones.
Japan
Construction OEMs in Kansai and Chubu regions are piloting electro-hydrostatic actuation to eliminate separate hydraulic circuits in compact loaders. METI industrial efficiency guidelines favor integrated pump-motor units for urban equipment applications. Nagoya-based fabricators supply axial-piston platforms for telematics-ready drivelines.
France
Agricultural machinery demand in Île-de-France and Auvergne-Rhône-Alpes is climbing on precision farming capital investment. EU Stage V frameworks tighten particulate matter limits, forcing hydraulic component miniaturization in crowded engine bays. Lyon and Paris engineering clusters specialize in biodegradable hydraulic fluid formulations for spill-sensitive watersheds.
Hydrostatic Transmission Market Vendor Landscape
Strategic partnerships dominate the current landscape as electronic-hydraulic convergence demands cross-domain expertise. The vendor base clusters around three archetypes: diversified fluid power conglomerates with captive electronics divisions, specialized pump-motor fabricators with regional foundry networks, and precision machining houses serving aftermarket replacement channels. M&A activity and technology licensing agreements represent the primary competitive moves as OEMs consolidate supplier relationships.
Among diversified fluid power conglomerates, Dana Incorporated, Bosch Rexroth AG, and Danfoss Power Solutions exemplify the integrated electronics-hydraulics archetype. Dana's in-house casting capabilities anchor North American supply positions for off-highway OEMs. Bosch Rexroth occupies a position within closed-loop system engineering through its Germany-based R&D footprint. Danfoss sits within the electronic control module segment, integrating CANbus platforms with variable-displacement pump architectures. These three represent distinct geographic anchoring strategies across North American, European, and integrated electronics supply chains.
| Leading Market Players |
|---|
| Dana Incorporated |
| Linde Hydraulics GmbH & Co. KG |
| Danfoss Power Solutions |
| Carraro SpA |
| Kawasaki Heavy Industries Ltd. |
| Parker Hannifin Corporation |
| Bosch Rexroth AG |
| Tuff Torq Corporation |
| Eaton Corporation PLC |
| Others |
Supply Flow & Price Mechanics
Neodymium magnet costs for high-efficiency pump motors trace a volatile path from Chinese export quota policies through to finished transmission pricing tiers, compressing margin predictability for European and North American fabricators while amplifying procurement leverage for integrated conglomerates with captive rare-earth sourcing.
Pricing Analysis
Volume-driven gear pump segments sacrifice margin for fleet placement, while precision-machined piston pump architectures command premium positioning through ISO 4406 cleanliness certification and replacement-part exclusivity. Three-tier pricing structure across premium, standard, and economy levels separates closed-loop mining systems with regenerative braking from open-loop agricultural drivelines. Price erosion runs through aluminum housing commoditization as foundry capacity expands in Ohio and Illinois. Rental fleet operators exhibit lowest price sensitivity due to total-cost-of-ownership contracting, whereas independent agricultural equipment owners drive hardest bargain on first-cost.
Supply Chain Analysis
Precision machining expertise concentrates in Stuttgart, Changzhou, and Nagoya industrial zones, where skilled workforce availability constrains capacity expansion for hardened steel cylinder blocks and valve plate grinding operations. Supply chains draw from German additive houses for biodegradable hydraulic formulations, Chinese rare-earth processors for neodymium magnets, and North American aluminum foundries for pressure-tight housings. Single-source vulnerability in high-grade steel cylinder block supply from German and Japanese specialty mills threatens OEM platform launch timelines. Distribution runs through hydraulic-electronic integrators who warranty system-level performance for rental fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market occupies a technology-transition phase as electro-hydrostatic actuation displaces traditional valve-pump-motor architectures in compact loaders and telehandlers, compressing supply chains and redefining procurement relationships.
For Market Incumbents: Extend electronic control module capabilities through CANbus integration investments that anchor telematics-ready driveline contracts with rental fleet operators. Battery-electric wheel loader substitution in urban construction zones threatens hydrostatic system relevance; counter by deepening backward integration into aluminum casting to defend cost position against commodity housing suppliers. For New Entrants and Emerging Players: The premium-to-economy price gap in closed-loop agricultural transmissions offers white-space entry for specialized pump-motor fabricators targeting 200-300 horsepower tractor retrofits in France and Italy. Target EU Stage V retrofit incentive programs as the most penetrable demand pool. Pursue guaranteed fluid cleanliness contracting as the go-to-market angle that differentiates from transactional parts vendors. For Investors and Strategic Acquirers: German engineering center consolidation announcements are the leading indicator that precision agriculture R&D is concentrating among fewer closed-loop system architects. Five-to-ten year viability favors hydraulic-electronic integrators over pure-play mechanical fabricators. Acquire specialized machining houses with ISO 4406 qualification track records. Watch for OEM procurement team shifts from captive electronic development to external sourcing as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Electro-Hydrostatic Actuation Development | Unifies pump-motor units for compact loaders, eliminating separate hydraulic circuits per German OEM pilots. |
| Aluminum Housing Foundry Investment | Captures weight reduction demand from EPA Tier 4 Final engine downsizing in North American construction fleets. |
| CANbus Control Module Integration | Enables telematics-ready drivelines that rental fleet operators specify in total-cost-of-ownership contracts. |
| Biodegradable Fluid Formulation Partnership | Addresses EU Stage V spill-sensitive watershed requirements in French and Italian precision agriculture belts. |
| Closed-Loop System Certification Acceleration | Compresses IEC 61508 SIL rating timelines to match OEM platform launch cycles in mining modernization provinces. |
Methodological Framework
Independent corroboration across OEM procurement directors, aftermarket service heads, and hydraulic component engineering leads underwrites the qualitative findings in this study. Secondary validation draws from EPA regulatory filings, EU Stage V implementation directives, SEC 10-K disclosures from diversified fluid power conglomerates, and customs data tracking aluminum housing trade flows. Bottom-up equipment population modeling triangulates against top-down market sizing from transmission content-per-machine estimates.
Comparable-period anchoring to historical fleet renewal cycles and emissions compliance deadlines structures the projection horizon across the analysis window. Segmentation dimensions include product architecture (piston versus gear pump), end-use equipment sector (agriculture, construction, mining), technology complexity (closed-loop versus open-loop), and regional regulatory cluster (EPA Tier 4 Final, EU Stage V, China non-road mobile machinery standards). CAGRs derive from equipment replacement elasticity estimates and horsepower escalation trends in precision agriculture.
Inputs from OEM procurement teams and foundry operators were available through the study window; gaps in neodymium magnet pricing transparency and Chinese mining fleet modernization timelines introduce uncertainty bands around regenerative braking transmission forecasts. Assumptions reflect current emissions enforcement trajectories and aluminum casting yield improvements. Material deviation in rare-earth export policy or battery-electric construction equipment adoption rates warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Locomotive Pantographs Market
Vehicle Components
China Forklift Battery Market
Vehicle Components
Car Radiator Market
Vehicle Components
Mechanical Control Cables Market
Vehicle Components
Brake Hoses Market
Vehicle Components
Global Automotive Carbon Monocoque Chassis Market
Vehicle Components
Vehicle Pillar Market
Vehicle Components
Exhaust Gas Recirculation (EGR) Valve Market
Vehicle Components
Advanced Driver Assistance System (ADAS) Sensor Market
Vehicle Components
Hydraulic Actuators Market
Vehicle Components
Global Automotive EGR Valves Market
Vehicle Components
Tricycle Vending Cart Market
Vehicle Components
Steering Knuckle Market
Vehicle Components
Automotive Position Sensor Market
Vehicle Components
Japan Automotive Pneumatic Actuators Market
Vehicle Components
Towing Equipment Market