
 India Automotive Steering System Market | 2026-2036
India Automotive Steering System Market Size, Share, and Industry Trends Forecast 2026-2036
India Automotive Steering System Market Insights
Market Dynamics
Bharat Stage VI Phase II emission norms is restructuring the cost-of-entry calculus for steering system suppliers serving India's automotive sector. Bosch Auto Parts leverages its in-house electronics capabilities to dominate the electric power steering segment. JTEKT Corporation anchors its position through dedicated R&D centers in Haryana and Tamil Nadu. ZF Steering Gear India sustains manufacturing scale across its Halol and Mysuru plants.
Technology Landscape
India Automotive Steering System encompasses the mechanical and electromechanical assemblies that translate driver rotational input into angular wheel displacement, typically incorporating rack-and-pinion gear sets, steering columns, and electronic control modules operating at 12V or 48V architectures depending on vehicle electrification level. Electric Steering leads product type demand as OEMs pursue fuel efficiency gains and modular platform compatibility, while Hydraulic Steering retains substantial share in commercial vehicle applications where load-bearing capacity demands persist. Electric Vehicles represent the fastest-expanding vehicle type segment, drawing disproportionate technology investment from Tier-1 Suppliers who must adapt Column Steering architectures to skateboard platform designs.
Regulatory Environment
BIS mandates steering system durability and safety testing under automotive component certification protocols, while the Ministry of Road Transport and Highways enforces crashworthiness standards that cascade into structural requirements for steering column integrity. The Automotive Research Association of India conducts homologation assessments that determine market access for both domestic producers and imported sub-assemblies. Stakeholders must monitor how the proposed Vehicle Scrappage Policy expansion reshapes aftermarket demand patterns and influences OEM sourcing strategies for replacement-compatible steering platforms.
Market Dynamics
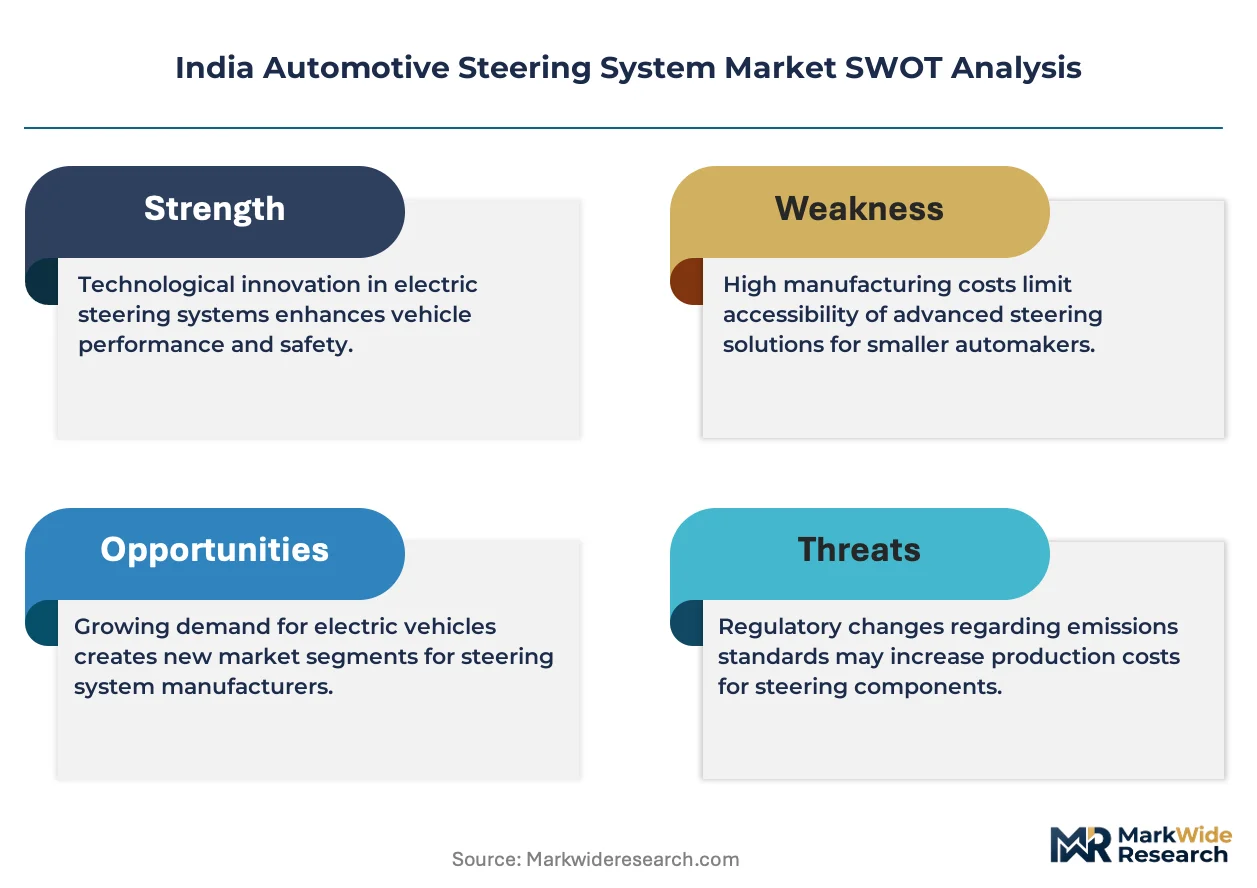
Electric power steering architectures are displacing hydraulic systems across India's passenger vehicle segment, driven by Bharat Stage VI Phase II efficiency mandates and the Automotive Mission Plan's localization targets for electromechanical sub-assemblies.
Growth Catalysts
- Automotive Mission Plan localization mandates:Tier-1 suppliers must achieve defined domestic value-add thresholds for electric steering components, accelerating in-house motor and ECU production.
- Tamil Nadu corridor concentration:Chennai-Sriperumbudur's integrated electronics ecosystem enables just-in-time delivery of steering control modules to adjacent OEM assembly plants.
- 48V mild-hybrid proliferation:Higher voltage architectures demand redesigned power steering inverters, opening procurement windows for suppliers with automotive electronics capabilities.
Market Restraints
- Rare earth magnet supply concentration:Permanent magnet motors in EPS units depend on neodymium-dysprosium supply chains concentrated outside India's trade agreements.
- BIS certification timeline friction:Steering system homologation requires sequential durability testing that extends supplier qualification cycles by 8-14 months.
- Hydraulic steering installed base:Commercial vehicle fleets retain hydraulic architectures for load-bearing applications, fragmenting R&D investment across dual technology tracks.
Strategic Opportunities
- Skateboard platform convergence:Dedicated EV architectures enable column-mounted steering module standardization across multiple vehicle classes.
- Maharashtra supplier park expansion:Pune-Nashik belt offers underutilized industrial land for steering system Tier-2 component clustering.
- Vehicle Scrappage Policy aftermarket:Expanded end-of-life mandates will generate replacement demand for steering columns and rack-and-pinion assemblies in aging vehicle parc.
Industry Challenges
- Embedded software talent scarcity:EPS development requires automotive-grade firmware engineers proficient in ISO 26262 functional safety standards.
- Legacy hydraulic supplier transition:Established pump and hose manufacturers face capex burdens to retool for electromechanical production lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Automotive Steering System Market |
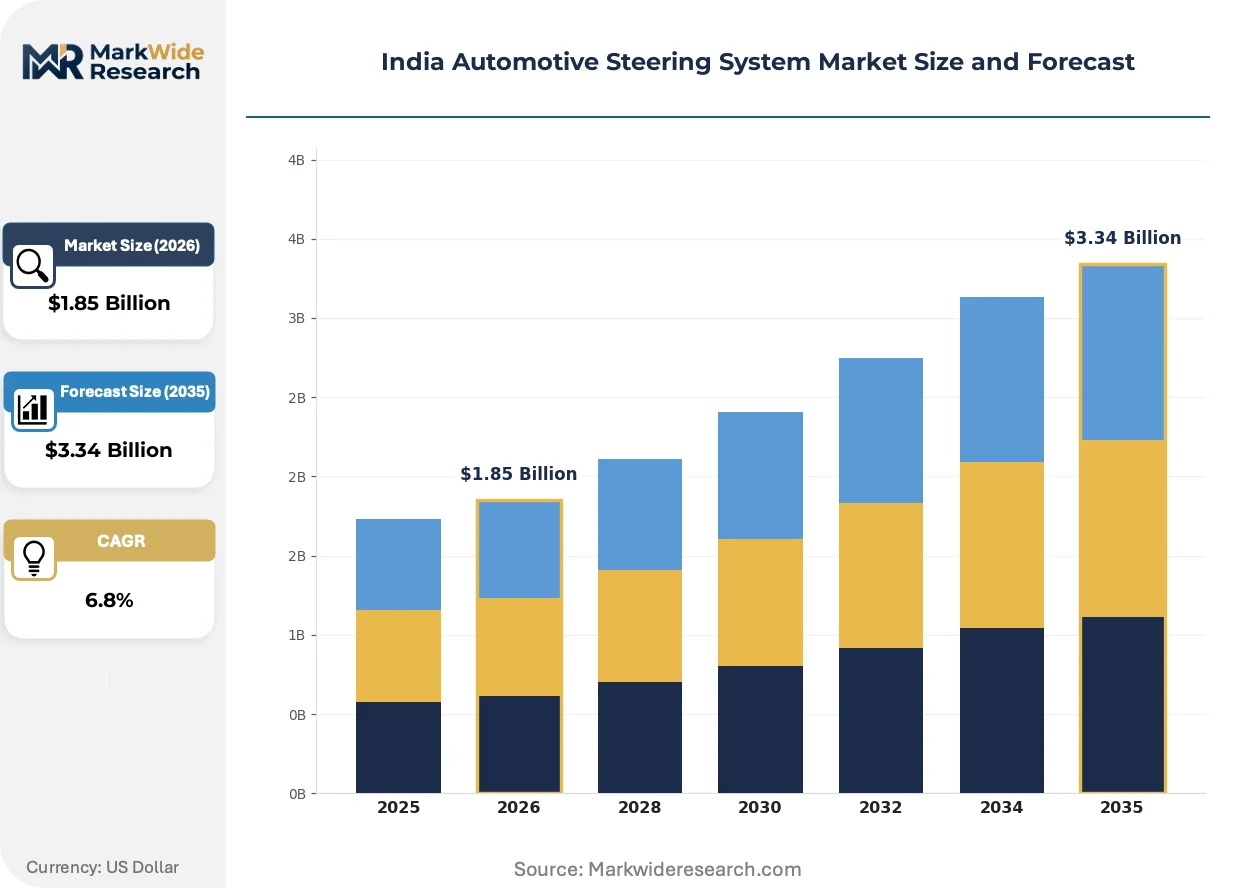
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Steering, Hydraulic Steering, Pneumatic Steering, Manual Steering End User: OEMs, Aftermarket Providers, Fleet Operations, Tier-1 Suppliers Technology: Active Steering, Power Steering, Variable Gear Ratio, Column Steering Vehicle Type: Passenger Cars, Commercial Vehicles, Two-Wheelers, Electric Vehicles |
| Companies Covered | Nexteer Automotive, WABCO, Rane Holdings Limited, Bosch Auto Parts, Knorr-Bremse, JTEKT Corporation, Mando Corporation, DENSO Corporation, ZF Steering Gear India, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Automotive Steering System Market Trends and Innovations
Steer-by-wire technology is migrating from concept vehicles to production roadmaps, compressing mechanical linkage requirements and redrawing supplier boundaries between chassis and electronics specialists.
Column-mounted electric power steering is modularizing across India's passenger vehicle platforms. This architecture integrates the motor, reduction gear, and torque sensor into a single replaceable unit. Maruti Suzuki and Hyundai Motor India are deploying these modules across compact and mid-size vehicle lines. The technology is modularizing supplier relationships, enabling OEMs to source complete steering columns rather than discrete hydraulic components.
Bharat Stage VI Phase II norms are mandating real-time fuel consumption optimization that electric steering directly enables. The regulation requires onboard diagnostics to monitor energy efficiency across auxiliary systems. Passenger vehicle OEMs are responding by eliminating hydraulic pumps that impose constant engine load. Commercial vehicle manufacturers face harder trade-offs between efficiency gains and load-bearing hydraulic performance.
Fleet operators are unbundling steering system maintenance from comprehensive service contracts. Large logistics companies now negotiate direct spare parts procurement for rack-and-pinion replacements rather than accepting OEM dealer markups. Tamil Nadu's commercial vehicle density makes this pattern most visible, with independent workshops capturing steering repair volume from authorized service networks.
India Automotive Steering System Market Segmentation
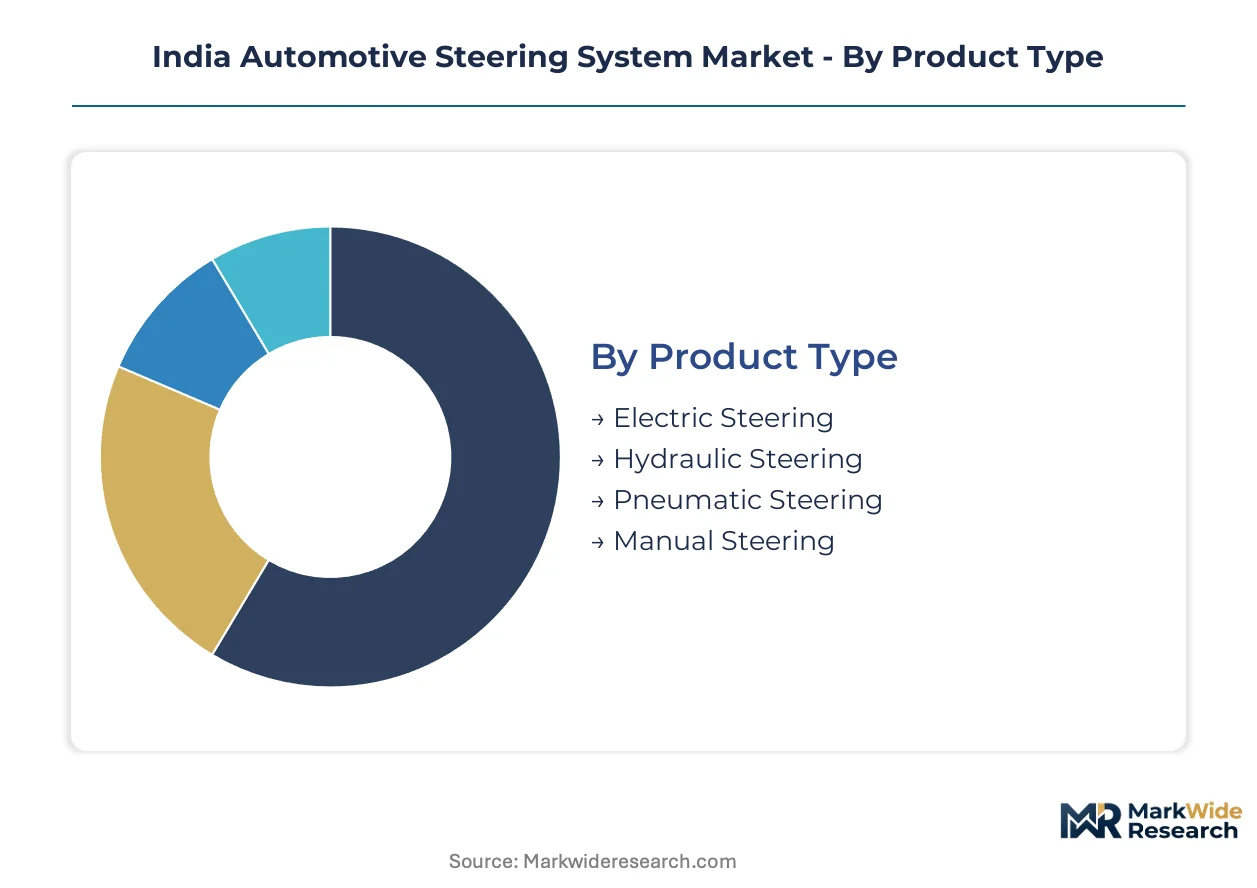
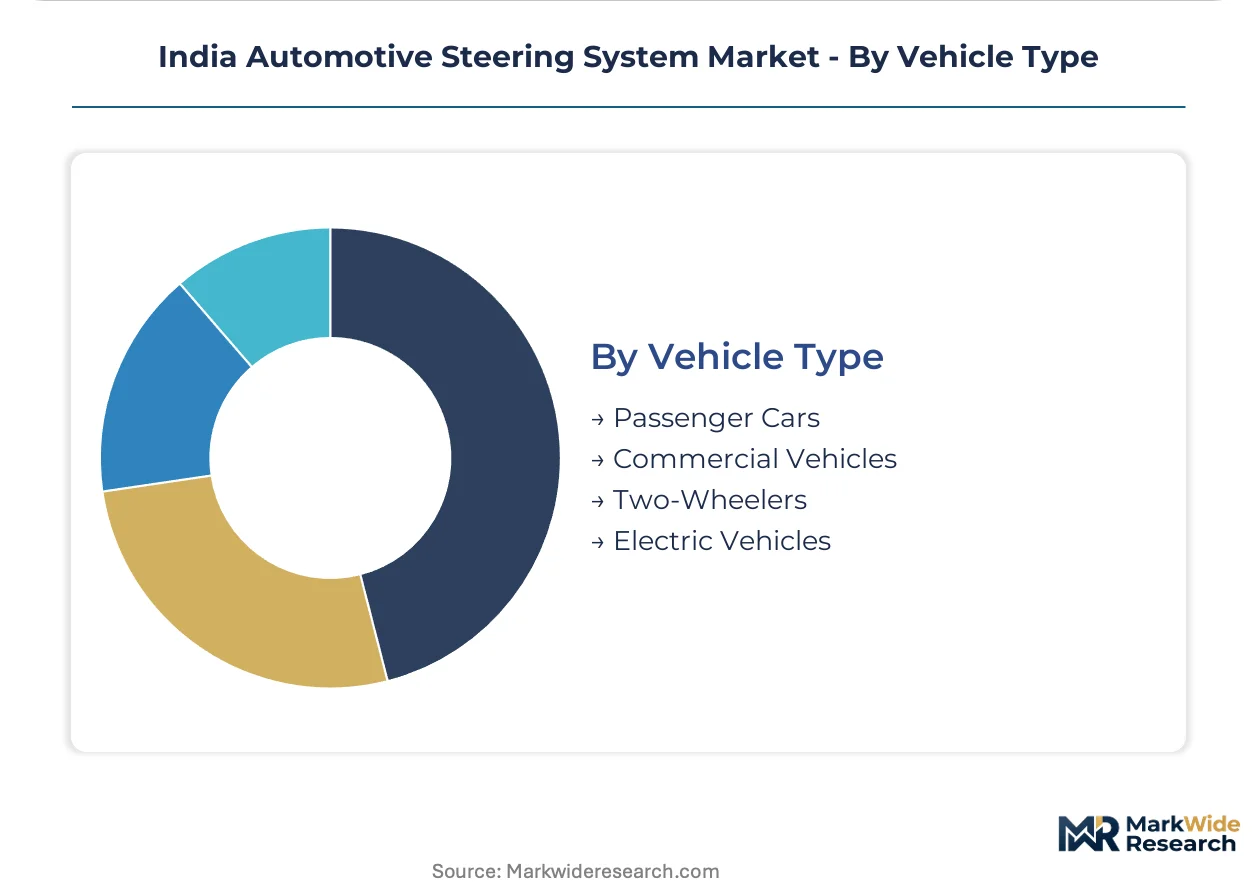
India's automotive steering system market fragments across four distinct dimensions. Each category reflects divergent engineering requirements, procurement patterns, and regulatory exposure. Understanding these splits clarifies where capital is concentrating and which technology platforms will dominate installed capacity through the forecast window.
Product Type:
Customization intensity varies sharply across this spectrum, from standardized electric modules to application-specific hydraulic architectures.
- Electric Steering:Electromechanical systems integrate brushless DC motors, torque sensors, and ECUs into column-mounted or rack-mounted configurations. Demand clusters in Tamil Nadu's Chennai-Sriperumbudur corridor where Maruti Suzuki and Hyundai Motor India operate high-volume assembly plants. BIS certification for motor durability and electromagnetic compatibility extends supplier qualification timelines.
- Hydraulic Steering:Pump-driven systems with fluid reservoirs and servo valves retain dominance in commercial vehicle load-bearing applications. Maharashtra's Pune-Nashik belt hosts the densest concentration of hydraulic steering production for truck and bus OEMs. Bharat Stage VI Phase II efficiency mandates are compressing this segment's growth trajectory in passenger vehicles.
- Pneumatic Steering:Compressed-air actuated systems serve specialized heavy-duty mining and construction equipment with extreme load requirements.
- Manual Steering:Unassisted rack-and-pinion mechanisms persist in economy two-wheelers and entry-level commercial three-wheelers where cost minimization overrides driver comfort specifications.
Most installed capacity flows through Electric Steering. Expansion is steepest in this same segment as 48V mild-hybrid architectures proliferate.
End User:
Procurement authority concentrates differently across this category, from consolidated OEM specification power to fragmented aftermarket price sensitivity.
- OEMs:Original equipment manufacturers exercise direct design authority over steering system architecture, sourcing complete electromechanical modules or hydraulic assemblies for vehicle platform integration. Tamil Nadu and Maharashtra assembly plants drive the highest procurement volumes, with just-in-time delivery requirements forcing Tier-1 suppliers to co-locate manufacturing capacity within 50-kilometer radii.
- Aftermarket Providers:Independent distributors and service networks supply replacement steering columns, rack-and-pinion assemblies, and hydraulic pump rebuilds for India's aging vehicle parc. The proposed Vehicle Scrappage Policy expansion will reshape demand patterns as older commercial vehicles exit circulation and replacement-compatible steering platforms gain priority.
- Fleet Operations:Large logistics companies negotiate direct spare parts procurement, unbundling steering maintenance from comprehensive service contracts to bypass OEM dealer markups.
- Tier-1 Suppliers:Mid-tier component manufacturers source sub-assemblies like steering angle sensors and electric motor housings for integration into complete system modules.
Volume dominance sits with OEMs. Margin expansion is most pronounced in Fleet Operations as direct procurement models mature.
Technology:
Engineering maturity spans from proven power assistance architectures to emerging steer-by-wire prototypes.
- Active Steering:Systems with variable steering ratio adjustment based on vehicle speed and yaw rate, requiring sophisticated sensor fusion and chassis domain integration. Development concentrates in supplier R&D centers in Haryana where embedded software talent scarcity constrains expansion timelines.
- Power Steering:Conventional hydraulic or electric assistance systems that reduce driver effort through mechanical advantage, representing the installed base majority across India's vehicle parc.
- Variable Gear Ratio:Mechanically or electronically modulated rack-and-pinion geometries that adjust steering sensitivity without full active control capability.
- Column Steering:Integrated motor-reduction gear-torque sensor units mounted directly on the steering column, modularizing across passenger vehicle platforms and enabling skateboard EV architecture compatibility.
Deployment scale favors Power Steering. Technology investment is heaviest in Active Steering as functional safety standards tighten.
Vehicle Type:
Platform electrification level determines voltage architecture and steering system specification intensity.
- Passenger Cars:Compact and mid-size vehicles are eliminating hydraulic pumps in favor of column-mounted electric power steering modules. Maruti Suzuki and Hyundai Motor India deployment patterns establish procurement specifications that cascade to smaller OEMs.
- Commercial Vehicles:Trucks and buses retain hydraulic steering for load-bearing capacity, though 48V mild-hybrid trials are beginning in long-haul segments. Fleet operator maintenance unbundling is reshaping aftermarket demand in Tamil Nadu's commercial vehicle density centers.
- Two-Wheelers:Motorcycles and scooters predominantly use manual steering with minimal assistance, though premium electric scooter platforms are introducing electric power steering for stability control integration.
- Electric Vehicles:Dedicated EV architectures with skateboard platforms enable steering module standardization across vehicle classes, drawing disproportionate technology investment from suppliers adapting to 12V and 48V dual electrical systems.
Production volume concentrates in Passenger Cars. Technology refresh cycles are shortest in Electric Vehicles as platform architectures stabilize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's automotive steering system industry traces its manufacturing lineage to the 1980s Maruti Suzuki joint venture, which established component supplier ecosystems in the Delhi-NCR belt before southward migration toward Tamil Nadu's electronics corridors reshaped production geography.
Maharashtra
Pune-Nashik belt anchors commercial vehicle steering production for truck and bus OEMs. The state government's industrial policy offers capital subsidies for automotive component manufacturing in designated mega projects. Chakan supplier park hosts hydraulic steering assembly lines serving Tata Motors and Mahindra & Mahindra heavy commercial platforms.
Tamil Nadu
Chennai-Sriperumbudur corridor concentrates electric power steering module production adjacent to Hyundai Motor India and Renault-Nissan assembly plants. The state's Electronics Manufacturing Policy incentivizes ECU and motor controller localization. Sriperumbudur's integrated electronics ecosystem enables just-in-time delivery of steering control modules within 50-kilometer radii.
Haryana
Manesar-Bawal automotive belt houses R&D centers where embedded software development for active steering systems concentrates. Haryana's proximity to Delhi-NCR technical universities feeds firmware engineering talent pools. Bawal industrial area hosts steering angle sensor and torque sensor manufacturing for Tier-1 system integrators.
Karnataka
Mysuru and Bengaluru regions split between manufacturing scale and technology development. Mysuru hosts ZF Steering Gear India's high-volume production facility for rack-and-pinion assemblies. Bengaluru's aerospace and defense electronics ecosystem cross-pollinates automotive steering control algorithms through shared embedded systems expertise.
Gujarat
Sanand-Vithalapur corridor emerged as a secondary manufacturing node following Tata Motors' Nano plant establishment. The state's port infrastructure at Mundra and Hazira facilitates import of rare earth magnets for EPS motor production. Sanand supplier parks now accommodate steering column sub-assembly operations for western India OEM distribution.
India Automotive Steering System Market Competitive Landscape
The competitive structure tilts toward diversified multinational Tier-1 suppliers with captive electronics capabilities. Market concentration is moderate, with the top five participants commanding substantial share in electric power steering while hydraulic steering retains fragmented domestic supplier participation. Two strategic archetypes dominate: integrated electromechanical system houses with in-house motor and ECU production, and hydraulic legacy specialists attempting electromechanical transition. Capacity expansion and backward integration into motor manufacturing represent the dominant competitive moves.
Among multinational system integrators, Nexteer Automotive, Bosch Auto Parts, and JTEKT Corporation exemplify the electromechanical archetype with established India manufacturing footprints. These entities occupy positions where steering system architecture design authority converges with component-level production scale. Domestic specialists including Rane Holdings Limited and ZF Steering Gear India represent manufacturing-scale players with historical strength in mechanical steering assemblies now navigating technology transition requirements. The competitive terrain rewards suppliers who can deliver complete electric steering columns rather than discrete hydraulic components, compressing procurement relationships toward module-level sourcing.
| Leading Market Players |
|---|
| Nexteer Automotive |
| WABCO |
| Rane Holdings Limited |
| Bosch Auto Parts |
| Knorr-Bremse |
| JTEKT Corporation |
| Mando Corporation |
| DENSO Corporation |
| ZF Steering Gear India |
| Others |
Pricing and Supply Chain Analysis
EPS certification-grade divergence between BIS-validated Tier-1 modules and uncertified Tier-2 alternatives manifests in procurement bifurcation: OEMs pay premiums for homologated electromechanical columns while aftermarket channels absorb commodity hydraulic rebuilds from Maharashtra's unregulated workshops.
Pricing Analysis
Bundled steering column assemblies with integrated ECUs command contract-based long-term offtake premiums from Maruti Suzuki and Hyundai Motor India, while unbundled rack-and-pinion replacements face commodity spot erosion in Tamil Nadu's independent service network. Price differentiation separates BIS-certified motor durability tiers from uncertified imports, with fleet operators showing least sensitivity due to total-cost-of-ownership calculations and aftermarket distributors most sensitive to per-unit procurement margins. Cost compression in hydraulic steering intensifies because Bharat Stage VI Phase II mandates accelerate passenger vehicle electrification, forcing legacy pump manufacturers into price wars for shrinking commercial vehicle volumes.
Supply Chain Analysis
Warehouse-distribution layers in the Chennai-Sriperumbudur corridor operate hub-and-spoke patterns radiating from Sriperumbudur's integrated electronics parks to OEM assembly plants within 50-kilometer radii. Geographic supply concentration centers on China for neodymium-dysprosium permanent magnets, Japan for precision torque sensors, and Germany for rack-and-pinion machining equipment. Raw material dependencies draw from rare earth magnet supply chains, automotive-grade copper windings, and high-strength steel forgings. Single-source vulnerability in magnet procurement threatens EPS motor production timelines. Distribution runs through Tier-1 supplier direct-to-OEM channels with limited aftermarket warehousing in Pune-Nashik.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bharat Stage VI Phase II operates as a regulatory compounder, forcing hydraulic-to-electric technology transitions that concentrate procurement authority among electromechanical specialists with captive ECU production.
For Market Incumbents: Extend backward integration into brushless DC motor manufacturing to neutralize rare earth magnet supply concentration risks. Lock in BIS certification pipelines early to compress 8-14 month homologation cycles before competitor qualification windows open. Defensive positioning requires co-locating final assembly within 50 kilometers of Tamil Nadu OEM plants to defend just-in-time delivery contracts against emerging Tier-1 challengers. For New Entrants and Emerging Players: Enter via Maharashtra's underutilized Pune-Nashik industrial land for Tier-2 component clustering serving western India commercial vehicle OEMs. Target the hydraulic steering aftermarket for aging truck fleets where fleet operator maintenance unbundling creates direct procurement openings. Pursue skateboard platform EV steering module standardization as the most penetrable application, leveraging 48V mild-hybrid proliferation to bypass entrenched 12V supplier relationships. For Investors and Strategic Acquirers: Consolidation pressure builds where embedded software talent scarcity constrains active steering development timelines in Haryana R&D centers. Five-to-ten year viability favors suppliers with demonstrated ISO 26262 functional safety compliance and captive motor-controller integration. Acquisition target archetype: mid-tier hydraulic specialists with established OEM relationships but incomplete electromechanical transition. Watch for inflection when Vehicle Scrappage Policy implementation accelerates replacement-compatible steering platform demand in the aftermarket channel.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Column-mounted EPS modules enable skateboard EV architecture compatibility across Maruti Suzuki and Hyundai Motor India vehicle lines. |
| Backward Integration | In-house brushless DC motor production reduces dependency on China-sourced neodymium-dysprosium magnet supply chains. |
| Geographic Manufacturing Footprint | Co-location within 50 kilometers of Chennai-Sriperumbudur OEM plants secures just-in-time delivery contracts. |
| Software-Defined Vehicle Investment | Active steering firmware development in Haryana R&D centers addresses embedded talent scarcity for chassis domain integration. |
| Long-term Supply Agreement | Contract-based offtake with Tata Motors and Mahindra & Mahindra stabilizes revenue through Bharat Stage VI Phase II transition volatility. |
Research Methodology
Direct dialogue with Tier-1 supplier procurement managers, OEM platform engineers, aftermarket distributors, and BIS certification officials grounded qualitative assessment in operational reality. Secondary validation drew from vehicle production databases, IHS Markit registration data, Ministry of Road Transport and Highways regulatory filings, and Automotive Research Association of India homologation records. Bottom-up unit economics triangulated against top-down market sizing from production forecasts and content-per-vehicle assumptions.
Segmentation outputs across vehicle class, propulsion architecture, and regional production cluster fed into analytical framework construction over the projection horizon. CAGRs emerged from regression analysis against historical penetration curves and regulatory mandate implementation schedules. Industry-specific forecast inputs incorporated 48V mild-hybrid adoption timelines and Vehicle Scrappage Policy expansion scenarios.
Inputs from BIS certification databases and OEM procurement disclosures were available through the study window; gaps in real-time rare earth magnet pricing introduce uncertainty bands around EPS cost projections. Forecasts reflect documented assumptions regarding regulatory implementation pace and technology substitution elasticities. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Wheel Chocks Market
Vehicle Components
CV Brake Controls Market
Vehicle Components
Ceramic Ball Bearings Market
Vehicle Components
Piston Market
Vehicle Components
RV Battery Market
Vehicle Components
Hydraulic Actuators Market
Vehicle Components
Steer-by-Wire Road Wheel Actuator Modules Market
Vehicle Components
Motorcycle Monoshock Suspension Market
Vehicle Components
HCV Suspension System Market
Vehicle Components
Global Truck and Trailer Landing Gear Market
Vehicle Components
High Precision Heavy Load Bearings Market
Vehicle Components
Global Automotive Carbon Monocoque Chassis Market
Vehicle Components
Global Automotive Carbon Fiber Composites Market
Vehicle Components
Off-Highway Diesel Engine Market
Vehicle Components
Precision Bearing Market
Vehicle Components
Forklift Seats Market