
 Industrial Gearbox and Gear Motors Market | 2026-2036
Industrial Gearbox and Gear Motors Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Gearbox and Gear Motors Market Analysis
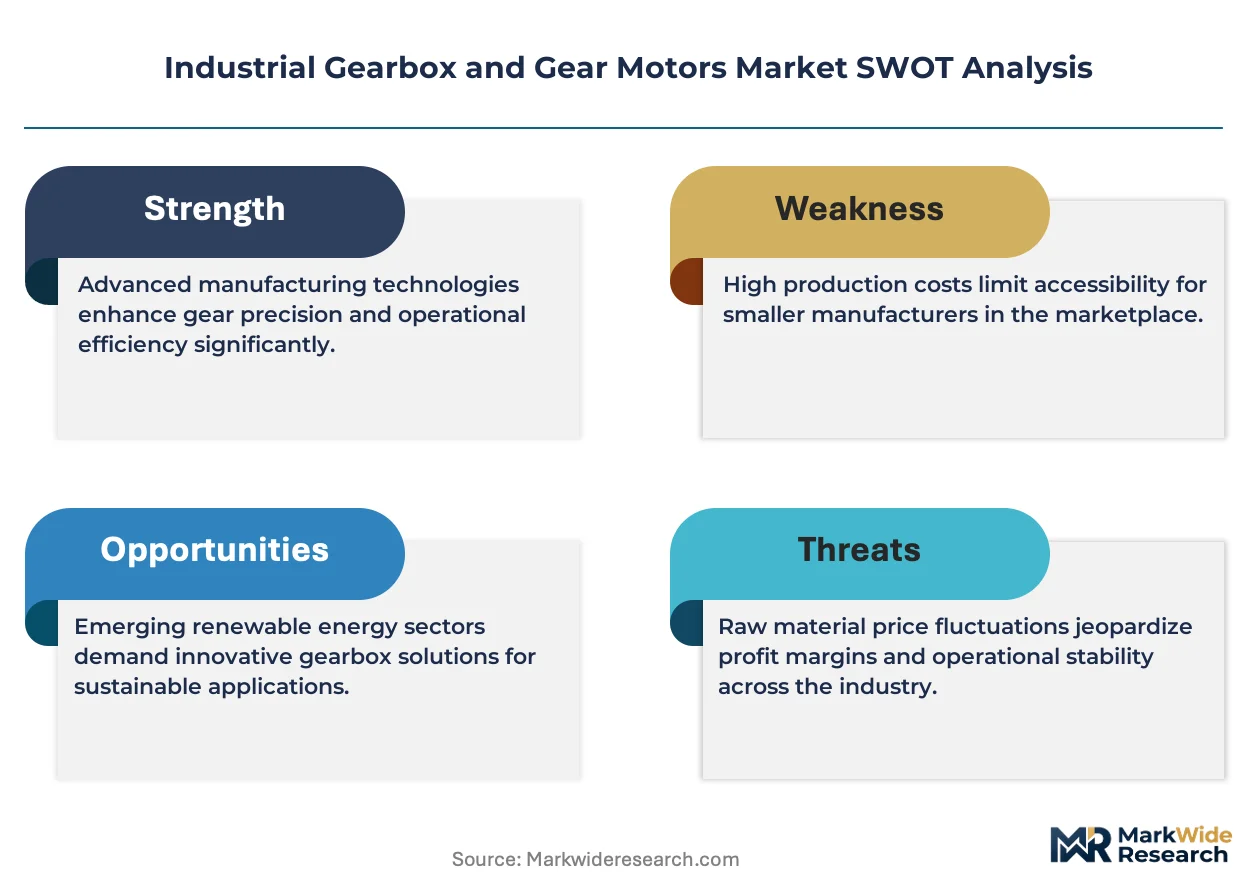
ISO 6336 gear rating and load capacity certification is bifurcating the competitive landscape between qualified precision manufacturers and commodity assemblers. SEW-EURODRIVE leverages its captive foundry and assembly network to sustain delivery reliability across European automation projects. Siemens anchors its position through digital twin integration with gearbox predictive maintenance platforms. Bonfiglioli specializes in compact foot-mount and flange-mount configurations for intralogistics and renewable energy nacelle positioning.
Industrial gearboxes and gear motors are enclosed mechanical power transmission systems comprising hardened alloy steel gear sets, bearing assemblies, and lubrication circuits designed to reduce motor speed while multiplying torque output for heavy-duty machinery. Helical and planetary configurations dominate precision motion applications where backlash below three arc-minutes proves critical for CNC positioning and robotic articulation. Worm and bevel segments occupy mature, cost-sensitive niches in bulk material handling and mining conveyors where intermittent duty cycles tolerate lower mechanical efficiency. Medium and high power rating classes capture the deepest margin pools as foundry-grade housings and carburized gearing command premium pricing over standard-duty low-power units.
The EU Machinery Directive and CE marking requirements enforced by national market surveillance authorities mandate fail-safe braking and emergency stop compatibility for integrated gear motor systems deployed in automated production lines. OSHA lockout-tagout standards and EPA lubricant disposal regulations in the United States add compliance layers that favor sealed-for-life synthetic oil formulations over conventional mineral-based maintenance schedules. Stakeholders must monitor evolving IEC 60034 energy efficiency tiers and local content thresholds in industrial incentive schemes to align sourcing strategies with shifting qualification barriers.
Market Dynamics
ISO 6336 gear rating certification is bifurcating the competitive landscape, forcing precision manufacturers to invest in captive heat treatment and grinding capacity while commodity assemblers retreat to standard-duty segments with lower technical barriers.
Growth Catalysts
- Automated warehouse expansion:E-commerce fulfillment centers in Germany and the Netherlands deploy compact planetary gear motors for high-density storage retrieval systems. Rack-climbing shuttles require backlash below three arc-minutes.
- EU Machinery Directive compliance:CE marking mandates for fail-safe braking systems push OEMs toward integrated gear motor suppliers with certified emergency stop compatibility. National market surveillance authorities enforce random factory audits.
- Carburized alloy steel gearing:Vacuum carburizing with high-pressure gas quenching extends surface fatigue life for wind turbine yaw drives and heavy conveyor applications. Foundries with SECO/WARWICK furnaces capture premium pricing.
Market Restraints
- Specialized steel input volatility:Case-hardening grades 18CrNiMo7-6 and 20MnCr5 face price swings tied to molybdenum and nickel exchange markets. Smaller gear shops lack forward-contracting power against mill minimums.
- German supply concentration:Precision helical and planetary gearbox assembly clusters around Stuttgart, Nuremberg, and Bielefeld. Disruption at any major captive foundry ripples through European automation project timelines.
- Worm gear efficiency ceiling:Single-enveloping and double-enveloping worm sets top out at 90% mechanical efficiency versus 98% for helical alternatives. Bulk material handling buyers accept the trade-off; energy-intensive continuous duty applications do not.
Strategic Opportunities
- Renewable energy nacelle positioning:Offshore wind installations off Denmark and the Scottish coast demand compact slew drives with integrated holding brakes. Bonfiglioli and local specialists already supply pitch and yaw systems.
- Intralogotics channel expansion:Direct specification relationships with warehouse automation integrators bypass traditional distributor markups. SEW-EURODRIVE and Nord Drivesystems maintain captive application engineering teams for this channel.
- IEC 60034 energy efficiency tiers:Premium efficiency motor-gearbox combinations qualify for industrial incentive schemes in Italy and Spain. Synchronous reluctance motor integration with helical gearboxes hits IE5-equivalent system efficiency.
Industry Challenges
- Metrology technician scarcity:Coordinate measuring machine operation for ISO 1328 gear accuracy verification requires specialized training. Vocational pipelines in Saxony and Bavaria produce fewer qualified inspectors than replacement demand.
- Synthetic lubricant certification timelines:Sealed-for-life gear motors using polyalphaolefin formulations must pass extended wear testing under FVA 54/7 micro-pitting standards. Laboratory backlog stretches validation to 18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Gearbox and Gear Motors Market |
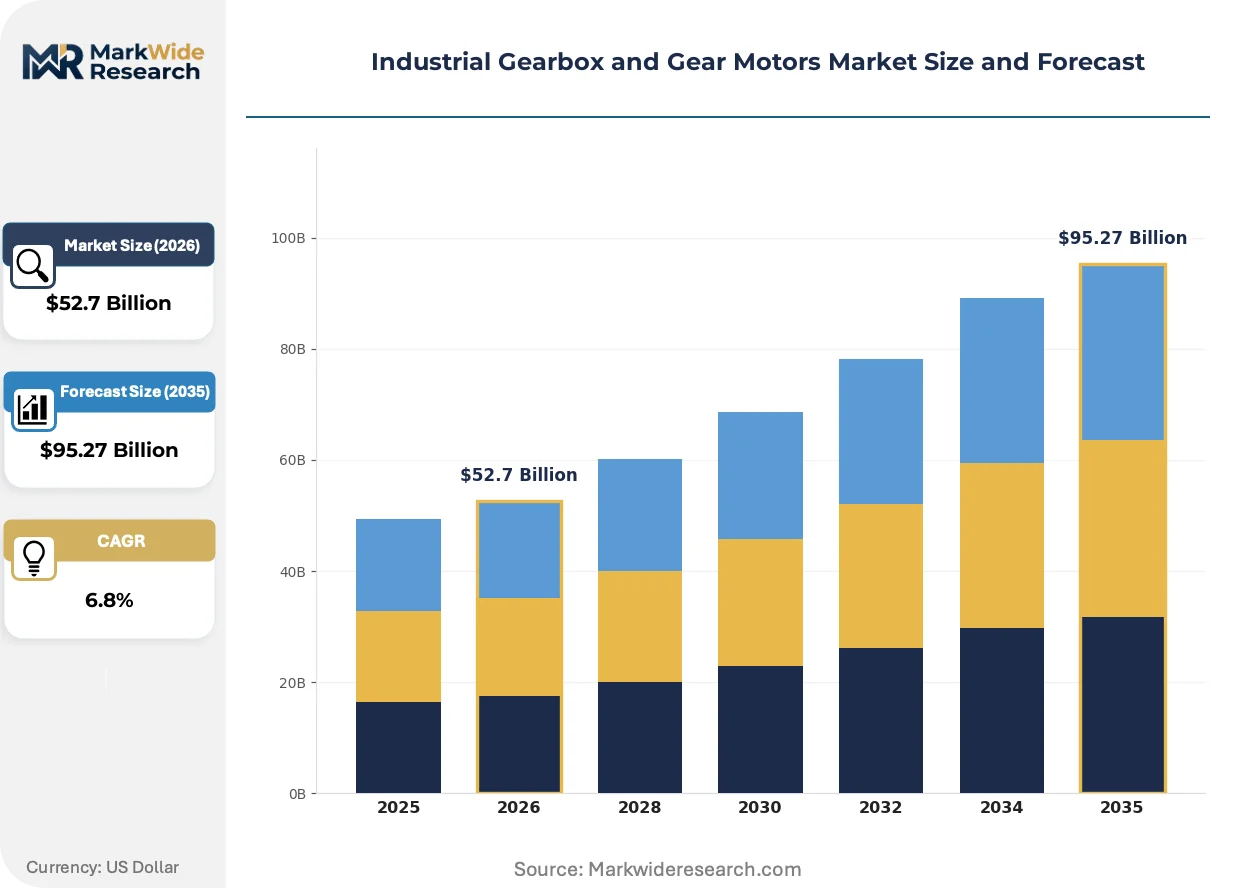
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $95.27 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Helical, Bevel, Worm, Planetary End Use Industry: Manufacturing, Mining, Oil & Gas, Automotive Power Rating: Low, Medium, High, Ultra-High Mounting Type: Foot-Mount, Flange-Mount, Shaft-Mount, Hollow Shaft |
| Companies Covered | Sumitomo Heavy Industries, Nidec Corporation, SEW-EURODRIVE, Nord Drivesystems, Siemens, Bonfiglioli, Flender, Bosch Rexroth, Regal Rexnord Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Gearbox and Gear Motors Market Emerging Trajectories
Digital twin integration is compressing maintenance cycles and reshaping buyer expectations for predictive uptime guarantees. Three interconnected developments are redefining how power transmission systems are specified, operated, and serviced.
Additive manufacturing of conformal cooling channels in gearbox housings is bifurcating thermal management strategies. High-horsepower units for steel rolling mills now embed topology-optimized coolant galleries that cut operating temperatures by 15°C versus conventional drilled passages. Foundries with EOS M 400-4 metal powder bed systems capture prototype-to-production contracts from European heavy machinery OEMs.
REACH restrictions on perfluorinated lubricant additives are forcing reformulation of extreme-pressure gear oils. ECHA substance evaluation under SVHC candidate listing targets zinc dialkyldithiophosphate anti-wear compounds used in mining gearboxes. Blenders in Belgium and the Netherlands accelerate calcium sulfonate complex grease development for open-gear applications in cement kilns and stacker-reclaimers.
Buyer consolidation among automated warehouse operators is compressing vendor qualification cycles. Large fulfillment networks in Poland and the Czech Republic now mandate single-source accountability for entire conveyor drive lines spanning gear motors, variable frequency drives, and condition monitoring sensors. System integrators like Vanderlande and BEUMER Group bundle specification authority, marginalizing standalone gearbox distributors.
Industrial Gearbox and Gear Motors Market Segmentation
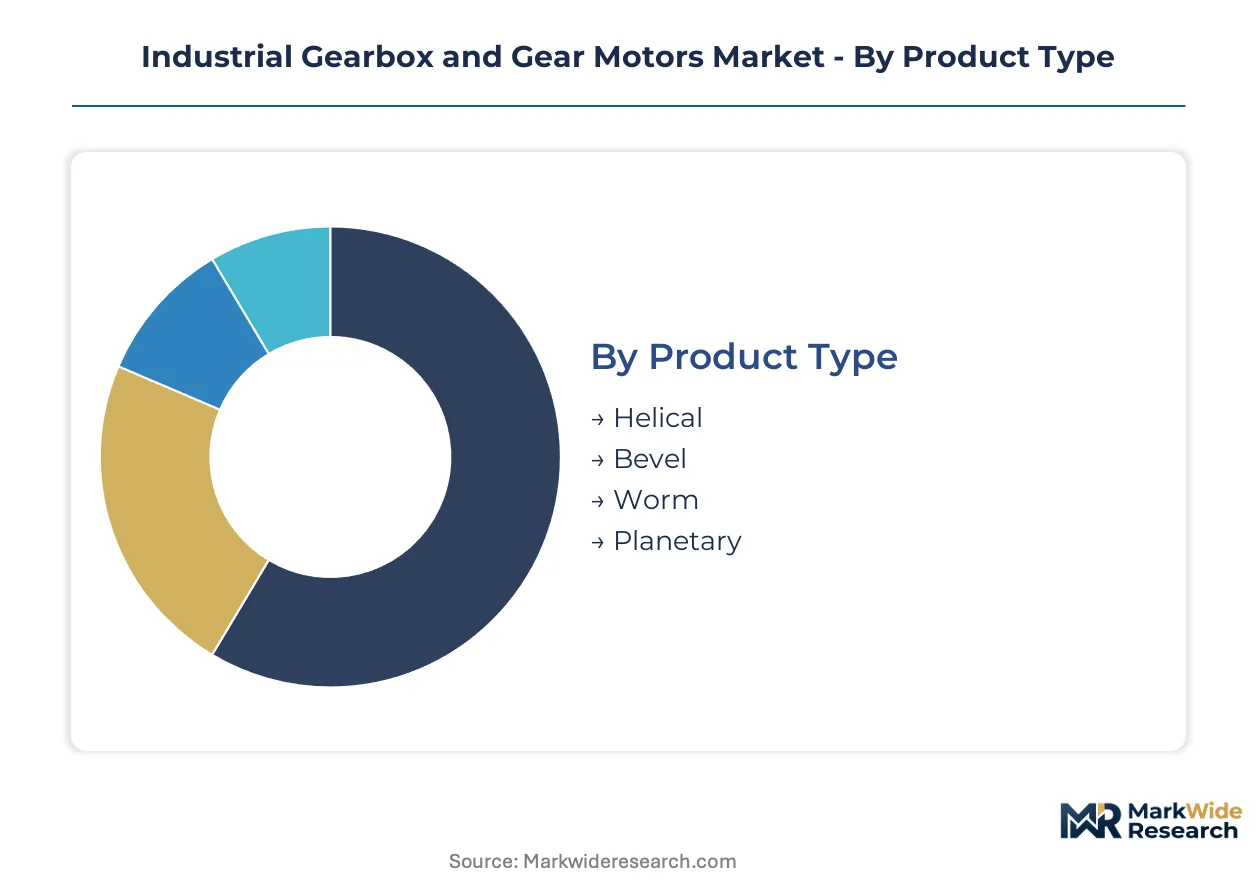
Segmentation in this market reveals how technical specifications and duty cycles create distinct margin pools. Buyers specify gear systems by mechanical configuration, load profile, and mounting geometry rather than treating power transmission as a commodity category.
Product Type:
Planetary and helical configurations face intensifying substitution pressure from direct-drive torque motors in precision robotics, while worm and bevel segments defend entrenched positions in cost-sensitive bulk handling.
- Helical:Parallel-axis gear sets with inclined tooth engagement deliver 98% mechanical efficiency and noise levels below 75 dB. German automotive press lines and Dutch automated warehouses specify these for continuous-duty conveyor drives where energy recovery matters.
- Planetary:Epicyclic arrangements with sun, planet, and ring gears achieve torque density ratios exceeding 200 Nm per kilogram. Danish offshore wind yaw systems and Czech rack-climbing shuttles demand the sub-three arc-minute backlash only precision planetary units provide.
- Bevel:Right-angle power transmission for confined machinery footprints. Mining haul truck wheel drives and cement kiln rotation systems in Poland deploy spiral bevel sets for 90-degree shaft redirection.
- Worm:Single-enveloping screw-and-wheel pairs topping 90% efficiency. Accepted in intermittent-duty mining conveyors and grain elevators where purchase cost trumps operating expense.
Helical configurations anchor the volume base while planetary systems gain share at the steepest rate.
End Use Industry:
Cost tier stratification separates capital-intensive extraction sectors from high-volume manufacturing automation.
- Manufacturing:Automated assembly lines and CNC machine tools demand ISO 1328 Grade 4 accuracy for positioning repeatability. Stuttgart-area OEMs source integrated gear motor systems with predictive maintenance interfaces.
- Mining:Crusher drives and overland conveyors subject gearboxes to shock loads exceeding 300% of nominal torque. Australian iron ore operations and Chilean copper belts specify AGMA 2001 service factors above 2.0.
- Oil & Gas:Mud pump drives and top-drive drilling systems require explosion-proof enclosures meeting ATEX Zone 1 certification. North Sea platforms and Permian Basin fracking fleets favor sealed-for-life synthetic lubrication.
- Automotive:Stamping press automation and paint shop conveyor systems demand synchronized multi-axis motion. German press shops specify helical-bevel combinations with electronic overload protection.
Manufacturing commands the deepest specification expertise while mining contributes the highest per-unit pricing.
Power Rating:
Application maturity curves diverge sharply between established low-power intralogistics and emerging ultra-high power offshore wind.
- Medium:7.5 to 75 kW output range dominating automated warehouse retrieval systems. Polish fulfillment centers specify these for shuttle drives requiring 10,000-hour maintenance intervals.
- High:75 to 375 kW ratings for steel rolling mill stands and cement grinding tables. Vacuum-carburized gearing from SECO/WARWICK-equipped foundries commands 40% price premiums over standard induction-hardened alternatives.
- Low:Below 7.5 kW compact units for packaging machinery and light conveyor segments. Volume production in Chinese and Indian assembly shops compresses margins to single-digit percentages.
- Ultra-High:Above 375 kW for offshore wind turbine main bearings and marine propulsion. Only six European foundries possess the 50-ton casting capacity and five-axis gear grinding precision this segment demands.
Medium power ratings generate the broadest revenue base while ultra-high systems expand most quickly on renewable energy capital deployment.
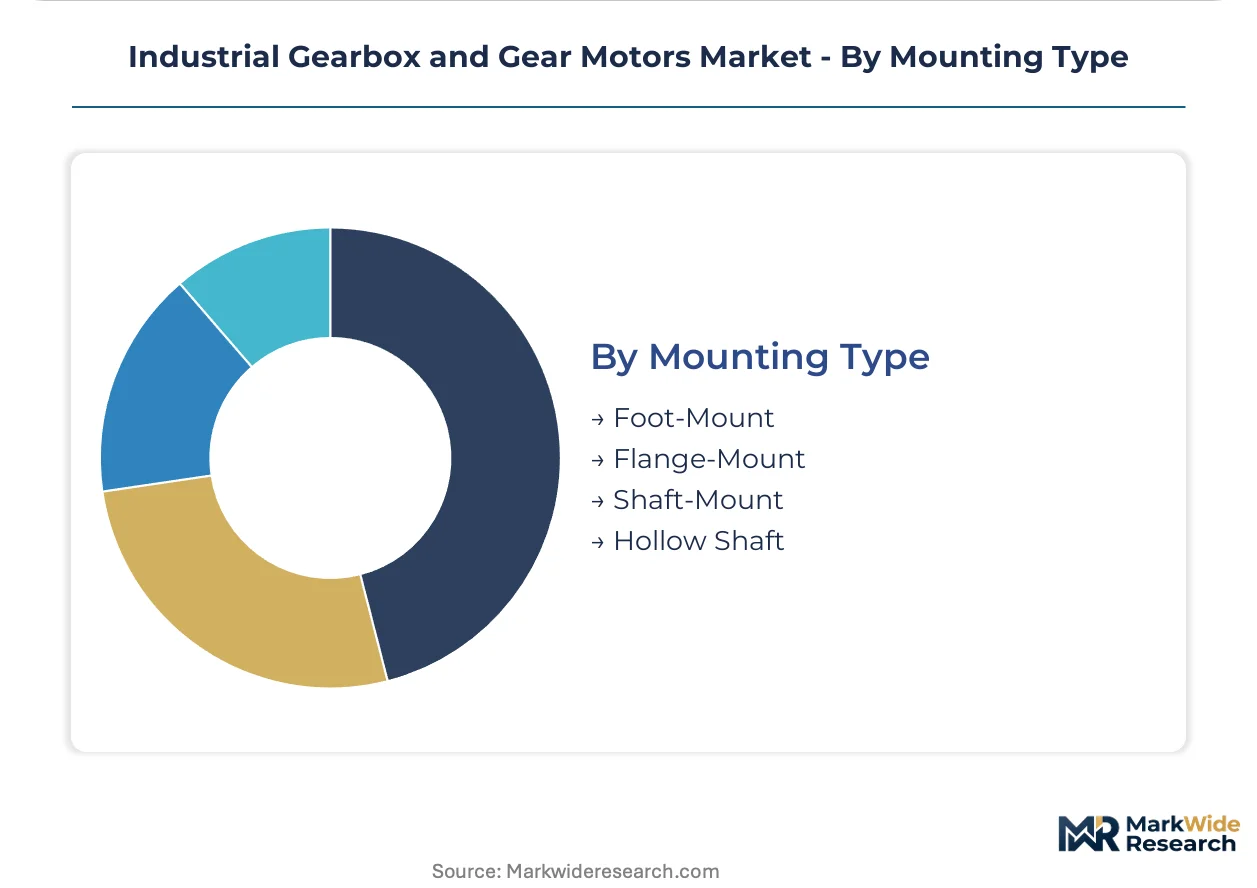
Mounting Type:
Customer type bifurcation separates machinery OEMs seeking design flexibility from end-users prioritizing field serviceability.
- Foot-Mount:Rigid baseplate installation for permanent machinery foundations. German machine tool builders and Italian packaging OEMs prefer this configuration for vibration isolation and alignment precision.
- Flange-Mount:Face-mounted integration for compact nacelle and robotic joint applications. Bonfiglioli dominates renewable energy positioning with this geometry.
- Shaft-Mount:Direct bore mounting on driven equipment shafts without additional couplings. Mining conveyor pulley drives in Australia and South Africa favor this for maintenance access.
- Hollow Shaft:Pass-through design allowing cable routing or auxiliary shaft extension. Automated storage retrieval systems in the Netherlands and Belgium specify these for rack-climbing mechanisms.
Foot-mount retains the largest installed base while hollow shaft configurations climb fastest on warehouse automation density trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers of precision gear systems cluster around automated manufacturing corridors and renewable energy installation zones, with specification authority residing in German automotive OEMs, Dutch logistics operators, and Danish offshore wind developers.
Germany
Automotive press automation and CNC machine tool retrofits consume helical-bevel combinations with electronic overload protection. The EU Machinery Directive enforces CE marking with mandatory fail-safe braking for integrated gear motor systems deployed on Stuttgart-area production lines. Captive foundry clusters around Nuremberg and Bielefeld supply vacuum-carburized gearing for continuous-duty conveyor drives.
Netherlands
High-density warehouse retrieval systems and rack-climbing shuttles demand planetary gear motors with backlash below three arc-minutes. REACH restrictions on perfluorinated lubricant additives force reformulation of extreme-pressure gear oils used in Rotterdam-port material handling equipment. Eindhoven-region automation integrators specify foot-mount and hollow-shaft configurations for shuttle drive mechanisms.
Denmark
Offshore wind turbine yaw and pitch positioning systems require compact slew drives with integrated holding brakes. IEC 60034 energy efficiency tiers qualify premium motor-gearbox combinations for national renewable energy incentive schemes. Copenhagen-area developers source flange-mount configurations for nacelle positioning in North Sea installations.
United States
Permian Basin fracking fleets and mining overland conveyors specify explosion-proof gearboxes with sealed-for-life synthetic lubrication. OSHA lockout-tagout standards and EPA lubricant disposal regulations favor maintenance-free synthetic oil formulations over mineral-based schedules. Pittsburgh-area steel rolling mills deploy ultra-high power units from foundries with 50-ton casting capacity.
Poland
E-commerce fulfillment center expansion drives procurement of medium-power gear motors for shuttle drives requiring 10,000-hour maintenance intervals. Local content thresholds in industrial incentive schemes align sourcing strategies with EU-funded infrastructure projects. Warsaw-region warehouse operators mandate single-source accountability for entire conveyor drive lines spanning gear motors and condition monitoring sensors.
Industrial Gearbox and Gear Motors Market Vendor Landscape
Player mix skews toward diversified industrial conglomerates with captive power transmission divisions alongside specialized precision manufacturers. The competitive terrain splits between vertically integrated European specialists controlling heat treatment and grinding capacity and Asian-scale producers serving cost-sensitive standard-duty segments. Strategic archetypes include precision-certification leaders, automotive-integrated suppliers, and renewable energy positioning specialists. Dominant competitive moves center on foundry capacity expansion for carburized alloy steel gearing and direct specification relationships with warehouse automation integrators bypassing traditional distribution channels.
Among Germany-based precision manufacturers, SEW-EURODRIVE, Siemens, and Bonfiglioli occupy positions representing distinct strategic vectors. SEW-EURODRIVE exemplifies the captive foundry and assembly network model sustaining delivery reliability across European automation projects. Siemens anchors digital twin integration capabilities with gearbox predictive maintenance platforms. Bonfiglioli sits within the compact foot-mount and flange-mount specialization for intralogistics and renewable energy nacelle positioning.
| Leading Market Players |
|---|
| Sumitomo Heavy Industries |
| Nidec Corporation |
| SEW-EURODRIVE |
| Nord Drivesystems |
| Siemens |
| Bonfiglioli |
| Flender |
| Bosch Rexroth |
| Regal Rexnord Corporation |
| Others |
Supply Flow & Price Mechanics
ISO 6336 gear rating certification gates both supplier qualification and price differentiation simultaneously, bifurcating the competitive landscape between precision manufacturers commanding 40% premiums for vacuum-carburized gearing and commodity assemblers competing on standard-duty volume. CE marking requirements under the EU Machinery Directive add compliance layers that concentrate pricing power among captive foundry operators in Germany's industrial corridor.
Pricing Analysis
Cost-plus contracts with molybdenum and nickel indexation dominate procurement for case-hardening grades 18CrNiMo7-6 and 20MnCr5. Three-tier pricing structure across precision-certified, standard-duty, and economy segments reflects ISO 1328 accuracy grades and heat treatment method. Cost compression in low-power compact units intensifies because Chinese and Indian assembly shops flood packaging machinery segments. Bulk material handling buyers in mining prove most price-sensitive, while automated warehouse operators prioritize backlash precision over unit cost.
Supply Chain Analysis
Inventory buffers for alloy steel bar stock and carburized gear blanks stretch lead times to 16-22 weeks at European foundries. Supply concentrates in Germany, Italy, and China, with Nuremberg and Bielefeld clusters anchoring precision helical and planetary assembly. Raw material dependencies draw from Swedish specialty steel mills, Chinese rare earth processing for magnetic materials in integrated motors, and Belgian lubricant blending for sealed-for-life formulations. Single-source vulnerability at SECO/WARWICK-equipped heat treatment facilities poses structural risk. Distribution runs through captive OEM specification teams and automation integrators bypassing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across precision certification tiers creates niche opportunities as warehouse automation buyers consolidate vendor accountability for entire drive lines. Direct specification relationships now bypass distributors, opening entry points for specialized engineering shops.
For Market Incumbents: Compound captive foundry capacity in Germany's industrial corridor to defend margin pools against emerging Asian scale producers. Additive manufacturing of conformal cooling channels in gearbox housings represents a critical R&D lever. Backward integration into vacuum carburizing secures supply continuity against specialty steel input volatility.
For New Entrants and Emerging Players: Lead with hollow-shaft planetary configurations for rack-climbing shuttles in Polish and Czech fulfillment centers, the most penetrable automation segment. Target direct specification relationships with Vanderlande and BEUMER Group as the go-to-market angle, bypassing traditional distribution markups through captive application engineering teams.
For Investors and Strategic Acquirers: REACH restrictions on perfluorinated lubricant additives and zinc dialkyldithiophosphate compounds reshape the acquisition landscape toward synthetic formulation specialists with FVA 54/7 validation capabilities. Five-to-ten year viability favors mid-cap precision manufacturers with ISO 6336 certification and captive heat treatment. Watch ECHA SVHC candidate listing timelines as the inflection signal for lubricant reformulation winners.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Foundry Capacity Expansion | SECO/WARWICK vacuum carburizing furnaces command 40% price premiums for wind turbine yaw drives. |
| Digital Twin Platform Integration | Siemens anchors predictive maintenance interfaces with gearbox condition monitoring for Stuttgart OEMs. |
| Direct Channel Specification Relationships | SEW-EURODRIVE and Nord Drivesystems bypass distributor markups through automation integrator partnerships. |
| Synthetic Lubricant Certification Investment | Polyalphaolefin formulations meeting FVA 54/7 standards qualify for sealed-for-life gear motor contracts. |
| Additive Manufacturing Prototype-to-Production | EOS M 400-4 metal powder bed systems capture topology-optimized coolant gallery contracts from European heavy machinery OEMs. |
Methodological Framework
Operator-level perspectives from maintenance directors at German automotive press shops, procurement leads at Dutch logistics operators, plant engineers at Polish fulfillment centers, and aftermarket service heads at mining conveyor OEMs anchored the qualitative base. Primary interviews combined with secondary validation from SEC 10-K filings, customs and trade data for alloy steel imports, and IEC 60034 energy efficiency tier disclosures. Bottom-up unit economics triangulated against top-down industrial automation capex forecasts.
Sensitivity analysis tested variable assumptions across the projection horizon. Segmentation dimensions modeled include gear configuration type, power rating tier, mounting geometry, end-use industry, and regional regulatory cluster. CAGRs derived from installed base replacement cycles and new automation project pipelines. Forecast inputs incorporated REACH substance evaluation timelines and EU Machinery Directive enforcement intensity variations.
Forecasts assume regulatory continuity in EU Machinery Directive CE marking regimes and ECHA SVHC candidate listing procedures; material policy shifts would require re-modeling. Synthetic lubricant certification backlogs and metrology technician scarcity in Saxony and Bavaria represent specific risk factors. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Center and Drag Link Market
Automotive Parts
Automotive Belts Market
Automotive Parts
Automotive Electric Water Pump Market
Automotive Parts
Lug Wrench Market
Automotive Parts
Automotive Bellows Market
Automotive Parts
Colombia Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Carbon Canister Market
Automotive Parts
Global Automotive Leaf Spring Market
Automotive Parts
Cylinder Head Cover Market
Automotive Parts
France Commercial Vehicles Lubricants Market
Automotive Parts
South America Automotive Lubricants Market
Automotive Parts
Automotive Radiator Hose Market
Automotive Parts
Global Automotive Closure Market
Automotive Parts
UAE Automotive Lubricants Market
Automotive Parts
China Ceramic Ball Bearing Market
Automotive Parts
Global Passenger Vehicles Lubricants Market