
 South America Automotive Lubricants Market | 2026-2036
South America Automotive Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
South America Automotive Lubricants Market Analytics
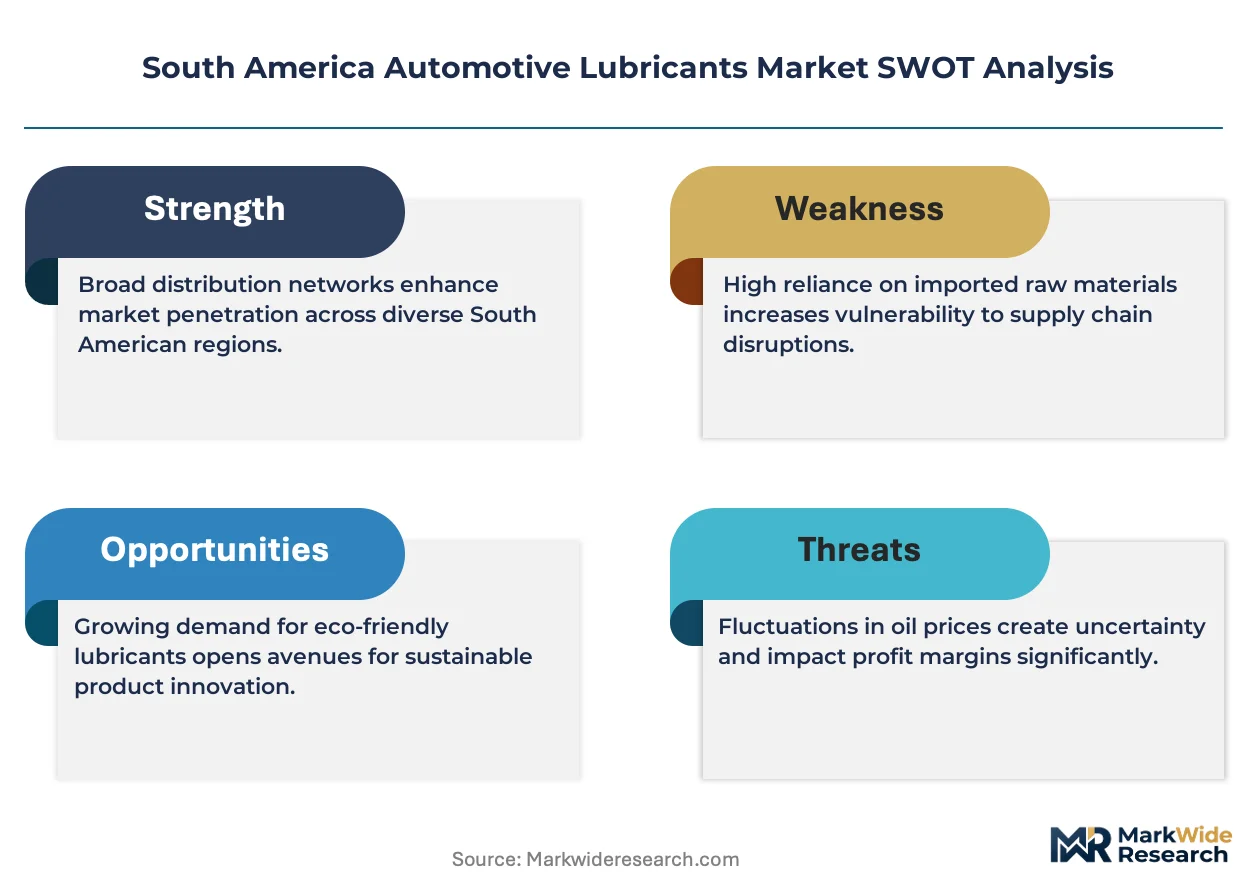
Asset-light leasing models for lubricant blending plants is narrowing the capital barrier for regional entrants. Petrobras leverages its captive refinery network to anchor supply security across Brazilian coastal markets. Shell Plc competes through controlled distribution networks that extend into Andean retail channels. FUCHS Petrolub SE specializes in high-performance synthetic formulations for mining and off-highway equipment.
Automotive lubricants are formulated base oil and additive packages designed to reduce friction, dissipate heat, and prevent wear in internal combustion and transmission systems, with viscosity grades typically spanning SAE 0W-16 through 20W-50 depending on operating temperature and engine architecture. Their primary commercial purpose is to extend equipment life and maintain fuel efficiency across vehicle and machinery fleets. Engine Oil occupies the dominant margin pool given its high replacement frequency and technical complexity, while Transmission Fluid represents the fastest-growing category as automatic and dual-clutch penetrations deepen in Brazilian and Chilean passenger vehicle parc. Aftermarket Providers channel segment leads volume throughput due to the region's aging vehicle fleet and extended ownership cycles.
ANVISA in Brazil and the Argentine national chemical regulator enforce evolving standards on additive chemistry and biodegradability that reshape import eligibility for multinational suppliers. Brazil's PLI scheme for domestic lubricant manufacturing and Chile's alignment with OECD chemical safety frameworks are redirecting capital toward local blending capacity. Stakeholders must monitor how pending Mercosur harmonization on lubricant specifications alters cross-border product registration requirements and inventory positioning.
Market Dynamics
Fleet operators in Brazil's São Paulo industrial corridor are extending drain intervals for heavy-duty commercial vehicles, compressing replacement frequency and forcing reformulation toward higher-performance synthetic base stocks.
Growth Catalysts
- ANVISA REACH-equivalent protocols:Brazil's alignment with chemical safety frameworks is elevating import specifications for Group II and III base oils, favoring suppliers with technical documentation capabilities.
- Mining equipment parc expansion:Chilean and Peruvian open-pit operations are deploying larger haul trucks and excavators, multiplying off-highway lubricant consumption per machine-hour.
- Dual-clutch transmission penetration:Brazilian and Chilean passenger vehicle fleets are adopting wet-clutch architectures that demand specialized friction-modified fluids with extended thermal stability.
Market Restraints
- API Group I base oil dependency:Regional blending capacity remains anchored to solvent-refined stocks with inferior oxidation stability, limiting premium product differentiation.
- Argentine import financing constraints:Central bank foreign exchange rationing is extending lead times for additive packages sourced from North American and European suppliers.
- Electric commercial vehicle pilots:Brazilian postal and urban delivery fleets are testing battery-electric trucks that eliminate engine oil demand entirely from specific duty cycles.
Strategic Opportunities
- Colombia's Andean corridor:Bogotá's altitude-driven thermal stress on engines creates demand for SAE 5W-40 and 0W-30 formulations with enhanced high-temperature shear stability.
- Biodegradable hydraulic fluids mandate:Chile's OECD-aligned chemical safety framework is creating preferential procurement channels for vegetable-oil-based formulations in forestry and agriculture.
- Telematics-enabled oil analysis:Integration of particle counters and viscosity sensors into fleet management platforms permits condition-based drain intervals that favor premium synthetic products.
Industry Challenges
- Additive chemist scarcity:Brazilian universities produce limited lubricant formulation specialists, forcing blenders to recruit from petrochemical or coatings sectors.
- Mercosur specification harmonization delays:Divergent national registration requirements between Brazil, Argentina, and Paraguay force redundant testing protocols for cross-border product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Automotive Lubricants Market |
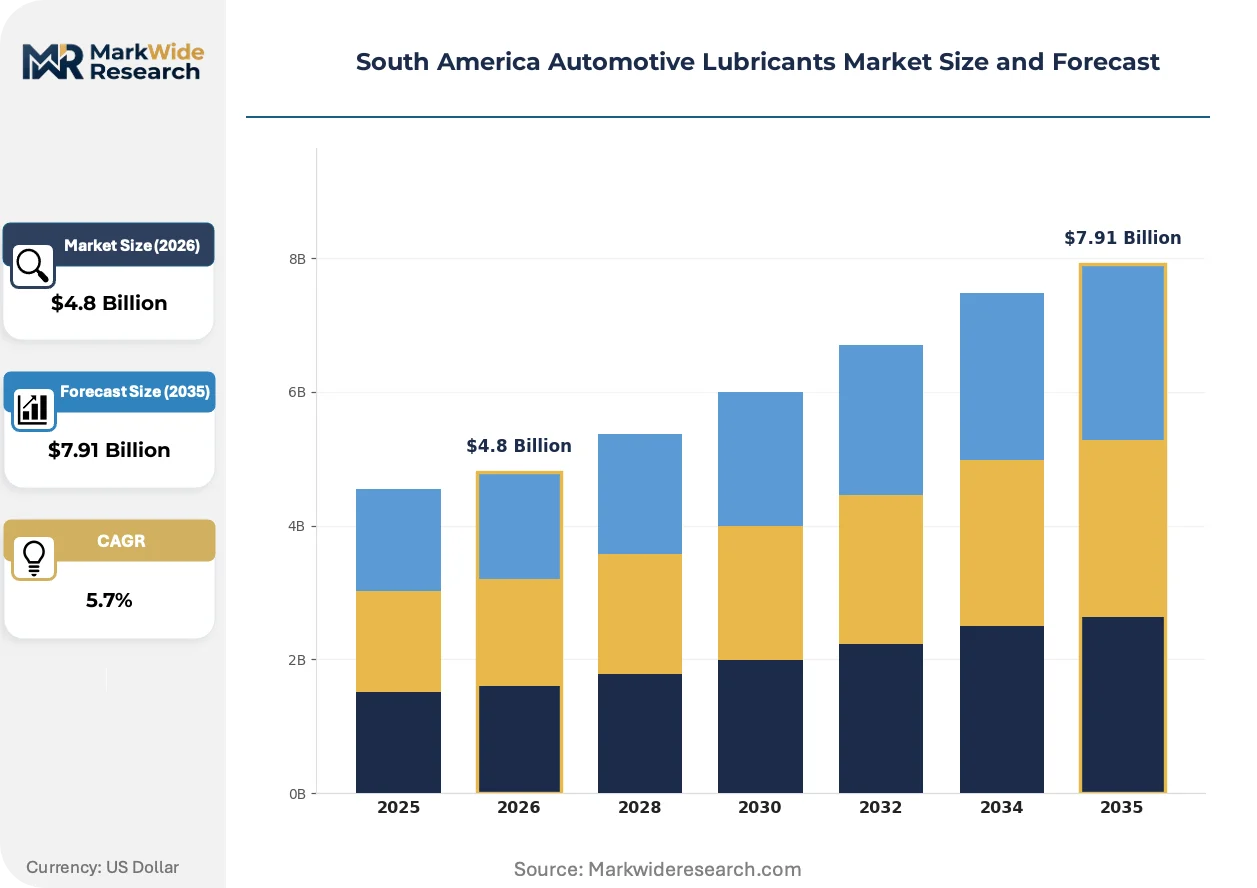
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Gear Oil, Transmission Fluid, Hydraulic Fluid End User: OEMs, Aftermarket Providers, Fleet Operators, Dealerships Application: Passenger Vehicles, Commercial Vehicles, Heavy Machinery, Motorcycles Distribution Channel: Retail, Online, Direct Sales, Wholesalers |
| Companies Covered | BP Plc (Castrol), ExxonMobil Corporation, Shell Plc, Chevron Corporation, TotalEnergies, Petrobras, Repsol S.A., Iconic Lubrificantes, FUCHS Petrolub SE, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Automotive Lubricants Market Evolving Landscape
Synthetic base oil technology and connected fleet diagnostics are compressing traditional maintenance paradigms while regulatory chemistry restrictions reshape import eligibility.
Group III+ and GTL base oils are achieving parity with Group IV PAO stocks in oxidative stability and low-temperature pumpability. Brazilian heavy-duty fleet operators are adopting these stocks for 100,000-kilometer drain intervals in long-haul applications. Mineral-based formulations are rendering obsolete in premium commercial segments where total cost of ownership calculations dominate procurement.
ANVISA's additive chemistry disclosure requirements are tightening documentation burdens for imported lubricant formulations. The regulation is forcing reformulation of zinc dialkyldithiophosphate levels and friction modifier packages to meet biodegradability thresholds. Engine oil categories targeting São Paulo state's industrial corridor are experiencing the most intensive compliance scrutiny.
Condition-based maintenance contracts are displacing fixed-interval service schedules among Chilean mining contractors. Equipment lessors are bundling oil analysis laboratory services with fluid supply agreements, capturing lubricant procurement decisions from end-user maintenance departments. This shift concentrates buying power with fewer distributor-integrator entities in the Antofagasta and Atacama mining regions.
South America Automotive Lubricants Market Segmentation
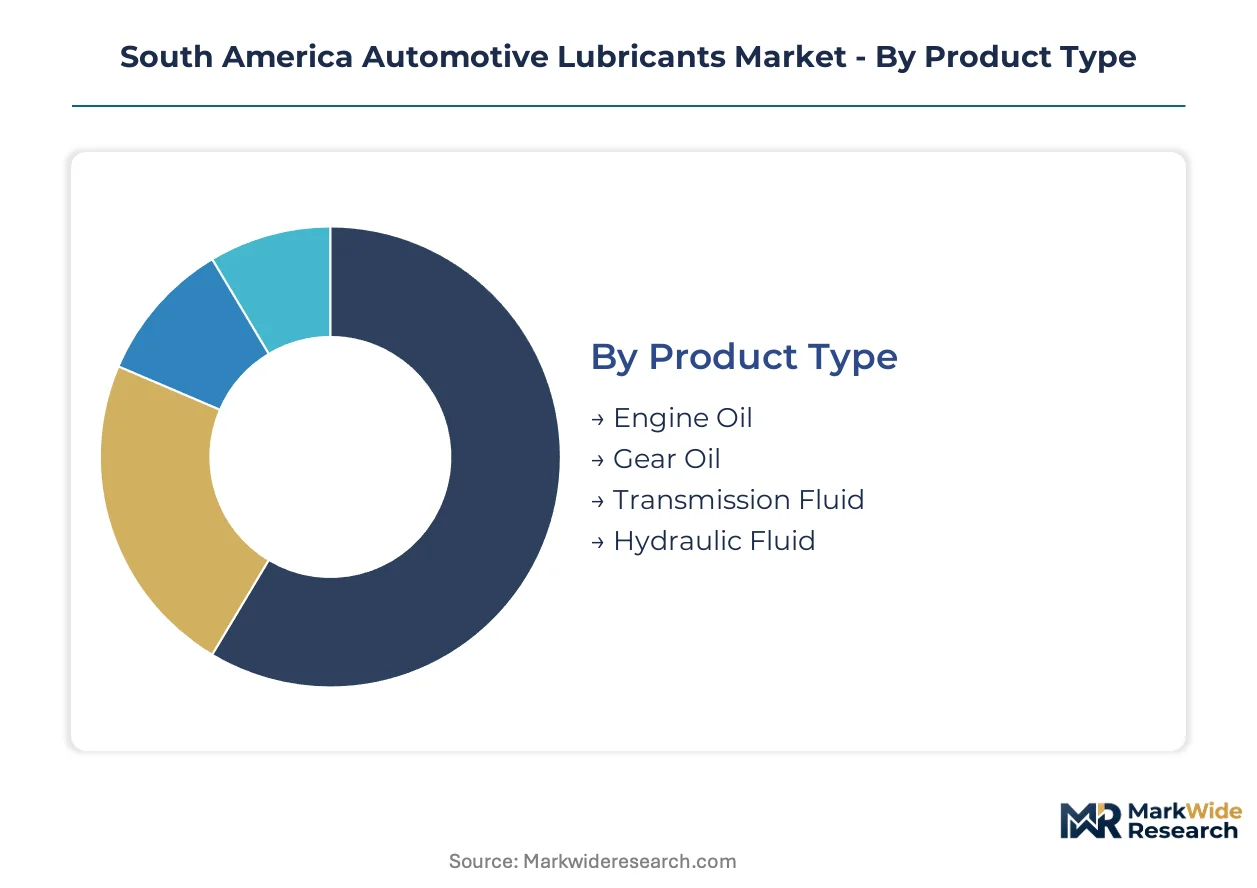
Automotive lubricant purchasing patterns diverge sharply across duty cycles and procurement authority structures. Fleet operators negotiate bulk supply contracts with technical service bundling, while individual vehicle owners prioritize retail accessibility and brand recognition. Understanding these segment boundaries clarifies where formulation investments translate into volume capture.
Product Type:
Formulation chemistry and replacement frequency create distinct margin profiles across lubricant categories.
- Engine Oil:Blends of Group II/III base stocks with detergent-dispersant and anti-wear additive packages protect against piston deposits and bearing corrosion. Demand concentrates in São Paulo state's industrial corridor where ANVISA compliance scrutiny on zinc dialkyldithiophosphate levels is most intensive.
- Transmission Fluid:Friction-modified formulations with enhanced thermal stability serve wet-clutch dual-clutch architectures. Brazilian and Chilean passenger vehicle parc expansion drives specification complexity as OEM fill requirements diverge.
- Gear Oil:Extreme-pressure additives protect hypoid gear sets in commercial vehicle axles.
- Hydraulic Fluid:Anti-wear and oxidation inhibitors serve construction and agricultural equipment across the Andean foothills.
The dominant share belongs to Engine Oil, while Transmission Fluid is closing the gap fastest.
End User:
Procurement authority determines whether lubricant selection prioritizes total cost of ownership or convenience.
- Aftermarket Providers:Independent workshops and quick-lube chains serving Brazil's aging vehicle fleet dominate volume throughput. Extended ownership cycles in Argentina's Córdoba automotive cluster sustain replacement demand outside warranty periods.
- Fleet Operators:Heavy-duty commercial vehicle lessors in Brazil's São Paulo corridor negotiate condition-based maintenance contracts with oil analysis laboratory bundling. Telematics-enabled drain interval extension compresses unit consumption while elevating synthetic product specification.
- OEMs:Factory-fill agreements with Brazilian and Argentine vehicle assemblers require just-in-time blending capacity proximity.
- Dealerships:Authorized service networks capture warranty-period maintenance with captive lubricant branding.
Aftermarket Providers command the largest volume position, though Fleet Operators are expanding their share through consolidated procurement.
Application:
Operating environment severity dictates base oil group selection and additive treat rates.
- Passenger Vehicles:SAE 0W-20 and 5W-30 formulations serve Brazilian flex-fuel engines with ethanol compatibility requirements. Dual-clutch transmission penetration in Chilean metropolitan markets multiplies specialized fluid demand per vehicle.
- Commercial Vehicles:Group III+ and GTL base stocks enable 100,000-kilometer drain intervals for long-haul operators. ANVISA REACH-equivalent documentation requirements favor suppliers with technical dossier capabilities for cross-border fleet specifications.
- Heavy Machinery:Open-pit mining equipment in Chile's Antofagasta region consumes off-highway formulations with enhanced soot handling.
- Motorcycles:Wet-clutch-compatible engine oils serve two-wheeler parc concentration in Colombian urban centers.
Passenger Vehicles anchor volume consumption, with Commercial Vehicles gaining share fastest through fleet consolidation.
Distribution Channel:
Channel selection reflects customer technical sophistication and purchase scale.
- Retail:Branded lubricant presence in auto parts chains and hypermarkets serves individual vehicle owners. Brazil's coastal population concentration supports shelf-space competition between multinational and domestic brands.
- Direct Sales:Blending plants in Argentina's Córdoba cluster ship bulk formulations to mining contractors under long-term supply agreements.
- Online:E-commerce penetration remains limited by technical specification verification challenges.
- Wholesalers:Regional distributors bridge import logistics for additive packages facing Argentine central bank foreign exchange rationing delays.
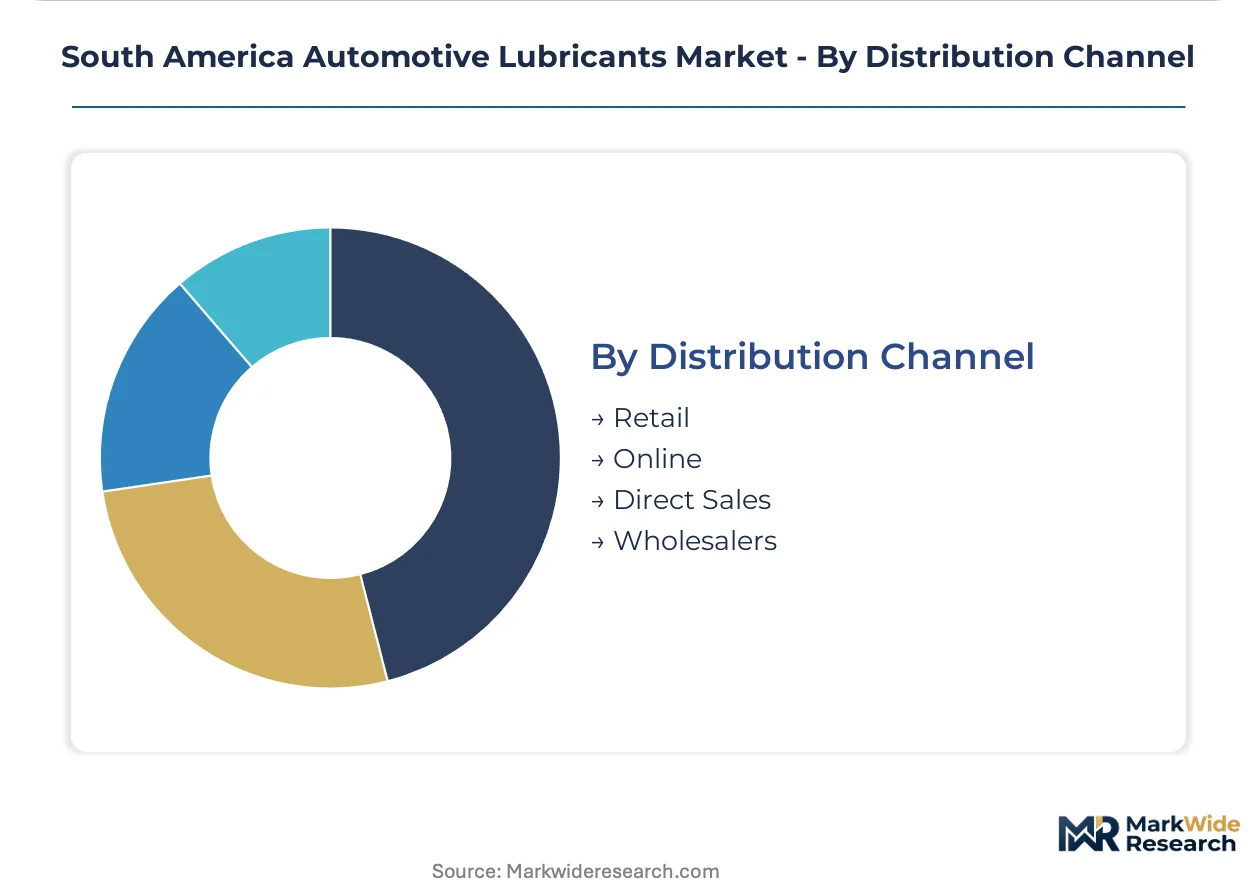
Retail maintains the broadest reach, while Direct Sales is deepening its position through equipment lessor integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Base oil imports flow disproportionately toward blending capacity concentrated in coastal industrial zones, while finished lubricant exports remain constrained by Mercosur tariff structures and divergent national registration protocols.
Brazil
Flex-fuel engine parc expansion and heavy-duty fleet consolidation in São Paulo state's industrial corridor sustain volume demand for Group III+ synthetic formulations. ANVISA's REACH-equivalent chemical safety protocols are elevating documentation burdens for imported additive packages. Blending plants in Paulínia and Mauá anchor supply security for coastal distribution networks.
Argentina
Córdoba's automotive manufacturing cluster generates factory-fill demand alongside aftermarket replacement for an aging passenger vehicle fleet. The central bank's foreign exchange rationing extends lead times for additive imports from North American suppliers. Blending capacity in Rosario serves agricultural equipment operators across the Pampas grain belt.
Chile
Antofagasta's open-pit mining operations multiply off-highway lubricant consumption per machine-hour for haul trucks and excavators. OECD-aligned chemical safety frameworks are creating preferential procurement channels for biodegradable hydraulic fluids in forestry applications. Santiago's metropolitan passenger vehicle parc drives dual-clutch transmission fluid specification complexity.
Colombia
Bogotá's altitude-driven thermal stress on engines creates differentiated demand for SAE 5W-40 and 0W-30 formulations with enhanced high-temperature shear stability. The national petroleum company maintains captive blending capacity for domestic supply security. Medellín's manufacturing base sustains industrial hydraulic fluid consumption.
Peru
Lima's commercial vehicle fleet and Andean mining operations in the central highlands generate parallel demand streams for on-highway and off-highway formulations. Import dependency for Group II and III base oils exposes blenders to Pacific shipping lane volatility. Arequipa's agro-industrial processing equipment sustains seasonal lubricant procurement cycles.
South America Automotive Lubricants Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in base oil and additive supply. The market structures around three tiers: multinational majors with captive distribution networks, national oil companies leveraging refinery integration, and specialized blenders serving niche mining and industrial applications. Competitive moves concentrate on backward integration into base oil production and telematics-enabled service bundling for fleet operators.
Within the multinational tier, Shell Plc and BP Plc occupy positions anchored by controlled distribution networks extending into Andean retail channels. Petrobras exemplifies the national oil company archetype through captive refinery network leverage across Brazilian coastal markets. FUCHS Petrolub SE represents specialized formulation expertise directed toward mining and off-highway equipment segments.
| Leading Market Players |
|---|
| BP Plc (Castrol) |
| ExxonMobil Corporation |
| Shell Plc |
| Chevron Corporation |
| TotalEnergies |
| Petrobras |
| Repsol S.A. |
| Iconic Lubrificantes |
| FUCHS Petrolub SE |
| Others |
Value Network & Pricing Analysis
The Santos-Guarulhos freight corridor's diesel surcharge volatility transmits directly into Group II and III base oil landed costs, concentrating pricing power with Paulínia blending plants while forcing São Paulo fleet operators into synthetic premium tiers to offset compressed drain intervals.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on ANVISA REACH-equivalent certification grade and volume scale in bulk fleet contracts. Cost compression in economy mineral formulations is intensifying because Argentine import financing constraints extend additive package lead times. Aftermarket workshop chains exhibit highest price sensitivity, while mining contractors in Antofagasta prioritize total cost of ownership over unit price.
Supply Chain Analysis
Extended payment terms from Brazilian distributors to Argentine additive suppliers now stretch 90-120 days, straining working capital for regional blenders. Supply concentrates in Brazil, the United States, and South Korea for Group III base stocks and friction modifier packages. The chain rests on zinc dialkyldithiophosphate and viscosity index improver imports vulnerable to central bank foreign exchange rationing. Distribution runs through controlled retail networks in coastal Brazil and direct sales contracts for Andean mining operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telematics-enabled oil analysis platforms are reconfiguring lubricant procurement into subscription ecosystems, where equipment lessors bundle fluid supply with predictive maintenance software and displace traditional distributor relationships.
For Market Incumbents: Build captive refinery-to-retail moats through backward integration into Group III+ base oil production at Paulínia and Mauá facilities. Secure ANVISA technical dossier capabilities to preempt additive reformulation mandates. Defend against asset-light leasing entrants by embedding oil analysis laboratories into fleet management contracts. For New Entrants and Emerging Players: Pursue biodegradable hydraulic fluid white-space in Chilean forestry and agricultural applications under OECD-aligned procurement preferences. Target Colombia's Andean corridor for altitude-stressed SAE 0W-30 formulations with enhanced high-temperature shear stability. Enter through telematics-integrated service bundling with regional equipment lessors. For Investors and Strategic Acquirers: Carve-out targets emerge from national oil company lubricant divisions seeking operational focus on upstream exploration. Five-to-ten year viability hinges on synthetic formulation capabilities and ANVISA compliance infrastructure. Watch for Mercosur specification harmonization as inflection signal for cross-border inventory consolidation plays.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Group III+ Base Oil Production | Petrobras's captive refinery network secures supply security against import volatility for São Paulo industrial corridor demand. |
| Telematics-Enabled Oil Analysis Platform Launch | Equipment lessors in Chile's Antofagasta mining region bundle predictive maintenance with fluid supply to capture procurement decisions. |
| ANVISA REACH-Equivalent Certification Investment | Technical documentation capabilities unlock Brazilian coastal market access for imported additive packages facing elevated scrutiny. |
| Biodegradable Hydraulic Fluid Manufacturing Scale-Up | Chile's OECD-aligned chemical safety framework creates preferential procurement channels for vegetable-oil-based forestry formulations. |
| Joint Venture with Andean Equipment Lessor | Condition-based maintenance contracts in Colombia's altitude-stressed commercial vehicle fleet displace fixed-interval service schedules. |
Research Methodology
Cross-validation between blending plant production records and customs import declarations anchors the qualitative findings on base oil flow patterns. Primary interviews with lubricant formulation chemists, fleet procurement managers at São Paulo heavy-duty operators, ANVISA regulatory affairs specialists, and mining maintenance directors in Antofagasta were triangulated against secondary sources including SEC filings of multinational lubricant suppliers, Brazilian trade ministry import statistics, and OECD chemical safety framework documentation. Bottom-up volume modeling from individual blending capacity and top-down demand estimation from vehicle parc data were reconciled.
Calibration against historical Group II and III base oil price series and fleet drain interval extension trends informed the projection framework across the analysis window. Segmentation dimensions include product type chemistry tiers, end-user procurement authority structures, application severity classifications, and distribution channel control levels. CAGRs were derived from elasticity-adjusted demand curves incorporating flex-fuel engine penetration and dual-clutch transmission adoption rates in Brazilian and Chilean passenger vehicle fleets.
Sensitivities concentrate around ANVISA additive chemistry disclosure rulemaking, Mercosur specification harmonization timelines, and Argentine central bank foreign exchange rationing intensity. Forecasts embody documented assumptions on electric commercial vehicle pilot conversion rates and mining equipment utilization hours. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Oil Pans Market
Automotive Parts
Mexico Automotive Parts Die Casting Market
Automotive Parts
Tire Mold Market
Automotive Parts
Mexico Automotive Parts Zinc Die Casting Market
Automotive Parts
Automotive Aluminum Parts High Pressure Die Casting (HPDC) Market
Automotive Parts
Brake Fluids Market
Automotive Parts
Malaysia Brake Pads Market
Automotive Parts
Philippines Automotive Engine Oils Market
Automotive Parts
Global Automotive Door Hinges Market
Automotive Parts
Italy Automotive Hydraulic Actuators Market
Automotive Parts
Europe Roll Forming Body in White Market
Automotive Parts
India Automotive Lubricants Market
Automotive Parts
Tire Vulcanizer Market
Automotive Parts
Wiper Blade Market
Automotive Parts
Global Intelligent All-Wheel Drive System Market
Automotive Parts
Automotive Cylinder Head Gasket Market