
 China Ceramic Ball Bearing Market | 2026-2036
China Ceramic Ball Bearing Market Size, Share, and Industry Trends Forecast 2026-2036
China Ceramic Ball Bearing Market Intelligence
China's dual carbon goals and the Ministry of Ecology and Environment's tightened industrial emissions standards are shifting procurement priorities toward ceramic bearings in high-wear applications. Jiangsu Dongpu Fine Ceramic leverages its Jiangsu province production base to dominate domestic supply of zirconium oxide bearings for precision machinery. Wafangdian Bearing Group Co., Ltd. anchors the heavy-industry segment with scale manufacturing for steel and cement equipment. Jiangsu Sinocera Jinsheng Ceramic specializes in silicon nitride formulations for aerospace and semiconductor tooling customers.
Ceramic ball bearings employ non-metallic rolling elements—typically silicon nitride, zirconium oxide, or silicon carbide—precision-ground to Grade 5 or better sphericity, housed in steel or ceramic races to achieve operating temperatures above 500°C and DN values exceeding one million. Their primary purpose is to eliminate adhesive wear, electrical pitting, and thermal distortion in spindles, turbomachinery, and EV motors where steel bearings fail. Deep groove bearings occupy the largest volume share due to universal fitment across industrial motors and automotive auxiliary drives. Silicon nitride material leads growth because its fracture toughness and thermal shock resistance enable direct substitution in high-speed machine tool spindles previously limited to steel. Thin-walled bearings concentrate margin pools in semiconductor lithography and medical imaging equipment where dimensional stability under vacuum conditions commands premium pricing.
MIIT's GB standards for high-performance bearings and SAMR's product quality certification requirements shape domestic market access and create compliance barriers for uncertified imports. The national standardization administration's push for indigenous ceramic powder processing standards is forcing upstream integration among bearing manufacturers. Stakeholders must monitor how Beijing's equipment renewal subsidy programs redirect toward ceramic-bearing-specified machine tools versus conventional steel alternatives.
Market Dynamics
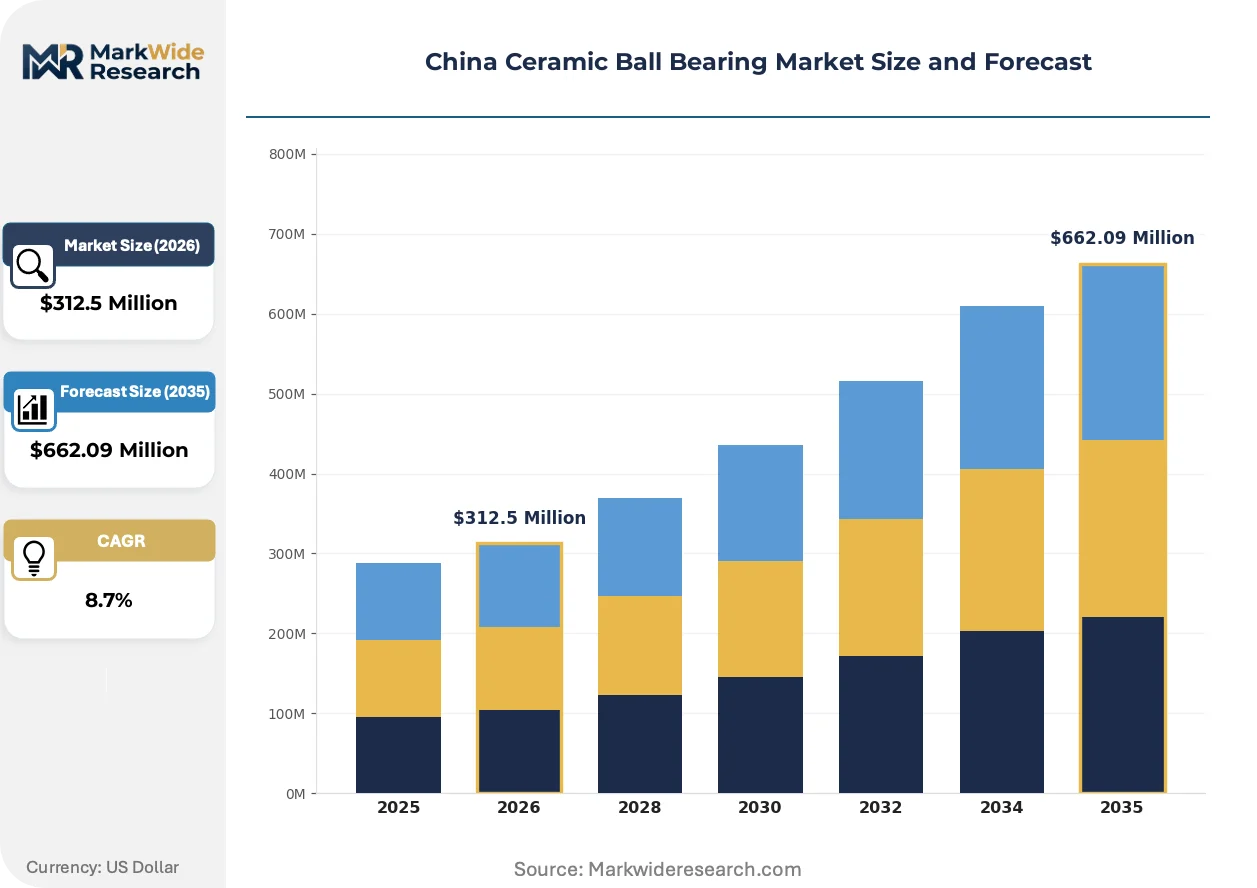
Beijing's dual carbon goals and MEE emissions enforcement are compressing steel bearing lifecycles in heavy manufacturing, forcing industrial buyers toward ceramic alternatives that withstand thermal shock and eliminate lubricant contamination risks in precision applications.
Growth Catalysts
- Silicon nitride substitution:EV powertrain manufacturers in the Yangtze River Delta are specifying ceramic bearings for motor spindles operating above 20,000 RPM where steel fatigue limits fail.
- MEE emissions standards:Tightened industrial emissions oversight under the Ministry of Ecology and Environment is disqualifying oil-lubricated steel bearings from new equipment certifications in Jiangsu and Shanghai manufacturing zones.
- Semiconductor lithography tooling:Wafer fabrication equipment builders are mandating vacuum-compatible ceramic bearings to eliminate outgassing and magnetic interference in EUV scanner stages.
Market Restraints
- Silicon nitride powder supply concentration:Domestic ceramic powder production concentrates in state-controlled refineries around Shandong province, creating input bottlenecks during quota allocation periods.
- Grade 5 sphericity grinding capacity:Precision grinding equipment for ceramic ball finishing is import-dependent from German and Japanese machine tool builders, extending lead times to 16-24 weeks.
- Steel bearing residual performance:Advanced vacuum-degassed steel formulations with ceramic coatings are retaining cost advantage in sub-10,000 RPM industrial motor applications.
Strategic Opportunities
- Xinjiang rare earth integration:Ceramic bearing manufacturers with backward integration into yttria-stabilized zirconia supply chains can capture margin from rare earth processing subsidies in western China.
- Medical imaging equipment:MRI scanner OEMs are specifying non-magnetic silicon nitride bearings for gradient coil positioning systems, opening premium pricing tiers above aerospace applications.
- MIIT equipment renewal subsidies:The Ministry of Industry and Information Technology's 2024-2027 machine tool replacement program explicitly favors ceramic-bearing-specified spindles in grant allocation scoring.
Industry Challenges
- Ceramic metallization expertise:Bonding ceramic rolling elements to steel races requires plasma spray and active brazing specialists whose training programs lag demand expansion in Guangdong and Zhejiang.
- SAMR certification timelines:Product quality certification under the State Administration for Market Regulation involves 8-14 month validation cycles for new ceramic formulations, compressing product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Ceramic Ball Bearing Market |
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $662.09 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Angular Contact Bearings, Deep Groove Bearings, Thin-Walled Bearings, Customized Bearings End User: Aerospace, Automotive, Electronics, Industrial Machinery Material: Zirconium Oxide, Silicon Nitride, Ceramic Hybrid, Silicon Carbide Application: High-Temperature, High-Speed, Corrosive Environments, Low Friction |
| Companies Covered | Jiangsu Dongpu Fine Ceramic, Wafangdian Bearing Group Co., Ltd., Jiangsu Sinocera Jinsheng Ceramic, Luoyang Bearing Corp, Renben Group Co., Ltd., Sinoma, Acro New Materials, Harbin Bearing Group Co., Ltd., Luoyang Bearing Research Institute, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Ceramic Ball Bearing Market Strategic Shifts & Innovations
Process automation in ceramic powder synthesis and precision grinding is compressing unit economics while regulatory mandates on industrial emissions are rewriting equipment procurement specifications across China's manufacturing heartland.
Hybrid ceramic bearing architectures combining silicon nitride balls with PEEK cages and corrosion-resistant steel races are automating the transition from full-steel to full-ceramic designs in chemical processing pumps. Fluoropolymer composite cage materials from Japanese suppliers are penetrating Chinese market channels through joint ventures in Suzhou industrial parks. This technology is automating the elimination of metal-to-metal contact in seawater desalination and nuclear coolant pump applications where lubricant contamination risks dominate lifecycle costing.
MIIT's updated GB standards for high-performance bearings are mandating indigenous ceramic powder processing documentation for domestic market access. The national standardization administration's push for traceable zirconia and silicon nitride supply chains is forcing bearing manufacturers to integrate upstream into powder synthesis or partner with state-certified refineries. Heavy-industry segments in Hebei and Shanxi provinces are responding by consolidating procurement around suppliers with verified GB/T certification compliance.
Direct technical collaboration between bearing manufacturers and end-user engineering teams is displacing distributor-mediated specification processes in precision machinery segments. Semiconductor and aerospace OEMs in Shanghai and Beijing are embedding ceramic bearing specialists within their spindle and turbomachine design departments. This pattern concentrates most visibly in the Yangtze River Delta cluster where Jiangsu-based ceramic suppliers maintain resident engineers at major machine tool builder headquarters.
China Ceramic Ball Bearing Market Segmentation
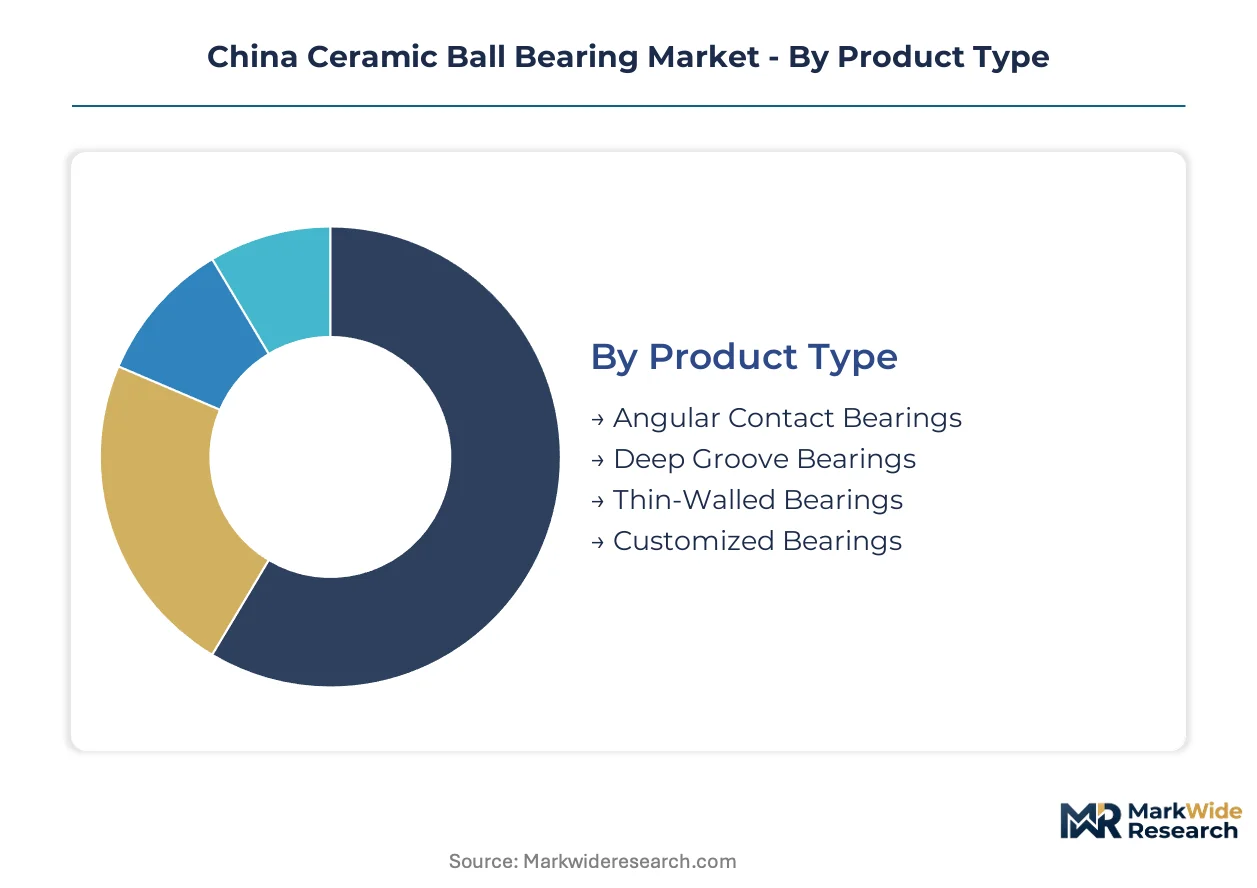
Ceramic ball bearing procurement in China fragments across four distinct classification systems. Each dimension reveals divergent margin structures, capital requirements, and regulatory exposure that shape supplier strategy.
Product Type:
Deep groove bearings demand the heaviest upfront tooling investment due to high-volume race grinding automation, while thin-walled configurations require specialized vacuum-chamber dimensional stabilization equipment.
- Angular Contact Bearings:Designed for combined radial and axial loads with contact angles between 15° and 40°. Machine tool spindle OEMs in the Yangtze River Delta specify these for rigidity-critical applications where preload control eliminates thermal runout.
- Deep Groove Bearings:Full-radius raceway geometry accommodates radial loads and moderate axial thrust in either direction. Jiangsu and Shanghai manufacturing clusters drive volume procurement for industrial motor retrofits under MEE emissions compliance deadlines.
- Thin-Walled Bearings:Section heights below standard ISO dimensions enable compact integration in semiconductor lithography stages. Vacuum-compatible variants command premium positioning in Beijing and Shenzhen wafer fabrication facilities.
- Customized Bearings:Application-specific geometries including flanged housings and integrated sensor mounts. Aerospace tier-one suppliers in Chengdu and Xi'an dominate specification authority for these low-volume, high-margin configurations.
Most installed capacity flows through deep groove bearings. Expansion is steepest in thin-walled bearings.
End User:
Automotive applications generate the highest unit volumes but compress margins through consolidated procurement, whereas aerospace programs sustain price premiums via qualification barriers.
- Aerospace:Satellite reaction wheel assemblies and jet engine auxiliary systems require Grade 3 sphericity with full material traceability. SAMR certification alignment with CAAC airworthiness directives extends validation timelines.
- Automotive:EV motor spindles and auxiliary drives dominate demand concentration. MIIT equipment renewal subsidies explicitly favor ceramic-bearing-specified powertrains in grant scoring.
- Electronics:Wafer handling robots and wire bonding equipment utilize non-magnetic silicon nitride to eliminate ESD damage. Shenzhen and Dongguan contract manufacturers drive specification standardization.
- Industrial Machinery:Steel mill continuous casters and cement kiln drives prioritize thermal shock resistance over precision. Hebei and Shanxi heavy-industry consolidation favors suppliers with verified GB/T compliance.
Automotive procurement absorbs the greatest production volume. Aerospace maintains the steepest price escalation curve.
Material:
Silicon nitride powder synthesis requires the most capital-intensive infrastructure, with plasma densification furnaces and isostatic pressing equipment dominating facility cost structures.
- Zirconium Oxide:Yttria-stabilized tetragonal phase delivers fracture toughness for moderate-speed applications. Medical imaging OEMs specify non-magnetic variants for MRI gradient coil positioning systems.
- Silicon Nitride:Highest strength-to-weight ratio among engineering ceramics enables direct steel substitution above 20,000 RPM. State-controlled Shandong refineries concentrate domestic powder supply.
- Ceramic Hybrid:Silicon nitride balls paired with steel races balance performance and cost in transitional applications. Chemical processing pumps in Zhejiang and Guangdong automate migration through this architecture.
- Silicon Carbide:Extreme hardness suits abrasive environments and ultra-high temperature seals. Nuclear coolant pump specifications in coastal provinces drive qualification investment.
Silicon nitride commands the largest production footprint. Ceramic hybrid configurations are gaining share fastest.
Application:
High-speed applications impose the most stringent manufacturing tolerances, with DN value thresholds above one million requiring specialized grinding wheel formulations and in-process measurement systems.
- High-Temperature:Operating envelopes exceeding 500°C demand silicon carbide or advanced silicon nitride grades. Steel and cement equipment in northern provinces sustain replacement cycles compressed by thermal fatigue.
- High-Speed:DN values above one million eliminate steel bearing viability in machine tool spindles. German and Japanese grinding equipment dependency extends lead times to 16-24 weeks.
- Corrosive Environments:Seawater desalination and chemical processing applications mandate full-ceramic or hybrid architectures with PEEK cages. Fluoropolymer composite materials penetrate through Suzhou joint ventures.
- Low Friction:Medical devices and precision instrumentation exploit ceramic's inherent lubricity for maintenance-free operation. Dental handpiece manufacturers in Guangdong specify sub-micron surface finishes.
High-temperature applications anchor current installation base. High-speed specifications show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized ceramic powder metallurgists and precision grinding technicians concentrate in eastern China's manufacturing corridors, anchoring production capacity for high-grade bearing components.
Yangtze River Delta
EV powertrain manufacturers in Shanghai and Jiangsu province specify silicon nitride bearings for motor spindles exceeding 20,000 RPM. MEE emissions enforcement disqualifies oil-lubricated steel bearings from new equipment certifications. Machine tool builders in Suzhou and Wuxi embed resident ceramic bearing specialists within design departments.
Beijing-Tianjin-Hebei
Aerospace tier-one suppliers in Beijing mandate Grade 3 sphericity with full material traceability for satellite reaction wheel assemblies. SAMR certification alignment with CAAC airworthiness directives extends validation timelines. Wafer fabrication facilities in the region specify vacuum-compatible ceramic bearings for EUV scanner stages.
Shandong Peninsula
State-controlled refineries concentrate domestic silicon nitride powder supply, creating input bottlenecks during quota allocation periods. MIIT's GB standards for high-performance bearings mandate indigenous ceramic powder processing documentation. Heavy-industry segments consolidate procurement around suppliers with verified GB/T compliance.
Pearl River Delta
Electronics contract manufacturers in Shenzhen and Dongguan drive specification standardization for wafer handling robots and wire bonding equipment. Fluoropolymer composite cage materials penetrate through Japanese joint ventures in Suzhou industrial parks. Medical device manufacturers in Guangdong specify sub-micron surface finishes for dental handpiece applications.
Sichuan-Chongqing
Aerospace programs in Chengdu and Xi'an sustain price premiums via qualification barriers for customized bearing configurations. Plasma spray and active brazing specialist training programs lag demand expansion. Regional suppliers focus on ceramic hybrid architectures balancing performance and cost in transitional applications.
China Ceramic Ball Bearing Market Key Industry Players
Capital-heavy producers compete with asset-light designers across China's ceramic bearing sector. The vendor base organizes around three strategic tiers: state-affiliated heavy-industry suppliers with integrated steel-ceramic hybrid capacity, specialized ceramic powder processors serving precision machinery segments, and regional bearing assemblers targeting retrofit markets. Dominant competitive moves include backward integration into ceramic powder synthesis and strategic partnerships with semiconductor lithography OEMs for thin-walled bearing qualification.
Among Jiangsu-based ceramic specialists, Jiangsu Dongpu Fine Ceramic and Jiangsu Sinocera Jinsheng Ceramic occupy positions within the precision-grade tier, while Wafangdian Bearing Group Co., Ltd. anchors the heavy-industry segment with scale manufacturing capabilities. These companies exemplify the geographic clustering of ceramic bearing production in eastern China's manufacturing heartland, where proximity to EV powertrain and semiconductor equipment customers shapes competitive positioning.
| Leading Market Players |
|---|
| Jiangsu Dongpu Fine Ceramic |
| Wafangdian Bearing Group Co., Ltd. |
| Jiangsu Sinocera Jinsheng Ceramic |
| Luoyang Bearing Corp |
| Renben Group Co., Ltd. |
| Sinoma |
| Acro New Materials |
| Harbin Bearing Group Co., Ltd. |
| Luoyang Bearing Research Institute |
| Others |
Cost & Logistics Intelligence
Silicon nitride powder spot indices in Shandong province cascade through three distinct pricing tiers, with state-controlled refinery quotas compressing margin pools for ceramic bearing assemblers lacking backward integration into powder synthesis.
Pricing Analysis
Unbundled ceramic ball procurement dominates high-volume industrial retrofits, while bundled spindle-integrated solutions command premiums in semiconductor lithography applications. Three-tier pricing structure across precision-grade, standard-grade, and economy-grade certification levels separates aerospace-qualified suppliers from mass-market assemblers. Cost compression in economy-grade deep groove bearings is intensifying because Jiangsu-based manufacturers are absorbing powder quota volatility to maintain OEM contracts. Automotive EV powertrain procurement teams exhibit the highest price sensitivity, whereas Beijing aerospace tier-one suppliers tolerate 40-60% premiums for full material traceability.
Supply Chain Analysis
MIIT's indigenous ceramic powder processing documentation mandates are reshaping sourcing patterns, forcing bearing manufacturers to abandon German and Japanese powder suppliers in favor of state-certified Shandong refineries. Domestic production draws from silicon nitride powder synthesis, precision grinding wheel imports, and PEEK cage materials through Suzhou joint ventures. Single-source vulnerability concentrates in Grade 5 sphericity grinding equipment anchored in Germany and Japan. Distribution runs through direct technical collaboration channels where Jiangsu-based suppliers embed resident engineers at major machine tool builder headquarters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The China ceramic ball bearing market functions as a stable compounder, with MIIT equipment renewal subsidies providing predictable demand visibility across multi-year replacement cycles.
For Market Incumbents: Cement dominance in silicon nitride formulations by securing captive powder supply from Shandong state refineries before quota allocation periods tighten further. Expand precision grinding capacity through technology licensing agreements with German machine tool builders to compress 16-24 week lead times. Defend against emerging hybrid ceramic entrants by accelerating SAMR certification timelines for next-generation EUV-compatible thin-walled bearings. For New Entrants and Emerging Players: MIIT's GB standards for high-performance bearings in China opens a window for specialized ceramic metallization service providers to capture margin from plasma spray and active brazing bottlenecks in Guangdong and Zhejiang. Target medical imaging equipment OEMs specifying non-magnetic silicon nitride bearings for MRI gradient coil positioning systems, where premium pricing exceeds aerospace benchmarks. Pursue joint venture structures with Japanese fluoropolymer composite cage suppliers to access Suzhou industrial park distribution channels. For Investors and Strategic Acquirers: Consolidation pressure builds where precision grinding equipment import dependency creates insurmountable scale barriers for sub-scale domestic assemblers. Over a multi-decade industrial upgrading cycle, acquisition targets with verified GB/T compliance and resident engineer relationships at Yangtze River Delta machine tool builders offer defensive positioning. Monitor Shandong province silicon nitride powder quota allocation announcements as the primary inflection indicator for input cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Powder Synthesis | Captures margin from state-controlled Shandong refinery quotas under MIIT documentation mandates. |
| Precision Grinding Equipment Technology Licensing | Compresses lead times dependent on German and Japanese machine tool builders. |
| SAMR Certification Acceleration | Shortens 8-14 month validation cycles for new ceramic formulations in aerospace applications. |
| Resident Engineer Embedding Programs | Displaces distributor-mediated specification processes at Yangtze River Delta machine tool headquarters. |
| Medical Imaging Equipment Partnership | Accesses premium pricing tiers for non-magnetic silicon nitride bearings in MRI gradient coil systems. |
Research Approach
Coverage spans the Yangtze River Delta, Beijing-Tianjin-Hebei, Shandong Peninsula, Pearl River Delta, and Sichuan-Chongqing regions, with primary inputs from each manufacturing cluster triangulated against secondary validation. Conversations with ceramic powder metallurgists, precision grinding technicians, EV powertrain procurement managers, semiconductor lithography equipment engineers, and SAMR certification specialists informed demand-side assumptions. Secondary sources include MIIT GB standards documentation, MEE emissions enforcement records, SAMR product quality certification databases, and provincial industrial statistics bureaus. Bottom-up unit economics modeling reconciled with top-down market sizing across each regional production hub.
Granularity-level modeling disaggregated volume and value projections by product type, end user industry, ceramic material formulation, and application environment across the projection horizon. Segmentation dimensions included angular contact versus deep groove versus thin-walled versus customized bearing geometries, with silicon nitride, zirconium oxide, ceramic hybrid, and silicon carbide material tiers separately forecasted. CAGRs were derived from regression analysis of historical procurement patterns against MIIT equipment renewal subsidy allocation trajectories and MEE emissions compliance deadline schedules.
Revisions become necessary when Shandong province silicon nitride powder quota allocations tighten beyond historical seasonal patterns, or when German and Japanese precision grinding equipment export controls disrupt Grade 5 sphericity capacity expansion timelines. Forecasts reflect assumptions about continued MIIT subsidy favoritism toward ceramic-bearing-specified machine tools and stable CAAC-SAMR certification alignment timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Electric Vehicle Aluminum Electric Drive Parts Market
Automotive Parts
Automotive AC Compressor Market
Automotive Parts
Automotive Transmission Valve Spool Market
Automotive Parts
Automotive Control Arms Market
Automotive Parts
Industrial V Belt Market
Automotive Parts
Automotive Proportioning Valves Market
Automotive Parts
Latin America Automotive Parts Magnesium Die Casting Market
Automotive Parts
Thin-Section Ball Bearings Market
Automotive Parts
Automotive Antifreeze Market
Automotive Parts
Automotive Lifts Market
Automotive Parts
Tire Mold Market
Automotive Parts
Automotive Electric Water Pump Market
Automotive Parts
Automotive Pneumatic Actuators Market
Automotive Parts
Automotive Parts Die Casting Market
Automotive Parts
Automotive Screenwash Products Market
Automotive Parts
Automotive Fluids Market