
 Global Passenger Vehicles Lubricants Market | 2026-2036
Global Passenger Vehicles Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Global Passenger Vehicles Lubricants Market Foresight
China's refining capacity expansion is reshaping competitive dynamics in passenger vehicle lubricants. ExxonMobil Corporation leverages its integrated upstream-downstream model to secure base oil supply security across Asia-Pacific. Shell plc anchors its position through synthetic technology leadership and OEM co-development partnerships. BP PLC differentiates via carbon-neutral product lines and circular economy initiatives.
Passenger vehicle lubricants comprise formulated oils and functional fluids engineered to reduce friction, dissipate heat, and protect powertrain components across internal combustion and hybrid architectures. Synthetic formulations achieve viscosity grades as low as 0W-8 through polyalphaolefin and ester base stocks, enabling fuel economy gains under stop-start urban duty cycles. Engine oil remains the largest value pool, though transmission fluid captures disproportionate margin growth as dual-clutch and continuously variable transmissions proliferate. Synthetic technology leads volume growth, while mineral oil retains share in emerging markets where price sensitivity constrains upgrade cycles.
The US EPA, Europe's REACH framework, and China's MEE enforce tightening volatility and toxicity standards that force reformulation investments and compress regional product variance. Japan's METI and South Korea's MFDS extend these requirements through national fuel economy regulations that effectively mandate lower-viscosity lubricants. Stakeholders must monitor regulatory divergence between emissions-focused jurisdictions and emerging markets where enforcement remains uneven, as this bifurcation will determine portfolio complexity and capital allocation priorities.
Market Dynamics
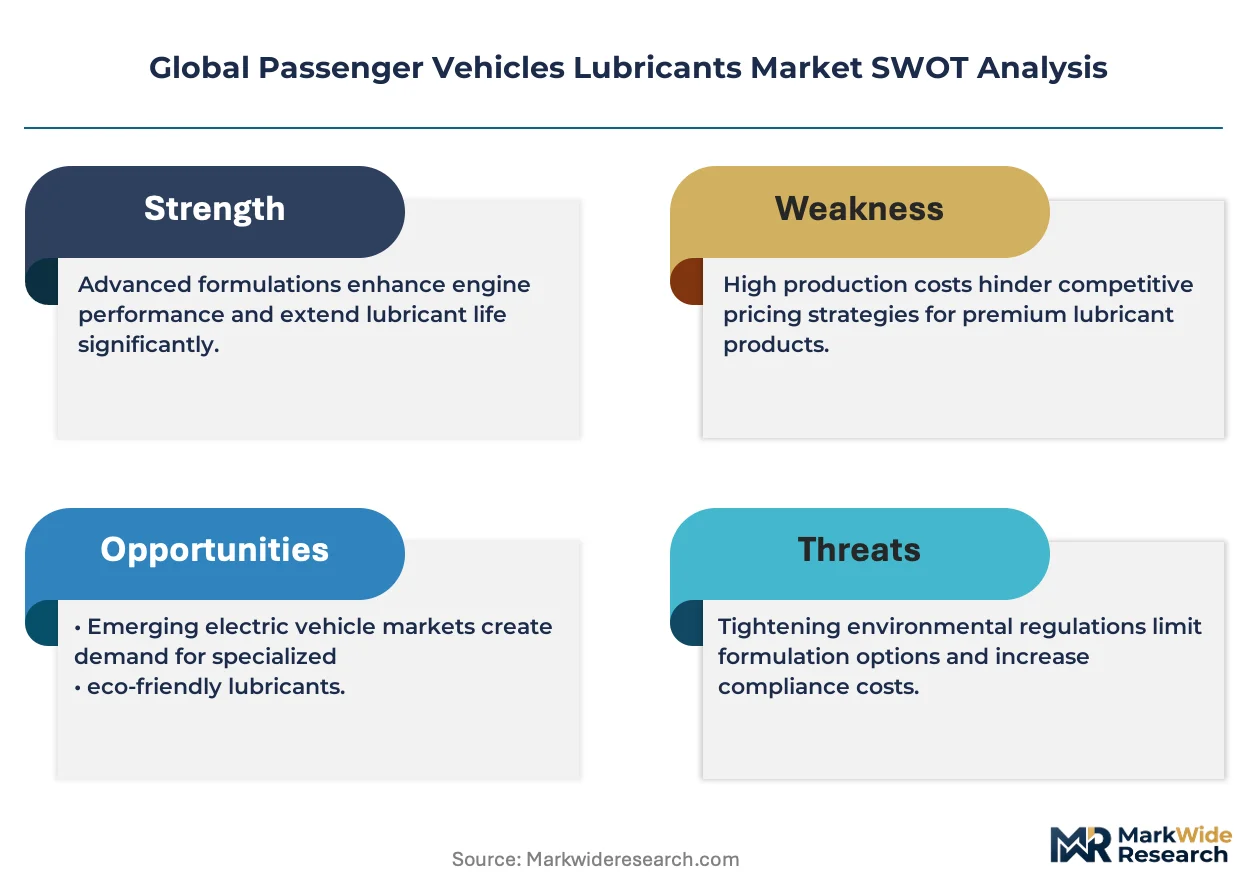
Synthetic lubricant formulations are compressing mineral oil margins while regulatory volatility standards in the EU, US, and China force simultaneous reformulation across all major supply bases.
Growth Catalysts
- Dual-clutch transmission proliferation:Advanced transmission architectures demand specialized fluids with friction stability under high thermal loads. OEM specification tightening pulls premium synthetic volumes.
- Europe's F-Gas Regulation:Mandatory phase-down of high-GWP substances accelerates reformulation toward lower-viscosity, lower-emission lubricant chemistries across passenger vehicle categories.
- Ride-hailing fleet standardization:Uber, Didi, and Grab operators specify extended-drain synthetic protocols to maximize vehicle utilization rates and reduce total cost of ownership.
Market Restraints
- Group III base oil supply concentration:Asian refinery expansions in China and South Korea control critical synthetic feedstock volumes, creating import dependency for Western blenders.
- REACH compliance cost escalation:ECHA substance evaluation and authorization procedures extend reformulation timelines and raise R&D expenditure for products entering European markets.
- Battery electric vehicle fluid displacement:Reduced lubrication points in pure electric powertrains eliminate engine oil demand entirely, threatening the category's largest volume segment.
Strategic Opportunities
- India's BIS certification expansion:Mandatory quality standards for automotive lubricants create premium tier openings as informal mineral oil channels face compliance pressure.
- Hybrid thermal management fluids:Dual-powertrain architectures require coolants and lubricants with broader operating temperature ranges than conventional ICE formulations.
- Direct-to-fleet digital distribution:Telematics-integrated oil monitoring enables predictive drain scheduling and subscription-based fluid replenishment models.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in polyalphaolefin-ester blending and additive package optimization concentrates among retiring technical staff at major oil companies.
- OEM approval timeline compression:Accelerated vehicle development cycles demand lubricant certification completion within 18-month windows, straining testing infrastructure.
- Legacy system integration friction:Established mineral oil production assets require costly retrofit for synthetic base stock handling and additive dosing precision.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Passenger Vehicles Lubricants Market |
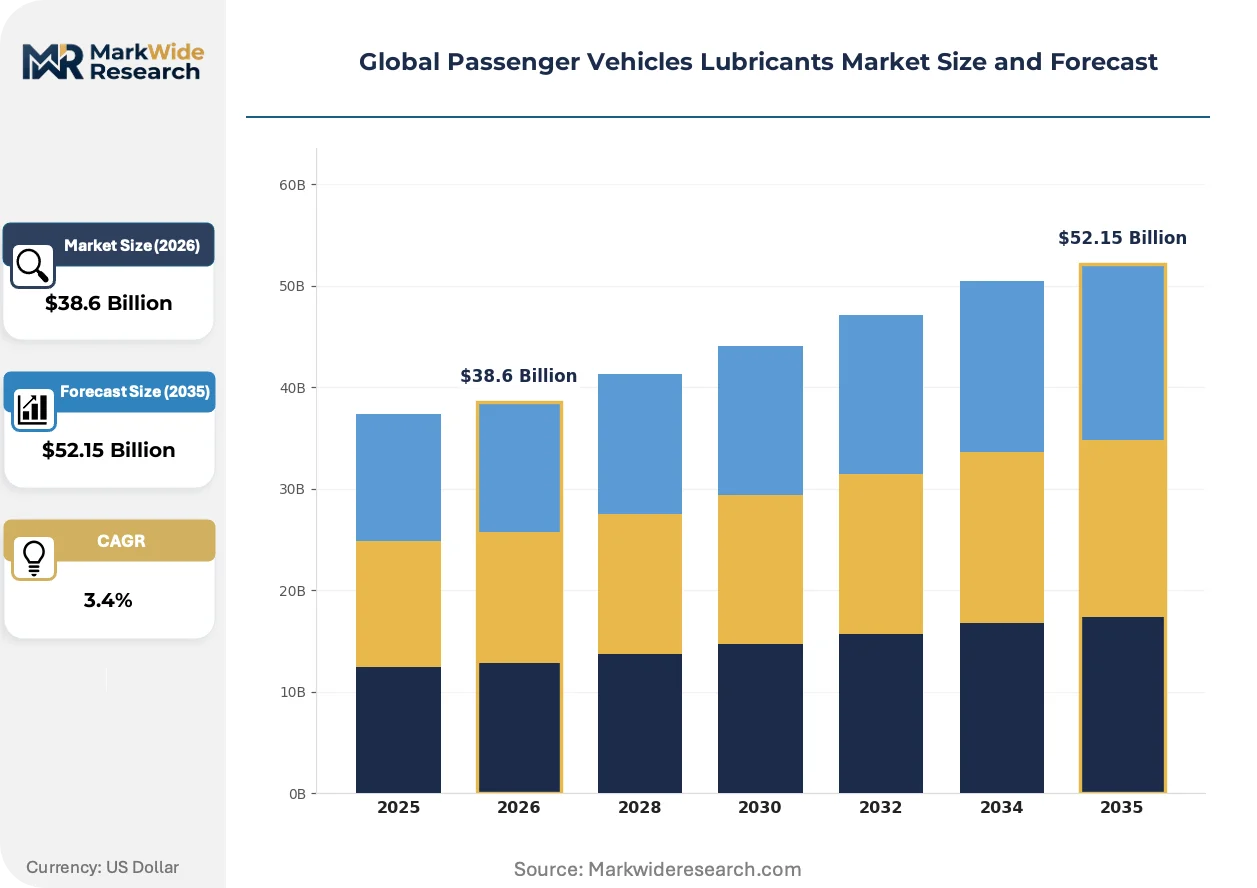
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $52.15 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Gear Oil, Transmission Fluid, Brake Fluid, Hydraulic Oil, Greases Technology: Synthetic, Semi-Synthetic, Mineral, Bio-Based, Nanotechnology-Enhanced, Ester Application: Passenger Cars, Light Commercial Vehicles, SUVs, Multi-Purpose Vehicles, Compact Vehicles, Luxury Cars End User: OEMs, Independent Garages, Dealerships, Aftermarket Providers, Vehicle Assemblers, Specialty Service Centers |
| Companies Covered | ExxonMobil Corporation, Shell plc, BP PLC, Chevron Corporation, TotalEnergies SE, China Petroleum & Chemical Corporation, China National Petroleum Corporation, PetroChina Company Limited, Idemitsu Kosan Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Passenger Vehicles Lubricants Market Shifts & Advancements
Formulation science is converging with powertrain electrification to redefine fluid performance specifications across thermal, electrical, and mechanical stress domains.
Polyalphaolefin-ester base stock technology is hybridizing conventional mineral oil supply chains. High-performance synthetic blends now dominate OEM first-fill contracts in Germany, Japan, and South Korea. This chemistry migration is compressing Group I and Group II base oil utilization rates in premium passenger vehicle segments.
REACH authorization procedures are tightening volatility and toxicity thresholds for lubricant components sold into European markets. ECHA substance evaluation forces additive package redesigns and accelerates substitution of legacy friction modifiers. Asian blenders serving EU export channels face accelerated compliance investments or market exclusion.
Telematics-enabled condition monitoring is restructuring fleet procurement relationships. Commercial vehicle operators in North America and China now specify oil-drain intervals based on actual degradation metrics rather than fixed mileage schedules. This data-driven approach unbundles traditional workshop service bundles and shifts volume concentration toward direct supplier-fleet contracts.
Global Passenger Vehicles Lubricants Market Segmentation
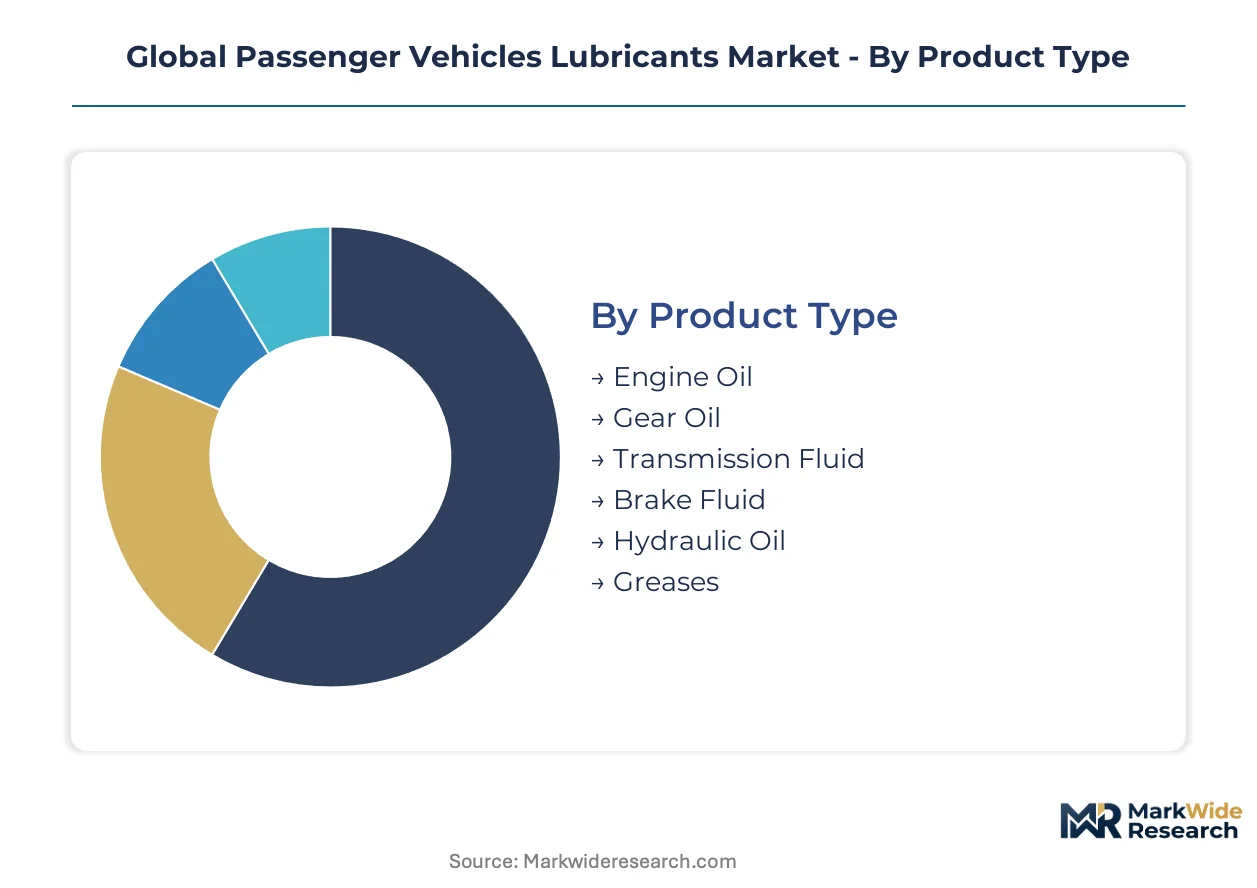
Passenger vehicle lubricants fragment across technical specifications, supply chain positions, and vehicle architectures that each carry distinct margin profiles and certification requirements. Understanding these divisions reveals where formulation investments concentrate and which channels command pricing power.
Product Type:
Application function determines additive package complexity and drain interval economics across the vehicle powertrain.
- Engine Oil:Formulated with detergent-dispersant and anti-wear additive packages to manage combustion byproducts and cylinder wall friction. Demand concentrates in China and India where ICE fleet expansion continues, though OEM first-fill contracts in Germany and Japan now specify 0W-8 and 0W-12 synthetic grades for fuel economy compliance.
- Transmission Fluid:Dual-clutch and continuously variable transmission architectures require friction stability under high thermal cycling and shear stress. South Korean and Japanese OEMs pull premium synthetic volumes through specification tightening for 8-speed and 10-speed automatic gearboxes.
- Gear Oil:Hypoid gear protection formulations serve final drive differentials with extreme pressure additive chemistry.
- Brake Fluid:Glycol-ether and silicone-based formulations meet DOT 3, DOT 4, and DOT 5.1 boiling point specifications.
- Hydraulic Oil:Power steering and suspension systems require anti-foam and oxidation stability.
- Greases:Lithium complex and polyurea thickeners serve chassis and wheel bearing applications.
Engine oil holds installed capacity. Transmission fluid is rotating up the share rankings.
Technology:
Base stock chemistry tiers separate cost structures, performance envelopes, and regulatory compliance pathways.
- Synthetic:Polyalphaolefin and Group III+ hydrocracked base stocks achieve viscosity indices above 140 and pour points below minus 40 degrees Celsius. OEM co-development partnerships in Japan and Germany now mandate synthetic first-fill for turbocharged direct-injection engines facing stop-start urban duty cycles.
- Mineral:Solvent-refined Group I and hydrocracked Group II base stocks dominate price-sensitive replacement demand. India's informal service channels and Southeast Asian independent garages sustain volumes despite synthetic upgrade pressure from BIS certification expansion.
- Semi-Synthetic:Blended formulations balance cost and performance for mid-market vehicle segments.
- Bio-Based:Vegetable oil esters and biodegradable additives serve environmental compliance niches in Nordic markets.
- Nanotechnology-Enhanced:Boron nitride and tungsten disulfide nanoparticles reduce boundary friction in extreme load conditions.
- Ester:Diester and polyol ester base stocks deliver thermal stability for aviation-derived automotive applications.
Synthetic commands the steepest expansion trajectory. Mineral retains volume leadership in emerging market aftermarket channels.
Application:
Vehicle architecture and duty cycle intensity drive fluid specification divergence across weight classes and use patterns.
- Passenger Cars:Compact and mid-size sedans constitute the largest addressable reservoir, with Chinese domestic brands and Japanese transplants specifying extended-drain synthetic protocols. Ride-hailing fleet operators in Mexico City and São Paulo now mandate 15,000-kilometer drain intervals through telematics-validated oil condition monitoring.
- SUVs:Higher displacement engines and all-wheel-drive differentials multiply lubrication points per vehicle. North American and Australian markets sustain disproportionate synthetic consumption through towing duty cycles and high-temperature climate exposure.
- Light Commercial Vehicles:Delivery van and small truck applications prioritize durability over fuel economy.
- Multi-Purpose Vehicles:Family transport configurations balance passenger comfort with load capacity.
- Compact Vehicles:A-segment and B-segment cars in India and Brazil face severe cost compression on fluid specifications.
- Luxury Cars:BMW, Mercedes-Benz, and Audi first-fill contracts specify ester-enhanced synthetics with bespoke additive packages.
Passenger cars anchor volume throughput. SUVs are climbing the fastest in value contribution per vehicle.
End User:
Channel structure determines brand loyalty mechanics, technical specification influence, and inventory carrying economics.
- OEMs:Vehicle manufacturers specify first-fill lubricants through multi-year supply agreements with technical co-development clauses. Toyota, Volkswagen, and Hyundai validate additive packages through 100,000-kilometer durability testing, locking in supplier relationships across model generations.
- Independent Garages:Fragmented service networks in Italy, Spain, and Poland compete on price with bulk mineral oil purchasing. India's unorganized sector faces compression from BIS mandatory certification requirements that elevate compliance costs.
- Dealerships:Authorized service channels maintain OEM specification adherence for warranty compliance.
- Aftermarket Providers:Retail and e-commerce distribution of packaged lubricants serves DIY maintenance segments.
- Vehicle Assemblers:Contract manufacturing facilities require just-in-time fluid delivery for production line fill.
- Specialty Service Centers:Quick-lube chains and fleet maintenance depots concentrate volume purchasing power.
OEMs hold specification authority. Independent garages are rotating up the share rankings through fleet outsourcing contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ningbo-Zhoushan Port anchors Asia-Pacific lubricant trade flows, handling Group III base oil imports that feed China's coastal blending plants. This maritime infrastructure underwrites the region's dominance in synthetic feedstock logistics.
China
State-owned refinery expansions in Shandong and Liaoning provinces are capturing synthetic base oil supply chains previously served by imports. MEE enforcement of volatility standards is accelerating reformulation toward 0W-8 viscosity grades. The Yangtze River Delta clustering around Shanghai hosts the country's largest lubricant blending capacity, where domestic brands now supply OEM first-fill contracts for Geely and BYD.
Germany
Automotive OEM specification tightening by Volkswagen and BMW is pulling premium synthetic volumes through extended-drain protocols. REACH authorization procedures through ECHA are forcing additive package redesigns for friction modifiers entering European markets. The Rhine-Ruhr industrial corridor concentrates blending assets near BASF's Ludwigshafen chemical complex, enabling just-in-time additive sourcing for export-bound formulations.
United States
Fleet telematics adoption by Uber and Lyft operators is restructuring procurement toward condition-based drain scheduling rather than fixed intervals. EPA volatility standards under the Clean Air Act are compressing regional product variance and elevating compliance costs for small blenders. The Gulf Coast petrochemical corridor around Houston anchors Group II and Group III base oil production, with pipeline connectivity to Midwest automotive assembly plants.
India
BIS mandatory certification for automotive lubricants is elevating compliance costs for informal mineral oil channels in Mumbai and Delhi aftermarket networks. The country's national automotive regulator is aligning fuel economy testing protocols with global WLTP standards, effectively mandating lower-viscosity lubricants for new vehicle homologation. The Gujarat refinery complex near Jamnagar is expanding Group II capacity to reduce import dependency for synthetic feedstocks.
Japan
METI fuel economy regulations are accelerating OEM adoption of 0W-16 and 0W-20 synthetic grades for hybrid powertrains. Toyota and Honda co-development partnerships are locking in additive package validation through 100,000-kilometer durability testing. The Chubu region around Nagoya hosts concentrated blending capacity serving Toyota's just-in-time production system, with formulation adjustments synchronized to powertrain launch cycles.
Global Passenger Vehicles Lubricants Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream on base stock and additive chemistry. The market structure concentrates around integrated oil majors with captive refinery assets and national oil companies leveraging domestic feedstock security. Three archetypes dominate: vertically integrated multinationals with global brand equity, state-owned enterprises with protected home-market share, and regional blenders competing on price in fragmented aftermarket channels. Competitive dynamics center on backward integration into base oil production and strategic partnerships with OEMs for first-fill specification authority.
Among the integrated multinational tier, ExxonMobil Corporation and Shell plc exemplify platform-scale positioning through upstream-downstream coordination and synthetic technology leadership respectively. BP PLC occupies a position within the carbon-neutral product segment, anchoring reformulation efforts around circular economy initiatives. These three entities represent the competitive standard against which national oil companies and regional specialists benchmark their strategic positioning.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| Shell plc |
| BP PLC |
| Chevron Corporation |
| TotalEnergies SE |
| China Petroleum & Chemical Corporation |
| China National Petroleum Corporation |
| PetroChina Company Limited |
| Idemitsu Kosan Co., Ltd. |
| Others |
Supply & Pricing Matrix
Asian refinery concentration in China and South Korea for Group III base oils concentrates margin capture upstream, forcing Western blenders to absorb feedstock volatility or surrender share in premium synthetic tiers. This upstream leverage cascades downstream into OEM first-fill negotiations and fleet procurement contracts.
Pricing Analysis
REACH authorization through ECHA dictates the pricing tier structure across European markets, separating ester-enhanced synthetics certified for extended-drain protocols from mineral oil formulations facing compliance exclusion. Three-tier pricing structure across premium, standard, and economy levels reflects additive package complexity, drain interval validation, and OEM approval status. Cost compression in mid-tier synthetics is intensifying because Asian blenders are exporting surplus Group III capacity into EU aftermarket channels. Price-sensitive independent garages in Southern Europe and Southeast Asia resist upgrade cycles, while German and Japanese OEMs lock in premium synthetic contracts regardless of spot feedstock movement.
Supply Chain Analysis
Tariff exposure between China and Western export markets dominates supply chain risk calculus for multinational blenders sourcing Group III base oils. Production gravity centers on China's Shandong and Liaoning provinces, South Korea's Ulsan refining complex, and the US Gulf Coast petrochemical corridor. Feedstock sourcing draws from polyalphaolefin production in Belgium and Singapore, hydrocracked Group III from South Korea, and additive packages from BASF's Ludwigshafen and Infineum's Singapore facilities. Single-source vulnerability concentrates in friction modifier chemistry subject to ECHA substance evaluation. Distribution runs through coastal blending plants at Ningbo-Zhoushan, Rotterdam, and Houston, with inland logistics via rail to Midwest US and Rhine-Ruhr automotive clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Passenger Vehicles Lubricants Market is cycling through an ICE-to-hybrid transition trough, with recovery tied to fleet renewal rates in ride-hailing and commercial lease channels. OEM specification tightening for lower-viscosity synthetics provides the cyclical uplift mechanism.
For Market Incumbents: Entrench synthetic formulation leadership through captive Group III supply arrangements in Asia-Pacific and accelerated OEM co-development timelines. Battery electric vehicle fluid displacement threatens engine oil volumes; defend through hybrid thermal management fluid portfolios and transmission fluid specification authority. Backward integration into base oil production in China and South Korea secures feedstock cost position against Asian national oil companies.
For New Entrants and Emerging Players: India's informal aftermarket channels present the most penetrable white-space target as BIS certification forces compliance investment beyond informal mineral oil blenders. Direct-to-fleet digital distribution models bypass entrenched workshop networks in Mexico City and São Paulo. Target telematics-integrated oil monitoring subscriptions to capture predictive maintenance spend from Uber and Didi operators.
For Investors and Strategic Acquirers: Capital is best deployed toward additive package specialists with ECHA pre-registration status and OEM validation through 100,000-kilometer durability testing. Long-term viability hinges on hybrid powertrain fluid portfolios bridging ICE decline and BEV adoption lag. Watch for inflection in Chinese state-owned refinery export pricing as synthetic base oil surplus triggers regional price wars.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Group III Base Oil | Captive supply from Chinese and South Korean refinery expansions neutralizes import dependency for Western blenders. |
| OEM Co-Development Partnership | Toyota and Volkswagen validation protocols lock in additive package specification across model generations. |
| Telematics-Integrated Fleet Distribution | Predictive drain scheduling unbundles workshop service bundles for Uber and Didi procurement teams. |
| REACH Compliance Pre-Registration | ECHA substance evaluation status prevents market exclusion for friction modifier chemistry suppliers. |
| Hybrid Thermal Management Fluid Launch | Dual-powertrain architectures require broader operating temperature ranges than conventional ICE formulations. |
Research Methodology
Desk research of customs trade data, SEC filings from integrated oil majors, and vehicle production databases preceded structured interviews with lubricant formulation chemists, OEM procurement directors, and fleet operations managers. Primary fieldwork captured specification tightening timelines, drain interval validation protocols, and telematics procurement patterns. Secondary validation drew from EPA volatility standards documentation, ECHA REACH authorization records, and China's MEE enforcement bulletins. Bottom-up volume modeling triangulated against top-down refinery capacity and base oil trade flow analysis.
Assumptions held ICE fleet composition, regulatory enforcement intensity, and OEM development cycle timing fixed across the modeling period. Segmentation dimensions included base stock chemistry tier, powertrain architecture, and regional regulatory cluster. CAGRs were derived from installed vehicle parc projections and content-per-vehicle estimates for synthetic penetration rates. Forecast inputs incorporated ride-hailing fleet standardization protocols and BIS certification expansion timelines in India.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Chinese state-owned refiners or accelerated BEV adoption by European OEMs would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Argentina Automotive Actuators Market
Automotive Parts
Automotive Hinges Market
Automotive Parts
Germany Automotive Parts Aluminium Die Casting Market
Automotive Parts
India Automotive Coolant Market
Automotive Parts
Automotive Coolant Market
Automotive Parts
Camshaft Lifters Market
Automotive Parts
South Korea Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Differential Housing Market
Automotive Parts
Motorcycle Catalyst Market
Automotive Parts
Automotive Brake Fluid Market
Automotive Parts
Leaf Spring Shackle Side Bar Market
Automotive Parts
Nigeria Commercial Vehicles Lubricants Market
Automotive Parts
Saudi Arabia Vehicle Exhaust Hose Market
Automotive Parts
China Ceramic Ball Bearing Market
Automotive Parts
Connecting Rods Market
Automotive Parts
Aluminum Parts Gravity Die Casting Market