
 Colombia Passenger Vehicles Lubricants Market | 2026-2036
Colombia Passenger Vehicles Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Colombia Passenger Vehicles Lubricants Market Outlook
Fleet operator demand is expanding faster than individual owner consumption in Colombia's passenger vehicle lubricants sector. Royal Dutch Shell PLC leverages its integrated supply chain to dominate coastal distribution corridors. Chevron Corporation sustains competitive positioning through specialized synthetic formulations for high-altitude Andean operations. Terpel anchors its market presence via extensive retail fuel station networks that double as lubricant points of sale.
Colombia passenger vehicles lubricants comprise refined petroleum-based and synthetic formulations engineered to reduce friction, dissipate heat, and prevent wear in internal combustion engines operating under tropical and mountainous conditions. These products typically incorporate viscosity modifiers, detergents, and anti-wear additives meeting SAE and API performance classifications to ensure engine longevity across diverse Colombian terrain. Engine oil occupies the largest volume share among product types, reflecting the high frequency of oil changes in stop-and-go urban traffic prevalent in cities like Bogotá and Medellín. Synthetic grade formulations represent the fastest-expanding segment as fleet operators prioritize extended drain intervals to minimize vehicle downtime. Mineral lubricants retain residual demand among price-sensitive individual car owners in secondary cities where workshop infrastructure remains limited.
Colombia's Ministry of Mines and Energy enforces fuel quality and biofuel blending standards that directly influence lubricant additive chemistry and compatibility requirements. The Superintendency of Industry and Commerce oversees competition and consumer protection rules affecting distribution channel structures. ANLA, the national environmental licensing authority, regulates waste oil disposal and recycling protocols that shape aftermarket service economics. Stakeholders must monitor regulatory adjustments to biofuel mandates and evolving emissions standards that will determine formulation investments and channel compliance costs.
Market Dynamics
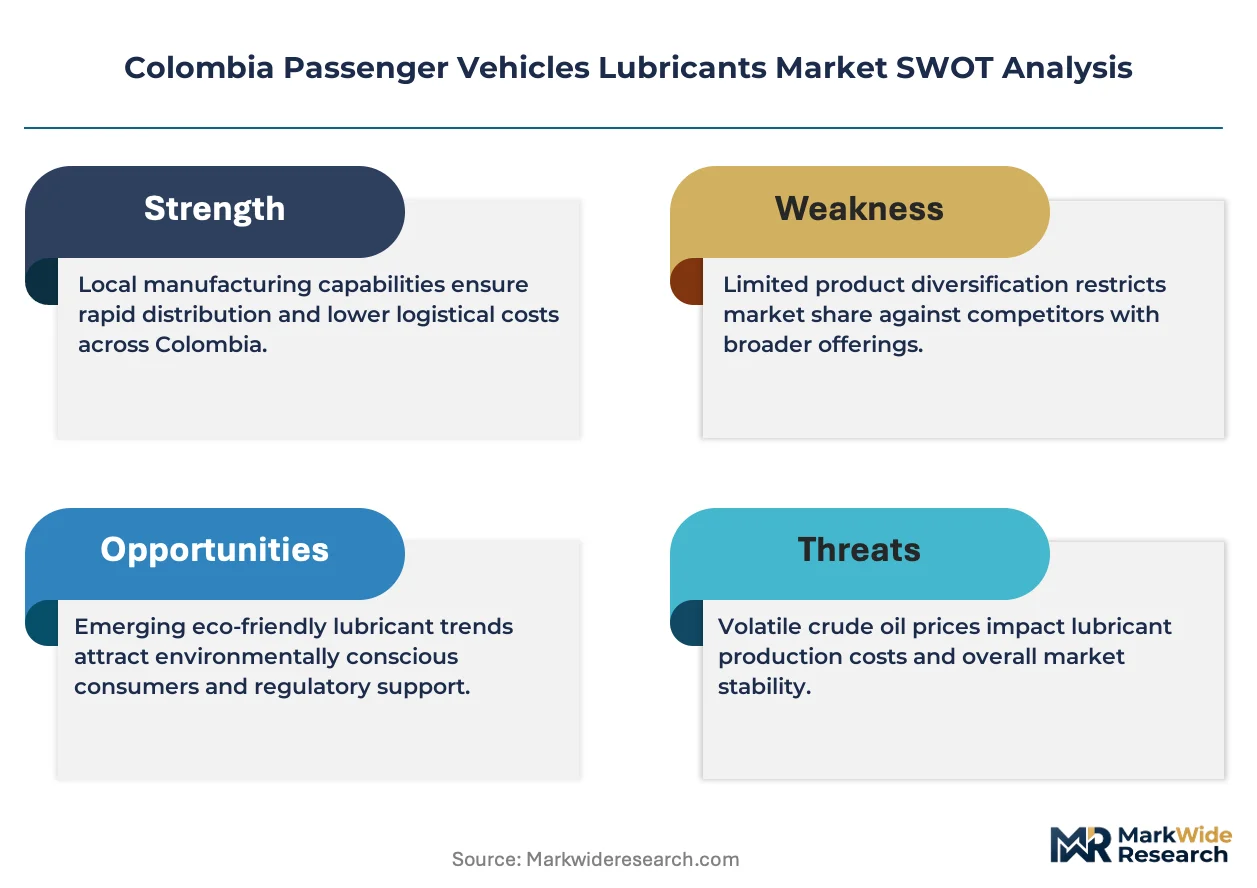
Biofuel blending mandates from Colombia's Ministry of Mines and Energy are forcing lubricant formulators to redesign additive packages for compatibility with ethanol-gasoline mixtures, reshaping R&D priorities across the value chain.
Growth Catalysts
- Fleet operator consolidation:Commercial vehicle pooling in Bogotá and Medellín generates concentrated bulk purchasing power that rewards suppliers offering extended-drain synthetic formulations.
- ANLA waste oil protocols:Mandatory recycling and disposal regulations create recurring aftermarket service relationships between workshops and licensed collectors, locking in lubricant brand loyalty.
- High-altitude engine stress:Andean topography above 2,500 meters elevates thermal loading on passenger vehicle engines, accelerating oil degradation and shortening replacement cycles.
Market Restraints
- Base oil import dependency:Colombia lacks domestic Group II/III refining capacity, exposing formulators to price volatility in US Gulf Coast feedstock markets.
- Workshop infrastructure gaps:Secondary cities beyond the Bogotá-Medellín-Cali triangle suffer from limited synthetic oil handling equipment and technician training.
- Biofuel compatibility testing costs:ANLA and Ministry of Mines and Energy certification requirements for ethanol-blend lubricant validation extend product development timelines.
Strategic Opportunities
- Pacific coastal logistics corridors:Buenaventura port expansion enables direct import of Asian base oil cargoes, bypassing traditional Atlantic routing through Cartagena.
- Hybrid powertrain penetration:Stop-start engine cycling in congested urban traffic creates demand for specialized low-viscosity formulations with enhanced anti-wear chemistry.
- Digital fleet management integration:Telematics-enabled oil condition monitoring allows predictive maintenance scheduling, opening subscription-based lubricant supply contracts.
Industry Challenges
- Additive chemist talent scarcity:Domestic universities produce limited graduates with formulation expertise for tropical biofuel-compatible lubricants.
- Workshop certification backlog:ANLA licensing delays for hazardous waste handling constrain expansion of authorized synthetic oil service points.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Colombia Passenger Vehicles Lubricants Market |
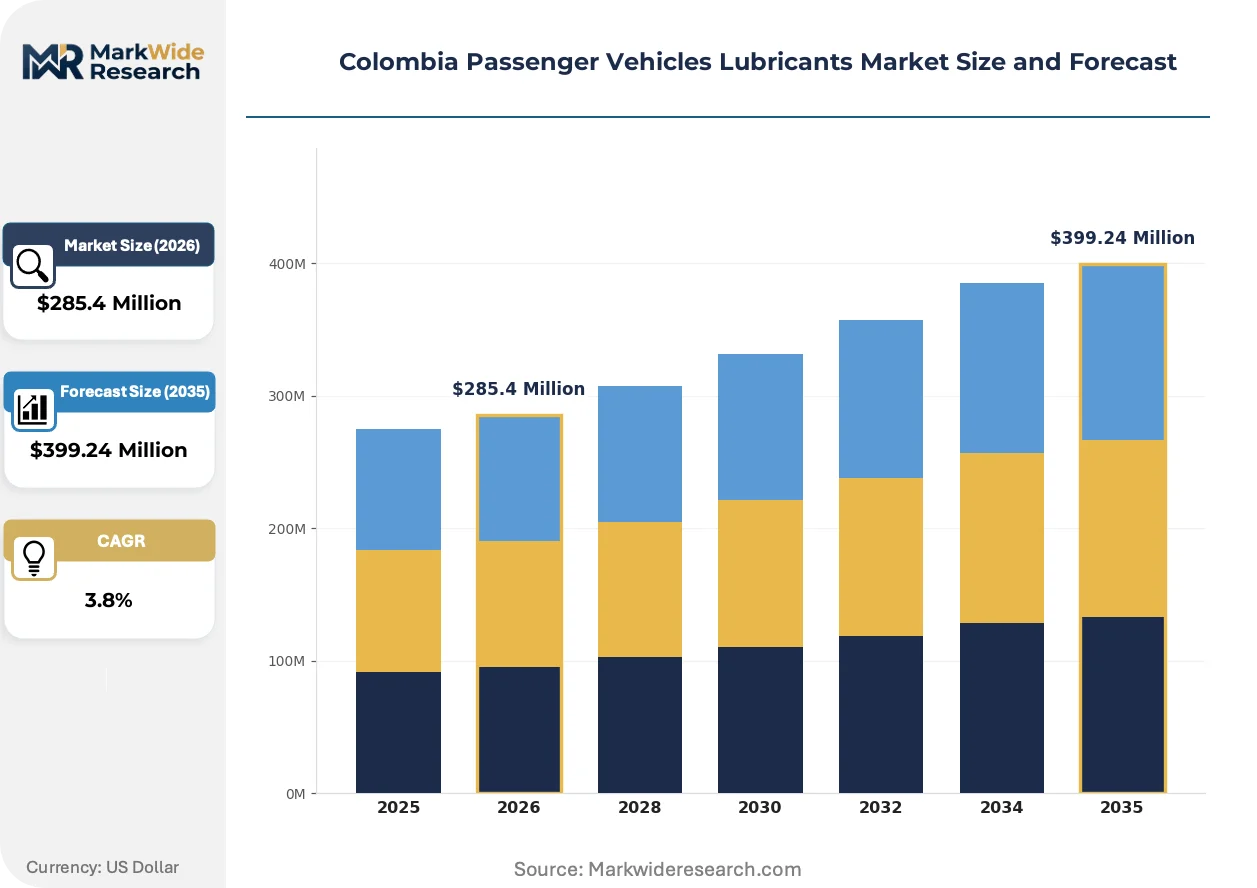
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $399.24 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Brake Fluid, Coolant End User: Individual Car Owners, Automotive Workshops, Fleet Operators, Car Dealerships Application: Light-Duty Vehicles, Heavy-Duty Vehicles, Off-Road Vehicles, Sports Cars Grade: Synthetic, Semi-Synthetic, Mineral, Others |
| Companies Covered | Royal Dutch Shell PLC, Chevron Corporation, BP Plc (Castrol), Petrobras, Terpel, Biomax, Petromil SA, TotalEnergies, Valvoline Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Colombia Passenger Vehicles Lubricants Market Strategic Shifts
Formulation chemistry and distribution architecture are evolving in parallel as Colombian lubricant suppliers respond to regulatory mandates and fleet operator efficiency demands.
Synthetic base stocks engineered for extended drain intervals are expanding into the commercial fleet segment as operators prioritize vehicle uptime over upfront fluid costs. Major logistics providers in Bogotá now specify 15,000-kilometer service intervals, compressing demand for conventional mineral grades. This technology shift is expanding into individual owner segments through workshop upselling programs.
Colombia's Ministry of Mines and Energy biofuel blending mandates require lubricant additives that neutralize acids formed during ethanol combustion. Formulators must reformulate detergent packages to prevent deposit accumulation in fuel injectors and valve trains. Passenger vehicles operating in tropical lowlands face the most severe compatibility stress, driving regional differentiation in product portfolios.
Fleet procurement departments now centralize lubricant purchasing through negotiated annual contracts rather than ad-hoc workshop transactions. This consolidation displaces traditional distributor networks in favor of direct manufacturer relationships with large operators. The shift is most visible among intercity bus cooperatives operating between Bogotá and Cali, where volume concentration enables price benchmarking against international reference grades.
Colombia Passenger Vehicles Lubricants Market Segmentation
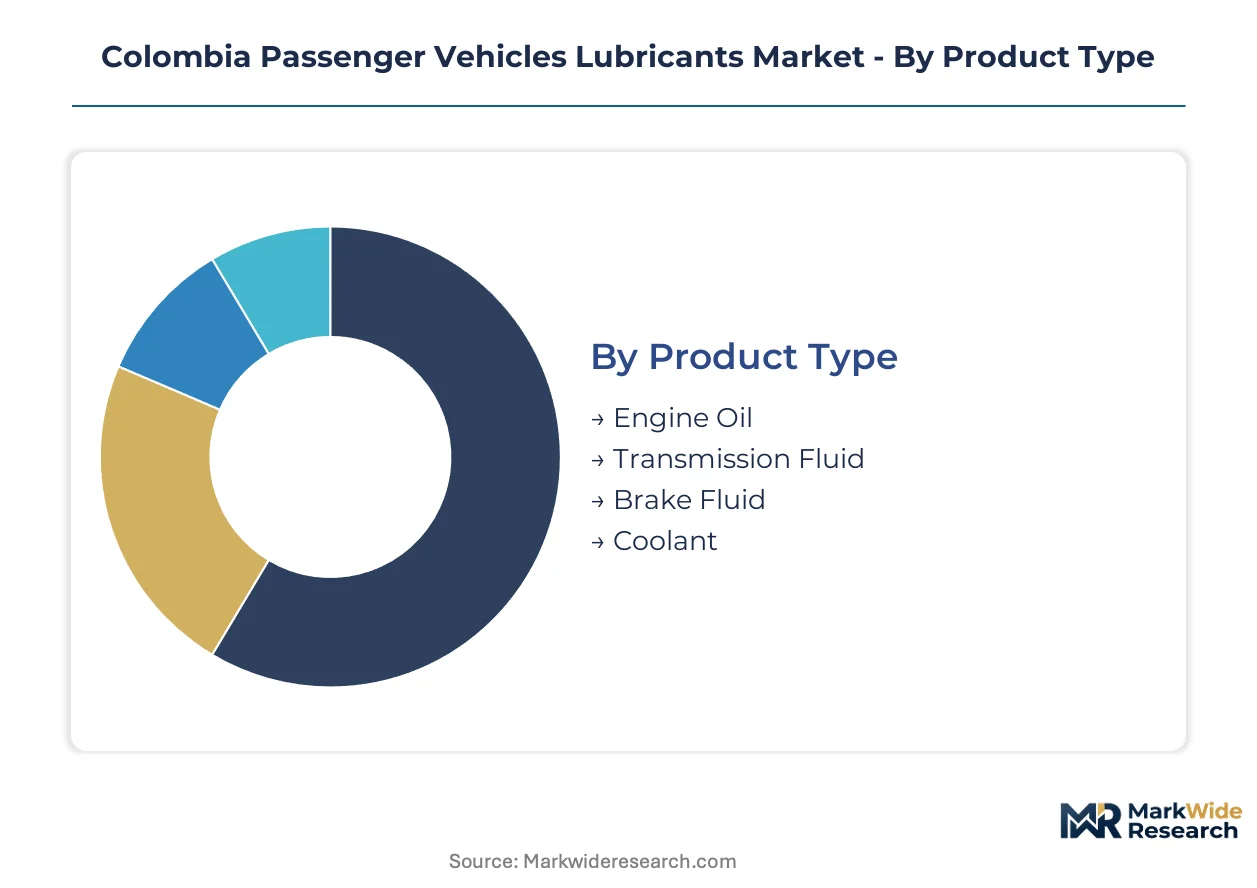
Colombia's passenger vehicle lubricants market fragments across four distinct axes that determine formulation chemistry, distribution channel selection, and pricing architecture. Understanding these segment boundaries reveals where procurement power concentrates and where technical specifications diverge.
Product Type:
Specification standards and replacement frequency create divergent margin profiles across fluid categories.
- Engine Oil:Formulated with viscosity modifiers and detergent packages meeting API SP and ILSAC GF-6 standards for tropical high-altitude operation. Bogotá's dense workshop corridor generates the highest per-capita consumption rates as stop-and-go traffic accelerates oil degradation cycles.
- Transmission Fluid:ATF and CVT formulations incorporating friction modifiers for Colombian road gradients. Demand concentrates among Medellín-based fleet operators maintaining automatic vehicle pools on Andean intercity routes.
- Brake Fluid:DOT 3 and DOT 4 hygroscopic formulations absorbing moisture in humid coastal climates. Cali workshops report elevated replacement rates due to tropical humidity penetration.
- Coolant:Ethylene glycol and propylene glycol blends with corrosion inhibitors for aluminum engine compatibility. Secondary cities show residual demand for universal coolants lacking OEM-specific certification.
Mature deployment sits with Engine Oil. Newer deployment is concentrated in Transmission Fluid.
End User:
Procurement scale and technical sophistication separate customer tiers across Colombia's service economy.
- Fleet Operators:Centralized purchasing departments negotiate annual volume contracts specifying extended-drain synthetic formulations. Intercity bus cooperatives operating Bogotá-Cali routes represent the most concentrated demand node.
- Automotive Workshops:Independent service centers in the Bogotá-Medellín-Cali triangle stock multi-grade portfolios to capture walk-in trade. ANLA waste oil handling certification distinguishes authorized synthetic oil service points from uncertified competitors.
- Individual Car Owners:Price-sensitive consumers in secondary cities favor mineral grades through informal neighborhood mechanics. Barranquilla and Cartagena show strongest preference for low-cost bulk purchasing.
- Car Dealerships:OEM-branded lubricant programs tied to warranty compliance requirements. Premium positioning in Andean urban centers supports synthetic-first recommendation protocols.
Volume leadership belongs to Fleet Operators. Margin expansion concentrates in Car Dealerships.
Application:
Vehicle duty cycles and operating environments dictate viscosity grade and additive package selection.
- Light-Duty Vehicles:0W-20 and 5W-30 low-viscosity formulations for fuel economy compliance in urban commuter fleets. Bogotá's congestion-charged central business district drives demand for stop-start compatible chemistries.
- Heavy-Duty Vehicles:High-TBN diesel engine oils neutralizing sulfuric acid from biofuel combustion. Ministry of Mines and Energy biodiesel mandates force reformulation of legacy HDMO products.
- Off-Road Vehicles:Extreme-pressure gear oils and hydraulic fluids for agricultural and mining operations in the Llanos Orientales. Contamination tolerance specifications exceed on-road requirements.
- Sports Cars:Racing-specification synthetics with enhanced thermal stability for high-performance engines. Limited volume concentrates in Medellín and Cali luxury vehicle service centers.
Unit economics favor Light-Duty Vehicles. Technical complexity peaks in Heavy-Duty Vehicles.
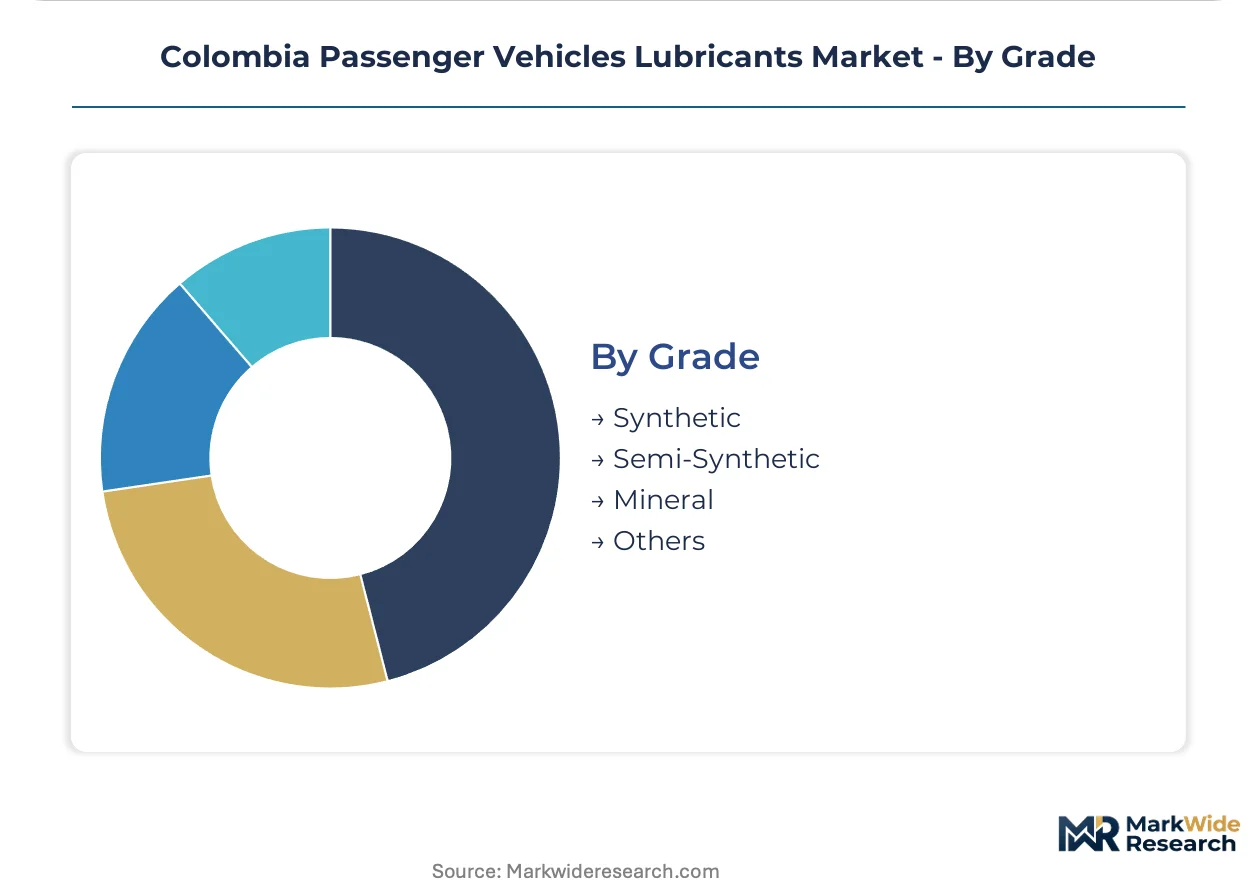
Grade:
Base stock quality and additive investment separate price-performance tiers in Colombian distribution.
- Synthetic:Group III and PAO base stocks enabling 15,000-kilometer drain intervals. Fleet operators in Bogotá specify synthetics to minimize vehicle downtime in high-utilization commercial pools.
- Semi-Synthetic:Blended formulations balancing extended service life against mineral-grade pricing. Workshop upselling programs in Medellín convert mineral users to mid-tier products.
- Mineral:Group I base stocks meeting API SL specifications for older vehicle populations. Residual demand persists in secondary cities with limited synthetic handling infrastructure.
- Others:Bio-based and re-refined lubricants emerging under ANLA circular economy protocols. Pilot programs in Cali test collection-to-re-refining supply chain viability.
Value capture concentrates in Synthetic. Volume retention depends on Mineral.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Colombia's Zona Franca del Pacifico free-trade zone accelerates lubricant import throughput at Buenaventura port, concentrating distribution infrastructure along the Pacific coastal corridor.
Bogotá Capital Region
Fleet operator consolidation and stop-and-go traffic degradation cycles drive synthetic lubricant consumption. Colombia's Ministry of Mines and Energy biofuel mandates require reformulated additive packages for ethanol compatibility. The Bogotá-Medellín automotive service corridor hosts the densest workshop concentration, with ANLA-certified waste oil handling facilities clustering in industrial zones.
Antioquia and Medellín Metro
Andean intercity bus cooperatives generate bulk procurement demand for extended-drain formulations. The Superintendency of Industry and Commerce monitors competition compliance across distributor networks. Medellín-based fleet maintenance pools specify high-altitude synthetic grades for vehicles operating above 2,500 meters.
Valle del Cauca and Cali
Tropical humidity elevates brake fluid replacement rates while hybrid vehicle penetration creates low-viscosity formulation demand. ANLA circular economy pilot programs test re-refined lubricant collection infrastructure. Cali's workshop upselling programs convert mineral-grade users to semi-synthetic products.
Caribbean Coast
Price-sensitive individual owners in Barranquilla and Cartagena favor mineral lubricants through informal service channels. Base oil import dependency exposes formulators to US Gulf Coast feedstock volatility. Coastal retail fuel station networks double as lubricant points of sale, extending distribution reach.
Eje Cafetero and Secondary Cities
Workshop infrastructure gaps constrain synthetic oil handling capacity outside major metros. Colombia's national environmental licensing authority certification backlogs delay authorized service point expansion. Pereira and Manizales show residual mineral-grade demand among older vehicle populations.
Colombia Passenger Vehicles Lubricants Market Competitive Environment
Top-tier vendors anchor coastal and capital-region distribution, while mid-tier regional blenders compete on price in secondary markets. The market structure reflects petroleum-major dominance alongside national fuel-retailer integration. Three archetypes define competitive positioning: integrated petroleum majors with captive supply chains, fuel-station-network operators leveraging retail density, and specialized lubricant formulators targeting fleet procurement departments. Capacity expansion through Pacific port infrastructure and strategic partnerships with telematics providers constitute the dominant competitive moves.
Within the integrated petroleum-major tier, Royal Dutch Shell PLC and Chevron Corporation exemplify supply-chain control strategies, while Terpel represents fuel-retailer-network leverage. These three entities anchor distinct distribution models: Shell dominates coastal corridors, Chevron sustains high-altitude positioning, and Terpel maximizes retail fuel-station penetration. BP Plc (Castrol) and TotalEnergies occupy positions emphasizing synthetic formulation specialization for commercial fleet segments.
| Leading Market Players |
|---|
| Royal Dutch Shell PLC |
| Chevron Corporation |
| BP Plc (Castrol) |
| Petrobras |
| Terpel |
| Biomax |
| Petromil SA |
| TotalEnergies |
| Valvoline Inc |
| Others |
Value Chain & Pricing Dynamics
US Gulf Coast Group II/III base oil spot indices cascade through Colombian formulator procurement budgets into three-tier pricing stratification across synthetic, semi-synthetic, and mineral grades. Fleet operators in Bogotá absorb premium markups for 15,000-kilometer extended-drain formulations while individual owners in secondary cities trade drain interval for per-liter economy.
Pricing Analysis
Short lead-time premiums reward suppliers holding Atlantic port inventory at Cartagena, while spot purchasers of Asian base oil cargoes through Buenaventura capture volume discounts at extended delivery horizons. Price differentiation hinges on ANLA waste oil handling certification tier and synthetic grade API performance classification. Cost compression in mineral-grade channels is intensifying because workshop upselling programs convert price-sensitive users to semi-synthetic mid-tier products. Fleet procurement departments exhibit lowest price sensitivity due to total-cost-of-ownership modeling, while individual car owners in Barranquilla and Cartagena drive hardest bargain hunting through informal neighborhood mechanics.
Supply Chain Analysis
Specialized lubricant additive chemist availability constrains domestic formulation capacity in Colombia, forcing reliance on imported additive packages from the United States, Singapore, and Belgium. Raw material flows draw from US Gulf Coast Group II/III base stocks, Southeast Asian viscosity modifier polymers, and European detergent additive systems. Single-source vulnerability concentrates in Colombian Atlantic port routing, where Cartagena throughput bottlenecks expose formulators to demurrage cost spikes. Distribution runs through Terpel's retail fuel station network, Shell's coastal logistics corridors, and Chevron's high-altitude Andean service infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Colombia's passenger vehicle lubricants market functions as a cost-of-compliance arena where ANLA waste oil handling certification and Ministry of Mines and Energy biofuel compatibility validation erect barrier-to-entry moats favoring incumbents with established regulatory affairs infrastructure.
For Market Incumbents: Anchor market position by deepening backward integration into Pacific port infrastructure at Buenaventura, bypassing Atlantic supply chokepoints while securing direct Asian base oil sourcing. Prioritize R&D investment in ethanol-gasoline additive chemistry to preempt regulatory mandate acceleration. Defensive consolidation through acquisition of ANLA-certified workshop networks in the Eje Cafetero closes synthetic service infrastructure gaps before regional blenders capture secondary city volume. For New Entrants and Emerging Players: Capture white-space opportunity in telematics-enabled predictive maintenance subscriptions, where fleet operators seek oil condition monitoring bundled with lubricant supply contracts. Target Pacific coastal logistics corridors for direct import arbitrage against established Atlantic-routed competitors. Penetrate through specialized hybrid powertrain low-viscosity formulations, where stop-start cycling chemistry demands outpace incumbent product portfolio refresh cycles. For Investors and Strategic Acquirers: The window for entry favors mid-scale regional blenders with ANLA certification infrastructure and established Bogotá-Medellín workshop relationships, positioned for petroleum-major consolidation plays. Long-term viability hinges on biofuel mandate trajectory and synthetic grade penetration rates across fleet operator segments. Monitor Ministry of Mines and Energy ethanol blending percentage increases as inflection signal for additive chemistry investment urgency.| Strategic Initiative | Industry Significance |
|---|---|
| Pacific Port Infrastructure Investment | Buenaventura expansion enables direct Asian base oil import, reducing Atlantic routing dependency. |
| Biofuel-Compatible Formulation R&D | Ethanol-gasoline additive chemistry investment aligns with Ministry of Mines and Energy mandate trajectory. |
| ANLA Certification Acquisition | Waste oil handling licensing accelerates authorized synthetic service point network expansion. |
| Telematics Integration Partnership | Oil condition monitoring subscriptions lock fleet operators into predictive maintenance supply contracts. |
| Workshop Network Consolidation | Eje Cafetero service infrastructure acquisition closes synthetic handling capacity gaps in secondary cities. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews involving lubricant formulator R&D directors, fleet procurement managers at Bogotá-based logistics cooperatives, ANLA compliance officers, automotive workshop owners in Medellín and Cali, and petroleum distributor channel heads. Secondary validation drew from Colombia Ministry of Mines and Energy biofuel mandate documentation, Superintendency of Industry and Commerce competition filings, ANLA environmental licensing databases, and US EIA base oil export statistics. Bottom-up volume modeling triangulated against top-down macroeconomic consumption projections.
Granularity-level modeling deployed product type, end user archetype, application duty cycle, and base stock grade tier as core segmentation dimensions across the projection horizon. CAGRs derived from trend extrapolation of fleet operator synthetic adoption curves, biofuel mandate implementation schedules, and workshop infrastructure expansion rates. Industry-specific forecast inputs incorporated Andean altitude engine stress degradation coefficients and tropical humidity brake fluid replacement frequency data.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Ministry of Mines and Energy ethanol blending percentage adjustments and Pacific port infrastructure completion timelines. Forecasts reflect documented assumptions regarding fleet operator consolidation velocity and ANLA certification processing efficiency. Material deviation in biofuel mandate acceleration or base oil import tariff structure warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
South America Automotive Engine Oils Market
Automotive Parts
Global Automotive Springs and Damper Market
Automotive Parts
Spain Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Exhaust System Market
Automotive Parts
Smart Adaptive Headlights Market
Automotive Parts
Global Automotive Ignition Market
Automotive Parts
Nigeria Automotive Lubricants Market
Automotive Parts
Two-Wheeler Lubricants Market
Automotive Parts
South America Automotive Lubricants Market
Automotive Parts
Cheetah Friction Reduction Technologies Market
Automotive Parts
Industrial Brakes Market
Automotive Parts
Two Wheeler Chain Sprocket Kit Market
Automotive Parts
China Automotive Parts Magnesium Die Casting Market
Automotive Parts
India Automotive Lubricants Market
Automotive Parts
Asia Pacific Automotive Parts Die Casting Market
Automotive Parts
Fluid Couplings Market