
 Automotive Carbon Canister Market | 2026-2036
Automotive Carbon Canister Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Carbon Canister Market Analysis
EPA Tier 3 compliance-grade activated carbon specifications is redrawing procurement priorities across the supply base. Tenneco leverages its exhaust aftertreatment heritage to anchor North American OEM contracts for integrated evaporative systems. MANN+HUMMEL sustains filter-to-canister bundling strategies that differentiate its position in European passenger car platforms. Robert Bosch GmbH competes through mechatronic integration, embedding pressure sensors directly into canister modules for real-time purge monitoring.
An automotive carbon canister is an emissions control device housing activated carbon media within sealed metal or polymer housings, designed to adsorb hydrocarbon vapors from the fuel tank and carburetor bowl vent lines during soak and diurnal temperature cycling; typical specifications include butane working capacity of 9-15 grams per 100 cubic centimeters and purge volumes calibrated to engine displacement. The device exists primarily to prevent volatile organic compound release into the atmosphere, satisfying evaporative emission test protocols. Activated carbon formulations dominate material selection due to established adsorption kinetics and regeneration durability, while hybrid canisters combining synthetic zeolite layers represent the fastest-growing product architecture as manufacturers seek lower bleed emissions under stringent diurnal test cycles. OEM direct supply channels control the dominant margin pool, though automotive aftermarket distributors are expanding inventory depth as vehicle parc age extends replacement intervals for degraded canister assemblies.
EPA, CARB, and China's MEE enforce the primary regulatory frameworks governing evaporative emission limits and test procedures for light-duty vehicles. EPA Tier 3 and CARB LEV III impose fleet-average hydrocarbon caps that effectively mandate enhanced carbon canister volume and purge efficiency, while MEE's China VI standards extend diurnal testing to 48-hour sequences that stress adsorbent capacity. Stakeholders must monitor the trajectory of PHEV and range-extended EV architectures, where fuel tank vapor management retains relevance even as powertrain electrification displaces conventional ICE platforms.
Market Dynamics
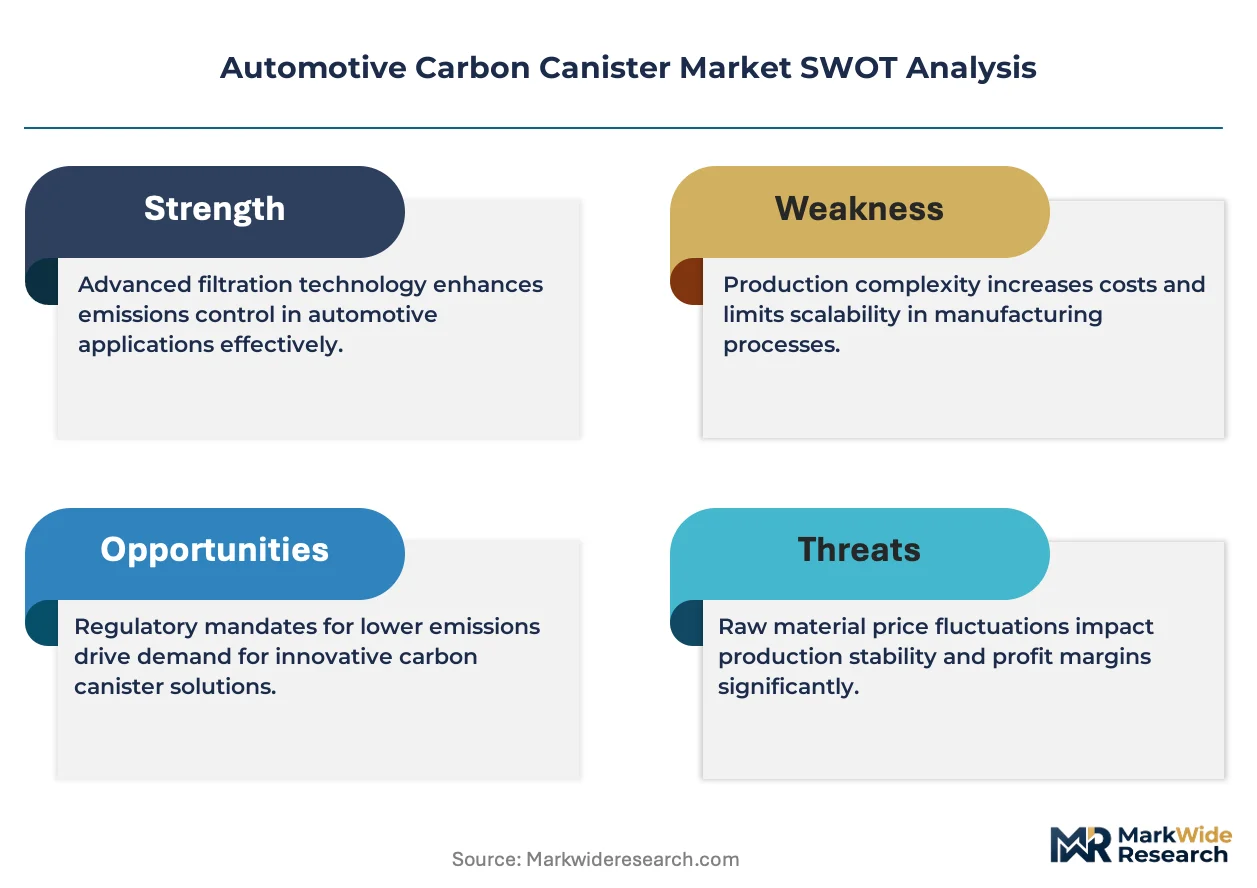
Regulatory stringency in evaporative emission control is compressing product development cycles while forcing material upgrades across the supply base. Activated carbon specifications are tightening faster than manufacturing capacity can adapt.
Growth Catalysts
- EPA Tier 3 fleet-average hydrocarbon caps:These mandates force OEMs to expand canister volume and purge efficiency in light-duty vehicle architectures, creating sustained demand for high-butane-working-capacity formulations.
- China VI 48-hour diurnal test sequences:MEE's extended testing protocols stress adsorbent capacity beyond legacy standards, accelerating adoption of hybrid zeolite-carbon canister architectures in domestic production.
- PHEV range-extended platforms:Fuel vapor management retains criticality even as electrification advances, with plug-in hybrid architectures integrating specialized canister systems for sealed fuel tank integrity.
Market Restraints
- Activated carbon feedstock volatility:Petroleum coke and coconut shell precursor costs fluctuate with energy commodity cycles, compressing margin stability for canister manufacturers.
- Automotive OEM supply concentration:Tier-1 purchasing power concentrates in Detroit, Stuttgart, and Shanghai corridors, squeezing pricing leverage for specialized adsorbent suppliers.
- Zeolite-carbon hybrid manufacturing complexity:Layered adsorbent architectures require precision coating equipment and humidity-controlled assembly environments that limit production scaling.
Strategic Opportunities
- India's delayed BS-VI Phase 2 enforcement:The country's national automotive regulator is tightening evaporative limits, opening procurement windows for suppliers with proven diurnal test performance.
- Aftermarket channel digitization:E-commerce platforms serving aging vehicle parc are expanding canister replacement inventory, bypassing traditional distributor networks for direct technician sales.
- Mechatronic purge monitoring convergence:Integration of pressure sensors and flow meters into canister modules creates serviceable intelligence layers that differentiate premium system offerings.
Industry Challenges
- Adsorption kinetics engineering specialization:The talent pool for optimizing butane working capacity under dynamic temperature cycling remains shallow relative to demand from electrified powertrain programs.
- Dual-certification timeline compression:Simultaneous EPA and CARB validation protocols for new canister architectures extend development schedules without guaranteeing harmonized approval outcomes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Carbon Canister Market |
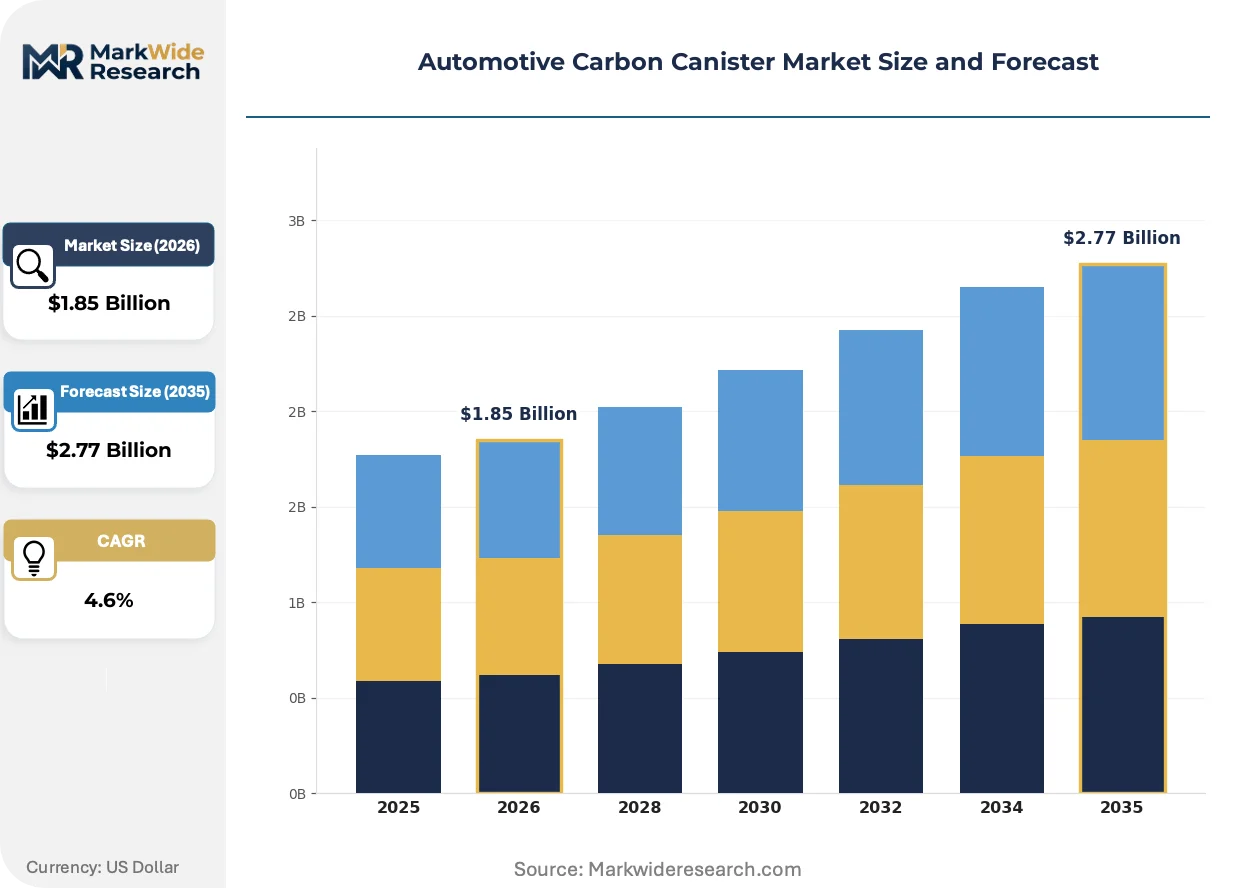
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.77 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Activated Carbon, Metal Canisters, Plastic Canisters, Hybrid Canisters Application: Fuel Evaporation Control, Emission Reduction, Air Filtration, Environmental Protection End User: OEMs, Automotive Aftermarket, Vehicle Assemblers, Component Manufacturers Distribution Channel: Direct Sales, Online Retail, Wholesalers, Distributors |
| Companies Covered | Tenneco, MANN+HUMMEL, Robert Bosch GmbH, Aptiv PLC, Sogefi Group, Stant Corporation, Delphi Technologies, Aisan Industry Co., Ltd., Mahle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Carbon Canister Market Emerging Trajectories
Material science advances and embedded intelligence are redefining canister performance benchmarks. The competitive frontier now sits at the intersection of adsorbent chemistry and real-time system monitoring.
Hybrid synthetic zeolite layers bonded to activated carbon substrates are achieving sub-20 mg diurnal bleed emissions under 48-hour test protocols. European passenger car OEMs are specifying these architectures for 2027 platform launches. The technology is miniaturizing overall canister volume requirements while maintaining regulatory compliance margins.
China's MEE has extended evaporative emission testing to 48-hour sequences under China VI standards, exceeding EPA Tier 3 duration requirements. This regulatory divergence forces multinational suppliers to maintain parallel product variants for export and domestic Chinese markets. Domestic Chinese OEMs are responding with localized hybrid canister sourcing to avoid import certification delays.
Fleet procurement departments are consolidating evaporative system contracts under integrated emission control packages rather than discrete component sourcing. Tier-1 suppliers with exhaust aftertreatment heritage are capturing these bundled awards, displacing standalone canister specialists from direct OEM relationships. This concentration is most visible in North American light-truck platforms where powertrain and emission system integration carries premium value.
Automotive Carbon Canister Market Segmentation
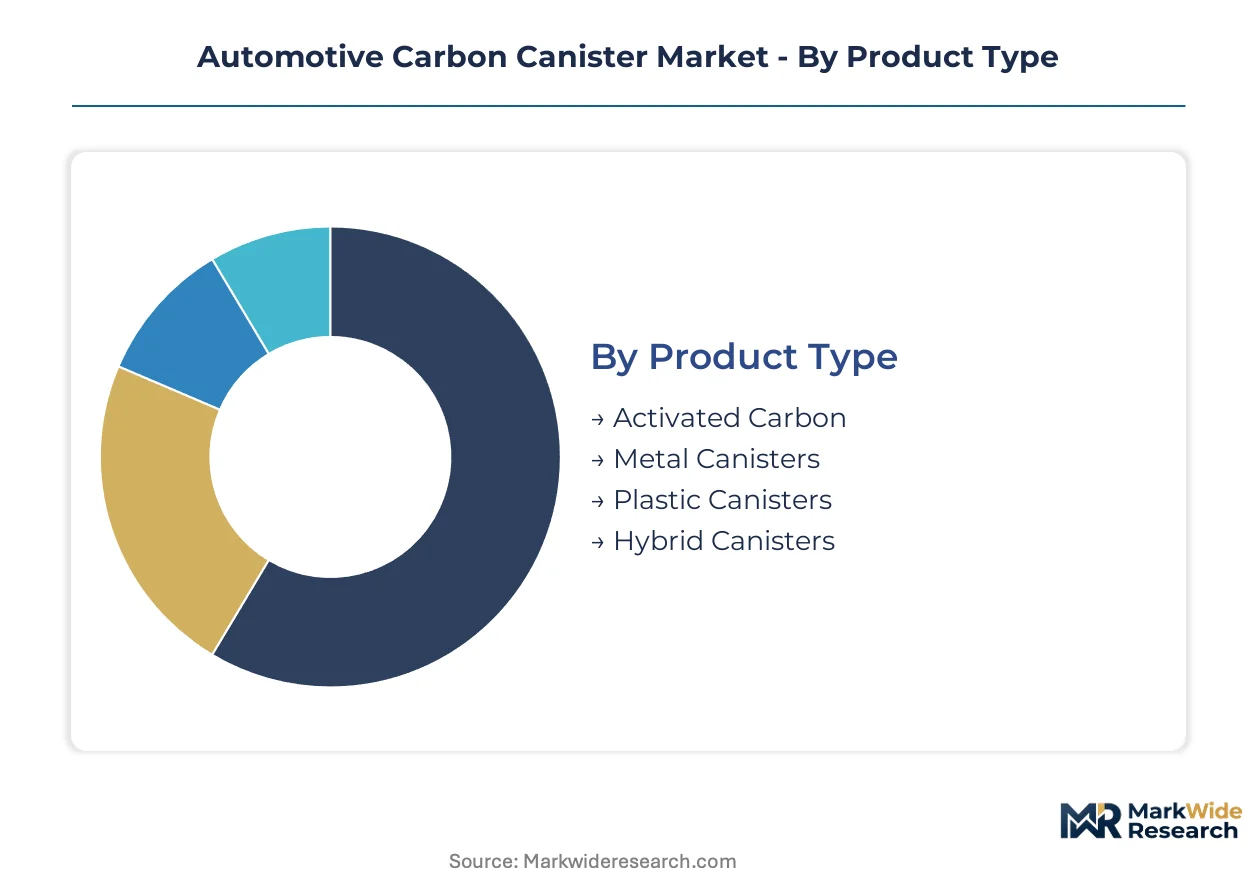
Carbon canister procurement channels diverge sharply by segment, with OEM direct supply capturing premium volumes while aftermarket distributors serve replacement demand. Understanding these flow patterns exposes margin concentration and competitive access points.
Product Type:
Channel-mix varies dramatically by housing material and adsorbent formulation, with integrated system suppliers favoring bundled metal-hybrid architectures and aftermarket channels stocking standardized activated carbon units.
- Activated Carbon:Petroleum coke and coconut shell formulations deliver 9-15 grams per 100cc butane working capacity. Demand concentrates in legacy passenger car platforms across the United States where EPA Tier 3 compliance requires proven adsorption kinetics, though feedstock cost volatility compresses manufacturer margins.
- Hybrid Canisters:Synthetic zeolite layers bonded to activated carbon substrates achieve sub-20 mg diurnal bleed emissions under extended test protocols. Expansion concentrates in China's domestic production as MEE's 48-hour China VI sequences stress conventional carbon capacity beyond limits.
- Metal Canisters:Sealed aluminum or steel housings withstand high-pressure purge cycles in commercial vehicle applications.
- Plastic Canisters:Polymer housings reduce weight in cost-sensitive compact passenger car segments.
Activated Carbon dominates installed base. Hybrid Canisters is where expansion concentrates.
Application:
Cost-tier stratification separates compliance-mandated fuel vapor control from premium environmental protection positioning.
- Fuel Evaporation Control:Primary function adsorbing hydrocarbon vapors from fuel tank vent lines during soak and diurnal temperature cycling. Demand concentrates in range-extended PHEV architectures where sealed tank integrity retains criticality despite powertrain electrification.
- Emission Reduction:Fleet-average hydrocarbon cap compliance drives specification tightening. European passenger car OEMs are specifying enhanced purge efficiency for 2027 platform launches as ECHA frameworks extend evaporative monitoring requirements.
- Air Filtration:Secondary cabin air quality applications in premium vehicle segments.
- Environmental Protection:Voluntary certification programs for ultra-low bleed emission positioning.
Fuel Evaporation Control commands volume share. Emission Reduction carries steepest expansion trajectory.
End User:
Customer-type concentration determines pricing leverage, with consolidated OEM purchasing power squeezing standalone component suppliers.
- OEMs:Direct supply relationships with Detroit, Stuttgart, and Shanghai corridor manufacturers control dominant margin pools. Tenneco and MANN+HUMMEL anchor these channels through integrated evaporative system bundling.
- Automotive Aftermarket:Distributor and e-commerce channels serve aging vehicle parc as replacement intervals extend for degraded canister assemblies. Digitization enables direct technician sales bypassing traditional wholesale networks.
- Vehicle Assemblers:Contract manufacturing relationships for regional production facilities.
- Component Manufacturers:Tier-2 supply to integrated system suppliers.
OEMs dominate revenue concentration. Automotive Aftermarket offers channel diversification.
Distribution Channel:
Supply concentration shapes access economics, with direct sales capturing specification-grade volumes and online retail fragmenting replacement parts procurement.
- Direct Sales:OEM and Tier-1 supplier relationships for platform-integrated canister systems. Robert Bosch GmbH embeds pressure sensors directly into module assemblies for real-time purge monitoring, differentiating premium direct supply offerings.
- Distributors:Regional wholesale networks inventory standardized replacement units for independent repair facilities.
- Online Retail:E-commerce platforms expand technician-direct procurement, compressing traditional distributor markups.
- Wholesalers:Bulk procurement intermediaries serving smaller aftermarket operators.
Direct Sales anchors value capture. Online Retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in China demonstrate the lowest price elasticity as domestic OEMs prioritize compliance-grade hybrid canister architectures, while aftermarket channels in mature Western markets remain highly sensitive to replacement cost differentials.
United States
Detroit's light-truck platforms sustain premium procurement volumes for integrated evaporative systems. EPA Tier 3 fleet-average hydrocarbon caps force specification upgrades across the production base. The Michigan-Ohio corridor anchors North American supply relationships as Tenneco leverages exhaust aftertreatment heritage for bundled emission control awards.
Germany
Stuttgart-based OEMs specify hybrid zeolite-carbon architectures for 2027 passenger car launches. ECHA frameworks extend evaporative monitoring requirements beyond baseline compliance. MANN+HUMMEL sustains filter-to-canister bundling strategies that differentiate its position in European platform sourcing.
China
Domestic EV-hybrid platforms integrate carbon canisters into range-extended architectures despite powertrain electrification. MEE's 48-hour China VI diurnal test sequences stress conventional carbon capacity beyond legacy limits. The Yangtze River Delta concentrates localized hybrid canister sourcing as multinational suppliers maintain parallel product variants.
Japan
Keiretsu-affiliated OEMs emphasize mechatronic integration for real-time purge monitoring capabilities. METI-aligned industrial policy supports precision manufacturing equipment for humidity-controlled assembly environments. The Nagoya-Toyota corridor specializes in pressure sensor embedding for premium system differentiation.
India
Delayed BS-VI Phase 2 enforcement opens procurement windows for suppliers with proven diurnal test performance. The country's national automotive regulator tightens evaporative limits on compressed development timelines. Tamil Nadu and Maharashtra absorb initial compliance-grade canister volumes as domestic production scales.
Automotive Carbon Canister Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with mechatronic integration specialists commanding premium positioning against scale-driven metal-forming fabricators. The supply base concentrates around exhaust aftertreatment heritage players and filtration system bundlers, leaving standalone canister specialists squeezed between integrated Tier-1 purchasing power. Three archetypes dominate: integrated emission system suppliers, filter-to-canister bundlers, and mechatronic module specialists. Competitive dynamics center on strategic partnerships for hybrid adsorbent manufacturing capacity and geographic expansion into delayed regulatory enforcement markets.
Within the integrated system supplier tier, Tenneco anchors North American OEM relationships through evaporative system bundling. MANN+HUMMEL occupies a parallel position in European sourcing corridors. Robert Bosch GmbH exemplifies the mechatronic convergence archetype, embedding sensor intelligence directly into module assemblies.
| Leading Market Players |
|---|
| Tenneco |
| MANN+HUMMEL |
| Robert Bosch GmbH |
| Aptiv PLC |
| Sogefi Group |
| Stant Corporation |
| Delphi Technologies |
| Aisan Industry Co., Ltd. |
| Mahle |
| Others |
Supply Flow & Price Mechanics
Ninety-day activated carbon inventory cycles in Detroit corridor procurement expose the tight coupling between feedstock availability and Tier-1 pricing leverage. This lead-time compression concentrates margin pressure on standalone canister specialists while integrated emission system suppliers absorb volatility through bundled contract structures.
Pricing Analysis
Aftermarket replacement parts revenue sustains lifetime value for distributors serving aging vehicle parc. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and purge efficiency specifications. Cost compression in standard-grade activated carbon units is intensifying because petroleum coke feedstock volatility transfers directly to contract renegotiations. Automotive OEMs demonstrate lowest price sensitivity due to compliance mandate rigidity, while independent repair facilities remain highly elastic to replacement cost differentials.
Supply Chain Analysis
China and Germany anchor activated carbon precursor processing and precision canister assembly respectively. The supply chain draws from coconut shell feedstocks in Southeast Asia and petroleum coke derivatives in North America, with synthetic zeolite layers sourced from specialized chemical producers. Single-source vulnerability concentrates in humidity-controlled coating equipment for hybrid canister manufacturing. Distribution runs through OEM direct channels for platform-integrated systems and e-commerce platforms for aftermarket replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in regulatory-driven cyclical recovery as EPA Tier 3 and China VI enforcement waves force specification upgrades across successive platform generations.
For Market Incumbents: Compound defensive positioning through backward integration into activated carbon precursor supply and captive humidity-controlled assembly capacity. Secure dual-certification EPA and CARB validation pipelines ahead of 2027 European platform launches to preempt emerging hybrid canister specialists from Tier-1 procurement windows. For New Entrants and Emerging Players: CARB LEV III certification fast-track programs in California open procurement access for proven diurnal test performers. Target India's BS-VI Phase 2 enforcement window where compressed development timelines disadvantage established suppliers with rigid certification pipelines. Lead with mechatronic purge monitoring modules as differentiated entry wedge against legacy metal-forming fabricators. For Investors and Strategic Acquirers: Long-term, this sits as a compliance-mandated replacement cycle play because evaporative emission standards tighten irreversibly even under powertrain electrification. Acquire filtration system bundlers with established OEM relationships and latent hybrid adsorbent engineering capability. Monitor PHEV platform launch cadence as inflection signal for sealed fuel tank canister demand durability.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Adsorbent Capacity Expansion | China VI 48-hour diurnal compliance forces zeolite-carbon layer investments in Yangtze River Delta manufacturing clusters. |
| Mechatronic Module Integration | Pressure sensor embedding into canister assemblies differentiates premium supply relationships with Stuttgart-based OEMs. |
| Regulatory Certification Fast-Track | Parallel EPA and CARB validation pipelines compress development schedules for 2027 European platform sourcing decisions. |
| Aftermarket Channel Digitization | E-commerce technician-direct procurement bypasses traditional distributor markups in aging United States vehicle parc replacement cycles. |
| Backward Integration into Feedstocks | Captive coconut shell and petroleum coke precursor supply stabilizes margin volatility against energy commodity cycles. |
Methodological Framework
A spread of perspectives from Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and activated carbon feedstock specialists converged on the working assumptions governing canister demand trajectories. Primary field engagement with dealership service operations and evaporative system validation laboratories combined with secondary triangulation against EPA certification databases, vehicle production registries, and customs trade flow records. Bottom-up unit demand modeling and top-down emission regulation compliance requirements were cross-validated to establish market sizing boundaries.
Segmentation dimensions modeled span vehicle propulsion architecture, adsorbent formulation type, housing material specification, and regional regulatory framework cluster across the analysis window. CAGRs were derived from polynomial trend fitting to historical platform launch cadences and projected powertrain mix shifts. Industry-specific forecast inputs include butane working capacity evolution curves and diurnal test protocol duration extensions.
Decision-makers should treat outputs as directional under assumptions of sustained EPA Tier 3 and China VI enforcement stringency; material deviation in regulatory timeline compression or PHEV platform cancellation rates would warrant model refresh. Recalibration cycles align with material shifts in evaporative emission standard adoption trajectories and hybrid powertrain penetration rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Two Wheeler Chain Sprocket Kit Market
Automotive Parts
Automotive Power Window Regulator Market
Automotive Parts
Engine Oil Pan Market
Automotive Parts
Automotive Propeller Shaft Couplings Market
Automotive Parts
Wind Shield Washer Market
Automotive Parts
France Automotive Pneumatic Actuators Market
Automotive Parts
Powerglide Shifter Market
Automotive Parts
Autonomous Forklift Market
Automotive Parts
United States Ceramic Ball Bearings Market
Automotive Parts
Automotive Parking Heater Market
Automotive Parts
France Passenger Vehicles Lubricants Market
Automotive Parts
Power Liftgate Market
Automotive Parts
Automotive Rear Spoiler Market
Automotive Parts
Automotive Pinion Gear Market
Automotive Parts
Automotive Fuel Rail Market
Automotive Parts
Global Automotive Leaf Spring Market