
 Industrial Brakes Market | 2026-2036
Industrial Brakes Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Brakes Market Intelligence
Skilled brake system technicians is rotating toward electromagnetic and smart braking architectures as factories automate material handling. Eaton Corporation plc leverages its hydraulic expertise to anchor heavy-lift applications across North American ports. Nabtesco Corporation dominates precision servo brake supply for automated crane systems in Asian manufacturing hubs. SIBRE Siegerland Bremsen GmbH specializes in custom drum brake solutions for steel mill conveyor operations.
Industrial brakes are friction-based kinetic energy dissipation devices engineered with sintered metallic or organic composite linings, rated for torque capacities spanning 50 Nm to over 500 kNm, and designed to arrest or hold rotating machinery under emergency and service conditions. Their primary purpose is protecting personnel, preventing load drops, and enabling controlled deceleration in continuous-process environments. Disk brake configurations lead the product type landscape due to superior heat rejection and maintenance access, while electromagnetic technology is gaining fastest as plant electrification eliminates pneumatic infrastructure. Crane applications within the application category command the highest torque specification requirements and replacement part value per unit.
OSHA lockout/tagout standards and EU Machinery Directive 2006/42/EC enforcement through CE marking authorities are mandating redundant braking systems and documented safety integrity levels for new installations. EPA friction material regulations in the United States and REACH chemical restrictions administered by ECHA are reshaping lining composition roadmaps toward copper-free and low-cobalt formulations. Stakeholders must monitor evolving regional certification timelines and raw material substitution curves to align procurement with compliance deadlines.
Market Dynamics
Electromagnetic brake architectures are displacing pneumatic systems across automated material handling installations, compressing maintenance intervals and eliminating compressed air infrastructure while forcing incumbent suppliers to retool their manufacturing footprints.
Growth Catalysts
- EU Machinery Directive 2006/42/EC:CE marking enforcement mandates redundant braking systems for new crane installations, compelling facility upgrades across German and French port operations.
- Sintered metallic friction materials:Copper-free formulations meeting EPA friction material regulations are opening procurement pathways for US steel mill conveyor operators.
- China:Port modernization programs in Shanghai and Ningbo-Zhoushan are accelerating demand for high-torque disk brake configurations in container handling equipment.
Market Restraints
- Cobalt supply concentration:DRC and Indonesian cobalt refining bottlenecks are destabilizing lining composition roadmaps for low-cobalt formulations.
- REACH chemical restrictions:ECHA substance authorization timelines are creating 18-24 month compliance gaps for organic composite brake pad suppliers.
- Hydraulic brake substitution:Electromagnetic actuation is eroding addressable volume for fluid-power brake architectures in sub-100 kNm torque bands.
Strategic Opportunities
- India:PLI scheme incentives for domestic manufacturing are lowering landed costs for brake system OEMs serving Mumbai and Mundra port expansions.
- Smart braking convergence:IoT sensor integration with predictive maintenance platforms is creating premium pricing tiers for automated warehouse crane operators.
- Direct procurement channels:E-commerce platforms for replacement friction linings are disintermediating traditional distributor networks in Southeast Asian maintenance markets.
Industry Challenges
- Electromagnetic system integration:Legacy pneumatic infrastructure retrofitting requires specialized technicians scarce in US Midwest manufacturing corridors.
- SIL certification timelines:TÜV Rheinland safety integrity level documentation for new brake architectures extends product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Brakes Market |
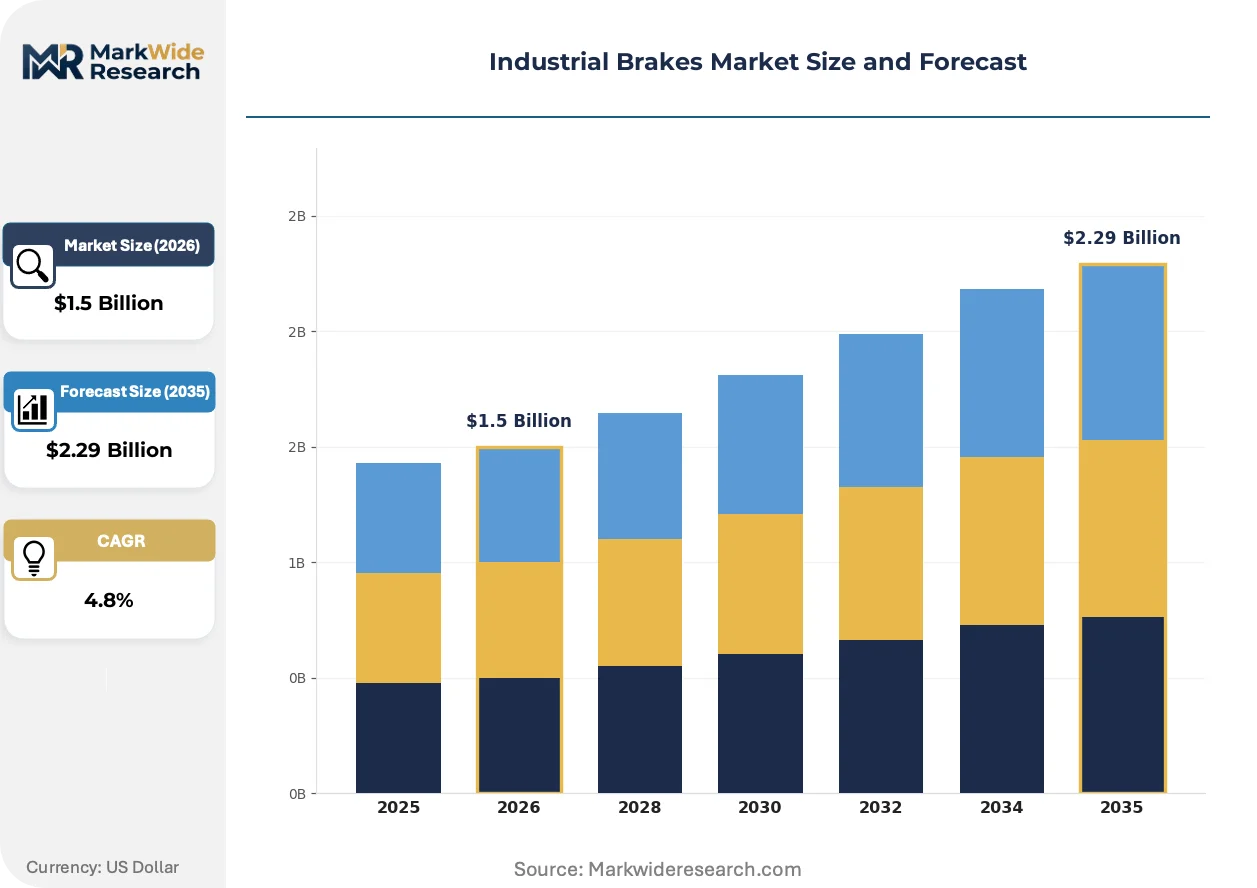
| Market Size in 2026 | $1.5 Billion |
| Market Size in 2035 | $2.29 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disk Brakes, Drum Brakes, Hydraulic Brakes, Pneumatic Brakes Application: Manufacturing Equipment, Forklifts, Conveyor Systems, Cranes Technology: Electromagnetic, Mechanical, Hydraulic, Pneumatic End User: Construction, Mining, Manufacturing, Transportation |
| Companies Covered | Dellner Bubenzer, SIBRE Siegerland Bremsen GmbH, Eaton Corporation plc, Nabtesco Corporation, Carlisle Brake & Friction, Parker Hannifin Corporation, Hilliard Corporation, TMD Friction Holding GmbH, Altra Industrial Motion Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Brakes Market Strategic Shifts & Innovations
Digital torque monitoring and copper-free material science are converging to redefine brake system value propositions, shifting competitive advantage toward predictive maintenance capabilities and regulatory pre-certification.
Permanent magnet hysteresis brake technology is fragmenting the traditional electromagnetic actuator landscape by eliminating coil heating losses and enabling precise torque modulation across automated guided vehicle fleets. Automotive battery plant operators in Michigan and South Carolina are specifying these configurations for cleanroom material handling. The technology is fragmenting supplier hierarchies by rewarding magnetic material specialists over legacy friction engineering houses.
REACH Annex XVII restrictions on cobalt compounds are forcing reformulation of sintered metallic linings ahead of 2026 authorization deadlines. Brake pad manufacturers are accelerating ceramic-fiber composite development programs to maintain CE marking eligibility. German steel mill operators face the steepest compliance cliffs given their reliance on high-torque drum configurations with legacy cobalt-bearing formulations.
Aftermarket service unbundling is compressing replacement part procurement cycles as crane maintenance teams bypass OEM service contracts for direct friction lining sourcing. Independent distributors in Texas and Louisiana port corridors are capturing volume through same-day delivery commitments. This pattern is most pronounced in North American bulk material handling where downtime costs exceed premium OEM part markups by factors of four to six.
Industrial Brakes Market Segmentation
Brake system procurement patterns diverge sharply across torque bands and actuation methods. Margin capture concentrates in configurations serving automated material handling and heavy-lift port infrastructure.
Product Type:
Disk brake architectures command premium positioning through superior thermal management and maintenance accessibility.
- Disk Brakes:These friction devices employ ventilated rotors and sintered metallic pads rated for continuous heat rejection above 300°C. Demand concentrates in Shanghai and Ningbo-Zhoushan port modernization programs where container crane duty cycles exceed 20 stops per hour. EPA copper-free friction regulations are reshaping procurement specifications for US steel mill operators.
- Drum Brakes:Enclosed shoe-and-drum configurations excel in contaminated environments with torque ratings spanning 50 kNm to 500 kNm. German steel mill operators face steep REACH compliance cliffs as cobalt-bearing formulations phase out, forcing accelerated ceramic-fiber composite adoption. Maintenance access limitations compress replacement intervals versus disk alternatives.
- Hydraulic Brakes:Fluid-power actuation dominates sub-100 kNm torque bands in legacy North American manufacturing corridors.
- Pneumatic Brakes:Compressed air infrastructure dependency limits new installations to brownfield facilities with existing compressor networks.
Disk brakes hold installed capacity. Electromagnetic configurations are rotating up the share rankings.
Application:
Crane systems generate the highest torque specification requirements and aftermarket part value per unit installed.
- Cranes:Overhead and portal crane installations demand redundant braking systems under EU Machinery Directive 2006/42/EC enforcement. Port operators in Hamburg and Rotterdam specify dual-circuit disk configurations with SIL 2 safety integrity documentation. Replacement friction lining procurement cycles compress as maintenance teams bypass OEM service contracts.
- Conveyor Systems:Continuous-process bulk material handling requires holding brakes rated for static torque multiples of 150-200% full load. US Midwest grain elevator operators and Australian iron ore export terminals specify spring-applied, hydraulically-released drum configurations for emergency stopping duty.
- Manufacturing Equipment:Automated press lines and metal forming installations favor compact electromagnetic caliper designs.
- Forklifts:Warehouse material handling equipment specifies wet multi-disc brakes for contamination resistance in battery plant cleanrooms.
Crane applications dominate torque specifications. Conveyor systems are climbing the fastest in replacement part revenue intensity.
Technology:
Electromagnetic architectures are displacing pneumatic infrastructure across automated installations.
- Electromagnetic:Coil-actuated friction engagement eliminates compressed air infrastructure while enabling precise torque modulation. Michigan and South Carolina automotive battery plant operators specify permanent magnet hysteresis variants for cleanroom AGV fleets. TÜV Rheinland SIL certification timelines extend product launch cycles.
- Mechanical:Spring-applied, manually-released configurations persist in manual hoist and winch applications where power failure protection is paramount.
- Hydraulic:Fluid-power actuation retains position in heavy-lift mobile cranes above 100 kNm torque requirements.
- Pneumatic:Compressed air systems face erosion in sub-100 kNm bands as plant electrification accelerates.
Mechanical systems anchor legacy installed base. Electromagnetic technology is gaining share fastest in new specification activity.
End User:
Mining operations generate the most severe duty cycles and shortest replacement intervals.
- Mining:Open-pit extraction equipment operates in abrasive environments with brake temperatures cycling between ambient and 400°C. Australian iron ore and Chilean copper belt operators specify sealed drum configurations with ceramic-composite linings. Downtime costs exceeding premium OEM part markups by four to six factors drive independent distributor capture in maintenance corridors.
- Construction:Mobile crane and piling rig applications demand weather-resistant enclosures for outdoor duty.
- Manufacturing:Automated production lines specify electromagnetic brakes for precise positioning and energy recovery integration.
- Transportation:Port terminal tractors and railcar positioning equipment require rapid-cycle friction engagement.
Mining commands replacement part velocity. Manufacturing is expanding most quickly in smart braking sensor integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes industrial brakes at unmatched scale for port modernization, while Germany and the United States prioritize regulatory-driven safety upgrades over volume expansion. This consumption-mix differential shapes supplier strategies across geographies.
China
Shanghai and Ningbo-Zhoushan port expansions drive demand for high-torque disk brake configurations in container handling equipment. MIIT industrial equipment standards mandate redundant braking architectures for new crane installations. Yangtze River Delta manufacturing clusters absorb the dominant share of electromagnetic brake specifications for automated guided vehicle fleets.
Germany
Hamburg and Rotterdam port operators specify dual-circuit disk configurations with SIL 2 safety integrity documentation under EU Machinery Directive enforcement. REACH Annex XVII cobalt restrictions are forcing accelerated ceramic-fiber composite adoption by 2026. Ruhr Valley steel mills face the steepest compliance cliffs given legacy high-torque drum configurations.
United States
Michigan and South Carolina automotive battery plant operators specify permanent magnet hysteresis brakes for cleanroom material handling environments. EPA friction material regulations are reshaping procurement specifications toward copper-free formulations for steel mill conveyor operators. Texas and Louisiana port corridors see independent distributors capturing aftermarket volume through same-day delivery commitments.
India
Mumbai and Mundra port expansions accelerate demand for brake system OEMs serving heavy-lift infrastructure. PLI scheme incentives for domestic manufacturing lower landed costs for electromagnetic brake suppliers. Gujarat manufacturing clusters absorb expanding share of replacement friction lining procurement as maintenance teams bypass OEM service contracts.
Japan
Automated crane systems in Asian manufacturing hubs drive precision servo brake specifications. METI industrial safety standards enforce documented safety integrity levels for new material handling installations. Osaka-based manufacturing clusters concentrate demand for compact electromagnetic caliper designs in automated press lines.
Industrial Brakes Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with hydraulic expertise anchoring heavy-lift applications and electromagnetic capabilities fragmenting traditional supplier hierarchies. The market structure rewards magnetic material specialists over legacy friction engineering houses as plant electrification accelerates. Three archetypes dominate: diversified industrial conglomerates with fluid-power heritage, precision motion control specialists, and regional brake system fabricators with port-specific service networks. Competitive moves center on backward integration into friction material supply and geographic expansion through distributor acquisition in Southeast Asian maintenance corridors.
Within the diversified industrial tier, Eaton Corporation plc and Parker Hannifin Corporation represent integrated fluid-power suppliers with established positions in North American heavy-lift infrastructure. Nabtesco Corporation exemplifies precision motion control specialization for automated crane systems. SIBRE Siegerland Bremsen GmbH anchors the regional specialist archetype with German-engineered custom drum solutions. Dellner Bubenzer and Altra Industrial Motion Corp. occupy positions spanning multiple actuation technologies across European and North American port modernization programs.
| Leading Market Players |
|---|
| Dellner Bubenzer |
| SIBRE Siegerland Bremsen GmbH |
| Eaton Corporation plc |
| Nabtesco Corporation |
| Carlisle Brake & Friction |
| Parker Hannifin Corporation |
| Hilliard Corporation |
| TMD Friction Holding GmbH |
| Altra Industrial Motion Corp. |
| Others |
Cost & Logistics Intelligence
Capacity utilization at Chinese electromagnetic coil foundries shapes both supply concentration and price floors for brake system OEMs serving automated material handling markets. Scale advantages in Yangtze River Delta manufacturing clusters compress component costs while forcing smaller European fabricators toward premium custom configurations or exit.
Pricing Analysis
Long-term offtake contracts dominate procurement between major port operators and brake system OEMs, with spot purchasing limited to emergency replacement scenarios. Three-tier pricing structure across premium, standard, and economy levels separates SIL-certified redundant systems from single-circuit configurations and unbranded aftermarket linings. Cost compression in economy-tier friction materials is intensifying because REACH-compliant ceramic-fiber formulations carry raw material premiums. Mining operators in Australian iron ore corridors exhibit the highest price sensitivity due to downtime cost multiples, while German automotive battery plants prioritize certification grade over unit cost.
Supply Chain Analysis
China and Germany anchor electromagnetic actuator and precision servo brake production respectively, with the United States retaining hydraulic brake manufacturing for heavy-lift mobile cranes. Sintered metallic friction materials draw from copper-free powder metallurgy feedstocks, permanent magnet hysteresis systems rest on neodymium-iron-boron supply, and drum brake shoes hinge on ceramic-fiber composite development. Single-source vulnerability concentrates in DRC and Indonesian cobalt refining for legacy lining formulations. Distribution runs through OEM captive service networks in European port corridors and independent distributors capturing aftermarket volume in North American bulk material handling markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart braking convergence with IoT sensor platforms is reshaping this market toward ecosystem economics, where predictive maintenance interoperability determines supplier viability rather than standalone component performance.
For Market Incumbents: Fortify backward integration into friction material supply to secure REACH-compliant ceramic-fiber capacity ahead of 2026 authorization deadlines. Capture channel control through distributor acquisition in Southeast Asian maintenance corridors where independent same-day delivery networks threaten OEM service contract retention. For New Entrants and Emerging Players: Differentiate on permanent magnet hysteresis specialization for cleanroom AGV applications in Michigan and South Carolina automotive battery plants, where electromagnetic expertise fragments traditional supplier hierarchies. Target India's PLI-subsidized domestic manufacturing ecosystem for cost-competitive entry into Mumbai and Mundra port expansions. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors magnetic material specialists over legacy friction engineering houses as plant electrification accelerates. Acquisition targets should demonstrate captive neodymium-iron-boron supply relationships or SIL pre-certification capabilities. The signal to watch is TÜV Rheinland documentation timelines extending product launch cycles, which will concentrate share among pre-certified suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Friction Materials | REACH Annex XVII compliance deadlines force captive ceramic-fiber composite supply for CE marking retention. |
| SIL Pre-Certification Investment | TÜV Rheinland safety integrity documentation accelerates product launch cycles for Hamburg and Rotterdam port operators. |
| IoT Sensor Platform Partnership | Predictive maintenance convergence creates premium pricing tiers for automated warehouse crane operators. |
| Distributor Acquisition in Southeast Asia | Independent same-day delivery networks in Texas and Louisiana corridors threaten OEM aftermarket capture. |
| Permanent Magnet Hysteresis R&D | Automotive battery plant cleanroom specifications in Michigan fragment traditional electromagnetic actuator hierarchies. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with maintenance directors at steel mills and port terminals, plant engineers specifying brake systems for automated material handling, OEM procurement teams at crane manufacturers, and aftermarket service heads at independent distributors; alongside secondary validation through customs and trade data on friction material imports, SEC filings from diversified industrial conglomerates, and MIIT equipment standard disclosures. Bottom-up triangulation across torque band specifications and top-down validation against port modernization expenditure patterns ensured cross-verification.
Across the analysis window, the forecast framework modeled demand by product type (disk, drum, hydraulic, pneumatic), application (crane, conveyor, manufacturing equipment, forklift), technology (electromagnetic, mechanical, hydraulic, pneumatic), and end user (mining, construction, manufacturing, transportation), with CAGRs derived from equipment replacement cycle analysis and regulatory compliance deadline clustering. Industry-specific inputs included EU Machinery Directive enforcement timelines and EPA friction material regulation phase-in schedules.
Decision-makers should treat outputs as directional under assumptions of continued port modernization expenditure and REACH authorization adherence; material deviation in cobalt supply stability or electromagnetic adoption curves would warrant model refresh. Recalibration cycles align with shifts in regulatory enforcement timelines and raw material substitution curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
United States Ceramic Ball Bearings Market
Automotive Parts
Odometer Market
Automotive Parts
Automotive Surface Coated Brake Market
Automotive Parts
Bearing Steel Balls for New Energy Vehicles Market
Automotive Parts
Global Automotive Jacks Market
Automotive Parts
Electric Vehicle Brake Pad Market
Automotive Parts
Mobile Diesel Heaters Market
Automotive Parts
Automotive Engine Oil Coolant Market
Automotive Parts
Global Automotive Motor Oil Market
Automotive Parts
Automotive Fuel Delivery System Market
Automotive Parts
Russia Automotive Airfilters Market
Automotive Parts
Insert Drive for Torque Wrench Market
Automotive Parts
Passenger Car Motor Oil Market
Automotive Parts
Global Intelligent All-Wheel Drive System Market
Automotive Parts
Needle Roller Bearings Market
Automotive Parts
Automotive Parts Magnesium Die Casting Market