
 Automotive Belts Market | 2026-2036
Automotive Belts Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Belts Market Analysis
Asset-light leasing models for commercial fleet maintenance is fragmenting the traditional aftermarket, allowing smaller service networks to stock premium inventory without balance-sheet strain. Gates Corporation leverages its captive distribution to control workshop channel pricing. Continental AG sustains R&D intensity in aramid-reinforced timing belt architectures. Bando Chemical Industries specializes in heat-resistant compounds for Southeast Asian operating conditions.
Automotive belts are power transmission components manufactured from rubber compounds reinforced with tensile cords of fiberglass, aramid, or polyester, engineered to synchronize camshaft rotation, drive accessories, or transfer torque in serpentine configurations. Timing belts dominate engineering margins due to precision tooth-profile requirements and failure-mode criticality in interference engines. Serpentine belts are displacing multiple V-belt layouts as OEMs consolidate accessory drives for packaging efficiency. Polyurethane formulations are capturing share in high-temperature zones where EPDM rubber degrades prematurely.
NHTSA durability standards and EPA fuel-economy mandates compel OEMs to specify lower-friction belt constructions that reduce parasitic losses. China's GB standards and MIIT energy-efficiency regulations enforce domestic testing protocols that foreign suppliers must navigate for homologation. Stakeholders must monitor how electrified powertrains eliminate mechanical accessory drives in battery-electric vehicles while extending belt life in hybrid architectures.
Market Dynamics
Electrified powertrain architectures are bifurcating belt demand trajectories, eliminating mechanical accessory drives in battery-electric platforms while extending service intervals in hybrid systems through reduced thermal cycling stress.
Growth Catalysts
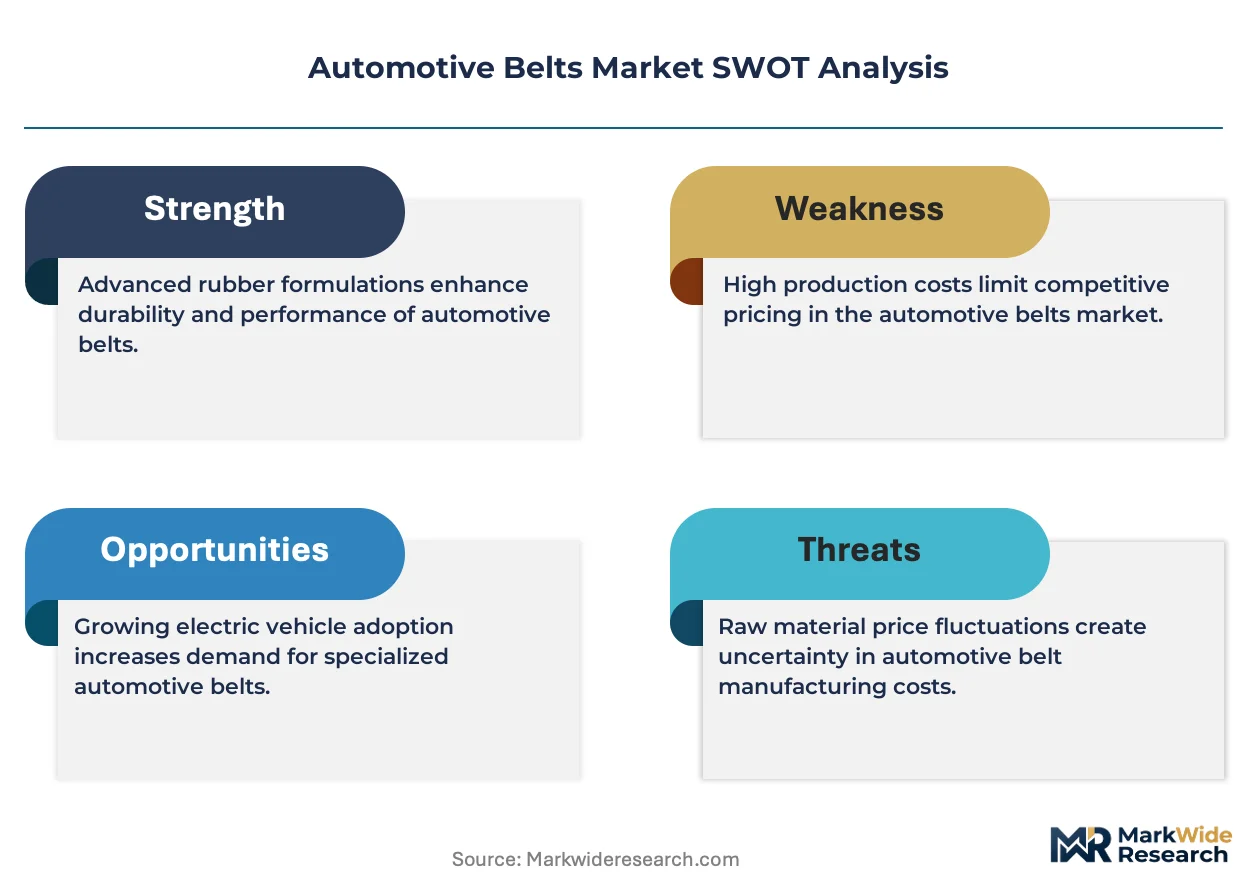
- EPA fuel-economy mandates:NHTSA durability standards compel OEMs to specify lower-friction belt constructions that reduce parasitic losses across accessory drive systems.
- China's MIIT energy-efficiency regulations:Domestic testing protocols under GB standards enforce homologation requirements that foreign suppliers must navigate, concentrating demand with certified manufacturers.
- Predictive maintenance platforms:Commercial vehicle fleets are expanding replacement cycles through IoT-enabled condition monitoring, sustaining aftermarket volume despite extended intervals.
Market Restraints
- EPDM compound volatility:Synthetic rubber feedstock costs fluctuate with petrochemical pricing, compressing margins for standardized serpentine belt production.
- Interference engine decline:Timing belt replacement demand weakens as automakers migrate to chain-driven valvetrains in internal combustion architectures.
- Aramid fiber supply concentration:Tensile cord reinforcement materials depend on limited specialty chemical producers, creating input bottleneck risks.
Strategic Opportunities
- Hybrid thermal management belts:Polyurethane formulations are capturing share in high-temperature zones where EPDM degrades prematurely, serving belt-in-oil applications.
- Southeast Asian aftermarket penetration:Heat-resistant compound specialization addresses operating conditions in tropical climates with sustained humidity exposure.
- Asset-light fleet service networks:Leasing models for commercial maintenance allow smaller workshops to stock premium inventory without balance-sheet strain.
Industry Challenges
- Tooth-profile precision engineering:Timing belt manufacturing requires micron-level tolerances that strain quality control systems and demand specialized tooling investments.
- Homologation timeline compression:China's GB standards evolution accelerates certification cycles, forcing simultaneous compliance with divergent regional protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Belts Market |
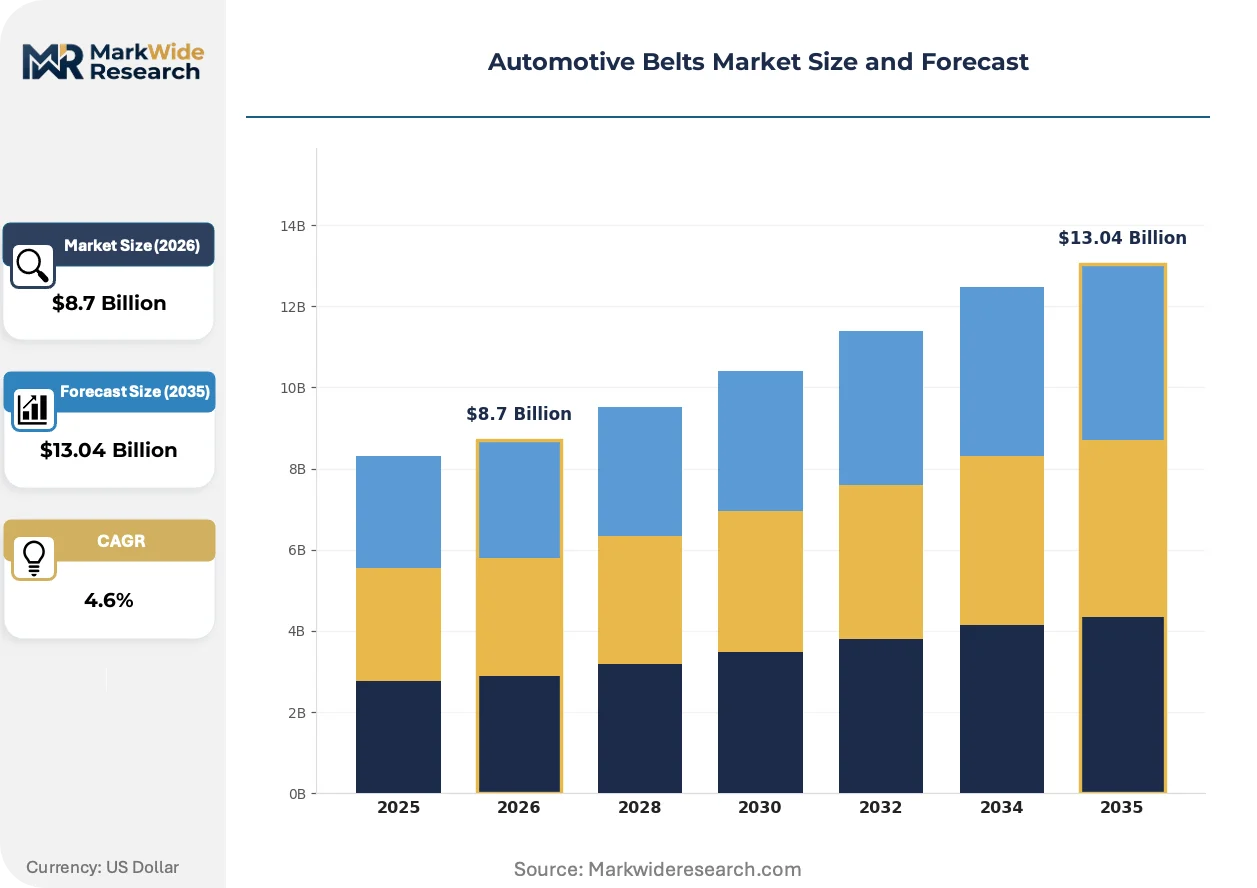
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Timing Belts, V-Belts, Serpentine Belts, Drive Belts Material: Rubber, Polyurethane, Nylon, Composite Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Heavy Machinery Distribution Channel: Retail Stores, Online Platforms, Distributors, Workshops |
| Companies Covered | Continental AG, Gates Corporation, Dayco Products LLC, Sumitomo Riko Co. Ltd, Toyoda Gosei Co. Ltd, Mitsuboshi Belting Ltd., Bando Chemical Industries, Ltd., Schaeffler AG, Hutchinson SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Belts Market Emerging Trajectories
Material science advances and regulatory efficiency mandates are converging to reshape belt architecture specifications, with compound chemistry and reinforcement geometries undergoing systematic revision.
Polyurethane belt formulations are collapsing the thermal performance gap between rubber compounds and engineered polymer alternatives in underhood environments. Tier 1 suppliers are qualifying these materials for belt-in-oil applications where continuous lubricant exposure previously excluded elastomeric constructions. The structural consequence is collapsing differentiation between accessory drive belts and timing component durability standards.
REACH substance restrictions are forcing reformulation of plasticizer packages in EPDM compounds across European supply chains. The industrial consequence is accelerated R&D investment in bio-based processing aids and alternative vulcanization chemistries. Timing belt manufacturers serving EU OEMs are responding with pre-certified compound portfolios that anticipate SVHC list expansions.
Workshop channel consolidation is compressing distributor tiers as captive distribution networks bypass traditional aftermarket wholesalers. Independent service networks are losing price transparency as vertically integrated suppliers control terminal pricing directly. This disintermediation is most visible in North American commercial fleet maintenance contracts where national accounts negotiate direct sourcing arrangements.
Automotive Belts Market Segmentation
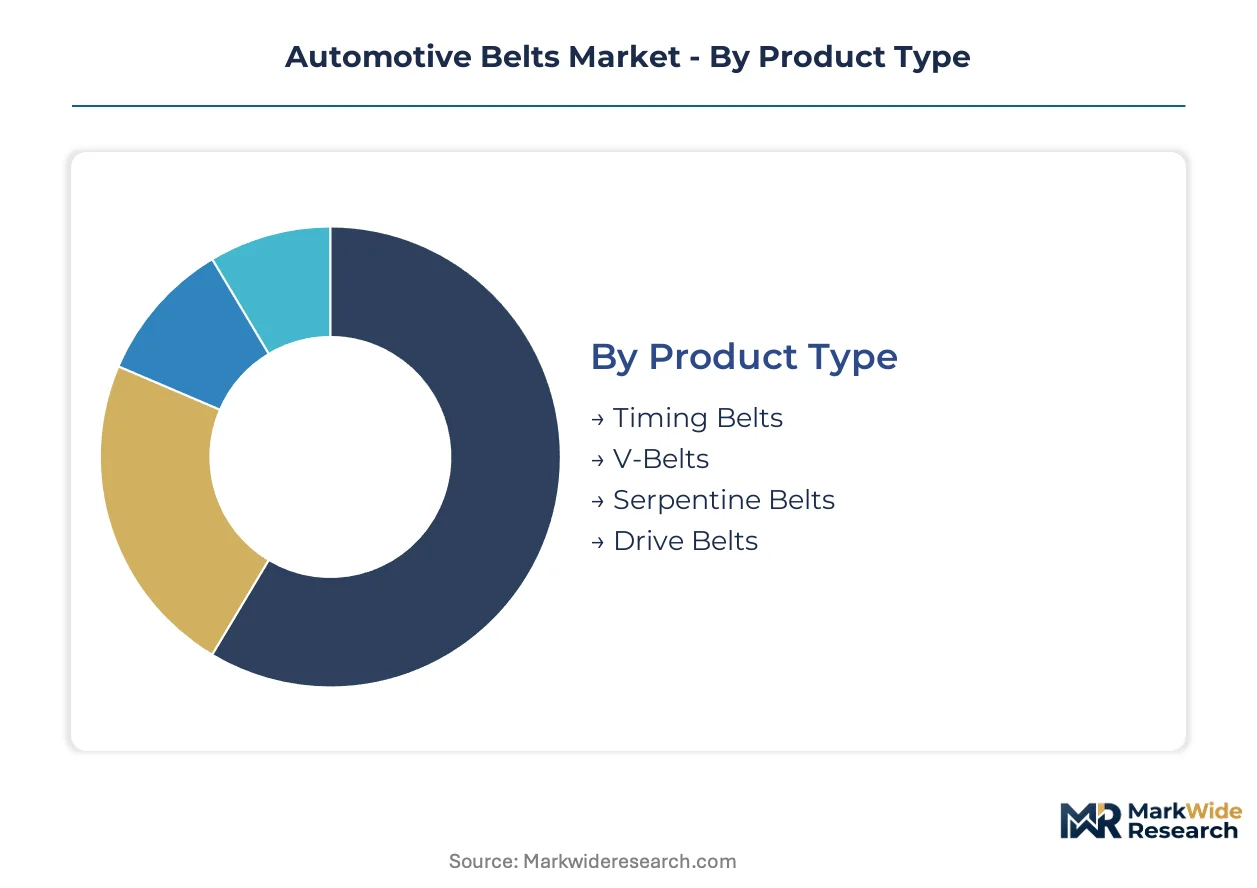
Segmentation in automotive belts reveals divergent margin structures across replacement cycles. After-sales service intensity varies dramatically between interference-engine timing belt replacements and commodity serpentine belt swaps. Material specifications and distribution channel economics further stratify profitability within each product category.
Product Type:
After-sales service intensity peaks with timing belt replacements requiring specialized tooling and engine bay disassembly, while serpentine belt swaps demand minimal labor investment.
- Timing Belts:Reinforced with fiberglass or aramid tensile cords and precision-molded tooth profiles, these components synchronize camshaft rotation in interference engines. Demand concentrates with independent workshops servicing aging vehicle parc in Eastern Europe and Latin America, where chain-driven valvetrain migration lags premium markets. Replacement intervals and labor-intensive installation sustain premium pricing power.
- Serpentine Belts:Multi-ribbed elastomeric constructions consolidate accessory drive functions into single belt paths. OEM specification in China and India for compact engine packaging is accelerating volume, though aftermarket replacement cycles extend through improved EPDM compound durability.
- V-Belts:Trapezoidal cross-section designs persist in legacy commercial vehicle applications and industrial auxiliary drives. Fleet maintenance contracts in Southeast Asia sustain residual demand.
- Drive Belts:Broad category encompassing specialty configurations for HVAC compressors and alternator pulleys. Niche specification in hybrid thermal management systems is emerging.
By volume, serpentine belts lead. By growth pace, timing belts are ahead in aftermarket value capture.
Material:
Cost tier stratification separates commodity rubber formulations from engineered polymer alternatives commanding specification premiums.
- Rubber:EPDM compounds dominate standardized serpentine and V-belt production through temperature resistance and flex fatigue performance. Petrochemical feedstock volatility compresses margins for undifferentiated manufacturers.
- Polyurethane:Thermoplastic elastomer formulations penetrate belt-in-oil applications and high-temperature zones where EPDM degrades. Hybrid powertrain thermal management requirements in Japan and South Korea are accelerating qualification timelines.
- Nylon:Reinforcement substrate for tensile cord jackets providing abrasion resistance. Limited direct belt body application.
- Composite:Multi-material laminates combining rubber elastomeric layers with engineered fiber reinforcement. OEM specification for extended-life accessory drives in German premium passenger vehicles.
By installed base, rubber dominates. By specification momentum, polyurethane is climbing fastest.
Application:
Customer type segmentation separates fleet procurement discipline from fragmented retail replacement behavior.
- Passenger Vehicles:Light-duty applications span timing, serpentine, and accessory drive configurations. Replacement demand fragments across DIY retail, workshop service, and dealer channel capture.
- Commercial Vehicles:Heavy-duty specifications emphasize durability under sustained load cycles. Predictive maintenance platforms in US long-haul fleets are compressing emergency replacement incidence.
- Two-Wheelers:Compact belt drives for scooter CVT transmissions and motorcycle final drives. High-volume, low-unit-value production concentrated in India and Indonesia.
- Heavy Machinery:Construction and agricultural equipment applications requiring extreme duty cycle resistance. Aftermarket parts availability in remote operating environments commands premium logistics pricing.
By unit volume, two-wheelers lead. By value per replacement, commercial vehicles are expanding most quickly.
Distribution Channel:
Supply concentration patterns determine pricing transparency and inventory carrying cost allocation across channel tiers.
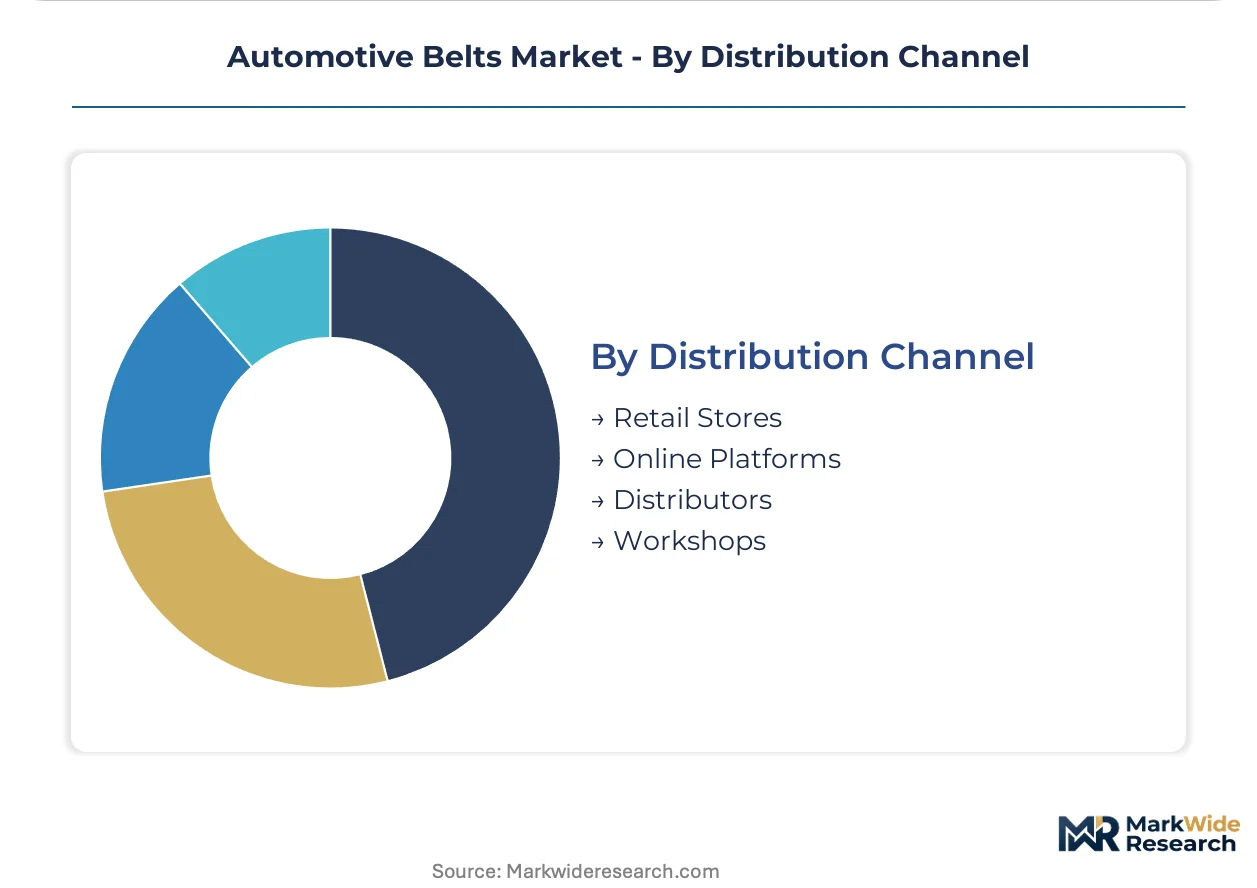
- Retail Stores:Big-box auto parts chains and independent jobbers serving DIY installers. Price transparency pressures margins on commodity serpentine belts.
- Online Platforms:E-commerce penetration accelerates in replacement parts comparison shopping. Counterfeit susceptibility complicates quality assurance for timing belt purchases.
- Distributors:Traditional wholesale tiers facing disintermediation from captive supplier networks. Remaining value concentrates in technical support and local inventory availability.
- Workshops:Service bay installation captures bundled labor-plus-parts revenue. National fleet accounts in North America negotiate direct sourcing arrangements bypassing distribution markup.
By transaction count, workshops lead. By channel shift velocity, online platforms are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA and NHTSA emissions standards in the United States are tightening accessory drive efficiency requirements, while China's MIIT energy-efficiency regulations enforce domestic testing protocols that concentrate demand with certified manufacturers. These policy frameworks are reshaping regional competitive positioning and supplier qualification timelines across major automotive production clusters.
United States
Commercial vehicle fleets are expanding belt replacement cycles through predictive maintenance programs, compressing emergency replacement incidence. NHTSA durability standards compel OEMs to specify lower-friction belt constructions that reduce parasitic losses across accessory drive systems. Detroit's automotive supplier corridor hosts concentrated R&D activity in aramid-reinforced timing belt architectures serving domestic OEMs.
Germany
German premium passenger vehicle manufacturers specify extended-life accessory drives with composite multi-material laminates. REACH substance restrictions are forcing reformulation of plasticizer packages in EPDM compounds across European supply chains. Stuttgart and Munich anchor engineering centers where pre-certified compound portfolios anticipate SVHC list expansions.
China
Domestic OEMs are expanding electrified powertrain production, bifurcating belt demand trajectories between eliminated mechanical drives and extended hybrid service intervals. GB standards and MIIT energy-efficiency regulations enforce homologation requirements that foreign suppliers must navigate. Shanghai and Guangzhou production clusters concentrate belt-in-oil application qualification for hybrid thermal management systems.
Japan
Hybrid powertrain thermal management requirements are accelerating polyurethane belt qualification timelines. METI industrial policy supports advanced materials development for high-temperature underhood applications. Nagoya and Toyota City manufacturing zones specialize in precision tooth-profile engineering for interference engine timing systems.
India
Two-wheeler CVT transmission and motorcycle final drive belts sustain high-volume, low-unit-value production concentrated in domestic manufacturing zones. BIS standards enforcement is tightening quality certification for aftermarket replacement components. Pune and Chennai industrial corridors host expanding capacity for heat-resistant compounds addressing tropical operating conditions.
Automotive Belts Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered market strata. The vendor base organizes around three strategic archetypes: vertically integrated system suppliers with captive distribution networks, compound-specialist manufacturers with regional formulation expertise, and scale-driven commodity producers serving standardized serpentine belt demand. Dominant competitive moves include backward integration into aramid fiber reinforcement supply and geographic expansion through qualified compound portfolios in China.
Within the integrated-system tier, Continental AG and Gates Corporation exemplify channel-control strategies, while Bando Chemical Industries occupies a specialization position in heat-resistant compound development. These three anchors represent distinct competitive vectors: German engineering-intensive architectures, North American distribution-captive models, and Japanese tropical-climate formulation expertise.
| Leading Market Players |
|---|
| Continental AG |
| Gates Corporation |
| Dayco Products LLC |
| Sumitomo Riko Co. Ltd |
| Toyoda Gosei Co. Ltd |
| Mitsuboshi Belting Ltd. |
| Bando Chemical Industries, Ltd. |
| Schaeffler AG |
| Hutchinson SA |
| Others |
Supply Flow & Price Mechanics
Aramid fiber production concentrates in the United States, Japan, and the Netherlands, tethering tensile cord supply to specialty chemical producers and anchoring margin pools with belt manufacturers commanding captive reinforcement supply. This upstream concentration cascades into pricing power asymmetries where integrated suppliers capture premium timing belt margins while commodity serpentine producers absorb EPDM feedstock volatility.
Pricing Analysis
Certification level under GB standards and REACH compliance creates the primary spread between premium and commodity tiers. Three-tier pricing structure separates OEM-specified polyurethane formulations from aftermarket EPDM replacements and legacy V-belt inventory. Cost compression in standardized serpentine production is intensifying because Chinese domestic OEMs consolidate specification power. Fleet procurement through national accounts exhibits lowest price sensitivity; independent workshops sourcing through fragmented distributors show highest.
Supply Chain Analysis
Petrochemical feedstock for EPDM compounds draws from integrated refineries in China, South Korea, and Singapore, while aramid reinforcement fibers source from DuPont and Teijin production clusters. Synthetic rubber and glass fiber dependencies expose manufacturers to commodity price swings. Single-source vulnerability in aramid tensile cord supply creates bottleneck risk during capacity constraints. Distribution runs through captive supplier networks bypassing traditional wholesale tiers in North America, with independent distributors retaining residual value in technical support and local inventory.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrified powertrain bifurcation fragments demand into eliminated mechanical drives and extended hybrid service intervals, creating specialization niches for compound chemists and thermal management engineers.
For Market Incumbents: Harden qualification timelines for belt-in-oil polyurethane formulations to defend against Japanese and South Korean compound specialists penetrating hybrid thermal management. Deepen backward integration into aramid fiber supply to mitigate single-source concentration risk from Teijin and DuPont. Channel control through captive workshop networks remains essential as national fleet accounts negotiate direct sourcing arrangements. For New Entrants and Emerging Players: Build out heat-resistant compound capabilities targeting Southeast Asian aftermarket conditions where sustained humidity and tropical operating temperatures degrade standard EPDM formulations. India's two-wheeler CVT belt segment offers penetrable volume with lower certification barriers than OEM timing belt qualification. Direct technical partnership with regional distributors provides go-to-market traction without captive network investment. For Investors and Strategic Acquirers: Capital is best deployed toward compound-specialist manufacturers with qualified polyurethane portfolios and GB standards certification for Chinese hybrid production clusters. Long-term viability hinges on positioning for belt-in-oil thermal management growth while managing timing belt decline from chain-driven valvetrain migration. Watch qualification timelines for polyurethane formulations in Japanese hybrid platforms as inflection indicator for material substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aramid Fiber Supply | Captive reinforcement supply mitigates Teijin and DuPont concentration risk for timing belt manufacturers. |
| GB Standards Certification Investment | MIIT homologation unlocks Chinese OEM specification for hybrid thermal management belt-in-oil applications. |
| Heat-Resistant Compound Regional Expansion | Southeast Asian formulation expertise captures tropical climate aftermarket replacement demand. |
| Captive Workshop Network Consolidation | Direct channel control preserves pricing power against disintermediation from national fleet accounts. |
| Polyurethane Belt-in-Oil Qualification | High-temperature hybrid thermal management specifications displace EPDM in underhood lubricant exposure zones. |
Methodological Framework
A spread of perspectives from OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors, and compound R&D directors converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against vehicle production databases, IHS Markit registration data, customs trade flows, and SEC filings from listed automotive suppliers. Bottom-up segmentation modeling triangulated against top-down macroeconomic drivers.
Demand-supply balance framing anchored the analytical approach across the analysis window, with vehicle parc aging curves and electrification penetration rates as primary demand inputs. Segmentation dimensions included propulsion architecture, belt type specification, material chemistry tier, and regional production cluster. CAGRs derived from installed base projections and replacement interval elasticity by vehicle class. Industry-specific inputs encompassed MIIT energy-efficiency regulation timelines and REACH substance restriction phase-ins.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese domestic compound specialists or accelerated chain-driven valvetrain migration would shift outcomes beyond modeled ranges. Cross-checking against IHS Markit vehicle powertrain forecasts and MIIT electrification targets is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Steering Wheel Armature Market
Automotive Parts
Cheetah Friction Reduction Technologies Market
Automotive Parts
Bulgaria Automotive Lubricants Market
Automotive Parts
Automotive Tonneau Market
Automotive Parts
Bumper Beam Market
Automotive Parts
Malaysia Passenger Vehicles Lubricants Market
Automotive Parts
Colombia Automotive Lubricants Market
Automotive Parts
Commercial Vehicles LED Bar Lights Market
Automotive Parts
India Automotive Coolant Market
Automotive Parts
China Automotive Lubricants Market
Automotive Parts
Morocco Automotive Engine Oils Market
Automotive Parts
Suspension Spring Market
Automotive Parts
Automotive Spring Market
Automotive Parts
Automotive AHSS Market
Automotive Parts
Automotive Brake Linings Market
Automotive Parts
Russia Automotive Airfilters Market