
 Global Automotive Closure Market | 2026-2036
Global Automotive Closure Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Closure Market Intelligence
Aftermarket service revenue is narrowing as OEMs extend warranty periods and integrate predictive maintenance into connected closure systems. Magna Closures leverages its vertical manufacturing footprint to control cost structures across door module production. Brose sustains engineering leadership through mechatronic integration in power closure applications. Huf Hülsbeck & Fürst anchors European premium supply relationships with specialized sealing and latching expertise.
Automotive closures encompass hinged, sliding, and powered panel assemblies that regulate occupant access, cargo loading, and vehicle aerodynamics, typically incorporating stamped metal substrates, polymer seals, and electronic latch mechanisms with specified intrusion resistance and weatherstrip compression set parameters. Doors and tailgates dominate value contribution due to complexity in power-actuated and hands-free variants, while carbon fiber and magnesium material segments attract development investment for mass reduction in electric vehicle architectures. The OEM end-user channel captures the majority of margin pools through long-term platform contracts, though aftermarket providers compete on replacement cycle timing and regional logistics density.
NHTSA Federal Motor Vehicle Safety Standards govern side-door strength and ejection mitigation in the United States, while ECE R11 and ECE R94 harmonize door retention and occupant protection across European type-approval processes. EPA fuel economy benchmarks and EU CO2 fleet targets indirectly accelerate lightweight material substitution in closure panels. Stakeholders must monitor evolving FMVSS updates for autonomous vehicle egress protocols and emerging battery enclosure integration standards that blur traditional closure boundaries.
Market Dynamics
Power closure electrification is compressing mechanical component demand while expanding mechatronic system complexity across door and tailgate assemblies. This shift reconfigures supplier hierarchies and engineering resource allocation throughout the value chain.
Growth Catalysts
- EU F-Gas Regulation:Phase-down mandates for high-global-warming-potential refrigerants are accelerating polymer seal material transitions toward low-permeation elastomers in European closure assemblies.
- Hands-free entry systems:Capacitive and radar-based proximity sensing is penetrating premium and mid-range vehicle segments, expanding actuator and control module attach rates per vehicle.
- China:NEV platform consolidation by domestic OEMs is concentrating closure sourcing decisions among vertically integrated module suppliers with localized stamping and injection capacity.
Market Restraints
- Magnesium price volatility:Primary magnesium supply concentration in Shaanxi Province creates input cost instability for lightweight closure panel programs targeting mass reduction targets.
- REACH substance restrictions:Candidate list expansion for SVHCs is forcing reformulation of chrome-based conversion coatings and certain plasticizers in weatherstrip compounds.
- Steel tariff regimes:Cross-border duties on cold-rolled and advanced high-strength steel grades are elevating landed costs for stamped closure substrates in multiple trade corridors.
Strategic Opportunities
- India:PLI scheme incentives for automotive component manufacturing are attracting door module investments to serve emerging domestic EV production clusters around Chennai and Pune.
- Battery enclosure integration:Closure engineering expertise in sealing, latching, and crashworthiness is transferring to underbody battery pack architectures, opening adjacent revenue pools.
- Over-the-air calibration:Connected closure systems enable remote diagnostic and parameter update capabilities, creating recurring service attachment opportunities beyond hardware shipment.
Industry Challenges
- Mechatronics talent scarcity:Shortage of engineers with combined mechanical and embedded software competency is delaying development timelines for smart latch and anti-pinch systems.
- Homologation divergence:Misalignment between NHTSA FMVSS side-door requirements and ECE R94 testing protocols forces parallel validation programs, duplicating crash test and documentation expenditure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Closure Market |
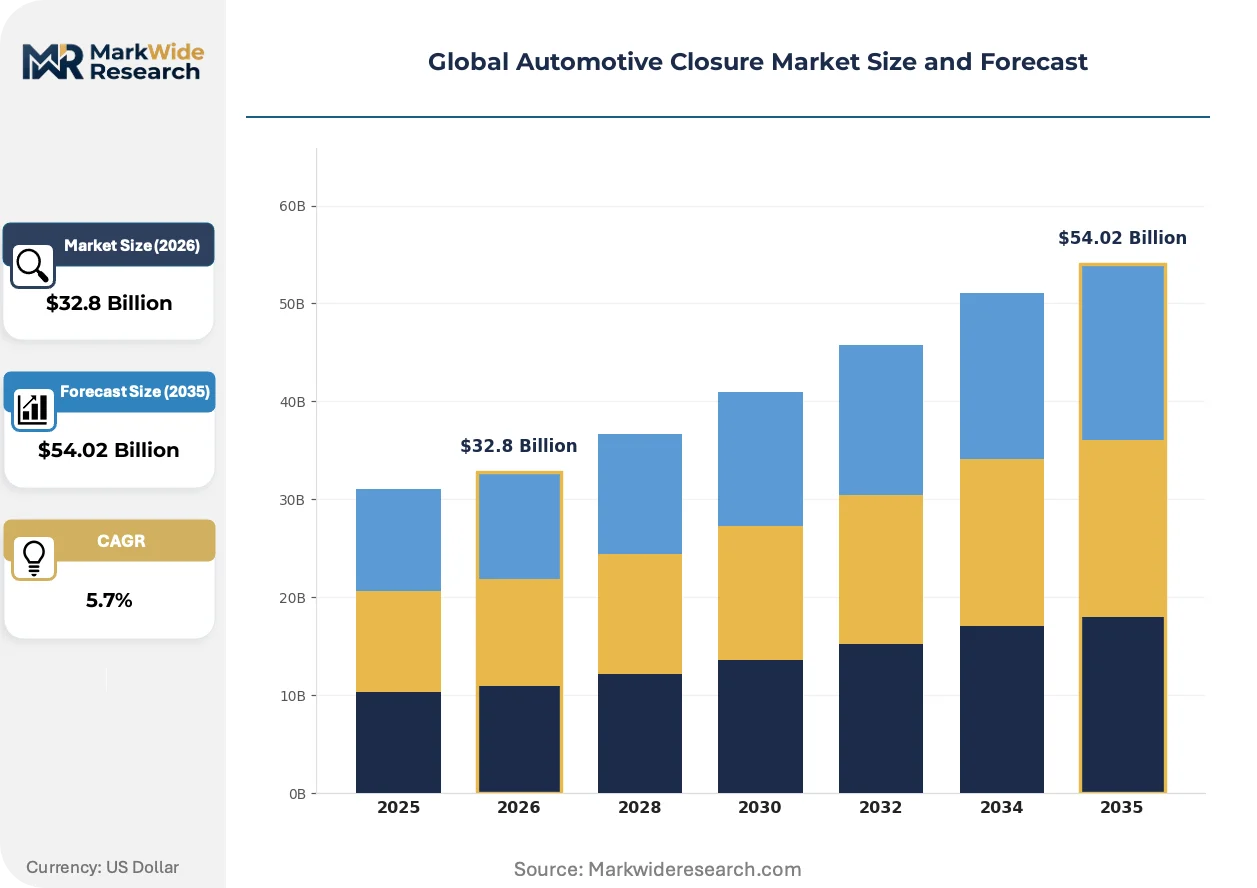
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $54.02 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Doors, Tailgates, Hooods, Sunroofs, Trunks Material: Steel, Aluminum, Carbon Fiber, Plastic, Magnesium Application: Passenger Cars, Commercial Vehicles, Electric Vehicles, Off-highway Vehicles End User: OEMs, Tier-1 Suppliers, Dealerships, Aftermarket Providers |
| Companies Covered | Inteva Products, Huf Hülsbeck & Fürst, Magna Closures, Valeo, U-Shin, Brose, Aisin, STRATTEC Security, Kiekert, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Closure Market Strategic Shifts & Innovations
Material substitution and embedded intelligence are converging to redefine closure system architecture, with implications rippling through stamping, sealing, and electronic control supply tiers.
Continuous fiber-reinforced thermoplastic (CFRTP) door inner panels are achieving production scale at select German OEM platforms. These hybrid structures integrate unidirectional tape layups with injection-molded ribs, cutting mass versus steel assemblies by approximately one-third. CFRTP is rendering obsolete traditional resistance spot-welding sequences, demanding adhesive bonding and laser joining process investments at tier suppliers.
REACH authorization requirements for chromium trioxide in surface treatment are tightening across European coating operations. The restriction is accelerating plasma electrolytic oxidation and thin-film conversion coating qualification programs for magnesium closure hardware. Suppliers with captive finishing capacity in Germany and the Czech Republic are consolidating process development to shared technical centers.
Fleet operators and mobility service providers are compressing replacement cycle timelines for closure wear components. These buyers are unbundling traditional OEM parts warranties in favor of usage-based maintenance contracts with guaranteed uptime clauses. The shift is most pronounced in North American last-mile delivery vehicle segments, where door actuator reliability directly impacts route completion metrics.
Global Automotive Closure Market Segmentation
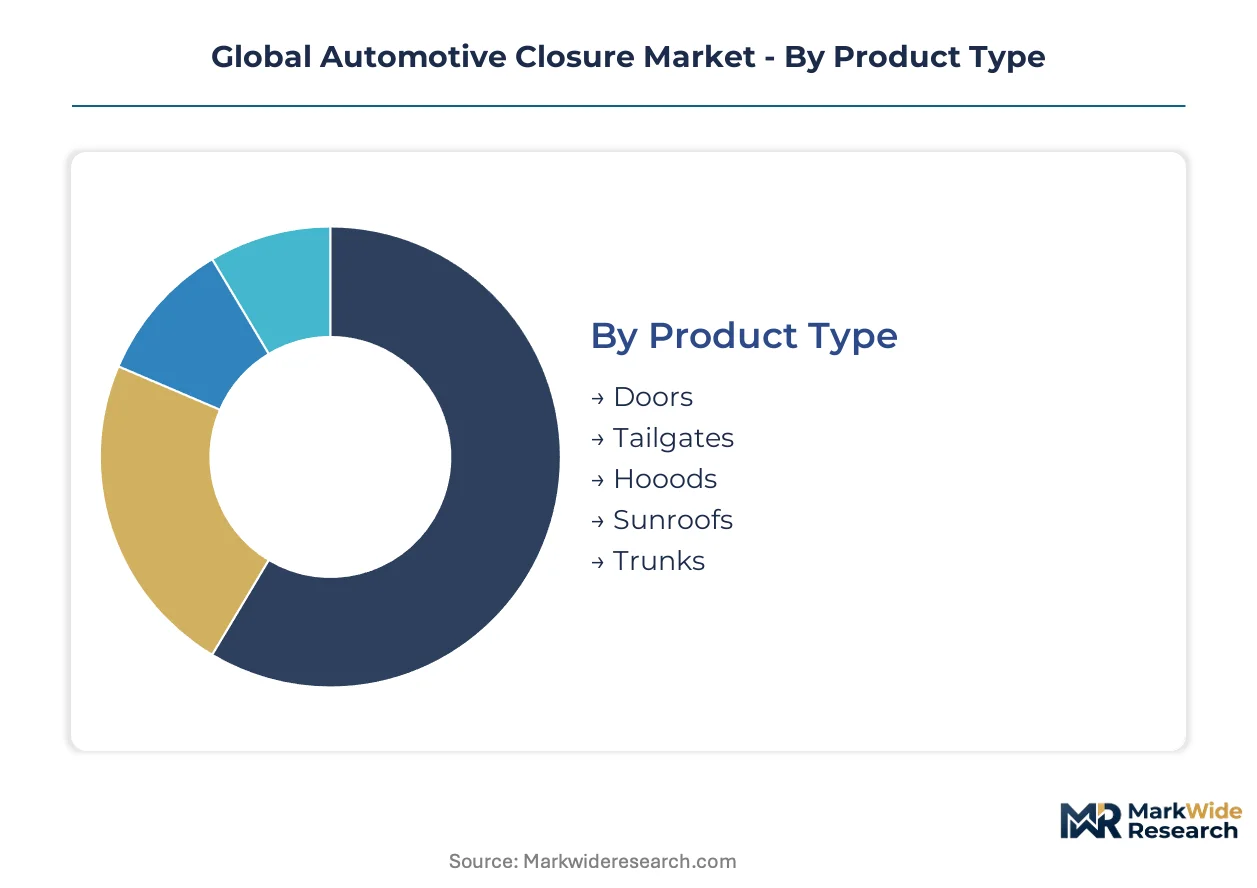
Segmentation in automotive closures reveals divergent investment cycles across product architectures, material platforms, and electrification readiness. Understanding these temporal patterns enables suppliers to calibrate capacity planning and R&D allocation against varying replacement velocities and platform lifespans.
Product Type:
Doors and tailgates turn over on 5-7 year platform cycles, while hoods and trunks follow slower 8-10 year refresh timelines. Sunroofs exhibit the most volatile demand swings tied to consumer option take rates.
- Doors:Power-actuated side doors integrate anti-pinch sensors, capacitive handles, and composite inner panels. European premium OEMs are driving hands-free entry adoption fastest, compressing mechanical latch development timelines.
- Tailgates:Hands-free liftgate systems with radar-based foot sensors now penetrate mid-range SUVs and crossovers. Chinese NEV platforms are consolidating power tailgate sourcing among module suppliers with localized actuator production.
- Hoods:Pedestrian protection regulations in Germany and the United States mandate active hood lift mechanisms. Aluminum hood substrates dominate mass reduction programs for internal combustion architectures.
- Sunroofs:Panoramic glass panels with polymer encapsulation face margin pressure from fixed-glass roof alternatives. German glass suppliers control tooling investments for large-format laminated assemblies.
- Trunks:Sedan trunk lids retain steel-intensive construction due to lower mass sensitivity versus liftgates. Japanese OEMs maintain proprietary hinge and latch engineering for this segment.
Doors anchor the volume base while tailgates gain share at the steepest rate.
Material:
Steel substrates maintain cost leadership for high-volume platforms, while aluminum and carbon fiber command premium positioning in electrification-focused architectures. Magnesium and advanced plastics occupy niche applications with constrained supply chains.
- Steel:Advanced high-strength steel grades achieve 980 MPa tensile strength in door intrusion beams. United States tariff exposure on cold-rolled imports is elevating landed costs for stamping operations serving Detroit Three programs.
- Aluminum:6xxx series extrusions and stampings cut panel mass versus steel by 40-50 percent. European OEMs in Germany and Sweden lead aluminum closure adoption for premium electric vehicle platforms.
- Carbon Fiber:CFRTP door inner panels achieve production scale at select German OEM platforms. Continuous fiber-reinforced thermoplastic processing demands adhesive bonding investments that obsolete traditional spot welding.
- Plastic:Long-fiber-reinforced polypropylene compounds serve non-structural trim and sealing applications. REACH restrictions on certain plasticizers are forcing weatherstrip compound reformulations.
- Magnesium:Primary supply concentration in Shaanxi Province creates input cost instability. Plasma electrolytic oxidation surface treatments are displacing chrome-based conversion coatings under EU authorization pressures.
Steel retains volume dominance while carbon fiber expands most quickly in premium electric architectures.
Application:
Passenger car closures operate on consolidated global platforms with 6-8 year lifecycles. Commercial vehicle and off-highway segments extend replacement cycles to 12-15 years, while electric vehicle architectures demand accelerated development cadences.
- Passenger Cars:Global platform consolidation by Volkswagen Group and Toyota compresses variant engineering. Chinese domestic OEMs are localizing door module sourcing around Shanghai and Guangzhou production clusters.
- Commercial Vehicles:Fleet operators in North American last-mile delivery segments are unbundling OEM warranties for usage-based maintenance contracts. Door actuator reliability directly impacts route completion metrics for these buyers.
- Electric Vehicles:Battery enclosure integration is transferring closure engineering expertise in sealing and crashworthiness to underbody architectures. German and Chinese OEMs lead this adjacent application expansion.
- Off-highway Vehicles:Construction and agricultural equipment closures prioritize dust ingress protection over aerodynamic refinement. Deere and Caterpillar maintain proprietary sealing specifications for extreme duty cycles.
Passenger cars anchor the volume base while electric vehicles gain share at the steepest rate.
End User:
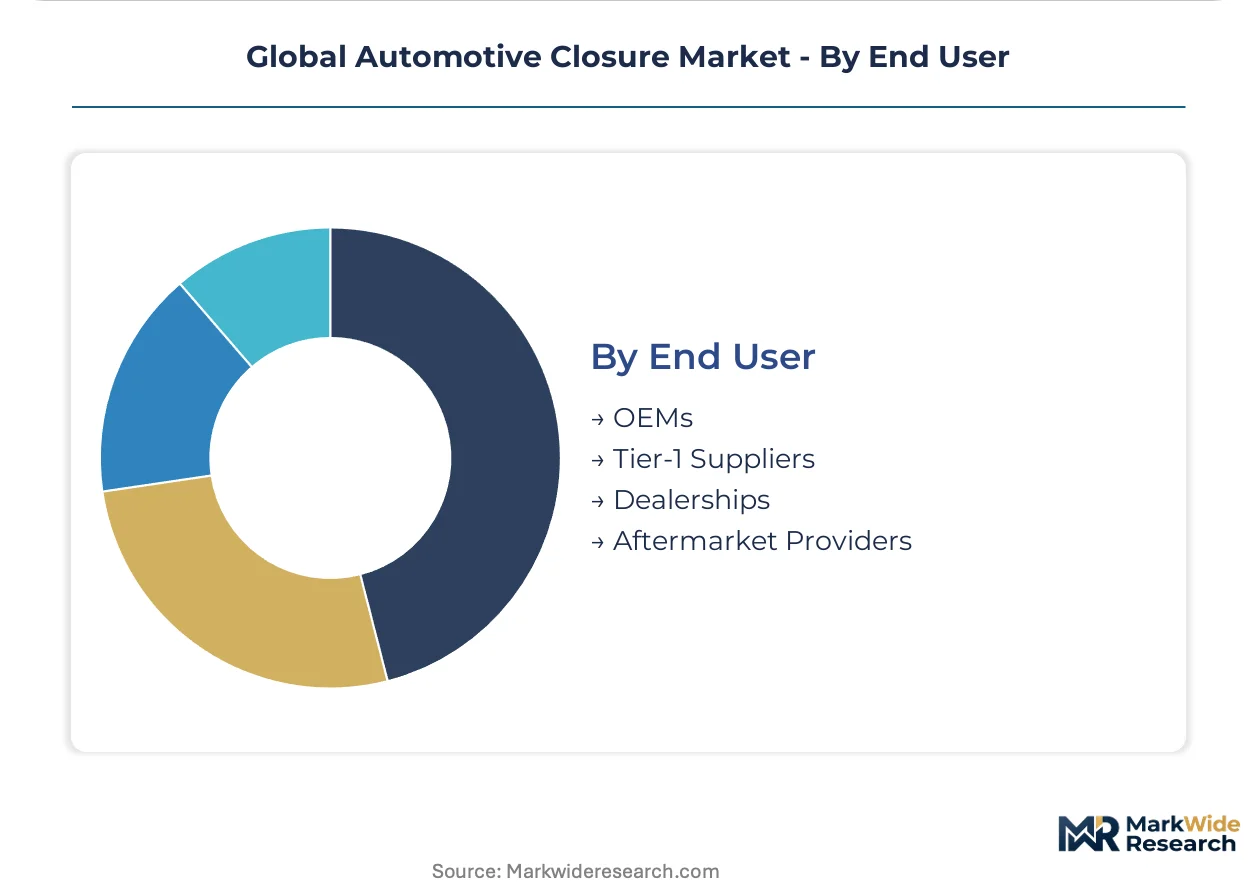
OEMs capture margin pools through long-term platform contracts with 5-7 year lock-in periods. Aftermarket providers compete on replacement cycle timing, while tier-1 suppliers face compressed payment terms from consolidated module sourcing.
- OEMs:Platform engineering decisions by Ford, BMW, and BYD determine material and technology trajectories. Predictive maintenance integration into connected closure systems is narrowing aftermarket service revenue.
- Tier-1 Suppliers:Magna Closures and Brose compete for door module contracts through mechatronic integration capabilities. Vertical manufacturing footprints control cost structures across stamping and injection operations.
- Dealerships:Warranty extension programs are capturing service revenue previously lost to independent repair networks. German premium brand dealers lead connected closure diagnostic tool investments.
- Aftermarket Providers:Regional logistics density determines competitiveness in replacement weatherstrip and latch mechanisms. Indian component manufacturers are expanding distribution networks to serve Africa and Southeast Asia.
OEMs anchor the volume base while tier-1 suppliers gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across major automotive closure markets. German and Japanese buyers absorb premium pricing for lightweight materials and mechatronic integration. Indian and Mexican markets remain acutely cost-conscious, compressing margins for imported substrate grades and power-actuated variants.
Germany
Premium OEM demand for CFRTP door inner panels and hands-free entry systems drives material innovation. EU F-Gas Regulation and REACH authorization requirements for chromium trioxide accelerate coating process transitions. Engineering clusters around Stuttgart and Munich host captive finishing technical centers serving BMW and Mercedes-Benz platforms.
United States
Fleet operators in last-mile delivery segments prioritize door actuator reliability under usage-based maintenance contracts. NHTSA FMVSS side-door strength and ejection mitigation standards govern platform engineering decisions. Detroit Three sourcing clusters in Michigan and Ohio face elevated landed costs from steel tariff exposure on cold-rolled imports.
China
NEV platform consolidation by BYD and domestic OEMs concentrates closure sourcing among vertically integrated module suppliers. MIIT dual carbon goals and GB standards for vehicle lightweighting shape material selection trajectories. Shanghai and Guangzhou production clusters anchor localized stamping and injection capacity for door module programs.
India
PLI scheme incentives attract door module investments to serve emerging domestic EV production. BIS automotive component standards and DGFT import policies influence substrate sourcing strategies. Chennai and Pune manufacturing corridors host expanding tier-1 operations targeting Africa and Southeast Asia distribution networks.
Japan
Toyota and Honda maintain proprietary hinge and latch engineering for sedan trunk lid segments. METI energy efficiency benchmarks and JIS standards guide closure mass reduction programs. Nagoya and Tokyo-Yokohama engineering centers sustain long-term platform contract relationships with consolidated supplier bases.
Global Automotive Closure Market Key Industry Players
Full-system integrators and specialized component suppliers split the market into distinct competitive tiers. Consolidation around door module contracts favors players with captive stamping, injection molding, and electronic control manufacturing. Three archetypes dominate: vertically integrated module suppliers, mechatronic specialists, and sealing hardware experts. Competitive moves center on backward integration into substrate production and geographic expansion through technical center consolidation.
Among European-based fabricators, Huf Hülsbeck & Fürst and Kiekert exemplify the sealing and latching specialization archetype, while Magna Closures occupies a position as a vertically integrated module supplier with North American and Asian production footprints. Brose represents the mechatronic integration tier, anchoring power closure engineering capabilities across premium and mid-range vehicle programs. These three entities collectively illustrate how supplier positioning stratifies around manufacturing depth versus component focus.
| Leading Market Players |
|---|
| Inteva Products |
| Huf Hülsbeck & Fürst |
| Magna Closures |
| Valeo |
| U-Shin |
| Brose |
| Aisin |
| STRATTEC Security |
| Kiekert |
| Others |
Cost & Logistics Intelligence
Primary magnesium concentration in Shaanxi Province anchors input cost instability for lightweight closure panels, compressing margin pools at stamping operations while concentrating pricing power among vertically integrated module suppliers with captive finishing capacity. This upstream dependency cascades downstream through door and tailgate assemblies, where OEM platform contracts lock in 5-7 year pricing trajectories that absorb commodity volatility differentially across supplier tiers.
Pricing Analysis
Extended warranty and predictive maintenance service tiers now capture lifetime value previously lost to aftermarket providers. Three-tier pricing structure across premium hands-free systems, standard power-actuated variants, and economy manual closures stratifies by mechatronic content and brand positioning. Cost compression in steel-intensive segments is intensifying because of tariff exposure on cold-rolled imports, with fleet operators in North American last-mile delivery proving most price-sensitive while German premium OEMs absorb material premiums for CFRTP and magnesium architectures.
Supply Chain Analysis
Contract manufacturing for door modules concentrates among Magna Closures, Brose, and Huf Hülsbeck & Fürst facilities across Germany, China, and Mexico. Stamped steel substrates, polymer weatherstrip compounds, and electronic latch mechanisms feed from these regional production clusters, with supply chain risk tethered to single-source vulnerability in Shaanxi Province magnesium and REACH-driven reformulation of chrome-based conversion coatings. Distribution runs through OEM platform engineering channels with tier-1 module consolidation, compressing payment terms for specialized sealing and latching component suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated OEM platform engineering decisions, as Volkswagen Group, Toyota, and BYD compress variant sourcing among vertically integrated module suppliers with localized stamping and injection capacity.
For Market Incumbents: Entrench mechatronic integration capabilities through captive software development centers and backward integration into actuator production. Defend against emerging Chinese NEV platform consolidation by securing long-term door module contracts with domestic OEMs in Shanghai and Guangzhou clusters. Prioritize certification investment in plasma electrolytic oxidation surface treatments to anticipate REACH authorization tightening on chromium trioxide. For New Entrants and Emerging Players: Pursue battery enclosure integration opportunities where sealing and crashworthiness expertise transfers to underbody architectures. The most penetrable white space sits in Indian EV production corridors around Chennai and Pune, where PLI scheme incentives attract component manufacturing investments. A usage-based maintenance contract go-to-market angle unbundles traditional OEM warranties for North American fleet operators. For Investors and Strategic Acquirers: Capital is best deployed toward mechatronic specialists with embedded software competency and European coating technical centers positioned for REACH transition. Long-term viability across the analysis window favors suppliers with demonstrated OEM platform contract execution and localized production footprints in China and India. The signal to watch is NHTSA FMVSS autonomous vehicle egress protocol updates that blur traditional closure boundaries with battery enclosure standards.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Volkswagen Group and Toyota consolidation compresses variant engineering costs across global door module programs. |
| Battery Supply Agreement | Closure engineering expertise in sealing and latching transfers to underbody battery pack architectures for German and Chinese OEMs. |
| Software-Defined Vehicle Investment | Over-the-air calibration capabilities for connected closure systems create recurring service attachment beyond hardware shipment. |
| Geographic Manufacturing Footprint | PLI scheme incentives in India attract door module investments to serve emerging domestic EV production clusters. |
| Charging Infrastructure Partnership | Hands-free entry system adoption in mid-range SUVs and crossovers expands actuator attach rates per vehicle. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with Tier 1 supplier procurement leads, OEM platform engineers, aftermarket distributors, and dealership operations managers; and secondary validation against vehicle production databases, IHS Markit registration data, SEC filings from Magna and Brose, and customs records for cold-rolled steel and magnesium trade flows. Bottom-up segmentation modeling triangulated with top-down macroeconomic drivers across the analysis window.
Forecast inputs considered vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster dimensions throughout the projection horizon. CAGRs were derived from regression analysis against historical platform lifecycles and electrification adoption curves, incorporating MIIT dual carbon goals and EU F-Gas Regulation phase-down mandates as structural demand shapers for lightweight material substitution.
Sensitivities concentrate around magnesium price volatility from Shaanxi supply concentration, REACH SVHC list expansion affecting weatherstrip compounds, and NHTSA FMVSS updates for autonomous vehicle egress protocols. Quarterly review of OEM platform engineering decisions, battery enclosure integration contract awards, and coating process qualification timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Powerglide Shifter Market
Automotive Parts
France Automotive Actuators Market
Automotive Parts
Automotive Hydraulic Filter System Market
Automotive Parts
Australia Automotive Parts Magnesium Die Casting Market
Automotive Parts
Electric Parking Brake Actuator Components Market
Automotive Parts
Mexico Automotive Air Filters Market
Automotive Parts
Middle East Automotive Lubricants Market
Automotive Parts
France Commercial Vehicles Lubricants Market
Automotive Parts
Automotive Tonneau Market
Automotive Parts
Automotive Electric Turbocharger Market
Automotive Parts
Global Automotive Coolant Reservoir Tank Market
Automotive Parts
Automotive Hoses Market
Automotive Parts
Global Automotive Cylinder Liner Market
Automotive Parts
Automotive Fastener Market
Automotive Parts
Automotive Speedometer Market
Automotive Parts
South Africa Passenger Vehicles Lubricants Market