
 Cylinder Head Cover Market | 2026-2036
Cylinder Head Cover Market Size, Share, and Industry Trends Forecast 2026-2036
Cylinder Head Cover Market Outlook
Mexico is tilting toward expanded die-casting capacity to serve North American powertrain assembly. Nemak leverages its integrated aluminum foundry network across Monterrey and northern industrial corridors. ThyssenKrupp anchors German engineering standards in cam cover design for European OEM supply chains. ElringKlinger specializes in polymer sealing interfaces that extend service intervals under thermal stress.
A cylinder head cover seals the valvetrain chamber atop an internal combustion engine, typically formed from aluminum alloy A380 through high-pressure die casting or from glass-reinforced polyamide via injection molding, and integrates positive crankcase ventilation baffles, oil fill ports, and ignition coil mounting bosses to manage blow-by gases and protect timing components. Aluminum product types dominate OEM supply for thermal conductivity and structural rigidity in heavy-duty cycles, while composite formulations gain traction in motorcycle and small-displacement engines where mass reduction commands priority. Passenger vehicle applications sustain the largest volume base, though commercial vehicle demand generates thicker margin pools due to durability specifications and lower price sensitivity in fleet procurement.
EPA tailpipe standards and Euro 6 emissions frameworks mandate enhanced crankcase ventilation integrity, directly tightening material specifications and gasket interface tolerances for cylinder head cover suppliers. China's GB standards and MIIT fuel consumption regulations add parallel compliance layers for components entering domestic vehicle assembly. ISO 9001 and IATF 16949 quality certifications function as baseline market access requirements across all major supply corridors. Stakeholders must monitor regulatory divergence between emissions jurisdictions to determine whether platform standardization or regional customization offers superior capital efficiency.
Market Dynamics
EPA Tier 4 and Euro 6 emissions standards are compressing sealing tolerances and forcing foundries to retool die-casting lines for higher-grade aluminum alloys, reshaping procurement relationships between Tier-1 suppliers and OEM powertrain divisions.
Growth Catalysts
- Light commercial vehicle production in Mexico:Assembly lines in Monterrey and Saltillo are pulling aluminum casting capacity northward, creating captive supply clusters for cylinder head cover procurement.
- EPA Tier 4 emissions frameworks:Crankcase ventilation integrity mandates are tightening material specifications and extending replacement cycles for sealing interfaces.
- Brazil's engine rebuild sector:Fleet operators in São Paulo and Minas Gerais concentrate aftermarket demand for replacement covers as commercial vehicle parc ages.
Market Restraints
- Primary aluminum price volatility:A380 alloy feedstock costs fluctuate with LME pricing, compressing foundry margins on fixed-price OEM contracts.
- Die-casting equipment concentration:High-tonnage HPDC machinery suppliers cluster in Germany, Japan, and Italy, creating lead-time bottlenecks for capacity expansion.
- Polyamide substitution ceiling:Glass-reinforced nylon 6,6 cannot match aluminum thermal conductivity above 180°C continuous operating temperatures, limiting penetration in heavy-duty cycles.
Strategic Opportunities
- India's two-wheeler electrification lag:Internal combustion motorcycle production persists longer than passenger vehicle segments, sustaining cylinder head cover demand for 100-150cc engines.
- China's MIIT fuel consumption regulations:Lightweighting mandates for passenger vehicles create openings for hybrid aluminum-composite cover designs.
- Additive manufacturing convergence:Binder jetting of aluminum alloys enables topology-optimized baffle geometries that HPDC cannot achieve, opening premium product tiers.
Industry Challenges
- IATF 16949 certification timelines:New entrants face 12-18 month audit cycles to qualify for OEM direct supply, forcing reliance on sub-tier distribution.
- High-pressure die-casting capex intensity:2,500-tonne HPDC cells require $4-6 million per installation, limiting foundry expansion to well-capitalized players.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cylinder Head Cover Market |
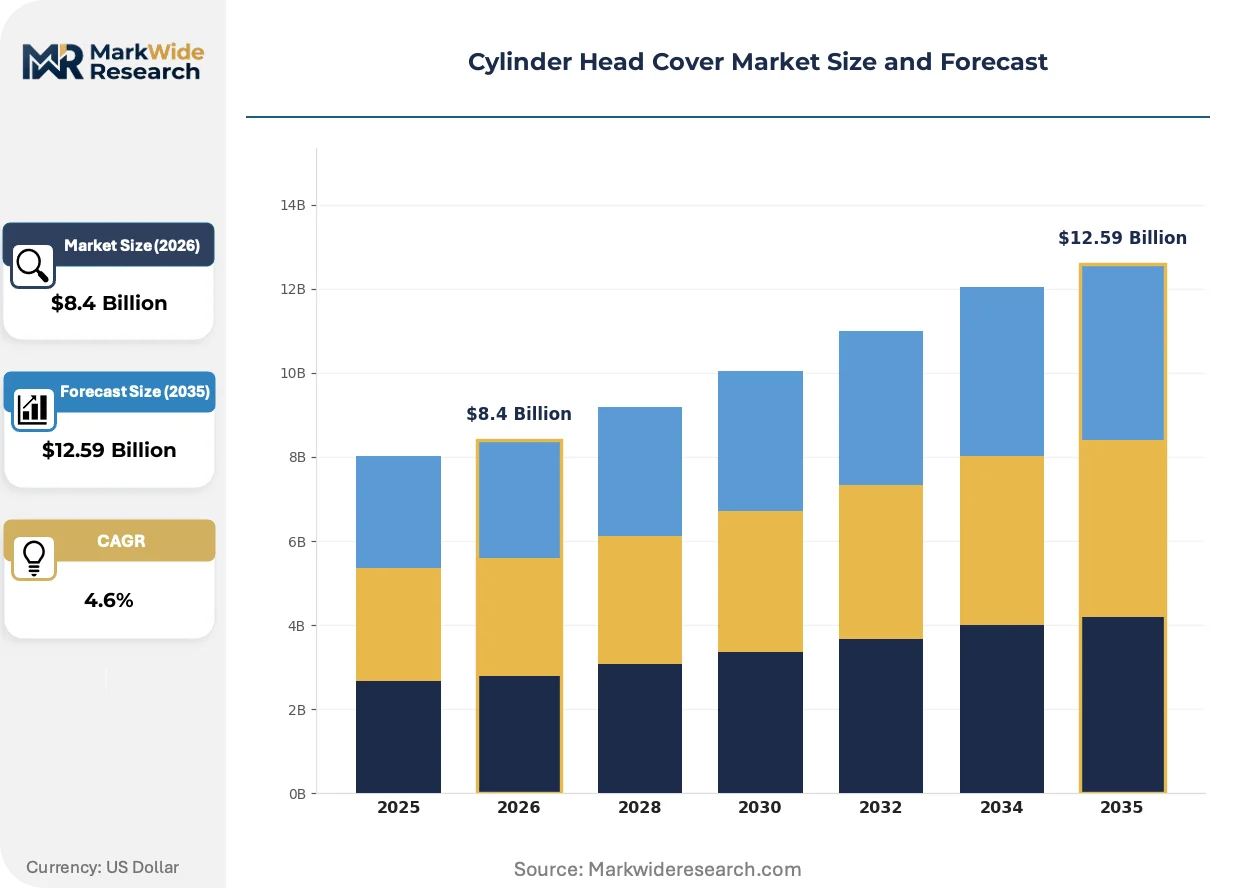
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $12.59 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum, Plastic, Composite, Steel End User: OEMs, Aftermarket Suppliers, Vehicle Assemblers, Repair Workshops Installation Type: Onshore, Mobile, Integrated, Fixed Application: Passenger Vehicles, Commercial Vehicles, Motorcycles, Industrial Engines |
| Companies Covered | Nemak, Linamar, Teksid, ThyssenKrupp, Sandvik Coromant, Rheinmetall, Tupy, Cummins, ElringKlinger, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cylinder Head Cover Market Strategic Shifts
Material substitution and emissions-driven design complexity are fragmenting the traditional aluminum-dominant supply base, creating parallel technology tracks for thermal management and mass reduction priorities.
Glass-reinforced polyamide formulations are migrating from motorcycle valve covers into sub-1.0L passenger vehicle engines where thermal loads permit polymer substitution. Maruti Suzuki and Hyundai Motor India specify these covers for their A-segment platforms, compressing aluminum content per vehicle by 40-60% in the smallest displacement categories. This migration from metal to polymer is forcing traditional foundries to diversify into hybrid material portfolios or cede the sub-1.0L segment entirely.
EPA tailpipe standards and Euro 6 emissions frameworks mandate positive crankcase ventilation systems with integrated oil separation baffles, adding 15-20% to cover complexity and tooling costs. The industrial consequence is a winnowing of supplier bases as smaller foundries lack CAPEX for multi-cavity molds with internal baffle cores. Heavy-duty commercial vehicle segments in the US and EU feel this most acutely, with fleet operators demanding 500,000-mile sealing integrity that only top-tier suppliers can guarantee.
Fleet procurement departments are consolidating cylinder head cover sourcing into powertrain system-level contracts rather than component-level spot purchasing. This behavioral shift disrupts traditional aftermarket distributors and replaces them with OEM-captive service networks managing total cost of ownership. Brazil's long-haul trucking corridors and Mexico's cross-border freight lanes exhibit this most visibly, where integrated maintenance contracts now specify cover replacement intervals tied to oil change cycles rather than failure events.
Cylinder Head Cover Market Segmentation
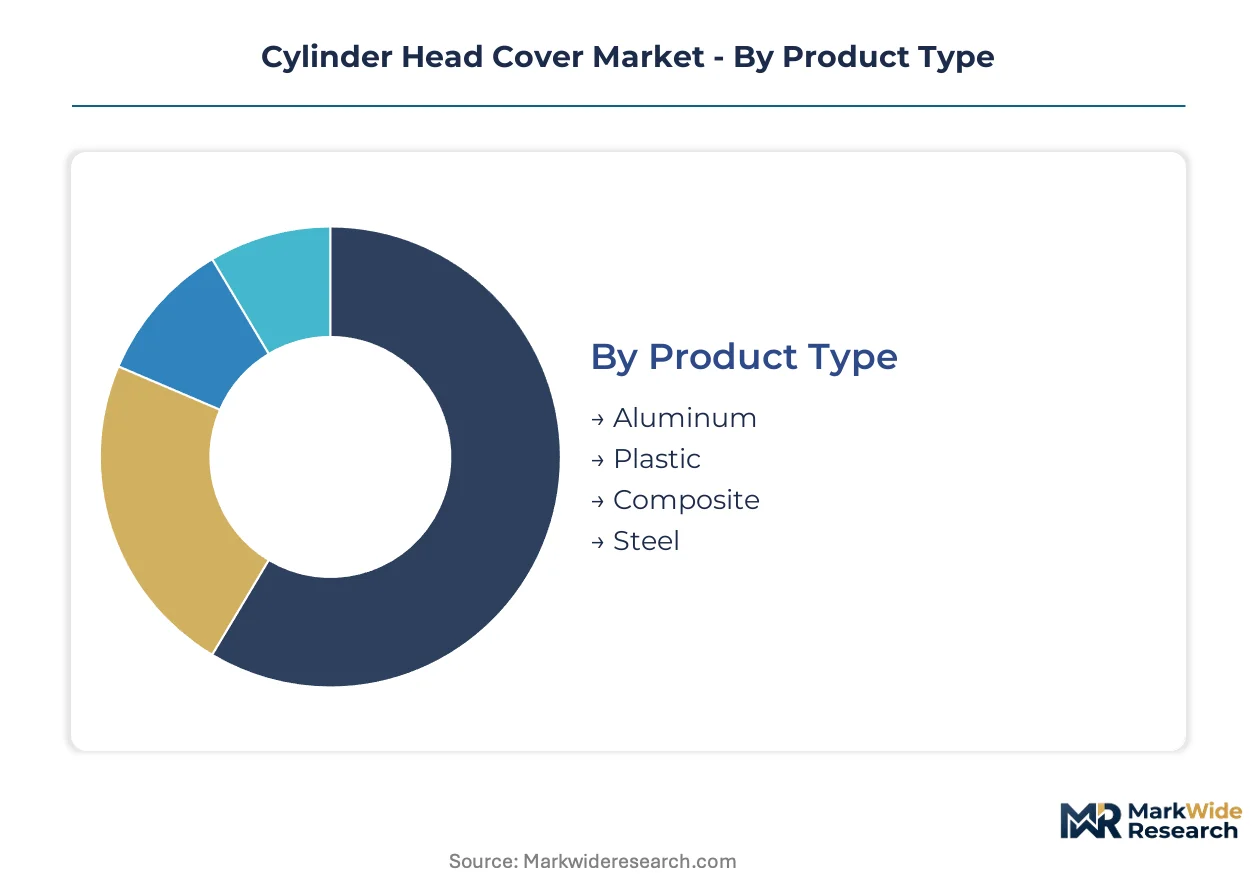
Cylinder head cover procurement patterns diverge sharply across material grades, supply chain tiers, and duty-cycle requirements. Understanding these fault lines reveals where margin pools concentrate and which technology transitions threaten incumbent positioning.
Product Type:
Material selection tracks thermal load tolerance against mass reduction targets across engine displacement categories.
- Aluminum:High-pressure die-cast A380 and AlSi10Mg alloys deliver thermal conductivity above 180°C continuous operating temperatures. OEM powertrain divisions in Germany and Japan specify these for heavy-duty commercial vehicle applications where structural rigidity under thermal cycling prevents polymer substitution.
- Plastic:Glass-reinforced polyamide 6,6 formulations achieve 40-60% mass reduction versus aluminum in sub-1.0L passenger vehicle engines. Maruti Suzuki and Hyundai Motor India source these covers for A-segment platforms where thermal loads permit polymer migration.
- Composite:Hybrid aluminum-polyamide structures balance thermal management with lightweighting for China's MIIT fuel consumption compliance tier.
- Steel:Stamped cold-rolled grades persist in aftermarket replacement channels for aging commercial vehicle parc in Brazil and Eastern Europe.
Established volume favors aluminum; emerging adoption favors plastic.
End User:
Supply chain position determines specification authority and contract structure.
- OEMs:Direct powertrain engineering teams specify material grades, sealing interfaces, and integrated baffle geometries. Tier-1 foundries compete for platform-level supply agreements with 7-10 year contract horizons.
- Aftermarket Suppliers:Brazil's engine rebuild sector and Mexico's cross-border freight operators drive replacement cover demand. Fleet procurement departments consolidate sourcing into system-level contracts tied to oil change intervals rather than failure events.
- Vehicle Assemblers:Contract manufacturers in Mexico's Monterrey-Saltillo corridor pull aluminum casting capacity northward through captive supply arrangements.
- Repair Workshops:Independent service networks in São Paulo and Minas Gerais concentrate demand for standardized replacement covers compatible with multiple engine families.
Direct OEM relationships command premium pricing tiers; aftermarket channels absorb volume fluctuations.
Installation Type:
Assembly methodology shapes tooling investment and field service requirements.
- Onshore:High-volume production lines in Mexico and Thailand integrate cover installation within powertrain assembly sequences.
- Mobile:Field service units in Brazil's long-haul corridors perform cover replacement without engine removal.
- Integrated:Cam cover and ignition coil module consolidation reduces assembly steps for European OEM lean manufacturing programs.
- Fixed:Rebuild facilities in São Paulo operate dedicated installation stations for commercial vehicle engine overhaul cycles.
Integrated designs capture engineering value; mobile installation expands serviceable addressable market.
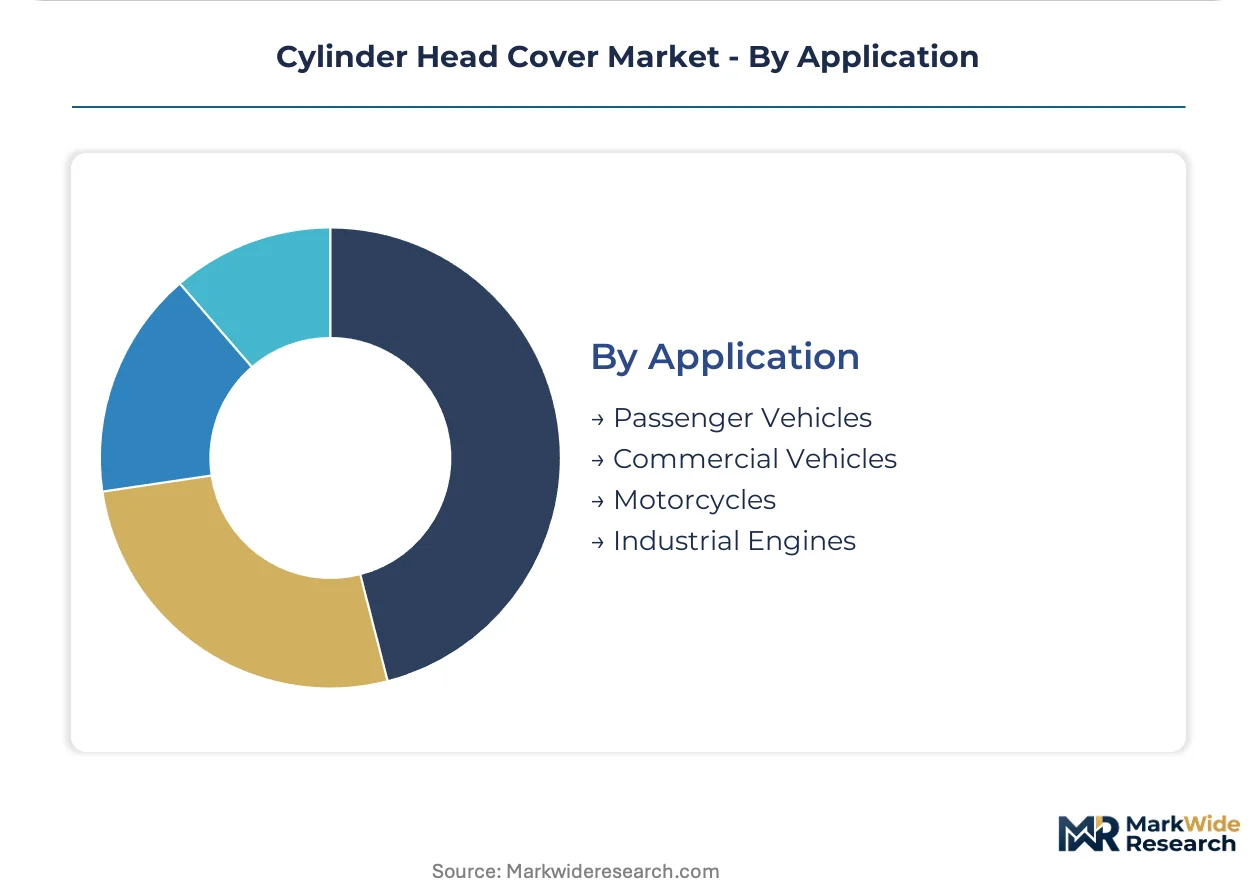
Application:
Duty-cycle severity separates material performance requirements and replacement frequency.
- Passenger Vehicles:A-segment and B-segment platforms drive plastic substitution fastest where thermal budgets permit. China's lightweighting mandates accelerate hybrid material trials.
- Commercial Vehicles:EPA Tier 4 and Euro 6 emissions standards mandate 500,000-mile sealing integrity. Fleet operators in the US and EU consolidate sourcing with top-tier suppliers capable of multi-cavity mold investment.
- Motorcycles:India's two-wheeler electrification lag sustains internal combustion cover demand for 100-150cc engines longer than passenger vehicle segments.
- Industrial Engines:Stationary power generation and agricultural equipment in Southeast Asia specify thicker-walled aluminum covers for dust ingress protection.
Commercial vehicle applications generate superior margin pools; motorcycle volumes extend technology transition timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA Tier 4 emissions standards anchor North American procurement patterns, while Euro 6 frameworks reshape European supply chains. Light commercial vehicle production clusters and aluminum casting infrastructure determine regional competitive positioning.
United States
Commercial vehicle fleet operators demand 500,000-mile sealing integrity under EPA Tier 4 mandates. The Environmental Protection Agency enforces crankcase ventilation integrity standards that tighten material specifications. Detroit-area powertrain engineering teams consolidate sourcing with top-tier suppliers capable of multi-cavity mold investment.
Mexico
Monterrey and Saltillo assembly lines pull aluminum die-casting capacity northward through captive supply arrangements. The Secretariat of Economy oversees automotive manufacturing incentives under the IMMEX program. Northern industrial corridors concentrate Nemak-integrated foundry networks serving North American OEM powertrain divisions.
Germany
ThyssenKrupp anchors German engineering standards in cam cover design for European OEM supply chains. The Kraftfahrt-Bundesamt enforces Euro 6 emissions compliance timelines for commercial vehicle certification. Baden-Württemberg engineering clusters specialize in high-pressure die-casting cells for heavy-duty thermal cycling applications.
China
MIIT fuel consumption regulations drive lightweighting trials for hybrid aluminum-composite cover designs. The Ministry of Industry and Information Technology mandates corporate average fuel consumption reductions through 2025. Yangtze River Delta foundries supply A-segment platforms where thermal budgets permit polymer substitution experiments.
Brazil
São Paulo and Minas Gerais fleet operators concentrate aftermarket demand for replacement covers as commercial vehicle parc ages. ANVISA regulates aftermarket component quality standards for engine rebuild sectors. Long-haul trucking corridors exhibit integrated maintenance contracts specifying cover replacement intervals tied to oil change cycles.
Cylinder Head Cover Market Competitive Environment
Integrated aluminum foundry networks and specialized sealing interface developers split the market between capital-intensive scale players and precision-component specialists. Tier-1 automotive suppliers compete for platform-level supply agreements with 7-10 year contract horizons. Two archetypes dominate: captive foundry operators with backward integration into primary aluminum sourcing, and polymer sealing specialists with thermal stress engineering capabilities. Competitive moves center on multi-cavity mold CAPEX expansion and hybrid material portfolio diversification.
Within the captive foundry tier, Nemak and Teksid exemplify scale-driven positioning through integrated aluminum casting infrastructure. ThyssenKrupp occupies a position bridging German engineering standards with European OEM supply chain anchoring. ElringKlinger represents the sealing specialization archetype, with polymer interface expertise extending service intervals under thermal stress. These three company structures illustrate the market's bifurcation between metallurgical scale and precision polymer engineering.
| Leading Market Players |
|---|
| Nemak |
| Linamar |
| Teksid |
| ThyssenKrupp |
| Sandvik Coromant |
| Rheinmetall |
| Tupy |
| Cummins |
| ElringKlinger |
| Others |
Value Chain & Pricing Dynamics
Primary aluminum price volatility tethered to LME pricing determines both the spread between OEM contract tiers and the geographic clustering of die-casting capacity. A380 alloy feedstock fluctuations compress foundry margins on fixed-price agreements while pushing procurement toward captive supply arrangements in Mexico and northern industrial corridors.
Pricing Analysis
Mexican foundries command 15-20% premiums over Brazilian counterparts due to IMMEX program incentives and proximity to Detroit-area powertrain engineering teams. Contract-based long-term offtake dominates OEM supply, with price differentiation hinging on IATF 16949 certification tier and volume scale commitments. Cost compression in aftermarket channels is intensifying because fleet procurement departments now consolidate sourcing into system-level powertrain contracts. Aftermarket distributors exhibit highest price sensitivity; OEM direct relationships show least sensitivity due to durability specification requirements.
Supply Chain Analysis
A380 and AlSi10Mg alloy feedstock draws from primary aluminum smelters in Canada, Russia, and the Middle East, with secondary recovery operations concentrated in Germany and Japan. High-tonnage HPDC machinery, multi-cavity molds with internal baffle cores, and polymer sealing interface components constitute critical input dependencies. Single-source vulnerability clusters around German, Japanese, and Italian equipment suppliers for 2,500-tonne die-casting cells. Distribution runs through Tier-1 automotive supplier networks with platform-level supply agreements rather than component-level spot purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cylinder head cover market sits at an early-cycle expansion story justified by India's two-wheeler electrification lag sustaining internal combustion demand longer than passenger vehicle segments.
For Market Incumbents: Insulate foundry margins through backward integration into secondary aluminum recovery operations in Monterrey-Saltillo corridors. Lock in 7-10 year platform agreements with Detroit and Baden-Württemberg engineering teams before EPA Tier 4 compliance deadlines tighten supplier qualification windows. Polymer substitution in sub-1.0L engines threatens aluminum volume; hybrid material portfolio diversification is essential. For New Entrants and Emerging Players: Build out additive manufacturing capabilities for topology-optimized baffle geometries that HPDC cannot achieve, targeting premium tiers in heavy-duty commercial vehicle segments. Brazil's engine rebuild sector offers the most penetrable aftermarket channel, with São Paulo fleet operators consolidating maintenance contracts around oil-change-interval replacement schedules. Pursue IATF 16949 certification early to qualify for OEM direct supply rather than sub-tier distribution. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialized sealing interface developers over capital-intensive foundry operators. Long-term viability across the 5-10 year window rests on polymer thermal stress engineering capabilities as much as metallurgical scale. Watch for inflection signals in China's MIIT fuel consumption compliance tier, where hybrid aluminum-composite designs may accelerate technology transition timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Cavity Mold Capacity Expansion | Enables 500,000-mile sealing integrity guarantees for EPA Tier 4 fleet contracts. |
| Hybrid Material Portfolio Diversification | Captures China's MIIT lightweighting mandates through aluminum-polyamide cover designs. |
| Backward Integration into Alloy Recovery | Insulates Mexican foundries from LME price volatility on fixed-price OEM agreements. |
| Additive Manufacturing Capability Buildout | Opens premium product tiers with binder-jetted baffle geometries HPDC cannot replicate. |
| IATF 16949 Certification Investment | Qualifies suppliers for direct OEM relationships with 7-10 year contract horizons. |
Study Parameters
Cross-validation between OEM powertrain engineering interviews and customs/trade data anchors the qualitative findings in observable procurement patterns. Primary fieldwork engaged Tier-1 supplier procurement leads, foundry operations managers, aftermarket distributor executives, and fleet maintenance directors across Mexico, Brazil, Germany, and India. Secondary sources included vehicle production databases, IHS Markit registration data, SEC 10-K filings from listed automotive suppliers, and EPA emissions compliance documentation. Bottom-up triangulation across material-grade demand curves and top-down validation against powertrain assembly forecasts ensured segmentation integrity.
Calibration against historical foundry capacity utilization rates and OEM contract award timelines shaped the projection framework. Segmentation dimensions modeled include material type, end-user supply chain position, installation methodology, and application duty-cycle severity. CAGRs were derived from elasticity-adjusted demand curves across the projection horizon, with specific inputs for India's two-wheeler electrification lag and China's MIIT fuel consumption compliance tier penetration rates.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by state-sponsored Chinese foundries or accelerated polymer substitution by Maruti Suzuki and Hyundai Motor India would shift outcomes. Cross-checking against Yangtze River Delta foundry utilization benchmarks and Brazilian commercial vehicle parc aging curves is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Racing Vehicles Market
Automotive Parts
Italy Automotive Parts Zinc Die Casting Market
Automotive Parts
Indonesia Commercial Vehicles Lubricants Market
Automotive Parts
United States Automotive Glass Market
Automotive Parts
Italy Automotive Parts Magnesium Die Casting Market
Automotive Parts
Automotive Differential Housing Market
Automotive Parts
Automotive Coolant Market
Automotive Parts
Nigeria Automotive Engine Oils Market
Automotive Parts
Automotive Seat Adjusters Market
Automotive Parts
Tappet Market
Automotive Parts
Automotive Lifts Market
Automotive Parts
Road Snow Melt Market
Automotive Parts
Global Intelligent Steering System Market
Automotive Parts
Japan Passenger Vehicles Lubricants Market
Automotive Parts
Electric Parking Brake Market
Automotive Parts
Malaysia Brake Pads Market