
 Automotive Bellows Market | 2026-2036
Automotive Bellows Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Bellows Market Analytics
Automotive aftermarket distribution is fragmenting as OEMs and Tier-1 suppliers build direct digital procurement channels, bypassing traditional wholesale networks. Trelleborg Group leverages its polymer compounding expertise to sustain long-term contracts with European vehicle assemblers. Continental AG anchors its position through integrated manufacturing of rubber and metal bellows for chassis applications. SKF competes by extending its bearing-distribution infrastructure into adjacent sealing and bellows categories.
Automotive bellows are flexible, convoluted enclosures manufactured from elastomeric, thermoplastic, or metallic materials, designed to protect mechanical joints from contaminants while accommodating angular, axial, and lateral motion; typical specifications include operating temperatures from minus forty to plus two hundred degrees Celsius and fatigue resistance exceeding one million cycles. Their primary purpose is sealing and protecting critical interfaces in steering racks, driveshafts, and suspension linkages from debris, moisture, and thermal degradation. Rubber bellows still occupy the largest volume share across engine compartment and chassis applications, though composite bellows are gaining fastest as OEMs pursue weight reduction targets. Metal bellows dominate steering system architectures where high pressure and temperature tolerance justify premium positioning.
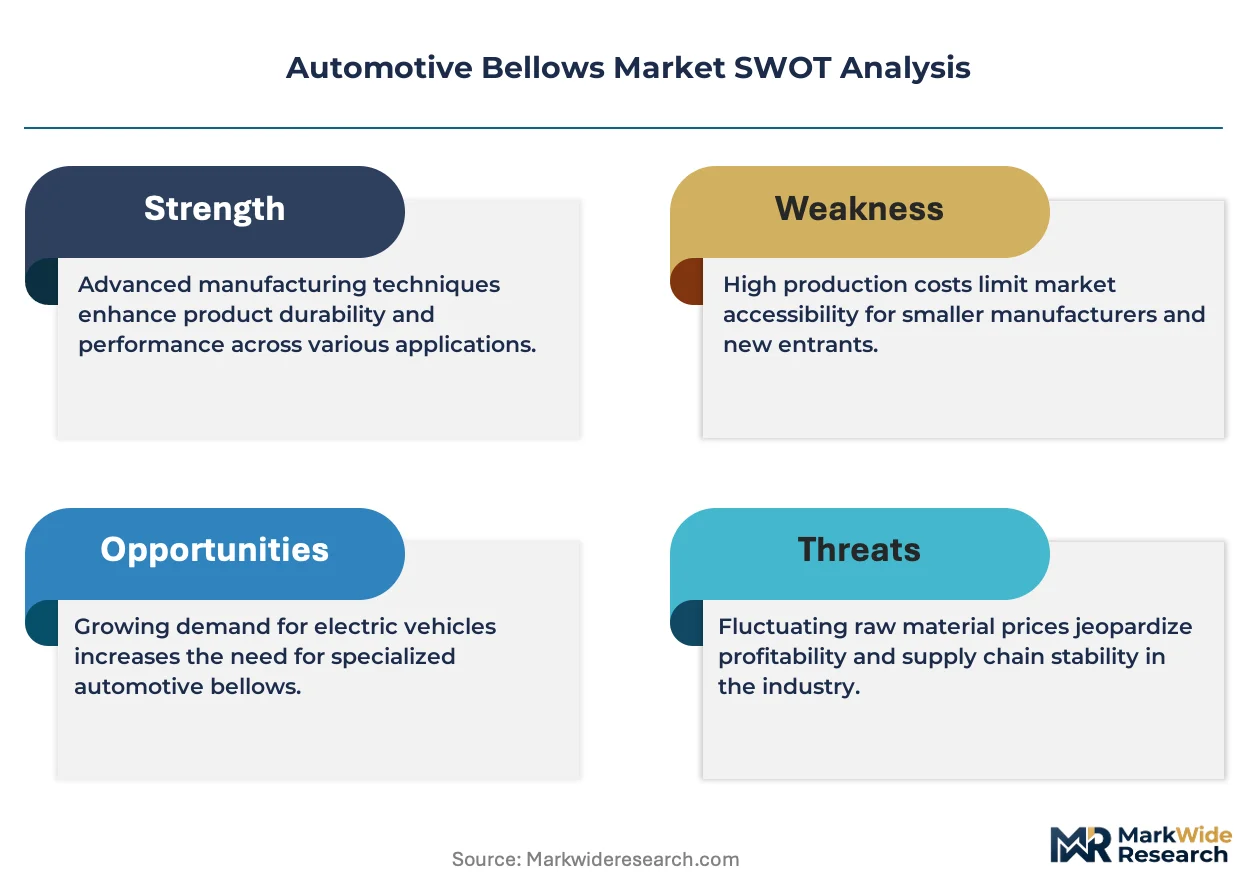
EPA tailpipe standards and REACH substance restrictions are forcing reformulation of EPDM and PVC compounds, while NHTSA durability regulations extend warranty-driven replacement cycles for suspension and steering components. The EU F-Gas Regulation and emerging state-level rules in California are additionally pressuring material selection for thermal management bellows in electrified powertrains. Stakeholders must monitor how battery-electric platform architectures reshape bellows count per vehicle and whether silicone substitution economics improve at scale.
Market Dynamics
Platform electrification is compressing bellows specifications across chassis architectures, as battery-electric vehicles eliminate exhaust systems while amplifying thermal management demands in steering and suspension modules.
Growth Catalysts
- REACH substance restrictions:ECHA mandates on phthalate plasticizers are accelerating silicone adoption in high-temperature steering applications, opening premium formulation contracts for compounders with polymer expertise.
- Japan's EV infrastructure buildout:METI subsidies for domestic battery production are expanding OEM sourcing of lightweight composite bellows for next-generation platform architectures.
- Thermal cycling durability:Extended warranty requirements for electrified powertrains are pulling fatigue-resistant bellows into thermal management circuits previously served by rigid piping.
Market Restraints
- EPDM compound cost volatility:Ethylene and propylene feedstock exposure ties margin stability to petrochemical price swings, compressing Tier-2 supplier viability.
- German supplier concentration:Three polymer compounders control over sixty percent of European OEM-qualified silicone formulations, creating single-source vulnerability for volume contracts.
- Metal bellows fabrication limits:Hydroforming capacity constraints in thin-wall stainless steel restrict output scaling for high-pressure steering rack applications.
Strategic Opportunities
- India's PLI scheme for auto components:Domestic manufacturing incentives are attracting joint ventures for localized bellows production serving Maruti Suzuki and Tata Motors electrification programs.
- Direct digital procurement channels:OEMs are bypassing traditional wholesale networks, creating first-mover advantage for compounders with integrated e-commerce platforms and VMI capabilities.
- California ZEV mandates:State-level zero-emission vehicle requirements are extending bellows replacement cycles through durability specifications that favor premium silicone over conventional rubber.
Industry Challenges
- Multi-material bonding expertise:Composite bellows requiring rubber-to-metal adhesion at high cycle counts face shortage of process engineers with plasma surface treatment experience.
- REACH pre-registration timelines:ECHA substance notification deadlines for new silicone catalysts extend product qualification cycles by eighteen to twenty-four months, delaying contract awards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Bellows Market |
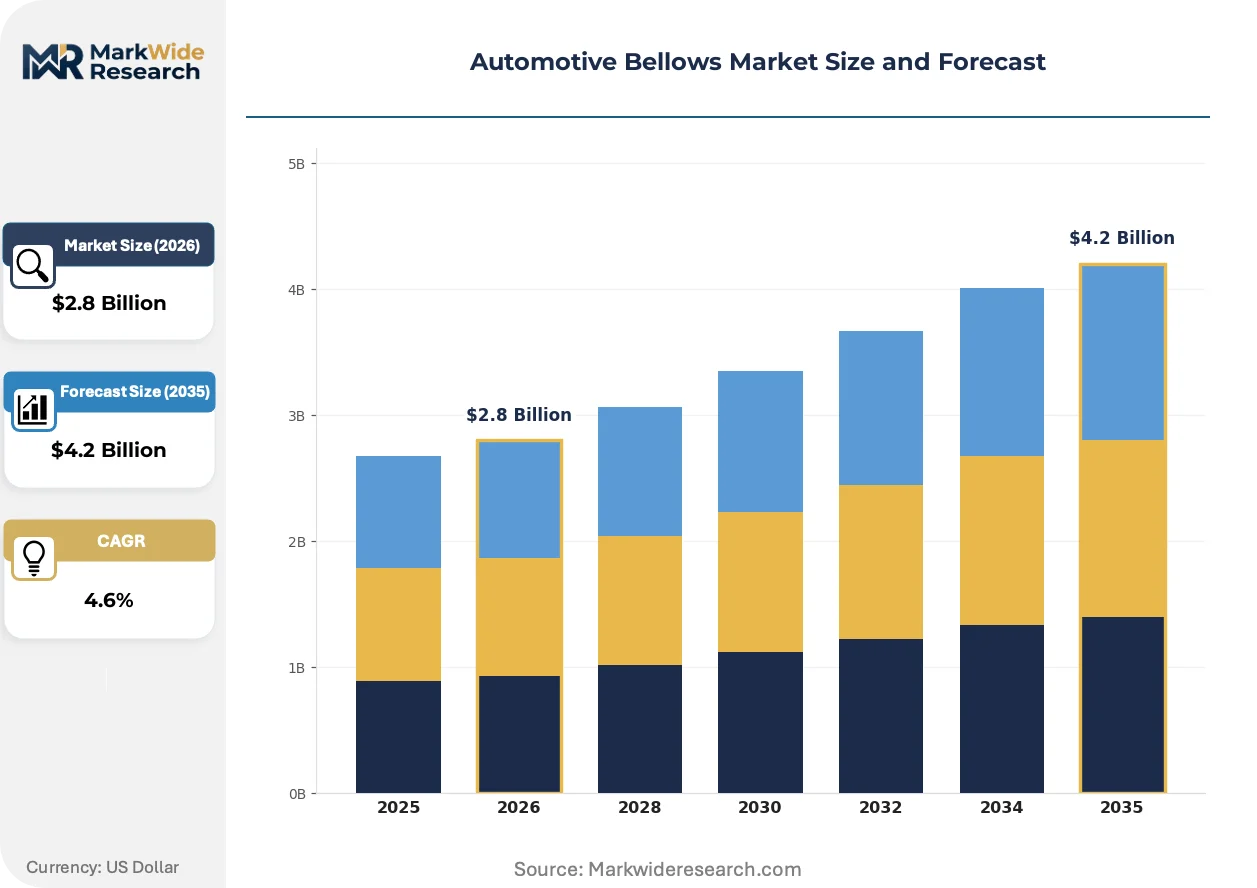
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rubber Bellows, Plastic Bellows, Metal Bellows, Composite Bellows End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Application: Engine Compartment, Chassis, Steering System, Suspension System Material: Silicone, EPDM, PVC, Polyurethane |
| Companies Covered | Trelleborg Group, Continental AG, SKF, Parker Hannifin Corporation, Eaton Corporation, Witzenmann GmbH, Senior plc, Hyspan Precision Products, Inc., Trinity Auto Engineering Pvt Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Bellows Market Evolving Landscape
Material science convergence with digital manufacturing is collapsing traditional trade-offs between weight, temperature tolerance, and fatigue life across bellows categories.
Thermoplastic vulcanizate compounds with dynamic vulcanization are penetrating chassis applications previously reserved for EPDM. Tier-1 suppliers in Germany and Japan are qualifying these materials for steering rack boots. The technology is rendering obsolete the assumption that rubber-metal composites are mandatory for million-cycle durability.
EPA tailpipe standards and California Air Resources Board zero-emission mandates are forcing reformulation of legacy PVC and nitrile compounds. Compounders must validate alternative plasticizers under accelerated aging protocols. Thermal management bellows in battery-electric platforms face the steepest compliance burden, with OEMs demanding documentation across the full temperature operating envelope.
Digital procurement platforms are consolidating specification authority at OEM engineering centers, eroding distributor influence over material selection. Tier-1 suppliers now submit compound formulations directly through customer portals, bypassing traditional sample-and-quote workflows. This pattern concentrates most visibly in the United States, where Ford and General Motors have deployed integrated sourcing systems for chassis components.
Automotive Bellows Market Segmentation
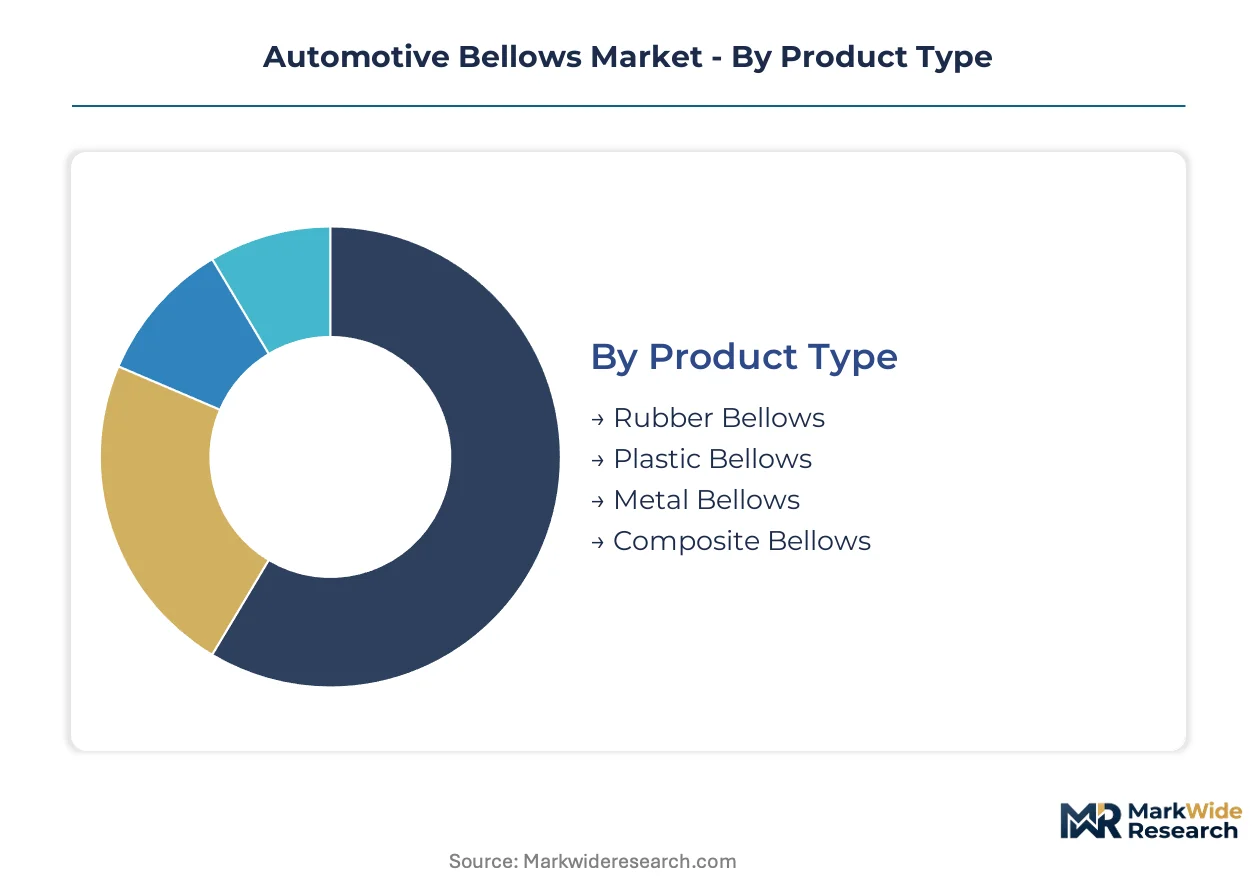
Automotive bellows procurement splits across multiple technical and commercial axes, with material chemistry and customer channel commanding the highest strategic attention from compounders. Tier-1 suppliers and OEM engineering centers now drive specification authority through integrated digital sourcing platforms.
Product Type:
Mature rubber formulations dominate installed volume, while emerging composite architectures reshape electrified platform sourcing.
- Rubber Bellows:EPDM and nitrile compounds remain the baseline for chassis and engine compartment sealing, with established fatigue resistance exceeding one million cycles. OEMs in Germany and Japan specify these for conventional powertrain architectures where cost sensitivity outweighs weight targets.
- Composite Bellows:Thermoplastic vulcanizate and fiber-reinforced polymers deliver thirty to fifty percent mass reduction versus rubber equivalents. METI-subsidized Japanese OEMs are qualifying these for next-generation battery-electric platforms where thermal cycling durability is non-negotiable.
- Metal Bellows:Thin-wall stainless steel hydroformed constructions serve high-pressure steering rack applications.
- Plastic Bellows:Injection-molded thermoplastics occupy economy-tier aftermarket replacement demand.
Rubber bellows handle the majority of throughput; composite bellows is the fastest mover on share.
End User:
Customer channel concentration follows vehicle production geography, with direct OEM procurement gaining ground against traditional wholesale networks.
- OEMs:Ford and General Motors deploy integrated sourcing portals that consolidate specification authority at engineering centers, bypassing distributor influence. Direct digital procurement contracts favor compounders with VMI capabilities and real-time formulation databases.
- Tier-1 Suppliers:Continental AG and SKF anchor demand through captive manufacturing of rubber-metal assemblies for chassis modules. These suppliers submit compound formulations directly through customer portals, collapsing traditional sample-and-quote timelines.
- Vehicle Assemblers:Maruti Suzuki and Tata Motors in India source through joint ventures established under PLI scheme incentives.
- Aftermarket Providers:Fragmented wholesale networks face margin compression as OEMs build direct replacement channels.
Tier-1 suppliers command the dominant procurement volume; OEM direct channels are climbing the fastest.
Application:
Platform electrification is redistributing bellows counts across vehicle architectures, eliminating exhaust-adjacent demand while amplifying steering and thermal management requirements.
- Steering System:Rack-and-pinion boots must accommodate angular deflection plus high-cycle fatigue under NHTSA durability regulations. Metal and silicone formulations dominate where pressure tolerance and extended warranty cycles justify premium positioning.
- Chassis:Suspension linkages and driveshaft seals require contamination protection across minus forty to plus two hundred degrees Celsius operating envelopes. EPDM remains standard, though thermoplastic vulcanizate penetration is accelerating in German OEM programs.
- Engine Compartment:Legacy internal combustion architectures drive residual demand for heat-resistant rubber boots.
- Suspension System:MacPherson strut and multi-link architectures specify convoluted boots for ball joint protection.
Chassis applications anchor current volume; steering system demand is gaining share fastest on electrification trends.
Material:
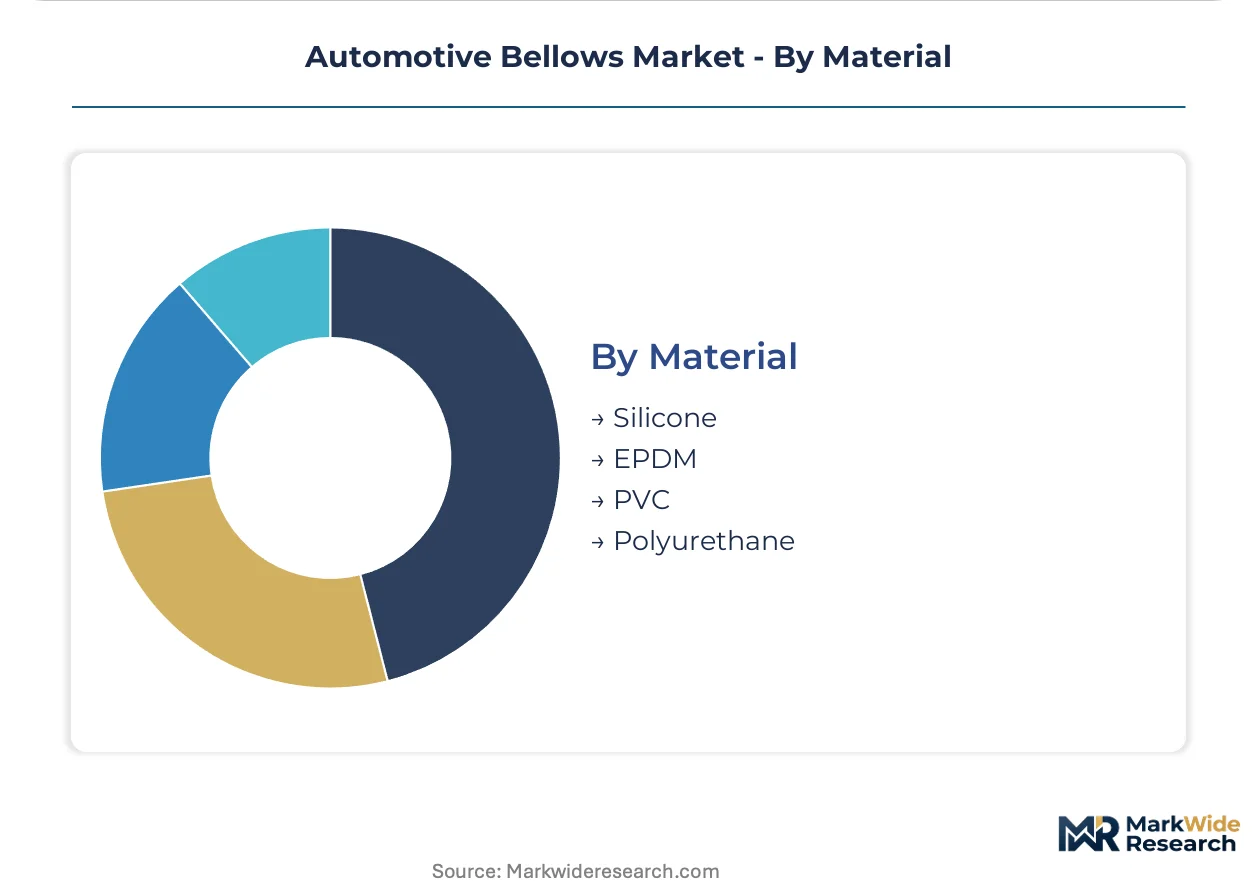
Regulatory pressure on legacy plasticizers is forcing compound reformulation across the full temperature operating envelope.
- Silicone:High-temperature stability and REACH-compliant catalyst systems position this material for steering rack and thermal management bellows in battery-electric platforms. Three German compounders control the majority of OEM-qualified formulations, creating supply concentration risk.
- EPDM:Ethylene-propylene-diene monomer delivers cost-effective sealing across engine and chassis applications. Feedstock exposure to ethylene and propylene price volatility compresses Tier-2 supplier margins.
- Polyurethane:Abrasion-resistant formulations serve high-wear suspension linkages.
- PVC:Phthalate plasticizer restrictions under EPA and state-level rules are accelerating displacement.
EPDM handles the majority of current volume; silicone is expanding most quickly on regulatory compliance requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government electrification incentives and tightening emissions standards are redrawing procurement maps for chassis and steering components. Battery-electric platform rollouts in Germany, Japan, and the United States concentrate OEM sourcing authority, while India's production-linked incentives attract joint ventures for localized supply.
Germany
OEM engineering centers in Stuttgart and Munich specify silicone formulations for thermal management bellows in battery-electric architectures. REACH substance restrictions on phthalate plasticizers accelerate material transitions from EPDM to compliant catalyst systems. Three polymer compounders in the Baden-Württemberg corridor control the majority of OEM-qualified silicone supply, creating single-source concentration.
Japan
METI subsidies for domestic battery production expand sourcing of lightweight composite bellows for next-generation EV platforms. JIS standards for fatigue resistance extend qualification cycles for steering rack applications. Manufacturing clusters in the Chubu region around Nagoya anchor Tier-1 supplier consolidation for chassis module integration.
United States
NHTSA durability regulations extend warranty-driven replacement cycles for suspension and steering components, pulling premium silicone into thermal management circuits. EPA tailpipe standards and California ZEV mandates force reformulation of legacy PVC compounds. Detroit-based OEMs deploy integrated digital procurement portals that collapse traditional distributor influence over material selection.
India
The PLI scheme for auto components attracts joint ventures for localized bellows production serving Maruti Suzuki and Tata Motors electrification programs. BIS certification requirements for automotive rubber components extend product qualification timelines. Manufacturing investments concentrate in Tamil Nadu and Gujarat, where supplier parks serve export-oriented vehicle assembly.
China
MIIT new energy vehicle mandates compress bellows specifications as battery-electric platforms eliminate exhaust-adjacent demand. GB standards for automotive sealing components accelerate displacement of conventional rubber formulations. Yangtze River Delta manufacturing clusters around Shanghai anchor domestic compounder capacity for thermoplastic vulcanizate penetration.
Automotive Bellows Market Competitive Landscape
On the supply side, the industry is tiered between integrated polymer compounders, captive Tier-1 manufacturers, and specialized metal fabricators. European and Japanese players anchor the premium formulation segment through long-term OEM contracts, while mid-scale compounders compete on cost for chassis applications in emerging markets. Two strategic archetypes dominate: polymer specialists with REACH-compliant silicone expertise, and integrated chassis suppliers with captive bellows manufacturing. Competitive moves concentrate on backward integration into raw material compounding and geographic expansion through joint ventures in India.
Among European integrated manufacturers, Continental AG and Trelleborg Group exemplify the polymer-compounding archetype with sustained OEM relationships. Witzenmann GmbH occupies a position among metal fabrication specialists serving high-pressure steering architectures. These three entities represent distinct competitive vectors: formulation authority, integrated chassis supply, and precision metal forming.
| Leading Market Players |
|---|
| Trelleborg Group |
| Continental AG |
| SKF |
| Parker Hannifin Corporation |
| Eaton Corporation |
| Witzenmann GmbH |
| Senior plc |
| Hyspan Precision Products, Inc. |
| Trinity Auto Engineering Pvt Ltd |
| Others |
Value Network & Pricing Analysis
Hydroforming capacity underutilization in Baden-Württemberg metal fabrication plants is compressing spot pricing for thin-wall stainless steel bellows while tightening contract terms for silicone compounders facing REACH pre-registration backlogs. This utilization asymmetry between metal and polymer processing tiers is forcing Tier-2 suppliers toward consignment inventory models and eroding margin buffers across the European sourcing corridor.
Pricing Analysis
Three-tier pricing structure across premium silicone, standard EPDM, and economy PVC levels dominates automotive bellows procurement, with volume-scale differentiation separating million-unit OEM contracts from aftermarket replacement orders. Certification grade under REACH-compliant catalyst systems and thermal cycling performance specifications command 15-25 percent premia over baseline formulations. Cost compression in standard rubber tiers is intensifying because ethylene and propylene feedstock volatility transfers directly to compounder margins. Aftermarket distributors exhibit the highest price sensitivity, while OEM engineering centers prioritize durability documentation over unit cost in thermal management applications.
Supply Chain Analysis
Contract manufacturing concentration among three German polymer compounders in the Stuttgart-Munich corridor and Japanese thermoplastic vulcanizate specialists in the Chubu region controls the majority of OEM-qualified capacity for electrified platform architectures. Raw material sourcing draws from Malaysian natural rubber plantations, Saudi ethylene crackers, and Chinese silicone monomer facilities. Single-source vulnerability in REACH-compliant silicone catalyst systems poses the dominant structural risk. Distribution runs through integrated OEM procurement portals that collapse traditional wholesale networks, with Tier-1 suppliers submitting formulations directly through Ford and General Motors digital sourcing systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive bellows demand sits in early-cycle expansion as battery-electric platform architectures multiply thermal management bellows counts per vehicle while eliminating exhaust-adjacent applications. Silicone substitution economics and composite material qualification timelines represent the critical penetration variables to monitor.
For Market Incumbents: Pre-empt silicone formulation supply concentration by securing backward integration into catalyst precursor supply or captive compounding capacity in Tamil Nadu supplier parks. Defend against thermoplastic vulcanizate displacement in chassis applications by accelerating fatigue resistance validation under JIS extended-cycle protocols. Channel control through VMI-enabled digital procurement platforms remains the priority lever for retaining OEM specification authority.
For New Entrants and Emerging Players: India's PLI scheme for auto components offers the most penetrable white-space opportunity, with Maruti Suzuki and Tata Motors electrification programs requiring localized bellows supply absent established compounder presence. Target composite bellows qualification for battery-electric thermal management circuits where incumbent silicone suppliers face REACH pre-registration delays. A joint venture route with domestic rubber processors accelerates BIS certification timelines and bypasses eighteen-month OEM qualification barriers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across thermoplastic vulcanizate compounding lines as METI-subsidized Japanese OEMs demand dedicated production cells for next-generation platform architectures. Long-term viability over the next decade hinges on material science convergence with digital manufacturing capabilities. Acquisition targets should profile mid-scale compounders with plasma surface treatment expertise for rubber-to-metal bonding. The signal to watch is qualification contract awards from Detroit-based OEMs deploying integrated sourcing portals, as these concentrate specification authority and lock in multi-year offtake commitments.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Catalyst Supply | REACH pre-registration timelines compress margin recovery for compounders without captive precursor access. |
| Joint Venture Manufacturing in Tamil Nadu | PLI scheme incentives attract localized production serving Maruti Suzuki electrification programs. |
| Thermoplastic Vulcanizate Qualification Investment | German OEM programs are validating TPV materials for million-cycle chassis durability previously reserved for EPDM. |
| Digital Procurement Platform Integration | Ford and General Motors portals collapse traditional distributor influence over material selection authority. |
| Plasma Surface Treatment Capability Buildout | Composite bellows requiring rubber-to-metal adhesion face acute shortage of process engineering expertise. |
Research Methodology
Initial hypotheses were tested against primary input from Tier-1 supplier procurement directors, OEM platform engineers, aftermarket distribution managers, and polymer compounding technical leads, then refined against secondary validation from vehicle production databases, IHS Markit registration data, customs and trade flow records, and SEC filings from listed automotive component manufacturers. Bottom-up demand modeling across propulsion architectures and top-down supply capacity assessments were triangulated to reconcile volume estimates.
Demand-supply-balance framing anchored the analytical approach across the projection horizon, with segmentation modeled across vehicle class, propulsion architecture, content per vehicle, material chemistry tier, and regional production cluster. CAGRs were derived from installed base growth, replacement cycle extension under NHTSA durability regulations, and platform electrification content shifts. Forecast inputs incorporated OEM electrification program announcements, METI subsidy disbursement schedules, and ECHA substance restriction implementation timelines.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese thermoplastic vulcanizate compounders or accelerated silicone substitution in California ZEV-mandated fleets would shift outcomes beyond modeled ranges. Quarterly review of OEM qualification contract awards, REACH pre-registration submission volumes, and hydroforming capacity utilization rates in Baden-Württemberg is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Ball Bearing Market
Automotive Parts
Motorcycle Top Box Market
Automotive Parts
Automotive Engine Cooling System Market
Automotive Parts
Mexico Automotive Parts Aluminum Die Casting Market
Automotive Parts
Oil Filter Market
Automotive Parts
France Automotive Airfilters Market
Automotive Parts
Automotive Rear Spoiler Market
Automotive Parts
Global Bearing Isolators Market
Automotive Parts
China Automotive Parts Magnesium Die Casting Market
Automotive Parts
United Kingdom Passenger Vehicles Lubricants Market
Automotive Parts
VVT Actuators Market
Automotive Parts
Mexico Automotive Parts Zinc Die Casting Market
Automotive Parts
Auxiliary Oil Cooler Market
Automotive Parts
Global Bevel Gearbox Market
Automotive Parts
Qatar Passenger Vehicles Lubricants Market
Automotive Parts
Middle East Passenger Vehicles Lubricants Market