
 UAE Automotive Lubricants Market | 2026-2036
UAE Automotive Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Automotive Lubricants Market Analytics
Fleet operators is bifurcating demand away from individual repair workshops across the UAE automotive lubricants landscape. ADNOC leverages its upstream refinery integration to secure feedstock cost advantages for domestic blending operations. Royal Dutch Shell competes through its technology leadership in synthetic engine oil formulations tailored to Gulf climate extremes. TotalEnergies anchors its position via extensive service station distribution across Abu Dhabi and Dubai corridors.
Automotive lubricants comprise refined base oils blended with performance additives to reduce friction, dissipate heat, and prevent wear in powertrain systems operating at temperatures exceeding 150°C. Their primary commercial purpose is extending engine life and maintaining fuel efficiency under severe thermal and dust-laden conditions characteristic of Arabian Peninsula operating environments. Engine oil commands the largest revenue pool among product types due to mandatory drain intervals and high vehicle parc turnover. Aftermarket providers represent the fastest-growing end-user channel as independent workshops expand beyond OEM-captive service networks. Passenger vehicles absorb the majority of volume, though heavy-duty trucks generate superior per-unit margins through specialized long-drain formulations.
MOHAP enforces product registration and quality certification for all lubricants sold in the UAE, while ESMA mandates SAE viscosity grade labeling and performance testing against API and ACEA standards. These frameworks elevate compliance costs for smaller blenders but create barrier effects that reinforce established suppliers with in-house testing laboratories. Stakeholders must monitor how impending EU-Gulf alignment talks on carbon border adjustments could reshape base oil sourcing economics for UAE formulators.
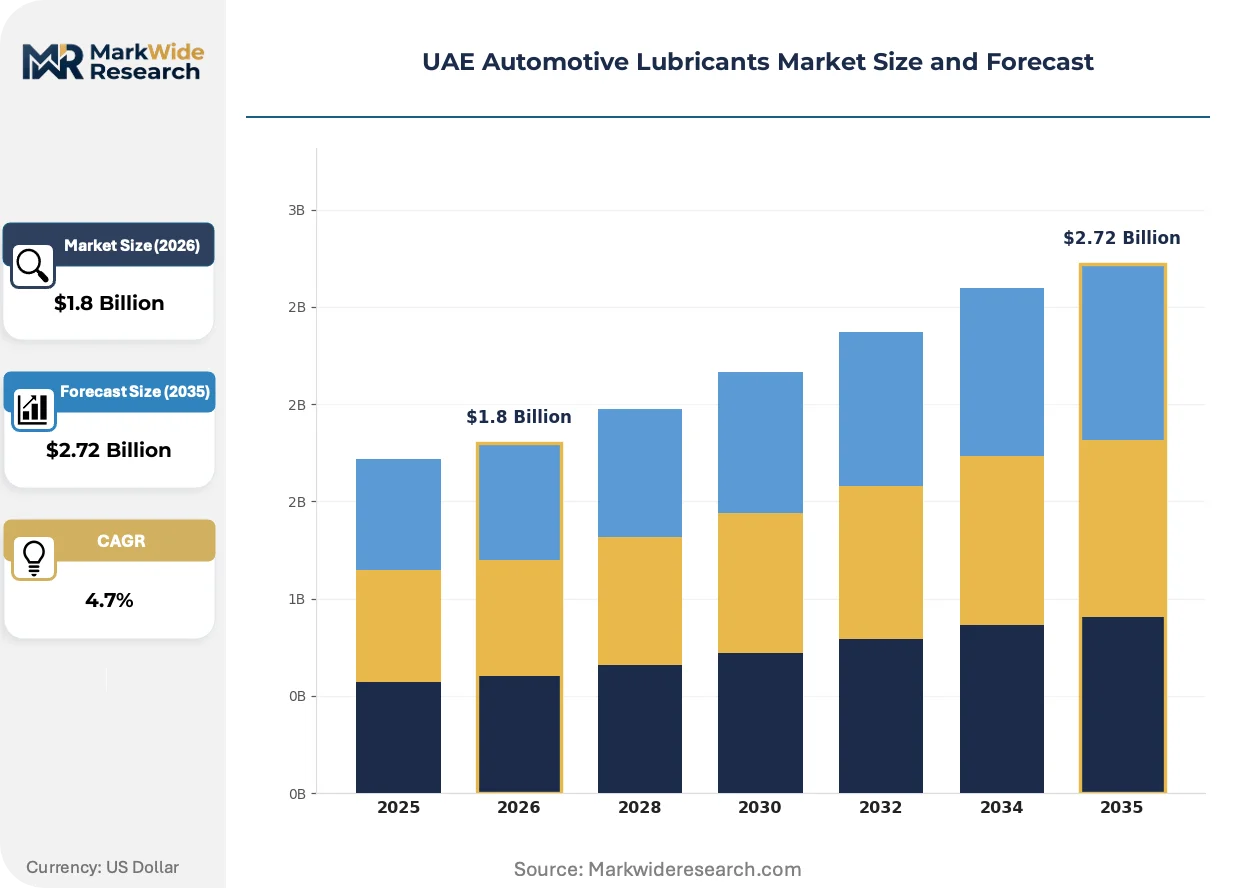
Market Dynamics
Fleet consolidation across Dubai and Abu Dhabi commercial corridors is compressing purchasing power into fewer procurement desks. This concentration is reshaping supplier relationships and margin structures for lubricant blenders serving the Emirates.
Growth Catalysts
- MOHAP Registration Mandates:Strict product quality certification requirements are filtering out substandard imports and elevating demand for tested, compliant formulations from established suppliers.
- Logistics Fleet Modernization:Heavy-duty commercial operators are extending drain intervals through synthetic oil adoption, driving premium product volume in Jebel Ali and Mussafah industrial zones.
- Group III Base Oil Availability:Regional refinery upgrades are improving feedstock access for high-performance lubricant production within the Gulf supply basin.
Market Restraints
- API Group II/III Base Oil Price Volatility:Feedstock costs tied to regional crude differentials create margin compression for independent blenders without captive supply.
- ESMA Labeling Compliance Burden:Mandatory SAE viscosity grade verification and performance testing against ACEA standards impose fixed costs that disadvantage smaller market entrants.
- Synthetic Lubricant Substitution Pressure:Extended-drain formulations reduce total volume demand per vehicle-kilometer, constraining revenue growth in mature segments.
Strategic Opportunities
- Ras Al Khaimah Industrial Expansion:Emerging manufacturing and logistics clusters in the northern Emirates offer first-mover positioning for lubricant distribution networks.
- EV Thermal Management Fluids:Electric vehicle battery and e-axle cooling requirements are creating new formulation categories beyond traditional engine oils.
- Carbon Border Adjustment Alignment:Anticipated EU-Gulf regulatory convergence on base oil carbon intensity metrics favors suppliers with low-carbon feedstock sourcing capabilities.
Industry Challenges
- Formulation Chemist Talent Scarcity:Gulf-based lubricant laboratories face recruitment gaps for specialists in high-temperature additive chemistry and tribology.
- Retrofitting Legacy Workshop Infrastructure:Independent service stations in Sharjah and Ajman require capital investment to handle synthetic oil disposal and storage specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Automotive Lubricants Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Brake Fluid, Grease End User: OEMs, Aftermarket Providers, Repair Workshops, Fleet Operators Application: Passenger Vehicles, Commercial Vehicles, Heavy-Duty Trucks, Motorcycles Distribution Channel: Online Retailers, Auto Parts Stores, Service Stations, Wholesalers |
| Companies Covered | Royal Dutch Shell, Exxon Mobil Corporation, ADNOC, Chevron Corporation, DANA Lubricants Factory LLC, Emirates Lube Oil Co. Ltd, TotalEnergies, Gulf Oil Middle East Limited, EPPCO Lubricants, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Automotive Lubricants Market Evolving Landscape
Climate-adaptive formulation science and procurement centralization are redefining competitive advantage in UAE automotive lubricants. Technology trajectories now prioritize thermal stability under severe operating conditions.
Synthetic polyalphaolefin (PAO) and ester-based lubricants are decomposing the traditional mineral oil dominance in heavy-duty fleet applications. Logistics operators running Dubai-Abu Dhabi corridor routes are adopting these formulations to extend drain intervals beyond 100,000 kilometers. This shift is compressing volume-based revenue models while expanding per-liter margin capture for technology-leading suppliers.
MOHAP and ESMA are tightening concurrent enforcement of product registration, quality certification, and environmental labeling standards. These frameworks are elevating compliance costs and accelerating market exit for non-compliant importers. Smaller blending operations in the northern Emirates are consolidating testing capabilities or exiting consumer segments entirely.
Centralized fleet procurement desks are displacing fragmented workshop purchasing across UAE commercial vehicle segments. Large logistics operators are negotiating direct supply agreements with blenders, bypassing traditional distributor networks. This concentration is most visible in Dubai's Jebel Ali logistics corridor, where multinational fleet managers now control lubricant specification and supplier selection.
UAE Automotive Lubricants Market Segmentation
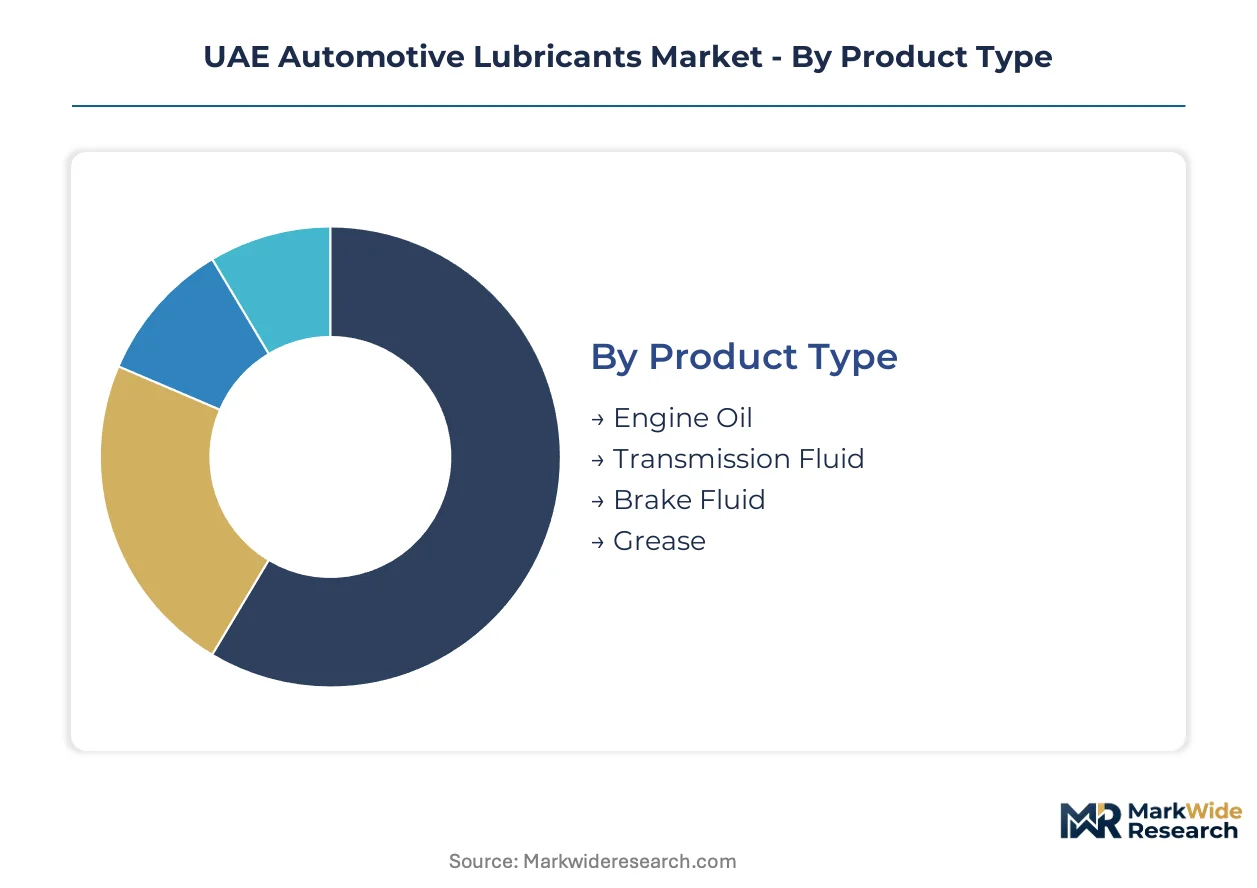
Segmentation in the UAE automotive lubricants market reveals how regulatory frameworks and procurement centralization concentrate value across distinct product tiers and channel structures. Understanding these divisions exposes where MOHAP compliance costs and fleet purchasing power reshape competitive dynamics.
Product Type:
MOHAP registration mandates and ESMA labeling requirements create divergent compliance burdens across formulation categories, filtering market participation by technical capability.
- Engine Oil:Refined base oils blended with detergent-dispersant and anti-wear additive packages dominate lubricant procurement budgets across UAE fleet operators. Dubai's commercial vehicle corridors and Abu Dhabi's industrial transport zones absorb the majority of high-viscosity formulations as logistics networks modernize drain interval specifications.
- Transmission Fluid:Synthetic ATF and CVT formulations incorporate friction modifiers and oxidation inhibitors calibrated for Gulf climate thermal stress. Heavy-duty truck operators in Jebel Ali and Mussafah industrial zones are specifying long-life formulations to synchronize with extended engine oil drain programs.
- Brake Fluid:Glycol-ether based DOT 3 and DOT 4 formulations meet SAE J1703 and FMVSS 116 specifications enforced through ESMA quality certification protocols.
- Grease:Lithium complex and calcium sulfonate thickened lubricants serve chassis and wheel bearing applications in Sharjah and Ajman independent workshops facing synthetic oil handling infrastructure gaps.
Established volume favors Engine Oil; emerging adoption favors Transmission Fluid.
End User:
Procurement centralization is compressing purchasing decisions into fewer desks, restructuring supplier relationships across the Emirates.
- OEMs:Factory-fill specifications for new vehicle production require first-fill lubricants meeting ACEA and API standards with full MOHAP registration documentation. Abu Dhabi assembly operations and Dubai import distribution centers specify formulations with extended warranty compliance.
- Aftermarket Providers:Independent distributors and retail chains expanding beyond OEM-captive service networks are climbing the fastest as vehicle parc turnover accelerates workshop demand for certified products.
- Repair Workshops:Fragmented independent service stations in northern Emirates face capital investment requirements for synthetic oil storage and disposal compliance.
- Fleet Operators:Centralized procurement desks at logistics companies running Dubai-Abu Dhabi corridor routes negotiate direct blender agreements, bypassing traditional distribution tiers.
Volume concentration sits with Fleet Operators; margin expansion sits with Aftermarket Providers.
Application:
Operating severity and duty cycles determine formulation premiumization potential across vehicle categories.
- Passenger Vehicles:High vehicle parc turnover in Dubai and Abu Dhabi urban corridors sustains baseline demand for semi-synthetic and mineral engine oils through retail and service station channels.
- Commercial Vehicles:Light-duty vans and delivery trucks operating last-mile logistics routes require mid-tier synthetic blends balancing drain interval extension with per-liter cost control.
- Heavy-Duty Trucks:Long-haul operators specify Group III base oil formulations with TBN retention and soot handling capabilities for 100,000+ kilometer drain intervals, generating superior per-unit margins through specialized additive chemistry.
- Motorcycles:Two-stroke and four-stroke formulations serve recreational and delivery segments in Ras Al Khaimah and Fujairah with distinct JASO and API service category requirements.
Revenue scale aligns with Passenger Vehicles; margin intensity aligns with Heavy-Duty Trucks.
Distribution Channel:
Channel economics reflect inventory carrying costs and technical consultation requirements for specification compliance.
- Online Retailers:E-commerce platforms are expanding fastest for packaged consumer lubricants as workshop buyers and fleet procurement desks digitize replenishment workflows.
- Auto Parts Stores:Counter-based technical consultation supports independent workshop specification decisions in Sharjah industrial zones with immediate availability requirements.
- Service Stations:ADNOC and international oil company retail networks anchor bulk and packaged lubricant availability across Abu Dhabi and Dubai transport corridors.
- Wholesalers:Traditional distributor tiers face compression as fleet direct agreements and online procurement disintermediate regional stocking operations.
Legacy infrastructure favors Service Stations; growth trajectory favors Online Retailers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jebel Ali Port anchors the UAE's lubricant distribution architecture, channeling Group II and III base oils from regional refineries into domestic blending facilities and re-export networks across the Gulf.
Dubai
Logistics fleet operators along the Sheikh Zayed Road corridor specify long-drain synthetic formulations to minimize downtime on Dubai-Abu Dhabi freight routes. ESMA enforces SAE viscosity grade labeling verification at bonded warehousing facilities in Jebel Ali Free Zone. Al Quoz industrial district hosts independent blending operations upgrading testing capabilities to meet MOHAP registration mandates.
Abu Dhabi
Heavy-duty truck operators in Mussafah industrial zone demand high-TBN engine oils for 100,000-kilometer drain intervals on long-haul routes. ADNOC's downstream integration secures captive feedstock supply for domestic lubricant production at Ruwais refinery complex. Khalifa Port logistics clusters concentrate procurement desks negotiating direct blender agreements.
Sharjah
Independent repair workshops in Sharjah industrial area face capital requirements for synthetic oil storage and disposal compliance. MOHAP quality certification protocols filter substandard imports entering through Hamriyah Free Zone. Saja'a industrial corridor workshops consolidate purchasing through distributor networks rather than direct blender relationships.
Northern Emirates
Ras Al Khaimah's emerging manufacturing clusters generate nascent demand for industrial lubricant distribution networks. Fujairah's port infrastructure supports bulk base oil storage and transshipment to eastern Emirates markets. Ajman automotive service stations require infrastructure retrofitting to handle extended-drain formulation specifications.
UAE Automotive Lubricants Market Competitive Landscape
Concentration sits with integrated oil companies and national energy champions commanding refinery-fed supply chains. The vendor base stratifies across three tiers: upstream-integrated majors with captive base oil production, regional blenders leveraging Gulf feedstock access, and specialty importers serving niche specification segments. Strategic moves center on procurement desk capture through direct fleet agreements and formulation licensing for EV thermal management fluids.
Within the integrated major tier, Royal Dutch Shell and Exxon Mobil Corporation exemplify technology-led positioning through synthetic formulation portfolios. ADNOC anchors the national champion archetype with Ruwais refinery integration securing domestic blending economics. Among regional specialists, DANA Lubricants Factory LLC and Emirates Lube Oil Co. Ltd occupy positions serving independent workshop channels and fleet operators with compliance-certified products.
| Leading Market Players |
|---|
| Royal Dutch Shell |
| Exxon Mobil Corporation |
| ADNOC |
| Chevron Corporation |
| DANA Lubricants Factory LLC |
| Emirates Lube Oil Co. Ltd |
| TotalEnergies |
| Gulf Oil Middle East Limited |
| EPPCO Lubricants |
| Others |
Value Network & Pricing Analysis
MOHAP registration mandates and ESMA certification requirements gate both supply qualification and price differentiation simultaneously, filtering substandard imports while elevating compliance costs that stratify pricing tiers across the Emirates.
Pricing Analysis
Volume-discount tiering structures dominate procurement negotiations as fleet operators consolidate purchasing desks along Dubai-Abu Dhabi corridors. Three-tier pricing separates synthetic long-drain formulations from semi-synthetic mid-tier products from mineral-based economy grades, with certification level and volume scale as primary differentiation drivers. Price erosion runs through the economy mineral oil segment as Group II base oil feedstock volatility compresses blender margins. Independent repair workshops in Sharjah and Ajman exhibit highest price sensitivity, while logistics fleet operators prioritize total cost of ownership over per-liter pricing.
Supply Chain Analysis
Strategic stockpile preferences dominate blender inventory management given Group II and III base oil price volatility and Jebel Ali port logistics chokepoints. Supply concentrates in Saudi Arabia, Kuwait, and the UAE itself through regional refinery complexes feeding Ruwais and Jebel Ali blending facilities. Raw material dependencies center on API Group II/III base oils, polyalphaolefin synthetic feedstocks, and additive packages sourced from specialty chemical suppliers. Single-source vulnerability persists for high-performance additive chemistries. Distribution runs through ADNOC retail networks, independent wholesalers, and emerging e-commerce platforms serving fleet procurement desks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a defensive-moat story anchored in regulatory entrenchment, where MOHAP and ESMA compliance costs create barrier effects that reinforce established suppliers with captive laboratory infrastructure.
For Market Incumbents: Fortify laboratory testing capabilities to accelerate MOHAP registration turnaround times and lock in fleet direct agreements. Deepen backward integration into Group III base oil production through Ruwais refinery capacity expansion. Synthetic lubricant substitution pressure from extended-drain formulations threatens volume-based revenue models, requiring pivot toward per-liter margin capture through premium additive chemistry licensing.
For New Entrants and Emerging Players: Differentiate on EV thermal management fluid formulations as electric vehicle penetration creates specification white-space beyond traditional engine oils. Target Ras Al Khaimah industrial corridor expansion where nascent manufacturing clusters lack established lubricant distribution relationships. Penetrate through direct technical service partnerships with northern Emirates fleet operators bypassing traditional distributor tiers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across synthetic formulation segments as additive R&D and testing infrastructure requirements escalate. Long-term viability favors blenders with upstream feedstock integration and MOHAP-registered product portfolios. Acquisition target archetype: regional specialists with compliance-certified manufacturing and underutilized northern Emirates distribution reach. Signal to watch: fleet procurement desk consolidation velocity along Jebel Ali-Mussafah logistics corridors.
| Strategic Initiative | Industry Significance |
|---|---|
| MOHAP Registration Acceleration | Fast-track certification timelines capture fleet procurement desk decisions before competitor formulations gain specification lock-in. |
| Group III Base Oil Backward Integration | Ruwais refinery expansion secures captive feedstock supply insulating blender margins from regional crude differential volatility. |
| EV Thermal Fluid Formulation Licensing | Early positioning in battery and e-axle cooling chemistry builds intellectual property moats ahead of electric vehicle fleet scaling. |
| Ras Al Khaimah Distribution Network Buildout | First-mover infrastructure in emerging northern Emirates manufacturing clusters preempts competitor channel saturation. |
| Fleet Direct Agreement Structuring | Long-term offtake contracts with Jebel Ali logistics operators disintermediate traditional wholesaler tiers and stabilize volume commitments. |
Research Methodology
Desk research of customs trade databases, refinery capacity disclosures, and MOHAP registration filings preceded structured interviews with lubricant blender procurement directors, fleet maintenance managers at logistics operators, independent workshop owners in Sharjah industrial zones, and additive supplier technical sales representatives. Secondary validation drew from ESMA labeling compliance bulletins, API licensing directories, and ACEA oil sequence documentation. Bottom-up volume estimates from fleet parc analysis and top-down value projections from refinery output data were triangulated to constrain forecast variance.
Variance-decomposition framing isolates segment-level growth contributions across the projection horizon. The analytical framework models lubricant demand by product type, end-user channel, vehicle application, and regional corridor cluster throughout the forecast period. CAGRs were derived from trend extrapolation of fleet modernization rates and synthetic adoption curves calibrated against base oil availability projections. Industry-specific inputs include drain interval extension trajectories for heavy-duty trucks and EV thermal fluid specification emergence timelines.
Material uncertainties — feedstock price volatility, regulatory enforcement intensity shifts, and electric vehicle penetration acceleration — sit outside the modeled envelope. Forecasts reflect assumptions about fleet procurement centralization velocity and MOHAP registration processing capacity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Europe Automotive Engine Oils Market
Automotive Parts
Automotive Radiator Hose Market
Automotive Parts
Constant Velocity Joint Market
Automotive Parts
South America Automotive Engine Oils Market
Automotive Parts
Automotive Oil Pans Market
Automotive Parts
Philippines Automotive Engine Oils Market
Automotive Parts
Automotive Aluminium Extrusion Market
Automotive Parts
Automotive Exhaust Heat Recovery System Market
Automotive Parts
Two Speed Gearbox Market
Automotive Parts
Automotive Oil and Valve Stem Seals Market
Automotive Parts
Electric Power Steering Market
Automotive Parts
UK Automotive Parts Aluminium Die Casting Market
Automotive Parts
Resin Silencer Market
Automotive Parts
Vietnam Commercial Vehicles Lubricants Market
Automotive Parts
Automotive Pneumatic Actuators Market
Automotive Parts
Japan Automotive Parts Zinc Die Casting Market