
 Center and Drag Link Market | 2026-2036
Center and Drag Link Market Size, Share, and Industry Trends Forecast 2026-2036
Center and Drag Link Market Intelligence
Fleet operator purchasing power is hardening across North American and European commercial vehicle corridors. JTEKT Corporation leverages its integrated steering systems portfolio to anchor long-term supply contracts with heavy-truck manufacturers. ZF Friedrichshafen AG competes through manufacturing scale across forged steel and aluminum alloy linkages for multiple vehicle classes.
Center and drag links transmit steering force from the gearbox to the steering knuckles via threaded or ball-joint terminations, typically forged from medium-carbon steel to withstand cyclic loads exceeding 50 kN in heavy-truck duty cycles. Their primary purpose is maintaining precise wheel alignment under dynamic suspension travel. The forged steel material segment sustains dominant share in heavy-truck and off-road applications where fatigue resistance commands priority. Aluminum alloy linkages are gaining fastest penetration in passenger cars and light commercial vehicles as OEMs pursue chassis mass reduction targets.
NHTSA enforces steering linkage integrity standards for on-highway vehicles, while EPA fuel-economy rules indirectly pressure chassis weight optimization. India's BIS certifies automotive steel grades under IS 1875, shaping local supplier qualification requirements. Stakeholders must monitor evolving alloy substitution economics and regulatory test-load escalation to calibrate material roadmaps and capacity allocation across vehicle-type portfolios.
Market Dynamics
Fleet operators in North America and Europe are compressing replacement cycles for aging commercial vehicle populations, while India's road freight expansion sustains aftermarket parts consumption at scale.
Growth Catalysts
- NHTSA Steering Linkage Standards:Tightened test protocols for heavy-duty applications mandate upgraded component integrity, forcing OEMs and Tier-1 suppliers to refresh product portfolios and capture replacement demand.
- India Road Freight Expansion:Domestic commercial vehicle production growth sustains aftermarket consumption of center and drag link assemblies across medium and heavy-duty truck segments.
- Aluminum Alloy Substitution:Chassis mass reduction targets in passenger cars and light commercial vehicles accelerate material transition from forged steel to aluminum linkages.
Market Restraints
- Scrap Steel Price Volatility:Medium-carbon steel feedstock costs fluctuate with global metallurgical coal and iron ore indices, compressing margin predictability for forged linkage manufacturers.
- Supplier Concentration in Forging Capacity:Heavy-truck grade forging presses concentrate in Germany, Japan, and select Indian industrial clusters, creating geographic supply risk during demand surges.
- Ball-Joint Seal Durability Limits:Cyclic load environments exceeding 50 kN in off-road duty cycles accelerate wear at threaded terminations, limiting service intervals and warranty exposure.
Strategic Opportunities
- Brazil Commercial Vehicle Fleet Renewal:Underpenetrated aftermarket infrastructure for steering linkage replacement creates white space for organized suppliers establishing distribution partnerships with local fleet operators.
- EU Green Deal Carbon Border Adjustments:Inbound tariff mechanisms on high-carbon steel imports incentivize regional forging capacity expansion and low-emission alloy development.
- E-Commerce Fleet Electrification:Last-mile delivery vehicle conversions require redesigned steering geometries, opening specification windows for lightweight linkage architectures.
Industry Challenges
- Weld Qualification Bottlenecks:AWS D1.1 and ISO 3834 certification timelines for automated forging-to-assembly operations extend 14-18 months, delaying capacity ramp schedules.
- Legacy ERP Integration Friction:Tier-1 suppliers retrofitting Industry 4.0 traceability systems encounter data architecture conflicts with decades-old production planning platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Center and Drag Link Market |
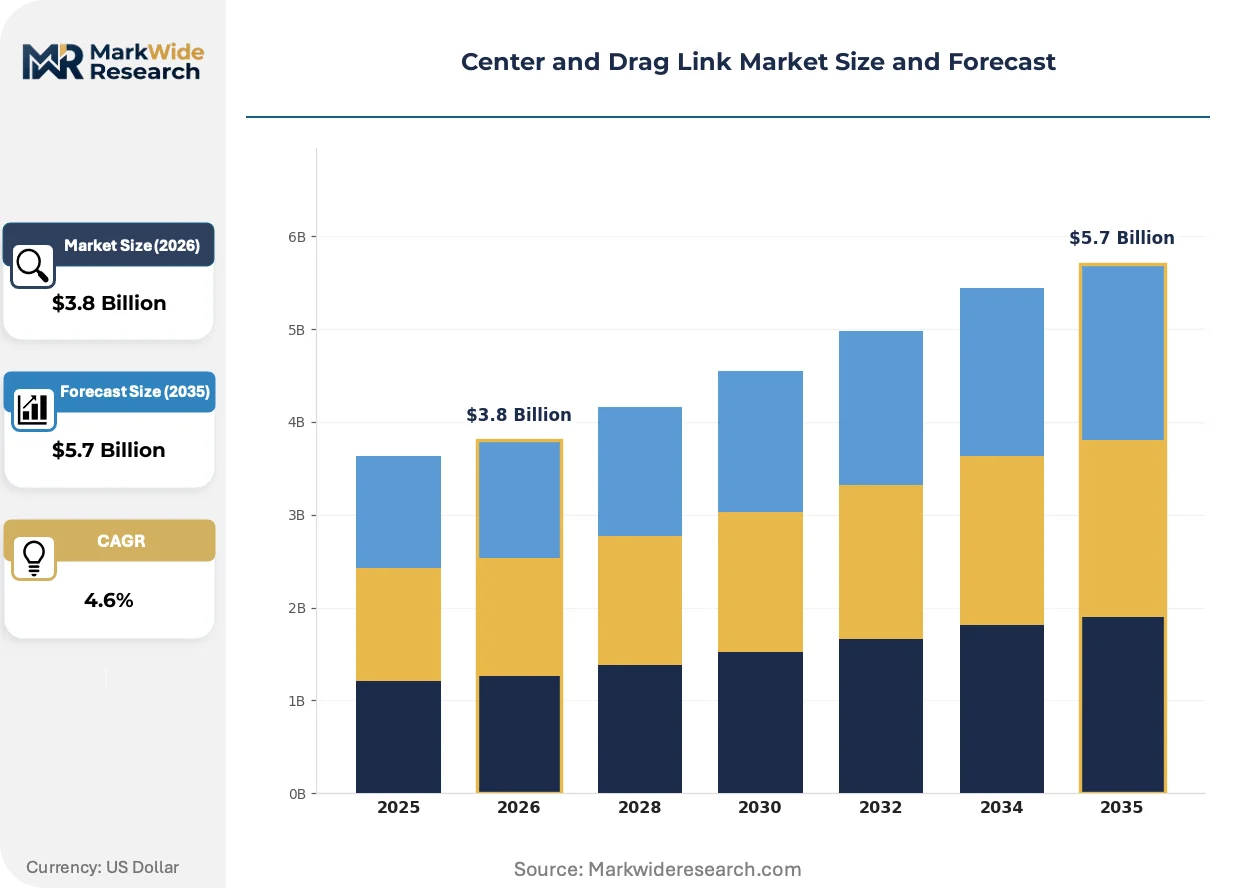
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Center Link, Drag Link, Tie Rod, Track Rod, Others Material: Forged Steel, Cast Iron, Aluminum Alloy, Carbon Steel, Composite Vehicle Type: Light Commercial Vehicles, Heavy Trucks, Off-Road Vehicles, Passenger Cars, Specialty Vehicles End User: OEMs, Aftermarket Suppliers, Fleet Operators, Vehicle Refurbishers |
| Companies Covered | Korea Central, JTEKT Corporation, Federal-Moghul, Hyundai MOBIS Co., Ltd., Moog Inc., ZF Friedrichshafen AG, Magna International Inc., AISIN Corporation, Rane (Madras) Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Center and Drag Link Market Strategic Shifts & Innovations
Steering linkage manufacturing is undergoing material and process transformation as regulatory load requirements escalate and chassis electrification demands new geometric configurations.
High-strength aluminum-magnesium-scandium alloys are rewriting the mass-performance tradeoff for light commercial vehicle linkages. European OEMs have accelerated specification approvals for these alloys across van and pickup platforms since 2022. The shift is compressing the traditional steel-forging supply base while elevating specialized extrusion and heat-treatment capabilities.
REACH substance restrictions on hexavalent chromium coatings are forcing conversion to trivalent alternatives or laser-clad surfaces for corrosion protection. German and French forging houses have absorbed compliance costs through process requalification. The regulatory pressure is most acute in passenger car segments where surface finish specifications are tightest and warranty terms longest.
Fleet procurement teams are unbundling steering linkage replacement from full suspension service contracts, creating direct aftermarket channels bypassing traditional dealer networks. North American long-haul operators now source linkages through consolidated parts platforms with 48-hour fulfillment guarantees. The behavioral shift is visible most prominently in Texas, California, and Ontario corridor freight corridors where fleet density supports dedicated distribution nodes.
Center and Drag Link Market Segmentation
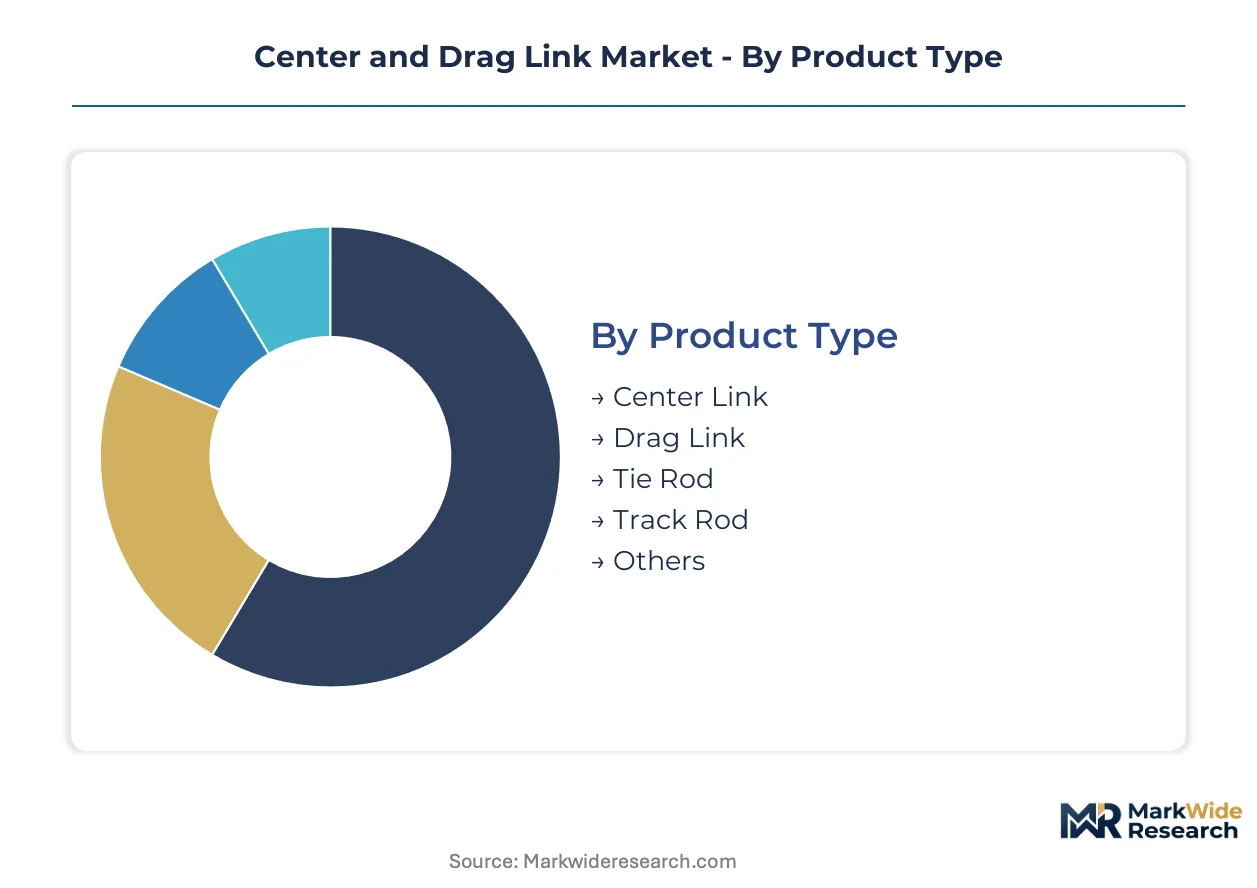
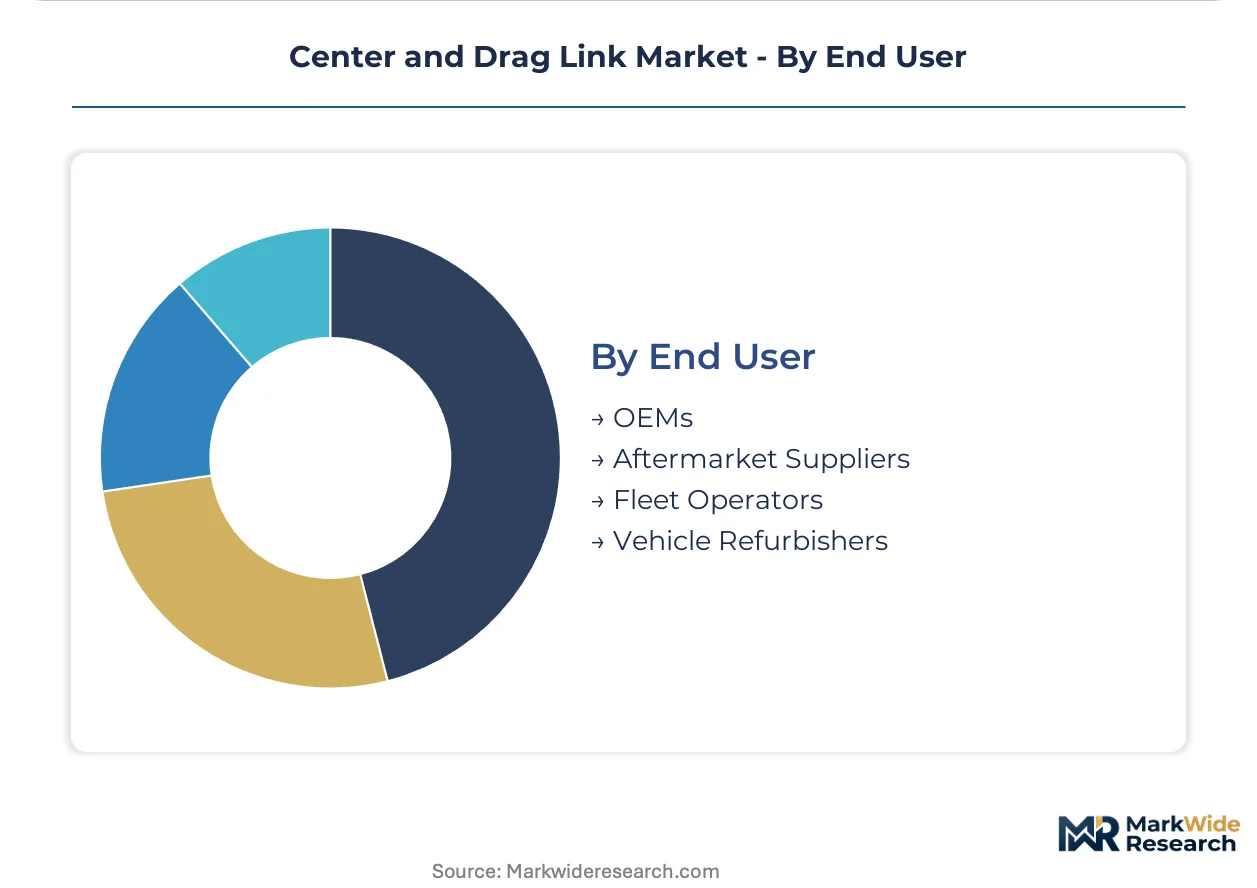
Center and drag link procurement patterns diverge sharply across product configurations, material grades, and vehicle duty cycles. Certification requirements from NHTSA, BIS, and KBA shape supplier qualification timelines differently for each segment tier. Fleet operators and OEMs calibrate specification strategies against these regulatory load protocols and replacement cycle economics.
Product Type:
NHTSA steering linkage integrity standards apply differential test loads across product categories, with heavy-duty center links facing the most stringent cyclic verification protocols.
- Center Link:Transmits steering torque between the pitman arm and idler arm in parallelogram steering architectures. Heavy-truck fleets in Texas and California corridor operations drive replacement demand as NHTSA test protocols escalate fatigue resistance requirements.
- Drag Link:Connects the steering gearbox pitman arm to the steering knuckle on beam-axle configurations. Off-road mining and construction vehicle operators in Western Australia specify drag links rated beyond 50 kN cyclic loads.
- Tie Rod:Links left and right steering knuckles to synchronize wheel angles during suspension travel.
- Track Rod:Maintains lateral wheel alignment in rigid axle assemblies under dynamic load conditions.
- Others:Includes idler arms, pitman arms, and auxiliary linkage components for specialized steering geometries.
Leading the category by volume: Center Link. Growing fastest: Drag Link.
Material:
Material selection trades fatigue resistance against chassis mass targets, with cost tiers separating forged steel premium specifications from aluminum alloy lightweight alternatives.
- Forged Steel:Medium-carbon grades forged under closed-die presses deliver fatigue resistance exceeding 50 kN cyclic loads. Indian forging clusters in Pune and Jamshedpur supply heavy-truck OEMs under BIS IS 1875 certification protocols.
- Aluminum Alloy:High-strength aluminum-magnesium-scandium extrusions reduce unsprung mass in passenger cars and light commercial vehicles. European van platforms specify these alloys to meet EPA-correlated fuel economy targets.
- Cast Iron:Lower-cost alternative for stationary steering loads in specialty and low-duty applications.
- Carbon Steel:Standard-grade material for aftermarket replacement linkages with moderate load requirements.
- Composite:Emerging polymer-matrix configurations for prototype electric vehicle steering architectures.
Highest specification density: Forged Steel. Steepest expansion trajectory: Aluminum Alloy.
Vehicle Type:
Application severity dictates material grade and joint sealing specifications across passenger, commercial, and off-road duty cycles.
- Heavy Trucks:Beam-axle configurations in long-haul freight demand center and drag links with ball-joint terminations rated for million-mile service intervals. German KBA type approval protocols govern linkage integrity for vehicles exceeding 12 tonnes gross weight.
- Light Commercial Vehicles:Parallelogram steering architectures in last-mile delivery fleets prioritize aluminum linkages to maximize payload capacity within axle weight limits.
- Passenger Cars:Rack-and-pinion systems reduce linkage complexity but retain tie rods for wheel alignment control.
- Off-Road Vehicles:Mining and agricultural equipment exposes linkages to abrasive contamination and impact loads.
- Specialty Vehicles:Military and emergency service platforms require hardened linkages with extended service intervals.
Dominant replacement volume: Heavy Trucks. Specification change velocity: Light Commercial Vehicles.
End User:
Procurement authority is fragmenting as fleet operators bypass dealer networks for direct aftermarket sourcing.
- Fleet Operators:North American long-haul carriers now consolidate linkage procurement through dedicated parts platforms with 48-hour fulfillment guarantees. Ontario corridor freight density supports regional distribution nodes serving multi-thousand vehicle fleets.
- OEMs:Heavy-truck manufacturers anchor long-term supply contracts with integrated steering system suppliers.
- Aftermarket Suppliers:Independent distributors serve fragmented vehicle populations outside OEM service networks.
- Vehicle Refurbishers:Secondary market operators restore steering linkages for export markets and domestic fleet extensions.
Fastest procurement transformation: Fleet Operators. Highest contract value concentration: OEMs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial vehicle fleet density concentrates in corridors linking major freight hubs across the United States, Germany, India, China, and Japan. Each market exhibits distinct regulatory load protocols and material substitution trajectories that reshape supplier qualification requirements.
United States
Long-haul operators in Texas and California freight corridors compress replacement cycles for aging heavy-truck populations. NHTSA steering linkage integrity standards mandate upgraded fatigue resistance test protocols for vehicles exceeding specific gross weight thresholds. Detroit-area forging clusters supply OEM anchor contracts while independent distributors build 48-hour fulfillment networks.
Germany
KBA type approval protocols govern linkage integrity certification for commercial vehicles above 12 tonnes gross weight. EU Green Deal carbon border adjustment mechanisms incentivize low-emission alloy development and regional forging capacity expansion. Bavarian and Baden-Württemberg industrial zones concentrate precision forging presses serving premium heavy-truck specifications.
India
Domestic commercial vehicle production growth sustains aftermarket consumption across medium and heavy-duty truck segments. BIS certifies automotive steel grades under IS 1875, shaping local supplier qualification timelines. Pune and Jamshedpur forging clusters supply heavy-truck OEMs under closed-die press operations.
China
Dual carbon goals accelerate chassis mass reduction targets in light commercial vehicle segments. GB standards govern steering component structural integrity for domestic and export vehicle platforms. Yangtze River Delta manufacturing zones integrate aluminum extrusion capabilities for emerging electric commercial vehicle architectures.
Japan
JIS standards prescribe material grades and fatigue test protocols for steering linkage applications in commercial and passenger vehicles. METI industrial policy supports lightweight alloy development for next-generation vehicle platforms. Nagoya-area suppliers anchor integrated steering system supply relationships with domestic OEMs.
Center and Drag Link Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue aluminum alloy specialization and electrification-ready geometries. The vendor base stratifies across three maturity tiers: multinational integrated system suppliers, regional forging specialists, and aftermarket-focused distributors. Strategic archetypes include scale-driven forged steel manufacturers, lightweight alloy developers, and fleet-direct fulfillment platform operators. Capacity expansion and strategic partnerships represent the dominant competitive moves as suppliers calibrate material roadmaps against regulatory load escalation.
Within the integrated system supplier tier, JTEKT Corporation and ZF Friedrichshafen AG exemplify scale-driven positioning across forged steel and aluminum alloy linkages. Hyundai MOBIS Co., Ltd. occupies a position within the Korean industrial ecosystem, representing the regional specialist archetype serving domestic OEM anchor contracts. These entities exemplify competitive positioning strategies without constituting an exhaustive market census.
| Leading Market Players |
|---|
| Korea Central |
| JTEKT Corporation |
| Federal-Moghul |
| Hyundai MOBIS Co., Ltd. |
| Moog Inc. |
| ZF Friedrichshafen AG |
| Magna International Inc. |
| AISIN Corporation |
| Rane (Madras) Limited |
| Others |
Cost & Logistics Intelligence
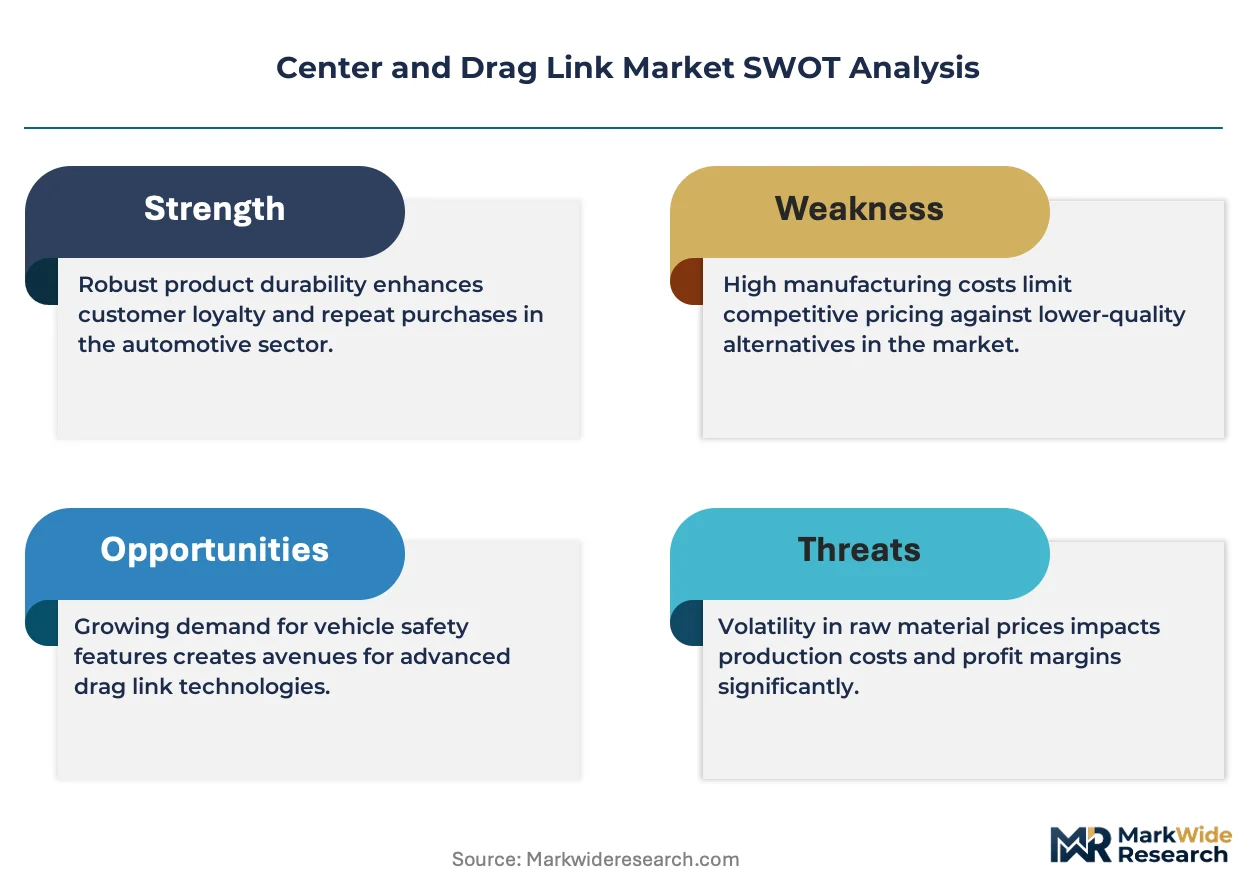
EU Green Deal carbon border adjustments gate both qualified supply and premium-tier pricing access for center and drag link manufacturers, as forged steel producers absorbing compliance costs through trivalent chromium conversion and low-emission alloy development secure preferential OEM contract tiers while higher-carbon import-dependent suppliers face margin compression.
Pricing Analysis
Volume-vs-margin splits sharply across material grades and certification tiers. Three-tier pricing structure across premium, standard, and economy levels separates NHTSA-certified heavy-truck linkages from BIS-grade Indian aftermarket units and uncertified gray-market alternatives. Cost compression in standard-grade forged steel intensifies because scrap steel price volatility feeds directly into medium-carbon feedstock economics. Fleet operators sourcing through consolidated parts platforms exhibit highest price sensitivity, while OEM anchor contracts for integrated steering systems show lowest sensitivity due to million-mile warranty bundling.
Supply Chain Analysis
Reverse-logistics flows for remanufactured linkages are gaining traction as North American fleet operators unbundle steering linkage replacement from full suspension service contracts. Geographic supply concentration centers on Germany, Japan, and India, with closed-die forging presses clustered in Bavarian industrial zones, Nagoya-area manufacturing corridors, and Pune-Jamshedpur supplier networks. Raw material dependencies draw from medium-carbon steel billets, aluminum-magnesium-scandium extrusion feedstock, and trivalent chromium coating chemistries. Single-source vulnerability in heavy-truck grade forging capacity creates structural risk during demand surges. Distribution runs through OEM direct channels for new vehicle content and dedicated parts platforms for aftermarket replacement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Forging press capacity scarcity in heavy-truck grade specifications props pricing power for qualified suppliers, as weld qualification bottlenecks extending 14-18 months prevent rapid capacity ramping.
For Market Incumbents: Extend certification coverage across NHTSA, KBA, and BIS protocols simultaneously to defend against aluminum alloy substitution threats in light commercial vehicle segments. Anchor long-term supply contracts through backward integration into specialized heat-treatment capabilities that emerging extrusion-focused competitors cannot replicate. Prioritize ERP modernization to resolve Industry 4.0 traceability conflicts before legacy data architecture friction compounds. For New Entrants and Emerging Players: Begin with Brazil's underpenetrated aftermarket infrastructure, where organized suppliers establishing distribution partnerships with local fleet operators face minimal incumbent saturation. Target aluminum-magnesium-scandium extrusion capabilities for European van platforms as specification windows open for electrification-ready lightweight geometries. Pursue direct fleet procurement relationships bypassing traditional dealer networks as the primary go-to-market angle. For Investors and Strategic Acquirers: NHTSA test protocol escalation for heavy-duty applications is the leading indicator that forged steel specification density will concentrate among vertically integrated suppliers with captive heat-treatment and surface coating capabilities. Long-term viability across the projection horizon favors acquisition targets possessing multi-regional certification portfolios rather than single-market specialists. Monitor EU carbon border adjustment implementation timelines as the critical inflection signal for low-emission alloy development returns.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Regional Certification Investment | Simultaneous NHTSA, KBA, and BIS qualification secures OEM anchor contract access across three major production hubs. |
| Aluminum Alloy Extrusion Capacity Buildout | High-strength aluminum-magnesium-scandium capabilities capture specification shifts in European van and pickup platforms. |
| Fleet-Direct Distribution Partnership | 48-hour fulfillment guarantees with North American long-haul operators bypass traditional dealer network margins. |
| Low-Emission Forging Process Conversion | Trivalent chromium and laser-clad surface technologies align with EU Green Deal carbon border adjustment compliance tiers. |
| Integrated Steering System Acquisition | Combined gearbox-linkage supply relationships lock in platform engineering specifications across multiple vehicle classes. |
Research Approach
SEC 10-K filings, customs and trade databases, and vehicle production registries formed the secondary backbone, supplemented by NHTSA regulatory documentation and BIS certification records. Primary interviews with Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distribution heads, and fleet maintenance directors validated demand assumptions and replacement cycle economics. Bottom-up and top-down triangulation cross-checked unit volume estimates against material consumption patterns and forging capacity utilization.
Bottom-up modeling anchored forecasts in segment-level vehicle production, content-per-vehicle assumptions, and replacement cycle compression rates across heavy-truck, light commercial, and off-road duty cycles. Top-down validation drew from aggregate commercial vehicle aftermarket spending patterns and steering system supplier revenue disclosures. CAGRs were derived from regression analysis of historical replacement demand against fleet age distributions and regulatory test load escalation timelines.
Underlying measurement precision varies by segment; heavy-truck center link volumes carry tighter precision than emerging aluminum alloy penetration estimates in passenger car applications. Forecasts reflect assumptions about NHTSA protocol implementation timing, scrap steel price stabilization, and fleet electrification conversion rates. Practitioners should monitor EU carbon border adjustment enforcement thresholds, India's domestic commercial vehicle production growth trajectories, and ball-joint seal durability field performance for early signals of forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Power Steering Oil Market
Automotive Parts
Two Speed Gearbox Market
Automotive Parts
Automotive Aluminium Extrusion Market
Automotive Parts
Ball Bearing Market
Automotive Parts
AC Electromagnetic Brakes Market
Automotive Parts
Automotive Fuel Supply System Market
Automotive Parts
Automotive Aluminum Parts High Pressure Die Casting (HPDC) Market
Automotive Parts
Brake Pad Market
Automotive Parts
Global Automotive Leaf Spring Market
Automotive Parts
Automotive Coolant Market
Automotive Parts
Global Very Narrow Aisle Trucks (VNA Truck) Market
Automotive Parts
Germany Automotive Parts Aluminium Die Casting Market
Automotive Parts
Air Brake Market
Automotive Parts
Electromagnetic Clutches Market
Automotive Parts
Motorcycle Battery Chargers Market
Automotive Parts
Italy Automotive Airfilters Market