
 Automotive Radiator Hose Market | 2026-2036
Automotive Radiator Hose Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Radiator Hose Market Analysis
Silicone is consolidating share against traditional EPDM rubber in upper-segment automotive radiator hose formulations, driven by superior temperature tolerance and longer service life. Gates Corporation leverages captive rubber-compounding capabilities to control raw-material quality across its hose portfolio. Continental sustains R&D intensity in molded multi-layer assemblies for electric-vehicle thermal loops. Toyoda Gosei anchors its position through deep supply relationships with Japanese OEMs and just-in-time manufacturing scale.
An automotive radiator hose is a flexible conduit, typically fabricated from EPDM rubber or silicone elastomer with textile or wire reinforcement, engineered to circulate coolant between engine, radiator, and heater core under pressures reaching several bar and temperatures exceeding 120°C. Its primary function is maintaining thermal equilibrium and preventing engine overheating across operating cycles. Silicone hoses command premium positioning in high-performance and commercial-vehicle segments where extended durability justifies cost, while rubber hoses retain volume leadership in economy passenger-car production. The reinforced technology segment captures the bulk of OEM specification, whereas molded configurations are gaining share as engine-bay packaging tightens and routing complexity rises.
The EPA regulates coolant-system leakage standards under broader emissions frameworks, while NHTSA safety standards influence hose burst-pressure requirements for on-highway vehicles. In Europe, REACH restricts certain curing-agent chemistries in rubber compounds, compelling reformulation investments by compounders serving the aftermarket. China's MIIT enforces fuel-consumption limits that intensify thermal-management system optimization, directly affecting hose specification. Stakeholders must monitor material-certification timelines and regional emissions-rule convergence to align product-development roadmaps with diverging compliance calendars.
Market Dynamics
Silicone elastomer displacement of EPDM in commercial-vehicle thermal systems is compressing replacement cycles and forcing compounders to recalibrate capacity allocation between commodity rubber and premium formulations.
Growth Catalysts
- EPA Corporate Average Fuel Economy standards:Tighter thermal-management mandates push OEMs toward higher-performance hose materials that maintain coolant integrity under elevated operating temperatures.
- Heavy-duty logistics expansion:Fleet operators in the United States prioritize extended service intervals to minimize downtime, accelerating specification of silicone-based assemblies.
- Electric-vehicle thermal-loop proliferation:Battery thermal-management systems require additional hose circuits per vehicle, expanding addressable content per unit.
Market Restraints
- Silicone raw-material concentration:Precursor supply concentrates among Asian chemical producers, exposing compounders to volatility in organosilicon monomer pricing.
- REACH curing-agent restrictions:ECHA limitations on specific vulcanization chemistries force European compounders into costly reformulation programs without immediate volume offset.
- Fluoroelastomer substitution threat:Aggressive OEMs in high-performance segments specify fluorocarbon hoses where chemical resistance trumps cost considerations.
Strategic Opportunities
- India commercial-vehicle production:Domestic truck and bus assembly growth outpaces local hose manufacturing capacity, creating import substitution potential for regional compounders.
- MIIT fuel-consumption enforcement:China's tightening corporate-average fuel-economy rules intensify thermal-system optimization, favoring suppliers with localized molded-hose capabilities.
- 3D-printed prototyping convergence:Additive manufacturing of hose-form tooling compresses development cycles for custom routing solutions in low-volume EV programs.
Industry Challenges
- Multi-material bonding expertise gap:Molded assemblies combining silicone, metal, and composite substrates require specialized process engineers scarce in traditional rubber-hose operations.
- Homologation timeline compression:OEM platform acceleration demands simultaneous validation across EPA, ECHA, and MIIT certification regimes, straining testing infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Radiator Hose Market |
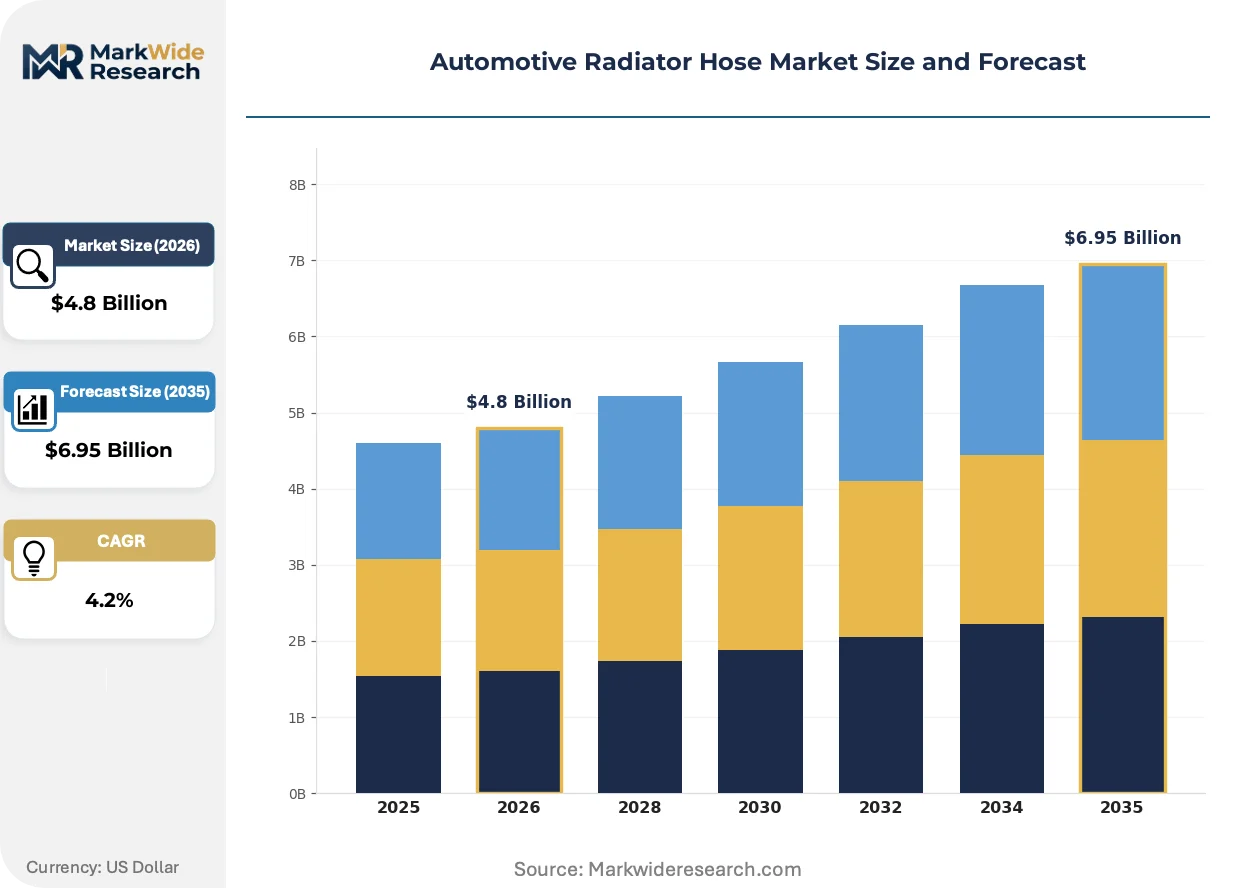
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.95 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone Hoses, Rubber Hoses, Complete Hose Assemblies, Custom Hoses Technology: Reinforced, Non-Reinforced, Smooth Bore, Molded End User: OEMs, Aftermarket, Fleet Operators, Repair Shops Application: Passenger Cars, Commercial Vehicles, Heavy-Duty Trucks, Off-Road Vehicles |
| Companies Covered | Goodyear, Shandong Meichen, Continental, Toyoda Gosei, Sichuan Chuanhuan, Gates Corporation, Hutchinson, ACDelco, Dayco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Radiator Hose Market Emerging Trajectories
Material science and manufacturing process evolution are converging to redefine hose architecture, with multi-layer construction and smart-forming technologies displacing legacy single-wall designs across premium vehicle segments.
Multi-layer co-extrusion is modularizing radiator hose construction by enabling discrete functional layers—barrier, reinforcement, and cover—to be optimized independently rather than compromised in a single compound. Tier-1 suppliers serving German OEMs have accelerated adoption of this architecture for electric-vehicle battery cooling circuits. The approach compresses development cycles for application-specific thermal solutions while reducing per-part mass.
REACH restrictions on specific rubber-curing agents are forcing compounders serving the European aftermarket to validate alternative vulcanization systems without sacrificing compression-set performance. The regulatory pressure most acutely affects small-batch aftermarket producers lacking captive R&D infrastructure. Reformulation investments are diverting capital from geographic expansion programs.
Fleet procurement departments are consolidating hose specification authority previously dispersed across regional maintenance managers, centralizing vendor qualification and long-term service agreements. This concentration favors suppliers with national distribution networks and electronic catalog integration over local jobber channels. The shift is most visible in United States heavy-duty trucking operations where total-cost-of-ownership analytics now dominate purchase decisions.
Automotive Radiator Hose Market Segmentation
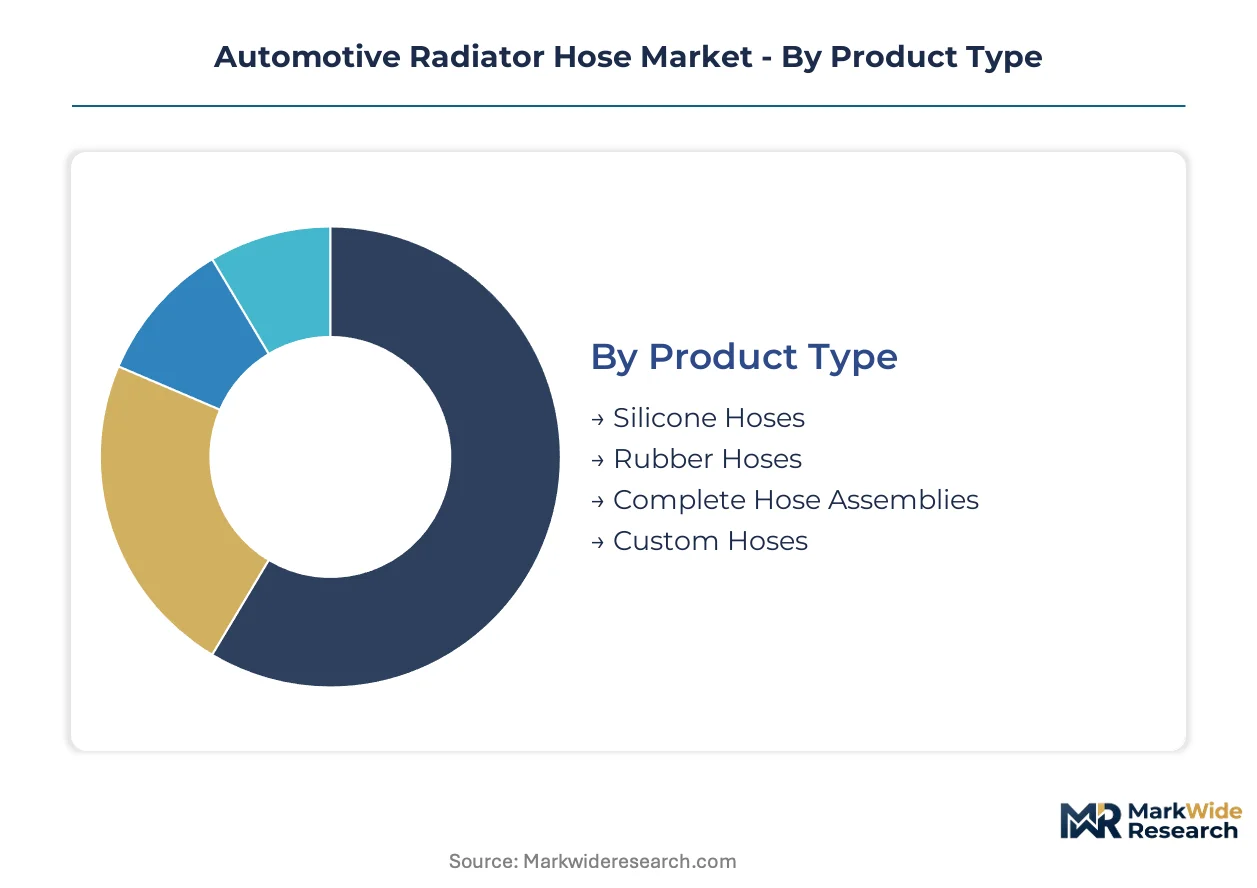
Segmentation in the automotive radiator hose market reveals how material specifications, manufacturing technologies, and customer procurement patterns fragment addressable demand. Each dimension carries distinct margin profiles and competitive intensity that shape supplier positioning strategies.
Product Type:
Supply concentration among Asian silicone precursor producers has compressed compounder margins on premium formulations while rubber hose manufacturing remains geographically dispersed across regional tire and rubber belt clusters.
- Silicone Hoses:Fabricated from high-purity VMQ or FVMQ elastomer with aramid or polyester reinforcement, rated for continuous operation above 150°C. Demand concentrates in United States heavy-duty fleet procurement where extended service intervals offset unit cost premiums. Fleet operators specify silicone for Class 8 trucks running 500,000+ mile replacement cycles.
- Rubber Hoses:EPDM-based constructions dominate economy passenger-car production in China and India where per-unit cost sensitivity overrides durability specifications. Compounders in Shandong and Tamil Nadu maintain excess EPDM mixing capacity that suppresses regional pricing.
- Complete Hose Assemblies:Pre-fitted with quick-connect couplings and mounting brackets, these integrated modules reduce OEM assembly-line labor.
- Custom Hoses:Low-volume specialty fabrications for motorsport and vintage restoration applications command 3-4x standard pricing.
Today's leader: Rubber Hoses. Tomorrow's challenger: Silicone Hoses.
Technology:
Cost tier separation between reinforced and non-reinforced constructions has widened as steel-cord and textile-winding equipment requires capital investment that smaller compounders cannot justify.
- Reinforced:Multi-ply constructions with wire helix or textile braid withstand 3-6 bar operating pressure and pulsing loads from modern turbocharged engines. OEM specification concentrates in German and Japanese passenger-car programs where burst-pressure margins are non-negotiable.
- Molded:Complex 3D geometries formed in heated metal tools eliminate connection points and reduce leak paths. Electric-vehicle battery cooling circuits in South Korea and California favor molded configurations for compact routing around cell modules.
- Non-Reinforced:Single-wall extrusions serve low-pressure heater core bypass lines and auxiliary circuits.
- Smooth Bore:Minimized flow resistance benefits high-flow cooling systems in performance applications.
Volume leadership sits with Reinforced. Steepest expansion trajectory belongs to Molded.
End User:
Customer type determines contract structure and working capital requirements, with OEMs demanding 90-120 day payment terms and aftermarket channels requiring inventory placement.
- OEMs:Direct supply relationships with Toyota, Volkswagen, and Ford specify PPAP-validated production processes and statistical process control documentation. Contract durations typically span 5-7 years with annual price-down provisions.
- Fleet Operators:Consolidated procurement departments at Schneider, J.B. Hunt, and Old Dominion Freight Line negotiate national stocking agreements with predictive maintenance analytics integration.
- Aftermarket:Independent distributors and jobber networks serve replacement demand with lower certification barriers.
- Repair Shops:Franchise chains like Meineke and Midas specify house-brand hose programs with guaranteed same-day availability.
Margin concentration favors OEMs. Procurement consolidation is accelerating fastest among Fleet Operators.
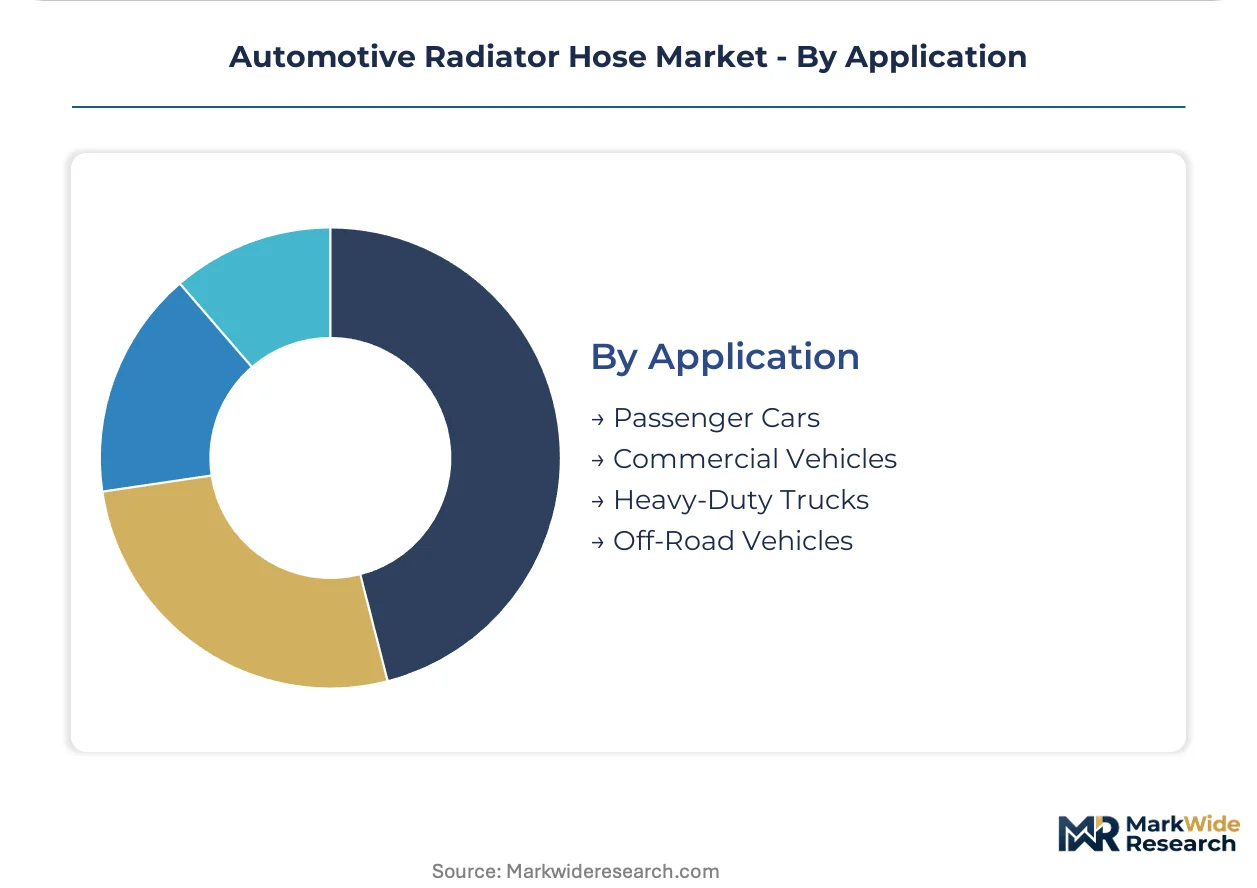
Application:
Application-driven specification divergence has created distinct competitive arenas where heavy-duty thermal loads justify material premiums unavailable in light-vehicle segments.
- Commercial Vehicles:Class 6-8 trucks and transit buses operate cooling systems at sustained high loads that degrade EPDM within 24-36 months. United States EPA emissions compliance has tightened under-hood thermal management, pushing fleet specification toward silicone constructions.
- Heavy-Duty Trucks:Long-haul tractors accumulate 100,000+ annual miles with minimal downtime tolerance. Mining and logging operators in Western Australia and Alberta specify aramid-reinforced silicone with 7-year service life guarantees.
- Passenger Cars:High-volume production in China, Germany, and the United States sustains commodity EPDM demand with 6-8 year replacement expectations.
- Off-Road Vehicles:Agricultural and construction equipment faces abrasive environments and extreme temperature swings.
Replacement cycle value concentrates in Heavy-Duty Trucks. Volume scale remains anchored in Passenger Cars.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Detroit-Windsor automotive corridor anchors North American radiator hose procurement, with Class 8 truck production and thermal-system upgrades driving material specification shifts across the continent.
United States
Heavy-duty fleet operators at Schneider and J.B. Hunt specify silicone hose assemblies for 500,000-mile service intervals. EPA Corporate Average Fuel Economy standards tighten thermal-management mandates for light-truck platforms. Manufacturing concentrates in Michigan and Ohio, where Tier-1 suppliers co-locate with Ford and General Motors assembly plants.
Germany
Volkswagen and BMW specify molded multi-layer hose configurations for electric-vehicle battery cooling circuits. REACH restrictions on rubber-curing agents force compounders serving the aftermarket into reformulation investments. Industrial activity clusters in Baden-Württemberg and Lower Saxony, where Continental maintains R&D facilities for thermal-loop assemblies.
China
Domestic light-truck production and heavy-duty logistics expansion sustain EPDM volume demand alongside silicone growth in premium segments. MIIT fuel-consumption enforcement intensifies thermal-system optimization requirements. Shandong Province hosts excess EPDM mixing capacity that suppresses regional pricing for economy passenger-car applications.
Japan
Toyota and Honda procurement specifications prioritize just-in-time delivery and statistical process control documentation for hose assemblies. METI industrial standards influence material certification timelines for export-bound vehicles. Manufacturing concentrates in Aichi Prefecture and Kanagawa, where Toyoda Gosei maintains deep supply relationships with domestic OEMs.
India
Domestic truck and bus assembly growth outpaces local hose manufacturing capacity, creating import substitution openings for regional compounders. BIS certification requirements for automotive rubber products intensify quality compliance investments. Tamil Nadu and Maharashtra host emerging rubber-hose production clusters serving commercial-vehicle assemblers.
Automotive Radiator Hose Market Vendor Landscape
Global majors compete with regional champions across material technology and geographic coverage, producing a tiered structure where scale-driven suppliers face pressure from specialized compounders. The vendor base separates into three archetypes: integrated rubber compounders with captive polymer production, automotive-focused Tier-1 suppliers with OEM direct relationships, and regional fabricators serving aftermarket and commercial-fleet channels. Dominant competitive moves include backward integration into silicone precursor supply and geographic expansion into underpenetrated commercial-vehicle production zones.
Among Germany-based diversified suppliers, Continental exemplifies the integrated Tier-1 archetype with R&D intensity in molded assemblies. Gates Corporation represents North American majors leveraging rubber-compounding capabilities across hose portfolios. Toyoda Gosei occupies a position within Japanese specialists anchored through OEM supply relationships and manufacturing scale.
| Leading Market Players |
|---|
| Goodyear |
| Shandong Meichen |
| Continental |
| Toyoda Gosei |
| Sichuan Chuanhuan |
| Gates Corporation |
| Hutchinson |
| ACDelco |
| Dayco |
| Others |
Supply Flow & Price Mechanics
Multi-layer co-extrusion adoption in electric-vehicle battery cooling circuits is compressing per-part mass while concentrating tooling investment among compounders with captive polymer production, simultaneously reshaping cost economics and supply concentration across silicone and rubber hose formulations.
Pricing Analysis
Input-cost pass-through from organosilicon monomer volatility exposes compounders to margin compression on premium silicone formulations, while EPDM rubber pricing anchors to regional petrochemical feedstock indices. Three-tier pricing structure across premium silicone, standard reinforced, and economy single-wall constructions reflects certification grade and volume scale differentiation. Pricing pressure stems from fleet procurement consolidation demanding predictive maintenance analytics bundling. Aftermarket jobber channels exhibit highest price sensitivity; OEM direct contracts show lowest sensitivity due to long-term service interval guarantees.
Supply Chain Analysis
Reverse-logistics flows for remanufactured hose assemblies remain underdeveloped, with fleet operators in the United States and Germany piloting core-return programs for silicone constructions to recover aramid reinforcement value. Geographic supply concentration centers on China for EPDM mixing capacity, Germany for molded multi-layer tooling, and Japan for just-in-time assembly scale. Raw material dependencies draw from Asian organosilicon precursor producers, Saudi petrochemical feedstocks, and Belgian aramid fiber suppliers. Single-source vulnerability in VMQ elastomer supply creates structural risk. Distribution runs through Tier-1 supplier direct channels to OEMs, national fleet stocking agreements, and regional aftermarket jobber networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in automotive radiator hose supply hinges on silicone formulation premiumization and fleet procurement consolidation, with compounders capturing value through extended service interval guarantees and predictive maintenance integration.
For Market Incumbents: Extend captive silicone precursor supply through backward integration into organosilicon monomer production or long-term offtake agreements with Asian chemical producers. Deepen molding capabilities for electric-vehicle thermal loops to defend against fluoroelastomer substitution in high-performance segments. Consolidate aftermarket channel control through electronic catalog integration before fleet procurement centralization displaces regional jobber relationships.
For New Entrants and Emerging Players: Additive manufacturing of hose-form tooling offers a technology-first wedge to compress development cycles for low-volume EV programs and custom routing solutions. Target India's commercial-vehicle production gap where domestic truck and bus assembly outpaces local hose manufacturing capacity. Pursue BIS certification investments as a go-to-market angle to qualify for OEM supply relationships in Tamil Nadu and Maharashtra production clusters.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional EPDM compounders with excess mixing capacity in Shandong and Tamil Nadu, positioned for import substitution as local content rules tighten. Long-term viability favors suppliers with demonstrated multi-material bonding expertise across silicone, metal, and composite substrates. Monitor REACH alternative vulcanization validation timelines and MIIT fuel-consumption enforcement intensity as inflection indicators for reformulation investment cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Precursors | Gates Corporation's captive rubber-compounding capabilities insulate margin from Asian organosilicon monomer volatility. |
| Molded Multi-Layer Capacity Expansion | Continental's R&D intensity in battery cooling circuits captures electric-vehicle thermal-loop proliferation. |
| Fleet Procurement Analytics Integration | Schneider and J.B. Hunt national stocking agreements favor suppliers with predictive maintenance platforms. |
| REACH Alternative Vulcanization Investment | European compounders serving aftermarket channels divert capital from geographic expansion to reformulation compliance. |
| India Manufacturing Footprint Establishment | Domestic truck and bus assembly growth outpaces local hose capacity, creating import substitution openings. |
Methodological Framework
Direct dialogue with Tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and fleet maintenance directors grounded qualitative findings in operational reality. Secondary validation drew from EPA emissions filings, NHTSA safety standards documentation, MIIT fuel-consumption enforcement records, REACH regulatory updates, and vehicle production databases. Bottom-up segment sizing triangulated against top-down market consolidation assessments.
Unit and value projections across the analysis window reflect a structured analytical framework incorporating vehicle class, propulsion architecture, content per vehicle, and regional production cluster segmentation. CAGRs derived from production volume trajectories, replacement cycle compression rates, and material substitution elasticity. Industry-specific forecast inputs included EPA Corporate Average Fuel Economy standard stringency and electric-vehicle thermal-loop circuit counts per platform.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to organosilicon monomer supply concentration, REACH curing-agent restriction expansion, and fluoroelastomer cost-down curves. Practitioners should monitor fleet procurement centralization velocity, alternative vulcanization system validation timelines, and India BIS certification enforcement intensity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Electric Vacuum Pump Market
Automotive Parts
Automotive Filter Paper Market
Automotive Parts
South America Automotive Engine Oils Market
Automotive Parts
Mexico Automotive Parts Zinc Die Casting Market
Automotive Parts
Automotive Fuel Accumulator Market
Automotive Parts
Philippines Automotive Engine Oils Market
Automotive Parts
Global Automotive Plain Carbon ERW Tubes Market
Automotive Parts
Automotive Parts Aluminum Die Casting Market
Automotive Parts
Electromagnetic Clutches Market
Automotive Parts
Thailand Automotive Lubricants Market
Automotive Parts
Cycloid Gear Market
Automotive Parts
Russia Passenger Vehicles Lubricants Market
Automotive Parts
Engine Oil Market
Automotive Parts
Europe Automotive Parts Zinc Die Casting Market
Automotive Parts
North America Automotive Actuators Market
Automotive Parts
Automotive Rear Spoiler Market