
 Automotive Electric Water Pump Market | 2026-2036
Automotive Electric Water Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Electric Water Pump Market Intelligence
The channel structure between Tier-1 manufacturers and OEM procurement departments is tilting toward direct co-development partnerships. Robert Bosch GmbH leverages its extensive electronics and systems integration expertise to secure these partnerships for EV platforms. MAHLE GmbH differentiates through its specialization in comprehensive thermal management solutions. Aisin Corporation sustains its position with a strong manufacturing footprint across key Asian automotive hubs.
An automotive electric water pump is a mechatronic device that uses an electric motor to circulate coolant through a vehicle's engine and battery thermal management systems. Unlike mechanical pumps, it operates independently of engine speed, often featuring a brushless DC motor design for variable speed operation and higher efficiency. Brushless DC motor-based pumps dominate the product landscape due to their longevity and precise control capabilities. While the passenger car segment constitutes the largest application volume, the commercial vehicles segment offers higher-margin opportunities driven by durability requirements.
Regulatory frameworks, including EPA emissions standards in the United States and the EU Green Deal, mandate greater powertrain efficiency. Concurrently, China's dual carbon goals and associated GB standards for new energy vehicles directly stimulate demand for advanced electric pumps. Component suppliers now face a strategic decision: specialize in high-performance EV thermal management or compete on volume in the hybrid and ICE aftermarket.
Market Dynamics
The fundamental shift from internal combustion engines to electric and hybrid vehicle platforms is the central force shaping the market. This transition necessitates more sophisticated thermal management systems for batteries and power electronics, directly driving demand for efficient, controllable electric water pumps beyond their traditional engine cooling role.
Growth Catalysts
- Regulatory Mandates:The EU Green Deal and China's dual carbon goals enforce stringent emissions and efficiency targets, compelling automakers to adopt electric pumps to reduce parasitic losses from mechanical counterparts.
- Brushless DC Motor Technology:The inherent efficiency, longevity, and variable speed control of brushless DC motors make them the default choice for EV thermal management, where precise coolant flow is critical for battery performance.
- Commercial Vehicle TCO:Fleet operators' focus on total cost of ownership (TCO) and fuel efficiency in the commercial vehicles segment creates a strong pull for high-margin, durable electric pumps that contribute to operational savings.
Market Restraints
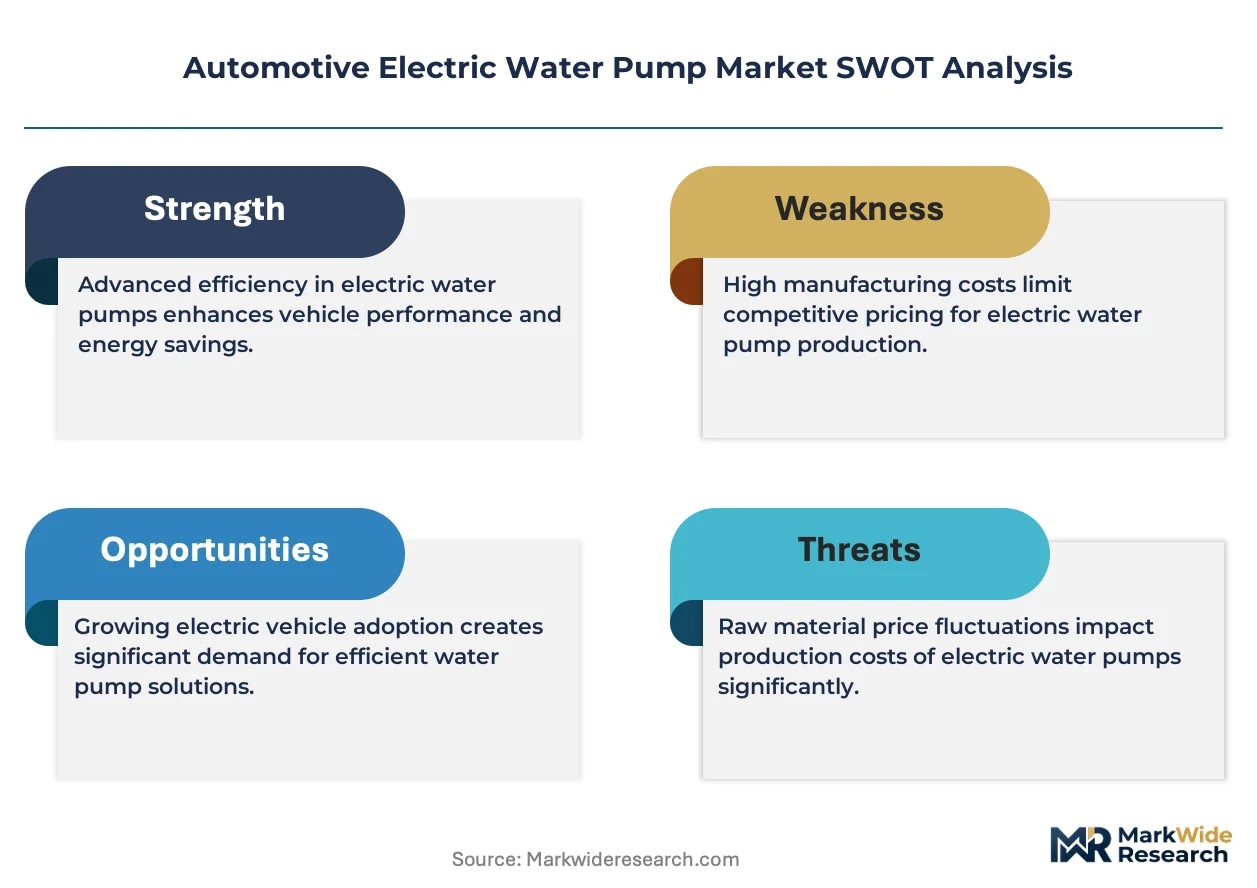
- Component Cost Premium:The higher upfront cost of advanced brushless DC electric pumps compared to traditional mechanical pumps remains a barrier to adoption in price-sensitive aftermarket and budget ICE vehicle segments.
- Semiconductor Supply Volatility:Dependence on a concentrated supply chain for microcontrollers and power electronics, primarily in Asia, exposes pump manufacturers to price fluctuations and potential production disruptions.
- Integration Complexity:Integrating smart pumps with diverse vehicle electronic architectures and validating their performance across various operating conditions presents a significant technical hurdle for Tier-1 suppliers and OEMs.
Strategic Opportunities
- Auxiliary System Cooling:There is a significant opportunity in developing specialized pumps for emerging EV applications beyond the main battery, including thermal management for high-power DC fast charging systems and advanced driver-assistance systems (ADAS) processors.
- Integrated Thermal Modules:Designing and supplying pre-validated, integrated thermal management modules that combine pumps, valves, sensors, and control logic offers a path to higher value and deeper OEM partnerships.
- Emerging EV Markets:Automotive manufacturing expansion in India and Southeast Asia presents new geographic growth frontiers as these regions increase local production of electric and hybrid vehicles.
Industry Challenges
- Protocol Standardization Gaps:A lack of standardized communication protocols, such as CAN or LIN bus message sets, across OEM platforms increases development costs and complexity for pump manufacturers aiming to supply multiple clients.
- Mechatronics Talent Scarcity:The industry faces a shortage of engineers with the combined expertise in fluid dynamics, electronic motor control, and automotive software required to design and validate advanced mechatronic pump systems.
- Durability Validation:Meeting the rigorous, long-life durability requirements for commercial vehicle applications, which often exceed 1 million kilometers, demands extensive and costly testing and validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Electric Water Pump Market |
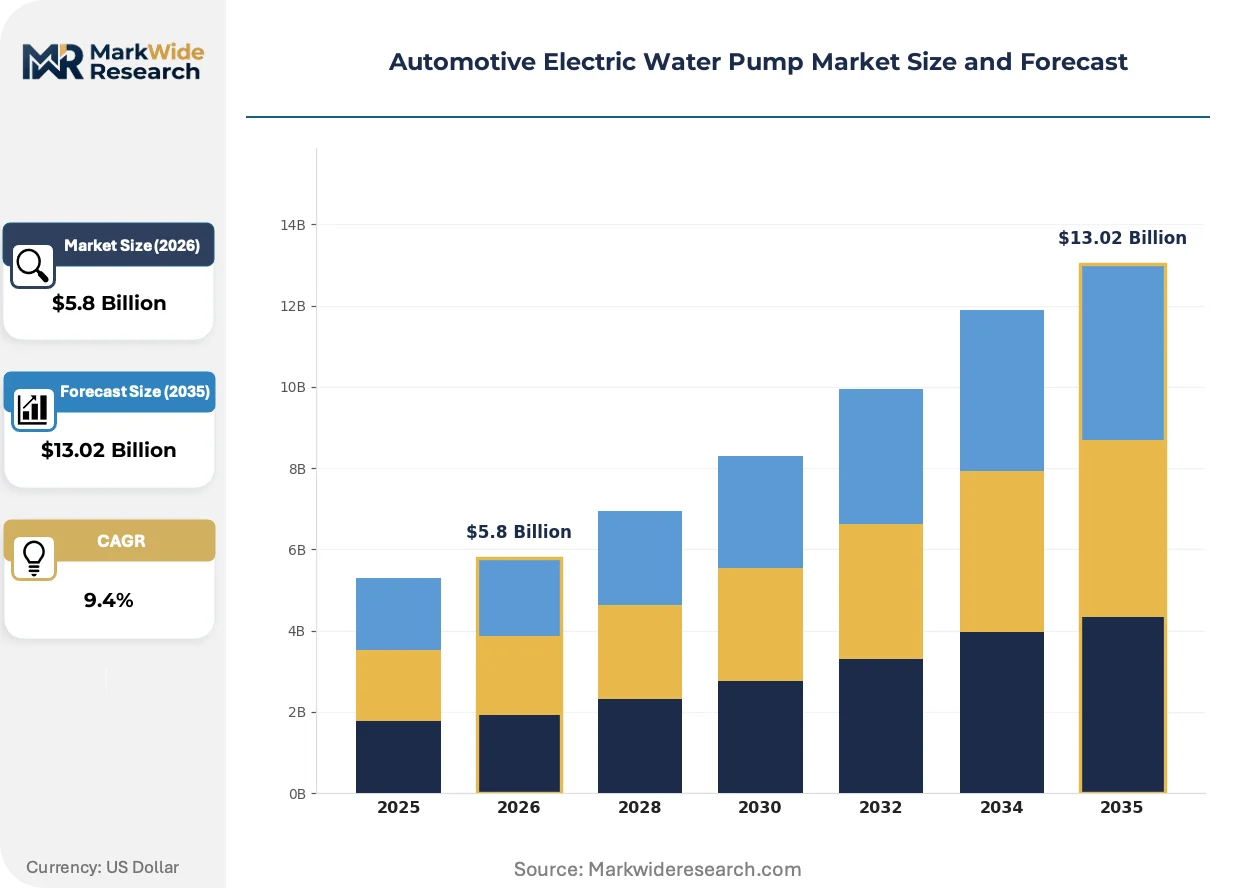
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $13.02 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Brushless DC Motors, Induction Motors, Synchronous Motors, Stepper Motors, Switched Reluctance Motors Application: Passenger Cars, Commercial Vehicles, Agricultural Machinery, Construction Equipment, Two-Wheelers End User: OEMs, Aftermarket Suppliers, Tier-1 Manufacturers, Service Centers Technology: Thermal Management, Coolant Circulation, Energy Recovery, Variable Speed Operation, Electromechanical Integration |
| Companies Covered | Schaeffler AG, Rheinmetall AG, Robert Bosch GmbH, Aisin Corporation, BLDC Pump Co., Ltd., Continental AG, Gates Corporation, MAHLE GmbH, Valeo SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Electric Water Pump Market Strategic Shifts & Innovations
Component evolution is trending toward intelligent, system-aware devices rather than simple fluid movers. The electric water pump is becoming a critical data-gathering node within the vehicle's broader thermal management network, essential for optimizing EV battery life and performance.
Sensor integration directly into the pump housing provides real-time feedback on coolant pressure, temperature, and flow. EV and high-performance vehicle manufacturers are rapidly adopting this for more granular control over battery and powertrain thermal states. The incorporation of onboard diagnostics is digitizing the pump from a passive component into an intelligent actuator that actively participates in vehicle health monitoring.
Stricter EPA emissions standards in the United States and comparable regulations globally mandate continuous improvements in powertrain efficiency. These rules create a direct incentive to eliminate parasitic losses from engine-driven accessories, including traditional mechanical water pumps. The passenger car segment, especially for hybrid models, is most affected as manufacturers are forced to adopt electric pumps to achieve compliance.
Automotive OEMs are altering their procurement models, moving from sourcing discrete components to co-developing entire thermal management subsystems with select Tier-1 suppliers. This model disrupts the conventional, transactional supplier relationship, favoring partners with deep systems integration expertise over manufacturers of standalone pumps. This collaborative approach is most visible in new EV platform development within China and Germany.
Automotive Electric Water Pump Market Segmentation
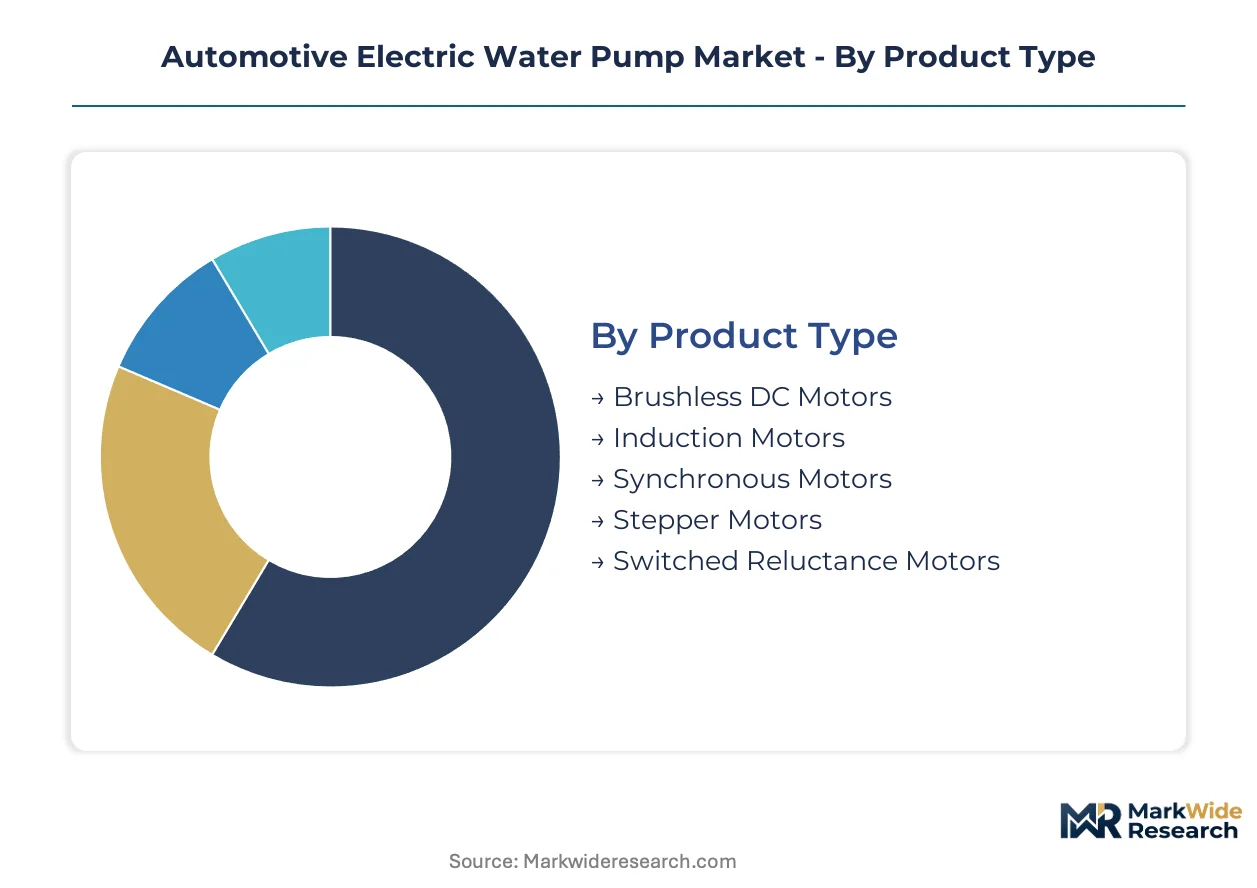
Understanding the distinct segments within the automotive electric water pump market is crucial for identifying targeted growth opportunities and strategic positioning. Each segment reflects unique technological requirements, application demands, and procurement dynamics that influence product development and market penetration strategies.
Product Type:
Technical sophistication and cost structure differentiate electric water pumps across various product types.
- Brushless DC Motors:Brushless DC motors utilize electronic commutation for variable speed control and high efficiency, making them the default choice for EV thermal management. Demand concentrates in new energy vehicle platforms across Germany and China, driven by their precise flow control capabilities.
- Induction Motors:Induction motors operate on alternating current, offering robust performance in certain industrial and automotive applications where brushless DC motor cost premium is a factor. Demand persists in cost-sensitive hybrid vehicle applications and specific heavy-duty machinery segments requiring reliable, less complex solutions.
- Synchronous Motors:Synchronous motors maintain a precise relationship between rotor speed and supply frequency, providing high efficiency and power factor. These motors find niche applications where exact speed synchronization is critical for system performance.
- Stepper Motors:Stepper motors provide precise positional control through discrete steps, commonly used in applications requiring accurate, incremental movements rather than continuous high-speed rotation. Their use in water pumps is limited to highly specialized, low-flow control systems.
- Switched Reluctance Motors:Switched reluctance motors offer a robust, fault-tolerant design with high efficiency over a wide speed range, making them suitable for demanding environments. They are considered for heavy-duty commercial vehicle applications requiring extreme durability.
Induction Motors command the established base. The steepest expansion runs through Brushless DC Motors.
Application:
Demand for electric water pumps varies significantly by vehicle application, reflecting diverse performance and durability needs.
- Passenger Cars:Passenger cars represent the largest volume application for electric water pumps, particularly within hybrid and electric vehicle models. Demand is significant in Europe due to stringent EU Green Deal regulations, compelling automakers to reduce parasitic losses and enhance fuel efficiency.
- Commercial Vehicles:Commercial vehicles offer higher-margin opportunities, driven by stringent durability requirements and fleet operators' focus on total cost of ownership. Demand is strong in North America and China, where heavy-duty trucks and buses require robust thermal management for prolonged operational cycles.
- Agricultural Machinery:Agricultural machinery uses electric pumps for engine cooling and auxiliary systems, where reliability in harsh operating conditions is paramount. These applications prioritize ruggedness and resistance to environmental factors over high-speed performance.
- Construction Equipment:Construction equipment integrates electric water pumps for thermal management in heavy-duty engines and hydraulic systems. The segment requires components capable of enduring extreme temperatures, vibrations, and extended duty cycles.
- Two-Wheelers:Two-wheelers, particularly higher-performance models and electric variants, increasingly incorporate electric water pumps for optimized engine or battery cooling. This segment focuses on compact design and efficient power consumption.
Passenger Cars consistently generate the largest volume, while Commercial Vehicles offer substantial value expansion.
End User:
The procurement and distribution channels for electric water pumps are shaped by distinct end-user requirements.
- OEMs:Original Equipment Manufacturers are the primary purchasers, integrating electric water pumps into new vehicle designs and increasingly seeking co-development partnerships. Procurement patterns in China and Germany emphasize direct collaboration for advanced EV thermal management solutions.
- Tier-1 Manufacturers:Tier-1 manufacturers act as key suppliers to OEMs, often specializing in complex mechatronic systems and thermal management modules. These suppliers leverage their systems integration expertise to secure contracts for new EV platforms, particularly in established automotive hubs.
- Aftermarket Suppliers:Aftermarket suppliers provide replacement electric water pumps for vehicle repair and maintenance, catering to a diverse installed base. Their focus is on compatibility with existing vehicle architectures and competitive pricing.
- Service Centers:Service centers primarily source electric water pumps for vehicle repairs and routine maintenance, often through OEM-approved channels or independent aftermarket distributors. Their needs revolve around component availability and ease of installation.
OEMs drive initial product development and integration, with Aftermarket Suppliers addressing replacement needs.
Technology:
Functional capabilities and operational principles define the technological segments within electric water pump systems.
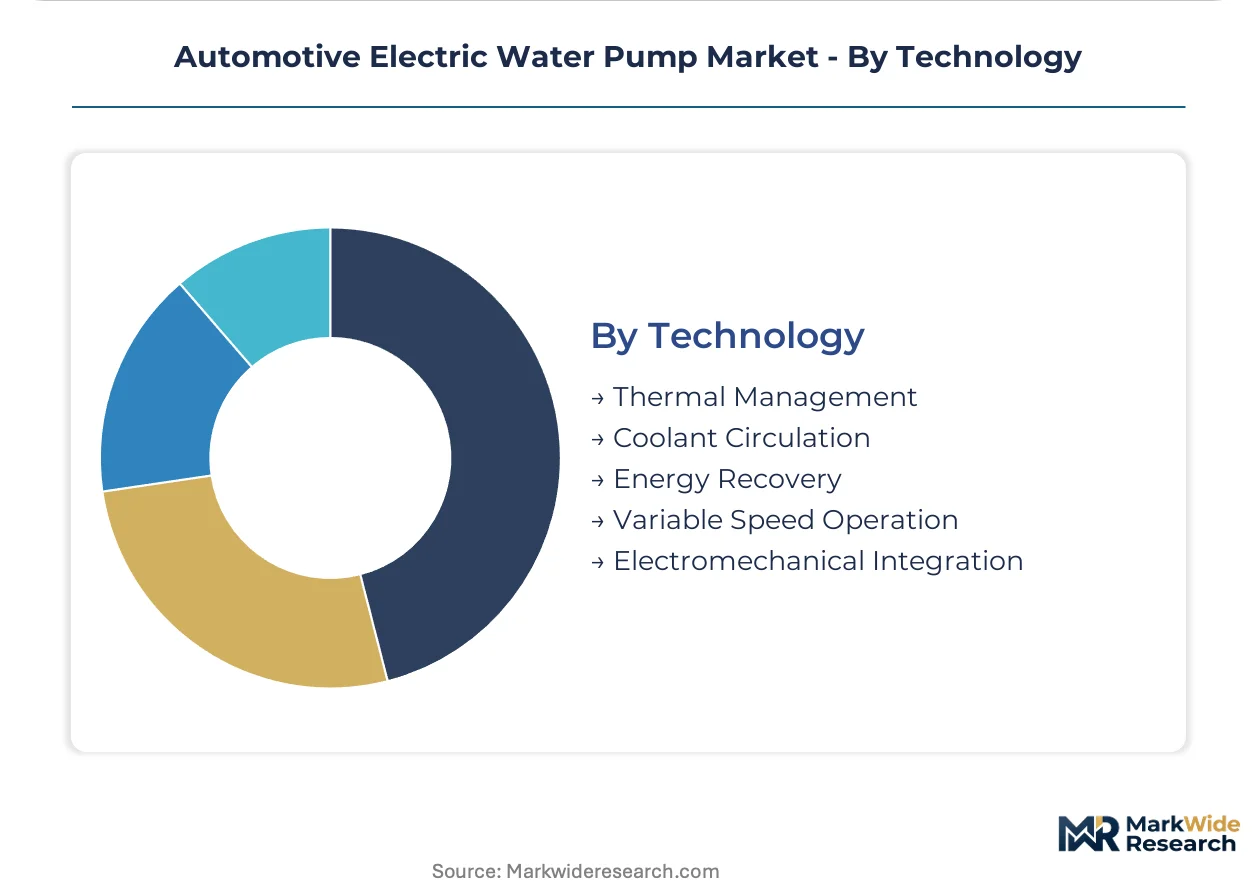
- Thermal Management:Thermal management encompasses the comprehensive control of heat within vehicle systems, including batteries, power electronics, and cabins, critical for EV performance and longevity. Demand for advanced thermal management solutions is escalating across all major automotive markets, especially for high-performance electric vehicles.
- Variable Speed Operation:Variable speed operation allows electric pumps to adjust coolant flow precisely based on real-time thermal demands, optimizing efficiency and reducing energy consumption. This capability is paramount for battery thermal management in electric vehicles, ensuring optimal operating temperatures for cell longevity.
- Coolant Circulation:Coolant circulation represents the fundamental function of moving coolant throughout the engine or battery cooling loop to dissipate heat. This core technology is present in all electric water pump applications.
- Energy Recovery:Energy recovery technologies, though less common in pumps themselves, relate to systems that capture waste heat for reuse, enhancing overall vehicle efficiency. Future pump designs may integrate with these broader energy management strategies.
- Electromechanical Integration:Electromechanical integration involves combining the electric motor, pump hydraulics, and control electronics into a single, cohesive unit. This integration optimizes packaging, communication, and overall system performance within the vehicle architecture.
Coolant Circulation represents the foundational function, while Electromechanical Integration represents the fastest-growing trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing-power asymmetry exists between established automotive manufacturing regions and emerging markets. While Germany and China drive significant demand and technological adoption for electric water pumps, the cost structures and procurement models vary, influencing market penetration and supplier strategies across different geographies.
Germany
Demand in Germany is high for advanced electric water pumps, driven by a strong automotive manufacturing base and the rapid electrification of vehicle fleets. The EU Green Deal mandates stringent emissions reductions, compelling German automakers to integrate efficient thermal management solutions. Manufacturing clusters in Bavaria and Baden-Württemberg lead in co-development partnerships for new electric vehicle platforms.
China
China presents a vast market for electric water pumps, fueled by ambitious new energy vehicle production targets and a focus on domestic innovation. The country's dual carbon goals and associated GB standards directly stimulate demand for high-efficiency pumps in both passenger and commercial vehicles. Major automotive hubs like the Yangtze River Delta and Pearl River Delta are centers for both manufacturing and advanced thermal management system integration.
United States
The United States market for electric water pumps is expanding, particularly in commercial vehicles and hybrid passenger cars, due to evolving emissions standards. EPA regulations push automakers to reduce parasitic losses from traditional mechanical pumps, driving the adoption of electric alternatives. Automotive manufacturing regions in the Midwest and Southeast are seeing increased investment in electric vehicle component production.
India
India represents an emerging growth frontier for electric water pumps, as the country's automotive sector pivots towards electric and hybrid vehicle production. Government initiatives and PLI schemes encourage local manufacturing and technology adoption in new energy vehicles. Industrial corridors in Maharashtra and Tamil Nadu are attracting investments for automotive component production, including advanced thermal management systems.
Automotive Electric Water Pump Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, providing critical mechatronic solutions. The market structure for automotive electric water pumps is characterized by a tiered ecosystem, where large Tier-1 suppliers with extensive systems integration capabilities secure deep OEM partnerships. Two strategic archetypes dominate: comprehensive thermal management specialists and electronics-focused system providers. Competitive moves center on co-development agreements and expanding manufacturing footprints in key automotive regions.
Within the systems integration and specialized component tiers, Robert Bosch GmbH and MAHLE GmbH exemplify strong positions, leveraging their expertise in electronics and thermal management respectively. Aisin Corporation, a Japanese manufacturer, sustains its market presence through a robust manufacturing network across key Asian automotive hubs. These companies anchor the market by providing sophisticated electric water pump solutions for advanced vehicle platforms.
| Leading Market Players |
|---|
| Schaeffler AG |
| Rheinmetall AG |
| Robert Bosch GmbH |
| Aisin Corporation |
| BLDC Pump Co., Ltd. |
| Continental AG |
| Gates Corporation |
| MAHLE GmbH |
| Valeo SA |
| Others |
Cost & Logistics Intelligence
The Trans-Pacific shipping lanes' cost volatility directly impacts component pricing, influencing supply concentration in Asian manufacturing hubs and shaping downstream price differentiation for automotive electric water pumps. This dynamic creates both cost pressures and strategic opportunities for market participants.
Pricing Analysis
Configured-to-order pricing for specialized EV thermal management modules contrasts with standard per-unit transactional pricing in the aftermarket. Price differentiation stems from customization level for co-developed solutions and rigorous automotive certification standards. Cost compression in the aftermarket is intensifying due to numerous suppliers and replacement demand. OEMs for high-performance EV platforms exhibit lower price sensitivity, prioritizing performance and reliability, while aftermarket buyers remain highly price-sensitive.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities often characterize relationships between Tier-1 suppliers and OEMs. Supply concentration for advanced electric water pumps centers on China, Germany, and Japan. The industry draws heavily from microcontrollers, power electronics, and specialized magnets. Semiconductor supply volatility presents a structural risk to production schedules. Distribution runs primarily direct to OEM procurement, with aftermarket channels relying on regional distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive electric water pump market highlights a critical gap in mechatronics engineering talent. This scarcity impacts the design and validation of complex thermal management systems for new energy vehicles.
For Market Incumbents: Build a deep intellectual property moat around advanced thermal management algorithms and control software. Incumbents should secure long-term co-development partnerships with OEMs, investing in manufacturing capacity within China and Germany. This defends against emerging specialists offering integrated thermal modules. Certification investment in new EV platforms becomes a critical lever against component commoditization.
For New Entrants and Emerging Players: Pursue niche applications in auxiliary system cooling for high-power ADAS processors and DC fast charging systems. The emerging EV markets in India and Southeast Asia represent highly penetrable geographies for specialized component providers. Offering pre-validated, integrated thermal modules with standardized communication protocols provides a compelling go-to-market angle. This strategy avoids direct competition in established engine cooling segments.
For Investors and Strategic Acquirers: Specialized mechatronics firms with deep software integration expertise represent attractive acquisition targets. The long-term viability of advanced thermal management solutions remains robust over the next decade, driven by EV proliferation. Investors should prioritize companies demonstrating proven capabilities in brushless DC motor control and sensor integration. The adoption rate of integrated thermal modules by mainstream OEMs is the signal to watch for market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Standardized interfaces reduce integration complexity for multiple OEM platforms. |
| Software-Defined Thermal Management | Advanced algorithms optimize EV battery life and powertrain efficiency. |
| Geographic Manufacturing Expansion | Local production in India and Southeast Asia addresses emerging EV demand. |
| Integrated Module Development | Bundled thermal solutions offer higher value and deeper OEM partnerships. |
| Advanced Material Research | Lightweight, durable materials enhance pump performance and longevity. |
Research Approach
Operator-level perspectives from OEM platform engineers, Tier-1 procurement leads, and thermal management R&D directors anchored the qualitative base. This primary research combined with secondary validation from automotive industry reports, regulatory filings, and patent databases. A rigorous bottom-up and top-down triangulation approach ensured data consistency. This dual methodology provided a comprehensive market view.
Scenario-bracketing across conservative and optimistic growth trajectories defined the forecast framework over the projection horizon. Segmentation dimensions modeled included product type, application, end-user, and vehicle propulsion type. Compound annual growth rates were derived from historical data, expert consensus, and regulatory impact analysis. Key forecast inputs included global EV production targets and regional emissions reduction mandates.
Macroeconomic conditions sit as an overlay; deviation in raw material prices or geopolitical stability would shift the trajectory. Forecasts reflect assumptions documented at the time of analysis. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Two-Wheeler Lubricants Market
Automotive Parts
Brake Fluids Market
Automotive Parts
Automotive Suspension Control Arms Market
Automotive Parts
Automotive Coolant Market
Automotive Parts
Autocatalyst Market
Automotive Parts
Automotive Electric Vacuum Pump Market
Automotive Parts
Uae Passenger Vehicles Lubricants Market
Automotive Parts
South Africa Automotive Parts Aluminium Die Casting Market
Automotive Parts
Automotive Seat Track Market
Automotive Parts
Suspension Bump Stopper Market
Automotive Parts
Asia Pacific Automotive Parts Die Casting Market
Automotive Parts
Automotive Forging Market
Automotive Parts
Automotive Evaporators and Blowers Market
Automotive Parts
Automotive Fuel Accumulator Market
Automotive Parts
Timing Gear Market
Automotive Parts
Oil Filter Market