
 Gear Box and Gear Motors Market | 2026-2036
Gear Box and Gear Motors Market Size, Share, and Industry Trends Forecast 2026-2036
Gear Box and Gear Motors Market Analysis
Modular drive-train bundling is repositioning buyer choice toward integrated motor-gearbox units that slash installation time and footprint. SEW-EURODRIVE GmbH & Co KG dominates this configuration through captive manufacturing of both motors and precision gearing. Siemens AG leverages digital twin integration to differentiate its bundled offerings across process industries. Bonfiglioli Transmissions Private Limited anchors its competitive stance with specialized planetary and helical modules for mobile and wind applications.
Gear boxes and gear motors are mechanical power-transmission devices that reduce motor output speed while multiplying torque through meshing gear trains, typically operating at efficiency ratings between 94% and 98% in helical configurations and serving as the critical drivetrain interface between prime movers and industrial loads. Planetary gear configurations command the highest torque-density margins and attract premium positioning in robotics and aerospace end uses, while worm gear architectures occupy mature, cost-sensitive niches in conveying and material handling. Electric technology leads absolute volume across all applications, though hydraulic variants sustain durable demand in heavy-lift material handling where stall torque and shock loading dominate operational requirements.
FDA machinery safety guidelines, ISO 6336 gear-rating standards, and EU machinery directives collectively shape product certification requirements and barrier-to-entry dynamics for suppliers serving regulated industries. EPA energy-efficiency frameworks in the United States and REACH material-compliance protocols in Europe further constrain lubricant chemistry and housing alloy selection. Stakeholders must monitor evolving carbon-border adjustments and regional content thresholds that threaten to fragment supply chain configurations and qualification costs.
Market Dynamics
Modular drive-train bundling is compressing procurement cycles as buyers shift from discrete component sourcing to integrated motor-gearbox units, forcing suppliers to recalibrate manufacturing footprints and captive component strategies.
Growth Catalysts
- EU Machinery Directives:Mandatory efficiency upgrades across industrial equipment are accelerating replacement demand for precision helical and planetary configurations in automated assembly environments.
- Robotics End-Use Expansion:Automated assembly lines in automotive and electronics manufacturing are pulling high-torque-density planetary gear configurations into volume deployment.
- ISO 6336 Standards:Gear-rating certification requirements are filtering out non-compliant suppliers and consolidating procurement toward qualified tier-one manufacturers.
Market Restraints
- Specialized Alloy Supply Concentration:Housing and gear blank production clusters in Germany and China create input vulnerability for non-integrated suppliers.
- REACH Lubricant Chemistry Constraints:European material-compliance protocols are eliminating conventional additive packages and forcing reformulation costs onto smaller manufacturers.
- Hydraulic Substitution in Heavy-Lift:Electric gear motor architectures face persistent displacement risk in material handling applications where stall torque and shock loading dominate operational requirements.
Strategic Opportunities
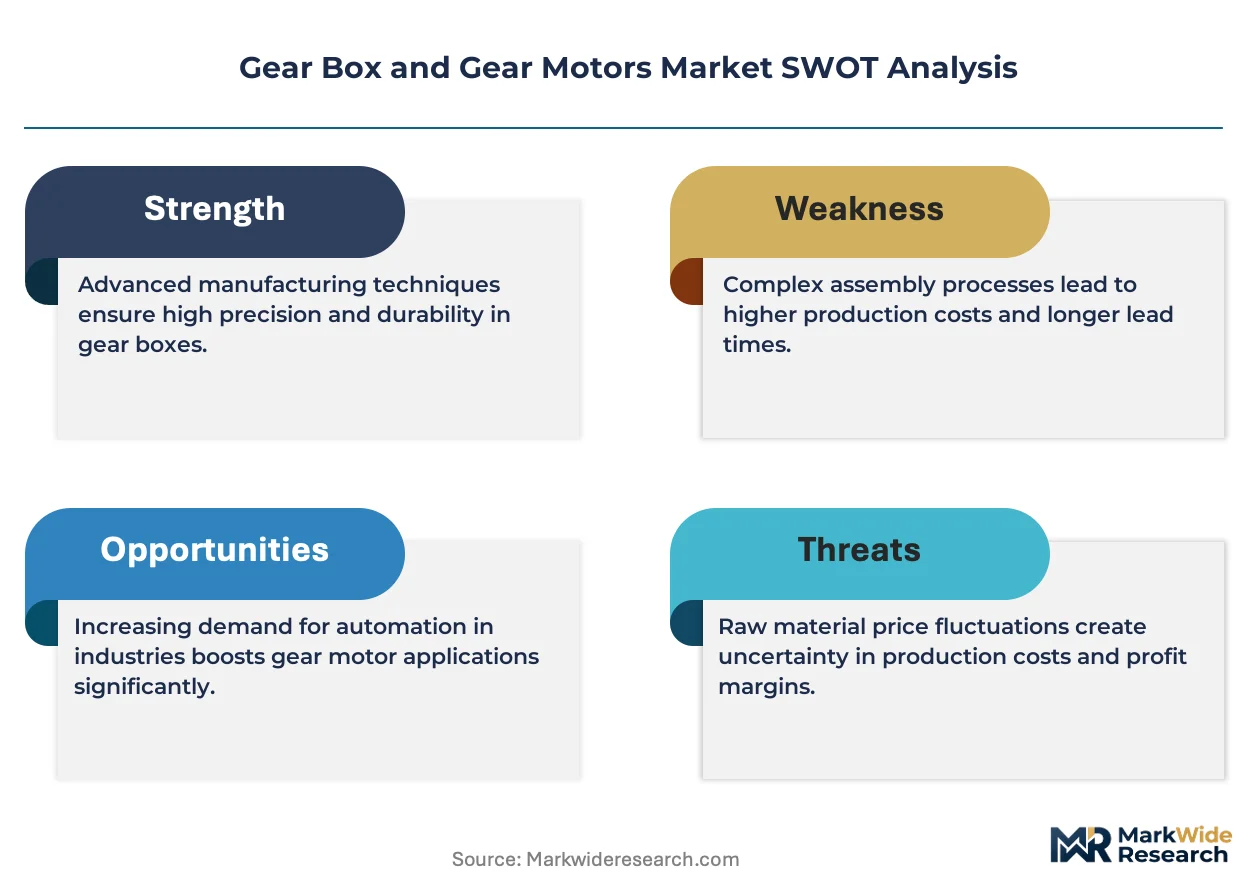
- Wind Energy Servicing:Specialized planetary and helical modules for turbine drivetrain maintenance represent underpenetrated aftermarket volume in coastal installations.
- Digital Twin Convergence:Integration of condition monitoring with predictive maintenance algorithms is creating premium pricing power for sensor-embedded gear motor bundles.
- Carbon Border Adjustments:Emerging regional content thresholds in the EU and United States are creating first-mover advantage for suppliers with localized alloy sourcing and assembly.
Industry Challenges
- Precision Grinding Skill Scarcity:Gear tooth profile finishing and heat treatment expertise is concentrating among aging workforces in traditional manufacturing clusters.
- Multi-Standard Certification Timelines:Simultaneous FDA machinery safety, ISO 6336, and EU machinery directive qualification is extending product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gear Box and Gear Motors Market |
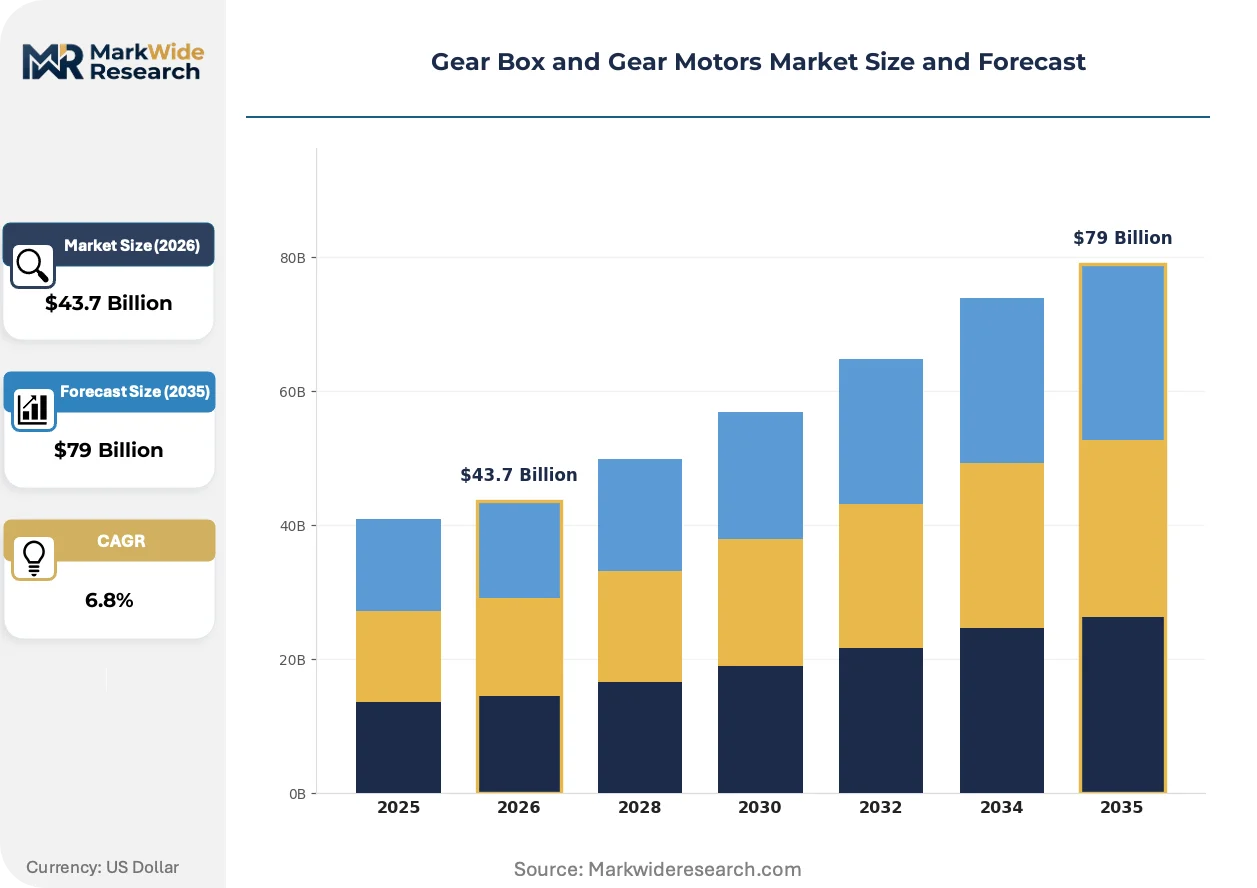
| Market Size in 2026 | $43.7 Billion |
| Market Size in 2035 | $79 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Helical, Bevel, Worm, Planetary End User: Automotive, Aerospace, Manufacturing, Robotics Technology: Electric, Hydraulic, Pneumatic, Mechanical Application: Material Handling, Power Transmission, Conveying, Packaging |
| Companies Covered | Bonfiglioli Transmissions Private Limited, Regal Rexnord Corporation, SEW-EURODRIVE GmbH & Co KG, ABB Ltd., Siemens AG, Sumitomo Heavy Industries, Lenze SE, Mitsubishi Electric Corporation, Nord Drivesystems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gear Box and Gear Motors Market Emerging Trajectories
Additive manufacturing is penetrating gear blank prototyping and low-volume production, compressing design iteration cycles and enabling topology-optimized tooth profiles previously impossible with conventional subtractive methods.
Topology-optimized metal powder bed fusion is absorbing development-stage tooling costs for custom gear ratios and hollow-shaft configurations. Medical device and aerospace OEMs are adopting these printed prototypes for validation runs before hard-tooling commitments. The technology is absorbing traditional forging and machining volume in sub-500 unit production tiers.
EPA energy-efficiency frameworks in the United States are tightening motor-gearbox system labeling requirements and test protocols. Industrial buyers now face mandatory disclosure of combined efficiency ratings across operating load curves. Process industry procurement in chemical and food processing plants is filtering specifications to NEMA Premium and IE4-equivalent bundled systems.
Buyer concentration among automotive tier-one suppliers is compressing contract negotiation cycles and unbundling traditional after-sales service packages. Direct sourcing agreements with gearbox specialists are displacing distributor-mediated procurement in high-volume assembly line deployments. This pattern is most visible in German and United States automotive manufacturing clusters where plant-level engineering teams specify drivetrain components independently of corporate motor procurement contracts.
Gear Box and Gear Motors Market Segmentation
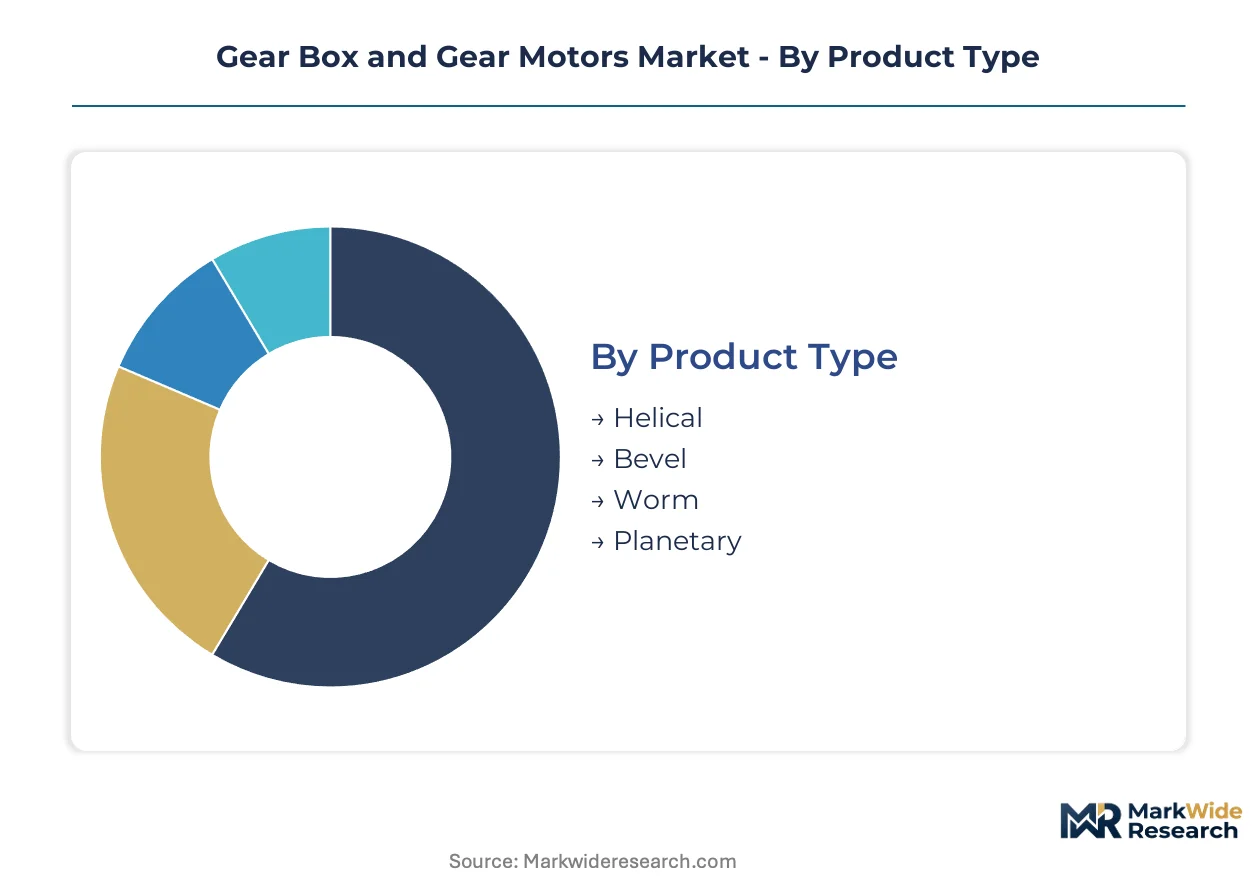
Gear box and gear motor procurement decisions hinge on torque density requirements, duty cycle intensity, and integration complexity. Buyers evaluate trade-offs between first-cost economics and lifecycle efficiency across discrete mechanical configurations and power transmission technologies.
Product Type:
Cost tier determines specification authority, with premium helical and planetary units commanding engineering-led procurement while worm and bevel variants follow price-sensitive maintenance budgets.
- Helical:Angled tooth engagement distributes load across multiple contact points, achieving 94-98% efficiency ratings in continuous-duty industrial environments. Automotive powertrain testing facilities in Germany and the United States specify these for durability validation rigs where thermal stability under sustained torque matters.
- Planetary:Concentric gear arrangements deliver the highest torque-to-weight ratios available in commercial power transmission. Robotics OEMs in Japan and aerospace actuator suppliers in France absorb premium pricing for compact multi-stage configurations that preserve payload capacity.
- Bevel:Right-angle power transfer suits space-constrained drivetrain layouts in packaging machinery and printing presses.
- Worm:Single-stage speed reduction with inherent locking characteristics dominates low-speed conveying applications where back-driving prevention justifies efficiency penalties.
Helical leads on scale; planetary leads on momentum.
End User:
Application maturity shapes vendor relationships, with established automotive and manufacturing sectors favoring qualified incumbent suppliers while robotics creates openings for specialized entrants.
- Automotive:Stamping press lines and paint shop conveyors consume high-volume helical and bevel units under fixed preventive maintenance schedules. Tier-one suppliers in Stuttgart and Detroit negotiate multi-year frame contracts that lock in volume pricing and spare parts availability.
- Robotics:Collaborative robot joints and autonomous mobile platforms demand zero-backlash harmonic and planetary precision gearing. Startups in Shenzhen and Boston source compact integrated actuators from captive motor-gearbox specialists rather than traditional industrial distributors.
- Aerospace:Flight control surface actuation and landing gear systems require certified aerospace-grade gearing with full material traceability.
- Manufacturing:General industrial machinery spans the full product spectrum from economy worm drives to precision servo-matched planetary systems.
Automotive leads on scale; robotics expands most quickly.
Technology:
Supply concentration dictates availability risk, with electric motor manufacturing scaling globally while hydraulic component sourcing remains concentrated in German and Italian industrial clusters.
- Electric:AC induction and permanent magnet synchronous motors paired with precision gearing dominate new installations across food processing, automotive assembly, and warehouse automation. NEMA Premium and IE4 efficiency mandates in the United States and European Union filter procurement toward integrated high-efficiency bundles.
- Hydraulic:Fluid power systems sustain durable demand in steel mill roughing stands, port cargo cranes, and mining haul trucks where stall torque and shock loading exceed electric motor thermal limits. Maintenance departments in Rotterdam port terminals and Pittsburgh steelworks retain hydraulic expertise that resists electrification conversion.
- Pneumatic:Compressed air drives serve light-duty positioning and clamping in explosive atmospheres where electrical spark risk is prohibitive.
- Mechanical:Direct mechanical linkages persist in legacy installations and safety-critical applications requiring positive isolation from power sources.
Electric leads on scale; hydraulic retains defensive positioning in heavy-lift niches.
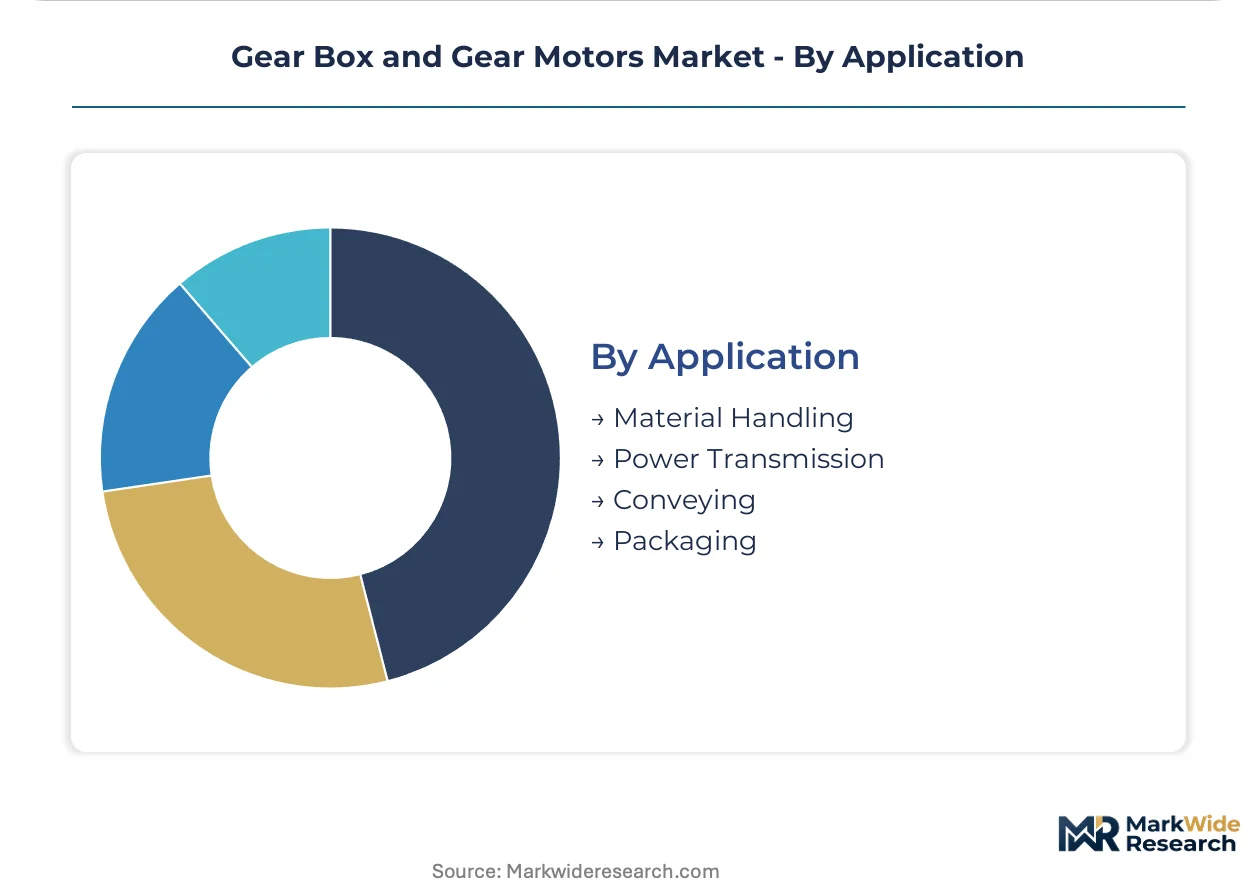
Application:
Customer type determines service intensity, with OEM machinery builders demanding engineering partnership while end-user facilities prioritize parts availability and swap-out speed.
- Material Handling:Overhead cranes, automated storage retrieval systems, and port container handling equipment subject gearboxes to intermittent shock loads and high-starting-torque demands. Harbor authorities in Hamburg and Singapore specify planetary and helical units with 50,000-hour design lives for continuous cargo throughput.
- Power Transmission:Industrial drivetrain infrastructure including pumps, compressors, and mixers requires reliable speed reduction across chemical plants, water treatment facilities, and oil refineries. Operators along the U.S. Gulf Coast and Rotterdam petrochemical corridor prioritize corrosion-resistant housings and synthetic lubricant compatibility.
- Conveying:Belt and chain transport systems in distribution centers and mining operations favor cost-optimized worm and helical configurations.
- Packaging:High-speed carton forming and palletizing machinery demands precise servo-matched gearing for synchronized motion control.
Material handling leads on scale; power transmission shows steadiest replacement demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered precision gear manufacturing during the industrial revolution, establishing standards still referenced worldwide. Today, production clusters span three continents with distinct regulatory and demand profiles.
Germany
Automotive powertrain testing facilities and wind turbine servicing operations drive helical and planetary unit procurement. EU machinery directives and REACH lubricant chemistry protocols filter supplier qualification toward integrated manufacturers. Stuttgart and Dortmund industrial corridors anchor captive production of alloy gear blanks and precision-ground components.
China
Robotics OEMs in Shenzhen and automated assembly lines across the Yangtze Delta absorb compact integrated motor-gearbox bundles. MIIT efficiency mandates and GB standards accelerate displacement of legacy worm configurations. Shanghai and Suzhou manufacturing clusters concentrate planetary gear production for export and domestic automation deployment.
United States
Automotive stamping press lines and Gulf Coast petrochemical infrastructure sustain replacement demand for corrosion-resistant helical units. EPA energy-efficiency frameworks and NEMA Premium motor standards reshape procurement specifications. Detroit and Houston industrial basins host qualified tier-one distributors with captive spare parts logistics.
Japan
Collaborative robot joint actuators and precision servo-matched gearing pull high-torque-density configurations from specialized suppliers. METI industrial efficiency programs and JIS certification requirements sustain barrier-to-entry dynamics. Nagoya and Osaka manufacturing belts concentrate harmonic and planetary precision gearing for aerospace and medical device OEMs.
India
Automotive assembly expansion and material handling infrastructure in Gujarat and Maharashtra generate volume demand for cost-optimized helical and bevel configurations. BIS mechanical safety standards and PLI scheme incentives attract gearbox specialists to establish localized assembly. Pune and Chennai industrial corridors emerge as sourcing hubs for Southeast Asian automotive tier-one suppliers.
Gear Box and Gear Motors Market Vendor Landscape
The competitive structure tilts toward vertically integrated specialists with captive motor and gearing production. Tier-one manufacturers with in-house alloy sourcing and precision grinding capacity command qualification advantages under ISO 6336 and EU machinery directive protocols. Three archetypes dominate: German-engineered integrated drive-train bundlers, Japanese precision robotics specialists, and Chinese scale-oriented automation suppliers. Consolidation pressure intensifies as automotive tier-one buyers compress contract cycles and displace distributor-mediated procurement.
Among European-anchored integrated manufacturers, SEW-EURODRIVE GmbH & Co KG and Siemens AG exemplify the bundled motor-gearbox archetype with digital twin integration capabilities. Bonfiglioli Transmissions Private Limited occupies a specialized position in planetary and helical modules for mobile equipment and wind energy applications. These three represent distinct competitive vectors: captive component manufacturing, software-enabled predictive maintenance, and application-specific engineering depth.
| Leading Market Players |
|---|
| Bonfiglioli Transmissions Private Limited |
| Regal Rexnord Corporation |
| SEW-EURODRIVE GmbH & Co KG |
| ABB Ltd. |
| Siemens AG |
| Sumitomo Heavy Industries |
| Lenze SE |
| Mitsubishi Electric Corporation |
| Nord Drivesystems |
| Others |
Supply Flow & Price Mechanics
Precision grinding expertise clustering in Stuttgart and Dortmund industrial corridors feeds directly into labor-cost spreads between premium helical configurations and economy worm gear tiers. German metallurgical skill premiums sustain three-tier pricing stratification across integrated motor-gearbox bundles.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs procurement, with ISO 6336 certification grade and captive motor manufacturing anchoring premium positioning. Price differentiation separates NEMA Premium efficiency tiers from IE4-equivalent bundles and legacy unlabeled configurations. Cost compression in standard helical segments is intensifying because automotive tier-one buyers unbundle after-sales service packages. Maintenance departments in material handling applications exhibit highest price sensitivity, while robotics OEMs in Japan and aerospace actuator suppliers absorb premium positioning for zero-backlash planetary configurations.
Supply Chain Analysis
Single-source vulnerability sits with specialized alloy gear blank production clustering in Germany and China, creating input fragility for non-integrated suppliers. Housing and precision-ground component sourcing draws from Stuttgart, Dortmund, Shanghai, and Suzhou manufacturing belts. Raw material dependencies rest on high-grade steel alloys, synthetic lubricant formulations, and rare-earth permanent magnets for servo-matched configurations. Tariff exposure on alloy imports threatens to fragment qualification costs for suppliers serving EU and United States markets. Distribution runs through qualified tier-one distributors with captive spare parts logistics in Detroit and Houston industrial basins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with robotics end-use expansion pulling specification authority toward premium planetary and helical configurations that command pricing power through ISO 6336 certification and digital twin integration.
For Market Incumbents: Extend captive motor-gearbox bundling advantages by deepening precision grinding capacity in established German clusters and accelerating digital twin convergence for predictive maintenance offerings. Hydraulic substitution risk in heavy-lift material handling demands defensive positioning through servo-matched electric architectures that match stall torque performance. Certification investment under simultaneous FDA machinery safety, ISO 6336, and EU machinery directive protocols sustains barrier-to-entry dynamics against emerging Asian competitors. For New Entrants and Emerging Players: Additive manufacturing-enabled topology optimization offers entry into sub-500 unit production tiers for medical device and aerospace prototyping applications. Wind energy servicing for coastal turbine drivetrain maintenance represents the most penetrable aftermarket segment, with specialized planetary modules commanding premium positioning absent from incumbent volume strategies. Direct sourcing relationships with Shenzhen robotics startups bypass established distributor networks that automotive tier-one suppliers have already displaced. For Investors and Strategic Acquirers: Industrial automation conglomerates seeking drivetrain integration are the most active acquirer in this space, targeting precision grinding specialists with aging workforce concentrations in traditional manufacturing clusters. Five-to-ten year viability hinges on carbon border adjustment compliance and localized alloy sourcing capabilities that preempt emerging regional content thresholds. Watch for carbon border adjustment implementation timelines as the critical inflection indicator for supply chain reconfiguration urgency.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Gear Blank Production | Captive supply of precision-ground components from Stuttgart and Dortmund clusters secures ISO 6336 qualification advantages. |
| Digital Twin Platform Integration | Siemens AG leverages condition monitoring algorithms to differentiate bundled offerings across process industries. |
| Carbon Border Adjustment Compliance Program | Localized sourcing and assembly in EU and United States markets creates first-mover positioning against tariff exposure. |
| Wind Energy Servicing Partnership | Specialized planetary modules for coastal turbine maintenance unlock underpenetrated aftermarket volume. |
| Additive Manufacturing Capability Buildout | Topology-optimized prototyping absorbs development-stage tooling costs for custom gear ratios and hollow-shaft configurations. |
Methodological Framework
Bottom-up robotics and automotive end-use modeling reconciled against top-down precision grinding capacity and alloy supply tracking forms the analytical core of this study. Primary interviews with maintenance directors at port cargo terminals, plant engineers in automotive stamping facilities, OEM procurement teams at robotics specialists, and aftermarket service heads in wind energy servicing operations combined with secondary validation from customs trade data, SEC 10-K filings, MIIT efficiency mandate disclosures, and EU machinery directive implementation records. Triangulation across these sources ensures segmentation integrity across helical, planetary, bevel, and worm configurations.
Input-output matrices map gear blank production capacity through precision grinding utilization rates to end-use demand absorption across material handling, power transmission, conveying, and packaging applications. Segmentation dimensions span product type, end user, technology, and application, with regional regulatory clusters modeled separately for EU machinery directive, EPA energy-efficiency framework, and MIIT efficiency mandate compliance tiers. CAGRs derive from installed base replacement cycles and new automation deployment trajectories, incorporating robotics end-use expansion rates and wind energy servicing penetration assumptions.
The model holds under stable alloy supply concentration and sustained regulatory enforcement; deviation in carbon border adjustment timelines or REACH lubricant chemistry reformulation scope would shift competitive positioning toward localized manufacturers. Forecasts reflect documented assumptions regarding efficiency mandate adoption curves and robotics deployment trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Spare Wheel Carrier Market
Automotive Parts
Automotive Brake Actuator Market
Automotive Parts
France Automotive Parts Zinc Die Casting Market
Automotive Parts
Steel Cords for Radial Tyres Market
Automotive Parts
Air Filter Cartridges Market
Automotive Parts
Automotive Crankshaft Materials Market
Automotive Parts
Automotive Hoses Market
Automotive Parts
Automotive OEM Brake Friction Material Market
Automotive Parts
Global Passenger Vehicles Lubricants Market
Automotive Parts
Colombia Passenger Vehicles Lubricants Market
Automotive Parts
Global Inductive Loop Vehicle Detector Market
Automotive Parts
Large Volume Injector Market
Automotive Parts
Philippines Automotive Lubricants Market
Automotive Parts
Norway Passenger Vehicles Lubricants Market
Automotive Parts
Norway Automotive Engine Oils Market
Automotive Parts
Automotive Propeller Shaft Couplings Market