
 France Commercial Vehicles Lubricants Market | 2026-2036
France Commercial Vehicles Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
France Commercial Vehicles Lubricants Market Foresight
The capability gap between integrated refiners and independent blenders is unwinding as formulation complexity rises. TotalEnergies leverages its domestic refining base and additive partnerships to control cost structures across engine oils and hydraulic fluids. BP PLC (Castrol) anchors its position through service workshop networks that lock in fleet maintenance contracts with Paris-based logistics operators. FUCHS specializes in high-performance gear oils for construction equipment, competing on technical service rather than volume scale.
France commercial vehicles lubricants are formulated base oil and additive packages engineered to manage thermal stress, wear protection, and friction reduction in diesel and increasingly natural gas engines operating under stop-start urban cycles and sustained highway loads. Engine oils dominate volume demand due to shorter drain intervals in heavy-duty trucks subjected to EURO VI emission system thermal loading, while synthetic hydraulic fluids represent the fastest-growing margin pool as construction firms adopt precision excavator fleets requiring fire-resistant, biodegradable formulations. The vehicle type split reveals heavy-duty trucks as the mature revenue base and delivery vans as the growth vector driven by last-mile electrification logistics serving Amazon and Carrefour distribution networks.
ANSM oversees chemical substance compliance for lubricant formulations marketed in France, while REACH mandates disclosure and restriction of certain additive chemistries including zinc dialkyldithiophosphate concentrations. The EU F-Gas Regulation indirectly shapes coolant demand profiles for transport refrigeration units integrated into commercial vehicle fleets. Fleet managers and lubricant procurement officers must track the implementation timeline of France's RE2020 environmental regulations and assess whether extended-drain synthetic investments align with residual value calculations for internal combustion engine assets.
Market Dynamics
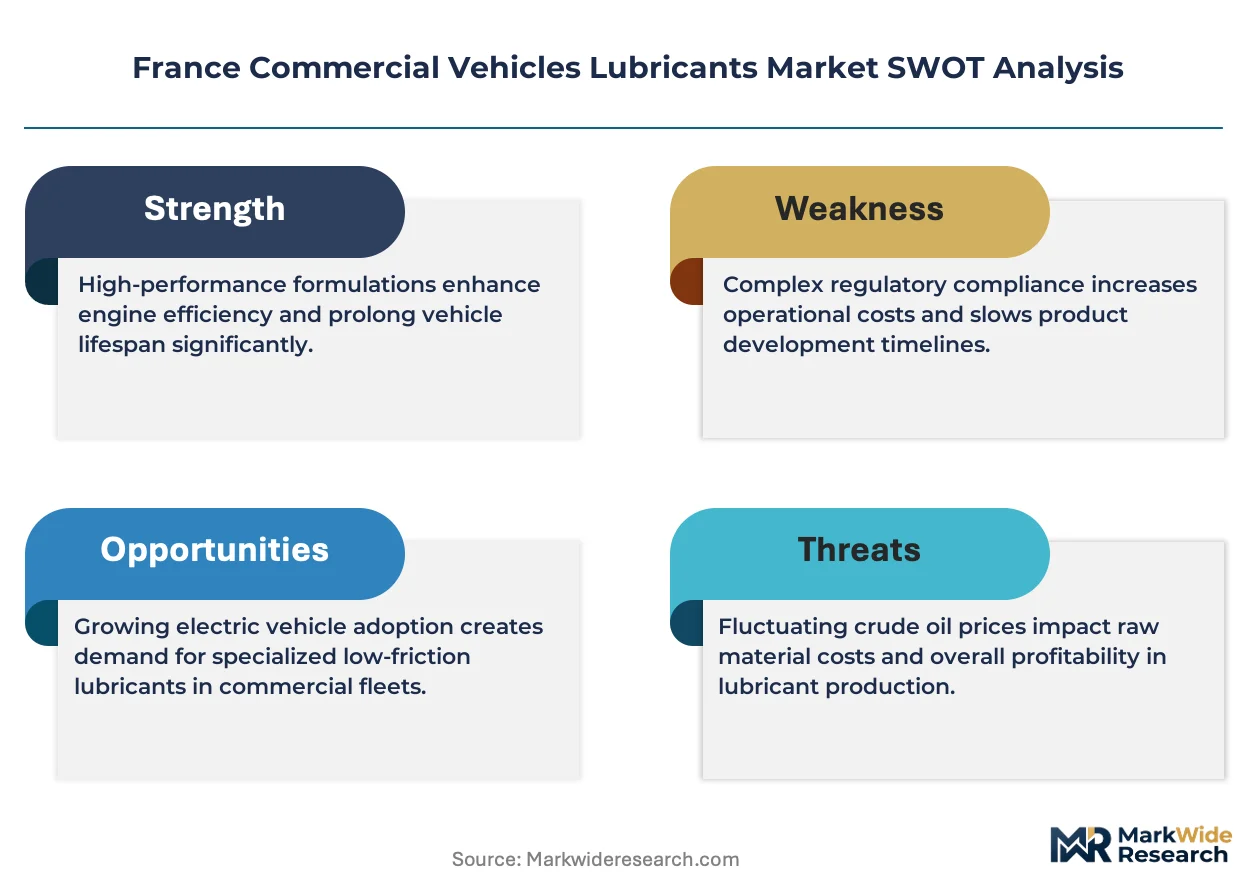
EURO VI thermal loading on exhaust aftertreatment systems is compressing drain intervals for heavy-duty truck fleets, forcing reformulation investments across the French supply base while synthetic alternatives capture margin from mineral-based volumes.
Growth Catalysts
- Île-de-France logistics corridor expansion:Amazon and Carrefour distribution networks are densifying last-mile van fleets, multiplying lubricant touchpoints for service workshops across the Paris basin.
- RE2020 environmental regulations:France's building decarbonization timeline is accelerating demand for bio-based hydraulic fluids in construction equipment serving urban renovation projects.
- Natural gas engine penetration:LNG and CNG powertrains in cross-border freight fleets require specialized low-ash oil chemistries that command formulation premiums.
Market Restraints
- Group II/III base oil import dependence:French blenders rely on northwest European refinery supply chains vulnerable to Rotterdam throughput volatility and Rhine barge disruptions.
- REACH additive disclosure burdens:ECHA restriction timelines for zinc dialkyldithiophosphate concentrations are forcing premature reformulation of established engine oil product lines.
- Electrification residual value risk:Fleet managers face stranded asset calculations for ICE lubricant inventories as municipal zero-emission zones expand in Lyon and Marseille.
Strategic Opportunities
- Rhône-Alpes freight hub specialization:Geneva-Lyon logistics corridors serving Swiss-Italian trade routes remain underpenetrated by technical service-oriented independent blenders.
- Extended-drain synthetic conversion:EU Green Deal fleet decarbonization reporting requirements are creating pull for premium formulations that reduce waste oil generation.
- Telematics-integrated fluid monitoring:Real-time viscosity and contamination sensors are enabling predictive drain scheduling that locks fleet customers into branded synthetic ecosystems.
Industry Challenges
- Tribology-chemistry skill convergence:Formulation labs lack personnel fluent in both additive chemistry and electrified powertrain thermal management requirements.
- ANSM compliance timeline compression:Dual notification pathways for novel bio-based base stocks are extending product launch cycles beyond fleet contract renewal windows.
- Workshop network digitization:Legacy garage management systems resist integration with lubricant supplier inventory APIs, fragmenting demand capture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Commercial Vehicles Lubricants Market |
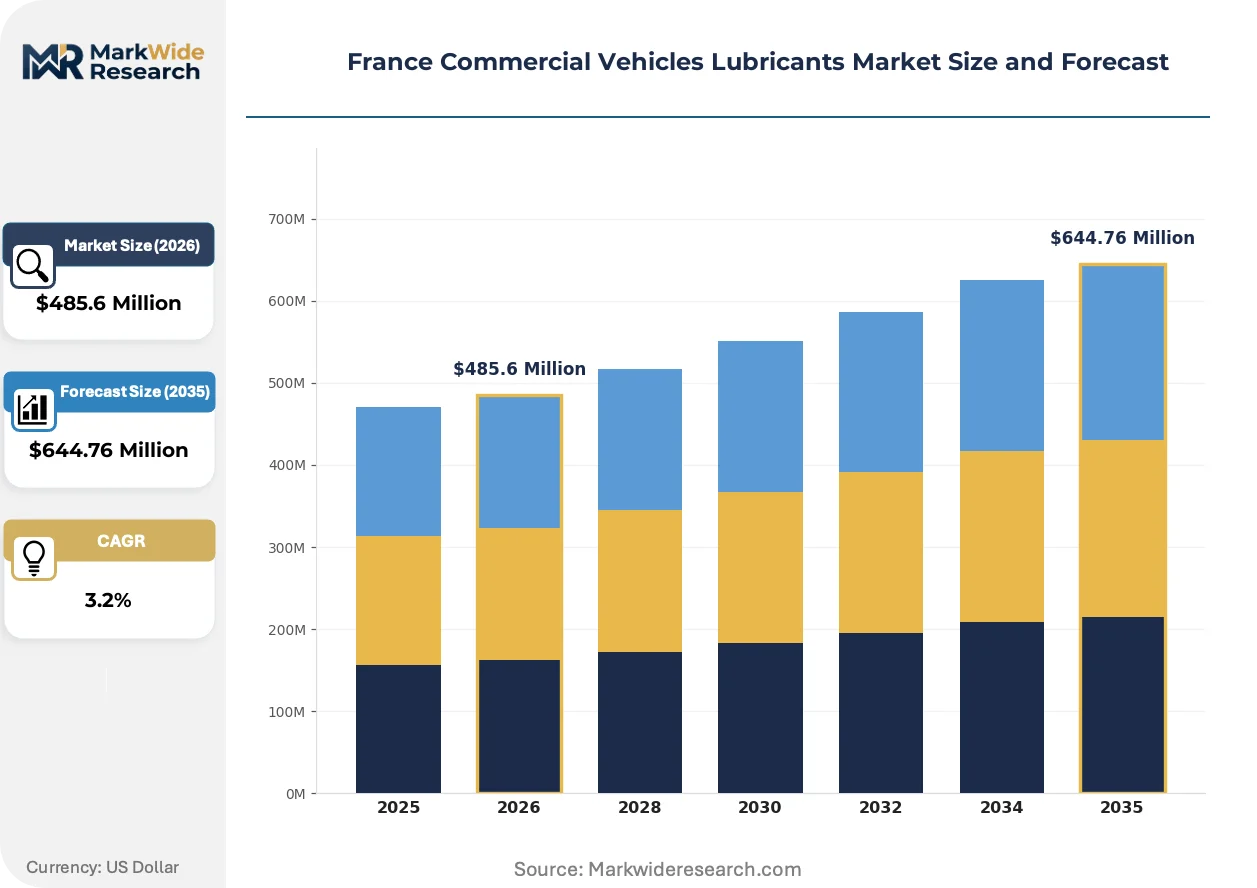
| Market Size in 2026 | $485.6 Million |
| Market Size in 2035 | $644.76 Million |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oils, Gear Oils, Hydraulic Fluids, Coolants, Brake Fluids Vehicle Type: Heavy-Duty Trucks, Light Commercial Vehicles, Buses, Trailers, Delivery Vans End User: Logistics Companies, Public Transport Operators, Construction Firms, Agricultural Services, Freight Haulers Distribution Channel: Direct Sales, Authorized Dealers, Aftermarket Suppliers, Online Retailers, Service Workshops |
| Companies Covered | TotalEnergies, ExxonMobil Corporation, BP PLC (Castrol), Royal Dutch Shell Plc, CHEVRON CORPORATION, FUCHS, Eni SpA, Motul, IGOL, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Commercial Vehicles Lubricants Market Shifts & Advancements
Formulation chemistry is diverging along powertrain thermal profiles, with electrification-adjacent fluids and precision agriculture hydraulics emerging as distinct R&D vectors from legacy diesel engine oils.
Additive package architectures are miniaturizing through polymer-bounded micro-dispersion technologies that concentrate friction modifiers and anti-wear agents into smaller molecular envelopes. Construction equipment OEMs serving precision excavation fleets are adopting these chemistries fastest, compressing the performance gap between 5-liter service packs and bulk tank installations. This miniaturization is enabling just-in-time blending at dealer points rather than centralized production.
REACH restriction proposals on per- and polyfluoroalkyl substances are forcing reformulation of fire-resistant hydraulic fluids used in tunneling and mining equipment. The industrial consequence is a scramble for phosphate ester and polyol ester alternatives that maintain ISO 6743 compliance without fluorinated content. Rhône-Alpes quarrying operations and Île-de-France underground infrastructure projects are most affected, with procurement officers accelerating qualification timelines for substitute chemistries.
Fleet maintenance contracts are consolidating lubricant procurement decisions into fewer hands as logistics operators centralize workshop networks under single service banners. Independent garage chains serving regional freight operators are losing volume to captive workshop networks that bundle fluids with telematics subscriptions. This concentration is most visible in the Amazon delivery van segment, where national maintenance agreements override local purchasing autonomy.
France Commercial Vehicles Lubricants Market Segmentation
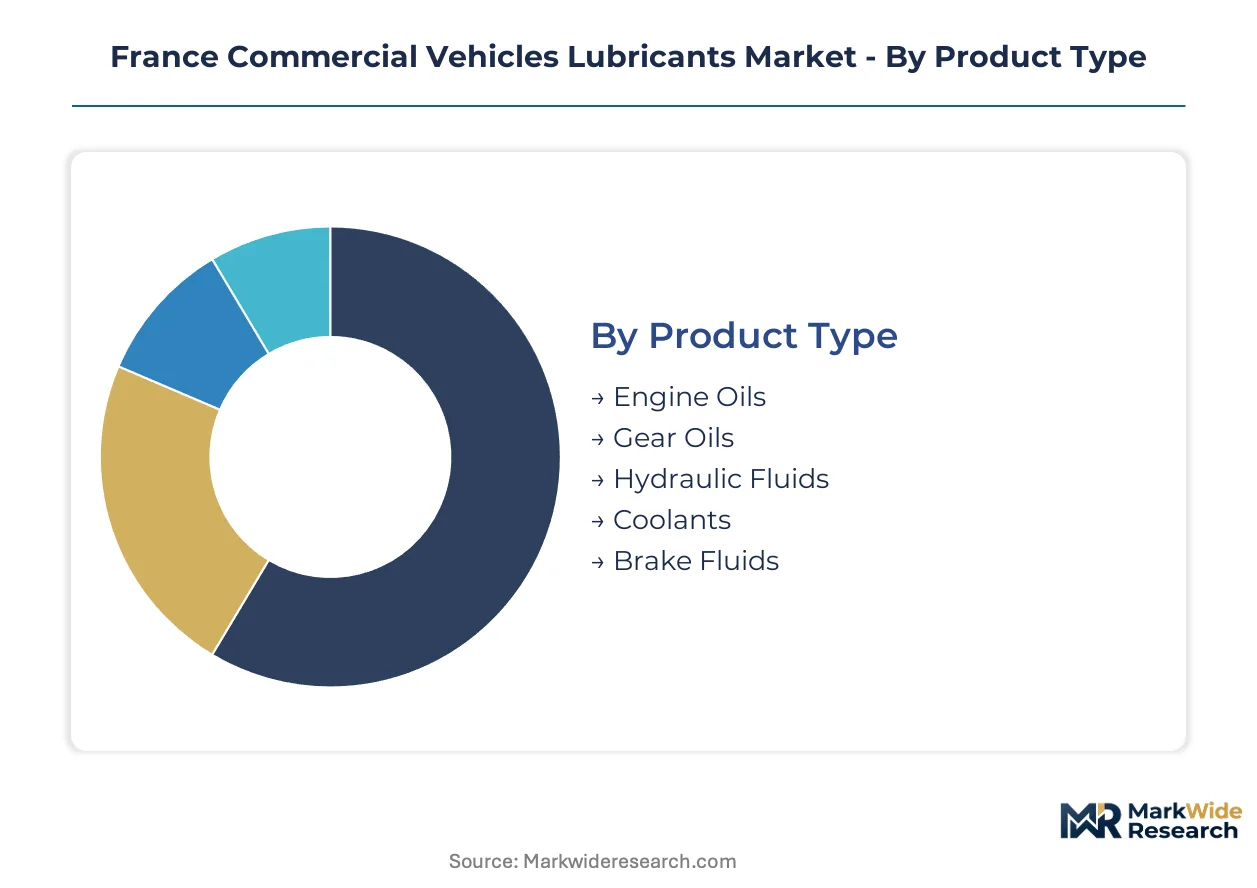
Segmentation in the France commercial vehicles lubricants market reveals how margin pools concentrate around powertrain thermal stress management and fleet procurement centralization. Formulation complexity and drain interval economics divide product categories, while vehicle electrification timelines reshape end-user spending patterns across logistics corridors.
Product Type:
Engine oils command the dominant margin pool due to compressed drain intervals under EURO VI thermal loading, while synthetic hydraulic fluids capture expanding premium pricing from construction equipment precision requirements.
- Engine Oils:Formulated with Group II/III base stocks and zinc dialkyldithiophosphate additive packages to manage diesel particulate filter thermal stress in heavy-duty trucks. Demand concentrates around the Île-de-France logistics corridor where Amazon and Carrefour fleet operators face shortened drain intervals from stop-start urban cycles.
- Hydraulic Fluids:Synthetic and bio-based formulations engineered for fire resistance and biodegradability in precision excavator fleets. RE2020 environmental regulations are accelerating procurement of phosphate ester alternatives in Rhône-Alpes quarrying operations and Paris basin infrastructure projects.
- Gear Oils:High-performance formulations for construction equipment differentials and transmissions, competing on technical service specifications.
- Coolants:Thermal management fluids for transport refrigeration units, shaped indirectly by EU F-Gas Regulation compliance requirements.
- Brake Fluids:DOT-specification formulations serving maintenance intervals in commercial vehicle workshop networks.
Engine oils hold installed capacity. Hydraulic fluids are rotating up the share rankings.
Vehicle Type:
Heavy-duty trucks anchor volume demand through established fleet maintenance contracts, while delivery vans represent the pivot point for electrification-adjacent fluid formulation investments.
- Heavy-Duty Trucks:Cross-border freight fleets operating EURO VI powertrains generate the baseline volume for mineral and synthetic engine oil demand. Natural gas engine penetration in Geneva-Lyon corridors is pulling specialized low-ash oil chemistries with formulation premiums.
- Delivery Vans:Last-mile electrification logistics serving Amazon and Carrefour distribution networks are multiplying lubricant touchpoints for service workshops. Fleet procurement centralization under national maintenance agreements is overriding local purchasing autonomy in this segment.
- Light Commercial Vehicles:Urban freight operators in Lyon and Marseille municipal zones facing zero-emission mandates.
- Buses:Public transport operator fleets subject to ANSM chemical substance compliance and extended-drain synthetic conversion timelines.
- Trailers:Refrigerated transport units integrating coolant demand profiles for F-Gas Regulation compliance.
Heavy-duty trucks maintain contract lock-in. Delivery vans are climbing the fastest on electrification logistics density.
End User:
Logistics companies concentrate procurement decisions through centralized workshop networks, while construction firms drive bio-based hydraulic fluid demand through RE2020 project pipelines.
- Logistics Companies:Fleet managers at Paris-based operators are consolidating lubricant procurement into captive workshop networks bundling fluids with telematics subscriptions. Extended-drain synthetic investments align with EU Green Deal fleet decarbonization reporting requirements.
- Construction Firms:Precision excavation fleet operators in Rhône-Alpes quarrying and Île-de-France tunneling projects are accelerating qualification timelines for phosphate ester hydraulic fluid alternatives. RE2020 building decarbonization timelines drive bio-based formulation procurement.
- Public Transport Operators:Municipal bus fleets subject to ANSM compliance and zero-emission zone expansion in Lyon and Marseille.
- Agricultural Services:Precision agriculture hydraulics emerging as distinct R&D vectors from legacy diesel engine oils.
- Freight Haulers:Cross-border operators on Swiss-Italian trade routes through Rhône-Alpes freight hubs.
Logistics companies dominate contract value. Construction firms are expanding most quickly on environmental regulation pull-through.
Distribution Channel:
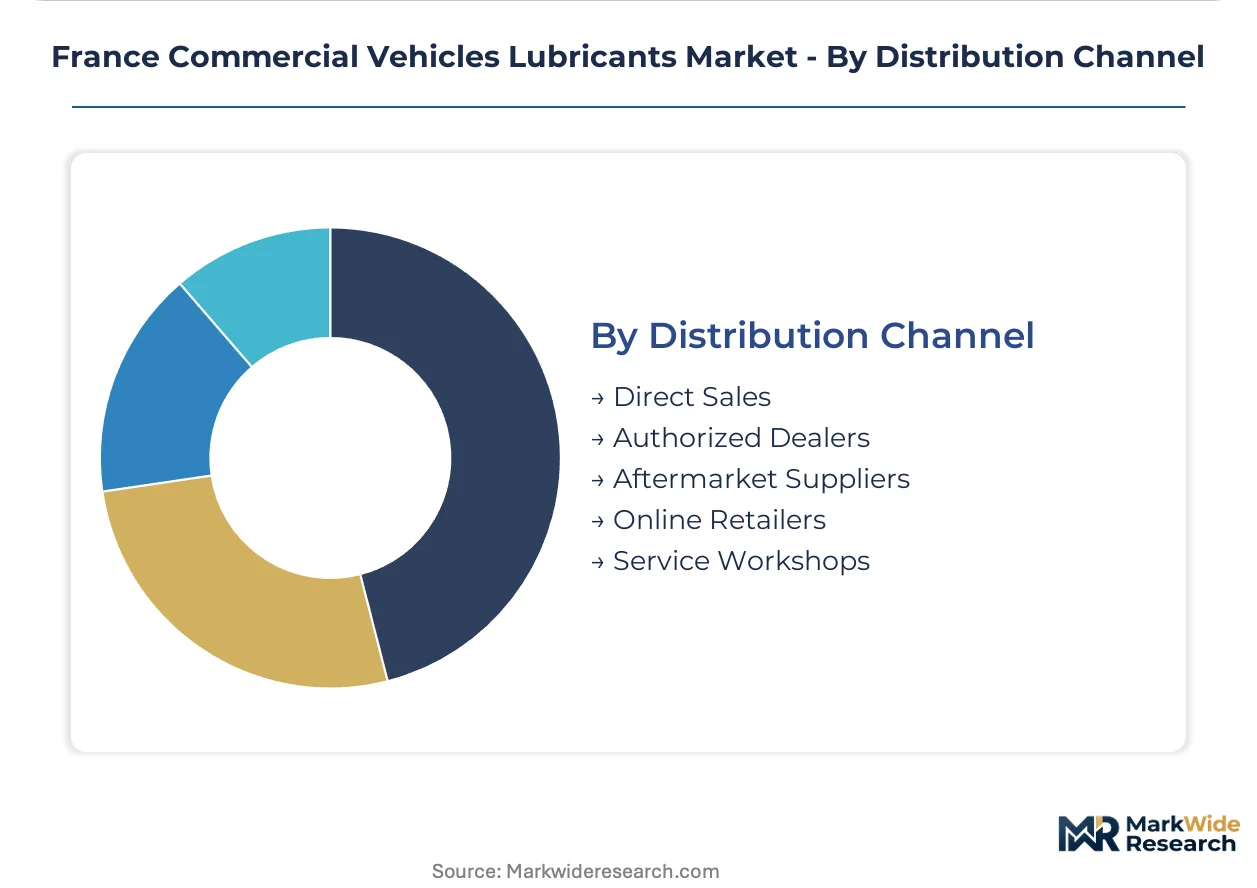
Service workshops capture margin through fleet maintenance contract bundling, while direct sales face digitization friction from legacy garage management system integration challenges.
- Service Workshops:Captive networks operated by national logistics banners are locking in fleet customers through bundled fluid and telematics subscriptions. Amazon delivery van maintenance agreements demonstrate how national procurement overrides regional independent garage volume.
- Direct Sales:Large fleet operators managing heavy-duty truck procurement directly from blenders face workshop network digitization barriers, as legacy garage management systems resist lubricant supplier inventory API integration.
- Authorized Dealers:OEM-affiliated channels serving construction equipment precision fleet requirements.
- Aftermarket Suppliers:Independent blenders competing on technical service in underpenetrated Rhône-Alpes freight corridors.
- Online Retailers:Emerging channels for standardized service pack formulations in fragmented regional operator segments.
Service workshops hold contract density. Direct sales are gaining share fastest on fleet centralization trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet procurement elasticity varies sharply across French logistics corridors. Île-de-France buyers absorb premium synthetic pricing for extended-drain intervals, while peripheral regional operators remain price-sensitive on mineral formulations.
Île-de-France
Amazon and Carrefour distribution networks drive dense last-mile van fleet deployment. ANSM chemical substance compliance timelines compress product launch cycles for bio-based formulations. Paris basin service workshops capture lubricant volume through bundled telematics subscriptions.
Auvergne-Rhône-Alpes
Geneva-Lyon freight corridors serving Swiss-Italian trade routes generate specialized low-ash oil demand for natural gas engine fleets. EU Green Deal fleet decarbonization reporting requirements pull extended-drain synthetic investments. Rhône-Alpes quarrying operations accelerate phosphate ester hydraulic fluid qualification timelines.
Provence-Alpes-Côte d'Azur
Marseille municipal zero-emission zones strand internal combustion engine asset values for light commercial vehicle operators. REACH additive disclosure burdens force premature reformulation of established engine oil product lines. Mediterranean port logistics clusters face electrification residual value risk calculations.
Hauts-de-France
Cross-border freight terminals connecting Benelux and UK markets concentrate heavy-duty truck fleet maintenance contracts. Group II/III base oil import dependence exposes blenders to Rotterdam throughput volatility. Lille-Calais logistics operators manage Rhine barge disruption vulnerabilities in lubricant supply chains.
Nouvelle-Aquitaine
Agricultural services and precision excavation fleets drive bio-based hydraulic fluid procurement through RE2020 project pipelines. ECHA restriction timelines for zinc dialkyldithiophosphate concentrations reshape additive package architectures. Bordeaux-Atlantic port corridor construction firms adopt fire-resistant formulations for tunneling infrastructure.
France Commercial Vehicles Lubricants Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier competing on technical service rather than volume scale. Domestic refining assets and additive partnerships separate the upper tier from blenders dependent on northwest European base oil supply chains. Three archetypes dominate: integrated energy majors with captive refining, independent specialists with formulation depth, and workshop-network operators locking fleet contracts. Competitive moves concentrate on extended-drain synthetic conversion investments and telematics-integrated fluid monitoring systems that bind customers to branded ecosystems.
Within the integrated major tier, TotalEnergies anchors French market presence through domestic refining infrastructure and additive partnerships controlling cost structures across engine oils and hydraulic fluids. BP PLC (Castrol) occupies a position in fleet maintenance contract density, exemplifying how service workshop networks lock in Paris-based logistics operators. FUCHS represents the specialist archetype, sitting within high-performance gear oil segments where technical service specifications outweigh volume scale advantages in construction equipment procurement decisions.
| Leading Market Players |
|---|
| TotalEnergies |
| ExxonMobil Corporation |
| BP PLC (Castrol) |
| Royal Dutch Shell Plc |
| CHEVRON CORPORATION |
| FUCHS |
| Eni SpA |
| Motul |
| IGOL |
| Others |
Supply & Pricing Matrix
Ninety-day inventory cycles for Group II/III base oils at French blenders concentrate pricing power with integrated refiners possessing Rotterdam-adjacent storage, while independent operators absorb margin compression from Rhine barge disruptions and spot market volatility.
Pricing Analysis
After-sales service revenue from extended-drain synthetic contracts drives lifetime value for lubricant suppliers serving Paris-based logistics fleets. Three-tier pricing structure across premium synthetic, mid-grade semi-synthetic, and economy mineral levels separates formulation complexity tiers. Cost compression in economy mineral grades is intensifying because fleet managers face stranded ICE asset calculations from municipal zero-emission zone expansion. Construction firms in Rhône-Alpes quarrying operations show least price sensitivity due to RE2020-mandated bio-based hydraulic fluid procurement timelines.
Supply Chain Analysis
Container availability constraints on Rotterdam-Antwerp barge lanes elevate inbound logistics costs for French blenders dependent on northwest European refinery supply chains. Belgium, Netherlands, and Germany concentrate Group II/III base oil production capacity feeding French formulation plants. Additive packages rest on zinc dialkyldithiophosphate chemistries facing ECHA restriction timelines. Single-source vulnerability concentrates around Rotterdam throughput volatility. Distribution runs through captive service workshop networks bundling fluids with telematics subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as Amazon and Carrefour national maintenance agreements override regional independent garage purchasing autonomy, fragmenting volume access for non-integrated suppliers.
For Market Incumbents: Fortify workshop network density through telematics-integrated fluid monitoring systems that lock fleet customers into branded synthetic ecosystems. Deepen additive partnerships controlling cost structures across engine oils and hydraulic fluids. Electrification residual value risk from municipal zero-emission zone expansion threatens ICE lubricant inventory positions. For New Entrants and Emerging Players: Differentiate on technical service specifications for natural gas engine low-ash oil chemistries in underpenetrated Geneva-Lyon freight corridors. Target precision excavation fleet operators in Rhône-Alpes quarrying operations with phosphate ester hydraulic fluid alternatives. Pursue authorized dealer partnerships with construction equipment OEMs bypassing captive logistics workshop networks. For Investors and Strategic Acquirers: Carve-out targets emerge from integrated energy majors divesting non-core lubricant blending assets amid portfolio decarbonization pressures. Extended-drain synthetic conversion viability over a multi-year horizon hinges on EU Green Deal fleet reporting requirement permanence. Monitor ANSM notification pathway timelines for novel bio-based base stocks as inflection indicator for formulation lab capacity constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Extended-Drain Synthetic Conversion | Aligns lubricant procurement with EU Green Deal fleet decarbonization reporting requirements for Paris-based logistics operators. |
| Telematics-Integrated Fluid Monitoring | Enables predictive drain scheduling that binds heavy-duty truck fleets to branded synthetic ecosystems through real-time viscosity sensors. |
| Phosphate Ester Hydraulic Fluid Qualification | Addresses REACH restriction timelines on per- and polyfluoroalkyl substances for Rhône-Alpes tunneling and mining equipment procurement. |
| Natural Gas Engine Low-Ash Oil Development | Captures formulation premiums from LNG and CNG powertrain penetration in Geneva-Lyon cross-border freight corridors. |
| Workshop Network Digitization Investment | Overcomes legacy garage management system resistance to lubricant supplier inventory API integration for direct sales channel expansion. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of ECHA restriction proposals, EU Green Deal policy documentation, and French national low-carbon strategy implementation timelines. Fleet procurement officers, lubricant formulation chemists, construction equipment maintenance directors, and logistics workshop network managers provided qualitative input. Customs data on Group II/III base oil imports, ANSM chemical substance notification records, and SEC filings from integrated energy majors supplied quantitative anchors. Bottom-up volume triangulation against top-down market sizing validated segment-level outputs.
Segmentation dimensions modeled include product type, vehicle type, end user category, and distribution channel across the analysis window. Powertrain thermal profile divergence between diesel, natural gas, and electrification-adjacent applications shaped formulation complexity assumptions. CAGRs derived from elasticity modeling of fleet procurement decisions against regulatory compliance cost curves. RE2020 environmental regulation implementation pace and EURO VI thermal loading impact on drain intervals informed demand trajectory calibration.
Decision-makers should treat outputs as directional under assumptions of sustained EU Green Deal policy continuity and stable Rotterdam-Antwerp supply lane throughput; material deviation would warrant model refresh. Electrification acceleration beyond municipal zero-emission zone timelines or abrupt ECHA additive restriction advancement could compress ICE lubricant demand faster than projected. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Iran Automotive Engine Oils Market
Automotive Parts
Electric Vehicle Fasteners Market
Automotive Parts
Automotive Oil and Air Filters Market
Automotive Parts
Fluid Couplings Market
Automotive Parts
Autocatalyst Market
Automotive Parts
Automotive Hydraulic Filter System Market
Automotive Parts
Light Vehicle Exhaust and Emissions Systems Market
Automotive Parts
Automotive Bearing Seals Market
Automotive Parts
Automotive Step Plate Market
Automotive Parts
Camshaft Lifters Market
Automotive Parts
Automotive Spacer Ring Market
Automotive Parts
Argentina Automotive Parts Aluminium Die Casting Market
Automotive Parts
Electric Power Steering System (EPS) Market
Automotive Parts
Tow Bar Market
Automotive Parts
Automotive AC Compressor Market
Automotive Parts
Wheel Arch Liner Market