
 Kazakhstan Power EPC Market | 2026-2036
Kazakhstan Power EPC Market Size, Share, and Industry Trends Forecast 2026-2036
Kazakhstan Power EPC Market Foresight
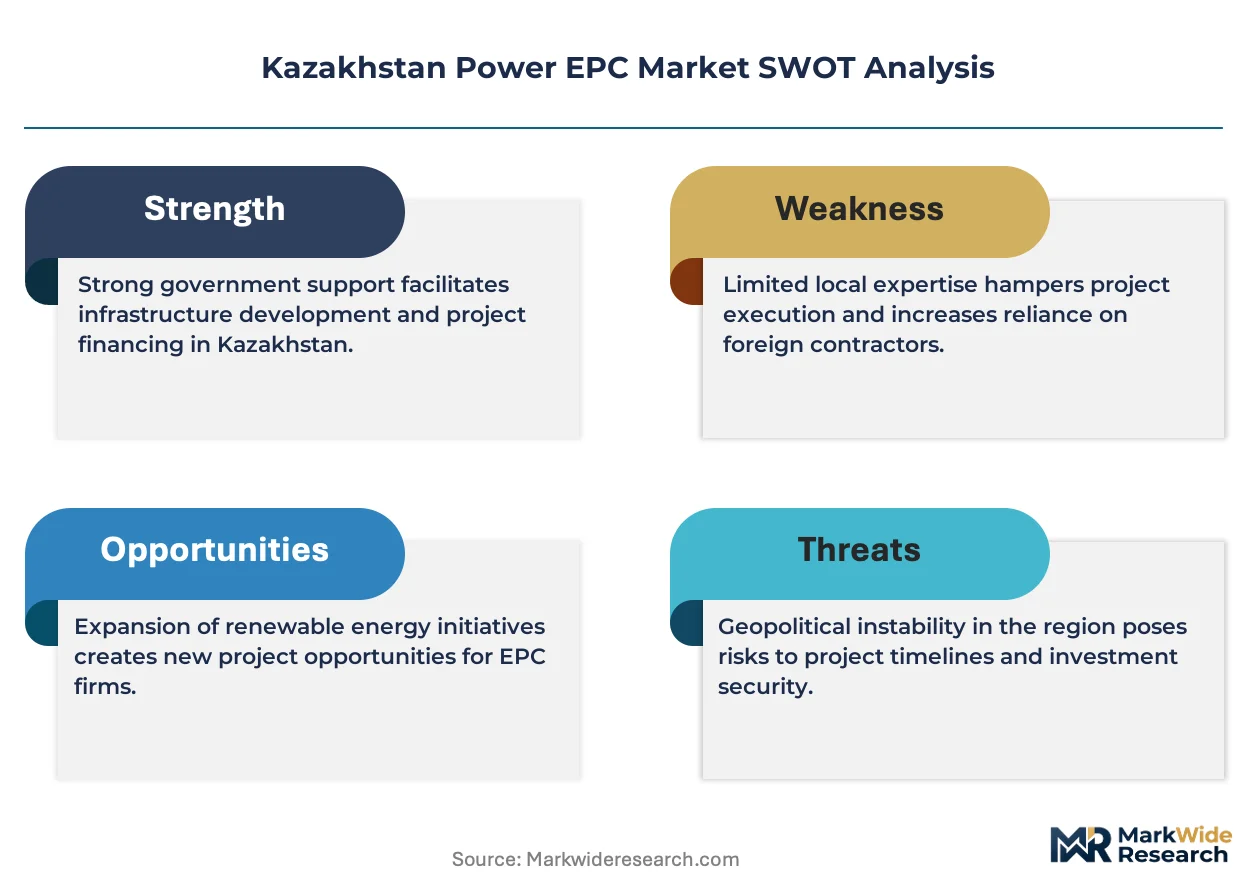
Hybrid renewable-to-storage integration is fragmenting conventional thermal EPC procurement into modular, technology-specific packages. Shanghai Electric Group Co. Ltd leverages its turbine manufacturing base to anchor coal-to-gas retrofit opportunities. Doosan Enerbility competes through combined-cycle expertise that sustains its relevance amid baseload diversification. Dongfang Electric International Cooperation Co differentiates via ultra-supercritical boiler technology leadership in Central Asian markets.
Kazakhstan Power EPC denotes the turnkey delivery of power generation infrastructure spanning feasibility studies, equipment sourcing, civil works, and grid synchronization, typically governed by IEC 61508 safety integrity levels and local GOST-K certification requirements. The primary purpose centers on delivering dispatchable capacity to industrial offtakers under long-term power purchase agreements. Commissioning services command premium margins where grid code compliance complexity rises with renewable penetration. Large and mega projects dominate absolute contract value, though small-scale distributed solar EPC is expanding fastest among private commercial offtakers seeking behind-the-meter supply.
The Committee for Regulation of Natural Monopolies and the Ministry of Energy enforce tariff frameworks and technical connection standards that determine EPC contract viability. GOST-K conformity assessment and emerging green bond eligibility criteria under the Astana International Financial Centre reshape equipment sourcing and subcontractor qualification requirements. Stakeholders must monitor regulatory treatment of hybrid project configurations where generation and storage assets fall under divergent permitting pathways.
Market Dynamics
State procurement under Kazakhstan's carbon neutrality strategy is fragmenting conventional thermal EPC contracts into modular renewable packages, forcing contractors to restructure delivery capabilities around hybrid solar-storage configurations.
Growth Catalysts
- Carbon Neutrality Procurement Mandate:The Ministry of Energy's renewable procurement quotas redirect state tenders toward solar and wind EPC contracts, displacing thermal baseload awards.
- Industrial Load Growth:Aluminum smelters and copper mining complexes in the Balkhash and Karaganda regions expand grid-connected generation requirements under long-term power purchase agreements.
- Southern Transmission Clustering:Turkestan and Jambyl regions concentrate solar and wind zone development near existing 500kV infrastructure, reducing grid synchronization costs for EPC bidders.
Market Restraints
- Equipment Import Dependency:Turbine generators and ultra-supercritical boiler components originate from concentrated East Asian manufacturing bases, exposing projects to shipping cost volatility and customs clearance delays.
- GOST-K Certification Bottleneck:Local conformity assessment procedures for electrical equipment extend procurement timelines by 4-8 months, compressing construction windows in regions with limited seasonal access.
- Grid Code Divergence:Renewable and storage assets fall under separate permitting pathways administered by the Committee for Regulation of Natural Monopolies, creating contractual ambiguity for hybrid project configurations.
Strategic Opportunities
- Coal-to-Gas Retrofit Pipeline:Aging Soviet-era thermal plants in Pavlodar and Akmola regions present equipment replacement opportunities compatible with turbine manufacturing supply chains.
- Behind-the-Meter Commercial Solar:Private offtakers in Almaty and Astana seek distributed generation EPC contracts to bypass regulated tariff structures and secure price certainty.
- Green Bond Eligibility Structuring:Astana International Financial Centre eligibility criteria for sustainable infrastructure finance reshape equipment sourcing specifications toward IEC-certified suppliers.
Industry Challenges
- Commissioning Engineer Shortage:Grid code compliance for inverter-dominated generation requires specialized protection and synchronization expertise scarce in Central Asian labor markets.
- Hybrid Integration Complexity:Battery energy storage systems interfacing with variable renewable output demand control system architectures unfamiliar to legacy thermal EPC contractors.
- Subcontractor Qualification Gaps:GOST-K certification requirements for civil works and electrical installation exceed capabilities of regional construction firms, forcing prime contractors to import specialized crews.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kazakhstan Power EPC Market |
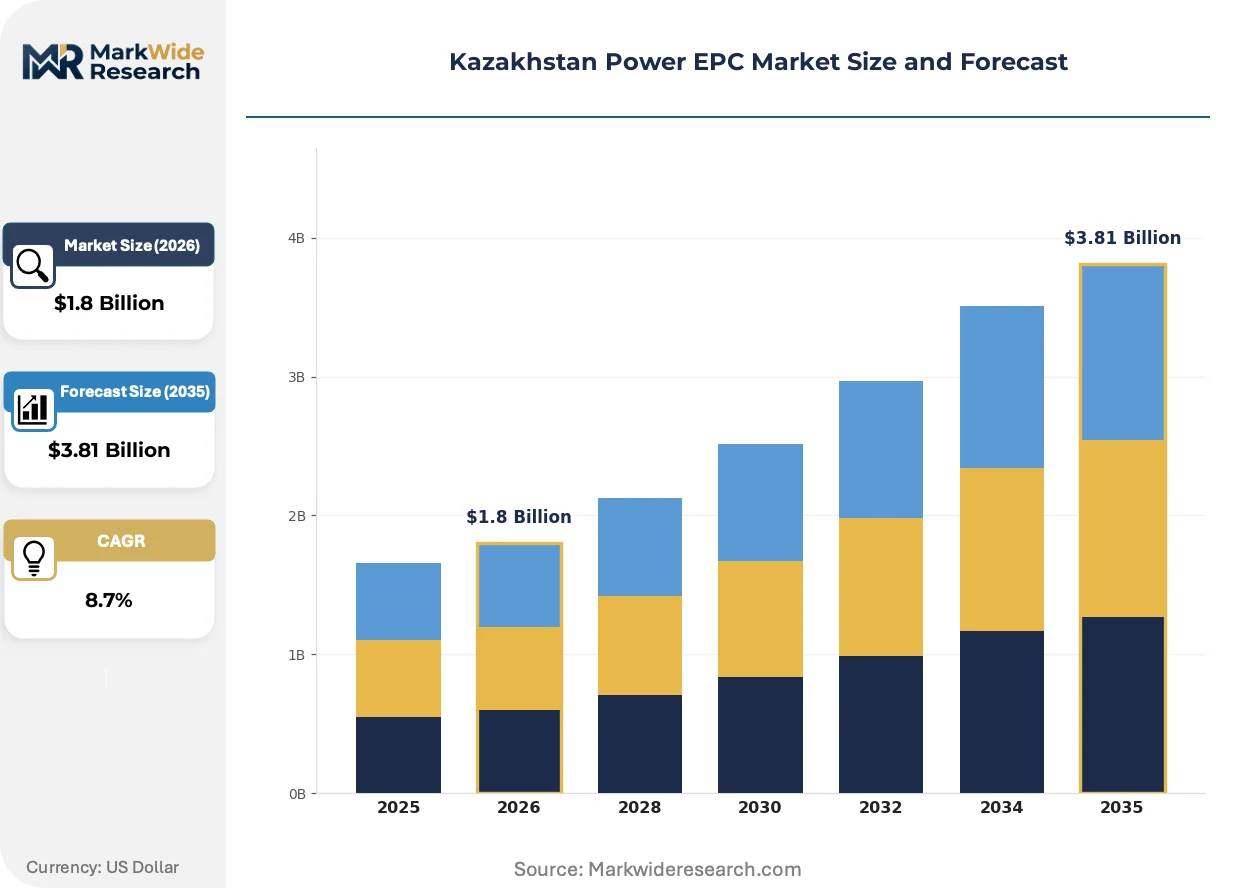
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Engineering, Procurement, Construction, Commissioning Project Size: Small, Medium, Large, Mega Energy Source: Renewable, Fossil Fuel, Nuclear, Hydropower End User: Utilities, Industrial, Government, Commercial |
| Companies Covered | Dongfang Electric International Cooperation Co, Doosan Enerbility, Shanghai Electric Group Co. Ltd, NatPower Kazakhstan, China Tianchen Engineering Corporation, GCD Partner LLP, Samruk-Energy JSC, Sany Central Asia Co., Ltd, POWERCHINA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kazakhstan Power EPC Market Shifts & Advancements
Digital engineering tools and modular construction methods are compressing project delivery timelines while regulatory pressure accelerates technology substitution in Kazakhstan's power infrastructure procurement.
Digital twin platforms are virtualizing plant design and commissioning workflows for combined-cycle and solar PV projects. Samruk-Kazyna sovereign wealth fund portfolio companies pilot these tools for 500MW-class developments. The technology is virtualizing traditional site-based engineering reviews into remote collaboration environments, reducing mobilization costs for international EPC firms.
The Ministry of Energy's renewable auction mechanism imposes local content requirements that reshape equipment sourcing strategies. Domestic steel fabrication and civil works quotas force contractors to qualify Kazakh subcontractors previously excluded from thermal plant construction. Thermal EPC incumbents face steepest adaptation costs as solar and wind packages demand entirely different supplier networks.
Industrial offtakers now unbundle long-term service agreements from initial EPC contracts, treating commissioning and O&M as separate competitive procurements. Mining groups in the East Kazakhstan region lead this disaggregation, seeking specialized renewable O&M providers distinct from construction primes. This pattern concentrates margin pressure on EPC firms dependent on captive aftermarket revenue.
Kazakhstan Power EPC Market Segmentation
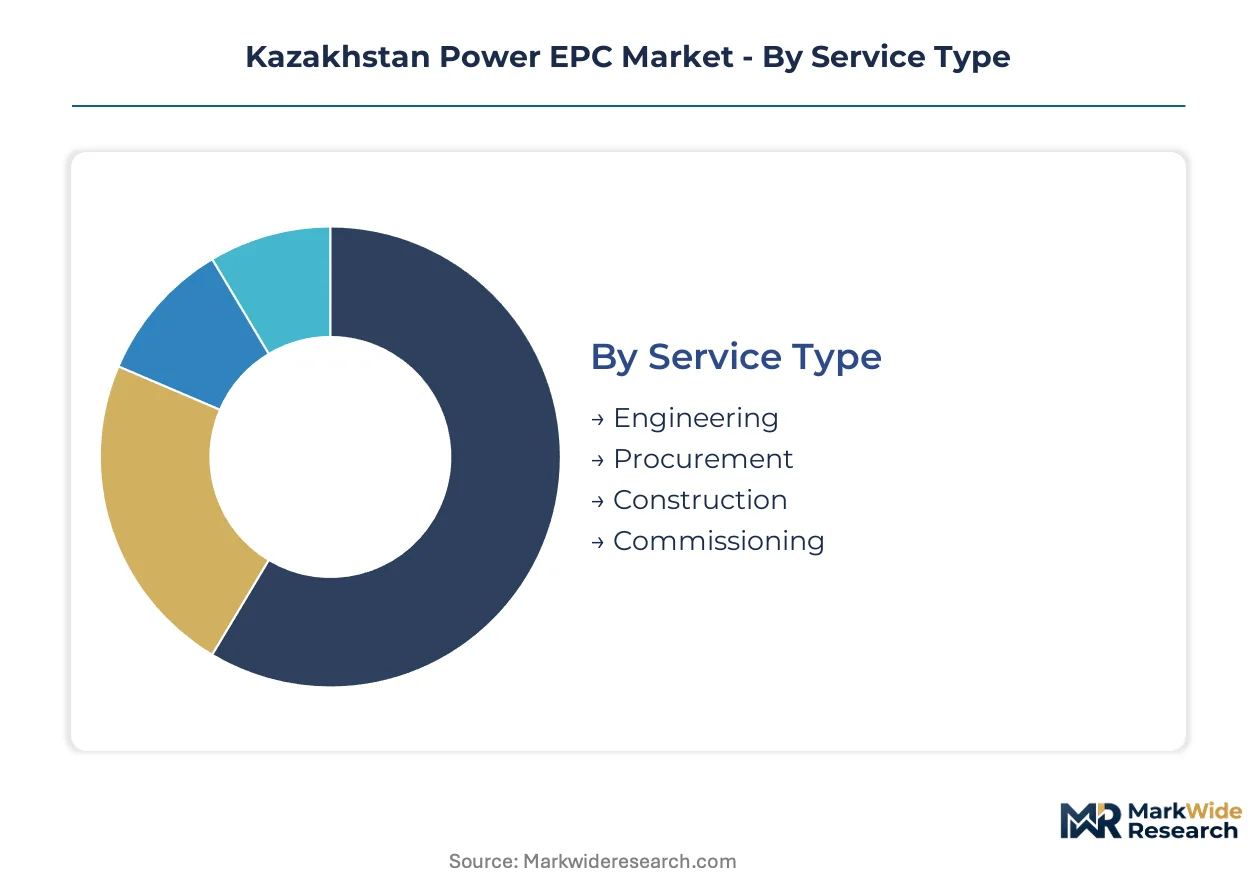
Kazakhstan's power EPC procurement fragments across service phases, project scales, energy technologies, and offtaker categories. Each dimension carries distinct margin profiles, certification burdens, and subcontractor qualification requirements that reshape contractor positioning.
Service Type:
After-sales service intensity varies dramatically across the EPC value chain, with commissioning commanding premium margins where grid code compliance complexity escalates.
- Engineering:Feasibility studies and front-end engineering design establish project bankability under IEC 61508 safety integrity levels. Demand concentrates among Samruk-Kazyna portfolio companies developing 500MW-class plants in the Turkestan region, driven by sovereign wealth fund mandates for digital twin integration.
- Procurement:Equipment sourcing spans turbine generators, ultra-supercritical boilers, and solar inverters subject to GOST-K conformity assessment. Aluminum smelters in the Balkhash region drive specification intensity, constrained by East Asian manufacturing concentration and shipping cost volatility.
- Construction:Civil works and electrical installation face seasonal access limitations in northern regions. Local content quotas under Ministry of Energy auction rules force qualification of Kazakh subcontractors previously excluded from thermal plant builds.
- Commissioning:Grid synchronization and protection system validation require specialized expertise scarce in Central Asian labor markets. Mining complexes in East Kazakhstan unbundle these services from EPC contracts, treating commissioning as separate competitive procurements.
By volume, Engineering leads. By growth pace, Commissioning is ahead.
Project Size:
Cost tier differentiation separates utility-scale developments from distributed commercial installations, with capital intensity dictating financing structures and risk allocation.
- Small:Behind-the-meter solar arrays under 10MW serve private commercial offtakers in Almaty and Astana seeking tariff bypass.
- Medium:Industrial captive power for copper mining complexes in Karaganda balances grid independence with economies of scale.
- Large:Grid-connected generation exceeding 100MW dominates absolute contract value, anchored by aluminum smelter demand in the Balkhash region.
- Mega:Multi-gigawatt complexes concentrate in southern solar and wind zones near existing 500kV transmission infrastructure.
By contract value concentration, Mega projects dominate. By expansion trajectory, Small-scale distributed solar is climbing the fastest.
Energy Source:
Technology maturity curves determine equipment supplier networks, with renewable penetration forcing thermal EPC incumbents to restructure procurement capabilities.
- Renewable:Solar and wind EPC contracts displace thermal awards under carbon neutrality procurement mandates. Turkestan and Jambyl regions cluster development near transmission infrastructure, reducing grid synchronization costs.
- Fossil Fuel:Coal-to-gas retrofits in Pavlodar and Akmola regions present equipment replacement opportunities compatible with existing turbine manufacturing supply chains.
- Nuclear:Baseload diversification discussions remain preliminary, with no active EPC procurement pipeline.
- Hydropower:Soviet-era asset refurbishment commands limited new-build activity relative to solar and wind investment flows.
By current award volume, Fossil Fuel retains position. By policy-directed momentum, Renewable is gaining share fastest.
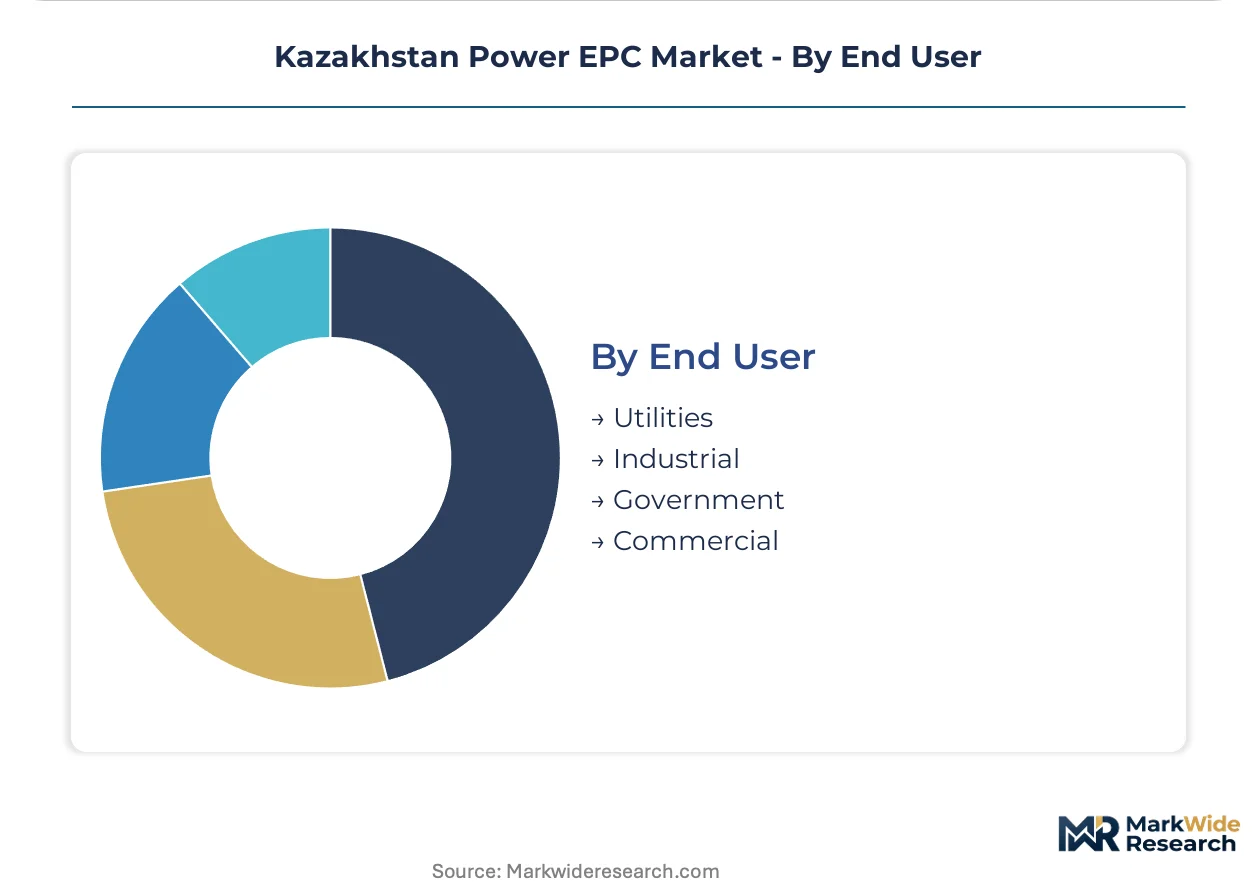
End User:
Customer type determines contract tenors, offtake security mechanisms, and local content compliance intensity.
- Utilities:State-owned generation companies procure under Ministry of Energy renewable quotas and tariff frameworks enforced by the Committee for Regulation of Natural Monopolies.
- Industrial:Aluminum smelters and copper mining complexes execute long-term power purchase agreements with dispatchability requirements.
- Government:Public infrastructure projects face extended procurement timelines through GOST-K certification bottlenecks.
- Commercial:Private offtakers in urban centers seek distributed generation EPC to secure price certainty outside regulated tariff structures.
By absolute contract value, Utilities lead. By procurement flexibility, Commercial is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese and South Korean equipment manufacturers dominate export flows into Kazakhstan's power infrastructure sector, with turbine generators and ultra-supercritical boiler components shipped through Alashankou and Dostyk rail corridors to serve southern solar zones and northern retrofit projects.
Turkestan Region
Aluminum smelter demand from the Balkhash complex drives 500MW-class solar procurement near existing 500kV transmission infrastructure. The Ministry of Energy's renewable auction mechanism imposes local content requirements that force contractor qualification of Kazakh steel fabricators. Shymkent anchors southern cluster development where grid synchronization costs fall below national averages.
Jambyl Region
Wind zone concentration near Taraz benefits from proximity to southern transmission corridors serving industrial load centers. GOST-K conformity assessment procedures extend equipment procurement timelines by 4-8 months, compressing construction windows. Taraz and surrounding districts host the densest renewable EPC contract awards outside state capital procurement.
Karaganda Region
Copper mining complexes execute long-term power purchase agreements requiring dispatchable generation capacity. The Committee for Regulation of Natural Monopolies enforces tariff frameworks that determine captive power project viability. Balkhash and surrounding industrial zones concentrate medium-scale industrial EPC procurement for grid-independent supply.
Pavlodar Region
Aging Soviet-era thermal plants present coal-to-gas retrofit opportunities compatible with East Asian turbine manufacturing supply chains. State procurement under carbon neutrality strategy fragments conventional thermal awards into modular equipment replacement packages. Pavlodar city and Ekibastuz coal cluster anchor northern baseload diversification investment.
Almaty and Astana Urban Centers
Private commercial offtakers seek behind-the-meter distributed solar EPC contracts to bypass regulated tariff structures. The Astana International Financial Centre's green bond eligibility criteria reshape equipment sourcing specifications toward IEC-certified suppliers. Almaty's commercial density and Astana's government procurement concentration generate fastest-expanding small-scale contract volume.
Kazakhstan Power EPC Market Competitive Landscape
Channel-controlling players compete with product-specialist players across Kazakhstan's procurement landscape, with sovereign wealth fund relationships determining access to utility-scale awards and manufacturing integration shaping retrofit competitiveness. Thermal EPC incumbents face steepest adaptation costs as solar and wind packages demand entirely different supplier networks than legacy coal plant construction. Three archetypes dominate: turbine-integrated heavy industrials, solar-specialist developers, and state-linked domestic champions. Competitive moves concentrate on local content compliance structuring and hybrid technology bundling.
Among Chinese and South Korean equipment-integrated contractors, Dongfang Electric International Cooperation Co, Doosan Enerbility, and Shanghai Electric Group Co. Ltd occupy positions defined by manufacturing depth and turbine technology access. Dongfang Electric exemplifies ultra-supercritical boiler leadership in Central Asian markets. Doosan Enerbility represents combined-cycle expertise sustaining relevance amid baseload diversification. Shanghai Electric anchors coal-to-gas retrofit positioning through captive turbine production. These manufacturers compete against development-specialist entrants including NatPower Kazakhstan and China Tianchen Engineering Corporation, which structure project finance and EPC delivery without captive equipment manufacturing.
| Leading Market Players |
|---|
| Dongfang Electric International Cooperation Co |
| Doosan Enerbility |
| Shanghai Electric Group Co. Ltd |
| NatPower Kazakhstan |
| China Tianchen Engineering Corporation |
| GCD Partner LLP |
| Samruk-Energy JSC |
| Sany Central Asia Co., Ltd |
| POWERCHINA |
| Others |
Supply & Pricing Matrix
Overcapacity in East Asian turbine manufacturing is compressing equipment margins and forcing suppliers toward bundled EPC-plus-service contracts to defend returns. Kazakh offtakers exploit this buyer's market to extract extended commissioning warranties and localized content commitments from prime contractors bidding on utility-scale solar and retrofit thermal packages.
Pricing Analysis
Thermal-to-renewable pricing gaps separate legacy coal plant EPC from solar PV packages, with ultra-supercritical boiler contracts commanding premium engineering margins against commoditized solar module installation. Project-based long-term offtake structures dominate utility procurement, while commercial behind-the-meter buyers favor fixed-price turnkey contracts. Price differentiation rests on GOST-K certification tier and after-sales service bundling intensity. Cost compression in solar EPC is intensifying as Chinese equipment manufacturers absorb shipping volatility to secure market share. State-owned generation companies exhibit lowest price sensitivity due to sovereign guarantee backing; private mining offtakers negotiate hardest on capex terms.
Supply Chain Analysis
Upstream feedstock for turbine generators and ultra-supercritical boilers draws from concentrated manufacturing bases in China, South Korea, and Japan. Critical component dependencies include high-grade steel forgings, precision casting assemblies, and power electronics inverters subject to IEC certification. Single-source vulnerability runs through Shanghai Electric and Dongfang Electric production facilities for supercritical pressure components. Distribution runs through Alashankou and Dostyk rail corridors connecting East Asian ports to southern Kazakhstan solar zones and northern retrofit sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized commissioning expertise for inverter-dominated generation represents the scarcest capability layer in Kazakhstan's power EPC market, constraining contractor scalability and inflating premium service margins. Prime contractors lacking grid-code synchronization depth face forced subcontractor reliance that erodes project control.
For Market Incumbents: Entrench position through captive qualification of Kazakh steel fabricators and civil works subcontractors ahead of Ministry of Energy local content enforcement. Thermal EPC heritage offers limited defense against solar-specialist entrants; backward integration into inverter supply partnerships reduces equipment procurement exposure. Anchor relationships with Samruk-Kazyna portfolio companies through digital twin pilot commitments that lock out competitor access to 500MW-class developments. For New Entrants and Emerging Players: Establish a beachhead in behind-the-meter commercial solar serving Almaty and Astana private offtakers seeking tariff bypass. Distributed generation EPC avoids sovereign procurement complexity and accelerates reference project accumulation. Target commissioning-only contracts unbundled from construction by East Kazakhstan mining complexes as the most penetrable service segment. Go-to-market positioning should emphasize IEC-certified protection engineering scarce in regional labor markets. For Investors and Strategic Acquirers: Long-term, this sits as a capability-accumulation play because hybrid project complexity will consolidate awards toward contractors with integrated solar-storage-control system competence. Acquisition target archetype: mid-scale EPC firms with existing GOST-K certification infrastructure and relationships with Kazakh steel fabrication subcontractors. Watch Ministry of Energy renewable auction local content threshold adjustments as the signal for accelerated domestic subcontractor M&A activity.| Strategic Initiative | Industry Significance |
|---|---|
| Local Content Compliance Structuring | Ministry of Energy auction rules force prime contractors to qualify Kazakh steel fabricators previously excluded from thermal construction. |
| Hybrid Technology Bundling | Battery energy storage integration with solar PV demands control architectures unfamiliar to legacy thermal EPC contractors. |
| Commissioning Capability Buildout | Grid code compliance for inverter-dominated generation commands premium margins where specialized protection expertise concentrates. |
| Digital Twin Platform Deployment | Samruk-Kazyna portfolio companies pilot remote engineering collaboration tools that reduce international firm mobilization costs. |
| Coal-to-Gas Retrofit Positioning | Aging Soviet-era thermal plants in Pavlodar present equipment replacement opportunities compatible with existing turbine supply chains. |
Research Methodology
Operator-level perspectives from EPC project directors, utility planning officers at Samruk-Energy JSC, grid operators at KEGOC, and procurement leads at aluminum smelters anchored the qualitative base. Secondary validation drew from Committee for Regulation of Natural Monopolies tariff filings, Ministry of Energy auction disclosures, Astana International Financial Centre green bond eligibility criteria, and customs data tracking equipment imports through Alashankou corridor. Bottom-up project pipeline aggregation and top-down macroeconomic triangulation cross-checked volume assumptions.
Scenario-bracketing framed projections across conservative, baseline, and accelerated renewable penetration pathways without year-specific milestone anchoring. Segmentation dimensions modeled encompassed service type, project scale tier, energy source technology, and end-user category across the analysis window. CAGRs derived from installed capacity buildout trajectories, equipment cost curves, and regulatory procurement quota enforcement intensity. Forecast inputs incorporated sovereign wealth fund capital deployment schedules and industrial offtaker power purchase agreement tenor patterns.
Stress conditions across GOST-K certification timeline extensions, East Asian shipping cost volatility, and grid code divergence between renewable and storage permitting pathways were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions subject to revision from regulatory treatment shifts or technology substitution acceleration. Cross-checking against Samruk-Kazyna disclosed capital expenditure plans is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
Magnetic Bearing Market
Power Equipment
Portable Power Station Market
Power Equipment
Global Auxiliary Power Unit Market
Power Equipment
Wind Turbine Maintenance Market
Power Equipment
Global Medium Voltage AC Drives Market
Power Equipment
Global Power System Simulator Market
Power Equipment
Wind Turbine Gearbox Repair and Refurbishment Market
Power Equipment
Deaerators Market
Power Equipment
Asia-Pacific SCR Power Controller Market
Power Equipment
Chad Power EPC Market
Power Equipment
Wind Tunnel Fans Market
Power Equipment
Process Air Heater Market
Power Equipment
Power Magnetics for MV AC Drive Market
Power Equipment
Asia-Pacific Power Plant Maintenance Market
Power Equipment
Middle East Power Filter Market
Power Equipment
Qatar Power EPC Market