
 Power Infrastructure Market | 2026-2036
Power Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
Power Infrastructure Market Insights
Software-defined grid management is realigning how power infrastructure vendors package their offerings. Siemens Energy leverages its digital twin platforms to differentiate long-term service contracts from hardware-only sales. General Electric anchors its competitive position through predictive maintenance subscriptions tied to gas turbine fleets. Schneider Electric extends its reach via energy-as-a-service models that bundle efficiency software with distribution hardware.
Power infrastructure encompasses the physical and digital systems for generating, transmitting, distributing, and storing electrical energy, including assets rated from distribution-level kilovolts to ultra-high-voltage direct current corridors exceeding 800 kV, with design lifespans typically spanning 30 to 60 years. Its primary purpose is delivering reliable, quality-regulated electricity to end users while accommodating bidirectional flows from distributed resources. The generation segment retains the largest installed base but faces margin compression as renewable asset costs decline, while smart grid technology captures expanding value pools through real-time monitoring and automated response capabilities. Storage infrastructure represents the fastest-expanding category as lithium-ion and emerging chemistries enable temporal arbitrage and grid stabilization services.
FERC Order 2222 in the United States enables distributed energy resource aggregation, while the EU Green Deal and its embedded F-Gas Regulation are phasing down fluorinated greenhouse gases used in switchgear and transformers across Europe. These frameworks compel equipment manufacturers to redesign product portfolios and accelerate alternative insulation technologies. Stakeholders must weigh stranded asset risk against the capital intensity of next-generation platform transitions.
Market Dynamics
Grid-scale battery storage integration is redirecting capital flows across generation, transmission, and distribution tiers as utilities reconcile NERC reliability mandates with renewable intermittency. This structural force compresses traditional peaker plant economics while elevating digital asset management platforms.
Growth Catalysts
- FERC Order 2222:Distributed energy resource aggregation in the United States unlocks revenue streams for behind-the-meter storage and demand response, compelling utilities to upgrade distribution management systems.
- EU F-Gas Regulation phase-down:Fluorinated gas restrictions accelerate switchgear redesign toward vacuum interruption and clean air insulation, creating replacement cycles across European transmission networks.
- India's interstate transmission corridors:State utilities pursue connectivity upgrades linking renewable-rich western and southern states to demand centers, driving ultra-high-voltage substation deployments.
Market Restraints
- Copper and rare earth price volatility:Transformer and cable manufacturing faces margin pressure from concentrated Chilean copper supply and Chinese rare earth processing dominance.
- Prolonged grid interconnection queues:US regional transmission organizations report multi-year backlogs for generation projects, freezing capital deployment and inflating carrying costs.
- Sulfur hexafluoride containment requirements:The EU F-Gas Regulation imposes stringent leak monitoring and reporting obligations, raising operational complexity for existing gas-insulated switchgear fleets.
Strategic Opportunities
- Vietnam's power development plan:Grid modernization programs create openings for digital substation and battery storage vendors as the country scales LNG-to-power and offshore wind.
- Green hydrogen electrolyzer co-location:Converging renewable generation, storage, and electrolysis at industrial hubs enables power-to-X revenue stacking and grid stabilization services.
- US Inflation Reduction Act storage credits:Investment tax credit extensions for standalone battery projects reshape project finance structures and accelerate merchant storage development.
Industry Challenges
- Protection engineer scarcity:Specialized expertise in relay coordination and wide-area stability control lags deployment timelines for complex inverter-based resource integration.
- Multi-vendor SCADA harmonization:Utilities struggle to unify legacy proprietary protocols with IEC 61850 standards during brownfield automation retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Infrastructure Market |
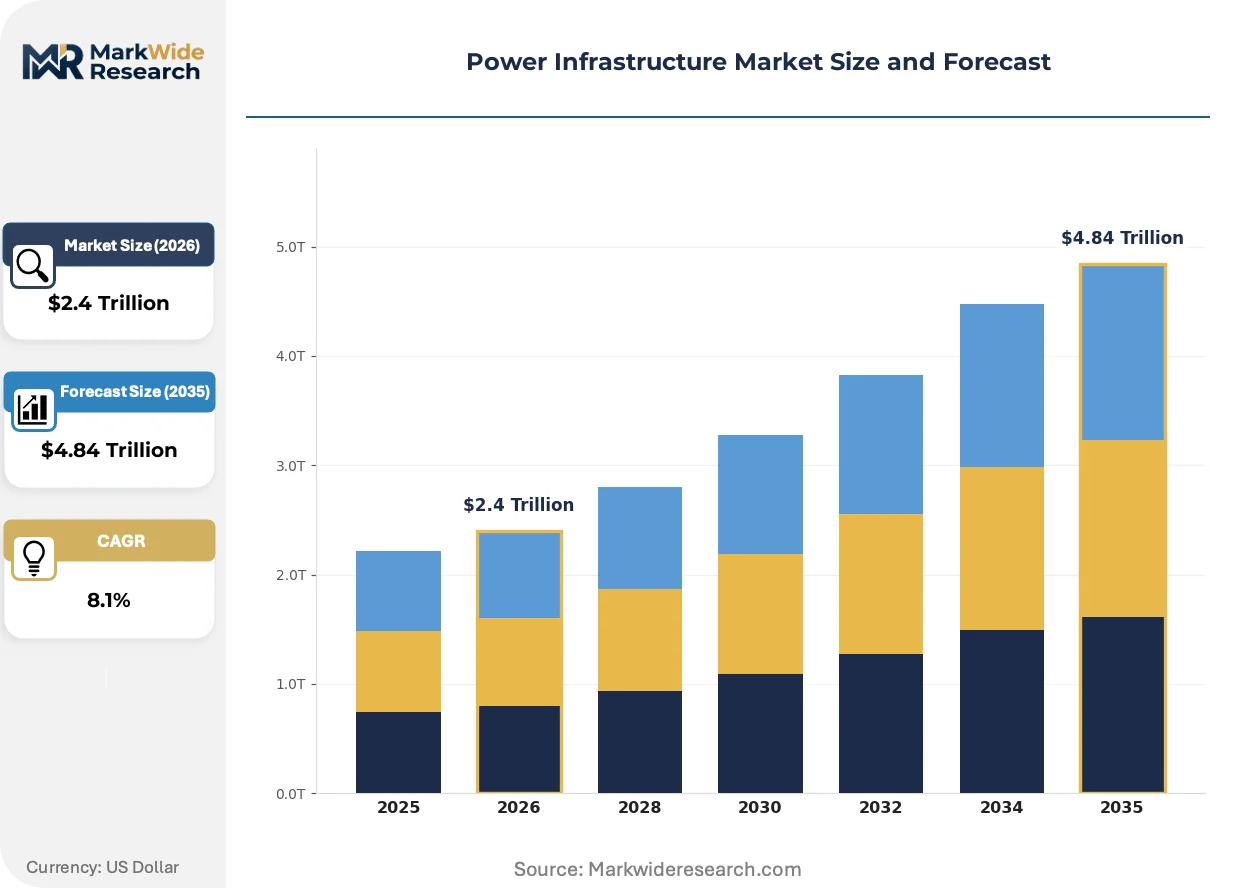
| Market Size in 2026 | $2.4 Trillion |
| Market Size in 2035 | $4.84 Trillion |
| CAGR (2026 – 2036) | 8.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Transmission, Distribution, Generation, Storage Technology: Smart Grid, Renewable Energy, Conventional Power, Energy Management End User: Utilities, Industrial Sector, Commercial Buildings, Residential Projects Service Type: Installation, Maintenance, Consulting, Project Management |
| Companies Covered | General Electric, Siemens Energy, Schneider Electric, ABB, Hitachi Energy, Mitsubishi Power, Larsen & Toubro, Fluor, Bechtel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Infrastructure Market Trends and Innovations
Digital twin platforms are redefining how power infrastructure vendors capture lifetime value, shifting revenue from equipment sales to predictive service subscriptions. This transformation compresses traditional maintenance windows and elevates software competency among hardware incumbents.
Solid-state transformer technology is consolidating medium-voltage distribution architectures by integrating power electronics directly into substation footprints. European distribution system operators pilot silicon carbide-based designs for rapid voltage regulation and harmonic isolation. The technology is consolidating conventional transformer-plus-switchgear assemblies into single-enclosure solutions, reducing substation footprints and enabling direct current microgrid interconnection.
The EU Green Deal's embedded F-Gas Regulation mandates fluorinated greenhouse gas phase-downs across switchgear and transformer fleets. Equipment manufacturers redesign product portfolios toward vacuum interruption and clean air dielectrics, accelerating alternative insulation qualification programs. European transmission utilities face the steepest compliance curves, with medium-voltage distribution switchgear conversions preceding high-voltage circuit breaker transitions.
Utility procurement departments now unbundle long-term service agreements from initial equipment purchases, treating predictive maintenance and spare parts as separate competitive tenders. This behavioral shift elevates independent service providers and software specialists against integrated OEM offerings. The pattern is most pronounced in North American gas turbine and wind turbine generator fleets, where operators seek to diversify vendor risk across multiple maintenance partners.
Power Infrastructure Market Segmentation
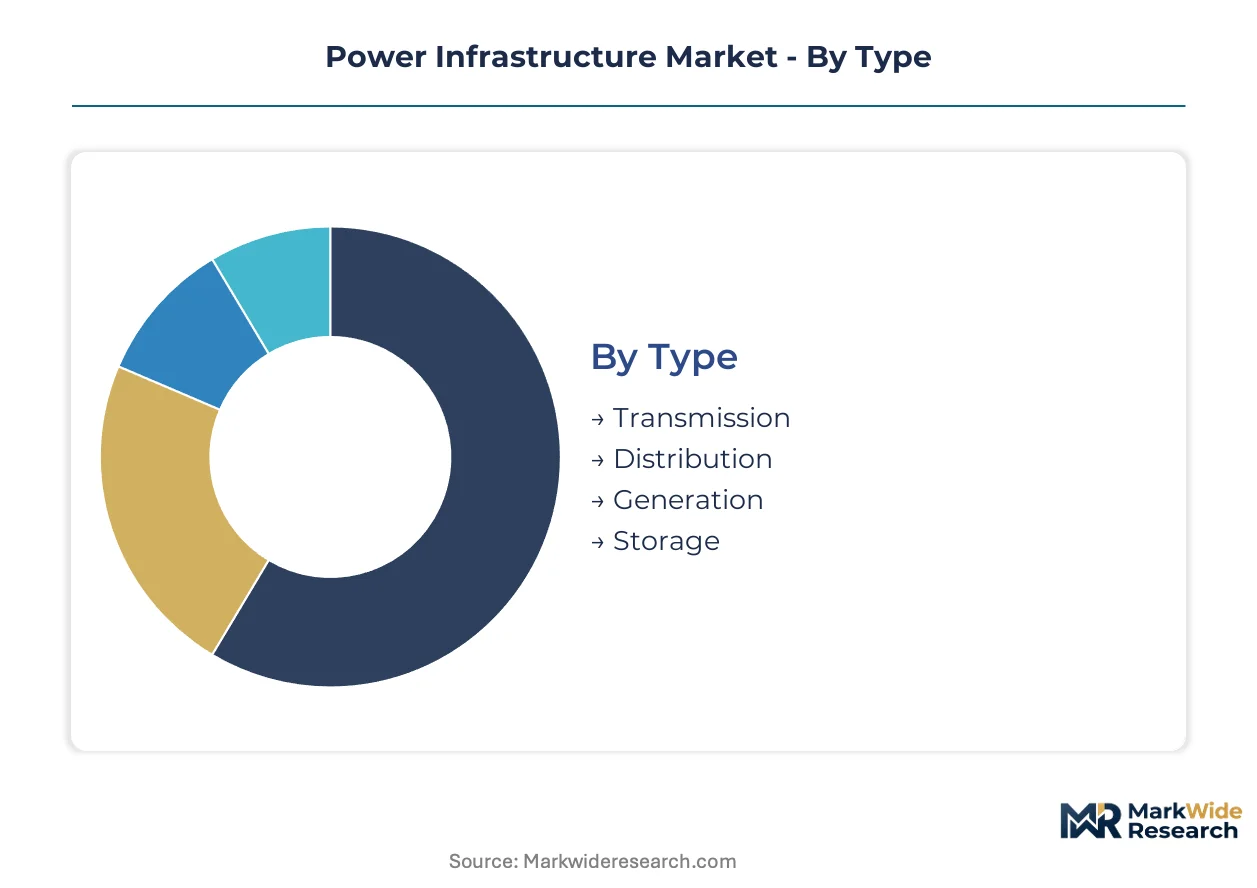
Power infrastructure vendors configure product portfolios around distinct asset lifecycles, technology maturity curves, and buyer procurement sophistication. Segmentation clarity enables suppliers to align hardware specifications, digital service bundles, and financing structures with the operational priorities of each customer cluster.
Type:
Replacement cycles and capacity expansion timelines differ sharply across voltage tiers and asset classes, dictating vendor sales cadence and service contract structures.
- Transmission:Ultra-high-voltage corridors above 800 kV require specialized converter stations and gas-insulated switchgear with 40-60 year design lives. India's interstate renewable evacuation projects and Southeast Asian cross-border interconnectors are absorbing the bulk of new orders as state utilities prioritize grid stability over cost minimization.
- Storage:Lithium-ion battery systems and emerging long-duration chemistries enable temporal arbitrage, frequency regulation, and renewable firming services. Merchant developers in the United States leverage Inflation Reduction Act credits to co-locate standalone storage with solar farms, compressing project payback periods.
- Distribution:Medium-voltage substations and feeder automation equipment form the physical backbone for bidirectional power flows from rooftop solar and electric vehicle chargers.
- Generation:Centralized thermal and renewable assets face margin compression as equipment costs decline and dispatch profiles shift toward flexibility services.
Volume placements concentrate in Distribution; the faster expansion belongs to Storage.
Technology:
Technology selection hinges on regulatory compliance deadlines, digital integration requirements, and the trade-off between proven reliability and performance optimization.
- Smart Grid:Advanced metering infrastructure, distribution management systems, and wide-area monitoring platforms enable real-time visibility and automated response. European distribution system operators pilot IEC 61850-compliant digital substations to unify multi-vendor SCADA protocols and reduce protection engineer staffing burdens.
- Energy Management:Software platforms for demand forecasting, asset optimization, and predictive maintenance capture recurring revenue streams. Siemens Energy and General Electric anchor competitive positions through digital twin subscriptions that extend customer lifetime value beyond initial equipment sales.
- Renewable Energy:Solar PV, wind turbine generators, and hybrid power plants require specialized grid-forming inverters and harmonic filtering equipment.
- Conventional Power:Gas turbine and coal-fired assets face retrofit pressure to accommodate hydrogen blending and carbon capture integration.
Smart Grid claims the largest installed base; Energy Management is climbing the fastest as utilities unbundle software procurement from hardware tenders.
End User:
Procurement sophistication and risk tolerance vary across buyer categories, shaping contract terms, financing structures, and vendor relationship intensity.
- Utilities:Vertically integrated and unbundled grid operators command multi-year capital programs governed by rate-case proceedings and reliability mandates. US investor-owned utilities navigate FERC Order 2222 compliance while Southeast Asian state utilities accelerate modernization timelines under national power development plans.
- Industrial Sector:Energy-intensive manufacturers pursue captive generation, on-site storage, and power purchase agreements to hedge volatile electricity tariffs. Green hydrogen electrolyzer co-location at industrial hubs creates demand for integrated renewable-to-storage-to-fuel systems with grid stabilization revenue stacking.
- Commercial Buildings:Office complexes and retail centers deploy behind-the-meter solar, battery storage, and building energy management systems to reduce demand charges.
- Residential Projects:Single-family and multi-family housing developers integrate rooftop solar, home batteries, and electric vehicle charging infrastructure.
Utilities absorb the majority of capital deployment; Industrial Sector applications are gaining share fastest through corporate renewable procurement and on-site power-to-X investments.
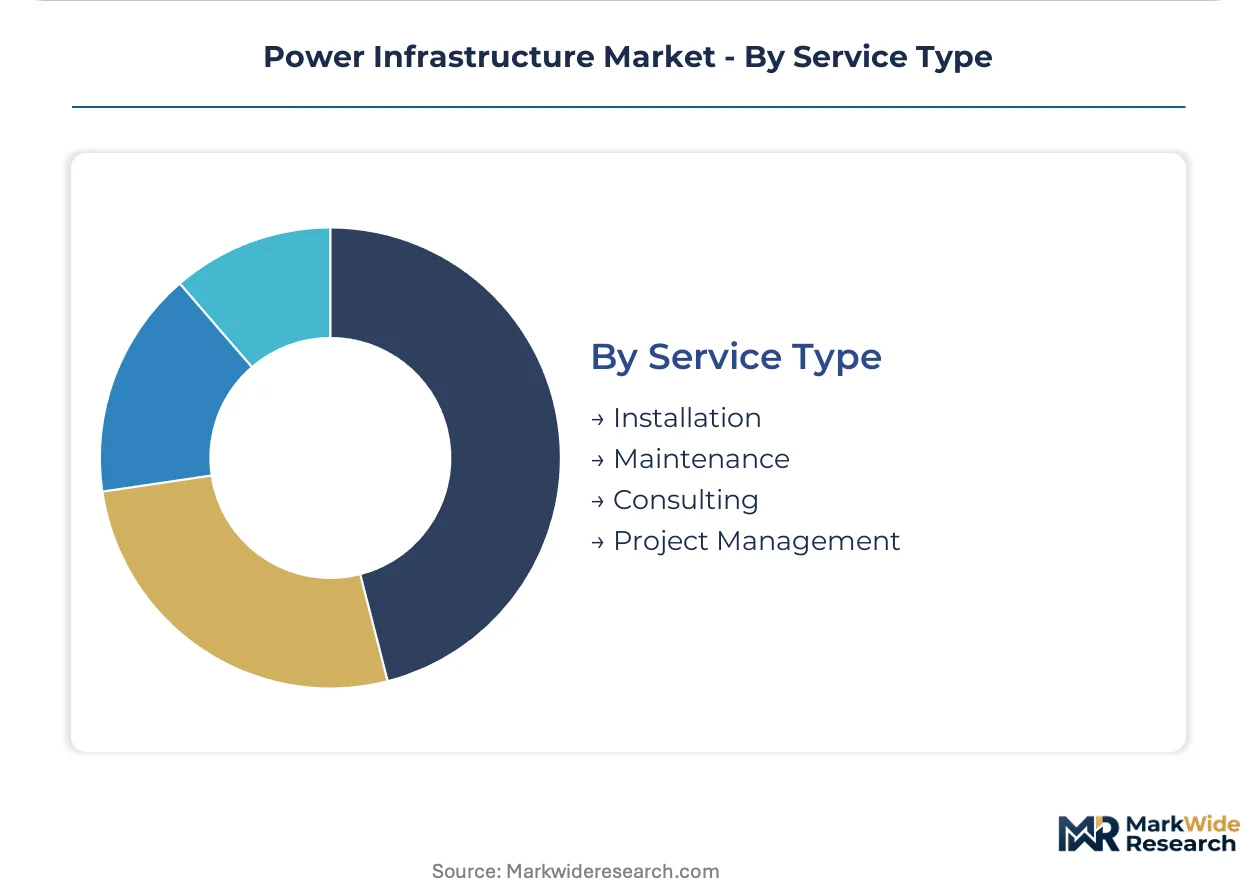
Service Type:
Service bundling strategies must align with asset criticality, technical complexity, and the availability of specialized labor pools in each geography.
- Installation:EPC contractors manage civil works, equipment delivery, commissioning, and grid interconnection for greenfield substations and renewable plants. Prolonged interconnection queues at US regional transmission organizations inflate carrying costs and compress contractor margins.
- Maintenance:Predictive service contracts leverage sensor data and machine learning to optimize outage scheduling and spare parts inventory. Independent service providers compete against OEM offerings as utility procurement departments unbundle long-term agreements from initial equipment purchases.
- Consulting:Engineering studies for grid planning, protection coordination, and regulatory compliance address specialized expertise scarcity.
- Project Management:Owner's engineer and construction supervision services mitigate execution risk for complex multi-vendor deployments.
Installation commands the largest revenue pool; Maintenance is expanding most quickly as digital platforms enable outcome-based service models and predictive intervention capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Power infrastructure investment flows split between mature markets replacing aging assets and emerging economies building first-generation grids. Consumption growth in Asia outpaces local manufacturing capacity for ultra-high-voltage equipment. Capital deployment concentrates where regulatory clarity meets procurement scale.
United States
Merchant battery developers exploit Inflation Reduction Act standalone storage credits to co-locate projects with solar farms across Texas and California. FERC Order 2222 compels investor-owned utilities to upgrade distribution management systems for distributed resource aggregation. Grid-scale deployments cluster in ERCOT and CAISO territories where interconnection reforms lag behind developer interest.
China
State Grid Corporation advances ultra-high-voltage direct current corridors exceeding 800 kV to transmit western renewable generation toward eastern demand centers. MIIT dual carbon goals accelerate solid-state transformer pilots in Yangtze River Delta distribution networks. Manufacturing concentration in Jiangsu and Zhejiang provinces supplies domestic and export markets for gas-insulated switchgear.
Germany
Transmission system operators face steep EU F-Gas Regulation compliance curves for SF6 phase-downs across existing switchgear fleets. Clean air and vacuum interruption technologies dominate new substation tenders in North Rhine-Westphalia industrial corridors. Offshore wind evacuation projects drive demand for converter stations linking North Sea generation to Bavarian load centers.
India
State utilities pursue interstate transmission corridors connecting renewable-rich Rajasthan and Tamil Nadu to northern demand hubs. CEA mandates and PLI scheme incentives accelerate domestic manufacturing of transformers and transmission towers. Greenfield ultra-high-voltage substations concentrate along the western-to-eastern renewable evacuation routes.
Vietnam
National power development plans prioritize LNG-to-power and offshore wind integration requiring digital substation upgrades. Grid modernization programs create procurement openings for battery storage vendors as EVN accelerates automation timelines. Southern economic zones around Ho Chi Minh City absorb priority distribution infrastructure investment.
Power Infrastructure Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the power infrastructure value chain. Equipment manufacturers with captive foundry and fabrication capabilities face margin pressure from engineering specialists outsourcing component production. Three archetypes dominate: integrated OEMs bundling hardware with digital service platforms, pure-play EPC contractors executing turnkey substation projects, and software specialists unbundling predictive maintenance from equipment sales. Consolidation concentrates among turbine and switchgear manufacturers while distribution automation remains fragmented. Dominant competitive moves include vertical integration into rare earth magnet supply chains and strategic partnerships for solid-state transformer commercialization.
Within the integrated OEM tier, General Electric and Siemens Energy exemplify the shift toward recurring revenue through predictive maintenance subscriptions. Schneider Electric occupies a position bridging hardware manufacturing with energy-as-a-service software models. These three anchors demonstrate how European and US-based incumbents are repositioning around digital twin platforms and long-term service contracts rather than transactional equipment sales.
| Leading Market Players |
|---|
| General Electric |
| Siemens Energy |
| Schneider Electric |
| ABB |
| Hitachi Energy |
| Mitsubishi Power |
| Larsen & Toubro |
| Fluor |
| Bechtel |
| Others |
Pricing and Supply Chain Analysis
Protection engineer scarcity in North America and Western Europe widens labor-cost differentials between premium-tier digital substation deployments and economy-tier conventional installations. This workforce concentration compresses margins on complex protection coordination projects while inflating pricing spreads across service bundling tiers.
Pricing Analysis
Margin tightening in gas turbine maintenance reflects utility procurement departments unbundling long-term service agreements from initial equipment purchases. Three-tier pricing structure across premium, standard, and economy levels separates predictive digital twin subscriptions from time-based spare parts contracts and break-fix emergency response. Price differentiation traces to certification grade—ISO 55000 asset management compliance commands premiums—and geographic delivery cost for remote substation access. Cost-down pressure on distribution automation accelerates because independent software vendors displace integrated OEM service packages. Merchant battery developers in ERCOT territories exhibit highest price sensitivity; ultra-high-voltage transmission utilities in India demonstrate lowest.
Supply Chain Analysis
Freight cost volatility for oversized transformer shipments from Jiangsu and Zhejiang provinces to Southeast Asian project sites compresses EPC contractor margins. Manufacturing concentration centers on China for gas-insulated switchgear, India for transmission towers and distribution transformers under PLI scheme incentives, and Germany for clean air insulation technologies. Raw material dependencies draw from Chilean copper cathode, Chinese rare earth processing for permanent magnet generators, and Australian lithium hydroxide for battery cathodes. Single-source vulnerability in SF6 gas supply chains amplifies operational risk for European utilities facing F-Gas Regulation compliance deadlines. Distribution runs through direct OEM-to-utility contracts for ultra-high-voltage equipment and regional EPC aggregators for distribution automation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Power infrastructure is consolidating around vendors with captive digital service platforms as margin compression in hardware-only sales forces weaker players toward exit or acquisition.
For Market Incumbents: Deploy predictive maintenance subscriptions to lock in recurring revenue streams beyond transactional equipment sales. Siemens Energy and General Electric exemplify this lever through digital twin platforms that extend customer lifetime value. Backward integration into rare earth magnet supply chains defends against Chinese processing dominance. Independent software specialists threaten unbundled service margins; incumbents should accelerate IEC 61850 protocol harmonization to maintain platform stickiness. For New Entrants and Emerging Players: EPC contractors in Vietnam's southern economic zones represent the most penetrable channel partner type for battery storage and digital substation vendors. Target greenfield ultra-high-voltage substation deployments along India's western-to-eastern renewable evacuation routes where domestic manufacturing capacity lags demand. Co-location with green hydrogen electrolyzer projects at industrial hubs enables power-to-X revenue stacking as a differentiated go-to-market angle. For Investors and Strategic Acquirers: Re-rating potential sits with solid-state transformer specialists given silicon carbide commercialization timelines and European distribution operator pilot programs. Long-term viability across the next decade favors asset-light engineering specialists with software-defined grid management capabilities over capital-heavy foundry operators. Acquisition targets should demonstrate captive digital service revenue streams exceeding hardware sales. The signal to watch is F-Gas Regulation enforcement acceleration triggering forced replacement cycles across European SF6 switchgear fleets.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Platform Deployment | Siemens Energy and GE anchor recurring revenue through predictive maintenance subscriptions tied to gas turbine fleets. |
| Backward Integration into Rare Earth Supply | Captive magnet production hedges Chinese processing dominance for wind turbine generator and transformer manufacturers. |
| Clean Air Insulation Qualification | ABB and Hitachi Energy accelerate vacuum interruption R&D to capture EU F-Gas Regulation-driven replacement cycles. |
| Battery Storage Co-location Strategy | Merchant developers leverage IRA standalone storage credits to compress project payback periods in ERCOT territories. |
| IEC 61850 Protocol Harmonization | Schneider Electric extends energy-as-a-service reach by unifying multi-vendor SCADA during brownfield automation retrofits. |
Research Methodology
SEC 10-K filings, FERC interconnection queue databases, and IEA power sector reports formed the secondary backbone for market sizing and competitive positioning. Primary interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators validated demand assumptions and procurement timelines. Bottom-up triangulation across project development pipelines and top-down reconciliation against national power development plans anchored volume estimates.
Historical trendline analysis of capital deployment patterns across generation, transmission, and distribution tiers informed growth trajectory modeling. Segmentation dimensions span voltage class, technology maturity, end-user procurement sophistication, and service bundling intensity. CAGRs were derived from installed base replacement cycles and capacity expansion timelines. Forecast inputs incorporate NERC reliability standard compliance costs and F-Gas Regulation phase-down enforcement curves.
Caveats apply where copper and rare earth price volatility, prolonged interconnection queue delays, or protection engineer scarcity could materially shift the outlook. Forecasts reflect assumptions about regulatory enforcement timelines and technology cost reduction curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
Thailand Power Market
Power Equipment
Europe Power Rental Market
Power Equipment
Automatic Power Factor Controller Market
Power Equipment
Wind Turbine Bolts Market
Power Equipment
Power Equipment Testing Market
Power Equipment
Kazakhstan Power EPC Market
Power Equipment
Induction Heating System Market
Power Equipment
Turbomachinery Control Systems, Retrofitting, and Ancillary Services Market
Power Equipment
Gas Turbine Compressor Market
Power Equipment
Global Exhaust Heat Recovery System Market
Power Equipment
Middle East Power Filter Market
Power Equipment
Industrial Gas Turbine Sales Market
Power Equipment
Steam Turbine Control System Market
Power Equipment
Equatorial Guinea Power EPC Market
Power Equipment
Industrial Power Transmission Drive Belts Market
Power Equipment
Power Plant Maintenance Market