
 United Arab Emirates Power EPC Market | 2026-2036
United Arab Emirates Power EPC Market Size, Share, and Industry Trends Forecast 2026-2036
United Arab Emirates Power EPC Market Analytics
Abu Dhabi utility procurement is hardening qualification barriers for power EPC contractors chasing gigawatt-scale renewable and conventional plant awards. Larsen & Toubro Limited leverages its integrated construction-engineering platform to compete for combined-cycle and solar thermal packages across the emirate. Siemens Energy AG anchors technology supply for gas turbine and grid stabilization components tied to EWEC and TAQA programs. Petrofac Limited specializes in project management and commissioning services for complex hybrid developments.
Power EPC in the United Arab Emirates covers the full-scope delivery of electricity generation, transmission, and distribution infrastructure, spanning engineering design, equipment procurement, civil works, and grid interconnection at voltages up to 400 kV. Contractors execute combined-cycle gas plants, photovoltaic fields, and substation upgrades under lump-sum turnkey contracts with performance guarantees on output and schedule. The Project Type segment shows Renewable Energy outpacing Conventional Power in new order intake, while Transmission and Distribution retrofits absorb steady maintenance capital. The Solution dimension sees Turnkey Projects commanding premium pricing for risk transfer, whereas Hybrid Solutions integrating battery storage with solar generation are capturing the fastest growth in developer pipelines.
MOHAP and the Emirates Authority for Standardization and Metrology enforce equipment certification and environmental compliance that shape contractor eligibility and technology selection for federal power programs. DEWA's independent regulatory mandate sets Dubai-specific grid codes and distributed generation standards that diverge from Abu Dhabi utility protocols. Stakeholders must monitor evolving carbon intensity benchmarks and localization requirements that will determine which EPC consortia retain access to the emirates' largest upcoming procurement cycles.
Market Dynamics
EWEC's Al Dhafra and Al Ajban solar-gas hybrid procurement cycles are compressing contractor qualification timelines while hardening technical barriers around grid-forming inverter capability and 400 kV substation integration.
Growth Catalysts
- Net-metering frameworks:Federal distributed generation standards under Emirates Authority for Standardization and Metrology are unlocking commercial and industrial rooftop solar EPC contracts across Dubai and the Northern Emirates.
- Abu Dhabi utility procurement:EWEC's gigawatt-scale renewable tenders are pulling integrated EPC consortia toward combined-cycle and photovoltaic hybrid packages with 25-year performance guarantees.
- MOHAP efficiency mandates:Medical facility energy performance requirements are driving hospital campus microgrid and captive solar installations, expanding addressable EPC scope beyond traditional utility programs.
Market Restraints
- Specialized labor scarcity:Grid-forming inverter commissioning and 400 kV gas-insulated switchgear installation require certified technicians that remain concentrated in European and South Korean supply bases.
- Steel and copper price volatility:Raw material input swings compress fixed-price turnkey margins on transmission tower and substation civil works packages.
- Localization requirements:In-country value thresholds for federal procurement are forcing EPC contractors to restructure procurement around nascent UAE manufacturing capacity with limited track records.
Strategic Opportunities
- Battery storage convergence:Lithium-ion and emerging sodium-ion systems paired with solar generation are creating new EPC service lines around four-hour duration hybrid plants in developer pipelines.
- Industrial zone microgrids:KIZAD and Jebel Ali Free Zone manufacturing clusters present captive power opportunities outside utility tariff structures.
- DEWA regulatory divergence:Dubai-specific grid codes and distributed generation standards are enabling specialized EPC positioning distinct from Abu Dhabi utility protocols.
Industry Challenges
- Grid code compliance timelines:DEWA and EWEC certification cycles for inverter and protection relay interoperability extend project mobilization schedules by six to nine months.
- Legacy SCADA integration:Existing TAQA transmission network control systems require custom protocol gateways that inflate engineering hours on brownfield substation upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Arab Emirates Power EPC Market |
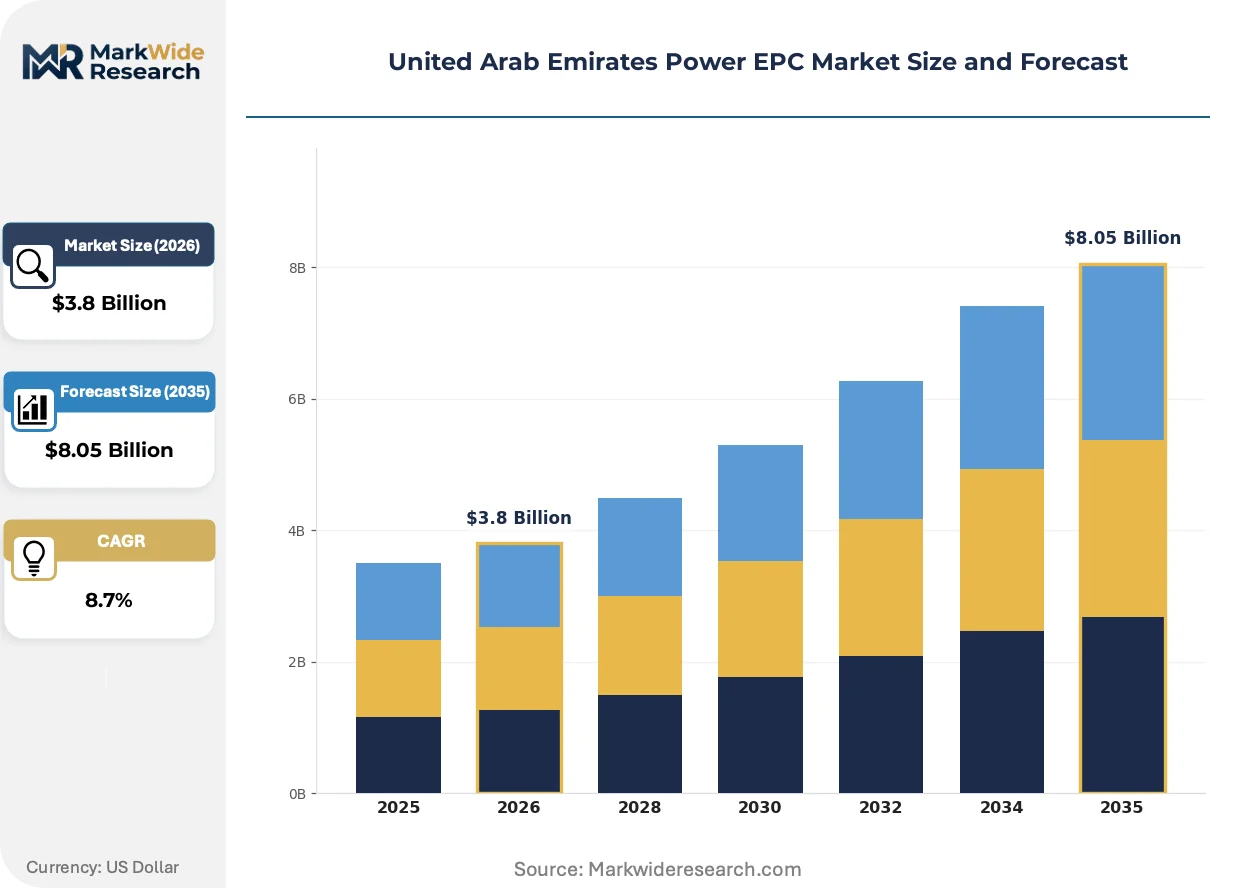
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Engineering, Procurement, Construction, Project Management End User: Public Sector, Private Sector, Utilities, Industrial Project Type: Renewable Energy, Conventional Power, Transmission, Distribution Solution: Turnkey Projects, Hybrid Solutions, Greenfield Developments, Retrofits |
| Companies Covered | Emirates Water & Electricity Co. (EWEC), Larsen & Toubro Limited, Dubai Electricity & Water Authority (DEWA), Bechtel Corporation, Petrofac Limited, Abu Dhabi National Energy Co. (TAQA), Siemens Energy AG, NMDC Group, ACWA Power, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Arab Emirates Power EPC Market Evolving Landscape
Hybrid plant architectures are collapsing the traditional separation between renewable and conventional power EPC scopes, forcing contractors to build integrated capabilities across photovoltaic, battery, and gas turbine domains simultaneously.
Grid-forming inverter technology is electrifying utility-scale solar EPC packages by replacing conventional synchronous condensers for voltage regulation. EWEC and ACWA Power partnerships are specifying these inverters for Al Dhafra phase extensions. The shift is compressing substation footprint requirements while raising power electronics engineering intensity across contractor bids.
MOHAP facility energy performance standards are mandating real-time metering and automated demand response for hospital campuses above 50,000 square meters. The regulation is pulling medical EPC contracts toward integrated building-to-grid control systems. Dubai Health Authority facilities are responding with design-build tenders that bundle HVAC, solar, and battery assets under single accountability structures.
Long-term service agreements are displacing traditional equipment-only procurement for gas turbine packages. DEWA and TAQA programs now require 15-year maintenance commitments with availability guarantees from EPC consortia. Abu Dhabi utility buyers are consolidating vendor relationships around fewer integrated construction-engineering platforms capable of absorbing operational risk across plant lifecycles.
United Arab Emirates Power EPC Market Segmentation
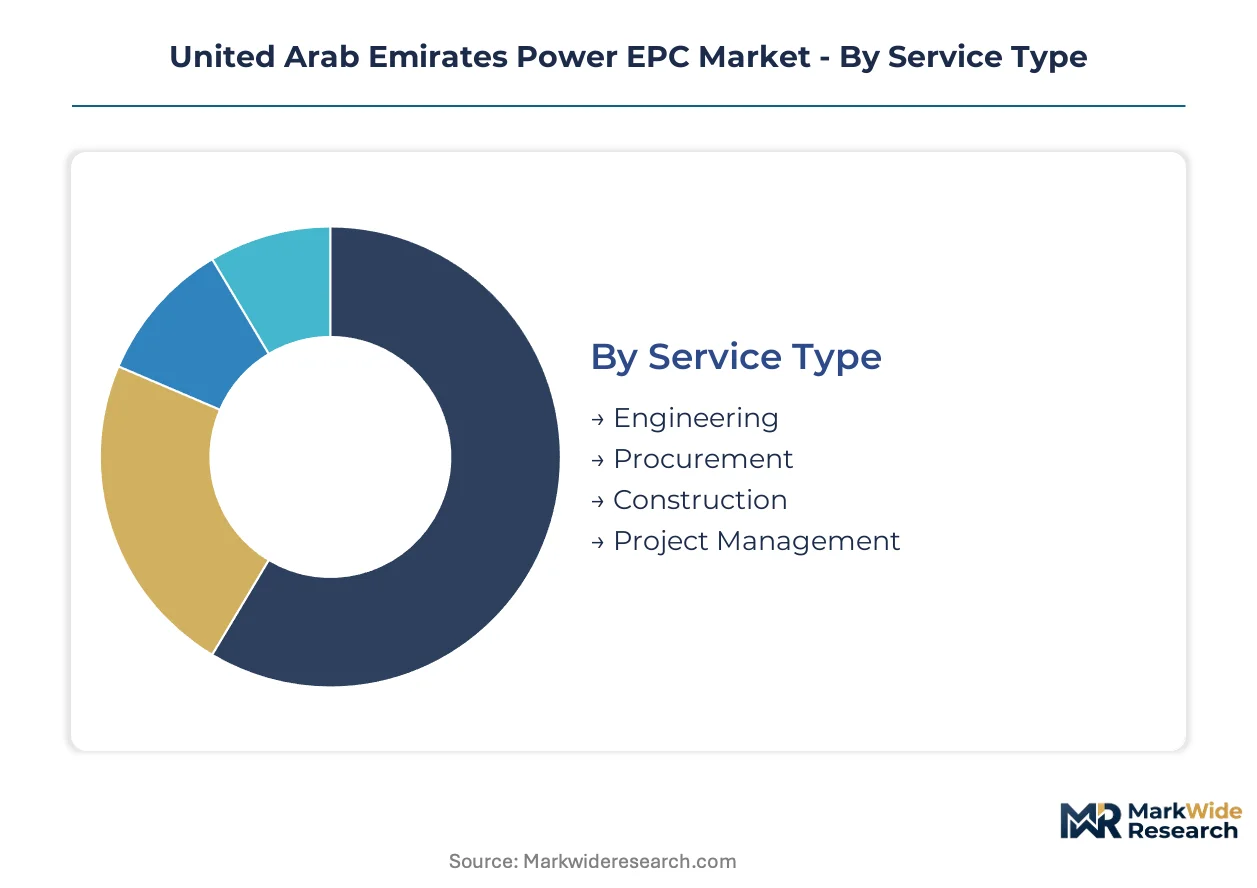
Segmentation in the UAE power EPC market reveals how procurement complexity varies across buyer mandates and technical scopes. Contractors must calibrate capabilities to match divergent risk profiles between federal utility programs and private industrial developments.
Service Type:
Buyer sophistication separates lump-sum turnkey demand from time-and-materials advisory work.
- Engineering:Front-end design and feasibility studies for 400 kV substations and combined-cycle configurations command premium fees from owners seeking bankable documentation. EWEC's Al Dhafra procurement requires engineering contractors to deliver grid-forming inverter specifications that satisfy Abu Dhabi utility interconnection standards.
- Procurement:Long-lead equipment sourcing for gas turbines and gas-insulated switchgear absorbs 45-60 percent of total project capital. Contractors with established vendor relationships with Siemens Energy AG and Hyundai Electric secure schedule advantages on EWEC and DEWA programs.
- Construction:Civil works, mechanical erection, and electrical installation execute the physical plant realization under fixed-price contracts with liquidated damages clauses. Desert site conditions and summer work restrictions compress construction windows for photovoltaic field deployments.
- Project Management:Owner's engineer and construction supervision services provide independent oversight on complex hybrid developments. Petrofac Limited and similar specialists compete for these risk-mitigation roles on ACWA Power partnership structures.
Construction leads volumes today; engineering is gaining share fastest as front-end complexity intensifies.
End User:
Capital commitment scale and regulatory exposure distinguish buyer categories.
- Public Sector:Federal and emirate-level infrastructure agencies procure under MOHAP efficiency mandates and federal net-metering frameworks with stringent localization thresholds. Hospital campus microgrids and government facility solar installations expand addressable scope beyond traditional utility programs.
- Private Sector:Commercial developers and real estate investment trusts pursue distributed generation under DEWA's independent regulatory mandate with Dubai-specific grid codes. Rooftop solar EPC contracts concentrate in Jebel Ali Free Zone and Dubai South logistics corridors.
- Utilities:Emirates Water & Electricity Co. and TAQA drive gigawatt-scale procurement with 25-year performance guarantees and integrated O&M commitments. These buyers consolidate vendor relationships around fewer EPC platforms capable of absorbing lifecycle operational risk.
- Industrial:KIZAD and Jebel Ali manufacturing clusters seek captive power outside utility tariff structures. Aluminum smelters and petrochemical facilities require high-reliability microgrids with islanding capability.
Utilities dominate current award value; industrial is expanding most quickly as energy-intensive manufacturing localizes.
Project Type:
Technology maturity and grid integration complexity shape contractor qualification requirements.
- Renewable Energy:Photovoltaic fields and solar thermal installations with battery storage integration absorb the majority of new order intake. EWEC's Al Ajban and Al Dhafra extensions specify grid-forming inverters that replace synchronous condensers for voltage regulation.
- Conventional Power:Combined-cycle gas turbine plants and simple-cycle peakers provide firming capacity for renewable intermittency. Long-term service agreements now displace equipment-only procurement, requiring 15-year maintenance commitments with availability guarantees.
- Transmission:400 kV substation upgrades and new grid interconnection infrastructure address renewable generation concentration in Al Dhafra region. Brownfield SCADA integration with legacy TAQA control systems inflates engineering hours through custom protocol gateways.
- Distribution:Medium-voltage network reinforcement and smart metering deployment serve load growth in Dubai and Northern Emirates. DEWA's regulatory divergence from Abu Dhabi protocols creates specialized EPC positioning opportunities.
Renewable Energy leads volumes today; Transmission is climbing the fastest as grid integration bottlenecks intensify.
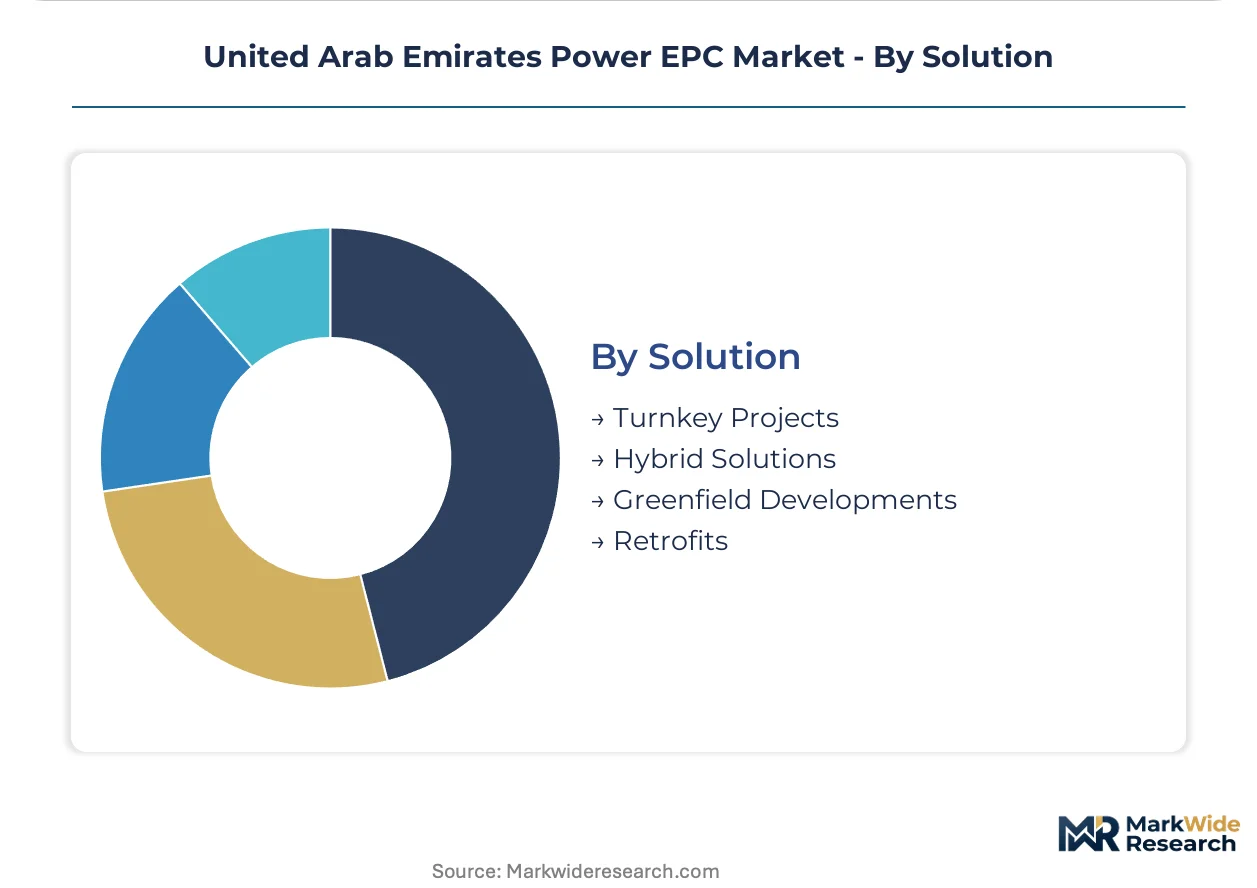
Solution:
Risk transfer scope and technology integration depth differentiate contract structures.
- Turnkey Projects:Lump-sum contracts with single-point accountability and performance guarantees on output, schedule, and efficiency. These command premium pricing for risk transfer and dominate utility-scale procurement from EWEC and DEWA.
- Hybrid Solutions:Integrated solar-gas or solar-battery configurations collapsing traditional separation between renewable and conventional EPC scopes. Four-hour duration lithium-ion and emerging sodium-ion systems represent the steepest expansion trajectory in developer pipelines.
- Greenfield Developments:New-build installations on undeveloped sites with full civil infrastructure construction. Desert site preparation and cooling water access constraints concentrate these opportunities in coastal and western Abu Dhabi locations.
- Retrofits:Brownfield upgrades of existing plants and substations requiring outage coordination and legacy system integration. TAQA transmission network control system compatibility demands extend mobilization schedules by six to nine months.
Turnkey Projects dominate current contract value; Hybrid Solutions are gaining share fastest as battery storage convergence accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Abu Dhabi and Dubai operate divergent procurement protocols, while Saudi Arabia and Qatar pursue parallel gigawatt-scale renewable programs that reshape contractor mobility across the Gulf Cooperation Council corridor.
Abu Dhabi
EWEC's Al Dhafra and Al Ajban solar-gas hybrid tenders absorb the majority of federal utility capital allocation. MOHAP efficiency mandates for medical facilities above 50,000 square meters expand EPC scope into hospital microgrids with real-time metering requirements. The Al Dhafra region concentrates photovoltaic field development with 400 kV substation integration demands.
Dubai
DEWA's independent regulatory mandate enforces grid codes that diverge from Abu Dhabi protocols, creating specialized contractor qualification pathways. Net-metering frameworks unlock commercial rooftop solar contracts across Jebel Ali Free Zone and Dubai South logistics corridors. Mohammed bin Rashid Al Maktoum Solar Park phases anchor utility-scale procurement with 25-year performance guarantees.
Sharjah
Sharjah Electricity and Water Authority pursues captive power solutions for industrial zones outside federal utility tariff structures. Federal net-metering standards under Emirates Authority for Standardization and Metrology enable distributed generation deployment across manufacturing clusters. The Hamriyah Free Zone presents microgrid opportunities for energy-intensive processing facilities.
Northern Emirates
Ras Al Khaimah and Fujairah utilities address transmission bottlenecks through 400 kV interconnection upgrades with Abu Dhabi grid infrastructure. Federal localization thresholds for procurement reshape contractor supply chain configurations around nascent domestic manufacturing capacity. Coastal desalination-power hybrid plants concentrate EPC demand in Fujairah's industrial port zone.
Saudi Arabia
ACWA Power's domestic gigawatt-scale renewable pipeline competes with UAE programs for integrated EPC consortium capacity. The Saudi Energy Efficiency Center enforces building performance standards that mirror MOHAP mandates across medical and commercial facilities. NEOM and Red Sea Project developments pull contractor resources toward northwestern solar and battery storage installations.
United Arab Emirates Power EPC Market Competitive Landscape
Indian construction-engineering platforms anchor one tier; European technology suppliers and Gulf state utilities hold procurement and project development positions. Market structure concentrates around integrated consortia capable of absorbing 25-year operational risk across hybrid plant lifecycles. Three archetypes dominate: lump-sum turnkey contractors, technology-anchored engineering firms, and utility-captive project developers. Competitive intensity centers on qualification barrier navigation and localization compliance rather than price alone.
Within the integrated construction-engineering tier, Larsen & Toubro Limited represents the Indian heavy infrastructure archetype with combined-cycle and solar thermal execution capabilities. Siemens Energy AG occupies the technology-supply position for gas turbine and grid stabilization components. Petrofac Limited exemplifies project management and commissioning specialization for complex hybrid developments. These three entities illustrate the cross-border consortium structures required for EWEC and DEWA program participation.
| Leading Market Players |
|---|
| Emirates Water & Electricity Co. (EWEC) |
| Larsen & Toubro Limited |
| Dubai Electricity & Water Authority (DEWA) |
| Bechtel Corporation |
| Petrofac Limited |
| Abu Dhabi National Energy Co. (TAQA) |
| Siemens Energy AG |
| NMDC Group |
| ACWA Power |
| Others |
Value Network & Pricing Analysis
MOHAP efficiency mandates for medical facilities gate both qualified EPC supply and premium-tier pricing access, compressing contractor margins for non-compliant bidders while rewarding integrated platforms with certification depth. Federal net-metering frameworks and EWEC's technical specifications further stratify the market, with grid-forming inverter capability and 400 kV integration experience commanding substantial price premiums over standard renewable packages.
Pricing Analysis
Capacity additions in South Korea and Germany are reshaping price floors for grid-forming inverters and gas-insulated switchgear, forcing UAE-based EPC consortia to absorb equipment cost volatility within fixed-price turnkey contracts. Pricing stratifies across premium, standard, and economy tiers based on contractor qualification depth and localization compliance, with EWEC and DEWA programs showing lowest price sensitivity among utility buyers. Cost compression in standard-tier photovoltaic EPC is intensifying because of Chinese module oversupply, while hybrid solutions with battery integration retain pricing power. Industrial zone developers in KIZAD and Jebel Ali exhibit highest price sensitivity due to captive power economics outside utility tariff structures.
Supply Chain Analysis
EWEC and DEWA certification requirements for grid-forming inverters and 400 kV equipment gate supply access to European and South Korean manufacturers with proven track records, excluding nascent UAE-based producers. Geographic supply concentration centers on Germany, South Korea, and China for power electronics, gas turbines, and battery cells respectively. Raw material dependencies span high-grade electrical steel, copper busbar, and lithium carbonate. Single-source vulnerability runs through specialized inverter commissioning technicians concentrated in European supply bases. Distribution runs through long-term framework agreements with Siemens Energy AG, Hyundai Electric, and tier-one battery integrators rather than spot procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE power EPC market represents a late-cycle quality story where contractor survival depends on qualification depth rather than scale alone. EWEC's hardening technical barriers around grid-forming inverters and 25-year performance guarantees signal demand-shift toward premium specifications that only integrated platforms can fulfill.
For Market Incumbents: Extend operational risk absorption capabilities through captive maintenance subsidiaries capable of fulfilling DEWA and TAQA long-term service agreement requirements. Deepen backward integration into battery storage system assembly within UAE free zones to satisfy federal localization thresholds while defending against emerging Korean EPC consortia. Prioritize certification investment in grid-forming inverter commissioning to maintain access to EWEC's Al Dhafra and Al Ajban procurement cycles. For New Entrants and Emerging Players: Capture distributed generation white space under DEWA's net-metering frameworks by specializing in commercial rooftop solar with Dubai-specific grid code compliance. Industrial zone microgrids in KIZAD and Hamriyah Free Zone present the most penetrable segment given limited incumbent presence outside utility programs. Pursue design-build positioning for MOHAP hospital campus projects that bundle HVAC, solar, and battery assets under single accountability structures distinct from traditional EPC consortia. For Investors and Strategic Acquirers: Roll-up economics work for project management specialists because EWEC and ACWA Power partnership structures increasingly unbundle construction supervision from integrated EPC risk. Five-to-ten year viability favors platforms with proven 400 kV substation integration and hybrid plant commissioning track records. Watch for inflection in Saudi Arabia's NEOM and Red Sea Project developments pulling contractor resources away from UAE programs, creating acquisition windows for distressed qualification-heavy assets.| Strategic Initiative | Industry Significance |
|---|---|
| Grid-Forming Inverter Certification | EWEC's Al Dhafra extensions specify these inverters, excluding non-qualified contractors from gigawatt-scale procurement. |
| Battery Storage Integration Capability | Four-hour duration lithium-ion and sodium-ion systems represent the steepest expansion trajectory in ACWA Power partnership pipelines. |
| Localization Supply Chain Restructuring | Federal in-country value thresholds force procurement reconfiguration around nascent UAE manufacturing with limited track records. |
| Long-Term Service Agreement Positioning | DEWA and TAQA programs now require 15-year maintenance commitments with availability guarantees from EPC consortia. |
| Industrial Zone Microgrid Development | KIZAD and Jebel Ali manufacturing clusters seek captive power outside utility tariff structures with islanding capability requirements. |
Research Methodology
Coverage spans Abu Dhabi, Dubai, Sharjah, and the Northern Emirates, with primary inputs from each emirate's utility and regulatory stakeholders. The analysis combines structured interviews with EWEC planning officers, DEWA grid operators, EPC contractor project directors, and ACWA Power partnership developers with secondary validation from FERC-equivalent regulatory filings, IEA regional power market reports, and project development databases. Bottom-up segmentation modeling triangulates against top-down utility capital expenditure disclosures to ensure consistency across the analysis window.
Granularity-level modeling distinguishes project scale tiers, technology integration depth, and regulatory framework clusters across the projection horizon. Segmentation dimensions include service type, end user category, project technology, and solution risk-transfer structure, with hybrid plant configurations receiving discrete treatment given their collapse of traditional renewable-conventional boundaries. CAGRs derive from utility procurement pipeline analysis and contractor order book trajectories, incorporating fuel price sensitivity and localization compliance scenarios as key forecast inputs.
Underlying measurement precision varies by segment; utility-scale turnkey contracts carry tighter precision than distributed generation estimates due to disclosed award values. Forecasts reflect documented assumptions regarding EWEC and DEWA procurement timelines, carbon intensity benchmark evolution, and federal localization threshold enforcement. A model refresh is warranted upon material change in Saudi Arabia's gigawatt-scale renewable pipeline competing for regional EPC capacity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
France Power EPC Market
Power Equipment
Power Grid Primary and Secondary Fusion Equipment Market
Power Equipment
Submarine Power Cable Market
Power Equipment
Uzbekistan Power EPC Market
Power Equipment
Wind Turbine Equipment Market
Power Equipment
Power Magnetics for MV AC Drive Market
Power Equipment
Turbomachinery Control Systems, Retrofitting, and Ancillary Services Market
Power Equipment
Wind Turbine Maintenance Market
Power Equipment
Power Engineering, Procurement, and Construction (EPC) Market
Power Equipment
Europe SCR Power Controller Market
Power Equipment
Thailand Power EPC Market
Power Equipment
Advanced Gas Generators Sales Market
Power Equipment
Asia-Pacific Steam Turbine Market
Power Equipment
Levant Power Cable Market
Power Equipment
Middle East Power Filter Market
Power Equipment
Heavy Duty Gas Turbine Market