
 Rail Traction Transformers Market | 2026-2036
Rail Traction Transformers Market Size, Share, and Industry Trends Forecast 2026-2036
Rail Traction Transformers Market Outlook
Lifecycle maintenance contracts is pivoting vendor revenue models from hardware-only sales to performance-based service agreements. Siemens leverages its rail electrification installed base to lock in long-term service revenue across European corridors. ABB anchors its competitiveness through integrated transformer-feeder systems that reduce substation footprint. Alstom specializes in compact traction transformers optimized for double-decker and high-speed train platforms.
Rail traction transformers are electromagnetic devices that step down overhead catenary voltage to levels suitable for traction motors, typically operating at 50/60 Hz with insulation classes rated for 25 kV or 15 kV networks and liquid-immersed or dry-type cooling configurations. Their primary purpose is to deliver stable, efficient power conversion under dynamic load conditions inherent to accelerating and braking rail vehicles. Three-phase traction transformers occupy the dominant share in freight locomotive applications where high power density and thermal endurance matter most. Solid-state and digital technology segments are expanding fastest as operators retrofit conventional fleets with condition-monitoring capabilities that cut unplanned downtime. Specialized transformer designs for metro systems represent a concentrated margin pool given tight dimensional constraints and customized cooling architectures.
Europe's F-Gas Regulation and REACH directives are phasing out conventional insulating fluids, compelling manufacturers to certify bio-based or fluoronitrile alternatives. IEC 60310 and EN 50329 standards govern temperature rise limits and short-circuit withstand tests, creating compliance barriers for new entrants without accredited testing infrastructure. China's GB standards and NMPA-equivalent rail certification processes add a parallel compliance track for suppliers targeting dual carbon-aligned procurement programs. Stakeholders must monitor how digital twin integration requirements in next-generation tender specifications reshape R&D allocation between hardware engineering and software development teams.
Market Dynamics
Electrification mandates for freight corridors and passenger networks are forcing transformer manufacturers to reconcile thermal performance gains with F-Gas-compliant insulating fluid transitions.
Growth Catalysts
- High-speed rail electrification:Public transport operators in China and Spain are procuring three-phase traction units for 350 km/h corridors, pulling volume demand from legacy diesel conversion programs.
- F-Gas Regulation phase-down:Europe's mandated reduction in fluorinated greenhouse gases is accelerating certification of bio-based ester and fluoronitrile coolants for liquid-immersed designs.
- Condition-monitoring retrofits:Solid-state sensor integration is enabling predictive maintenance contracts that extend asset life beyond traditional 30-year replacement cycles.
Market Restraints
- Copper and grain-oriented electrical steel volatility:Core material costs account for 55-65% of transformer manufacturing input, with price swings compressing margin visibility on fixed-price rail tenders.
- Testing infrastructure concentration:IEC 60310 and EN 50329 short-circuit withstand certification requires accredited high-power laboratories concentrated in Germany, China, and Japan, creating entry barriers for emerging suppliers.
- Extended replacement cycles:Traction transformers operate 40+ years in service, limiting annual addressable volume to greenfield installations and catastrophic failure replacements rather than routine refresh.
Strategic Opportunities
- India's Dedicated Freight Corridor expansion:The country's Ministry of Railways is electrifying 2,800 route-kilometers, creating demand for 25 kV/50 Hz single-phase units with tropical climate cooling architectures.
- Digital twin integration mandates:Next-generation European tender specifications require real-time thermal modeling, opening software-services revenue streams adjacent to hardware supply.
- Metro system densification:Underground rail operators in Brazil and Turkey are specifying compact dry-type designs for tunnel-constrained installations, commanding premium pricing over standard locomotive units.
Industry Challenges
- Multi-standard certification timelines:Suppliers targeting both European IEC and Chinese GB markets face parallel 18-24 month approval tracks, delaying revenue recognition on cross-border contracts.
- Field service technician scarcity:Specialized skills for on-rail transformer replacement and hot-oil processing are concentrated among aging workforces in France, Japan, and Switzerland, constraining maintenance capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rail Traction Transformers Market |
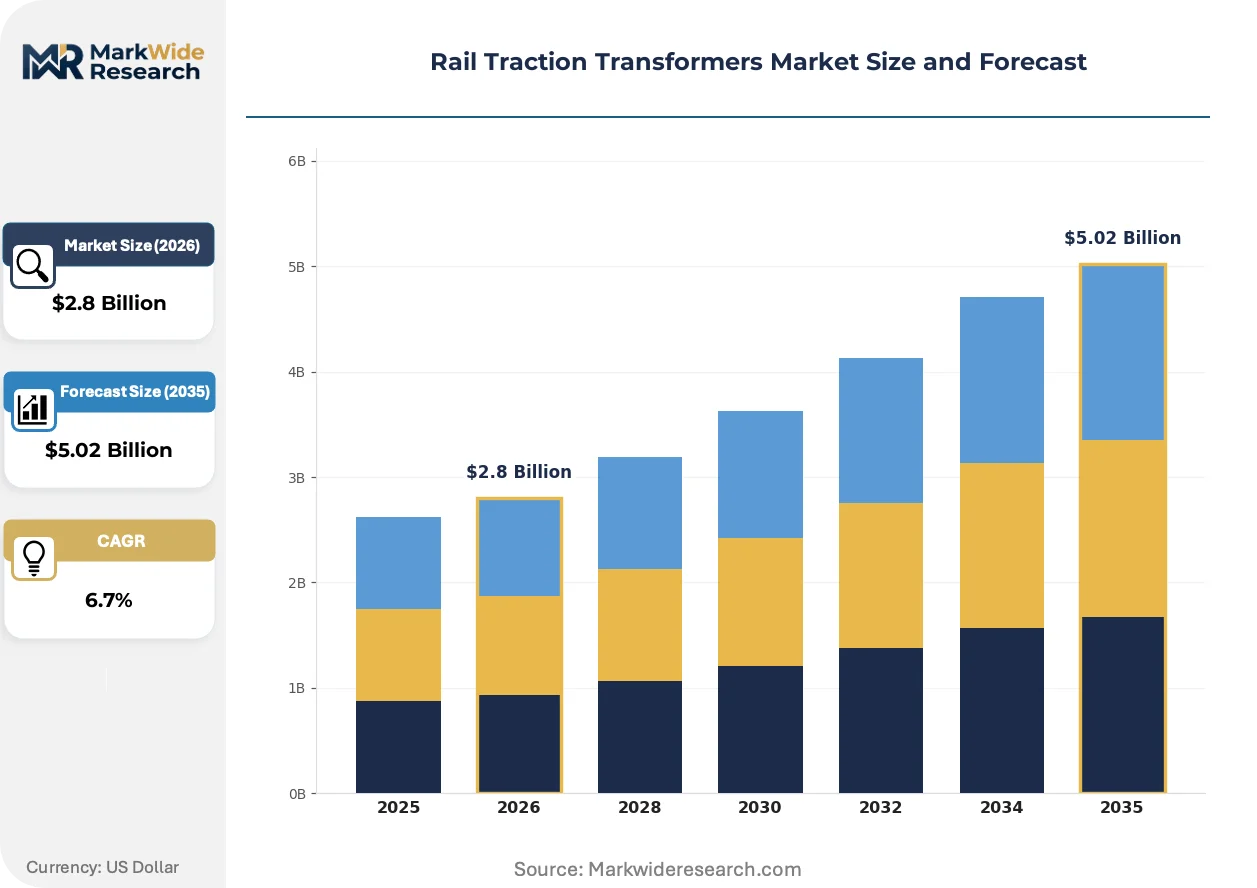
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Phase, Three-Phase, Auto Transformers, Specialized Transformers Application: Trains, Trams, Metro Systems, Freight Locomotives End User: Public Transport Operators, Private Rail Operators, Mining Companies, Industrial Users Technology: Conventional, Solid-State, Digital, Smart Grid |
| Companies Covered | ABB, Siemens, Mitsubishi Electric Corporation, Alstom, GE, Hitachi, JST Transformateurs, Hind Rectifiers Limited, CG Power & Industrial Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rail Traction Transformers Market Strategic Shifts
Digitalization of asset management and fluid chemistry innovation are compressing the traditional divide between hardware engineering and software-enabled service delivery in rail electrification.
Natural ester insulating fluids are consolidating market share in environmentally sensitive corridors. These vegetable-oil-based coolants deliver equivalent dielectric performance to mineral oil while eliminating aquatic toxicity risks in bridge and tunnel installations. Swiss and Austrian alpine operators have standardized on ester-filled designs, and Germany's KBA is fast-tracking type approvals for cross-border rolling stock compatibility.
Europe's F-Gas Regulation is forcing refrigerant-scale thinking into transformer thermal design. The 2024 ban on virgin hydrofluorocarbons above specific global warming potential thresholds is redirecting R&D budgets toward air-natural and forced-air cooling architectures that eliminate liquid insulation entirely. Dry-type traction transformers now dominate metro procurement specifications in France and the Netherlands, though weight penalties limit penetration in high-power freight locomotives.
Performance-based maintenance contracts are displacing time-based service schedules. European rail operators now specify availability guarantees rather than parts-and-labor coverage, transferring operational risk to manufacturers with installed base telemetry. This model concentrates service revenue with suppliers possessing digital infrastructure for remote dissolved gas analysis and thermal imaging, compressing margins for pure-hardware vendors.
Rail Traction Transformers Market Segmentation
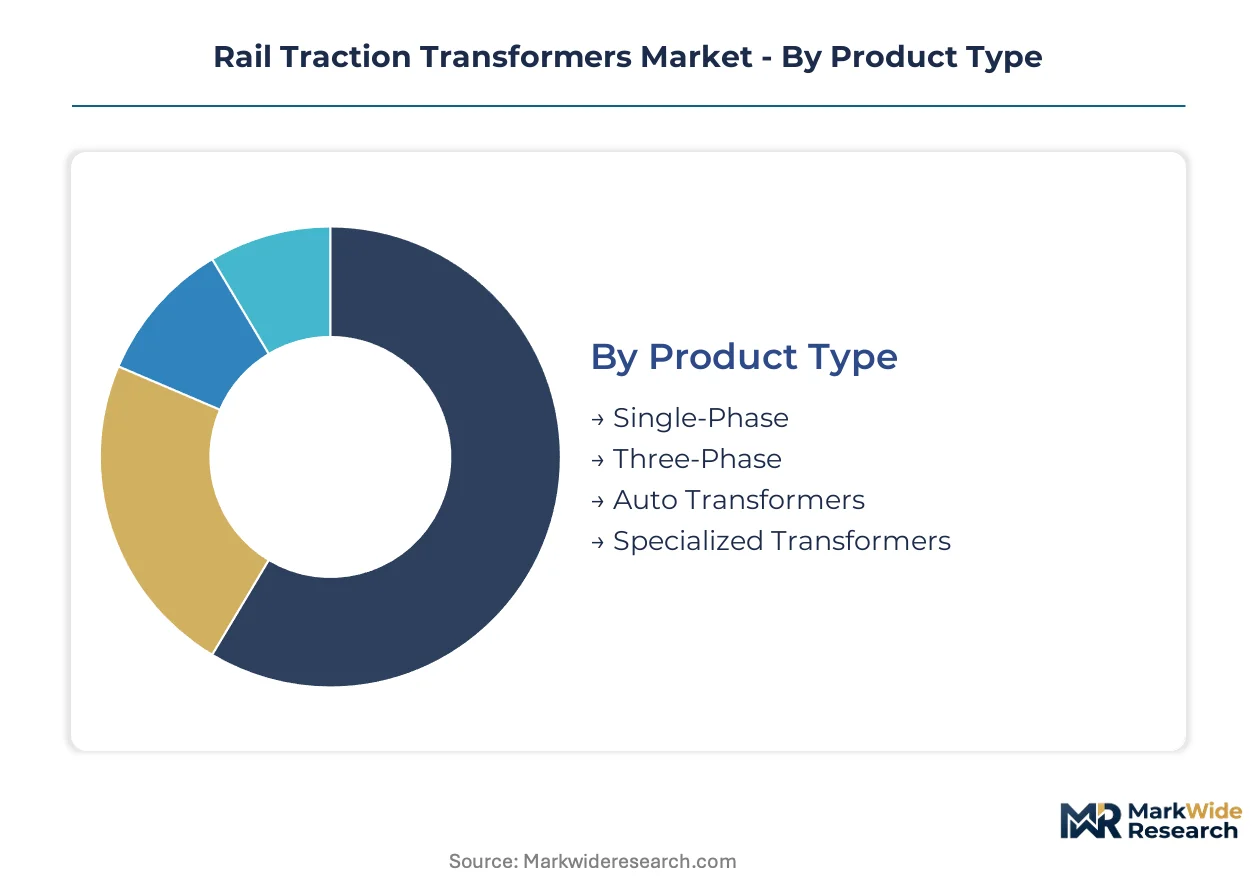
Rail traction transformer procurement splits across product architecture, vehicle platform, operator ownership structure, and embedded intelligence. Certification requirements vary sharply by segment, with liquid-immersed designs facing F-Gas Regulation scrutiny while dry-type units navigate fire-safety codes for tunnel installations.
Product Type:
Each architecture demands distinct IEC 60310 and EN 50329 test sequences, with liquid-immersed units requiring additional coolant toxicity certification under REACH.
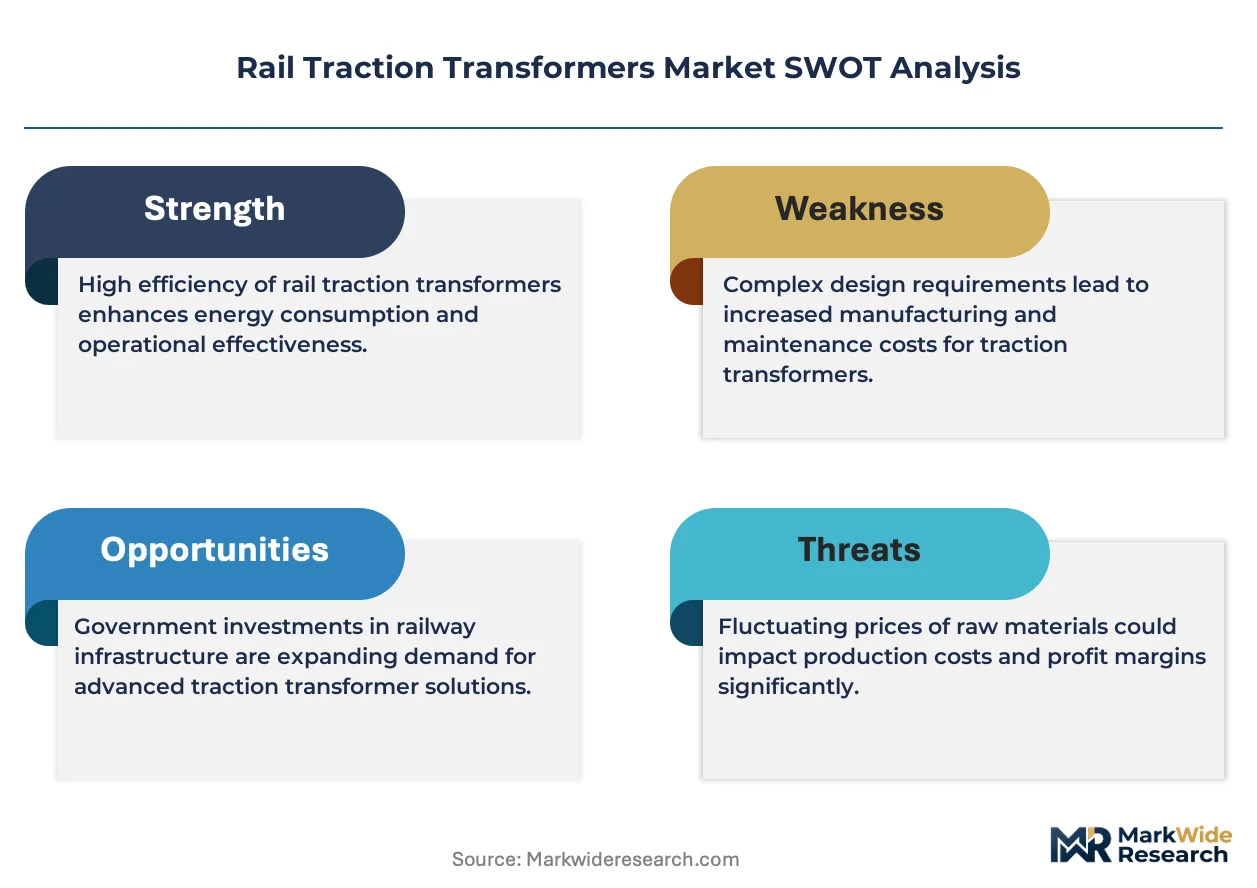
- Single-Phase:These units step down 25 kV or 15 kV catenary voltage for conventional passenger and freight locomotives. Indian Railways procures them heavily for its Dedicated Freight Corridor electrification, where tropical climate cooling architectures add thermal design complexity.
- Three-Phase:Delivering superior power density and thermal endurance, these transformers dominate high-speed rail applications above 300 km/h. China's state-backed rail expansion drives concentrated volume procurement for 350 km/h corridors, pulling demand from legacy diesel conversion programs.
- Auto Transformers:Voltage regulation devices for multi-system locomotives crossing electrification boundaries.
- Specialized Transformers:Compact designs for double-decker trains and narrow-gauge networks with dimensional constraints.
Three-Phase sits at the top of the volume ranking, with Specialized Transformers climbing the fastest.
Application:
Vehicle platform determines cooling system selection, with underground installations mandating dry-type fire-resistant designs while open-track freight tolerates liquid-immersed architectures.
- Trains:Intercity and regional passenger services specify standardized 25 kV/50 Hz units with modular replacement protocols. European operators prioritize F-Gas-compliant insulating fluids to satisfy KBA cross-border rolling stock approvals.
- Metro Systems:Tunnel-constrained installations command premium pricing for compact dry-type designs with forced-air cooling. Operators in Brazil and Turkey specify these units for underground densification projects where fire safety overrides weight considerations.
- Trams:Low-floor vehicle integration requires ultra-compact transformer footprints.
- Freight Locomotives:Heavy-haul applications demand thermal endurance for sustained high-load operation.
Trains generate the largest installed base, though Metro Systems is expanding most quickly as urban rail densifies across emerging economies.
End User:
Ownership structure shapes procurement risk allocation, with public operators favoring lifecycle maintenance contracts and private operators prioritizing capital expenditure minimization.
- Public Transport Operators:State-backed networks in China and Spain specify availability guarantees rather than parts-and-labor coverage, transferring operational risk to manufacturers with telemetry infrastructure for remote dissolved gas analysis.
- Private Rail Operators:Open-access freight carriers in Europe favor standardized transformer specifications to enable multi-vendor maintenance and avoid single-source dependency.
- Mining Companies:Captive rail networks for bulk commodity transport operate in harsh ambient conditions.
- Industrial Users:Plant-internal rail systems for steel and chemical facilities require specialized voltage configurations.
Public Transport Operators command the dominant share of procurement volume, with Private Rail Operators gaining traction fastest as European rail liberalization advances.
Technology:
Intelligence tier determines service revenue potential, with conventional hardware yielding one-time sales while connected platforms enable performance-based maintenance contracts.
- Conventional:Electromechanical designs without embedded sensing dominate legacy fleet replacement. These units operate 40+ years with minimal intervention, limiting annual addressable volume to catastrophic failure scenarios rather than routine refresh.
- Digital:Condition-monitoring capabilities enable predictive maintenance contracts that extend asset life beyond traditional replacement cycles. European operators retrofit conventional fleets with solid-state sensors to cut unplanned downtime.
- Solid-State:Power electronics-based voltage conversion for next-generation rolling stock.
- Smart Grid:Grid-interactive transformers with bidirectional power flow for regenerative braking energy recovery.
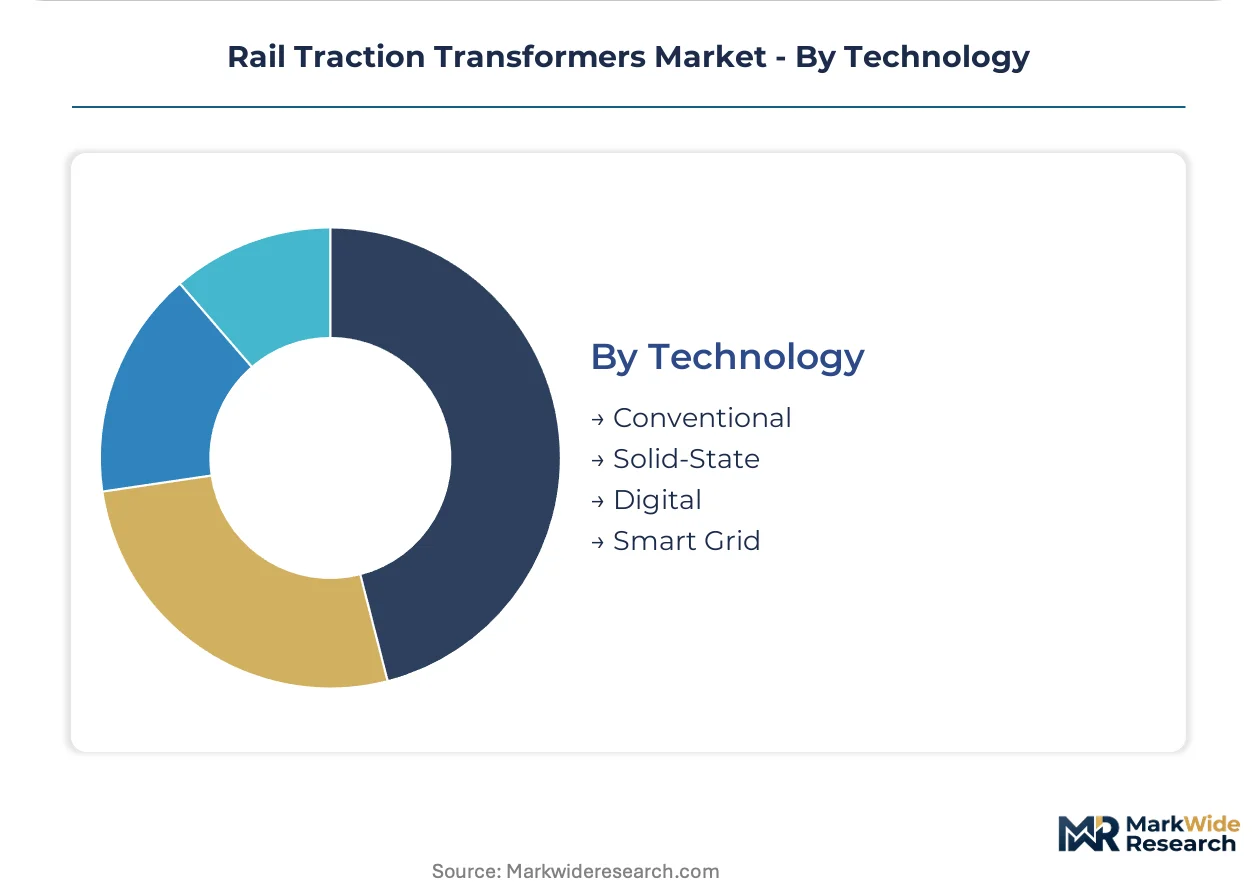
Conventional technology retains the largest installed base, while Digital is climbing fastest as operators retrofit telemetry for availability-based contracting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's state-backed rail expansion drives volume procurement of three-phase traction units, while India's Dedicated Freight Corridor electrification pulls demand for tropical climate cooling architectures. Europe's F-Gas Regulation tightens efficiency mandates across cross-border corridors. Brazil and Turkey specify compact dry-type designs for metro densification projects.
China
State-backed expansion of 350 km/h high-speed rail corridors concentrates procurement of three-phase traction transformers. GB standards and NMPA-equivalent rail certification processes create parallel compliance tracks for suppliers targeting dual carbon-aligned procurement programs. The Yangtze River Delta cluster anchors manufacturing capacity for both domestic deployment and export programs.
Germany
KBA fast-tracks type approvals for cross-border rolling stock compatibility with F-Gas-compliant insulating fluids. The F-Gas Regulation's 2024 ban on virgin hydrofluorocarbons redirects R&D toward air-natural cooling architectures. Bavaria and Baden-Württemberg host accredited IEC 60310 testing infrastructure that creates entry barriers for emerging suppliers.
India
The Ministry of Railways electrifies 2,800 route-kilometers of Dedicated Freight Corridor, generating demand for 25 kV/50 Hz single-phase units. BIS certification and CEA electrification mandates shape procurement specifications. Gujarat and Maharashtra industrial corridors concentrate transformer assembly capacity serving tropical climate applications.
Spain
Public transport operators procure three-phase traction units for high-speed corridor extensions above 300 km/h. EU Green Deal alignment pressures accelerate bio-based ester coolant adoption across Iberian networks. The Madrid-Barcelona corridor serves as the primary deployment zone for next-generation availability-based contracting models.
Brazil
Metro system densification in São Paulo and Rio de Janeiro commands premium pricing for compact dry-type designs with forced-air cooling. ANVISA-equivalent fire-safety codes for tunnel installations override weight considerations in procurement specifications. The São Paulo metropolitan rail cluster leads South American adoption of condition-monitoring retrofits.
Rail Traction Transformers Market Competitive Environment
Top-tier vendors anchor integrated transformer-feeder systems and long-term service agreements, while mid-tier specialists compete on tropical climate cooling architectures and compact dry-type footprints. The vendor base stratifies across three archetypes: electrification conglomerates with installed base telemetry infrastructure, regional fabricators serving single-country certification tracks, and metro-focused compact design specialists. M&A activity concentrates service revenue with telemetry-enabled suppliers, while geographic expansion targets India's freight corridor and Brazil's underground rail densification.
Among electrification conglomerates, Siemens and ABB exemplify the service-revenue pivot through performance-based maintenance contracts and integrated substation systems. Alstom occupies a position within the compact specialization tier, representing the double-decker and high-speed platform optimization archetype. These three anchors illustrate how digital infrastructure concentration compresses margins for pure-hardware vendors lacking remote dissolved gas analysis capabilities.
| Leading Market Players |
|---|
| ABB |
| Siemens |
| Mitsubishi Electric Corporation |
| Alstom |
| GE |
| Hitachi |
| JST Transformateurs |
| Hind Rectifiers Limited |
| CG Power & Industrial Solutions |
| Others |
Value Chain & Pricing Dynamics
Europe's F-Gas Regulation gates qualified supply and premium-tier pricing access by mandating fluoronitrile and bio-based ester coolant certifications that only established manufacturers with accredited testing infrastructure can satisfy. Rail operators seeking cross-border rolling stock compatibility now pay material premiums for KBA-fast-tracked units while legacy mineral-oil designs face procurement exclusion.
Pricing Analysis
Capacity additions in India and China are reshaping price floors for tropical climate cooling architectures and three-phase high-speed units. Three-tier pricing structure across premium, standard, and economy levels separates F-Gas-compliant designs with digital twin integration from conventional mineral-oil units and unmonitored legacy replacements. Pricing pressure stems from copper and grain-oriented electrical steel volatility that compresses margin visibility on fixed-price tenders. Private rail operators exhibit highest price sensitivity through standardized specifications enabling multi-vendor maintenance, while public transport operators in China and Spain accept premium positioning for availability-guaranteed performance contracts.
Supply Chain Analysis
Specialized field service technician scarcity in France, Japan, and Switzerland constrains manufacturing scale-up and aftermarket capacity expansion across liquid-immersed transformer assembly. Core material supply concentrates in China, Germany, and Japan for grain-oriented electrical steel and high-purity copper winding conductors. Raw material dependencies rest on rare earth elements for solid-state sensor integration and fluoronitrile chemistry for compliant insulating fluids. Single-source vulnerability runs through IEC 60310-accredited high-power testing laboratories concentrated in Bavaria, Baden-Württemberg, and the Yangtze River Delta. Distribution runs through electrification conglomerates with installed base telemetry infrastructure that capture long-term service revenue alongside hardware supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rail traction transformers represent a stable compounder anchored by state-backed electrification mandates that generate multi-decade replacement cycles and greenfield installation pipelines across freight and passenger networks.
For Market Incumbents: To counter margin compression from copper and electrical steel volatility, deepen backward integration into core material supply through captive sourcing arrangements with Japanese and German steel producers. Anchor competitive position by expanding IEC 60310-accredited testing infrastructure into India's Gujarat and Maharashtra industrial corridors, locking in certification revenue from emerging suppliers seeking dual-track European and Chinese market access. For New Entrants and Emerging Players: Launch via tropical climate cooling specialization targeting India's Dedicated Freight Corridor electrification, where BIS certification requirements create a narrower competitive set than saturated European corridors. Penetrate Brazil's metro densification segment with compact dry-type designs that command premium pricing under ANVISA-equivalent fire-safety codes, bypassing the high-power freight locomotive segment dominated by established telemetry-enabled suppliers. For Investors and Strategic Acquirers: Roll-up economics work for regional fabricators with single-country certification tracks because multi-standard approval timelines create stranded assets that strategic buyers can consolidate under unified testing infrastructure. Target mid-tier specialists possessing metro-focused compact design capabilities or tropical climate architectures that complement incumbent electrification conglomerates. Watch for inflection when European tender specifications mandate real-time thermal modeling as standard, accelerating software-services revenue capture and compressing pure-hardware vendor valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Integration | Real-time thermal modeling mandates in European tenders open software-services revenue streams adjacent to hardware supply. |
| Bio-Based Ester Certification | REACH-compliant coolant transitions eliminate aquatic toxicity risks while satisfying KBA cross-border rolling stock approvals. |
| Condition-Monitoring Retrofit | Solid-state sensor deployment extends asset life beyond traditional replacement cycles and enables availability-based contracting. |
| Testing Infrastructure Expansion | IEC 60310-accredited laboratory investment in India and China reduces certification barriers for emerging market penetration. |
| Performance-Based Maintenance Contract | Telemetry-enabled service agreements transfer operational risk from public transport operators to manufacturers with dissolved gas analysis capabilities. |
Study Parameters
Multiple input streams — primary interviews with rail electrification engineering directors, procurement leads at state transport operators, and aftermarket service heads; secondary validation through IEC standards documentation, customs trade data for core material flows, and SEC filings from electrification conglomerates; plus bottom-up and top-down triangulation across vehicle platform deployment databases — were reconciled to construct segment-level volume and value estimates.
Historical deployment trajectories were cross-referenced against expert panel inputs regarding F-Gas Regulation phase-down timelines and digital twin specification adoption curves across the projection horizon. The analytical framework modeled traction transformer demand by product architecture, vehicle platform, cooling system type, and embedded intelligence tier, with CAGRs derived from electrification mandate pacing and replacement cycle dynamics. Industry-specific forecast inputs included Dedicated Freight Corridor route-kilometer commitments and high-speed rail corridor speed-tier upgrades.
Several conditions sit outside the modeled scope, including catastrophic failure rates beyond historical baselines, abrupt copper price dislocations, and regulatory acceleration of dry-type mandates in freight applications. Forecasts reflect documented assumptions regarding state-backed procurement continuity and certification timeline stability. Material deviation in electrification funding allocation or F-Gas Regulation enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transformers
Europe Distribution Transformer Market
Transformers
Oil Immersed Transformer and Dry Type Transformer Market
Transformers
Box Transformer Substation Market
Transformers
Distribution Transformer Market
Transformers
Transformer Oil Market
Transformers
Liquid Filled Transformer Market
Transformers
India Power Transformer Market
Transformers
Cast Resin Transformers Market
Transformers
Green Power Transformers Market
Transformers
India Transformer Market
Transformers
Industrial Control Transformers Market
Transformers
North America Power Transformer Market
Transformers
Current Transformer Market
Transformers
Middle East Distribution Transformer Market
Transformers
Global Large Power Transformers Market
Transformers
Power Transformer Market